
 Aerospace Materials Market | 2026-2036
Aerospace Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Materials Market Intelligence
China's state-backed investment in domestic composite and specialty alloy production is rewriting the established supply chain for aerospace materials. Toray Industries sustains its market leadership through large-scale carbon fiber manufacturing capacity. Hexcel Corporation differentiates with its portfolio of qualified structural prepregs and adhesives. ATI positions itself as a key supplier of advanced titanium and nickel alloys for critical engine and airframe applications.
Aerospace materials are a class of high-performance substances, including alloys and polymers, qualified for aviation and space applications. These materials must exhibit exceptional strength-to-weight ratios and resistance to fatigue and extreme temperatures to ensure structural integrity. The composites segment, particularly carbon fiber reinforced plastics, represents the fastest-growing category for structural components. Titanium alloys continue to dominate applications in engine parts and landing gear where high-temperature strength is paramount.
Material qualification is governed by stringent standards from airworthiness authorities like the FAA in the United States and EASA in Europe. Europe's REACH regulation further constrains the use of certain chemical substances in alloys and composite resins, influencing material selection. Suppliers must now balance the pursuit of next-generation performance with increasing regulatory pressure for sustainable manufacturing and end-of-life recyclability.
Market Dynamics
The global aerospace materials supply chain is undergoing a fundamental reconfiguration, driven by the strategic imperative of major aviation nations to secure domestic production of critical composites and specialty alloys, challenging long-standing supply dependencies and altering competitive cost structures.
Growth Catalysts
- Ceramic Matrix Composites (CMCs):The operational maturation of CMCs in hot-section jet engine components, such as shrouds and nozzles, enables higher operating temperatures, which directly translates to improved fuel efficiency and reduced emissions for next-generation commercial and military aircraft.
- Commercial Aircraft Production:A sustained ramp-up in narrow-body and wide-body aircraft production to meet airline fleet renewal and expansion cycles provides a powerful demand signal for lightweight aluminum-lithium alloys and carbon fiber prepregs for fuselage and wing structures.
- National Space Programs:Renewed government investment in space exploration, exemplified by initiatives like the Artemis program in the United States, creates demand for specialized materials capable of withstanding extreme thermal cycling and radiation exposure for launch vehicles and crewed spacecraft.
Market Restraints
- Raw Material Cost Volatility:The high and often volatile cost of essential inputs, such as aerospace-grade titanium sponge and polyacrylonitrile (PAN) precursor for carbon fiber, creates significant cost pressure on material producers and complicates long-term pricing agreements with OEMs.
- Regulatory Compliance Burden:Europe's REACH regulation restricts or requires authorization for numerous chemical substances used in specialty alloys and composite resin systems, forcing costly material reformulation and requalification efforts for suppliers selling into the European market.
- Extended Qualification Timelines:The rigorous and lengthy material qualification and certification processes mandated by airworthiness authorities like the FAA and EASA act as a significant barrier, slowing the market introduction of innovative materials and increasing development costs.
Strategic Opportunities
- Urban Air Mobility (UAM) Platforms:The development of electric vertical takeoff and landing (eVTOL) aircraft for intra-city transport creates a new market for ultra-lightweight composites and novel material forms optimized for battery-powered flight and acoustic dampening.
- Additive Manufacturing Integration:The convergence of additive manufacturing (3D printing) with qualified titanium and nickel-based alloy powders allows for the production of complex, topology-optimized components, offering part consolidation and weight reduction opportunities for airframe and engine parts.
- Sustainable Aviation Fuels (SAF) Infrastructure:The build-out of infrastructure for SAF production and transport will require specialized corrosion-resistant alloys and composite materials for storage tanks, pipelines, and handling equipment, representing an adjacent growth vector.
Industry Challenges
- Supply Chain De-risking:Manufacturers face the operational challenge of reconfiguring global supply chains for critical raw materials, like nickel and cobalt, to mitigate geopolitical risks, which involves qualifying new suppliers and increasing inventory levels at significant cost.
- End-of-Life Material Circularity:The industry lacks scalable, cost-effective processes for recycling thermoset carbon fiber composites from retired aircraft, creating a significant waste management and sustainability challenge that regulators are beginning to address.
- Digital Thread Implementation:Integrating a digital thread from material production through to in-service performance monitoring is a complex operational task, requiring significant investment in sensors, data management systems, and new engineering skill sets to achieve.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Materials Market |
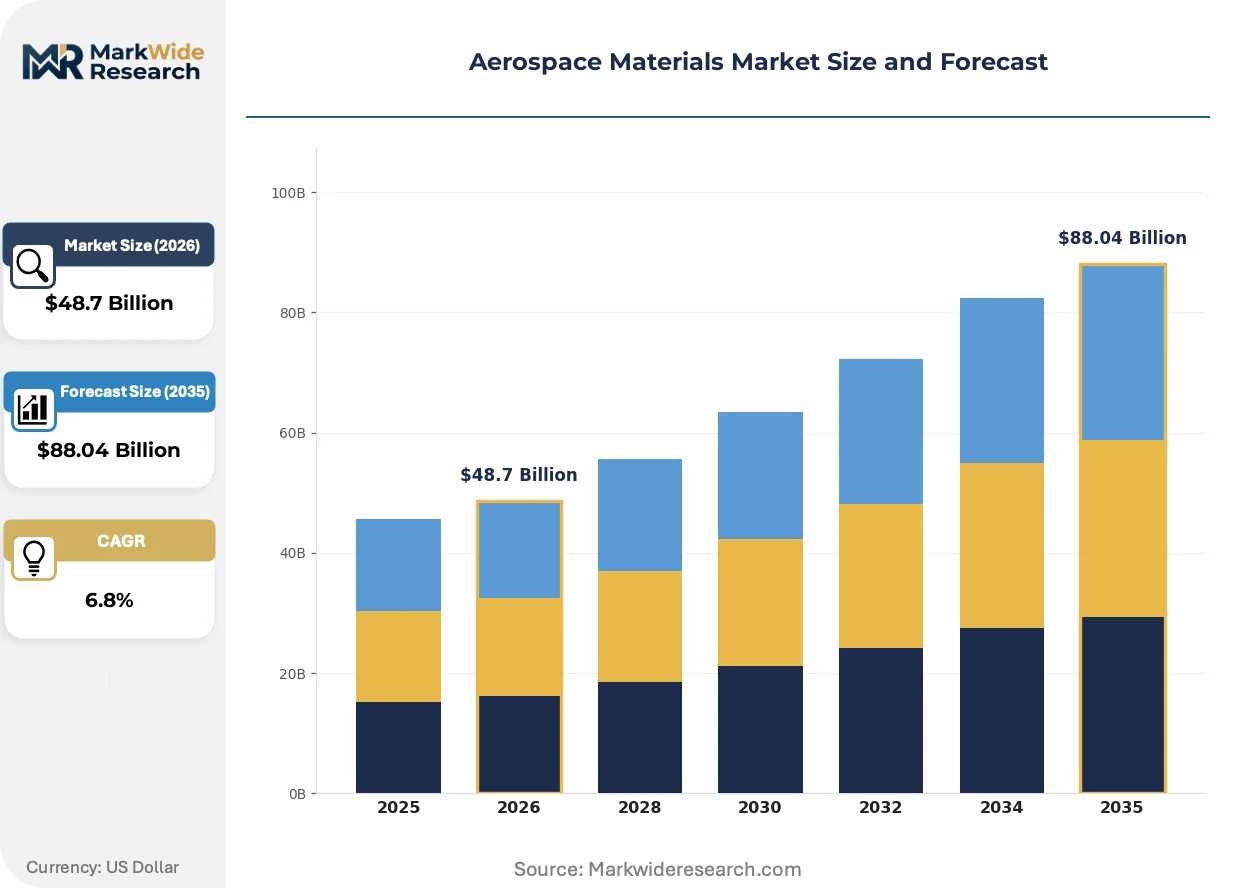
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum Alloys, Titanium Alloys, Composites, Nickel Alloys, Magnesium Alloys Application: Structural Components, Engine Parts, Cabin Interiors, Landing Gear, Avionics Housing Manufacturing Stage: Raw Material, Semi-Finished Product, Finished Product, Assembly Parts End User: Commercial Aircraft Manufacturers, Defense Contractors, Spacecraft Producers, MRO Providers |
| Companies Covered | Mitsubishi Chemical Group Corporation, Huntsman International, Syensqo, SGL Carbon, VSMPO-AVISMA Corporation, Toray Industries, Teijin Limited, ATI, Hexcel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Materials Market Strategic Shifts & Innovations
A shift toward life-cycle accountability is compelling material suppliers to innovate beyond pure performance metrics. The convergence of digital modeling, stringent sustainability reporting, and new manufacturing paradigms is creating a market where material selection depends on a holistic assessment of performance, producibility, and environmental impact.
Integrated Computational Materials Engineering (ICME) is a modeling-based approach that connects material processing to final component performance. Aerospace prime contractors and engine manufacturers are adopting ICME to drastically reduce the number of expensive and time-consuming physical tests required for material qualification. This methodology is digitizing the entire material design and certification pathway, compressing development timelines for new alloys and composites from decades to years.
Europe's Corporate Sustainability Reporting Directive (CSRD) is forcing a new level of transparency in the materials supply chain. The directive compels large companies and their suppliers to disclose detailed metrics on environmental impact, including greenhouse gas emissions and plans for material circularity. The composites segment is particularly affected, accelerating investment in recyclable thermoplastic composites and advanced fiber recovery technologies to meet these new disclosure mandates and demonstrate sustainability credentials.
Collaborative procurement models are displacing traditional, transactional supplier relationships for critical structural components. Major aircraft manufacturers increasingly favor long-term partnerships where material supplier engineers are co-located with OEM design teams to optimize material selection from the earliest stages of a program. This integrated approach is most prevalent in aerospace manufacturing hubs like Toulouse, France, and Charleston, USA, for complex wing and fuselage assemblies.
Aerospace Materials Market Segmentation
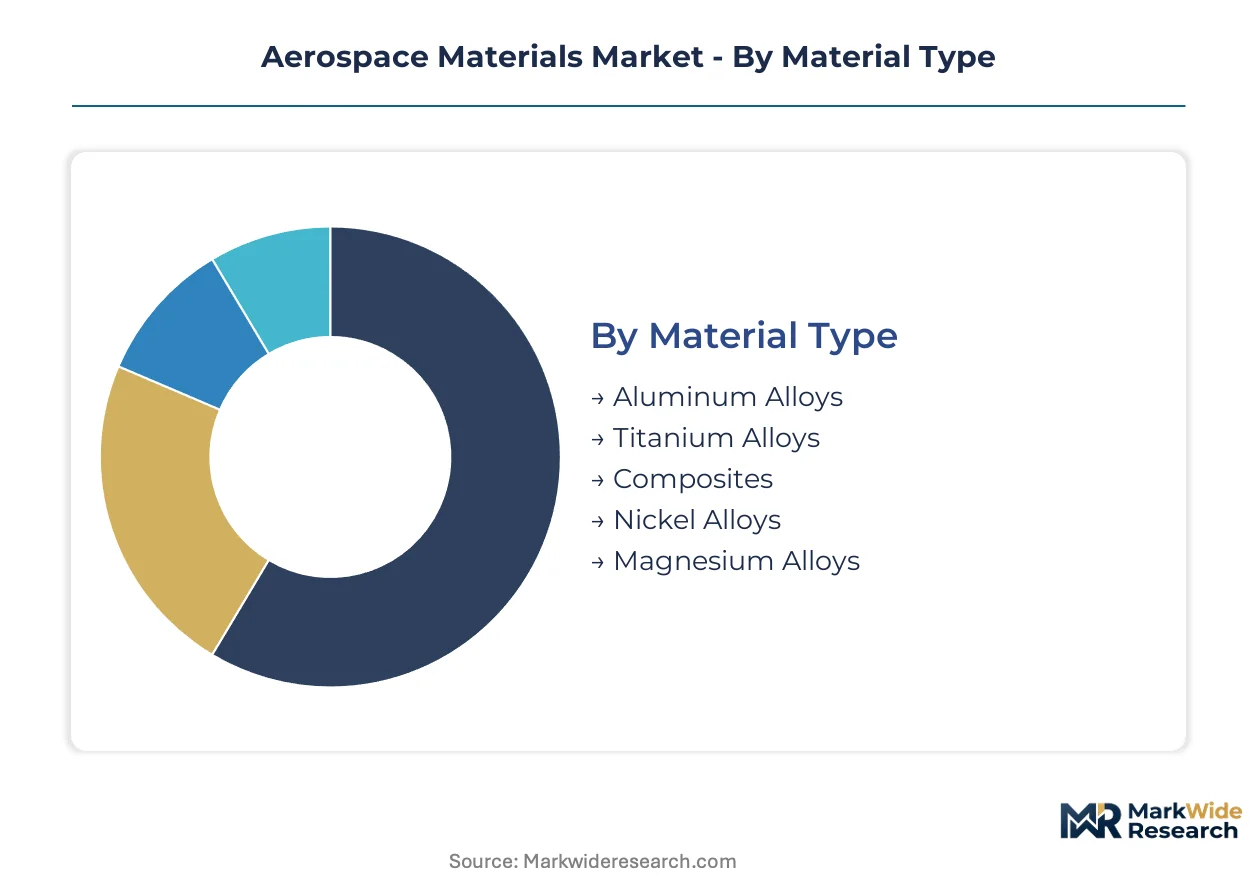
The aerospace materials market is intricately segmented, reflecting the diverse performance demands, regulatory constraints, and manufacturing complexities inherent in aviation and space applications. Understanding these segments is critical for material suppliers to align their innovation pipelines and for original equipment manufacturers to optimize material selection for next-generation platforms.
Material Type:
The performance characteristics of aerospace materials dictate their suitability for demanding applications across the industry.
- Aluminum Alloys:These lightweight metals, particularly advanced aluminum-lithium grades, offer an excellent strength-to-weight ratio and are widely used in fuselage and wing structures for commercial aircraft. Demand concentrates heavily in narrow-body production lines, where cost-efficiency and established manufacturing processes are paramount.
- Titanium Alloys:Known for exceptional high-temperature strength and corrosion resistance, titanium alloys are indispensable for engine components, landing gear, and critical airframe structures. Their application is expanding in military platforms and space vehicles, where extreme environmental conditions prevail.
- Composites:This category, dominated by carbon fiber reinforced plastics, provides superior strength-to-weight performance for structural components.
- Nickel Alloys:Engineered for extreme heat and stress, nickel-based superalloys are crucial for jet engine hot sections and high-performance military applications.
- Magnesium Alloys:Offering the lowest density among structural metals, magnesium alloys find niche applications in non-critical airframe parts and interior components where weight reduction is prioritized.
Titanium Alloys commands the established base. The steepest expansion runs through Composites.
Application:
Demand for aerospace materials is directly shaped by their intended application within aircraft and spacecraft systems.
- Structural Components:This segment includes fuselage, wings, empennage, and other primary load-bearing structures, heavily relying on lightweight composites and advanced aluminum alloys. Commercial aircraft production drives significant volume requirements for these materials, particularly in Europe and North America.
- Engine Parts:Materials for engine components, such as turbine blades, combustors, and casings, require extreme temperature resistance and fatigue strength, making titanium alloys, nickel superalloys, and ceramic matrix composites essential. Innovations in this area directly impact fuel efficiency and emissions for global aviation.
- Cabin Interiors:Materials for cabin interiors prioritize fire retardancy, acoustics, and aesthetic appeal, including specialized polymers and lightweight composites.
- Landing Gear:Requiring immense strength and fatigue resistance, landing gear components primarily utilize high-strength titanium and steel alloys.
- Avionics Housing:Materials for avionics enclosures provide electromagnetic interference shielding and thermal management, typically involving aluminum alloys and specialized plastics.
Material innovation primarily targets Engine Parts, while Structural Components drives volume requirements.
Manufacturing Stage:
The value chain for aerospace materials differentiates across manufacturing stages, from primary production to final component assembly.
- Raw Material:This stage encompasses the extraction and initial processing of base elements like bauxite, titanium sponge, and polyacrylonitrile (PAN) precursor for carbon fiber. Geopolitical stability and energy costs significantly influence the supply and pricing of these foundational inputs.
- Semi-Finished Product:This segment includes processed forms such as aluminum sheets, titanium plates, composite prepregs, and alloy billets, which are ready for further fabrication. Europe's REACH regulation impacts the chemical composition and processing of these materials for market entry.
- Finished Product:These are components ready for direct integration into aerospace systems, including machined parts, molded composite structures, and fasteners.
- Assembly Parts:This stage involves the integration of multiple finished products into larger sub-assemblies, such as wing sections or engine modules.
Upstream activities in Raw Material dictate cost structures, with Finished Product enabling specialized component production.
End User:
Customer requirements for aerospace materials vary significantly by the end-user segment, influencing material specifications and procurement strategies.
- Commercial Aircraft Manufacturers:This segment, including companies like Airbus and Boeing, demands high volumes of materials that offer excellent performance-to-cost ratios and support rapid production ramp-ups. Lightweighting solutions for fuel efficiency are a continuous focus.
- Defense Contractors:These users prioritize extreme performance, stealth capabilities, and high-temperature resistance for military aircraft, missiles, and unmanned aerial vehicles. Material qualification processes are often highly specialized and lengthy for defense programs.
- Spacecraft Producers:This segment requires materials capable of withstanding extreme thermal cycling, radiation, and vacuum conditions for launch vehicles and satellites.
- MRO Providers:Maintenance, Repair, and Overhaul (MRO) providers require certified replacement parts and repair materials that meet strict airworthiness standards.
Volume demand originates primarily from Commercial Aircraft Manufacturers, while Defense Contractors drives material performance envelopes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Aviation Administration (FAA) in the United States anchors material qualification standards for aerospace applications. This influences material selection across commercial and defense sectors. Global demand for advanced aerospace materials is driven by increasing aircraft production and renewed space exploration initiatives.
United States
United States demand for aerospace materials stems from robust commercial aircraft orders and significant defense program investments. FAA certification processes dictate material specifications for airframe and engine components. Major aerospace manufacturing clusters in Seattle and Wichita drive large volume requirements for aluminum and composite materials.
France
France's aerospace material consumption is propelled by Airbus production volumes and strategic defense procurements. EASA regulations, particularly REACH, influence the selection and qualification of composite resins and specialty alloys. Toulouse, as a primary aerospace manufacturing hub, concentrates material suppliers and design teams for complex assemblies.
China
China's aerospace material requirements are expanding with its ambitious domestic aircraft programs and space exploration goals. The Ministry of Industry and Information Technology (MIIT) directs state-backed investments into indigenous composite and alloy production. Aerospace manufacturing centers in Xi'an and Shanghai are rapidly developing local supply chains for critical components.
Germany
Germany's demand for high-performance aerospace materials focuses on engine components and advanced lightweight structures. European Union directives, including the EU Green Deal, push for sustainable material innovation and lifecycle accountability. Hamburg's aircraft assembly facilities and Munich's engine R&D centers are key nodes for material technology integration.
Japan
Japan's aerospace material industry excels in advanced carbon fiber and specialty metal production for global supply chains. The Ministry of Economy, Trade and Industry (METI) supports R&D initiatives for next-generation composite and alloy development. The Nagoya region, with its strong aerospace component manufacturing base, drives innovation in material processing.
Aerospace Materials Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the aerospace materials market. The market structure is tiered, featuring specialized high-performance material developers alongside integrated, high-volume manufacturers. Key strategic archetypes include specialty alloy producers and advanced composite system providers. Competitive moves frequently involve capacity expansion and strategic partnerships to secure critical raw material supply.
Within the advanced materials tier, Toray Industries, a Japanese multinational, anchors global carbon fiber manufacturing capacity. Hexcel Corporation, based in the United States, exemplifies a specialized provider with its portfolio of qualified structural prepregs and adhesives. ATI, also from the United States, occupies a position as a key supplier of advanced titanium and nickel alloys for critical engine and airframe applications.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group Corporation |
| Huntsman International |
| Syensqo |
| SGL Carbon |
| VSMPO-AVISMA Corporation |
| Toray Industries |
| Teijin Limited |
| ATI |
| Hexcel Corporation |
| Others |
Cost & Logistics Intelligence
Underutilized capacity in specialty alloy production, particularly across Chinese domestic facilities, creates competitive pricing pressures on established global suppliers. This dynamic influences investment decisions and long-term contract negotiations for aerospace OEMs.
Pricing Analysis
Geographic price spreads for aerospace materials vary significantly, reflecting regional supply concentration and regulatory overhead. Contract-based long-term offtake agreements dominate the market, providing stability for both suppliers and OEMs. Certification level, particularly FAA and EASA qualification, and volume scale are primary price differentiation drivers. Pricing pressure stems from the high and often volatile cost of essential inputs like titanium sponge, with commercial aircraft manufacturers exhibiting higher price sensitivity than defense contractors.
Supply Chain Analysis
Upstream feedstock for critical aerospace materials, such as polyacrylonitrile (PAN) precursor for carbon fiber and titanium sponge, originates from a concentrated set of countries. Japan and China are significant producers of PAN precursor, while the United States and Russia contribute substantially to titanium sponge supply. Geopolitical risks and trade policies represent a structural risk, influencing material availability and cost. Distribution runs through direct sales and long-term supply agreements between material producers and major aerospace OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerospace materials market presents a compelling fragmentation opportunity for specialized suppliers. The emergence of Urban Air Mobility (UAM) platforms creates distinct niches for ultra-lightweight composites and novel material forms optimized for battery-powered flight.
For Market Incumbents: Build regulatory qualification moats through accelerated Integrated Computational Materials Engineering (ICME) adoption. This reduces development timelines for new alloys and composites, countering the threat from emerging material science startups. Incumbents should also invest in advanced fiber recovery technologies to address the end-of-life circularity challenge, aligning with Europe's CSRD mandates. Deepening long-term partnerships with major OEMs, especially in aerospace manufacturing hubs like Toulouse, secures future demand.
For New Entrants and Emerging Players: Pursue specialized material forms for emerging aerospace applications, such as ultra-lightweight composites for Urban Air Mobility (UAM) platforms. The additive manufacturing segment, particularly for complex titanium and nickel alloy components, represents a penetrable market. New entrants can differentiate by offering rapid prototyping capabilities and material solutions optimized for battery-powered flight and acoustic dampening. Strategic partnerships with smaller, agile aerospace innovators provide a viable go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the advanced composites sub-segment, driven by complex manufacturing processes and stringent qualification requirements. The market offers long-term viability, anchored by sustained commercial aircraft production and renewed space initiatives. Acquisition targets should focus on specialized material developers with proprietary qualification data or unique additive manufacturing capabilities. The speed at which new materials achieve FAA or EASA certification serves as a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Carbon Fiber | Meets growing demand from commercial aircraft manufacturers for lightweight structures. |
| R&D in Recyclable Thermoplastics | Addresses regulatory pressure for sustainable manufacturing and end-of-life material circularity. |
| Strategic Partnership with OEMs | Secures long-term supply agreements and co-development opportunities for next-generation platforms. |
| Investment in Additive Manufacturing | Enables production of complex, topology-optimized components for weight reduction. |
| Qualification for UAM Applications | Unlocks new market opportunities in electric vertical takeoff and landing aircraft. |
Research Approach
A standing panel of material scientists, OEM procurement leads, and airworthiness regulators provided ongoing calibration for market assumptions. This study combined primary interviews with industry stakeholders with robust secondary validation from published reports and regulatory filings. Secondary sources included FAA certification documents, EASA REACH compliance reports, and public company 10-K statements. Bottom-up and top-down triangulation ensured data integrity across all segments.
Scenario-bracketing provided a robust framework for projecting market trajectory across the analysis window. Segmentation dimensions included material type, application, manufacturing stage, end-user, and regional demand patterns. Compound annual growth rates were derived from a blend of historical trends and projected future demand signals. Key industry-specific forecast inputs included projected commercial aircraft build rates and material qualification timelines.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or energy prices would shift the market trajectory. Forecasts reflect assumptions documented through extensive primary and secondary research. Raw material cost volatility and geopolitical instability represent key risk factors. Cross-checking against IEA reports and major OEM production forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Global Aerospace Insulation Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market
Aerospace and Aircraft Materials
Stealth Coating Market
Aerospace and Aircraft Materials
Aviation Carbon Fiber Market
Aerospace and Aircraft Materials
Aircraft Coatings Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Aerospace Radome Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Aerospace Foam Market
Aerospace and Aircraft Materials
Aerographite Market