
 Defense Aircraft Material Market | 2026-2036
Defense Aircraft Material Market Size, Share, and Industry Trends Forecast 2026-2036
Defense Aircraft Material Market Analysis
United States production expansion for titanium and advanced composites is rewriting supplier dynamics across Western defense aerospace. Boeing leverages captive forging capacity in the Pacific Northwest to secure titanium supply for fighter and bomber programs. Lockheed Martin anchors its F-35 supply chain through qualified domestic composite houses, while Hexcel Corporation sustains leadership in carbon fiber prepreg formulations for military wing structures. Raytheon Technologies competes across propulsion alloys and electronic materials, extending its materials portfolio beyond traditional airframe boundaries.
Defense aircraft material encompasses metallurgical and non-metallic substances engineered to withstand extreme thermal, mechanical, and electromagnetic stresses during military flight operations, including Ti-6Al-4V titanium alloys with tensile strengths exceeding 900 MPa and carbon fiber reinforced polymers cured under autoclave pressure cycles exceeding 100 psi. These materials primarily enable structural integrity, radar signature management, and fuel efficiency in platforms operating at supersonic speeds or in contested electromagnetic environments. Composite formulations for wing structures now command premium positioning as stealth requirements and weight reduction targets intensify across sixth-generation fighter programs. Aluminum alloys for fuselage applications retain volume dominance in legacy platform sustainment, though margin pools are migrating toward titanium and specialty steels for landing gear and engine mounts where fatigue resistance determines operational lifespan.
The FAA administers military airworthiness certifications through delegated authority agreements with the Department of Defense, while EASA REACH restrictions on hexavalent chromium surface treatments are forcing European suppliers to adopt alternative corrosion protection chemistries. Pentagon acquisition directives now mandate domestic sourcing thresholds for critical minerals including titanium sponge and rare earth elements, reshaping supplier qualification timelines. Stakeholders must monitor how ITAR export control revisions and emerging EU defense procurement autonomy frameworks will fragment qualified supplier bases across transatlantic programs.
Market Dynamics
Pentagon acquisition directives mandating domestic sourcing thresholds for titanium sponge and rare earth elements are restructuring supplier qualification timelines and fragmenting qualified vendor bases across transatlantic defense programs.
Growth Catalysts
- Fighter Jet Modernization:NATO allies are expanding procurement of advanced alloys and carbon fiber composites for sixth-generation platforms, creating sustained demand pull for qualified material suppliers.
- REACH Regulatory Pressure:EASA restrictions on hexavalent chromium surface treatments are forcing European suppliers to adopt alternative corrosion protection chemistries, opening qualification windows for compliant coating technologies.
- Domestic Supply Chain Mandates:The Pentagon prioritizes domestic supply chain resilience for critical aerospace inputs, accelerating investment in United States titanium and advanced composite production capacity.
Market Restraints
- Titanium Sponge Volatility:Concentrated global production of titanium sponge in limited geographies creates input cost instability for alloy processors serving military airframe programs.
- ITAR Export Controls:Stringent United States International Traffic in Arms Regulations restrict technology transfer and cross-border supplier qualification, lengthening procurement cycles for multinational programs.
- Aluminum Alloy Substitution Ceiling:Legacy platform sustainment retains volume dominance in aluminum fuselage applications, compressing margin pools available for advanced material conversion.
Strategic Opportunities
- EU Defense Procurement Autonomy:Emerging European Union frameworks for defense procurement autonomy are creating qualified supplier opportunities for continental composite houses and specialty alloy processors.
- Stealth-Grade Composite Convergence:Integration of radar signature management with structural load-bearing functions in wing structures opens premium positioning for multifunctional prepreg formulations.
- Digital Thread Certification:Model-based systems engineering approaches to airworthiness documentation are reducing qualification timelines for new material entrants with robust digital pedigree systems.
Industry Challenges
- Autoclave Capacity Constraints:Carbon fiber reinforced polymer curing requires specialized pressure vessels exceeding 100 psi, creating capital bottlenecks for suppliers scaling to meet fighter program volumes.
- Cross-Border Qualification Friction:FAA and EASA divergent airworthiness certification standards for next-generation military platforms generate duplicate testing burdens for material suppliers serving both regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defense Aircraft Material Market |
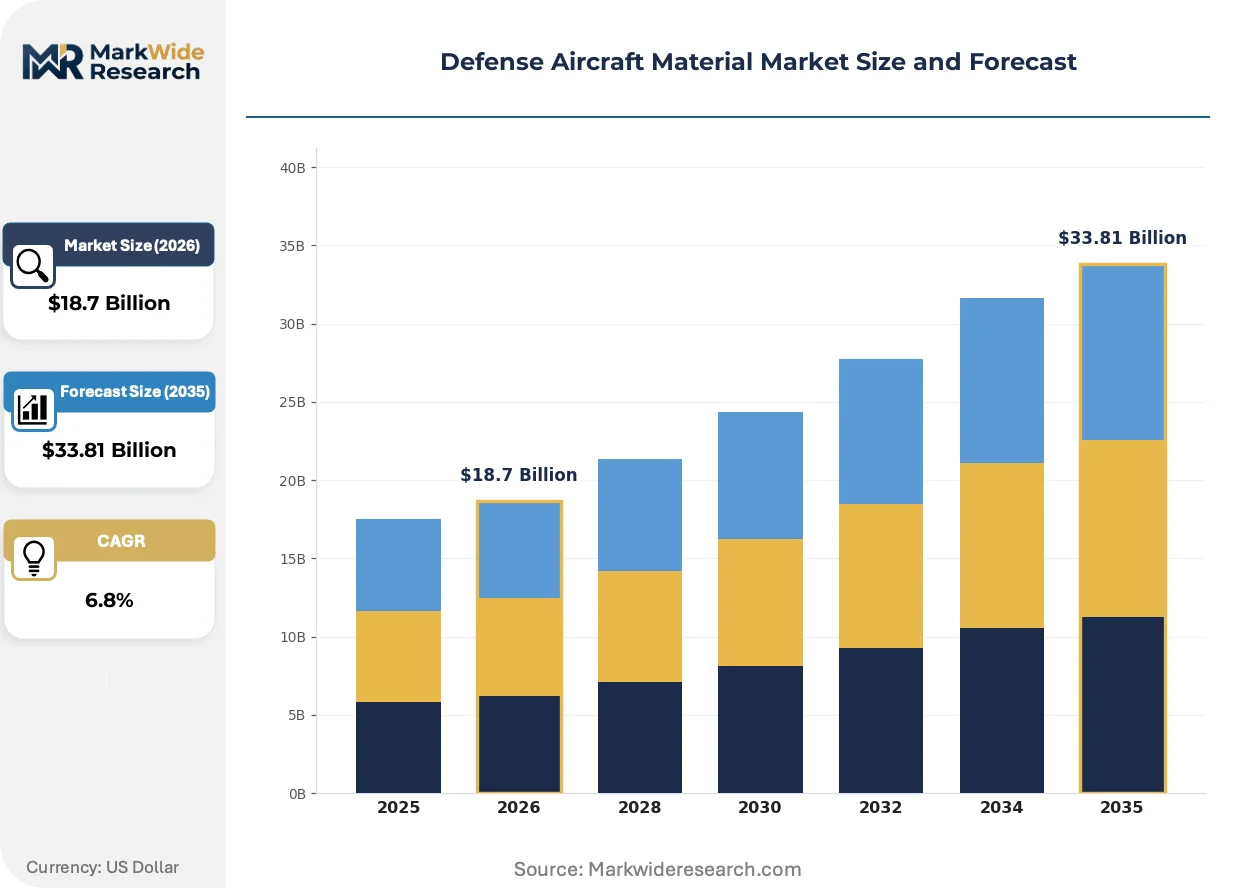
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Titanium, Steel, Composite Application: Fuselage, Wing Structure, Avionics, Landing Gear End User: Military, Defense Contractors, OEMs, Government Agencies Deployment Type: Onshore, Offshore, Integrated, Modular |
| Companies Covered | Boeing, Lockheed Martin, Northrop Grumman, Raytheon Technologies, Hexcel Corporation, Allegheny Technologies Incorporated, Toray Industries, Constellium, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defense Aircraft Material Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to accelerate qualification cycles for next-generation defense aerospace substances while compressing legacy process economics.
Thermoplastic composites are migrating from secondary structure applications to primary wing and fuselage components in sixth-generation fighter programs. Lockheed Martin and Boeing procurement teams are qualifying carbon fiber reinforced thermoplastics for high-rate production environments. This migration from thermoset to thermoplastic matrices is enabling out-of-autoclave processing that compresses cycle times and reduces capital intensity for military airframe fabrication.
REACH restrictions on hexavalent chromium surface treatments are compelling European defense suppliers to adopt trivalent chromium and sol-gel alternatives for corrosion protection of aluminum and titanium substrates. EASA enforcement timelines are accelerating qualification of compliant coating chemistries across Airbus Defence and Space platforms. Suppliers with qualified alternative surface treatment portfolios are capturing specification revisions in legacy platform sustainment contracts.
Long-term material service agreements are displacing spot purchasing for critical titanium alloys and carbon fiber prepreg in major fighter programs. United States prime contractors are consolidating supplier relationships through multi-year offtake commitments with qualified domestic sources. This pattern concentrates procurement leverage with Tier-1 integrators while compressing margin visibility for mid-tier material processors serving the F-35 and B-21 programs.
Defense Aircraft Material Market Segmentation
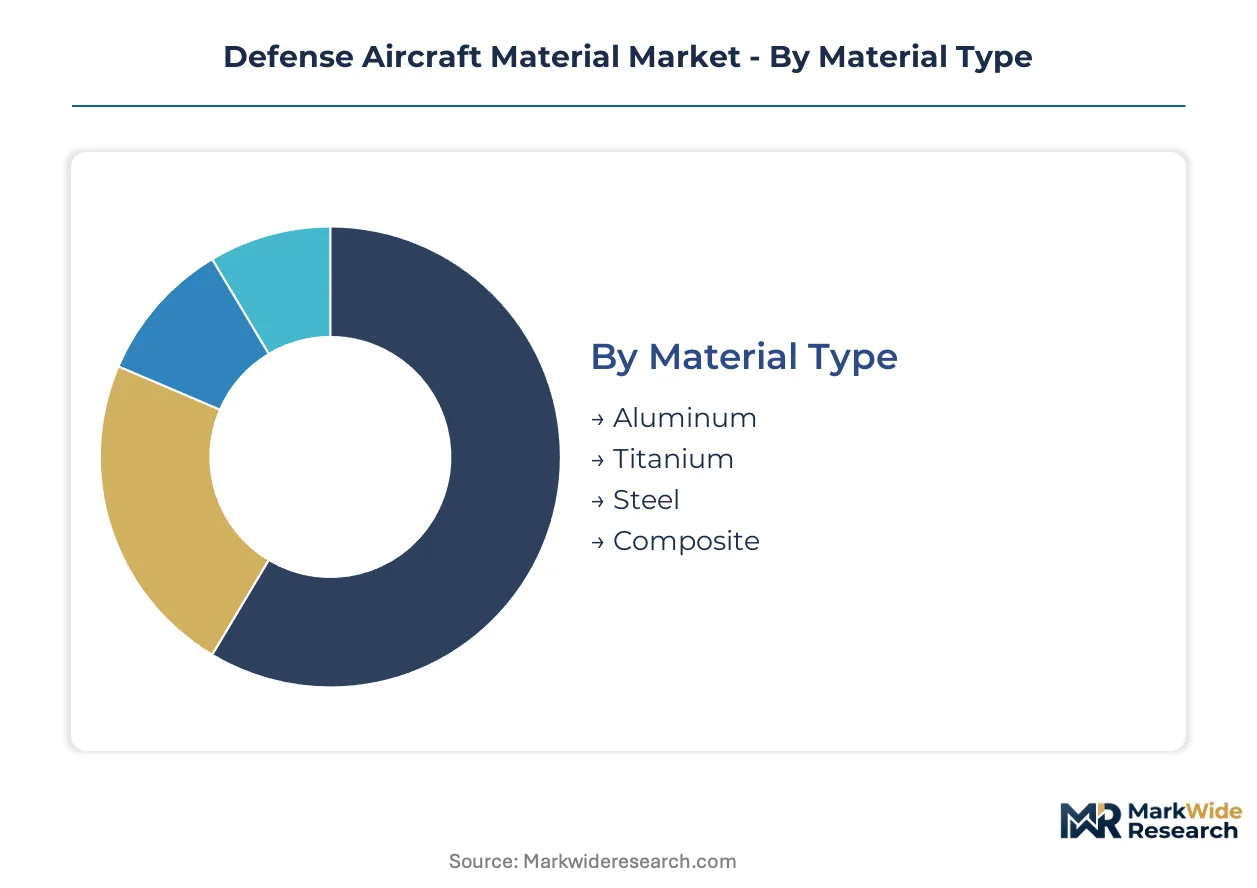
Defense aircraft material procurement patterns diverge sharply across material chemistry, structural application, and end-user qualification requirements. Understanding these segment boundaries clarifies where technology premiums concentrate versus where commodity substitution pressures dominate.
Material Type:
Structural load requirements span from lightweight fuselage panels to heat-resistant propulsion components, creating distinct performance tiers across metallurgical and non-metallic categories.
- Aluminum:Legacy airframe alloys including 7075-T6 and 2024-T3 retain dominance in transport and tanker sustainment programs. Volume concentrates in United States Air Force depot maintenance contracts where cost-per-flight-hour metrics prioritize proven material economics over weight reduction.
- Titanium:Ti-6Al-4V alloys with tensile strengths exceeding 900 MPa anchor fighter engine mounts, landing gear forgings, and empennage structures where thermal cycling resistance determines operational lifespan. Pentagon domestic sourcing mandates for titanium sponge are accelerating United States smelter capacity expansion.
- Steel:High-strength low-alloy grades and precipitation-hardening martensitic steels serve armored cockpit enclosures and carrier-based arresting hook assemblies.
- Composite:Carbon fiber reinforced polymers cured under autoclave pressure cycles exceeding 100 psi enable wing skin integration of radar-absorbent geometries with primary load-bearing functions.
Established volume favors aluminum; emerging adoption favors titanium and composite formulations in next-generation platforms.
Application:
Airframe engineering teams allocate material budgets according to stress concentration zones and signature management priorities rather than uniform platform-wide specifications.
- Fuselage:Semi-monocoque aluminum structures with longitudinal stringers and circumferential frames retain cost efficiency in legacy bomber and transport categories. F-15 and F-16 sustainment contracts specify 2024-T3 clad sheet for corrosion resistance in pressurized cabin sections.
- Wing Structure:Carbon fiber prepreg formulations dominate sixth-generation fighter wing boxes where radar cross-section reduction and fuel fraction optimization converge. Lockheed Martin and Boeing procurement teams specify bismaleimide resin systems for elevated-temperature wing leading edges.
- Avionics:Thermal management substrates and electromagnetic shielding enclosures utilize copper-beryllium alloys and nickel-iron soft magnetic materials.
- Landing Gear:300M ultra-high-strength steel and Ti-10V-2Fe-3Al alloys withstand sink-rate impacts exceeding 10 feet per second during carrier arrested landings.
Platform sustainment economics favor fuselage aluminum; stealth and performance specifications favor composite wing structures.
End User:
Procurement authority and qualification timelines fragment across institutional buyers with divergent technical oversight capabilities and budgetary constraints.
- Military:United States Air Force Material Command and Naval Air Systems Command establish material specifications through MIL-STD-810 environmental testing protocols. Service-level engineering authorities prioritize domestic supply chain resilience over unit cost minimization.
- Defense Contractors:Tier-1 integrators including Lockheed Martin, Boeing, and Northrop Grumman consolidate supplier relationships through multi-year material offtake agreements. These entities intermediate between raw material processors and platform-specific fabrication requirements.
- OEMs:Engine manufacturers Pratt & Whitney and General Electric Aviation specify superalloy compositions and thermal barrier coating chemistries for propulsion system applications.
- Government Agencies:Defense Advanced Research Projects Agency and Air Force Research Laboratory fund exploratory material development through Small Business Innovation Research contracts.
Operational risk tolerance distinguishes military direct procurement from contractor-mediated sourcing; research agencies occupy pre-qualification discovery roles.
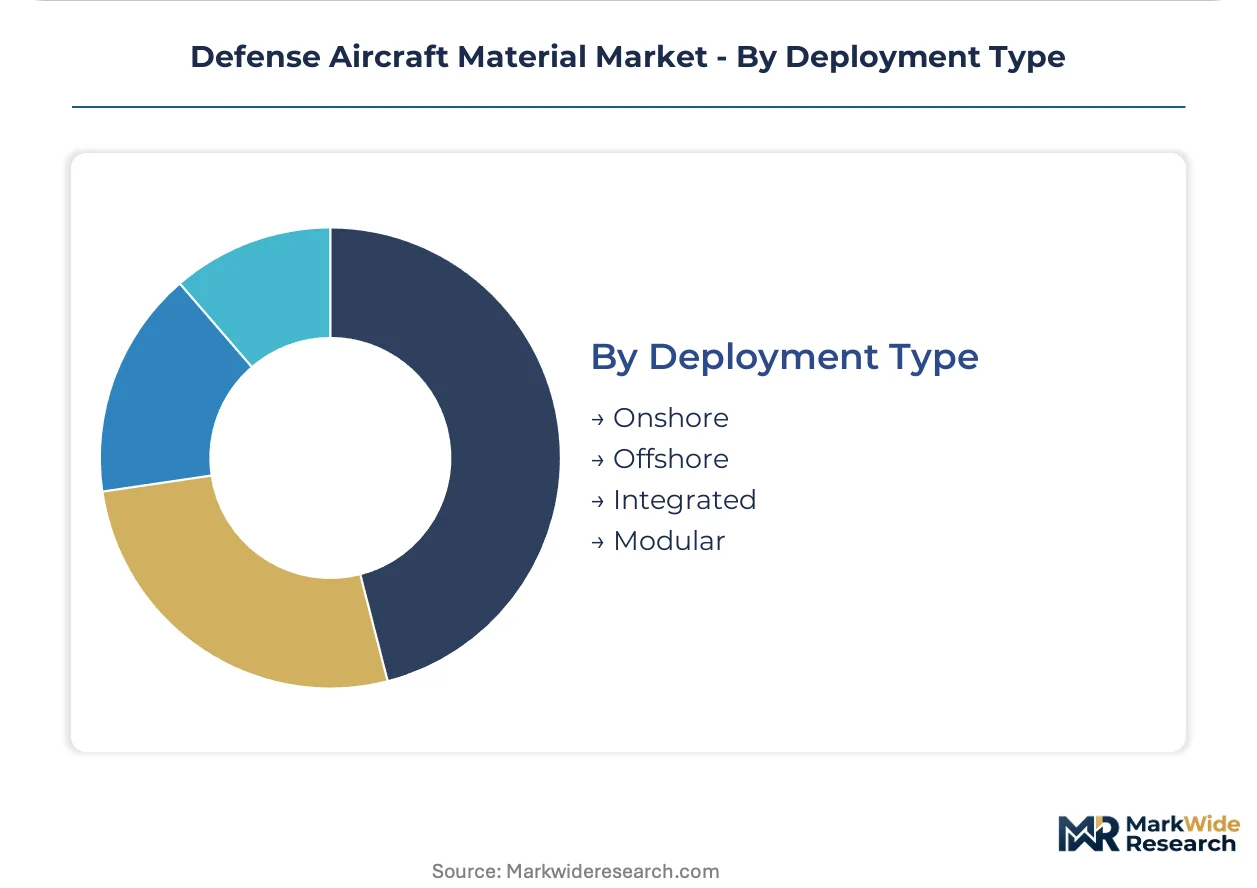
Deployment Type:
Supply chain configuration and fabrication site selection respond to security classification requirements and proximity to final assembly operations.
- Onshore:Pentagon acquisition directives mandate domestic sourcing thresholds for critical minerals including titanium sponge and rare earth elements. ITAR-controlled composite prepreg formulations require United States-personnel access restrictions.
- Offshore:Limited qualification exceptions exist for allied nation specialty alloy processors under reciprocal defense procurement agreements.
- Integrated:Captive forging and heat-treatment capabilities at Boeing's Auburn facility and ATI's Albany operations consolidate metallurgical processing under prime contractor vertical control.
- Modular:Pre-cured composite panel subassemblies ship to final integration lines, reducing autoclave capacity bottlenecks at airframe assembly sites.
Security classification intensity favors onshore and integrated configurations; capital efficiency considerations sustain modular subassembly strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense aircraft material consumption patterns diverge sharply between United States procurement focused on domestic supply chain security and European demand shaped by REACH regulatory chemistry restrictions.
United States
Pentagon acquisition directives mandate domestic sourcing thresholds for titanium sponge and rare earth elements, accelerating smelter capacity expansion in Utah and Nevada. The FAA administers military airworthiness certifications through delegated authority agreements with the Department of Defense. Boeing's Auburn facility and ATI's Albany operations anchor Pacific Northwest metallurgical processing under prime contractor vertical control.
United Kingdom
Royal Air Force Tempest sixth-generation fighter development drives qualified supplier demand for carbon fiber prepreg and stealth-grade composite formulations. UK Ministry of Defence procurement frameworks emphasize sovereign capability retention in critical aerospace supply chains. BAE Systems facilities in Lancashire and Samlesbury concentrate composite wing structure fabrication for multinational combat air programs.
Germany
Luftwaffe Tornado replacement and FCAS participation sustain alloy procurement for fighter airframe and propulsion applications. EASA REACH restrictions on hexavalent chromium surface treatments force adoption of trivalent chromium alternatives across Airbus Defence and Space platforms. Munich and Hamburg industrial clusters host specialty coating qualification laboratories serving continental defense programs.
France
Dassault Aviation Rafale export contracts and SCAF next-generation fighter development concentrate demand for titanium forgings and thermoplastic composites. French defense procurement agency DGA enforces European content requirements through offset agreements with allied nations. Toulouse and Bordeaux aerospace corridors integrate material processing with final assembly operations for combat and surveillance platforms.
Japan
Japan Air Self-Defense Force F-X indigenous fighter program qualifies domestic suppliers for carbon fiber reinforced polymers and advanced titanium alloys. METI industrial policy directs capital toward aerospace material capabilities through joint public-private development consortia. Nagoya and Komaki manufacturing zones concentrate Toray Industries composite production for military and commercial airframe applications.
Defense Aircraft Material Market Vendor Landscape
Capability concentration sits with integrated prime contractors commanding captive forging and composite processing assets; scale advantage sits with specialized material processors serving multiple platform programs. The vendor base stratifies across three tiers: Tier-1 integrators with vertical metallurgical control, qualified domestic composite houses under long-term offtake agreements, and commodity alloy distributors serving sustainment markets. Dominant competitive moves include multi-year material service agreements displacing spot purchasing, and strategic consolidation of supplier relationships through exclusive qualification pathways.
Among United States-based prime contractors, Boeing, Lockheed Martin, and Northrop Grumman occupy positions as anchor customers consolidating procurement leverage through integrated supply chain control. These entities exemplify the Tier-1 integrator archetype, intermediating between raw material processors and platform-specific fabrication requirements while mandating domestic sourcing thresholds for critical aerospace inputs.
| Leading Market Players |
|---|
| Boeing |
| Lockheed Martin |
| Northrop Grumman |
| Raytheon Technologies |
| Hexcel Corporation |
| Allegheny Technologies Incorporated |
| Toray Industries |
| Constellium |
| Solvay |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific container freight corridors connecting titanium sponge producers in Japan to United States alloy processors impose cost volatility that amplifies price differentiation between domestic and imported feedstock, concentrating procurement leverage with prime contractors who command captive smelter capacity and long-term offtake structures.
Pricing Analysis
Long-term material service agreements now dominate fighter program procurement, displacing spot purchasing for Ti-6Al-4V titanium alloys and carbon fiber prepreg formulations. Price differentiation separates ITAR-qualified domestic sources from allied-nation suppliers facing extended qualification timelines, with cost compression in aluminum sustainment tiers intensifying as legacy platform budgets prioritize flight-hour economics over weight reduction. United States Air Force depot maintenance contracts exhibit highest price sensitivity; sixth-generation stealth-grade composite specifications show lowest sensitivity due to sole-source qualification requirements.
Supply Chain Analysis
Titanium sponge feedstock concentrates in Japan, Russia, and Kazakhstan, creating input dependencies for United States alloy processors serving Pentagon programs. Carbon fiber precursor acrylonitrile and rare earth elements for high-temperature alloys draw from concentrated East Asian chemical production. Single-source vulnerability in qualified autoclave capacity for composite curing feeds from limited domestic installation bases. Distribution runs through prime contractor-integrated forging facilities and modular pre-cured panel subassemblies to final assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform modernization cycles fragment demand across sixth-generation fighters, unmanned wingmen, and legacy sustainment, creating specialization niches for qualified material suppliers who escape commodity aluminum pricing pressure.
For Market Incumbents: Pre-empt qualification bottlenecks by expanding captive titanium sponge reduction capacity in Utah and Nevada ahead of Pentagon domestic sourcing mandate enforcement. Consolidate supplier relationships through exclusive prepreg formulation partnerships with Lockheed Martin and Boeing procurement teams. Defend against thermoplastic composite substitution by accelerating bismaleimide resin system certification for elevated-temperature wing applications. For New Entrants and Emerging Players: European coating technology laboratories in Munich and Hamburg present underpenetration opportunities for REACH-compliant trivalent chromium alternatives displacing hexavalent chromium surface treatments. Target Airbus Defence and Space qualification pathways for corrosion protection chemistries in Tornado replacement and FCAS programs. Pursue digital thread certification investments to compress airworthiness documentation timelines for new material entrants. For Investors and Strategic Acquirers: Specialized composite houses with qualified military wing structure portfolios and established FAA-EASA dual certification represent priority acquisition archetypes for portfolio exposure to sixth-generation fighter material demand. Long-term viability hinges on securing multi-year offtake agreements with Tier-1 integrators before program launch windows close. Watch for ITAR export control revision announcements as inflection indicators for transatlantic supplier base fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Titanium Sponge Capacity Expansion | Pentagon sourcing mandates accelerate United States smelter investment ahead of allied-nation qualification restrictions. |
| REACH-Compliant Coating Qualification | EASA enforcement timelines open specification windows for trivalent chromium alternatives at Airbus Defence and Space. |
| Digital Thread Certification Investment | Model-based systems engineering approaches reduce airworthiness documentation burdens for new material entrants. |
| Long-Term Material Service Agreements | Multi-year offtake commitments with Lockheed Martin and Boeing consolidate procurement leverage for qualified suppliers. |
| Thermoplastic Composite Process Development | Out-of-autoclave curing capabilities enable high-rate production environments for sixth-generation fighter programs. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of Department of Defense acquisition directives, FAA airworthiness certification databases, and EASA REACH regulatory filings. Primary interviews engaged program managers at United States Air Force Material Command, procurement executives at Tier-1 defense contractors, technical directors at specialty alloy processors, and composite engineering leads at qualified prepreg suppliers. Secondary sources included Pentagon budget justification materials, MIL-STD-810 environmental testing protocols, trade customs data for titanium sponge and carbon fiber imports, and SEC filings from publicly traded material processors. Bottom-up segment sizing triangulated against top-down defense procurement budget allocations.
Forecast inputs considered fighter jet modernization program timelines, domestic sourcing mandate implementation schedules, and REACH regulatory phase-out deadlines across the analysis window. Segmentation modeling spanned material chemistry tiers, structural application categories, end-user procurement authorities, and deployment type configurations. CAGRs derived from regression analysis of historical defense procurement patterns against platform production rate assumptions. Industry-specific inputs incorporated titanium sponge capacity expansion announcements, autoclave installation pipelines, and thermoplastic composite qualification progressions.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by prime contractors or accelerated EU defense procurement autonomy frameworks would shift outcomes beyond modeled ranges. Cross-checking against Department of Defense Selected Acquisition Reports and NATO defense expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Global Aerospace and Defense Elastomers Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Magnesium Beryllium Alloy Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Aerospace Sealants Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Thermal Spray Coating Market
Aerospace and Aircraft Materials
Aerospace Plastics Market