
 Aerospace Cold Forgings Market | 2026-2036
Aerospace Cold Forgings Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Cold Forgings Market Analysis
Consolidation among tier-1 aerostructures suppliers is repositioning procurement leverage toward vertically integrated airframers. Arconic Corporation leverages its Tennessee and Hungary forging complexes to sustain long-term supply agreements with Boeing and Airbus. Precision Castparts Corporation anchors the high-pressure turbine disk segment through captive titanium melt-to-forge capability. LISI Aerospace competes on fastener system integration, bundling cold-forged bolts with installation tooling and logistics services.
Aerospace cold forgings are net-shape or near-net-shape metal components formed below recrystallization temperature, typically at 0.3 to 0.5 times the material's melting point, to achieve grain flow alignment and fatigue resistance in stress-critical airframe and propulsion applications. The process yields tensile strengths exceeding 1,200 MPa in alloy steels while maintaining dimensional tolerances within ±0.05 mm, making it indispensable for single-aisle jet engine mounts and landing gear trunnions. Titanium alloys dominate material selection for engine components due to their strength-to-density ratio and elevated-temperature performance, while aluminium alloys anchor the airframe fastener segment where weight reduction drives specification. Multi-component assemblies represent the fastest-growing product category as OEMs outsource integrated pylon and wing attachment systems to reduce part count and assembly labor.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements mandate damage tolerance analysis for all primary structure forgings, forcing suppliers to invest in ultrasonic and eddy-current inspection capacity. REACH restrictions on hexavalent chromium surface treatments are accelerating conversion to trivalent chrome and plasma electrolytic oxidation finishes across European supply chains. Stakeholders must monitor evolving EPA and MEE emissions standards for forging lubricants and heat treatment atmospheres, as compliance costs will determine which mid-size forgers retain airframe qualification.
Market Dynamics
Consolidation among tier-1 aerostructures suppliers is compressing procurement leverage toward vertically integrated airframers with captive forging capacity. Boeing and Airbus now specify integrated pylon and wing attachment systems rather than discrete components, forcing mid-size forgers to invest in multi-component assembly capability or exit airframe qualification.
Growth Catalysts
- FAA Part 25 Damage Tolerance Mandates:Airworthiness standards for primary structure forgings are accelerating ultrasonic and eddy-current inspection capacity investment across the supply base.
- Titanium Alloy Fastener Demand:Commercial aircraft OEMs are expanding procurement for next-generation narrowbody programs, concentrating orders in the United States Pacific Northwest aerospace manufacturing cluster.
- REACH Hexavalent Chromium Phase-Out:European supply chains are converting to trivalent chrome and plasma electrolytic oxidation finishes, creating specification refresh cycles.
Market Restraints
- Titanium Sponge Price Volatility:Input cost swings for aerospace-grade titanium sponge compress margin predictability for independent forgers without captive melt capacity.
- United States Pacific Northwest Supply Concentration:Geographic clustering of qualified forging capacity creates single-point-of-failure exposure for Boeing supply chains.
- Reciprocating Engine Component Substitution:Additive manufacturing is displacing certain legacy cold-forged turbine blade roots in small engine applications.
Strategic Opportunities
- Urban Air Mobility Airframe Attachments:Emerging eVTOL manufacturers in the United States are sourcing lightweight titanium pylon fittings outside traditional aerospace qualification pathways.
- EPA Forging Lubricant Emissions Standards:Compliance-driven equipment refresh cycles are creating entry points for forgers with advanced heat treatment atmosphere controls.
- Digital Twin Process Simulation:Convergence of finite element modeling with real-time forging press telemetry is enabling first-article qualification acceleration.
Industry Challenges
- Ultrasonic Inspection Technician Scarcity:FAA-mandated Level III NDT certification timelines stretch 18-24 months, constraining capacity expansion.
- Legacy ERP Integration with MES:Shop-floor digitalization for AS9100 traceability requirements demands capital outlays that mid-size forgers struggle to amortize.
- Dual Certification Synchronization:Simultaneous FAA and EASA qualification timelines for new forging lines compress program launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Cold Forgings Market |
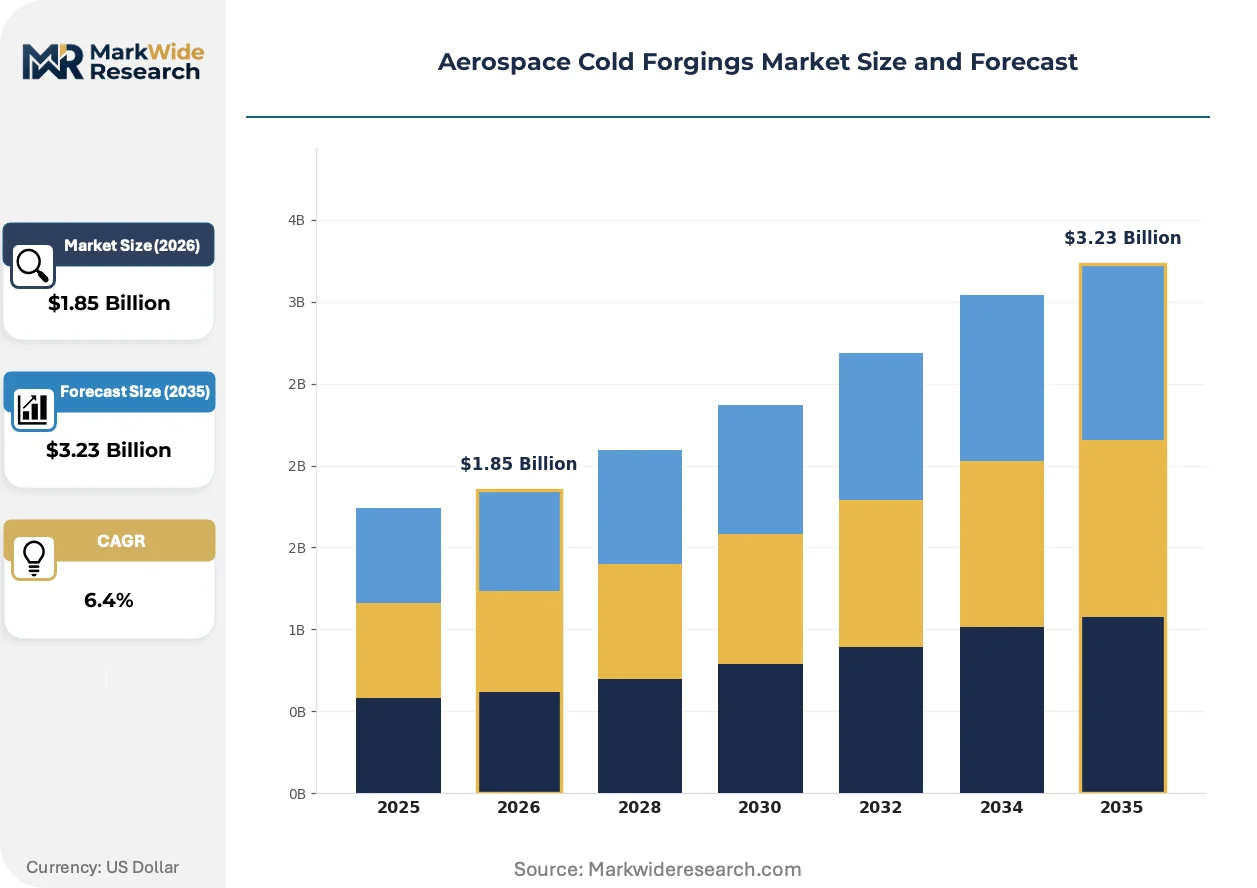
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolts, Nuts, Shackles, Multi-Component Assemblies Material: Aluminium Alloys, Titanium Alloys, Stainless Steel, Nickel Alloys Application: Aerospace Structures, Engine Components, Landing Gear, Control Surfaces End User: Aircraft Manufacturers, Defense Contractors, Maintenance Providers, Tier-1 Suppliers |
| Companies Covered | Arconic Corporation, Allegheny Technologies Incorporated, Precision Castparts Corporation, Howmet Aerospace, LISI Aerospace, Bharat Forge, Otto Fuchs KG, Kobe Steel, VSMPO-AVISMA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Cold Forgings Market Emerging Trajectories
Process digitalization and material specification convergence are compressing traditional qualification timelines while expanding performance envelopes for stress-critical applications.
Plasma electrolytic oxidation surface treatment is absorbing hexavalent chromium conversion coating volume in European fastener supply chains. Arconic Corporation and LISI Aerospace are qualifying trivalent chrome alternatives for Boeing 737 MAX and Airbus A320neo programs. This technology is absorbing approximately one-third of legacy chromate specification volume, forcing coating equipment suppliers to retool anodizing line configurations.
EASA CS-25 certification harmonization with FAA Part 25 damage tolerance requirements is tightening material traceability standards for fatigue-critical components. European forgers must now implement lot-controlled titanium melt records back to sponge source. The high-pressure turbine disk segment is responding by consolidating supplier audits and rejecting dual-source qualification for non-captive melt-to-forge operations.
Airframer direct sourcing of integrated pylon assemblies is disintermediating tier-2 fastener distributors. Boeing's 2024 supplier consolidation initiative bundles cold-forged bolts with installation tooling and logistics services under single-source agreements. This pattern is most visible in the United States Pacific Northwest, where Precision Castparts Corporation and Arconic Corporation have captured multi-year pylon attachment contracts previously fragmented across five discrete suppliers.
Aerospace Cold Forgings Market Segmentation
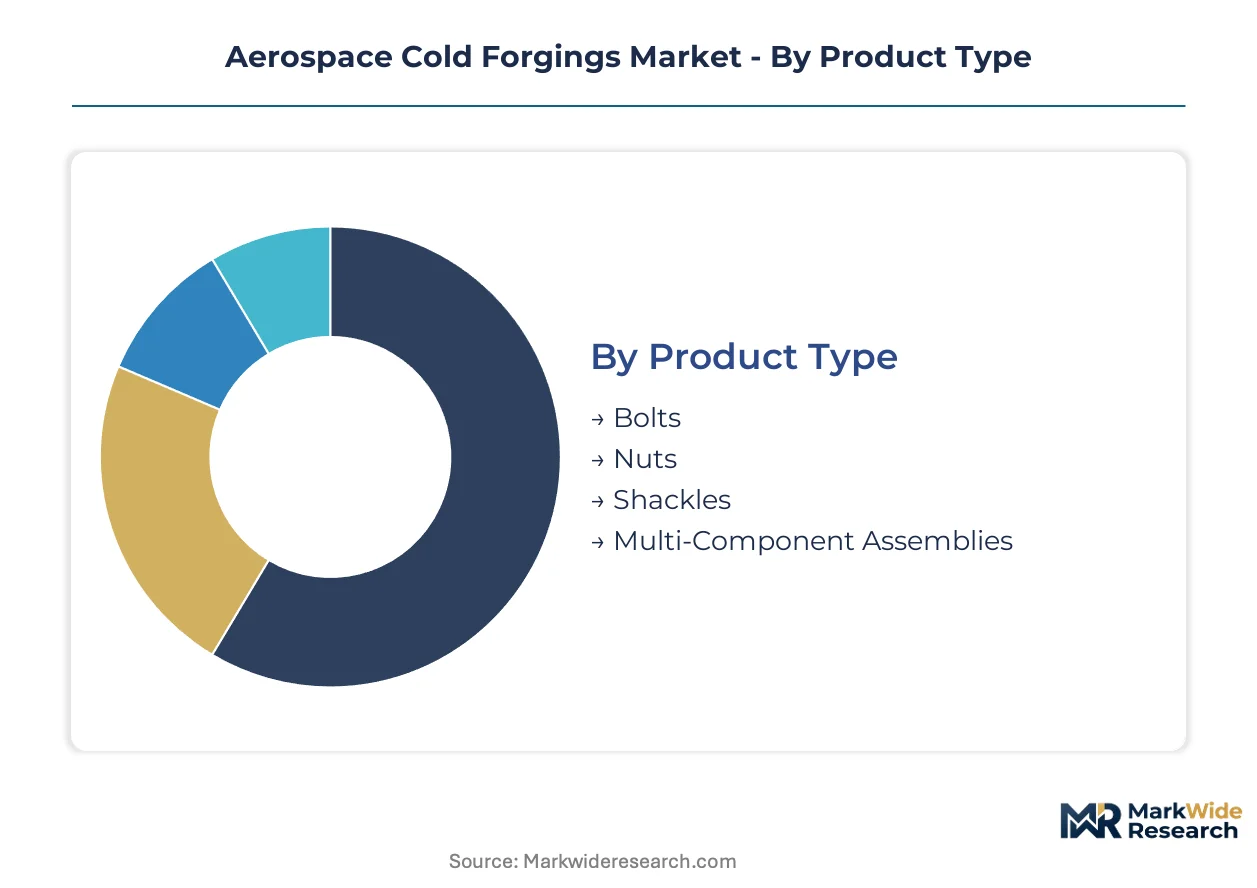
Cold-forged aerospace components serve distinct functional roles across airframe and propulsion systems, with material selection and assembly complexity determining procurement patterns and qualification pathways. Segmentation reveals where specification authority concentrates and how OEM consolidation is reshaping supplier tiering.
Product Type:
Standalone fasteners dominate discrete procurement, while multi-component assemblies embed deeper into airframer direct-sourcing strategies.
- Multi-Component Assemblies:Integrated pylon and wing attachment systems combine cold-forged bolts with brackets and bushings into single-source deliverables. Boeing and Airbus now specify these bundles under consolidated supplier agreements, displacing tier-2 distributors in the United States Pacific Northwest cluster.
- Bolts:Titanium alloy fasteners for next-generation narrowbody programs anchor the highest-volume procurement lane, with fatigue-critical specifications mandating ultrasonic inspection traceability under FAA Part 25 damage tolerance standards.
- Nuts:Self-locking collar configurations for engine mounts and structural joints.
- Shackles:Load-bearing connectors for cargo handling and emergency release systems.
Bolts lead volumes today; multi-component assemblies are gaining share fastest.
Material:
Cost tiers separate commodity aluminium from premium titanium, with nickel alloys occupying a narrow high-temperature niche.
- Titanium Alloys:Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr grades deliver strength-to-density ratios exceeding 250 kN·m/kg for high-pressure turbine disks and engine mounts. Captive melt-to-forge operations at Precision Castparts Corporation and Arconic insulate against sponge price volatility.
- Aluminium Alloys:7075-T73 and 2024-T4 specifications dominate airframe fastener applications where weight reduction outweighs temperature performance. REACH hexavalent chromium restrictions are forcing trivalent chrome conversion across European supply chains.
- Stainless Steel:A286 and 17-4PH grades for corrosion-critical landing gear and control surface attachments.
- Nickel Alloys:Inconel 718 and Waspaloy for exhaust nozzles and hot-section brackets.
Aluminium alloys anchor current procurement volumes; titanium alloys are climbing the fastest as engine thrust-to-weight ratios tighten.
Application:
Maturity gradients separate legacy airframe programs from next-generation propulsion investments.
- Engine Components:High-pressure turbine disks, compressor blades, and mounting trunnions demand grain-flow alignment for 10^7 cycle fatigue life. EASA CS-25 harmonization with FAA standards is tightening material traceability to sponge source for this segment.
- Aerospace Structures:Fuselage frame clips, wing ribs, and stringer attachments constitute the broadest specification base. Urban air mobility manufacturers in the United States are sourcing titanium pylon fittings outside traditional qualification pathways.
- Landing Gear:Trunnions and torque links for main and nose gear assemblies.
- Control Surfaces:Hinge fittings and actuator mounts for ailerons, elevators, and rudders.
Aerospace structures command the widest supplier base; engine components are expanding most quickly through narrowbody re-engining programs.
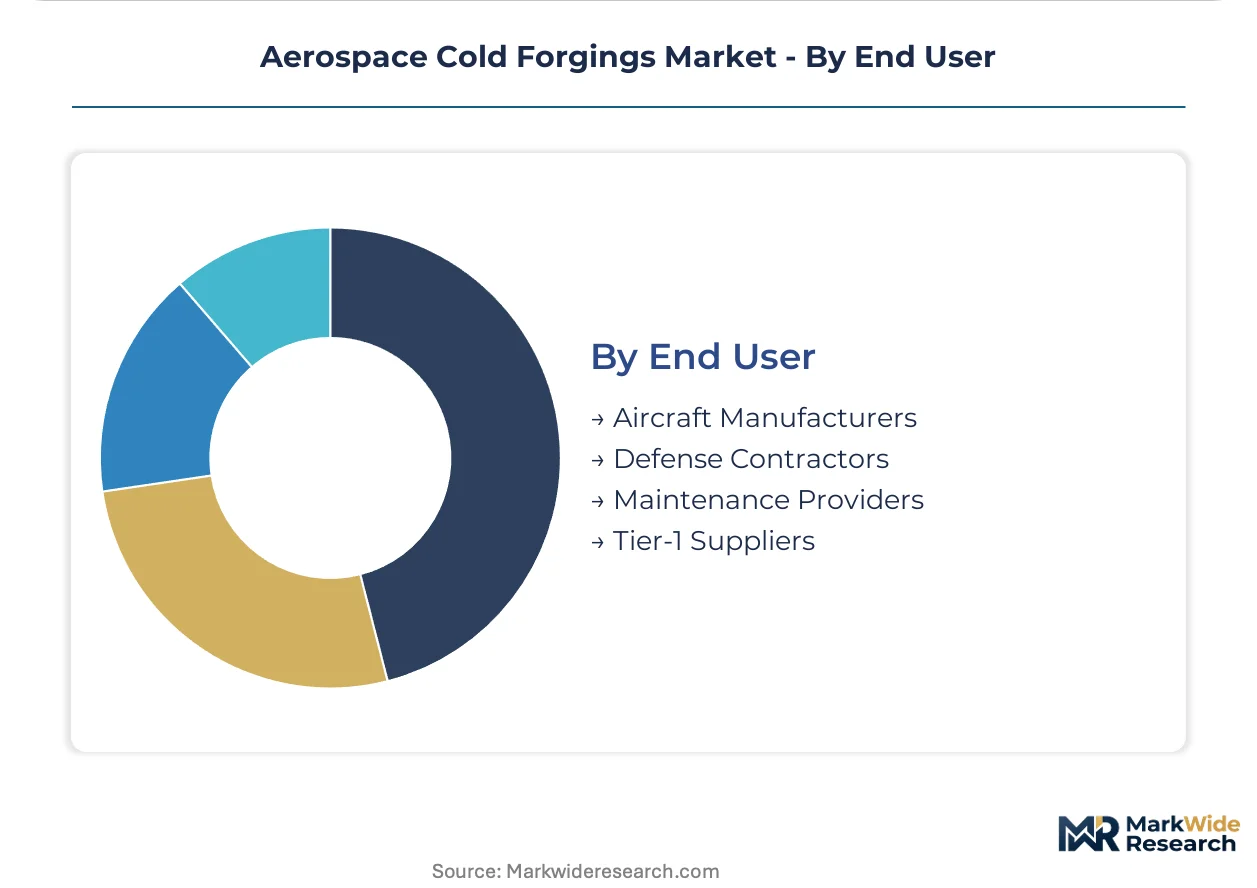
End User:
Customer type determines contract structure, with airframers consolidating leverage and MRO channels fragmenting.
- Aircraft Manufacturers:Boeing and Airbus direct-sourcing of integrated assemblies bundles cold-forged hardware with installation tooling and logistics services. Long-term agreements now span 7-10 years with penalty clauses for qualification delays.
- Tier-1 Suppliers:Spirit AeroSystems and GKN Aerospace intermediate discrete fastener procurement for subassemblies, though their consolidation is compressing supplier margins.
- Defense Contractors:Lockheed Martin and Northrop Grumman sustain lower-volume, higher-mix programs with longer qualification timelines.
- Maintenance Providers:MRO channels for fleet replacement fasteners operate on spot-buy and distribution agreements.
Aircraft manufacturers concentrate procurement authority; tier-1 suppliers are losing share to direct airframer engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates aerospace forging capacity in the Pacific Northwest while France anchors European turbine disk qualification, creating divergent supply chain geometries for narrowbody and widebody programs.
United States
Boeing's direct-sourcing consolidation and next-generation narrowbody development drive titanium fastener procurement in Washington State. FAA Part 25 damage tolerance mandates enforce ultrasonic inspection traceability across the supply base. The Puget Sound cluster hosts Precision Castparts Corporation and Arconic Corporation forging complexes serving 737 MAX and 777X programs.
France
Airbus A320neo and A350 production rates determine forging demand for engine mounts and wing attachments. EASA CS-25 certification harmonization with FAA standards tightens material traceability to sponge source for fatigue-critical components. The Toulouse-Blagnac aerospace corridor concentrates LISI Aerospace fastener integration facilities and supplier qualification authority.
Germany
MTU Aero Engines and Rolls-Royce Deutschland sourcing patterns shape high-pressure turbine disk specifications. REACH hexavalent chromium restrictions accelerate trivalent chrome conversion across Bavarian and Baden-Württemberg supply chains. The Munich-Stuttgart industrial axis hosts Otto Fuchs KG forging operations with captive heat treatment capacity.
Japan
SpaceJet program suspension and renewed F-X fighter development redirect forging capacity toward defense applications. METI industrial standards govern titanium alloy specification for propulsion components. The Nagoya aerospace cluster maintains Kobe Steel forging press capacity serving Mitsubishi Heavy Industries and IHI Corporation.
Russia
Import substitution programs and sanctions exposure reconfigure titanium sponge-to-forge supply chains for domestic airframe programs. Rosaviatsia certification requirements diverge from EASA harmonization timelines. The Sverdlovsk Oblast hosts VSMPO-AVISMA Corporation vertical integration from sponge production through forged billet output.
Aerospace Cold Forgings Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base clusters around three strategic archetypes: vertically integrated titanium melters, multi-metal forging houses with captive heat treatment, and fastener system integrators bundling hardware with logistics services. Consolidation among tier-1 aerostructures suppliers compresses procurement leverage toward airframers with captive forging capacity. Dominant competitive moves include multi-year supply agreement renegotiation and qualification line investment for integrated assembly capability.
Among North American diversified metalworkers, Arconic Corporation and Precision Castparts Corporation exemplify the captive melt-to-forge archetype insulating against titanium sponge volatility. Howmet Aerospace occupies a position within the engine component tier through aerospace casting and forging integration. LISI Aerospace represents the European fastener system integrator model competing on bundled hardware and installation tooling services.
| Leading Market Players |
|---|
| Arconic Corporation |
| Allegheny Technologies Incorporated |
| Precision Castparts Corporation |
| Howmet Aerospace |
| LISI Aerospace |
| Bharat Forge |
| Otto Fuchs KG |
| Kobe Steel |
| VSMPO-AVISMA Corporation |
| Others |
Supply Flow & Price Mechanics
Boeing and Airbus direct-sourcing consolidation in the United States Pacific Northwest anchors contract-based long-term offtake as the dominant pricing model, with multi-year agreements bundling cold-forged hardware with installation tooling and logistics services. This buyer concentration compresses margin predictability for independent forgers lacking captive titanium melt capacity while rewarding vertically integrated suppliers with qualification leverage.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for aerospace-grade titanium forgings as Otto Fuchs KG and Kobe Steel expand heat treatment atmosphere controls. Three-tier pricing structure across premium, standard, and economy levels separates FAA-EASA dual-certified titanium alloys from single-jurisdiction qualifications and commodity aluminium fasteners. Pricing pressure stems from titanium sponge volatility and REACH compliance costs, with tier-2 distributors most price-sensitive and airframer direct-sourcing least sensitive due to penalty clauses for qualification delays.
Supply Chain Analysis
Ultrasonic inspection technician scarcity in Washington State, Bavaria, and the Toulouse-Blagnac corridor constrains qualified forging capacity expansion across the United States, Germany, and France. The supply chain draws from aerospace-grade titanium sponge, alloy steel billets, and trivalent chrome conversion chemistries. Single-source vulnerability concentrates in the United States Pacific Northwest cluster where Boeing supply chains face geographic concentration risk. Distribution runs through airframer direct-sourcing agreements and tier-1 aerostructures supplier consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between the United States Pacific Northwest and European supply chains, where EASA REACH compliance costs exceed FAA-equivalent outlays by margins that reward dual-qualified forgers with cost-advantaged production footprints.
For Market Incumbents: Acquire captive titanium melt-to-forge operations to insulate against sponge price volatility threatening independent forgers. Expand ultrasonic and eddy-current inspection capacity to meet FAA Part 25 damage tolerance mandates before tier-2 competitors secure qualification slots. Consolidate multi-component assembly capability to capture Boeing and Airbus direct-sourcing bundles displacing discrete fastener distributors. For New Entrants and Emerging Players: Digital twin process simulation offers entry into urban air mobility airframe attachments where eVTOL manufacturers source outside traditional aerospace qualification pathways. Target EPA forging lubricant emissions compliance as a service wedge, selling advanced heat treatment atmosphere controls to mid-size forgers facing capital constraints. Pursue fastener system integration bundling cold-forged bolts with installation tooling to compete with LISI Aerospace logistics services. For Investors and Strategic Acquirers: Tier-1 aerostructures suppliers are the most active acquirer in this space, compressing procurement leverage toward vertically integrated airframers. Long-term viability favors forgers with captive melt capacity and dual FAA-EASA certification spanning the projection horizon. Monitor titanium sponge price volatility and additive manufacturing substitution rates in small engine applications as inflection indicators for legacy cold-forged component demand.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Titanium Melt-to-Forge Integration | Insulates Precision Castparts Corporation and Arconic Corporation against input cost swings. |
| Multi-Component Assembly Qualification | Enables single-source capture of Boeing 737 MAX and Airbus A320neo pylon attachment contracts. |
| Digital Twin Process Simulation Investment | Accelerates first-article qualification timelines for EASA CS-25 harmonization requirements. |
| Trivalent Chrome Surface Treatment Conversion | Addresses REACH hexavalent chromium phase-out across European fastener supply chains. |
| Ultrasonic Inspection Capacity Expansion | Responds to FAA-mandated Level III NDT certification constraints stretching 18-24 months. |
Methodological Framework
Multiple input streams — primary interviews with forging plant managers, aerospace OEM procurement leads, and NDT certification specialists; secondary validation through FAA airworthiness directives, EASA CS-25 certification databases, and SEC filings from tier-1 aerostructures suppliers; customs and trade data on titanium sponge flows — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Data-stream reconciliation applied analytical frameworks across the analysis window, modeling cold-forged aerospace components by product type, material grade, application function, and end-user procurement tier. CAGRs were derived from production rate assumptions for next-generation narrowbody programs and re-engining cycles, cross-referenced with airframer direct-sourcing consolidation patterns and REACH regulatory compliance cost trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to titanium sponge price volatility, additive manufacturing substitution rates in small engine applications, and EPA forging lubricant emissions standard enforcement timelines. Practitioners should monitor urban air mobility certification pathway divergence and tier-1 aerostructures supplier bankruptcy filings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aviation Carbon Fiber Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Europe Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Aviation Titanium Alloy Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Global Aerospace Insulation Market