
 Global Endovenous Ablation Devices Market | 2026-2036
Global Endovenous Ablation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endovenous Ablation Devices Market Intelligence
Procurement for endovenous ablation devices is pivoting from large hospital systems towards a more fragmented base of ambulatory surgical centers and specialty clinics. This shift favors suppliers with flexible distribution models capable of reaching a diffuse customer base. Medtronic plc leverages its extensive global sales network to serve these diverse accounts. AngioDynamics Inc. specializes in innovative ablation technologies for complex cases, while Biolitec AG differentiates with its focused portfolio of laser-based systems.
Endovenous ablation devices are medical instruments designed to treat venous insufficiency by delivering thermal or non-thermal energy to collapse and close diseased veins. These systems, often guided by ultrasound, use energy sources like radiofrequency or laser with specific wavelengths to achieve vessel occlusion from within the lumen. Radiofrequency ablation devices command a significant share due to their established safety profiles and physician familiarity. While varicose vein treatment remains the dominant application, use in managing chronic venous insufficiency represents a key growth vector.
Market access is governed by stringent regulatory approvals, including the FDA's 510(k) clearance process in the United States and CE marking under the Medical Device Regulation (MDR) in Europe. In China, all devices must comply with NMPA standards, influencing product design and clinical trial requirements. Future competitive advantage depends on navigating these evolving regulatory landscapes while demonstrating superior clinical outcomes and cost-effectiveness for payers.
Market Dynamics
The central structural force shaping the endovenous ablation device market is the decentralization of care from hospitals to ambulatory settings. This shift influences device design toward portability and ease of use, while also fragmenting the customer base for suppliers.
Growth Catalysts
- Favorable Demographics:Aging populations in developed countries like Germany and Japan, coupled with rising obesity rates, are expanding the patient pool for venous insufficiency, directly increasing procedure volumes for minimally invasive treatments.
- Regulatory Harmonization:The EU's Medical Device Regulation (MDR) provides a unified framework for market access, compelling manufacturers to meet higher safety and performance standards, which in turn builds physician and patient confidence across member states.
- Clinical Setting Evolution:The expansion of ambulatory surgical centers creates demand for ablation systems with smaller footprints, lower capital costs, and faster procedure turnaround, favoring suppliers who can meet these outpatient-specific requirements.
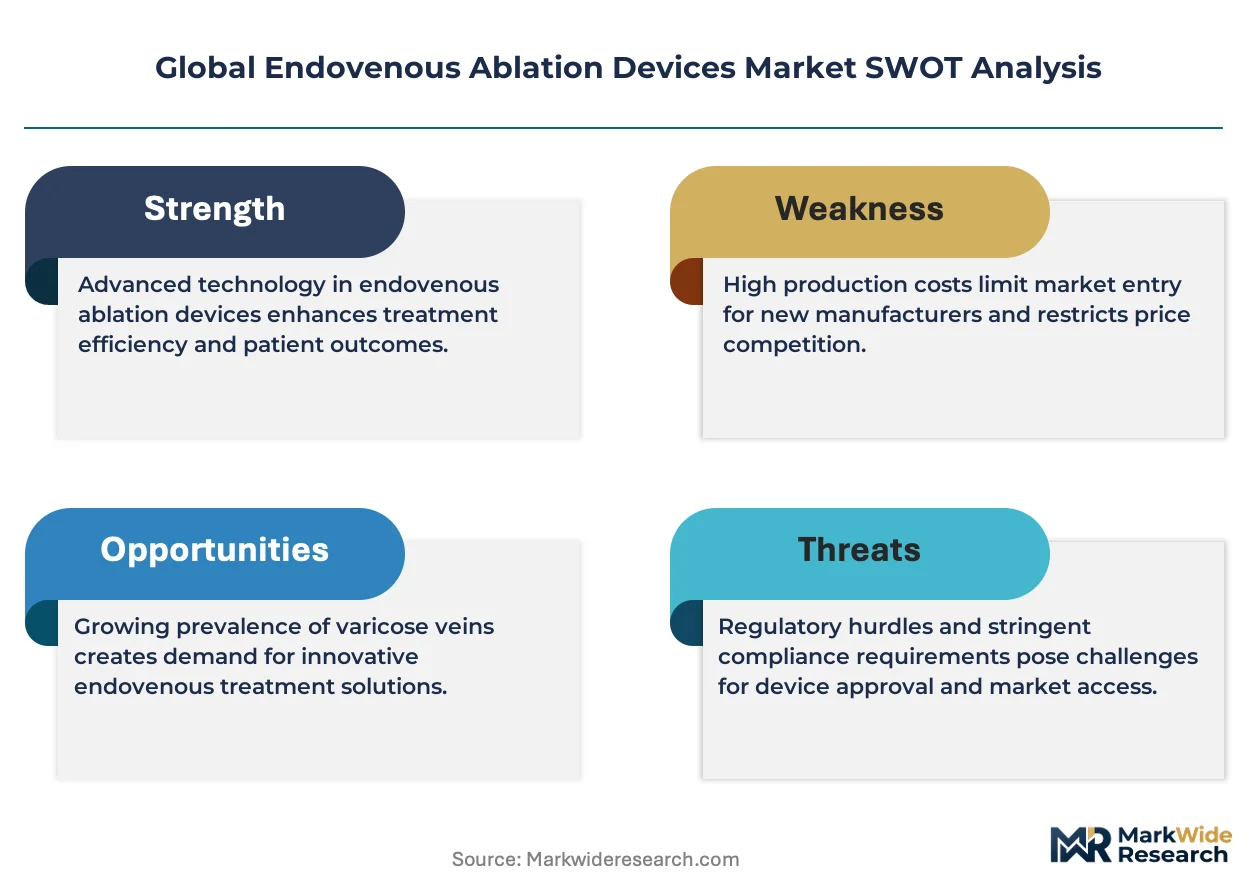
Market Restraints
- High Capital Investment:The initial acquisition cost of radiofrequency or laser generators remains a significant barrier for smaller, independent vein clinics, limiting their ability to offer a full range of thermal ablation services.
- Substitution from Non-Thermal Technologies:The availability of non-thermal, non-tumescent (NTNT) techniques, such as cyanoacrylate adhesive and mechanochemical ablation, presents a competitive alternative that does not require capital equipment or tumescent anesthesia.
- Reimbursement Variability:Inconsistent or declining reimbursement rates for endovenous procedures from public and private payers in certain jurisdictions can deter investment in new technologies and limit patient access.
Strategic Opportunities
- Emerging Market Penetration:Significant opportunities exist in countries like Brazil and Mexico, where a large, untreated population with venous disease coincides with a growing private healthcare sector seeking advanced medical technologies.
- Expansion into New Clinical Applications:Device development focused on treating pelvic congestion syndrome and other non-lower-extremity venous disorders opens new revenue streams beyond traditional varicose vein applications.
- Integration of AI and Robotics:Incorporating artificial intelligence for improved ultrasound image analysis and robotic assistance for precise catheter navigation can enhance procedural consistency and reduce operator dependency.
Industry Challenges
- Specialized Training Requirements:A shortage of vascular surgeons and interventional radiologists with specific training in advanced ablation techniques creates a bottleneck, limiting the rate at which procedures can be performed.
- Navigating Multi-Jurisdictional Approvals:Manufacturers face significant administrative and financial burdens in simultaneously navigating the distinct regulatory pathways of the FDA, EU MDR, and China's NMPA for device clearance.
- Post-Market Surveillance Demands:Increased regulatory scrutiny, particularly under the EU MDR, requires manufacturers to implement extensive and costly post-market clinical follow-up (PMCF) studies to continuously prove device safety and performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endovenous Ablation Devices Market |
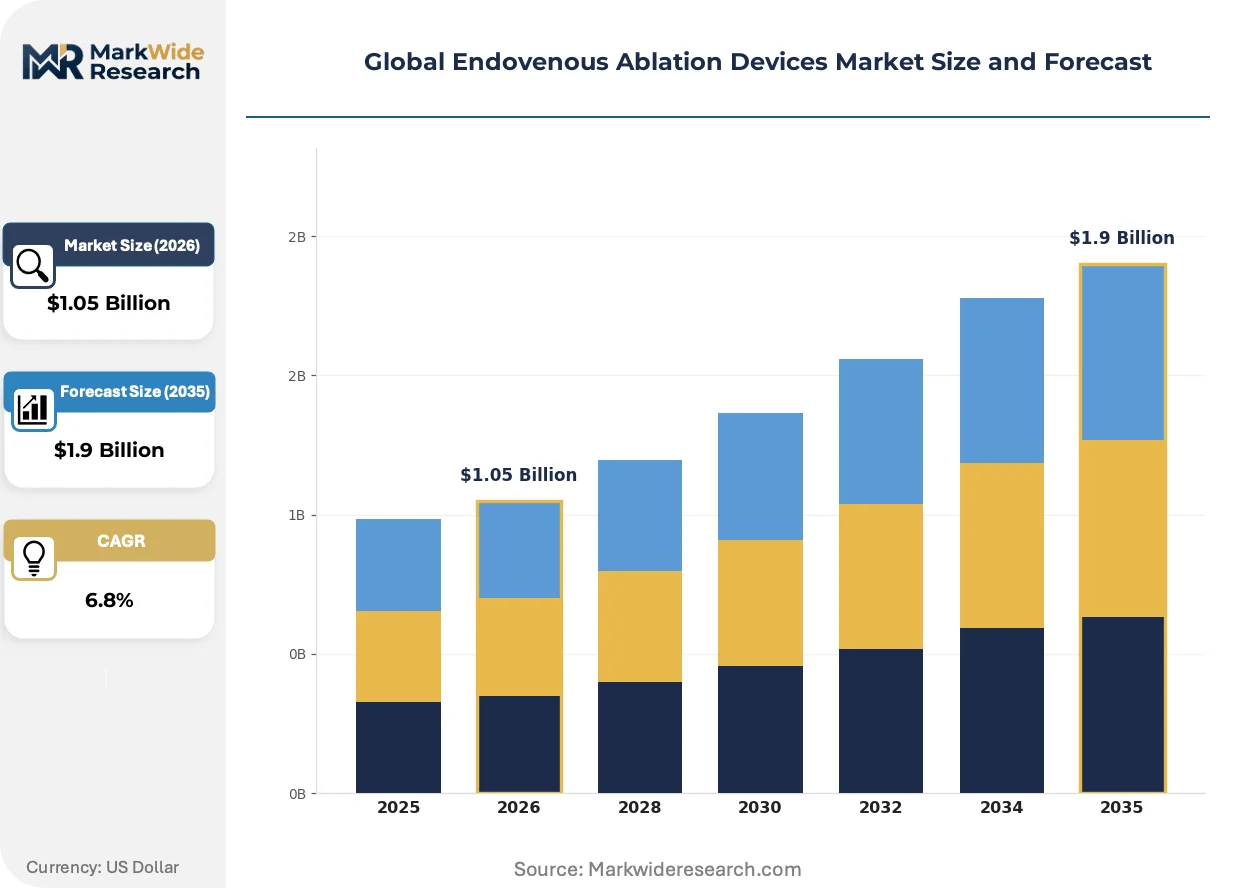
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.9 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency Ablation Devices, Laser Ablation Systems, Mechanochemical Ablation Devices, Ultrasound-Guided Devices Energy Source: Endovenous Laser Therapy, Bipolar Radiofrequency, Monopolar Radiofrequency, Steam Ablation Application: Varicose Vein Treatment, Chronic Venous Insufficiency, Venous Ulcers, Superficial Venous Reflux End User: Phlebologists, Vascular Surgeons, Ambulatory Surgical Centers, Specialty Clinics |
| Companies Covered | Teleflex Incorporated, Venclose Inc., Medtronic plc, Lumenis Ltd., AtriCure Inc., AngioDynamics Inc., Sciton Inc., Biolitec AG, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endovenous Ablation Devices Market Strategic Shifts & Innovations
Technological development is centered on improving procedural efficiency and patient comfort, which is reshaping the competitive landscape. This push aligns with clinical demand for treatments that facilitate faster recovery and can be performed in lower-cost outpatient settings.
Advanced software integration is a defining product evolution. These platforms connect ultrasound imaging, patient records, and ablation generator settings into a single interface for physicians. Ambulatory surgical centers and large vein clinics are adopting these systems to standardize workflows and improve data management. This trend is unifying the entire procedural workflow, from initial diagnosis to post-operative follow-up, onto a single digital backbone.
The European Union's Medical Device Regulation (MDR) is a significant policy shift. It elevates requirements for clinical evidence and post-market surveillance compared to the previous Medical Device Directive (MDD). This change is forcing manufacturers to invest heavily in generating new clinical data for both new and existing devices sold in Europe. The radiofrequency ablation device segment is most affected due to its large installed base of legacy products requiring updated technical files.
A preference for flexible acquisition models is altering purchasing behavior. Instead of large upfront capital expenditures, many new specialty clinics and physician-owned labs prefer pay-per-procedure or leasing arrangements for ablation generators and catheters. This disrupts the traditional sales model, favoring suppliers who can offer adaptable financial terms. This shift is most prominent in the United States, where the number of independent outpatient vascular centers is growing.
Global Endovenous Ablation Devices Market Segmentation
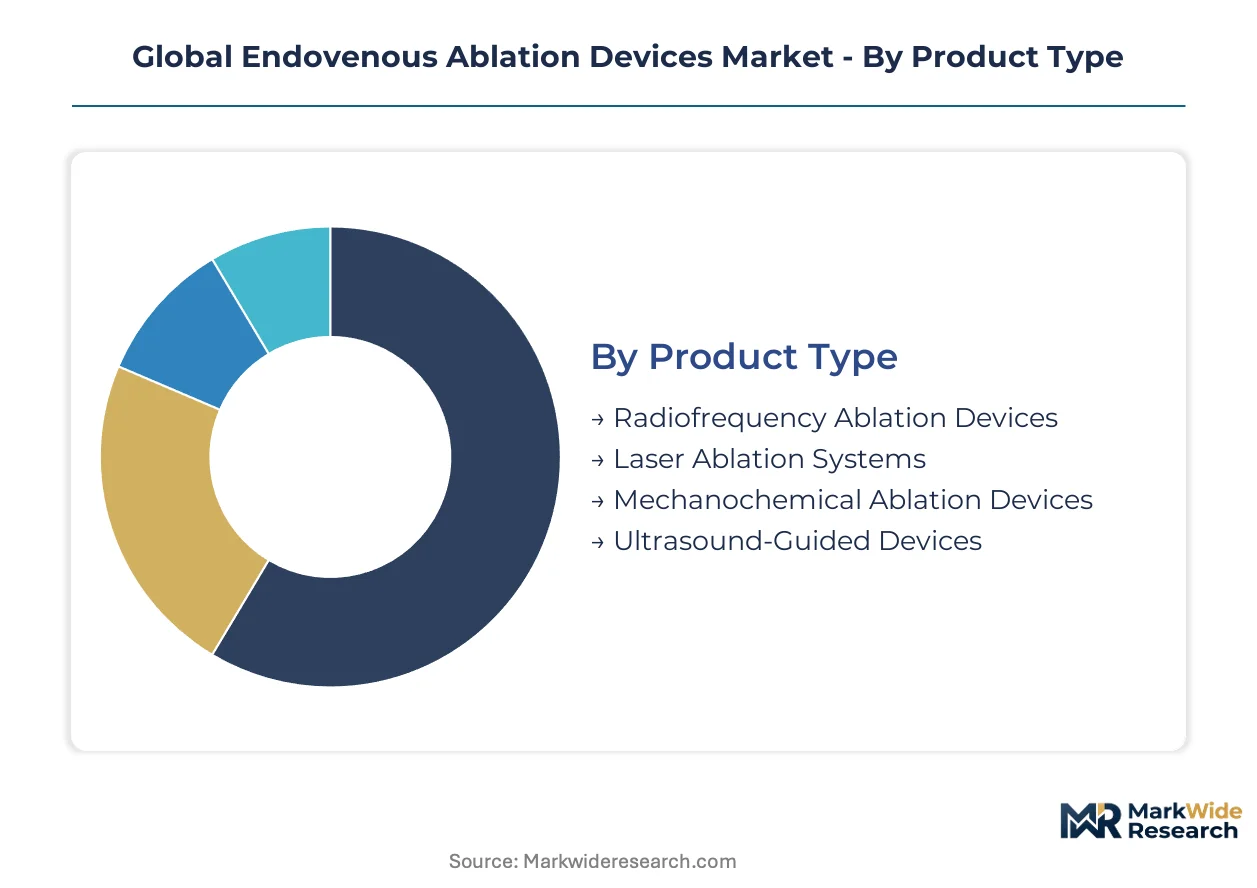
Understanding the endovenous ablation devices market requires granular analysis across product types, energy sources, applications, and end users. This segmentation illuminates where innovation is concentrated and how diverse clinical needs drive product development. Each segment reflects distinct technological preferences and operational requirements within venous care.
Product Type:
Product type segmentation highlights the trade-offs between established high-volume solutions and specialized premium technologies.
- Radiofrequency Ablation Devices:These systems use electrical current to generate heat, occluding diseased veins from within. Demand concentrates in ambulatory surgical centers across the United States, driven by established safety profiles and physician familiarity with the technology.
- Laser Ablation Systems:Laser ablation devices employ specific light wavelengths to deliver thermal energy, causing vein collapse. Germany and other European markets show strong adoption, supported by clinical evidence for efficacy in complex cases and manufacturer specialization.
- Mechanochemical Ablation Devices:Mechanochemical devices combine mechanical disruption with chemical sclerosant for vein closure, offering a non-thermal option.
- Ultrasound-Guided Devices:These devices integrate ultrasound imaging for precise catheter placement and real-time procedural monitoring during ablation.
Today's leader: Radiofrequency Ablation Devices. Tomorrow's challenger: Mechanochemical Ablation Devices.
Energy Source:
Energy source differentiation directly correlates with specific procedural techniques and patient comfort considerations.
- Endovenous Laser Therapy:This therapy utilizes a laser fiber inserted into the vein to deliver focused heat, causing irreversible vein wall damage. Adoption remains strong in specialty clinics seeking precise energy delivery for various vein sizes.
- Bipolar Radiofrequency:Bipolar radiofrequency systems deliver energy between two electrodes on the catheter tip, limiting thermal spread to surrounding tissues. This method sees significant use in outpatient settings due to its controlled heating and reduced risk profile.
- Monopolar Radiofrequency:Monopolar radiofrequency uses a single electrode with a grounding pad, delivering energy through the patient's body.
- Steam Ablation:Steam ablation introduces superheated water vapor into the vein, collapsing it through thermal energy.
Bipolar Radiofrequency is gaining share fastest, while Steam Ablation is expanding its niche.
Application:
Application segmentation reflects the spectrum of venous disorders, from common conditions to more complex pathological presentations.
- Varicose Vein Treatment:This application addresses enlarged, twisted veins, primarily in the legs, using ablation to close the diseased vessel. Demand is widespread globally, particularly in countries with aging demographics like Japan and Germany.
- Chronic Venous Insufficiency:Chronic venous insufficiency treatment targets impaired vein valves leading to blood pooling and symptoms like swelling and skin changes. This represents a key growth vector, particularly in regions with high obesity rates.
- Venous Ulcers:Venous ulcers, severe skin lesions caused by prolonged venous hypertension, are managed through targeted ablation of underlying diseased veins.
- Superficial Venous Reflux:Superficial venous reflux involves faulty valves in surface veins, often treated to alleviate symptoms and prevent progression to more severe disease.
Varicose Vein Treatment represents a mature segment, while Chronic Venous Insufficiency drives future procedural volume.
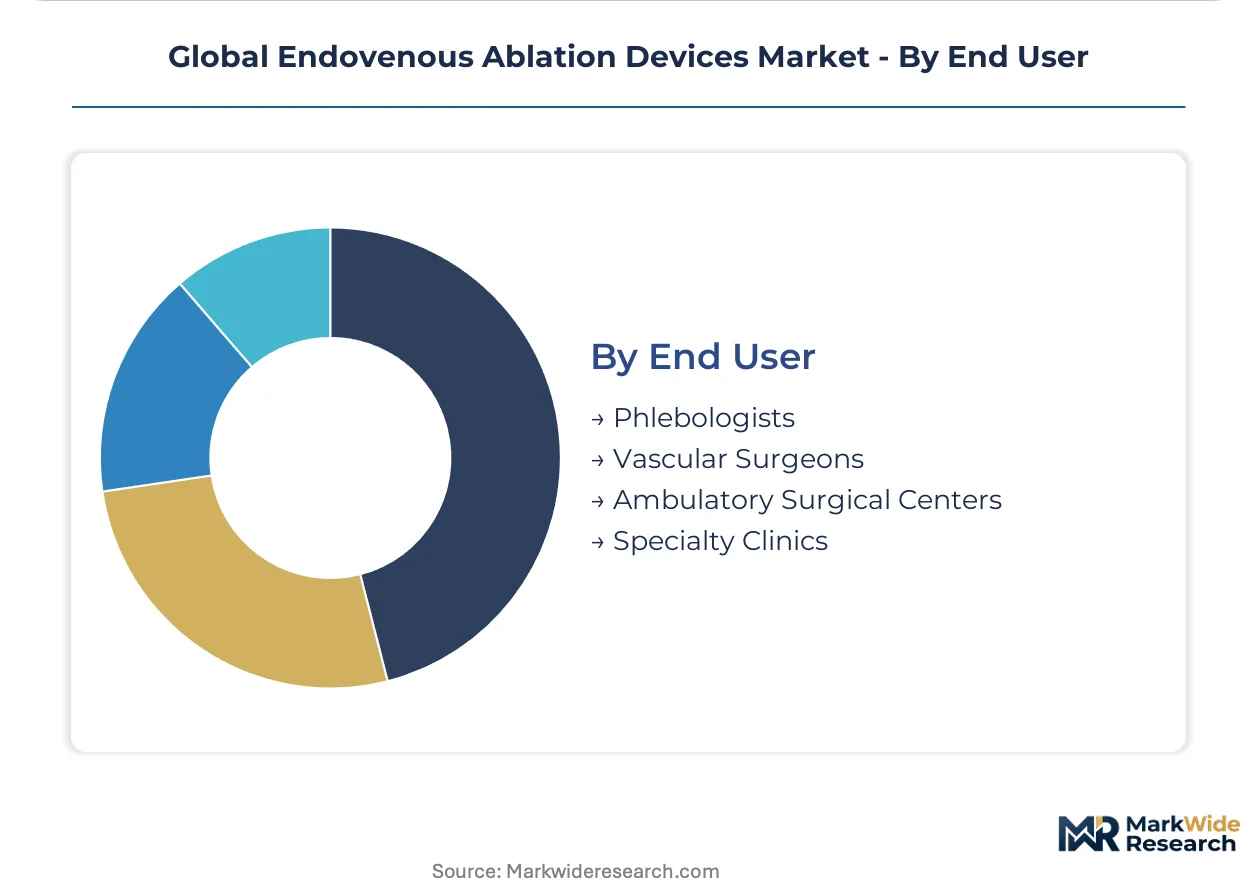
End User:
End user segmentation illustrates the evolving procurement patterns and care delivery models within the vascular health ecosystem.
- Ambulatory Surgical Centers:These outpatient facilities prioritize efficient, minimally invasive procedures for venous conditions, including ablation. Their growth in the United States and Europe is decentralizing care from traditional hospital settings.
- Specialty Clinics:Specialty clinics, often physician-owned, focus exclusively on venous disorders, requiring compact and cost-effective ablation systems. These clinics are increasing in number, particularly in urban centers across Brazil and Mexico.
- Phlebologists:Phlebologists are medical specialists diagnosing and treating venous diseases, often operating within their own clinics or larger medical groups.
- Vascular Surgeons:Vascular surgeons perform a range of procedures for vascular disease, including endovenous ablation, in both hospital and outpatient settings.
Ambulatory Surgical Centers dictate device portability, while Specialty Clinics seek flexible acquisition models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While Germany's aging population significantly drives demand for endovenous ablation devices, the United States market is shaped by the expansion of ambulatory surgical centers. These distinct demographic and healthcare infrastructure trends influence device adoption and procedural volumes differently across regions. Both markets prioritize minimally invasive solutions for venous conditions.
United States
Demand for endovenous ablation devices is robust due to a growing elderly population and increasing preference for outpatient procedures. The FDA's 510(k) clearance pathway ensures device safety and efficacy, supporting market access. Major medical device hubs in California, such as those around San Jose, are innovating new portable ablation systems for ASCs.
Germany
An aging demographic profile and high prevalence of chronic venous insufficiency fuel consistent demand for advanced ablation therapies. CE marking under the Medical Device Regulation (MDR) ensures high safety and performance standards for devices sold across Europe. The Rhine-Main region, with its concentration of medical technology firms, focuses on developing next-generation laser ablation systems.
Japan
Rising awareness of venous disease and a rapidly aging society are expanding the patient pool for endovenous treatments. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates market entry, emphasizing clinical evidence for new technologies. Tokyo's medical device ecosystem is actively integrating advanced imaging with ablation systems to enhance procedural precision.
China
The large, untreated patient population and increasing healthcare expenditure drive significant opportunities for endovenous ablation device adoption. All devices must comply with NMPA standards, influencing product design and clinical trial requirements within the country. Shanghai's medical technology parks are becoming centers for local manufacturing and distribution of thermal ablation devices.
Brazil
A large population with venous disease, combined with a growing private healthcare sector, creates substantial demand for advanced treatment options. ANVISA, the national health surveillance agency, oversees medical device approvals, ensuring product quality. São Paulo's burgeoning medical device industry is focusing on cost-effective and accessible ablation solutions for local clinics.
Global Endovenous Ablation Devices Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists for market share in endovenous ablation devices, creating a dynamic competitive landscape. The market exhibits a tiered structure, with established global medical technology providers alongside innovative niche firms. Strategic archetypes include large-scale integrators offering broad portfolios and specialized technology firms concentrating on specific energy sources or procedural techniques. Portfolio diversification into complementary venous therapies and strategic partnerships to expand geographic reach are dominant competitive moves among market participants.
Within the segment of global medical technology leaders, Medtronic plc exemplifies a diversified approach, leveraging its extensive global sales network to serve a wide array of healthcare accounts, including ambulatory surgical centers. Biolitec AG, conversely, represents a focused pure-play specialist, concentrating its efforts on a refined portfolio of laser-based ablation systems tailored for complex venous cases. Venclose Inc. occupies a position as an innovator in specific radiofrequency ablation technologies, catering to the evolving needs of outpatient settings with an emphasis on procedural efficiency.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Venclose Inc. |
| Medtronic plc |
| Lumenis Ltd. |
| AtriCure Inc. |
| AngioDynamics Inc. |
| Sciton Inc. |
| Biolitec AG |
| Koninklijke Philips N.V. |
| Others |
Cost & Logistics Intelligence
Private-equity-backed specialty clinics, favoring flexible acquisition models, influence supply behavior and pricing discipline in the endovenous ablation device market. This shift towards pay-per-procedure arrangements impacts manufacturer revenue recognition and capital expenditure planning.
Pricing Analysis
Capacity additions in China are reshaping price floors for thermal ablation devices, particularly in emerging markets. The dominant pricing model involves per-unit transactional sales for catheters, often bundled with leasing options for capital equipment. Price differentiation stems from brand premium and the extent of after-sales service and clinical support. Pricing softness runs through the radiofrequency ablation device segment due to increased competition and non-thermal alternatives. Smaller, independent vein clinics exhibit the highest price sensitivity, preferring cost-effective solutions and flexible payment terms.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the downstream logistics for endovenous ablation devices. Geographic supply concentration for key components resides in China for microelectronics and in Germany for specialized laser diodes. Raw material dependencies include medical-grade polymers for catheters and precision-engineered metals for generator components. Regulatory restriction, particularly navigating NMPA standards for device approval in China, presents a significant structural risk. The distribution model primarily involves a mix of direct sales forces and third-party distributors, especially for reaching diffuse ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The endovenous ablation device market currently presents as a late-cycle quality story, driven by a demand-shift toward advanced software integration for improved procedural consistency and data management.
For Market Incumbents:
Deploy a flexible acquisition model strategy, offering pay-per-procedure or leasing options to cater to the growing number of ambulatory surgical centers. Diversify portfolio offerings to include non-thermal technologies, mitigating the threat from substitution. Invest in R&D for AI-powered ultrasound guidance systems to enhance procedural precision and reduce operator dependency. Leverage extensive global sales networks to expand into emerging markets like Brazil and Mexico, where patient populations are substantial.
For New Entrants and Emerging Players:
Capture white-space opportunities in new clinical applications, such as pelvic congestion syndrome, moving beyond traditional varicose vein treatments. Target cost-effective, portable ablation systems specifically designed for specialty clinics in underserved urban centers. The most penetrable segment is independent specialty clinics in Latin America, seeking accessible technology. A compelling go-to-market angle involves offering comprehensive training programs alongside device sales, building physician confidence and loyalty.
For Investors and Strategic Acquirers:
Valuations sit cheapest among niche technology firms specializing in non-thermal ablation or advanced software integration for existing platforms. The market demonstrates long-term viability, underpinned by aging global populations and the sustained shift to minimally invasive outpatient procedures. Acquisition targets should prioritize companies with strong regulatory dossiers and proven clinical outcomes for complex cases. The signal to watch is the adoption rate of AI and robotics in procedural guidance, indicating future competitive advantage.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway Acceleration | Streamlines market entry for innovative devices, securing competitive advantage in regulated geographies like Europe and the United States. |
| Software Companion Development | Enhances procedural efficiency and data management for clinicians in ambulatory surgical centers, improving workflow. |
| Geographic Expansion into Brazil | Taps into a large, untreated patient population with venous disease and a growing private healthcare sector. |
| Flexible Acquisition Model Implementation | Addresses capital investment barriers for smaller clinics, increasing market access for ablation generators. |
| Clinical Trial Advancement for Pelvic Congestion Syndrome | Opens new revenue streams beyond traditional varicose vein applications, diversifying market opportunities. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, forming a robust data collection strategy. Primary research involved discussions with vascular surgeons, hospital procurement managers, medical device engineers, and regulatory affairs specialists. This was complemented by secondary validation using FDA 510(k) clearances, EU MDR documentation, NMPA guidelines, and clinical trial registries, ensuring comprehensive market understanding through bottom-up and top-down triangulation.
The forecast framework anchored the projection horizon to historical reference periods, establishing a consistent basis for trend analysis. Segmentation dimensions modeled included product type, energy source, application, end user, and the regional regulatory environment. Compound annual growth rates were derived from a synthesis of historical market performance, demographic shifts, and projected healthcare expenditure growth across the modeling period, providing forward-looking insights.
Unforeseen technological breakthroughs, shifts in reimbursement policies, and major regulatory changes are the dominant revision risks for the market outlook. Forecasts reflect assumptions documented within the analytical framework. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cellular Encapsulation Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Airotar Handpiece Market
Medical Devices
Smart Medical Devices Market
Medical Devices
Prefilled Glass Syringes Market
Medical Devices
3D Printed Medical Implants Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Computer Aided Trauma Fixators Market
Medical Devices
South America C-Arms Market
Medical Devices
Pathology Devices Market
Medical Devices
Global Retinoscopes Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Diode Laser Hair Removal Equipment Market