
 United States Anesthesia Devices Market | 2026-2036
United States Anesthesia Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Anesthesia Devices Market Analytics
The capital-intensity divergence between integrated platform manufacturers and single-product specialists is reorganizing competitive dynamics across the sector. GE Healthcare leverages its imaging-anesthesia convergence architecture to sustain premium positioning in hospital systems. Medtronic anchors its portfolio through neuromuscular monitoring and infusion system integration. Draegerwerk AG competes on vaporizer precision and workstation modularity for high-throughput surgical environments.
Anesthesia devices encompass inhalation delivery systems, intravenous administration apparatus, and patient monitoring interfaces engineered to maintain controlled unconsciousness, analgesia, and physiological stability during surgical procedures. Precision vaporizer units regulate volatile anesthetic concentration within parts per million accuracy to prevent underdosing awareness or overdosing cardiovascular depression. Anesthesia workstations command the largest installed base and replacement cycle revenue pool, while ultrasound-guided regional anesthesia techniques represent the fastest-expanding technology segment as facilities pursue opioid-sparing protocols. Computer-assisted systems concentrate margin capture among academic medical centers investing in closed-loop titration research.
FDA 510(k) clearance pathways and EPA anesthetic gas emission guidelines constrain product design and facility infrastructure investments across the United States. The Joint Commission accreditation standards and ASA practice parameters further shape capital equipment specifications and replacement timelines. Stakeholders must monitor evolving CMS reimbursement structures for ambulatory surgery and hospital outpatient departments to align portfolio development with site-of-care migration trends.
Market Dynamics
Site-of-care migration from inpatient hospitals to ambulatory surgical centers is compressing capital equipment replacement cycles and forcing manufacturers to recalibrate service revenue models around decentralized maintenance networks.
Growth Catalysts
- Ultrasound-guided regional anesthesia:Academic medical centers in Texas and California are deploying nerve block systems to reduce opioid consumption. The technique expands procedure volumes in orthopedic and trauma settings.
- Closed-loop anesthesia delivery:Research institutions are validating algorithmic control systems that automate propofol titration. This convergence of infusion pumps and depth-of-monitoring sensors reduces clinician cognitive load.
- EPA anesthetic gas capture mandates:Facility infrastructure investments in scavenging systems and waste anesthetic gas destruction units are accelerating workstation replacement timelines across Florida health systems.
Market Restraints
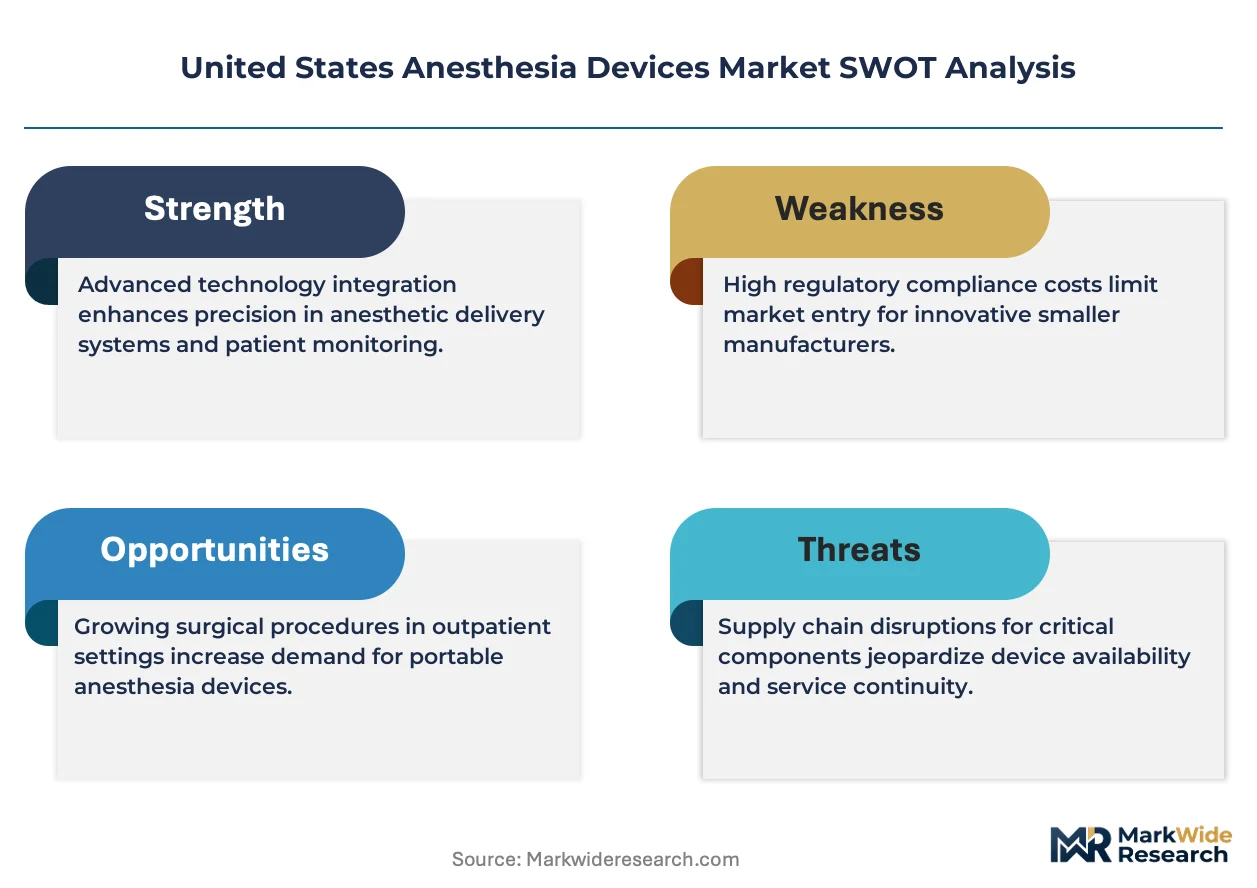
- Sevoflurane and desflurane supply concentration:Active pharmaceutical ingredient production for volatile anesthetics concentrates among a limited set of chemical manufacturers, exposing vaporizer-dependent systems to input volatility.
- FDA 510(k) pathway friction:Substantial equivalence determinations for anesthesia workstation modifications extend clearance timelines, delaying feature releases for integrated platform manufacturers.
- Total intravenous anesthesia substitution:TIVA protocols using propofol and remifentanil bypass vaporizer-based delivery entirely, threatening inhalation system revenue pools in ambulatory settings.
Strategic Opportunities
- Rural hospital consolidation zones:Critical access hospitals in the Mountain West and Great Plains regions lack capital for full workstation replacement, creating lease and refurbished equipment channels.
- Closed-loop research partnerships:Device manufacturers collaborating with academic anesthesiology departments on FDA breakthrough device designation pathways for autonomous titration systems.
- Service unbundling for ASCs:Standalone surgery centers in California prefer preventive maintenance contracts separate from capital purchase, enabling recurring revenue models distinct from hospital integrated service agreements.
Industry Challenges
- Biomedical technician specialization gaps:Vaporizer calibration and pneumatic system troubleshooting require expertise that ASC staffing models rarely accommodate, forcing manufacturer field service dependency.
- Legacy Draeger and GE system integration:Health systems running mixed-vendor installed bases face data interoperability failures between anesthesia information management systems and electronic health records.
- 510(k) clinical data requirements:Novel monitoring interfaces must demonstrate equivalence to predicate devices through prospective studies, extending development timelines for startups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Anesthesia Devices Market |
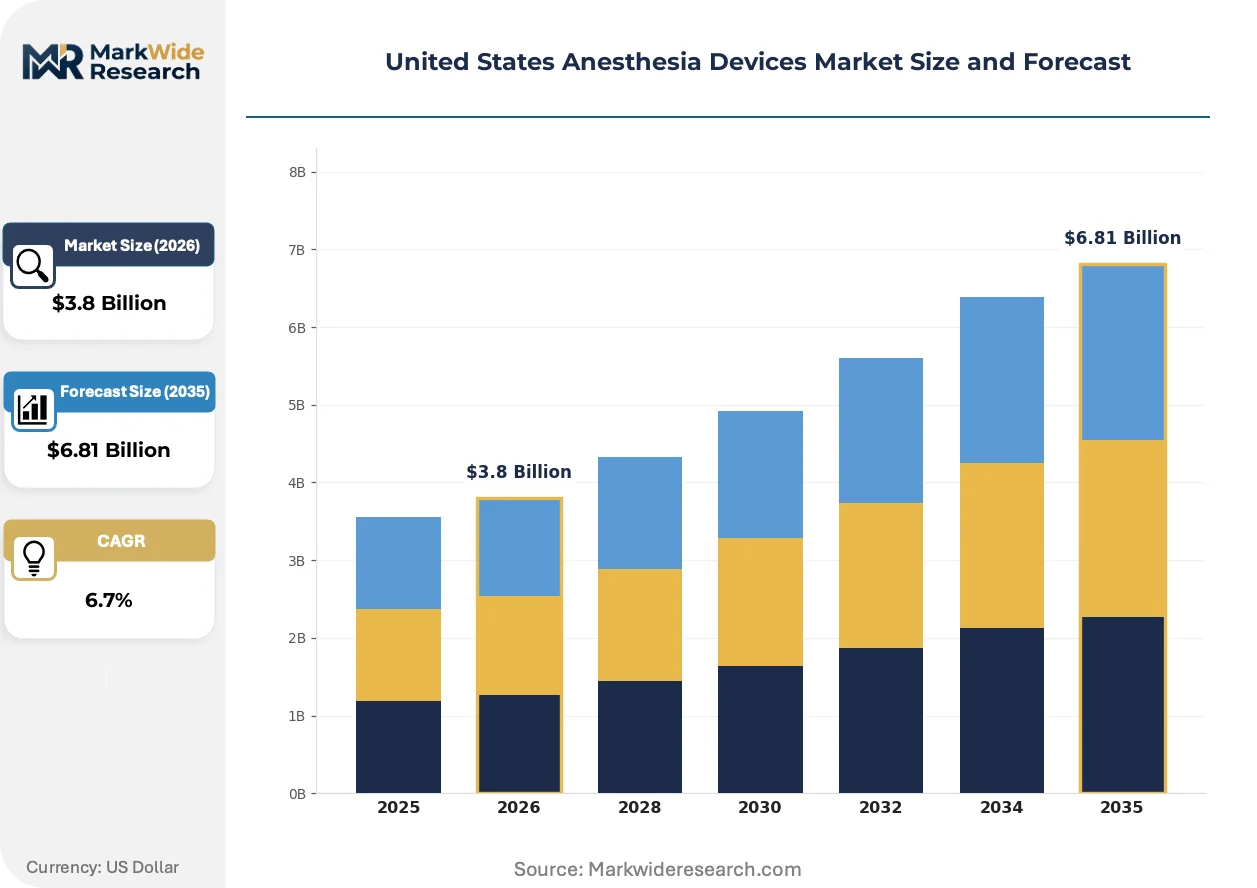
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalation Devices, IV Anesthetics, Anesthesia Workstations, Anesthesia Masks End User: Hospitals, Surgical Centers, Clinics, Ambulatory Care Facilities Technology: Ultrasound-Guided Techniques, Computer-Assisted Systems, Vaporizer Technologies, Neuromuscular Monitoring Delivery Mode: General Anesthesia, Regional Anesthesia, Sedation, Local Anesthesia |
| Companies Covered | GE Healthcare, Medtronic, Draegerwerk AG, Koninklijke Philips NV, B. Braun SE, Fisher & Paykel Healthcare, Mindray Medical International Limited, Smiths Medical, Ambu A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Anesthesia Devices Market Evolving Landscape
Digital integration between anesthesia delivery platforms and hospital information systems is redefining competitive advantage around data liquidity rather than hardware specifications alone.
Ultrasound-guided peripheral nerve block systems are supplanting landmark-based techniques in orthopedic and pain management settings. Ambulatory surgical centers in Texas and Florida are deploying compact, tablet-integrated devices to support same-day discharge protocols. This modality shift is compressing demand for general anesthesia vaporizer capacity in knee and shoulder arthroscopy volumes.
FDA guidance on predetermined change control plans for artificial intelligence-enabled devices is altering software update pathways for closed-loop anesthesia systems. Manufacturers must now validate algorithm modifications through pre-submission protocols rather than post-market patches. Academic medical centers pursuing autonomous delivery research face extended institutional review board timelines as a result.
Consolidated purchasing through regional health system supply chain offices is displacing individual hospital capital budgeting for anesthesia workstations. Multi-hospital networks in California and Texas are negotiating enterprise pricing for standardized platforms across inpatient and ambulatory sites. This concentration is marginalizing independent surgery centers unable to meet minimum volume commitments for preferred pricing tiers.
United States Anesthesia Devices Market Segmentation
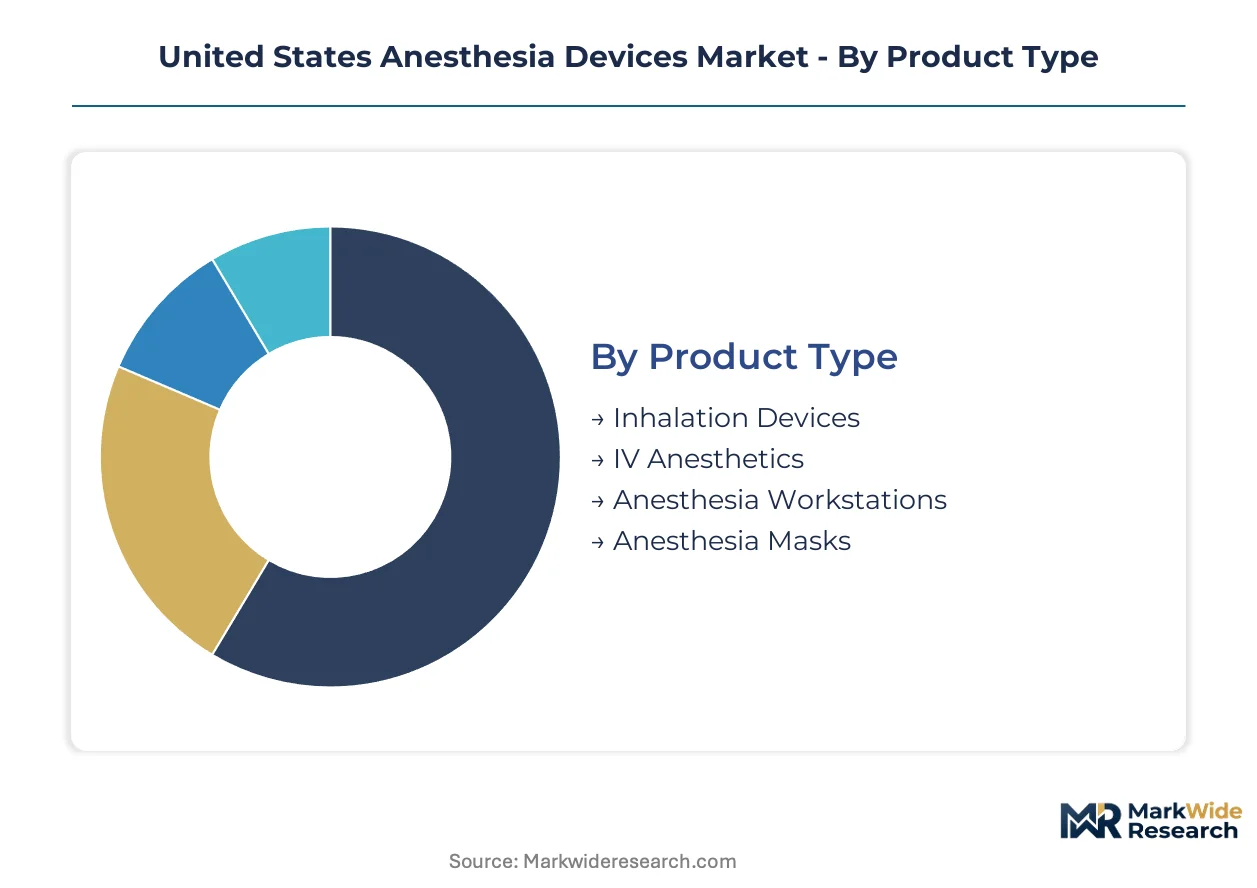
Segmentation in the United States anesthesia devices market reveals divergent investment priorities across care settings. Product architecture, delivery modality, and site-of-care economics collectively determine procurement patterns and replacement cycles.
Product Type:
Domestic manufacturing concentrates anesthesia workstations and vaporizer assemblies in Wisconsin and Pennsylvania industrial corridors. IV anesthetics draw heavily on imported active pharmaceutical ingredients.
- Anesthesia Workstations:Integrated platforms combine gas delivery, scavenging, and patient monitoring in unified pneumatic architectures. Texas and California health systems drive replacement demand as EPA waste gas regulations force infrastructure upgrades.
- Inhalation Devices:Precision vaporizers regulate volatile agent concentration through temperature-compensated flow control. Florida surgical networks favor modular units permitting rapid sevoflurane-desflurane switching between cases.
- IV Anesthetics:Infusion pumps and syringe drivers for propofol and remifentanil delivery.
- Anesthesia Masks:Disposable interfaces for preoxygenation and induction.
Anesthesia workstations command the established base. The steepest expansion runs through IV anesthetics.
End User:
Capital intensity separates hospital integrated platforms from ambulatory compact systems. Reimbursement differentials between HOPD and ASC settings reshape equipment specifications.
- Hospitals:Academic medical centers and community hospitals deploy full-featured workstations with anesthesia information management system integration. California's Kaiser Permanente and Sutter Health networks standardize platforms across 50-plus facilities.
- Surgical Centers:Ambulatory settings in Texas prioritize portable, tablet-integrated systems for orthopedic nerve blocks. Same-day discharge protocols compress equipment footprints.
- Clinics:Pain management and dental anesthesia favor compact sedation systems.
- Ambulatory Care Facilities:Endoscopy and interventional radiology suites demand monitored anesthesia care capabilities.
Hospitals anchor installed capacity. Surgical centers are gaining share fastest.
Technology:
Regulatory clearance timelines vary sharply between hardware-based vaporizers and software-dependent closed-loop systems. FDA 510(k) pathways favor predicate-based vaporizer submissions.
- Ultrasound-Guided Techniques:Compact, high-frequency probes with needle visualization software enable peripheral nerve blocks. Texas orthopedic ASCs deploy these for opioid-sparing protocols in joint replacement.
- Vaporizer Technologies:Agent-specific, temperature-compensated flowmeters maintain concentration stability across varying fresh gas flows. Precision engineering concentrates among German and US manufacturers.
- Computer-Assisted Systems:Algorithmic propofol titration remains investigational at academic centers.
- Neuromuscular Monitoring:Quantitative train-of-four sensors guide neuromuscular blocker reversal.
Vaporizer technologies dominate current revenue. Ultrasound-guided techniques show the steepest expansion trajectory.
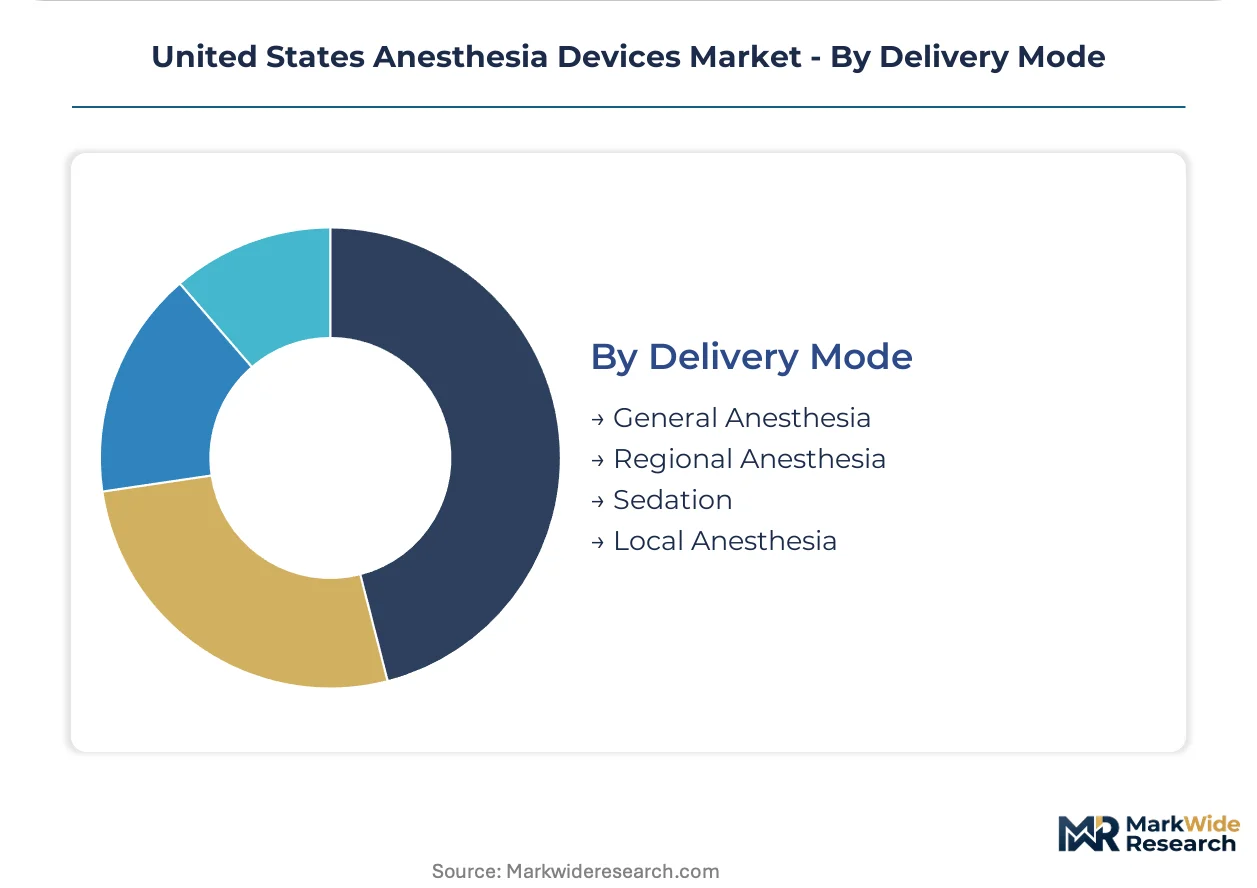
Delivery Mode:
Site-of-care migration favors regional and sedation modalities over general anesthesia in outpatient settings. TIVA protocols bypass vaporizer infrastructure entirely.
- General Anesthesia:Endotracheal intubation with volatile or intravenous agents maintains unconsciousness for major surgery. California cardiac and neurosurgical programs sustain demand for advanced workstation capabilities.
- Regional Anesthesia:Neuraxial and peripheral nerve blocks provide surgical anesthesia without airway instrumentation. Florida health systems expand epidural and spinal programs for obstetric and lower-extremity cases.
- Sedation:Monitored anesthesia care for endoscopy and minor procedures.
- Local Anesthesia:Infiltration techniques without systemic agent delivery.
General anesthesia retains the largest procedure volume base. Regional anesthesia climbs the fastest as ASC penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas health systems command pricing leverage through consolidated procurement that California's fragmented independent ASCs cannot match. This asymmetry reshapes manufacturer go-to-market strategies across state lines. Regional demand patterns diverge sharply between EPA-regulated hospital networks and cost-constrained ambulatory settings.
Texas
Texas Medical Center in Houston and Dallas-Fort Worth hospital networks drive workstation replacement demand through enterprise standardization. EPA waste anesthetic gas regulations accelerate scavenging system upgrades across Harris and Dallas counties. Orthopedic ASCs in Austin deploy ultrasound-guided nerve blocks for same-day joint replacement discharge.
California
Kaiser Permanente and Sutter Health networks spanning 50-plus facilities consolidate anesthesia platform purchasing power. FDA 510(k) clearance timelines for AI-enabled monitoring shape investment pacing at Stanford and UCSF academic centers. Silicon Valley medical device clusters supply closed-loop algorithm development partnerships.
Florida
Florida Hospital Association members face compressed replacement cycles from combined EPA and Joint Commission compliance deadlines. Tampa and Orlando health systems expand epidural programs for obstetric and lower-extremity surgical volumes. Independent ASCs in Miami-Dade struggle with biomedical technician gaps for vaporizer maintenance.
Illinois
Chicago-based academic medical centers anchor neuromuscular monitoring research for quantitative train-of-four validation. CMS reimbursement differentials between HOPD and ASC settings reshape equipment specifications across Cook County networks. Northwestern and University of Chicago drive closed-loop propofol titration clinical trials.
Pennsylvania
Pittsburgh and Philadelphia manufacturing corridors concentrate domestic anesthesia workstation and vaporizer assembly capacity. UPMC and Penn Medicine networks standardize platforms across inpatient and ambulatory sites. Rural critical access hospitals in central Pennsylvania create refurbished equipment and lease channel demand.
United States Anesthesia Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated platform manufacturers commanding premium positioning while modular specialists capture ambulatory price sensitivity. The market structures around three tiers: full-workstation incumbents, regional anesthesia device specialists, and emerging closed-loop research collaborators. Dominant competitive moves include service unbundling for ASCs and academic partnership pathways for breakthrough device designations.
Within the integrated platform tier, GE Healthcare and Draegerwerk AG occupy positions defined by imaging-anesthesia convergence and vaporizer precision engineering respectively. Medtronic anchors the neuromuscular monitoring and infusion system integration vector. These three exemplify how hardware-software convergence separates premium hospital contracts from cost-driven ambulatory procurement.
| Leading Market Players |
|---|
| GE Healthcare |
| Medtronic |
| Draegerwerk AG |
| Koninklijke Philips NV |
| B. Braun SE |
| Fisher & Paykel Healthcare |
| Mindray Medical International Limited |
| Smiths Medical |
| Ambu A/S |
| Others |
Value Network & Pricing Analysis
Propofol and remifentanil substitution for volatile anesthetics is simultaneously redrawing API sourcing geography from German chemical corridors to Indian pharmaceutical clusters and compressing vaporizer-premium capture across ambulatory surgical center procurement.
Pricing Analysis
Configured-to-order pricing for integrated anesthesia workstations commands 40-60% premiums over standard configurations across Texas health system contracts. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center specifications from ambulatory compact systems. Cost compression in the economy tier is intensifying because independent ASCs in Florida and California lack capital for full-platform replacement. Surgical centers exhibit the highest price sensitivity, while integrated delivery networks in Pennsylvania and Texas leverage volume scale for enterprise discounts.
Supply Chain Analysis
Strait of Hormuz transit underwrites sevoflurane and desflurane precursor shipments from Middle Eastern petrochemical hubs to Wisconsin and Pennsylvania assembly plants. German and US manufacturers dominate precision vaporizer engineering, while China and India supply temperature-compensated flowmeter subassemblies. Single-source vulnerability concentrates in active pharmaceutical ingredient production for volatile agents. Distribution runs through regional health system supply chain offices and group purchasing organizations rather than direct hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anesthesia devices market functions as a service-attach opportunity where preventive maintenance contracts and refurbished equipment leasing expand faster than capital hardware sales across ambulatory surgical center penetration.
For Market Incumbents: Compound service revenue capture through unbundled preventive maintenance contracts targeting California ASCs that prefer operational expenditure models over capital purchase. Defend installed base positions against closed-loop algorithm specialists by deepening anesthesia information management system integration. Prioritize FDA breakthrough device designation partnerships with academic medical centers to anchor autonomous titration research pipelines. For New Entrants and Emerging Players: Differentiate on ultrasound-guided regional anesthesia portability for orthopedic ASCs in Texas and Florida pursuing same-day discharge protocols. Target rural critical access hospitals in the Mountain West and Great Plains with lease-to-own refurbished workstation programs. Pursue GPO contracts as the primary go-to-market channel rather than direct hospital sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional anesthesia device specialists holding FDA 510(k) clearances but lacking service network scale. Five-to-ten year viability hinges on closed-loop algorithm validation and ASC reimbursement expansion. Watch CMS ambulatory surgery payment policy shifts as the inflection indicator for capital equipment replacement pacing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates closed-loop propofol titration pathways at Stanford and UCSF research centers. |
| Hospital System Partnership | Kaiser Permanente and Sutter Health enterprise contracts standardize platforms across 50-plus facilities. |
| Software Companion Development | Anesthesia information management system integration anchors premium positioning against modular competitors. |
| Reimbursement Strategy | Alignment with CMS HOPD-ASC payment differentials shapes equipment specifications across site-of-care migration. |
| CE Marking Pathway | European vaporizer precision standards validate export-ready manufacturing from Wisconsin and Pennsylvania corridors. |
Research Methodology
The analysis maps anesthesia workstations, inhalation devices, IV anesthetics, and ultrasound-guided systems, each validated through biomedical engineers, hospital purchasing committees, GPO contracts managers, and anesthesiology department chairs. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, CMS Medicare payment data, hospital procurement databases, and EPA emission compliance records. Bottom-up and top-down triangulation cross-checked segment-level outputs against health system capital expenditure disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product architecture, delivery modality, end-user setting, and site-of-care economics. CAGRs were derived from replacement cycle analysis and procedure volume elasticity. Forecast inputs incorporated EPA regulatory compliance deadlines and ASC penetration trajectories without specifying year markers.
Decision-makers should treat outputs as directional under stable reimbursement and regulatory enforcement assumptions; material deviation would warrant model refresh. Forecasts reflect these base conditions and EPA anesthetic gas capture mandate pacing. Practitioners should keep alternative scenarios live as TIVA substitution rates and closed-loop algorithm validation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Steerable Needles Market
Medical Devices
Global Digital Pathology Systems Market
Medical Devices
China Artificial Organs and Bionic Implants Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Europe Invisible Orthodontics Market
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
Smart Pills Technology Market
Medical Devices
Reprocessed Medical Devices Market
Medical Devices
Brazil Aesthetic Equipment Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Anesthesia Resuscitators Masks Market
Medical Devices
Global Microelectronic Medical Implants Market
Medical Devices
Global Medical Tricorder Device Market
Medical Devices
Video Dermatoscope Market
Medical Devices
Nephrostomy Devices Market