
 Global Vein Illuminator Market | 2026-2036
Global Vein Illuminator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vein Illuminator Market Foresight
Aftermarket service revenue is fragmenting across the vein illuminator landscape as hardware commoditization pushes vendors toward recurring calibration and software update contracts. AccuVein Inc. leverages its installed base of near infrared devices to lock in multi-year service agreements with hospital networks. Christie Medical Holdings Inc. anchors its position through proprietary vein visualization algorithms that sustain premium pricing on replacement components. VueTek Scientific LLC competes by offering flexible service tiers that extend equipment lifespan without requiring full platform swaps.
A vein illuminator is a medical device that projects near infrared light—typically at wavelengths between 700 and 900 nanometers—onto subcutaneous tissue to visualize superficial veins for vascular access procedures. The device captures reflected light through specialized sensors and renders real-time vein maps on the skin surface, primarily serving clinicians performing phlebotomy, intravenous catheterization, and blood draws. Portable vein illuminators command the largest revenue pool due to their deployment flexibility across emergency departments and ambulatory settings, while wearable illuminators represent the fastest-expanding segment as manufacturers miniaturize sensor arrays and integrate wireless data transmission. Near infrared imaging technology dominates the technology landscape because it penetrates deeper tissue layers than transillumination methods, though ultrasound-based systems capture premium margins in bariatric and deep-vein applications where optical methods fail.
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape product development timelines and clinical validation burdens for manufacturers seeking market access in the United States and Europe. ISO 13485 quality management certification and IEC 60601 electrical safety standards further constrain supplier eligibility, particularly for Asian manufacturers targeting Western healthcare procurement channels. Stakeholders must monitor how FDA guidance on optical imaging devices evolves alongside EU AI Act risk classifications for systems incorporating automated vein detection algorithms.
Market Dynamics
Hardware commoditization across near infrared vein illuminators is compressing margins and forcing vendors toward recurring revenue models anchored in calibration services and algorithm subscriptions.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for optical imaging devices are reducing time-to-market for manufacturers targeting US hospital networks.
- Pediatric emergency departments:Rising first-attempt success mandates in US and German children's hospitals are concentrating procurement of portable vein visualization systems.
- EU MDR clinical validation requirements:Stricter venipuncture accuracy standards under the Medical Device Regulation are displacing legacy transillumination devices in European diagnostic centers.
Market Restraints
- Indium gallium arsenide sensor costs:Near infrared detector arrays face input price volatility from concentrated Taiwanese and Japanese semiconductor foundries.
- Deep-vein optical limitation:Near infrared wavelengths fail to penetrate adipose tissue beyond 3mm, ceding bariatric applications to ultrasound-based substitutes.
- EU AI Act risk classification:Automated vein detection algorithms face elevated compliance burdens as Class IIa or higher medical devices, extending validation timelines.
Strategic Opportunities
- India's Ayushman Bharat expansion:Underpenetrated district hospitals and primary health centers present untapped demand for cost-optimized portable illuminators.
- Wireless data transmission convergence:Integration of Bluetooth Low Energy with miniaturized sensor arrays enables remote procedure documentation in ambulatory surgery centers.
- Japan's METI medical device subsidy:Domestic production incentives for geriatric care technologies are creating procurement preference for locally manufactured wearable systems.
Industry Challenges
- ISO 13485 certification timelines:Asian manufacturers targeting Western markets face 12-18 month quality management system validation delays.
- Legacy EMR integration complexity:Proprietary data formats from vein illuminator vendors require custom middleware development for hospital information system connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vein Illuminator Market |
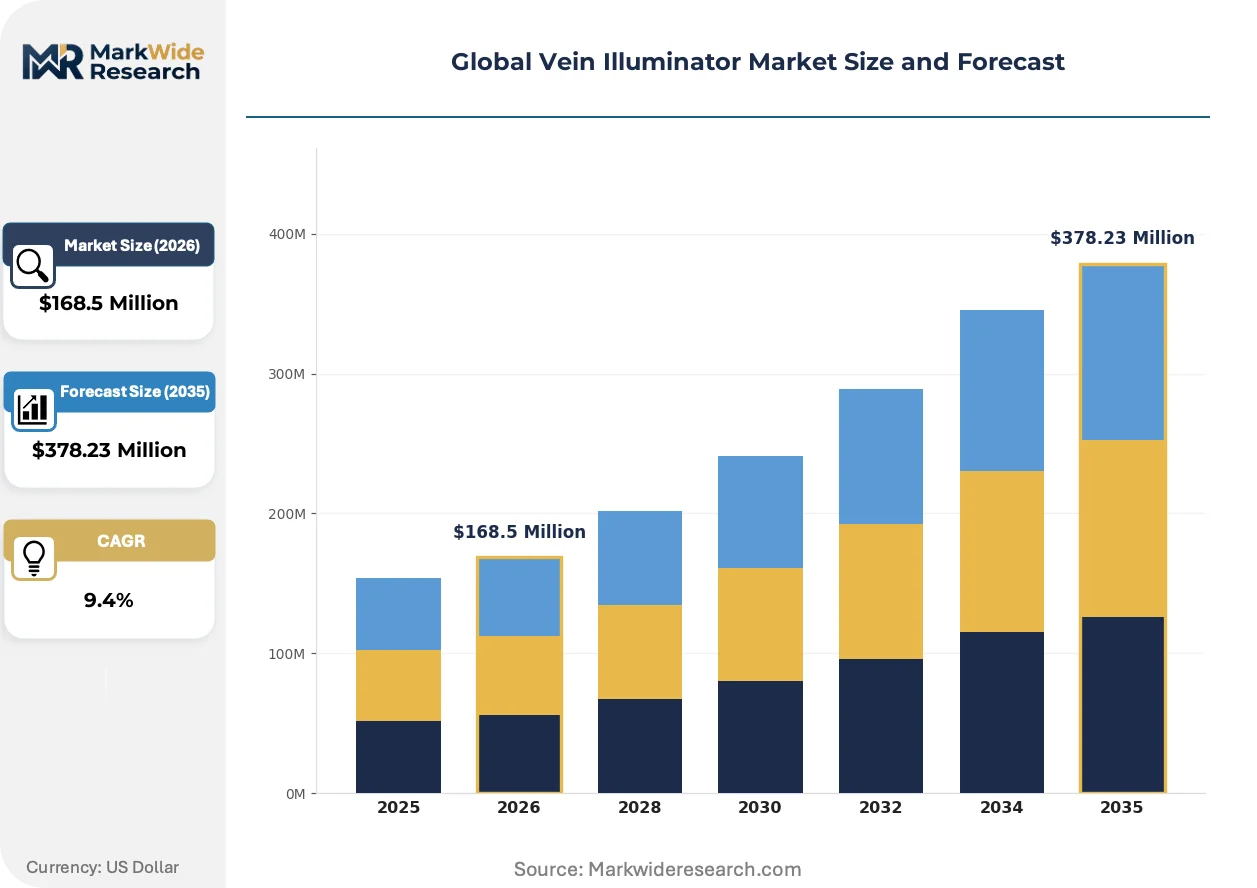
| Market Size in 2026 | $168.5 Million |
| Market Size in 2035 | $378.23 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Vein Illuminators, Handheld Devices, Wearable Illuminators, Tabletop Models Technology: Near Infrared Imaging, Transillumination, Ultrasound, Infrared Light Application: Phlebotomy, Intravenous Therapy, Pediatric Care, Geriatric Care, Emergency Care End User: Hospitals, Diagnostic Centers, Ambulatory Care, Blood Banks |
| Companies Covered | AccuVein Inc., Christie Medical Holdings Inc., Venoscope LLC, TransLite LLC, ZD Medical Inc., Sharn Anesthesia, VueTek Scientific LLC, Near Infrared Imaging, Veinlite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vein Illuminator Market Shifts & Advancements
Algorithm-driven vein mapping is displacing hardware-centric competition as manufacturers differentiate through software update cadence and AI-enhanced detection accuracy rather than optical specifications alone.
Multispectral imaging arrays combining near infrared with visible light wavelengths are penetrating deeper tissue layers than single-band devices. Bariatric surgery units in US academic medical centers are piloting these systems for patients with body mass indices exceeding 35. Conventional transillumination methods are rendering obsolete in deep-vein access procedures where optical penetration limits previously forced ultrasound escalation.
The EU AI Act's risk-based classification framework is elevating compliance requirements for vein illuminators incorporating automated vessel detection. Manufacturers must now maintain algorithm training documentation and post-market surveillance protocols previously reserved for higher-risk device categories. German notified bodies are processing these submissions with 40% longer review cycles than conventional optical devices without AI components.
Hospital procurement departments are consolidating vendor relationships through multi-year service agreements that bundle hardware, calibration, and software access. Independent service organizations and third-party biomedical engineering firms are losing share to manufacturer-direct contracts that lock in replacement component revenue. This concentration is most visible in US health system purchasing cooperatives where GPO-negotiated agreements favor single-source relationships over best-of-breed component sourcing.
Global Vein Illuminator Market Segmentation
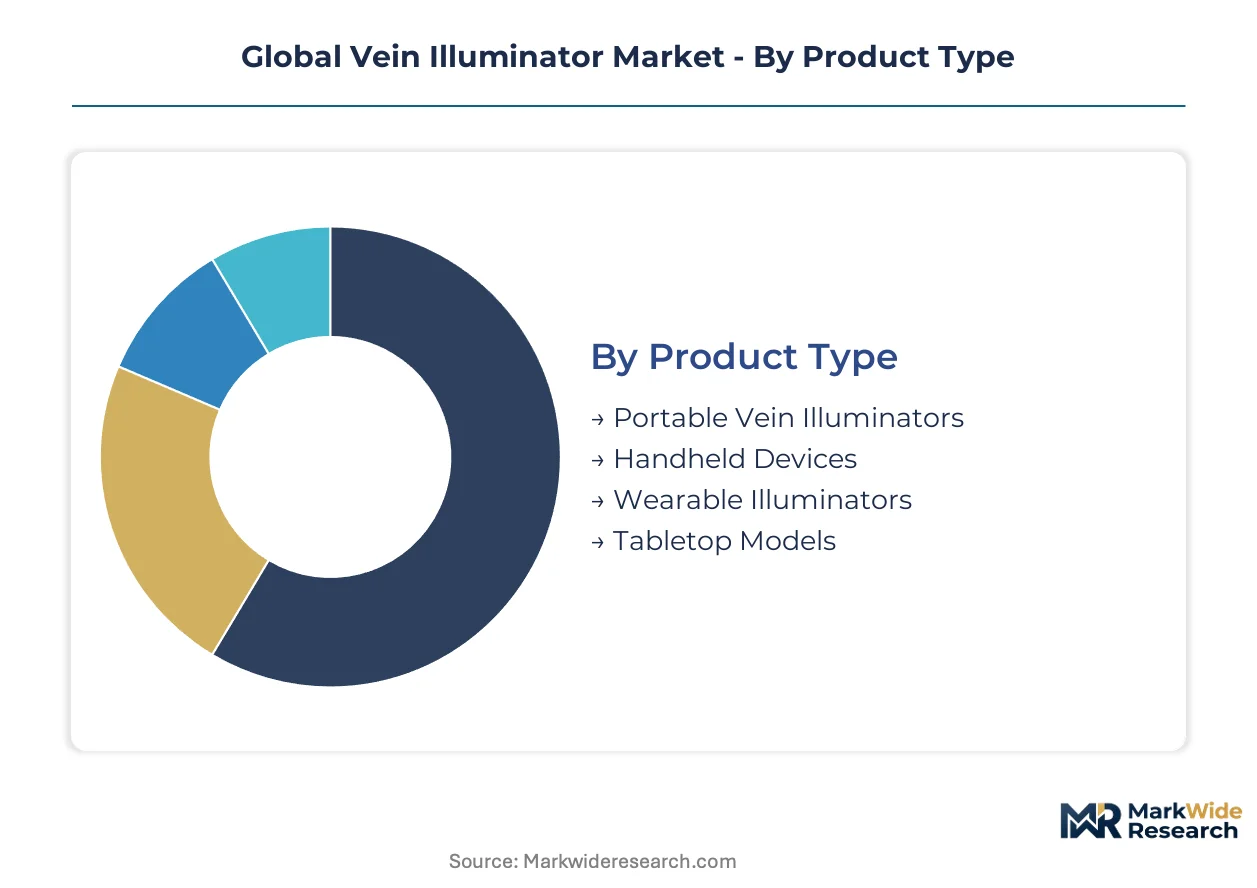
Segmentation in the vein illuminator market reveals how clinical requirements, facility infrastructure, and patient demographics shape procurement priorities. Product portability, imaging depth, and end-user workflow constraints each create distinct competitive battlegrounds for manufacturers.
Product Type:
The use-case spectrum spans emergency department mobility to fixed-station procedural volume, with each form factor optimizing for specific clinical throughput and capital deployment models.
- Portable Vein Illuminators:Battery-powered units weighing under 500 grams deploy across triage bays and pre-hospital settings. Emergency departments in the United States and Germany are standardizing on these devices to meet pediatric first-attempt success mandates. Their rechargeable power systems and wireless charging docks minimize downtime during high-volume shifts.
- Wearable Illuminators:Head-mounted and wrist-worn configurations integrate miniaturized sensor arrays with hands-free operation. Japan's METI subsidy programs are accelerating domestic production for geriatric long-term care facilities where clinician mobility is constrained. Bluetooth Low Energy modules enable real-time documentation integration with electronic medical records.
- Handheld Devices:Pistol-grip form factors balance optical performance with single-hand operation for phlebotomy technicians.
- Tabletop Models:Stationary units with articulated arms serve high-throughput blood draw centers requiring consistent positioning.
Established volume favors portable configurations; emerging adoption favors wearable systems.
Technology:
Cost tier stratification separates premium deep-tissue modalities from accessible optical methods, with reimbursement codes and procedure complexity driving technology selection.
- Near Infrared Imaging:Wavelengths between 700 and 900 nanometers penetrate subcutaneous tissue to 3mm depth, capturing hemoglobin absorption contrast through indium gallium arsenide sensor arrays. This technology dominates hospital procurement in North America and Europe due to superior performance on diverse skin tones. FDA 510(k) pathway streamlining has compressed clearance timelines for manufacturers incorporating updated detector designs.
- Ultrasound:High-frequency transducers visualize veins beyond optical penetration limits, commanding premium pricing in bariatric surgery units where adipose tissue exceeds 3mm thickness. Academic medical centers in the United States pilot these systems for patients with body mass indices above 35, where near infrared methods fail to resolve vascular targets.
- Transillumination:Visible light projection through tissue edges serves cost-constrained primary care settings with shallow vein requirements.
- Infrared Light:Single-band emitters without multispectral processing occupy economy pricing tiers in emerging market district hospitals.
Near infrared imaging commands the largest installed base; ultrasound captures the steepest expansion trajectory in specialized surgical applications.
Application:
Patient population vulnerability determines accuracy requirements, with regulatory pressure concentrating demand in pediatric and geriatric segments.
- Pediatric Care:Neonatal and pediatric populations present small, mobile, and deeply situated veins that challenge conventional palpation. Children's hospitals in Germany and the United States face institutional mandates for first-attempt success rates above 90 percent, driving dedicated procurement of high-resolution portable systems. Device footprints must accommodate incubator access and warming equipment proximity.
- Phlebotomy:High-volume blood collection centers process thousands of daily draws where cumulative needlestick complications generate substantial liability exposure. Diagnostic laboratory networks in Japan and France are deploying vein visualization to reduce hemolysis rates and specimen rejection.
- Intravenous Therapy:Peripheral catheter placement in general medical-surgical units benefits from rapid vein assessment.
- Geriatric Care:Fragile, rolling, and sclerotic veins in aging populations require gentle tissue handling and shallow angle insertion guidance.
- Emergency Care:Trauma resuscitation and critical access scenarios prioritize speed over image fidelity.
Phlebotomy generates the highest unit volume; pediatric care imposes the most stringent performance specifications.
End User:
Customer type segmentation aligns with capital intensity, procedure complexity, and regulatory oversight depth across healthcare delivery settings.
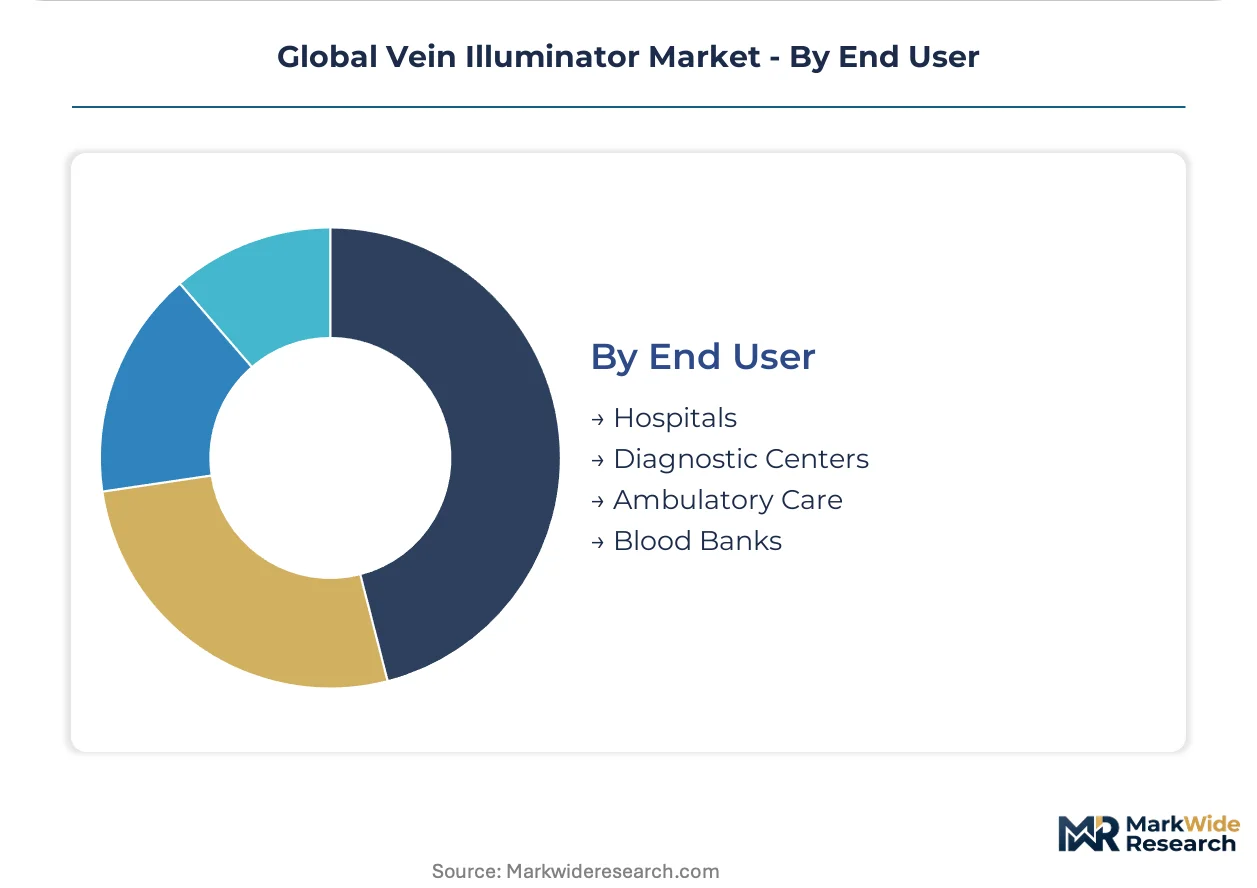
- Hospitals:Integrated delivery networks consolidate purchasing through group purchasing organizations, favoring multi-year service agreements that bundle hardware, calibration, and algorithm subscriptions. EU MDR clinical validation requirements are displacing legacy devices in European hospital systems ahead of certificate expiration deadlines.
- Diagnostic Centers:High-throughput phlebotomy and specimen collection operations prioritize device durability and standardized operator training protocols. These facilities represent concentrated demand for tabletop configurations with fixed positioning and minimal calibration drift.
- Ambulatory Care:Freestanding surgery centers and urgent care clinics balance acquisition cost against procedure documentation requirements.
- Blood Banks:Donor collection operations emphasize donor comfort and throughput efficiency over diagnostic precision.
Hospital procurement concentrates the largest revenue pool; diagnostic centers offer the most predictable replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate low price elasticity as regulatory mandates override cost considerations, while procurement in India and Brazil remains acutely sensitive to upfront capital outlays despite expanding healthcare infrastructure.
United States
Pediatric emergency departments and academic medical centers drive procurement of portable near infrared systems as Joint Commission standards tighten venipuncture accuracy requirements. FDA 510(k) pathway streamlining has compressed clearance timelines for optical imaging devices. Boston and Philadelphia hospital networks concentrate demand for wearable illuminator pilot programs in geriatric long-term care facilities.
Germany
Children's hospitals in Berlin and Munich face institutional mandates exceeding 90 percent first-attempt success rates for vascular access procedures. EU MDR clinical validation requirements are displacing legacy transillumination devices ahead of certificate expiration deadlines. The Rhine-Ruhr medical technology cluster anchors manufacturing partnerships for miniaturized sensor arrays serving Western European distribution.
Japan
Geriatric care units and long-term care facilities generate concentrated demand for hands-free wearable configurations as clinician mobility constraints intensify. METI medical device subsidies create procurement preference for domestically manufactured systems. Osaka-based production facilities supply sensor-integrated devices to Southeast Asian export markets under bilateral trade agreements.
India
District hospitals and primary health centers under Ayushman Bharat expansion present volume opportunities for cost-optimized portable illuminators with simplified calibration protocols. CDSCO medical device regulations are harmonizing with ISO 13485 standards to accelerate import clearance timelines. The Mumbai-Pune pharmaceutical corridor hosts assembly operations for economy-tier near infrared devices serving domestic and African export markets.
Brazil
Public hospital networks in São Paulo and Minas Gerais prioritize acquisition cost over feature depth as federal health budgets constrain capital expenditure. ANVISA medical device registration pathways are extending validation timelines for imported optical imaging systems. The Campinas medical device cluster supports local assembly partnerships to circumvent import tariff structures on finished equipment.
Global Vein Illuminator Market Competitive Landscape
Capability concentration sits with algorithm developers and sensor specialists; scale advantage sits with distributors holding multi-year hospital network contracts. The vendor base separates into three functional tiers: premium-tier manufacturers commanding proprietary visualization software, mid-tier assemblers sourcing commodity near infrared components, and regional licensees adapting foreign designs for local regulatory pathways. Dominant competitive moves include geographic expansion through distributor partnerships and technology licensing agreements that transfer algorithm access without hardware manufacturing obligations.
Within the premium-tier segment, AccuVein Inc. and Christie Medical Holdings Inc. occupy positions anchored by installed base scale and proprietary software ecosystems. VueTek Scientific LLC exemplifies the flexible-service archetype competing through tiered maintenance contracts rather than hardware differentiation. These three entities collectively represent the strategic spectrum spanning algorithm lock-in, component premiumization, and service-model adaptability that defines current competitive positioning.
| Leading Market Players |
|---|
| AccuVein Inc. |
| Christie Medical Holdings Inc. |
| Venoscope LLC |
| TransLite LLC |
| ZD Medical Inc. |
| Sharn Anesthesia |
| VueTek Scientific LLC |
| Near Infrared Imaging |
| Veinlite |
| Others |
Supply & Pricing Matrix
The Shanghai-Long Beach transpacific corridor absorbs semiconductor freight premiums that cascade through indium gallium arsenide sensor pricing, concentrating margin pressure on mid-tier assemblers while premium-tier manufacturers with captive calibration revenue offset logistics volatility through multi-year hospital network contracts.
Pricing Analysis
Aftermarket service contracts now anchor lifetime value capture across the vein illuminator landscape. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared near infrared systems with algorithm subscriptions from basic transillumination units lacking software update pathways. Cost compression in the standard tier intensifies because Taiwanese foundry input volatility feeds component price instability. Pediatric emergency departments in Germany and the United States demonstrate lowest price sensitivity as Joint Commission mandates override capital expenditure constraints, while district hospitals under India's Ayushman Bharat expansion prioritize acquisition cost above feature depth.
Supply Chain Analysis
Taiwanese and Japanese semiconductor foundries hold concentrated capacity for near infrared detector arrays, with Osaka-based sensor packaging facilities and Shenzhen contract electronics manufacturers completing device assembly. The supply chain draws from indium phosphide substrates, gallium arsenide wafers, and specialized optical filters as critical inputs. Single-source vulnerability in InGaAs sensor production creates exposure to foundry allocation decisions during capacity crunches. Distribution runs through hospital group purchasing organizations in North America, direct procurement by integrated delivery networks, and regional medical device distributors serving European diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vein illuminator market sits in early-cycle expansion as regulatory mandates for first-attempt vascular access success accelerate replacement of legacy transillumination devices across pediatric and geriatric care units.
For Market Incumbents: Harden algorithm lock-in through mandatory software update subscriptions that tether hospital procurement committees to proprietary visualization platforms. Deepen backward integration into indium gallium arsenide sensor design to insulate margins from Taiwanese foundry price volatility. Expand ISO 13485-certified service infrastructure across Germany and Japan to capture multi-year calibration contracts displacing independent service organizations.
For New Entrants and Emerging Players: Build out cost-optimized portable configurations for India's district hospital tier under harmonized CDSCO-ISO pathways, where simplified calibration protocols and localized assembly partnerships circumvent import tariff structures. Target wireless data transmission integration as a differentiated feature for ambulatory surgery centers seeking EMR documentation compliance without premium-tier pricing.
For Investors and Strategic Acquirers: Algorithm developers with FDA-cleared training datasets and post-market surveillance protocols represent the most defensible acquisition archetype as EU AI Act compliance burdens extend validation timelines for automated vein detection systems. Monitor German notified body queue lengths for optical imaging devices with AI components as an inflection indicator for regulatory-driven consolidation pressure. Quarterly review of GPO contract renewal rates and METI subsidy allocation shifts is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Streamlining | Accelerated clearance timelines compress time-to-market for near infrared device manufacturers targeting US hospital procurement cycles. |
| EU MDR Clinical Validation | Stricter venipuncture accuracy standards displace legacy transillumination devices ahead of certificate expiration deadlines in German diagnostic centers. |
| Hospital System Partnership | Multi-year service agreements with GPO-negotiated terms lock in replacement component revenue and displace third-party biomedical engineering firms. |
| Software Companion Development | Bluetooth Low Energy-enabled documentation integration addresses ambulatory surgery center workflow requirements without hardware platform swaps. |
| Reimbursement Strategy | Pediatric first-attempt success mandates in US and German children's hospitals create procurement preference for premium-tier portable systems. |
Research Methodology
The analysis maps portable, wearable, handheld, and tabletop device configurations, each validated through hospital purchasing committees, biomedical engineering directors, GPO contracts managers, and phlebotomy operations supervisors across primary interviews with secondary triangulation against FDA 510(k) filings, EU MDR notified body submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up unit shipment estimates and top-down value aggregation cross-validate segmentation outputs across the analysis window.
Assumptions held regulatory pathway timelines and sensor input cost trajectories within observed patterns while varying adoption penetration rates across pediatric emergency departments, geriatric long-term care facilities, and high-throughput diagnostic centers. The projection framework models technology transitions from transillumination to near infrared imaging, product type shifts toward wearable miniaturization, and end-user concentration through integrated delivery network consolidation. CAGRs derive from procedure volume elasticity to venipuncture accuracy mandates and replacement cycle compression under EU MDR certificate expiration deadlines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by algorithm-native entrants or foundry-integrated device manufacturers would shift outcomes beyond modeled ranges. Regulatory reclassification under EU AI Act risk tiers, indium gallium arsenide sensor supply disruptions, or GPO contract consolidation beyond historical concentration levels represent specific revision triggers. Quarterly review of German notified body queue lengths, METI subsidy allocation rates, and Indian CDSCO import clearance timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electric Handpiece Market
Medical Devices
Ventilator Accessories Market
Medical Devices
Veterinary Injectable Devices Market
Medical Devices
Europe Clear Aligners Market
Medical Devices
Sterile Filtration Module Market
Medical Devices
Skincare Devices Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
Manual Resuscitators Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Healthcare Additive Manufacturing Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Hospital and Pre-Hospital External Defibrillator Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market
Medical Devices
Radiotherapy Devices Market