
 South America C-Arms Market | 2026-2036
South America C-Arms Market Size, Share, and Industry Trends Forecast 2026-2036
South America C-Arms Market Outlook
Flat-panel detector technology is restructuring South America C-Arms product economics by displacing legacy image intensifier architectures that carried heavier maintenance burdens and shorter replacement cycles. Siemens Healthineers leverages its digital fluoroscopy portfolio to anchor premium positioning across Brazilian university hospital networks. Ziehm Imaging GmbH specializes in mobile surgical C-Arms with compact footprints suited for Latin American ambulatory surgery centers with constrained cath lab infrastructure. GE Healthcare dominates refurbished system channels that sustain affordability for mid-tier public hospital procurement programs.
C-Arms are motorized X-ray imaging systems with C-shaped gantry architectures that rotate around the patient table, typically operating at 50-120 kV tube voltage with flat-panel detectors capturing real-time fluoroscopic sequences for intraoperative guidance. Mobile C-Arms command the broadest installed base across South American surgery centers due to their flexibility across orthopedic, trauma, and pain management workflows. Digital C-Arms with 3D imaging capability represent the fastest-expanding technology segment as Brazilian and Colombian hospitals prioritize cone-beam CT integration for complex spinal navigation. Fixed C-Arms retain stable demand within cardiovascular catheterization laboratories where dedicated room installations support high-volume interventional cardiology programs.
ANVISA governs medical device registration and post-market surveillance in Brazil, enforcing Good Manufacturing Practice alignment that filters non-compliant Asian manufacturers from direct market entry. Argentina's national administration of medications, food and medical technology applies parallel import licensing requirements that extend product approval timelines for multinational imaging vendors. Colombia's INVIMA operates risk-based classification protocols that accelerate clearance for Class II diagnostic equipment while maintaining technical documentation standards. Stakeholders must monitor how Mercosur harmonization negotiations reshape mutual recognition agreements for medical device certifications across the southern cone.
Market Dynamics
Flat-panel detector migration is compressing replacement cycles across South American hospital networks while simultaneously elevating minimum performance thresholds for new system procurement.
Growth Catalysts
- ANVISA streamlined registration:Brazil's medical device regulator has reduced technical documentation requirements for digital imaging systems, accelerating import timelines for advanced fluoroscopy equipment.
- Minimally invasive spine adoption:Orthopedic clinics across São Paulo state corridors are investing in real-time 3D navigation capabilities to support complex vertebral fusion procedures.
- Cone-beam CT integration:Brazilian and Colombian hospitals are prioritizing intraoperative tomography for surgical precision, creating pull-through demand for detector upgrades.
Market Restraints
- Import dependency for core components:Flat-panel detectors and high-voltage generators concentrate manufacturing in German and Japanese supply bases, exposing Brazilian distributors to currency volatility and extended lead times.
- ANVISA Good Manufacturing Practice alignment:Non-compliant Asian manufacturers face direct market exclusion, limiting price competition at the economy tier.
- Legacy infrastructure lock-in:Public hospital networks in Argentina and Chile retain functional image intensifier systems, depressing replacement urgency despite superior digital alternatives.
Strategic Opportunities
- Refurbished system channels:Mid-tier public hospital procurement programs in Brazil present volume potential for certified pre-owned digital C-Arms with warranty coverage.
- Ambulatory surgery center expansion:Compact mobile systems with reduced cath lab footprints address infrastructure constraints across Latin American outpatient facilities.
- Mercosur harmonization:Mutual recognition negotiations for medical device certifications could collapse redundant approval processes across Argentina, Brazil, Paraguay, and Uruguay.
Industry Challenges
- Specialized biomedical engineering scarcity:Flat-panel calibration and detector maintenance require trained technicians that Brazilian technical institutes currently produce in insufficient volume.
- Multi-vendor integration complexity:Surgical navigation software from independent suppliers demands proprietary interface protocols that complicate interoperability with existing PACS infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America C-Arms Market |
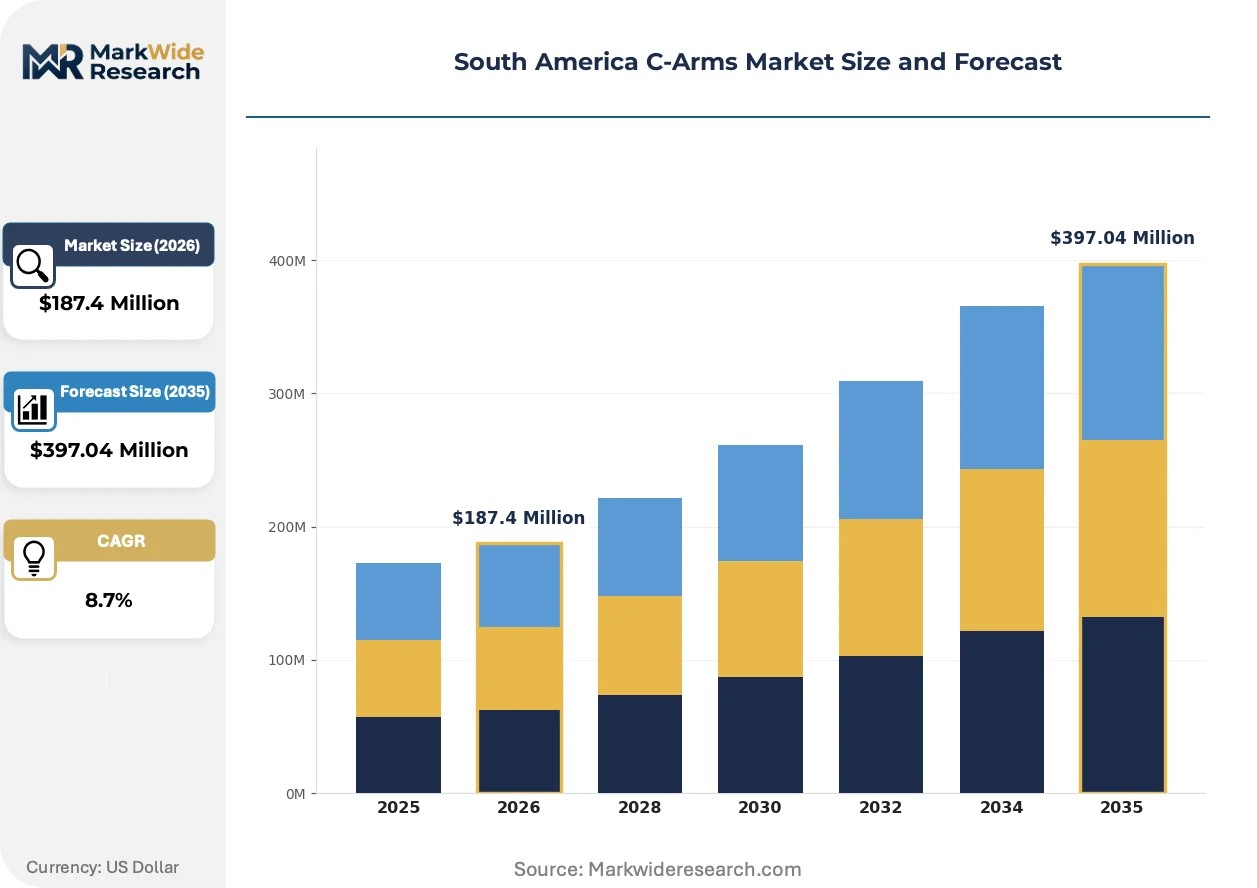
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed C-Arms, Mobile C-Arms, Mini C-Arms, High-End C-Arms End User: Hospitals, Surgery Centers, Orthopedic Clinics, Diagnostic Imaging Centers Technology: Analog C-Arms, Digital C-Arms, Fluoroscopy, 3D Imaging Application: Orthopedic Surgery, Cardiovascular Procedures, Gastroenterology, Pain Management |
| Companies Covered | Philips Healthcare, GE Healthcare, Siemens Healthineers, Ziehm Imaging GmbH, Canon Medical Systems Corporation, Koninklijke Philips NV, Shimadzu Corporation, Hologic Inc., Medtronic plc, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America C-Arms Market Strategic Shifts
Digital fluoroscopy architectures are restructuring competitive positioning across South American imaging markets, with three interconnected developments reshaping how hospitals evaluate capital equipment investments.
Flat-panel detector technology is electrifying product economics by eliminating vacuum-tube image intensifiers and their associated maintenance burdens. Brazilian university hospital networks are adopting these solid-state architectures at accelerated pace, compressing acceptable system lifecycles from fifteen years toward seven-year replacement horizons. This electrification is forcing distributors to restructure service contract pricing around detector warranty periods rather than mechanical component longevity.
ANVISA's risk-based classification protocols for Class II diagnostic equipment are tightening technical documentation standards while paradoxically accelerating clearance timelines for compliant submissions. Industrial consequence flows through procurement departments, which now prioritize vendors with established Brazilian regulatory affairs capabilities over price-competitive newcomers. Colombian INVIMA operates parallel protocols, creating divergent compliance burdens that multinational suppliers must navigate simultaneously.
Hospital procurement departments are unbundling after-sales service from equipment acquisition, demanding transparent parts pricing and third-party maintenance rights. This behavioral shift disrupts traditional vendor lock-in strategies across São Paulo and Rio de Janeiro state networks. The fragmentation is most visible in cardiovascular catheterization laboratories, where high-volume interventional cardiology programs negotiate separate service agreements from capital purchase contracts.
South America C-Arms Market Segmentation
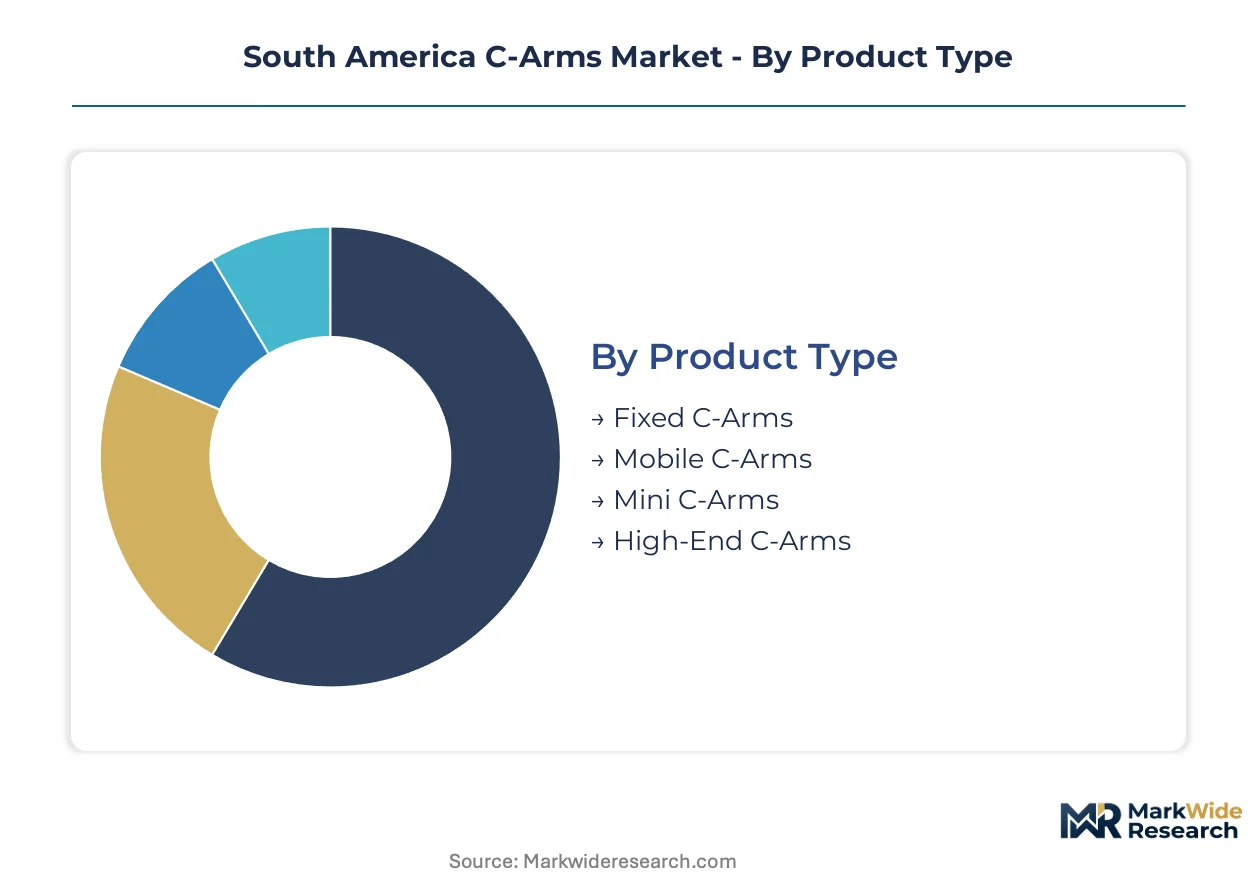
C-Arms procurement patterns across South America diverge sharply by facility infrastructure, surgical volume, and reimbursement tier. Understanding these fault lines enables vendors to align detector specifications, mobility features, and service contract structures with buyer capabilities and clinical priorities.
Product Type:
Budget flexibility and cath lab footprint constraints differentiate buyers across Brazilian and Colombian hospital networks.
- Mobile C-Arms:Motorized systems with rotating C-shaped gantries operate at 50-120 kV tube voltage, delivering real-time fluoroscopic guidance without fixed room installation. São Paulo state surgery centers prioritize these units for orthopedic and trauma workflows where room sharing maximizes capital utilization. ANVISA registration streamlining accelerates import timelines for digital mobile configurations.
- Fixed C-Arms:Permanent installations integrate with dedicated cardiovascular catheterization laboratories, supporting high-volume interventional cardiology through ceiling-suspended or floor-mounted architectures. Rio de Janeiro university hospital networks anchor demand here, driven by complex electrophysiology and structural heart procedures requiring stable, high-resolution imaging chains.
- Mini C-Arms:Compact units with reduced source-to-image distances serve extremity-focused orthopedic practices and podiatry clinics across Argentina's ambulatory sector.
- High-End C-Arms:Premium configurations with flat-panel detectors and 3D cone-beam capability target Brazilian private hospital groups performing advanced spinal navigation.
Volume sits with Mobile C-Arms across mid-tier public procurement; growth tilts toward High-End C-Arms in southeastern Brazilian private networks.
End User:
Reimbursement scale and surgical case complexity determine detector performance requirements and replacement cadence.
- Hospitals:Multi-service institutions with dedicated radiology departments and interventional suites command the broadest C-Arms installed base, spanning emergency trauma bays through electrophysiology labs. Brazilian SUS-funded public hospitals and large private groups in São Paulo and Rio de Janeiro states concentrate procurement volume, though budget fragmentation between federal, state, and municipal funding streams complicates capital planning.
- Surgery Centers:Ambulatory facilities with constrained infrastructure prioritize compact mobile systems and rapid room turnover capabilities. Colombian outpatient surgical networks in Bogotá and Medellín corridors are expanding fluoroscopy capacity for same-day orthopedic and pain management procedures.
- Orthopedic Clinics:Specialized spine and joint practices across Brazil's southeastern corridor drive demand for 3D navigation integration.
- Diagnostic Imaging Centers:Standalone facilities focus on fluoroscopy for barium studies and arthrography, with lower surgical navigation requirements.
Procurement volume clusters at Hospitals; expansion rates peak at Surgery Centers adapting to outpatient migration.
Technology:
Image acquisition architecture separates maintenance burden, detector longevity, and interoperability with surgical navigation ecosystems.
- Digital C-Arms:Solid-state flat-panel detectors capture fluoroscopic sequences with direct digital readout, eliminating vacuum-tube image intensifiers and their phosphor degradation. Brazilian university hospital networks are compressing replacement cycles toward seven-year horizons as these architectures displace legacy systems. ANVISA technical documentation requirements now prioritize vendors with established digital imaging regulatory track records.
- 3D Imaging:Cone-beam CT integration enables intraoperative tomographic reconstruction for complex spinal and cranial navigation. Colombian INVIMA risk-based classification protocols accelerate clearance for these Class II diagnostic configurations, pulling demand from academic medical centers in Bogotá.
- Analog C-Arms:Image intensifier-based systems persist in Argentine and Chilean public hospitals with limited capital refresh budgets.
- Fluoroscopy:Continuous X-ray acquisition for real-time guidance remains the baseline functional requirement across all product tiers.
Installed base remains weighted toward Analog C-Arms in southern cone public networks; upgrade momentum concentrates in Digital C-Arms with 3D capability.
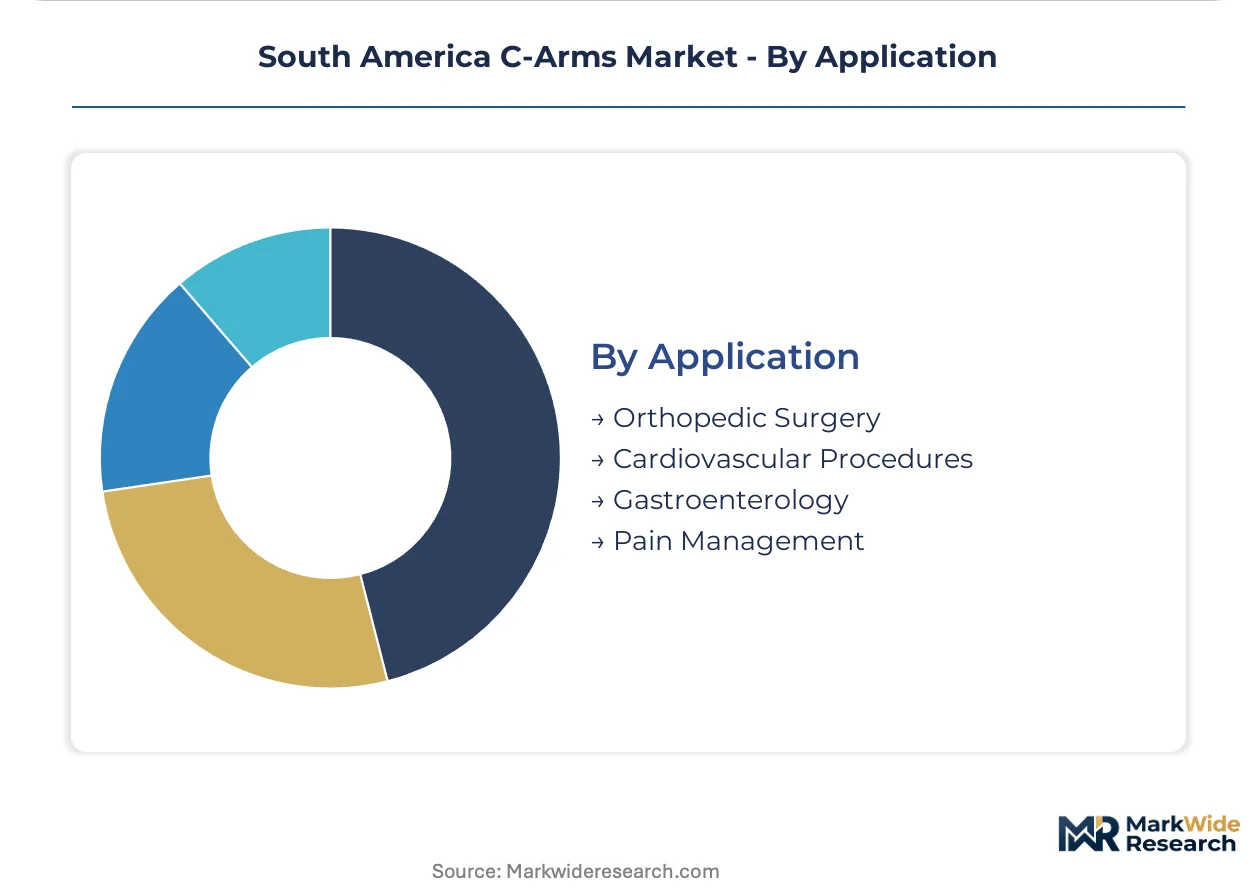
Application:
Surgical precision requirements and reimbursement intensity shape detector resolution priorities and navigation software integration needs.
- Orthopedic Surgery:Vertebral fusion, fracture fixation, and joint replacement procedures demand real-time 3D navigation for screw placement accuracy. São Paulo state spine clinics are expanding fluoroscopy capabilities specifically for minimally invasive approaches that reduce recovery times and complication rates.
- Cardiovascular Procedures:Interventional cardiology, electrophysiology, and structural heart interventions require high frame-rate fluoroscopy with low-dose optimization. Rio de Janeiro catheterization laboratories anchor regional demand for fixed C-Arms with advanced image processing.
- Pain Management:Epidural injections and nerve blocks utilize C-Arm guidance for needle placement precision, with growing adoption in Colombian ambulatory settings.
- Gastroenterology:ERCP and stent placement procedures employ fluoroscopy for biliary and pancreatic duct navigation, though volume concentrates in dedicated endoscopy suites with specialized equipment.
Procedure volume concentrates in Orthopedic Surgery; technology upgrade rates run highest in Cardiovascular Procedures demanding dose optimization and image quality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement volume concentrates in Brazil's southeastern hospital corridor, where São Paulo and Rio de Janeiro state networks drive digital fluoroscopy upgrades. Argentina, Colombia, Chile, and Peru follow with distinct regulatory environments and infrastructure constraints shaping C-Arms adoption patterns.
Brazil
Minimally invasive spine procedures and interventional cardiology programs anchor demand across São Paulo's university hospital networks. ANVISA's streamlined registration pathways for Class II diagnostic equipment accelerate import timelines for digital imaging systems. The southeastern corridor spanning São Paulo and Rio de Janeiro concentrates procurement volume for both mobile and fixed C-Arms configurations.
Argentina
Public hospital networks retain functional image intensifier systems, depressing replacement urgency despite superior digital alternatives. The national administration of medications, food and medical technology applies parallel import licensing requirements that extend approval timelines for multinational imaging vendors. Buenos Aires province clusters the majority of ambulatory surgery center expansion targeting compact mobile fluoroscopy units.
Colombia
Outpatient surgical networks in Bogotá and Medellín corridors are expanding fluoroscopy capacity for same-day orthopedic and pain management procedures. INVIMA's risk-based classification protocols accelerate clearance for Class II diagnostic equipment while maintaining technical documentation standards. Academic medical centers in Bogotá prioritize cone-beam CT integration for complex spinal navigation workflows.
Chile
Legacy infrastructure lock-in persists across public hospital networks with limited capital refresh budgets for detector upgrades. The country's national pharmaceutical and medical device regulator enforces Good Manufacturing Practice alignment that filters non-compliant manufacturers from direct market entry. Santiago Metropolitan Region anchors private hospital procurement for premium digital C-Arms with 3D imaging capability.
Peru
Diagnostic imaging centers in Lima concentrate fluoroscopy demand for barium studies and arthrography with lower surgical navigation requirements. The country's health technology regulator maintains technical documentation standards for imported medical equipment that extend initial market entry timelines. Coastal urban clusters drive modest mobile C-Arms adoption for trauma and emergency department workflows.
South America C-Arms Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium digital fluoroscopy systems commanding distinct procurement channels from refurbished equipment programs. The vendor base concentrates around multinational imaging conglomerates with established Brazilian regulatory affairs capabilities, filtering price-competitive newcomers from direct market participation. Three archetypes dominate: full-line diagnostic imaging conglomerates, mobile surgical C-Arms specialists, and certified pre-owned equipment distributors. Strategic moves center on detector technology licensing partnerships and geographic expansion through distributor network consolidation.
Within the premium-tier vector, Siemens Healthineers and Philips Healthcare occupy positions anchored by digital fluoroscopy portfolios across Brazilian university hospital networks. Ziehm Imaging GmbH exemplifies the mobile surgical C-Arms specialist archetype with compact footprint configurations suited for Latin American ambulatory surgery centers. GE Healthcare sits within the refurbished system channel, sustaining affordability positioning for mid-tier public hospital procurement programs through certified pre-owned digital C-Arms with warranty coverage.
| Leading Market Players |
|---|
| Philips Healthcare |
| GE Healthcare |
| Siemens Healthineers |
| Ziehm Imaging GmbH |
| Canon Medical Systems Corporation |
| Koninklijke Philips NV |
| Shimadzu Corporation |
| Hologic Inc. |
| Medtronic plc |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between ANVISA-compliant digital systems and non-compliant legacy equipment manifests in pricing spreads exceeding three-to-one at procurement, while simultaneously compressing distributor margins through extended warranty obligations and specialized biomedical engineering requirements. Brazilian public hospital networks face procurement fragmentation across federal, state, and municipal funding streams that amplifies price sensitivity at the economy tier, whereas southeastern private hospital groups absorb premium positioning for cone-beam CT integration.
Pricing Analysis
Volume-margin splits concentrate mobile C-Arms at thin margins through mid-tier public procurement programs, while fixed-room installations with 3D navigation capability command substantial premiums. Three-tier pricing structure across premium, standard, and economy levels reflects detector resolution grades, ANVISA registration status, and after-sales bundling arrangements. Cost compression in refurbished digital channels is intensifying because GE Healthcare and certified pre-owned distributors expand warranty-backed inventory. Public hospital procurement committees exhibit highest price sensitivity; private orthopedic clinic networks in São Paulo demonstrate lowest sensitivity given reimbursement rates for minimally invasive spine procedures.
Supply Chain Analysis
Dual-sourcing requirements for flat-panel detectors and high-voltage generators mandate qualification of both German and Japanese component suppliers, extending lead times for Brazilian distributors navigating currency volatility. Manufacturing concentrates in Germany, Japan, and the United States for core imaging chain components, with final assembly and regulatory packaging distributed through São Paulo-based facilities. Supply chain risk centers on single-source vulnerability for solid-state detector substrates and specialized X-ray tube glass envelopes. Distribution runs through authorized distributor networks with embedded regulatory affairs capabilities, filtering direct manufacturer-to-hospital transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA Good Manufacturing Practice alignment operates as a cost-of-compliance moat, filtering price-competitive Asian manufacturers from direct Brazilian market entry and sustaining margin premiums for established regulatory affairs capabilities.
For Market Incumbents: Anchor market position through backward integration into detector calibration service networks and exclusive hospital system partnerships that lock out competing navigation software vendors. Siemens Healthineers and Philips Healthcare face emerging pressure from Ziehm Imaging's compact mobile configurations; defensive capacity addition in Colombian and Chilean distributor networks extends geographic control. Certification investment in INVIMA parallel track registrations accelerates clearance velocity for cone-beam CT configurations. For New Entrants and Emerging Players: Capture white-space opportunity in refurbished digital C-Arms with warranty coverage for Argentine and Peruvian public hospital networks, where capital refresh budgets lag Brazilian levels by four-to-six years. The most penetrable segment sits with ambulatory surgery centers across Bogotá and Medellín corridors demanding compact footprints. Go-to-market angle emphasizes third-party maintenance rights and transparent parts pricing that unbundles traditional vendor lock-in. For Investors and Strategic Acquirers: Re-rating potential sits with mobile surgical C-Arms specialists given cone-beam CT integration pull-through and outpatient surgical migration across Latin America. Long-term viability over a five-to-ten year window favors archetypes with established Brazilian regulatory affairs infrastructure and detector technology licensing partnerships. Signal to watch: Mercosur harmonization implementation collapsing redundant approval processes across Argentina, Brazil, Paraguay, and Uruguay.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Streamlining | Accelerated import timelines compress working capital cycles for digital imaging distributors. |
| Flat-Panel Detector Technology Licensing | Partnerships with German and Japanese component suppliers anchor premium product positioning. |
| Refurbished System Channel Expansion | Certified pre-owned inventory with warranty coverage penetrates mid-tier public procurement. |
| Cone-Beam CT Integration Development | Intraoperative tomography capability pulls demand from São Paulo spine clinic networks. |
| Third-Party Maintenance Rights Negotiation | Unbundled service contracts disrupt traditional vendor lock-in across Rio de Janeiro state networks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital purchasing committee directors, biomedical engineering managers, GPO contracts administrators, and distributor regulatory affairs leads. ANVISA registration databases, INVIMA clearance records, hospital procurement platform disclosures, and import manifest data provided volume triangulation. Bottom-up facility-level equipment counts reconciled against top-down trade flow analysis.
Data-stream reconciliation across shipment records, installed base surveys, and capital expenditure disclosures informed the analytical framework. Segmentation dimensions modeled include product mobility tier, detector technology architecture, end-user facility type, application workflow, and state-level procurement funding source. CAGRs derived from logistic diffusion curves fitted to digital replacement cycle compression patterns, with surgical volume growth and reimbursement rate trajectories as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Mercosur harmonization negotiations, Brazilian real exchange rate volatility, and flat-panel detector supply allocation priorities. Forecasts reflect documented assumptions regarding replacement cycle compression rates and outpatient surgical migration velocity. Deviation in ANVISA regulatory enforcement intensity or INVIMA classification protocol revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market
Medical Devices
Global Brachytherapy Treatment Planning Systems Market
Medical Devices
Australia Aesthetic Devices Market
Medical Devices
Manual Wheelchair Market
Medical Devices
Luer Lock Connector Market
Medical Devices
United States Small Bone and Joint Devices Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Body Contouring Devices and Procedures Market
Medical Devices
Global Ablation Technologies Market
Medical Devices
Blood Warmer Devices/Sample Warmer Market
Medical Devices
Complementary Therapy Devices Market
Medical Devices
Occlusion Balloon Catheter Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
Wearable Artificial Kidney Market
Medical Devices
Retinal Implant Market
Medical Devices
US Orthopedic Spine Navigation Systems Market