
 Computer Aided Trauma Fixators Market | 2026-2036
Computer Aided Trauma Fixators Market Size, Share, and Industry Trends Forecast 2026-2036
Computer Aided Trauma Fixators Market Outlook
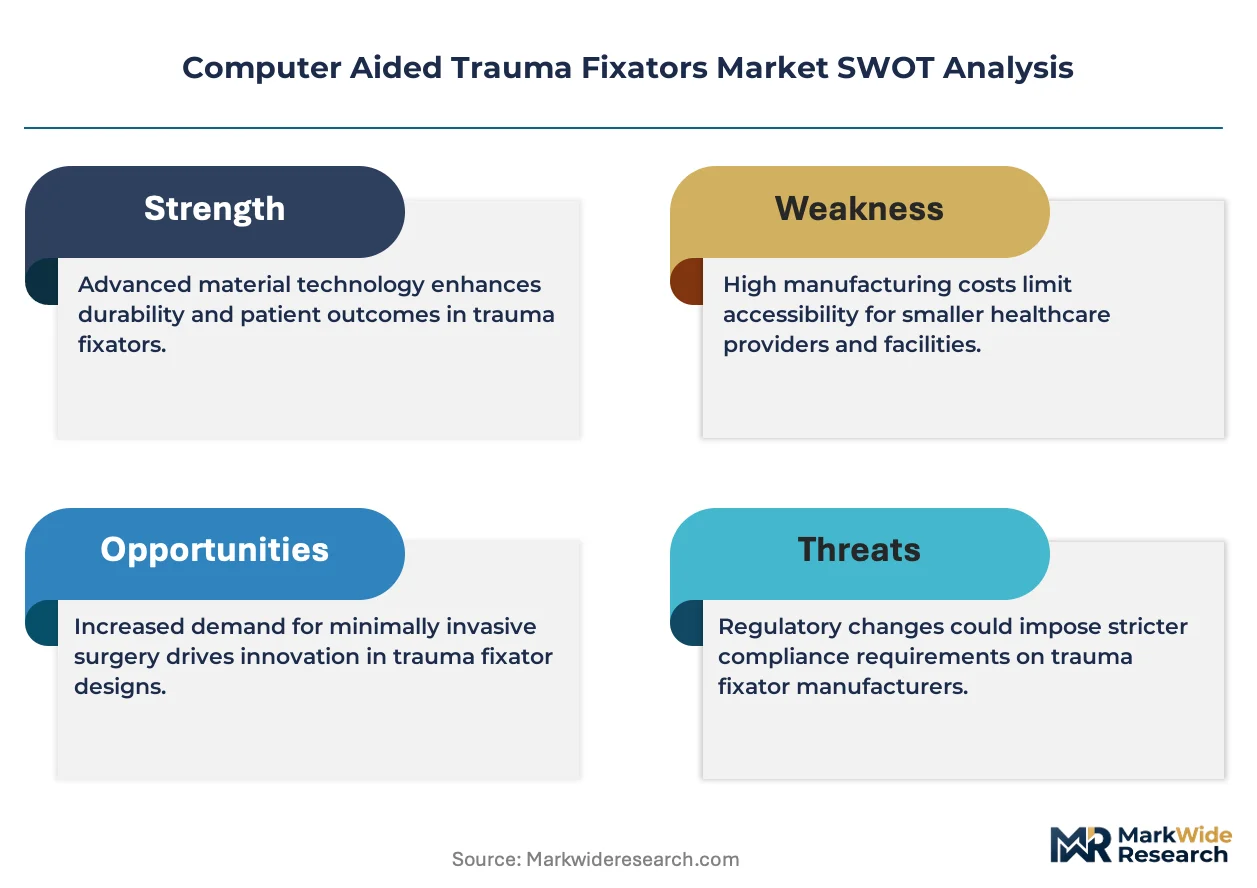
Buyer concentration across trauma centers is rebalancing as mid-sized orthopedic clinics adopt computer-aided surgical planning tools previously limited to academic hospitals. Stryker Corporation leverages its integrated robotics-imaging ecosystem to anchor premium positioning in robotic-assisted trauma fixation. Smith & Nephew differentiates through specialized software-hardware bundles for complex pelvic reconstruction. Orthofix Medical Inc. competes in the ambulatory surgery center channel with streamlined external fixator systems.
Computer aided trauma fixators comprise orthopedic stabilization devices designed using digital preoperative planning, patient-specific anatomical modeling, and precision manufacturing to achieve optimal fracture reduction and fixation alignment. These systems typically integrate CT-derived 3D reconstructions with mechanical simulation to determine screw trajectories, construct geometries, and load distributions prior to surgery. Internal fixators and hybrid fixators lead current revenue pools, while 3D printing technology segments expand fastest as point-of-care manufacturing gains hospital infrastructure investment. Titanium material segments sustain margin concentration due to biocompatibility requirements and supply chain qualification barriers.
FDA 510(k) and premarket notification pathways govern device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for patient-specific implants. ISO 13485 quality management standards and ASTM F3335 additive manufacturing guidelines shape supplier certification and production scalability across jurisdictions. Stakeholders must monitor evolving reimbursement codes for computer-assisted surgical procedures to capture value from planning software investments.
Market Dynamics
Point-of-care 3D printing infrastructure is compressing lead times for patient-specific trauma implants and redistributing manufacturing control from centralized suppliers toward hospital-based production cells.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated premarket clearance for additively manufactured devices reduces time-to-market for computer-aided fixators. Orthopedic device developers leverage this regulatory efficiency to iterate designs faster.
- Trauma center digitization:Academic medical centers in the United States integrate CT-to-implant workflows into standard fracture protocols. Surgical teams demand preoperative planning software that interfaces directly with imaging archives.
- Titanium powder bed fusion:Advances in metal additive manufacturing enable lattice structures that match bone mechanical properties. Biocompatible porous architectures improve osseointegration outcomes in complex reconstructions.
Market Restraints
- Raw material concentration:Spherical titanium powder supply concentrates among a limited set of qualified gas atomization facilities. Powder lot qualification timelines extend production schedules for patient-specific implants.
- EU MDR clinical evidence requirements:Stricter post-market surveillance and clinical data mandates for custom-made devices elevate compliance costs. Small manufacturers face disproportionate burden relative to large portfolio holders.
- Conventional plating systems:Standardized trauma plates and screws retain cost advantages for uncomplicated fractures. Price-sensitive procurement committees in public hospital systems favor established catalogs over patient-specific alternatives.
Strategic Opportunities
- Ambulatory surgery center channel:Streamlined external fixator systems suited for same-day discharge protocols address an underserved segment. Orthopedic clinics seek compact planning workstations that fit limited facility footprints.
- ISO 13485 certification arbitrage:Contract manufacturers in Eastern Europe and Southeast Asia build quality management capabilities to serve Western device developers. Outsourced production reduces capital requirements for software-focused entrants.
- Artificial intelligence-CT segmentation convergence:Automated anatomical reconstruction from imaging data reduces manual planning labor. Surgical planning software vendors integrate machine learning modules to accelerate preoperative workflow.
Industry Challenges
- Additive manufacturing technician scarcity:Qualified operators for metal 3D printing systems command premium compensation. Hospital-based manufacturing cells struggle to recruit talent with both biomedical and materials processing expertise.
- Legacy PACS integration friction:Surgical planning software must interface with heterogeneous hospital imaging infrastructure. Custom integration projects delay deployment timelines and inflate implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer Aided Trauma Fixators Market |
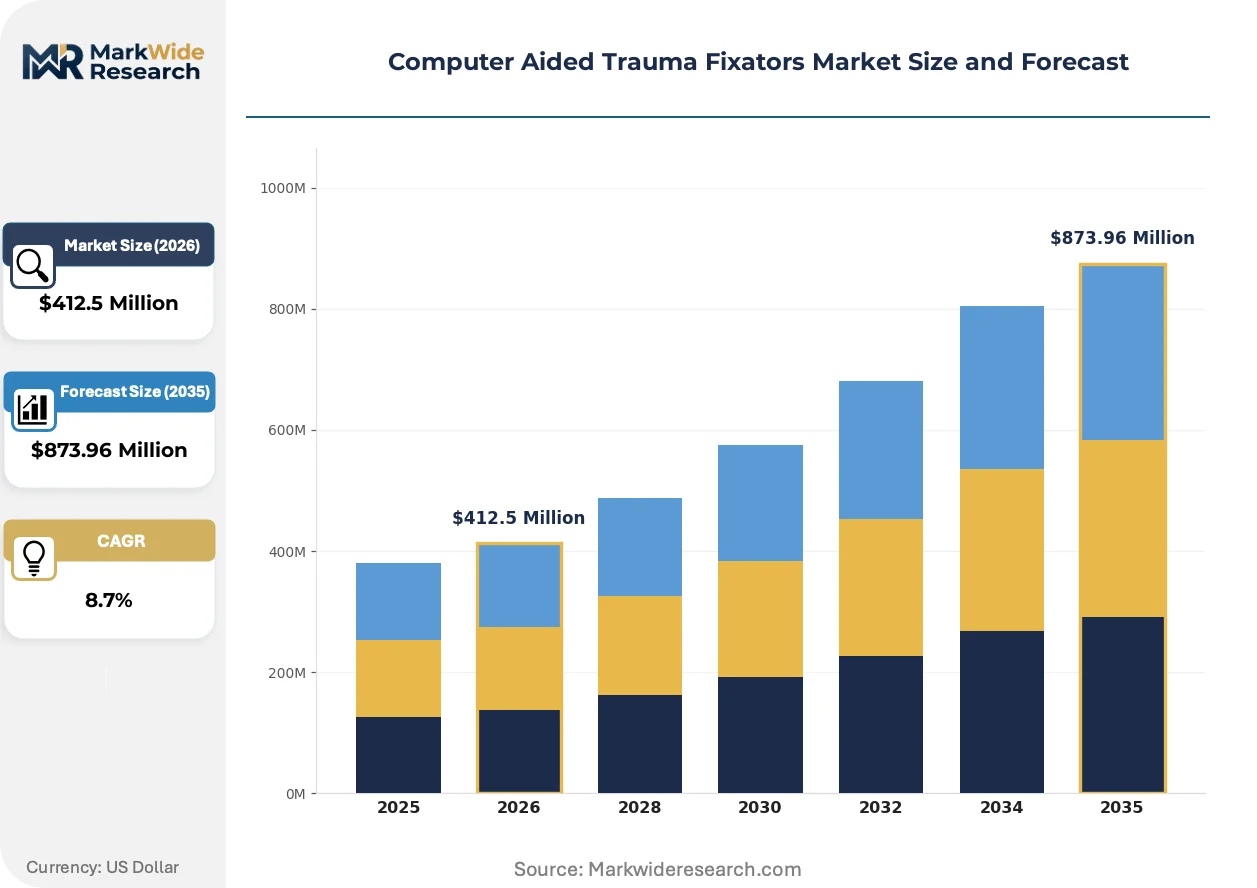
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Fixators, External Fixators, Hybrid Fixators, Intramedullary Nails End User: Hospitals, Clinics, Surgical Centers, Rehabilitation Facilities Technology: Robotic Surgery, Image Guidance, CAD, 3D Printing Material: Titanium, Stainless Steel, Bio-absorbable Polymers, Others |
| Companies Covered | Smith & Nephew, Arthrex Inc., Stryker Corporation, CONMED Corporation, Medtronic PLC, Johnson & Johnson (DePuy Synthes), Orthofix Medical Inc., Integra LifeSciences Holdings Corporation, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer Aided Trauma Fixators Market Strategic Shifts
Digital thread technologies are collapsing the boundary between diagnostic imaging and physical implant production, enabling same-day surgical planning and next-day device availability in equipped facilities.
Machine learning-based screw trajectory optimization is automating the determination of safe corridors for pelvic and acetabular fixation. Trauma surgeons at high-volume centers adopt these tools to reduce intraoperative fluoroscopy exposure. The technology is automating decisions previously requiring extensive fellowship-trained experience, compressing the learning curve for complex fracture patterns.
EU Medical Device Regulation Article 52 requirements for custom-made devices are elevating clinical documentation standards across European markets. Manufacturers must maintain design dossiers and post-market clinical follow-up protocols that parallel implantable device rigor. Patient-specific fixator developers in Germany and Switzerland invest in clinical affairs infrastructure to sustain market access.
Hospital procurement committees increasingly bundle software licensing with hardware acquisition, displacing standalone planning tool subscriptions. Integrated vendor relationships reduce vendor management overhead for supply chain directors. This consolidation pattern concentrates in United States health systems seeking to rationalize orthopedic technology portfolios under value-based care contracts.
Computer Aided Trauma Fixators Market Segmentation
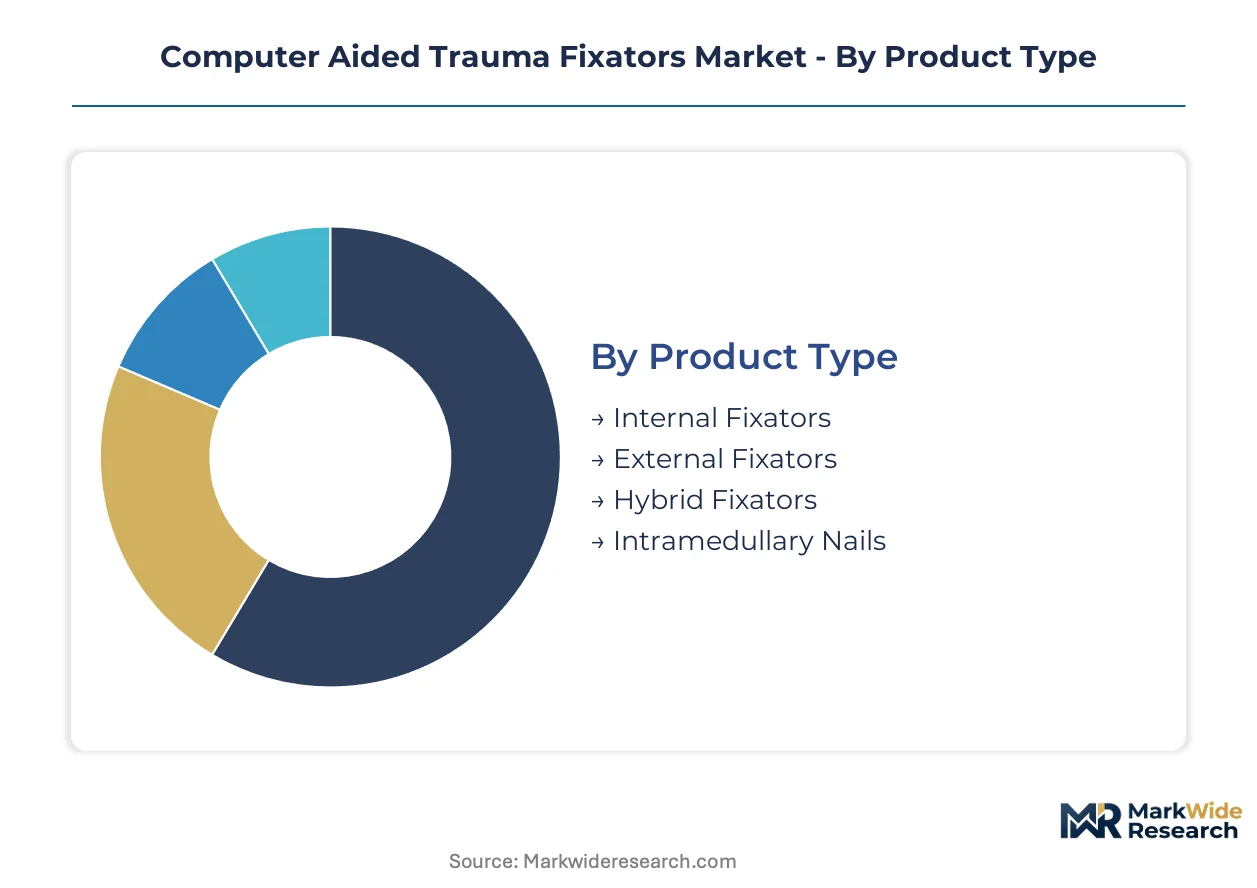
Segmentation in computer aided trauma fixators reveals how digital workflows reshape procurement patterns across care settings. Product architecture, end-user infrastructure readiness, and manufacturing technology each create distinct competitive arenas with divergent margin structures and regulatory pathways.
Product Type:
Integration depth varies sharply—internal fixators embed directly into bone while external and hybrid systems retain modularity for postoperative adjustment.
- Internal Fixators:Plate and screw constructs manufactured via patient-specific CAD/CAM workflows dominate revenue pools. United States trauma centers drive demand for titanium locking plates with preoperative trajectory planning. FDA 510(k) pathway streamlining accelerates design iterations for complex pelvic reconstructions.
- Hybrid Fixators:Combined internal-external systems enable staged fracture management with computer-aided construct optimization. German orthopedic surgical centers expand adoption for open tibia fractures requiring gradual length correction. Modular frame geometries reduce revision surgery rates in high-energy trauma.
- External Fixators:Pin-based stabilization frames suit temporary fixation and limb lengthening protocols.
- Intramedullary Nails:Medullary canal implants with navigated insertion guidance address long-bone diaphyseal fractures.
Internal fixators lead volumes today; hybrid fixators are gaining share fastest.
End User:
Customer infrastructure determines software-hardware bundling feasibility and planning workflow complexity.
- Hospitals:Academic medical centers with integrated PACS and surgical navigation suites capture the deepest planning tool penetration. United States Level I trauma centers mandate CT-to-implant protocols for acetabular and pelvic fractures. Capital equipment budgets accommodate robotic-assisted installation and maintenance contracts.
- Surgical Centers:Ambulatory facilities prioritize compact planning workstations and same-day discharge protocols. Streamlined external fixator systems address limited facility footprints and reduced anesthesia exposure requirements. Orthofix Medical targets this channel with simplified construct assembly.
- Clinics:Outpatient orthopedic practices adopt cloud-based planning subscriptions to avoid capital expenditure.
- Rehabilitation Facilities:Post-acute settings utilize external fixator adjustment protocols for gradual bone transport.
Hospitals retain the dominant spend share; surgical centers show the steepest expansion trajectory.
Technology:
Manufacturing and intraoperative guidance technologies stratify by regulatory maturity and capital intensity.
- 3D Printing:Additive manufacturing enables lattice-structured titanium implants matching bone mechanical properties. Point-of-care production cells in equipped United States hospitals compress lead times from weeks to days. Powder bed fusion advances improve osseointegration outcomes in complex reconstructions.
- Robotic Surgery:Navigated drilling and screw placement systems reduce fluoroscopy exposure in pelvic fixation. Stryker Corporation leverages integrated robotics-imaging ecosystems to anchor premium positioning. High-volume trauma centers adopt these tools to compress fellowship-trained learning curves.
- Image Guidance:Intraoperative navigation overlays preoperative plans onto live imaging for real-time alignment verification.
- CAD:Computer-aided design software forms the foundational layer for patient-specific implant engineering.
3D printing climbs the fastest; image guidance retains the broadest installed base.
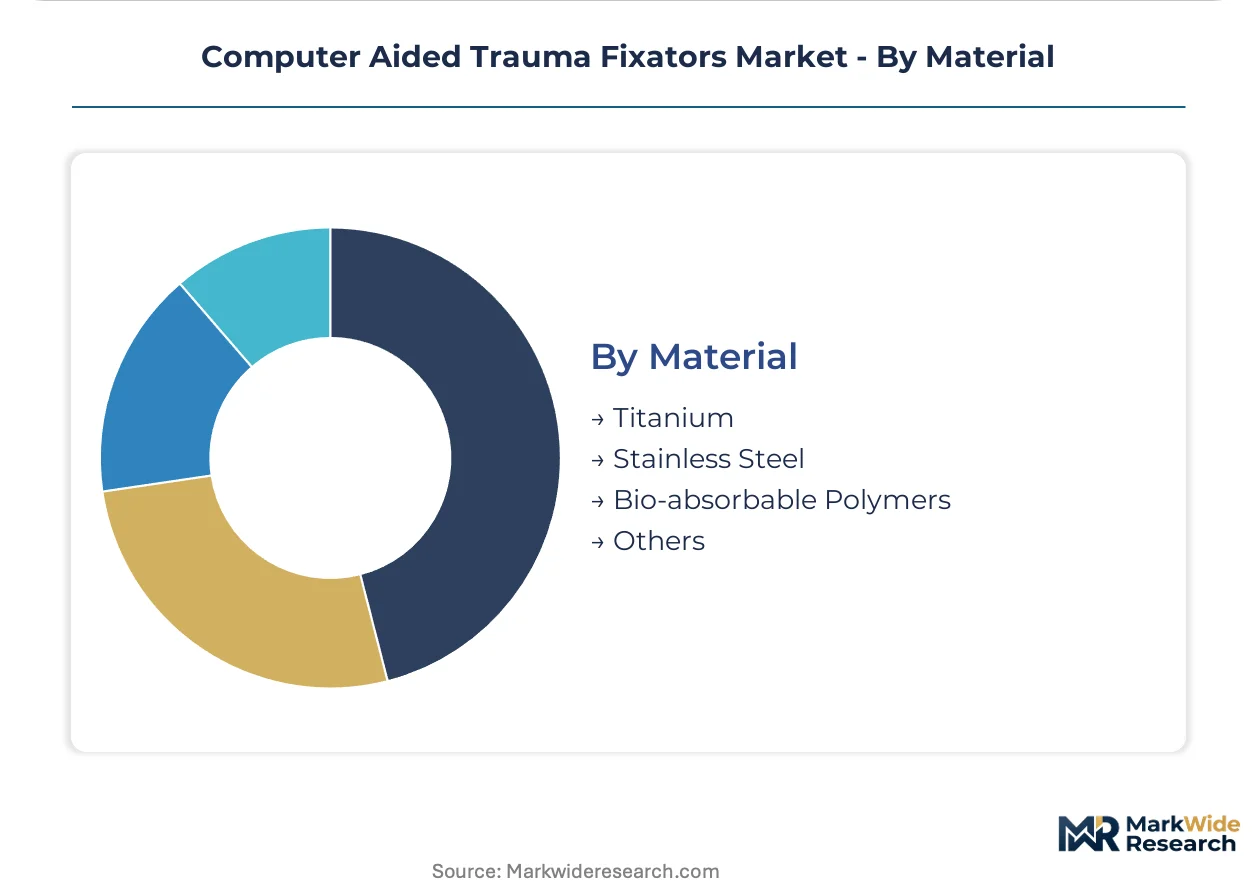
Material:
Biocompatibility requirements and supply chain qualification barriers concentrate margin in certified material grades.
- Titanium:Ti-6Al-4V ELI grade dominates patient-specific implant production due to strength-to-weight ratio and osseointegration performance. Spherical powder supply concentrates among qualified gas atomization facilities, extending lot qualification timelines. German manufacturers invest in vertical powder supply arrangements to secure production schedules.
- Stainless Steel:316L grade retains cost advantages for standardized trauma plates in price-sensitive procurement environments. Public hospital systems in emerging markets favor established catalogs over patient-specific alternatives. Conventional plating systems maintain volume leadership in uncomplicated fracture segments.
- Bio-absorbable Polymers:PLLA and PGA composites address pediatric applications requiring implant dissolution.
- Others:Cobalt-chrome and PEEK ceramics serve niche load-bearing and radiolucent requirements.
Titanium leads revenue concentration; bio-absorbable polymers expand most quickly in pediatric subsegments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German orthopedic surgical centers outpace French adoption of patient-specific implant workflows, while United States trauma centers maintain the deepest penetration of CT-to-implant protocols worldwide.
United States
Level I trauma centers mandate computer-aided planning for acetabular and pelvic fractures, driving software-hardware bundling contracts. FDA 510(k) pathway streamlining accelerates premarket clearance for additively manufactured devices. Academic medical clusters in Boston and Baltimore integrate robotic-assisted fixation into standard protocols.
Germany
Orthopedic surgical centers in Bavaria and North Rhine-Westphalia expand adoption of patient-specific CAD/CAM workflows for complex reconstructions. EU Medical Device Regulation Article 52 imposes stricter clinical evidence requirements for custom-made devices. Manufacturing concentrations around Stuttgart and Munich invest in vertical titanium powder supply arrangements.
Switzerland
Swiss trauma centers leverage precision manufacturing heritage for high-complexity pelvic fixation cases. Swissmedic maintains rigorous post-market surveillance standards for patient-specific implants. Basel and Zurich host specialized clinical affairs infrastructure serving German-speaking European markets.
Japan
Metropolitan Tokyo hospitals adopt image-guided navigation systems for minimally invasive trauma fixation. PMDA regulatory frameworks govern software-as-medical-device classifications for surgical planning tools. Osaka-Kobe industrial corridors concentrate titanium processing capabilities for medical-grade applications.
United Kingdom
NHS England procurement frameworks increasingly bundle planning software with hardware acquisition for orthopedic networks. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines for custom device approvals. London and Manchester academic centers pilot point-of-care 3D printing cells for same-day implant availability.
Computer Aided Trauma Fixators Market Competitive Environment
United States producers anchor the premium robotics-imaging tier; European specialists hold position in patient-specific implant engineering. Market structure concentrates around integrated platform vendors with surgical navigation ecosystems and modular software-hardware bundles. Three archetypes dominate: robotics-anchored systems vendors, specialized reconstruction software developers, and ambulatory-focused external fixation suppliers. Competitive moves center on FDA premarket pathway optimization and hospital procurement committee bundling strategies.
Within the integrated platform tier, Stryker Corporation and Smith & Nephew exemplify divergent specialization vectors—one leveraging robotics-imaging ecosystem integration, the other emphasizing complex pelvic reconstruction software-hardware combinations. Orthofix Medical Inc. occupies a distinct position serving ambulatory surgery center channels with streamlined external fixation systems. These three anchors represent the spectrum from capital-intensive robotics through specialized software to procedural efficiency-focused hardware.
| Leading Market Players |
|---|
| Smith & Nephew |
| Arthrex Inc. |
| Stryker Corporation |
| CONMED Corporation |
| Medtronic PLC |
| Johnson & Johnson (DePuy Synthes) |
| Orthofix Medical Inc. |
| Integra LifeSciences Holdings Corporation |
| Zimmer Biomet |
| Others |
Value Chain & Pricing Dynamics
Point-of-care 3D printing adoption simultaneously compresses production lead times and concentrates margin capture among hospitals with captive manufacturing cells, redistributing pricing power from centralized suppliers toward equipped trauma centers. FDA 510(k) pathway streamlining accelerates design iterations for titanium lattice implants, while spherical powder supply constraints in qualified gas atomization facilities sustain premium pricing for patient-specific constructs.
Pricing Analysis
Capacity additions in United States academic medical centers are reshaping price floors for computer-aided planning software as hospital procurement committees bundle licensing with hardware acquisition. Three-tier pricing structure across premium, standard, and economy levels separates robotic-integrated systems from navigated drilling platforms from standalone CAD subscriptions. Cost compression in the economy tier intensifies because conventional plating systems retain procurement committee favor for uncomplicated fractures. Ambulatory surgery centers exhibit highest price sensitivity; Level I trauma centers with value-based care contracts show lowest.
Supply Chain Analysis
Single-source vulnerability sits with spherical titanium powder qualified for medical-grade additive manufacturing, where gas atomization capacity concentrates in Germany, United States, and Japan. Production draws from Ti-6Al-4V ELI feedstock, surgical navigation electronics, and precision-machined screw components. Tariff exposure on Chinese-sourced rare earth elements in permanent-magnet motors for robotic systems elevates landed costs for navigated platforms. Distribution runs through orthopedic device distributors with GPO contracts, direct hospital procurement for point-of-care cells, and ambulatory surgery center channel specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where trauma center digitization and CT-to-implant protocol standardization concentrate demand toward premium specifications with integrated software-hardware validation.
For Market Incumbents: Acquire point-of-care 3D printing technician training capabilities to defend against hospital-based manufacturing cells poaching service revenue. Consolidate backward integration into spherical titanium powder supply through captive offtake agreements with German and United States atomization facilities. FDA premarket pathway optimization and ISO 13485 certification depth form the priority defensive levers against software-focused entrants lacking production scale. For New Entrants and Emerging Players: The price-point gap between premium robotic-integrated systems and economy-tier external fixators creates white-space opportunity for mid-tier navigated drilling platforms with streamlined planning software. Target ambulatory surgery centers in United States metropolitan corridors with compact workstation footprints and same-day discharge protocols. Cloud-based planning subscriptions with per-procedure licensing bypass capital expenditure barriers at outpatient orthopedic clinics. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers with ISO 13485 certification arbitrage in Eastern Europe and Southeast Asia, serving Western device developers without captive production. Long-term viability across the projection horizon hinges on sustained hospital infrastructure investment in point-of-care manufacturing. Watch FDA reimbursement code expansions for computer-assisted surgical procedures as the inflection signal for planning software value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Manufacturing Cell Deployment | Hospital-based 3D printing compresses implant lead times from weeks to days in equipped United States trauma centers. |
| FDA 510(k) Submission Acceleration | Premarket notification streamlining reduces time-to-market for additively manufactured patient-specific constructs. |
| Hospital System Partnership | Software-hardware bundling contracts with GPO-affiliated networks displace standalone planning tool subscriptions. |
| Software Companion Development | Machine learning-based CT segmentation modules automate anatomical reconstruction and reduce manual planning labor. |
| Reimbursement Strategy | CMS code capture for computer-assisted procedures enables value-based pricing for planning platform investments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with orthopedic surgeons, hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and additive manufacturing technicians with secondary validation against FDA 510(k) filings, CMS reimbursement databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up demand modeling and top-down market sizing triangulated volume and value estimates.
Segment-weighted projections applied product-type splits across internal fixators, hybrid systems, external fixators, and intramedullary nails; end-user stratification across hospitals, surgical centers, clinics, and rehabilitation facilities; technology tiers spanning 3D printing, robotic surgery, image guidance, and CAD; and material grades including titanium, stainless steel, and bio-absorbable polymers. CAGRs derived from installed base growth, procedure volume elasticities, and pricing trajectory assumptions across the modeling period. Titanium powder supply constraints and EU MDR clinical evidence requirements shaped downside scenario boundaries.
Caveats apply where FDA reimbursement code delays, raw material lot qualification timeline extensions, or EU MDR post-market surveillance enforcement shifts could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Global Embolization Particle Market
Medical Devices
Walkers and Rollators Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Transient Elastography Device Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
United States Stair Lift Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Artificial Spine Discs Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Global Angiography Catheters Market
Medical Devices
Digital Respiratory Devices Market
Medical Devices
Pectus Bar System Market
Medical Devices
Novel Vaccine Delivery Systems Market
Medical Devices
Transcatheter Pulmonary Valve Replacement Market