
 Prefilled Glass Syringes Market | 2026-2036
Prefilled Glass Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Prefilled Glass Syringes Market Insights
ISO 11040-4 qualification is reorganizing competitive access in prefilled glass syringes, as manufacturers must demonstrate particulate control and siliconization consistency to serve regulated biologics customers. SCHOTT Pharma leverages its Fiolax borosilicate glass platform to sustain supply relationships with mRNA vaccine producers across North America and Europe. Gerresheimer AG anchors its position through backward integration into tubular glass forming, while Stevanato Group differentiates via its integrated capabilities in glass processing, inspection systems, and contract manufacturing for complex drug-device combinations.
Prefilled glass syringes are cylindrical drug containment systems manufactured from Type I borosilicate glass, typically treated with silicone oil to ensure plunger glide force within ISO-standardized barrel dimensions, designed for pre-sterilized, ready-to-fill administration of injectable therapeutics. Safety syringes with integrated needle shields command premium positioning due to OSHA needlestick prevention alignment and higher compliance burdens in hospital procurement. Luer lock configurations dominate vaccination and antiviral applications where secure connection to vial adapters or safety needles prevents leakage during high-volume immunization campaigns, while homecare end users increasingly specify prefilled formats in hormone therapy to reduce dosing errors and improve adherence outside clinical settings.
FDA container closure integrity guidance, EU MDR technical documentation requirements, and ISO 11040 series standards collectively govern dimensional tolerance, extractables testing, and drug compatibility validation for prefilled glass syringes entering regulated markets. These frameworks elevate barriers for unqualified suppliers while channeling procurement toward manufacturers with established regulatory dossiers and pharmacopeial compliance histories. Stakeholders must monitor evolving USP glass classification revisions and EMA drug-device combination consultation procedures to anticipate qualification timeline shifts and capacity allocation decisions.
Market Dynamics
ISO 11040-4 qualification requirements are compressing supplier access and concentrating procurement among manufacturers with validated particulate control and siliconization consistency, fundamentally restructuring competitive access for regulated biologics customers.
Growth Catalysts
- Self-injection protocols:Biologics manufacturers in homecare segments are expanding prefilled glass syringe procurement as patients adopt hormone therapy and chronic disease management outside clinical settings.
- EU MDR technical documentation:Europe's tightened material traceability standards are elevating demand for qualified suppliers with established regulatory dossiers and pharmacopeial compliance histories.
- mRNA vaccine platforms:Specialized borosilicate glass production corridors in Germany are anchoring supply relationships with vaccine producers across North America and Europe.
Market Restraints
- Borosilicate glass supply concentration:Type I glass forming capacity clusters among specialized European manufacturers, creating vulnerability to energy cost volatility and geographic disruption.
- FDA container closure integrity testing:Extractables validation and drug compatibility documentation requirements extend qualification timelines and elevate R&D expenditure for market entry.
- Plastic syringe substitution:Cyclic olefin polymer alternatives are capturing volume in cost-sensitive generic injectables where thermal stability requirements permit material flexibility.
Strategic Opportunities
- Complex drug-device combinations:Integrated safety syringes with needle shields are commanding premium positioning through OSHA needlestick prevention alignment and higher compliance burdens in hospital procurement.
- US IRA domestic manufacturing incentives:Biologics producers are qualifying North American glass syringe capacity to secure supply chain resilience and federal procurement preference.
- Luer lock configuration expansion:Secure connection designs for vaccination campaigns are creating specification pull from national immunization programs requiring vial adapter compatibility.
Industry Challenges
- Siliconization process control:Maintaining plunger glide force consistency across batch scales requires specialized equipment and technician expertise that concentrates among established manufacturers.
- ISO 11040 series harmonization:Divergent interpretation of dimensional tolerance standards across notified bodies creates certification timeline uncertainty and dossier revision cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prefilled Glass Syringes Market |
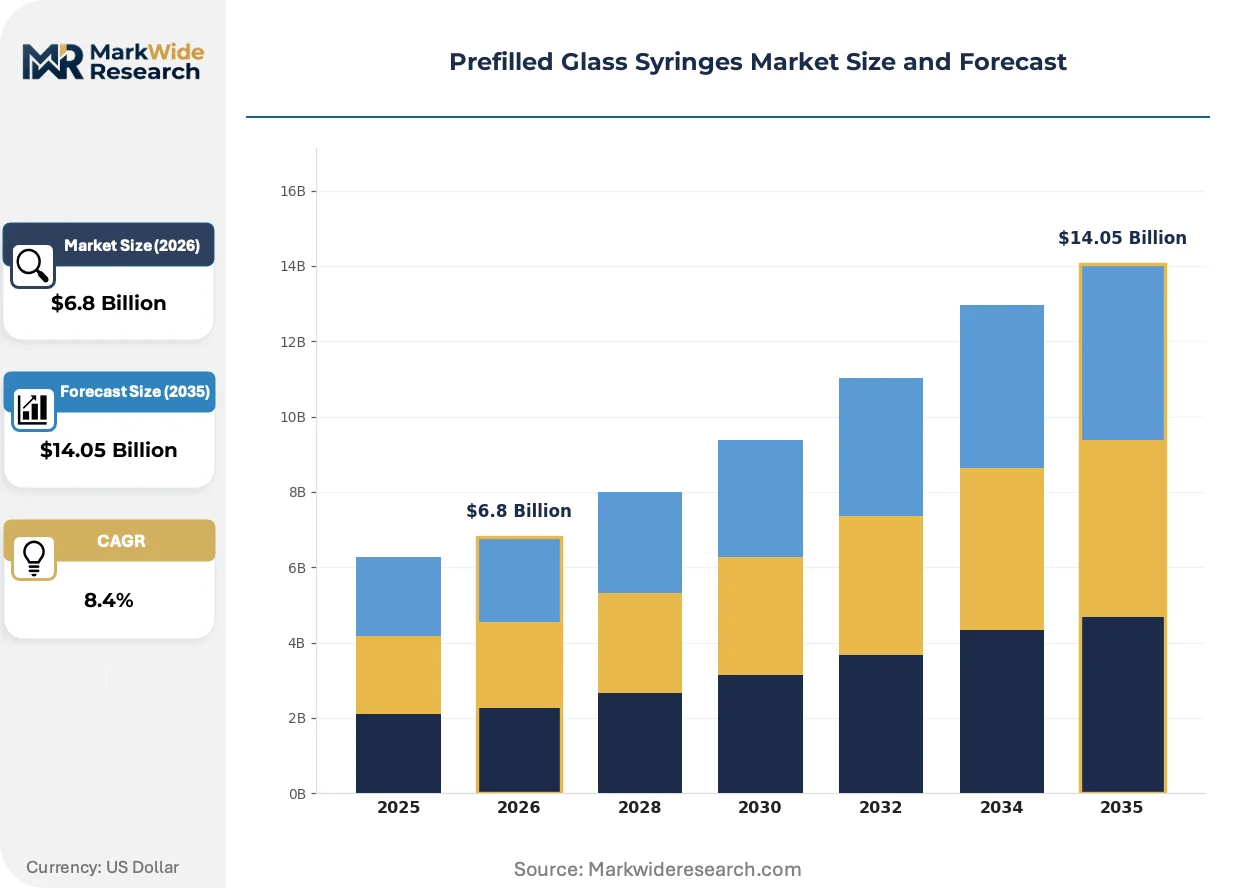
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Syringes, Safety Syringes, Insulin Syringes, Luer Lock Syringes Application: Vaccination, Pain Management, Hormone Therapy, Antiviral Treatment End User: Hospitals, Clinics, Homecare, Pharmacies Material: Glass, Rubber, Silicone, Plastic |
| Companies Covered | Gerresheimer AG, SCHOTT Pharma, BD, West Pharmaceutical Services, Nipro Corporation, Stevanato Group, Terumo Corporation, Taisei Kako Co., Ltd., AptarGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prefilled Glass Syringes Market Trends and Innovations
Ready-to-fill containment formats are compressing aseptic processing steps and reshaping how biologics manufacturers configure fill-finish operations and supplier relationships.
Ready-to-use (RTU) sterilized glass syringes are supplanting bulk unsterilized formats in high-value biologics manufacturing. Contract development and manufacturing organizations are adopting RTU platforms to eliminate in-house washing and depyrogenation capital expenditure. This technology is compressing facility qualification timelines and enabling faster product transfer between manufacturing sites.
EMA drug-device combination consultation procedures are tightening technical documentation requirements for prefilled syringes with integrated delivery systems. Manufacturers must now submit human factors validation and usability engineering files earlier in development cycles. Complex biologics segments are responding by embedding regulatory affairs specialists directly into product development teams.
Hospital procurement consortiums are consolidating supplier qualification around single-source contracts with comprehensive service agreements. Group purchasing organizations are displacing multi-vendor strategies in favor of preferred provider relationships covering safety syringes, needle systems, and disposal containers. This concentration is most visible in US integrated delivery networks managing formulary standardization across multi-state health systems.
Prefilled Glass Syringes Market Segmentation
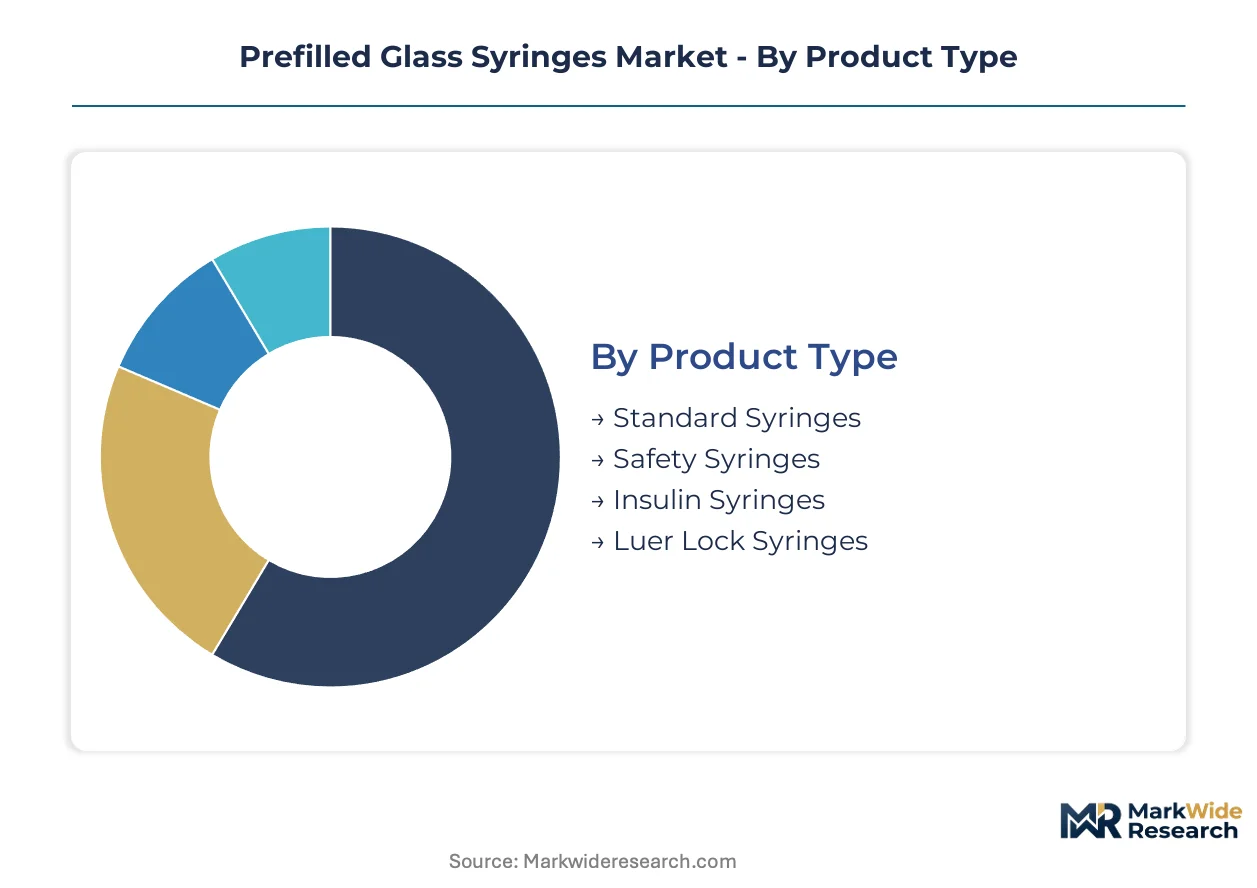
Segmentation in prefilled glass syringes reveals how ISO 11040-4 qualification requirements and drug-device combination complexity concentrate procurement decisions. Manufacturers align product portfolios across four intersecting dimensions that determine pricing power and regulatory burden.
Product Type:
Safety syringes and Luer lock configurations command the widest margin spreads, driven by OSHA compliance mandates and vaccination program specifications.
- Standard Syringes:Basic cylindrical borosilicate glass barrels with silicone-treated interior surfaces for plunger movement. Demand concentrates in generic injectables manufacturing where cost minimization outweighs integrated safety features.
- Safety Syringes:Needle shield integration prevents occupational needlestick injuries per OSHA Bloodborne Pathogens Standard. Hospital procurement consortiums specify these for premium positioning in US integrated delivery networks managing formulary standardization.
- Insulin Syringes:Low-dead-space designs with unit-dose markings for diabetes management protocols. Germany's SCHOTT Pharma and Gerresheimer AG anchor specialized production for European homecare segments.
- Luer Lock Syringes:Threaded hub connections secure vial adapter compatibility during high-volume immunization campaigns. National health ministries specify these for antiviral and vaccination applications requiring leak-proof connections.
Standard syringes hold installed capacity. Safety syringes are rotating up the share rankings.
Application:
Volume concentration clusters in vaccination and antiviral treatment where national immunization programs create specification pull through tender processes.
- Vaccination:Mass immunization campaigns require ISO 11040-4 qualified containers with validated extractables profiles. FDA container closure guidance and EMA drug-device combination procedures govern procurement for mRNA and viral vector platforms.
- Pain Management:Opioid and non-opioid analgesic delivery in acute care settings. Homecare expansion for chronic pain protocols is driving self-injection format adoption outside clinical facilities.
- Hormone Therapy:Endocrine disorder management with patient-administered dosing. Germany's specialized borosilicate glass corridors supply North American and European biologics producers for homecare segments.
- Antiviral Treatment:Pandemic preparedness stockpiling and seasonal prophylaxis distribution. Luer lock configurations dominate where secure connection to safety needles prevents leakage during high-volume administration.
Vaccination commands tender-driven volume. Hormone therapy is climbing the fastest as self-injection protocols expand.
End User:
Procurement authority concentrates in hospital consortiums and homecare channels, with pharmacies capturing residual retail distribution.
- Hospitals:Group purchasing organizations consolidate supplier qualification around single-source contracts with comprehensive service agreements covering safety syringes, needle systems, and disposal containers.
- Clinics:Outpatient infusion centers and specialty care facilities with intermediate volume requirements. Cost sensitivity permits standard syringe formats where safety integration is not mandated.
- Homecare:Patients managing chronic disease and hormone therapy outside clinical settings. FDA's updated container closure guidance shapes qualification requirements for biologics manufacturers serving this segment.
- Pharmacies:Retail dispensing of pre-filled formats for take-home administration. Europe's MDR technical documentation requirements tighten material traceability standards for qualified suppliers.
Hospitals anchor institutional procurement. Homecare is gaining share fastest as self-injection protocols displace clinical administration.
Material:
Type I borosilicate glass maintains pricing power against polymer alternatives where thermal stability and extractables control justify premium positioning.
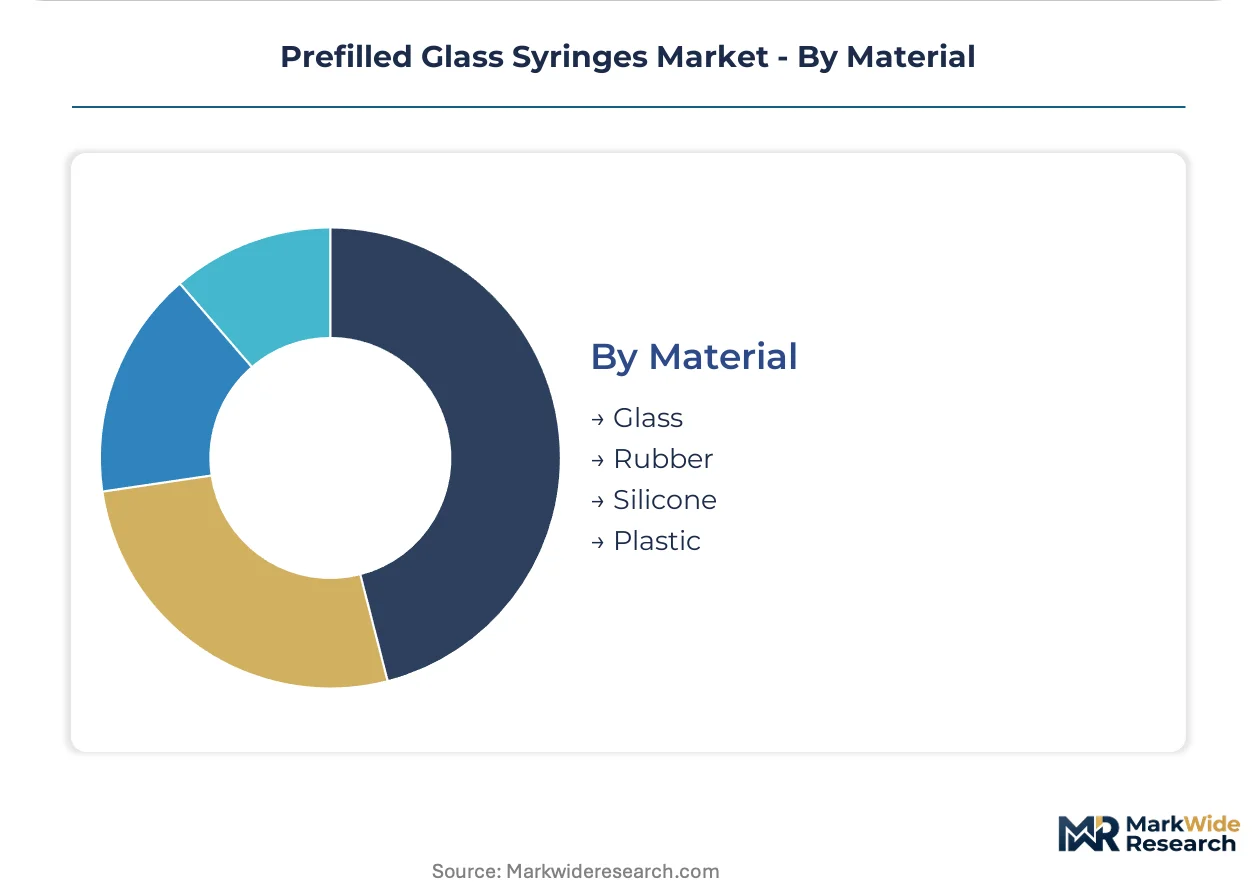
- Glass:Type I borosilicate formulations with controlled hydrolytic resistance per USP and EP pharmacopeial standards. Germany's production corridors anchor supply relationships with mRNA vaccine producers.
- Rubber:Bromobutyl and chlorobutyl elastomer formulations for plunger stoppers and tip caps. Extractables validation requirements extend qualification timelines under FDA container closure integrity guidance.
- Silicone:Medical-grade silicone oil for interior barrel treatment ensuring consistent plunger glide force. Siliconization process control concentrates among established manufacturers with specialized equipment.
- Plastic:Cyclic olefin polymer alternatives capturing volume in cost-sensitive generic injectables. Thermal stability limitations restrict substitution in high-value biologics requiring cold chain integrity.
Glass maintains installed capacity for regulated biologics. Plastic is rotating up the share rankings in generic injectables where material flexibility permits substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US IRA domestic manufacturing incentives are redirecting biologics procurement toward North American glass syringe capacity. Germany's specialized borosilicate production corridors anchor European supply relationships. Japan and India are expanding pharmaceutical packaging infrastructure to serve regional vaccine and hormone therapy demand.
United States
Biologics producers are qualifying domestic glass syringe manufacturing to secure federal procurement preference under IRA provisions. FDA container closure integrity guidance shapes qualification requirements for mRNA vaccine platforms. The Northeast corridor and California clusters concentrate sterile fill-finish operations serving homecare self-injection segments.
Germany
Specialized borosilicate glass production corridors in Bavaria and North Rhine-Westphalia supply North American and European vaccine producers. EU MDR technical documentation requirements tighten material traceability standards for qualified suppliers. SCHOTT Pharma and Gerresheimer AG anchor tubular glass forming capacity in the Mainz-Münchenstein industrial zone.
Japan
PMDA consultation procedures for drug-device combinations are compressing development timelines for integrated safety syringe formats. METI pharmaceutical packaging initiatives support domestic capacity expansion for hormone therapy applications. The Kanto region around Tokyo hosts precision glass processing facilities serving regional biologics manufacturers.
India
CDSCO regulatory harmonization with ICH standards is accelerating qualification timelines for export-oriented glass syringe producers. PLI scheme incentives for medical device manufacturing attract investment into sterile packaging infrastructure. Gujarat and Maharashtra pharmaceutical corridors expand borosilicate glass conversion capacity for generic injectables and vaccine supply.
Switzerland
Swissmedic drug-device combination oversight elevates documentation requirements for prefilled syringes with integrated delivery systems. Precision glass processing expertise in the Basel-Zurich corridor serves specialized biologics manufacturers. The country's pharmacopeial compliance history supports premium positioning in regulated European markets.
Prefilled Glass Syringes Market Competitive Landscape
Player mix skews toward integrated glass specialists with backward control over tubular forming and siliconization processes. Market structure concentrates procurement relationships among manufacturers with validated ISO 11040-4 dossiers and established pharmacopeial compliance histories. Two strategic archetypes dominate: European borosilicate glass formers with captive melt capacity, and diversified packaging conglomerates with multi-material platforms. Competitive moves center on capacity expansion in North American markets and regulatory dossier harmonization across notified bodies.
Among European integrated specialists, Gerresheimer AG and SCHOTT Pharma exemplify the glass-forming archetype with upstream control over borosilicate melt operations. Stevanato Group occupies a differentiated position spanning glass processing, inspection systems, and contract manufacturing capabilities. These three anchors represent distinct competitive vectors: tubular glass backward integration, specialty glass chemistry, and integrated device manufacturing services.
| Leading Market Players |
|---|
| Gerresheimer AG |
| SCHOTT Pharma |
| BD |
| West Pharmaceutical Services |
| Nipro Corporation |
| Stevanato Group |
| Terumo Corporation |
| Taisei Kako Co., Ltd. |
| AptarGroup |
| Others |
Pricing and Supply Chain Analysis
ISO 11040-4 qualification gates both supply access and price differentiation simultaneously, concentrating procurement relationships among manufacturers with validated particulate control dossiers while compressing margins for unqualified competitors. Certification burden feeds directly into pricing power: biologics manufacturers pay premiums for pharmacopeial compliance histories that de-risk their own regulatory submissions.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 11040-4 validation status, siliconization consistency, and backward integration depth. Cost compression in standard syringes is intensifying because cyclic olefin polymer alternatives capture generic injectables volume. Hospital procurement consortiums exhibit lowest price sensitivity due to OSHA compliance mandates, while cost-sensitive generic manufacturers drive economy-tier negotiation.
Supply Chain Analysis
Borosilicate glass melt capacity in Germany, Switzerland, and Japan anchors upstream supply for regulated biologics. Type I glass tubing, medical-grade silicone oil, and elastomer plunger components feed into finished syringe assembly. Single-source vulnerability concentrates in German tubular glass forming corridors exposed to energy cost volatility. Distribution runs through sterile fill-finish contract manufacturers and direct pharmaceutical company procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospital procurement consortiums and group purchasing organizations consolidating around single-source contracts. This consolidation fragments negotiating leverage for smaller manufacturers without comprehensive service agreements.
For Market Incumbents: Secure ISO 11040-4 dossier harmonization across notified bodies to compress certification timeline uncertainty. Deepen backward integration into borosilicate glass melting to defend against energy cost volatility and plastic substitution threats. Anchor capacity expansion in North American corridors to capture US IRA domestic manufacturing incentives and federal procurement preference.
For New Entrants and Emerging Players: Inspection system integration and contract manufacturing services represent under-served layers where incumbents maintain arm's-length relationships. Target Indian and Southeast Asian pharmaceutical corridors where CDSCO regulatory harmonization accelerates qualification timelines for export-oriented producers. Pursue co-development partnerships with regional biologics manufacturers seeking supply chain resilience outside European concentration zones.
For Investors and Strategic Acquirers: EU MDR technical documentation tightening reshapes the acquisition landscape toward targets with established pharmacopeial compliance histories and validated siliconization process control. Five-to-ten year viability hinges on regulatory dossier depth rather than pure capacity scale. Monitor USP glass classification revision timelines as inflection signals for qualification cost step-ups and capacity reallocation decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11040-4 Dossier Harmonization | Reduces certification timeline uncertainty across EMA and FDA parallel submissions. |
| Backward Integration into Tubular Glass | Captures margin from borosilicate melt through finished syringe in captive supply chains. |
| North American Capacity Expansion | Qualifies domestic supply for US IRA federal procurement preference and biologics reshoring. |
| Integrated Safety Syringe Development | Aligns with OSHA needlestick prevention mandates and hospital GPO premium positioning. |
| RTU Sterilized Platform Adoption | Eliminates customer capital expenditure in washing and depyrogenation infrastructure. |
Research Methodology
Operator-level perspectives from regulatory affairs directors, hospital procurement managers, fill-finish contract manufacturing executives, and glass forming technicians anchored the qualitative base. Primary fieldwork combined with secondary validation from FDA container closure guidance documents, EMA drug-device combination consultation records, ISO 11040 series standards, and pharmacopeial compliance databases. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates across the analysis window.
Sensitivity analysis tested forecast outputs against regulatory timeline acceleration, energy cost volatility in European glass corridors, and plastic substitution elasticity in generic injectables. Segmentation dimensions modeled include product type complexity, application therapeutic area, end-user procurement authority, and material certification grade. CAGRs derived from installed capacity expansion schedules, biologics pipeline administration format shifts, and national immunization program tender volumes.
Underlying assumptions cover sustained FDA and EMA regulatory stringency, with deviation risk concentrated in USP glass classification revisions and EU MDR notified body capacity constraints. Practitioners should keep alternative scenarios live as mRNA vaccine platform format preferences and IRA domestic content requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Radial Access Catheter Market
Medical Devices
Global Gynecology Devices Market
Medical Devices
US Wearable Medical Devices Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
MRI Coils Market
Medical Devices
Tinnitus Maskers Market
Medical Devices
Global Medical Devices Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Digital Stethoscope Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
Laparoscopic Surgical Robot Market
Medical Devices
Cytology Brush Market
Medical Devices
Digital Medical Thermometers Market
Medical Devices
Hemoconcentrators Market
Medical Devices
North America Medical Devices Market