
 Speech Generating Devices Market | 2026-2036
Speech Generating Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Speech Generating Devices Market Outlook
Medical distributor networks for assistive communication hardware is fragmenting as manufacturers build direct-to-clinic relationships and online portals. Tobii Dynavox leverages its eye-tracking specialization to dominate premium dedicated device categories. Prentke Romich Company anchors its position through extensive clinician training programs and institutional partnerships. Saltillo Corporation competes by focusing on compact, portable form factors for school-based deployment.
Speech generating devices are electronic augmentative and alternative communication (AAC) systems that synthesize spoken output from user inputs ranging from eye gaze to switch scanning, typically operating with latency under 200 milliseconds to enable real-time conversation. These systems serve individuals with autism spectrum disorder, amyotrophic lateral sclerosis, cerebral palsy, or post-stroke aphasia who lack functional verbal speech. Dedicated devices retain the highest margin pools due to specialized hardware and clinical validation requirements, while cloud-based solutions represent the fastest-expanding technology segment as remote therapy models normalize. Symbol-based technology still occupies the largest installed base among pediatric users, though text-to-speech interfaces gain ground among literate adults with degenerative conditions.
The FDA regulates speech generating devices as Class II medical devices under 510(k) premarket notification requirements, while the Centers for Medicare and Medicaid Services determines coverage criteria through local coverage determinations that vary by contractor jurisdiction. ISO 13485 quality management standards and IEC 60601-1 electrical safety requirements shape design verification protocols for manufacturers seeking multi-market access. Stakeholders must monitor evolving Medicaid waiver programs and school district IDEA funding allocations to anticipate procurement cycle timing and specification shifts.
Market Dynamics
Cloud-based AAC platforms are fragmenting procurement authority away from centralized hospital purchasing departments toward individual clinicians and family caregivers who configure subscriptions independently. This shift compresses traditional sales cycles and erodes distributor margins while accelerating deployment velocity.
Growth Catalysts
- Medicaid waiver expansion:State-level Home and Community-Based Services waivers in the United States now cover portable speech-generating hardware for community-dwelling adults, extending reimbursement beyond institutional settings.
- Eye-tracking latency reduction:Sub-100 millisecond response times in gaze-based input systems now support conversational speech rates for ALS patients with minimal residual motor function.
- IDEA funding stability:US school districts maintain dedicated assistive technology budgets under Individuals with Disabilities Education Act mandates, creating predictable replacement cycles for symbol-based devices.
Market Restraints
- Specialized semiconductor dependency:Custom voice-processing chips sourced from concentrated East Asian foundries expose manufacturers to input cost volatility and supply rationing.
- 510(k) clinical validation requirements:FDA premarket notification pathways demand extensive usability studies for novel input modalities, extending development timelines by 18-24 months.
- Tablet-based app substitution:Consumer-grade tablets running AAC software at sub-$500 price points capture price-sensitive school district segments, compressing dedicated device margins.
Strategic Opportunities
- Remote therapy normalization:Telehealth reimbursement permanence enables cloud-native AAC vendors to embed device configuration within virtual speech-language pathology sessions.
- EU Medical Device Regulation harmonization:MDR conformity assessment mutual recognition agreements streamline multi-country European market entry for ISO 13485-certified manufacturers.
- Post-stroke aphasia adult segment:Aging populations in Japan and Germany create demand for text-to-speech interfaces among literate adults with acquired communication disabilities.
Industry Challenges
- Speech-language pathologist training gaps:Clinician familiarity with advanced programming interfaces for dynamic display devices lags behind hardware capability expansion.
- IEC 60601-1 third-edition compliance:Electrical safety testing for battery-powered portable units requires specialized laboratory partnerships that extend certification timelines.
- Legacy device data migration:Proprietary symbol libraries and personalized utterance banks resist standardized transfer protocols during hardware replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speech Generating Devices Market |
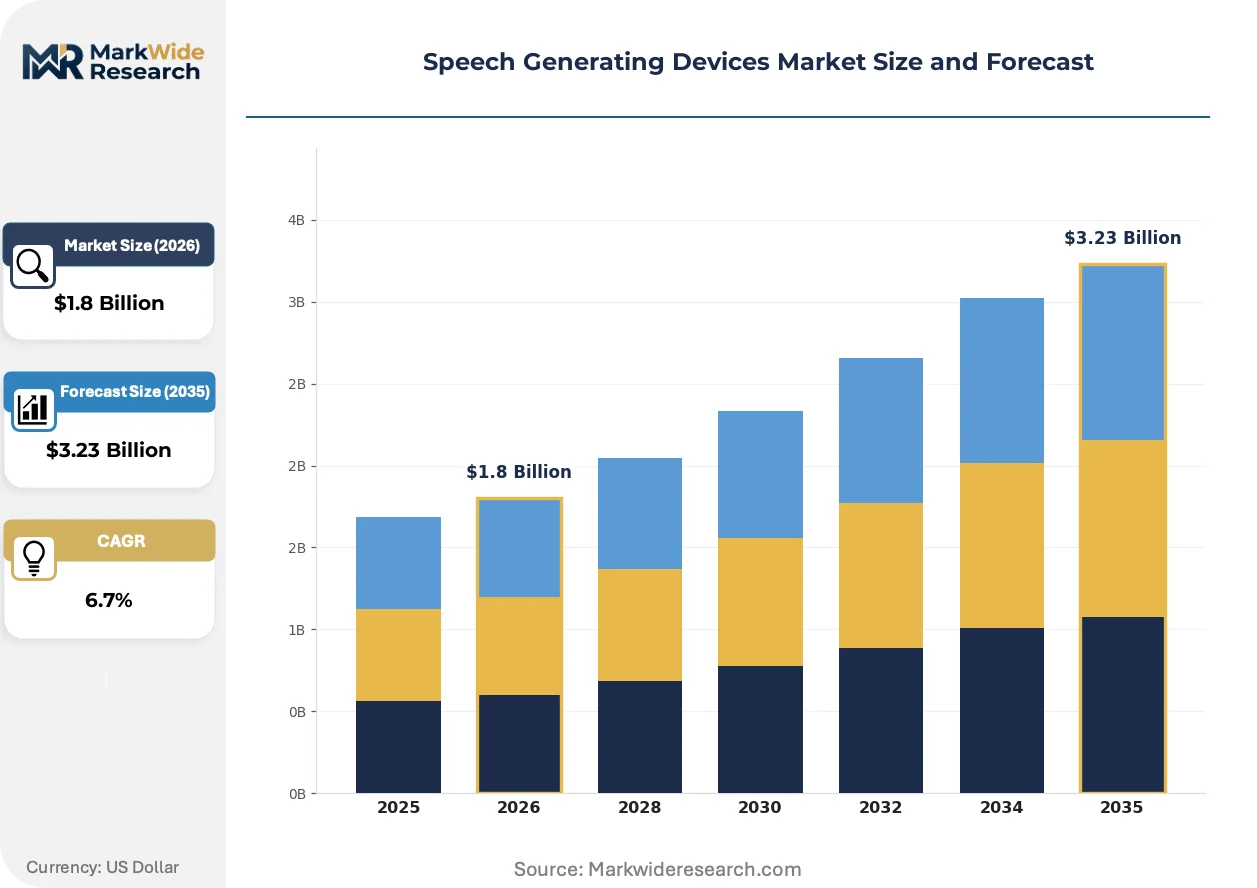
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dedicated Devices, Mobile Applications, Software Solutions, Adaptive Devices End User: Clinics, Educational Institutions, Home Care, Rehabilitation Centers Technology: Symbol-Based Technology, Text-to-Speech, Speech Recognition, Cloud-Based Solutions Distribution Channel: Online Retail, Direct Sales, Medical Distributors, Specialized Stores |
| Companies Covered | Tobii Dynavox, Prentke Romich Company, Saltillo Corporation, Lingraphica, ZYGO-USA, Jabbla, Smartbox Assistive Technology, Attainment Company, Liberator Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speech Generating Devices Market Strategic Shifts
Artificial intelligence integration is compressing the boundary between dedicated medical devices and consumer electronics, forcing manufacturers to redefine clinical value propositions around data continuity rather than hardware durability alone.
Neural text-to-speech synthesis is collapsing the quality gap between recorded voice banking and algorithmic voice cloning. Users with progressive conditions now preserve vocal identity through 10-minute training samples rather than hours of studio recording. Pediatric clinics in the United States adopt these systems fastest, prioritizing age-appropriate voice options over mechanical intelligibility.
EU Medical Device Regulation implementation is reshaping post-market surveillance obligations for AAC manufacturers. Class IIa classification now mandates systematic clinical follow-up data collection across member states. German and French notified bodies enforce stricter vigilance reporting timelines than southern European counterparts, creating compliance complexity for vendors seeking uniform EU market access.
Subscription-based software licensing is displacing perpetual purchase models in North American school districts. Annual per-seat fees for cloud-hosted vocabulary systems replace five-year hardware depreciation cycles. Texas and California education procurement offices now require SaaS compatibility statements in competitive bidding documents, pressuring legacy vendors to rearchitect product delivery.
Speech Generating Devices Market Segmentation
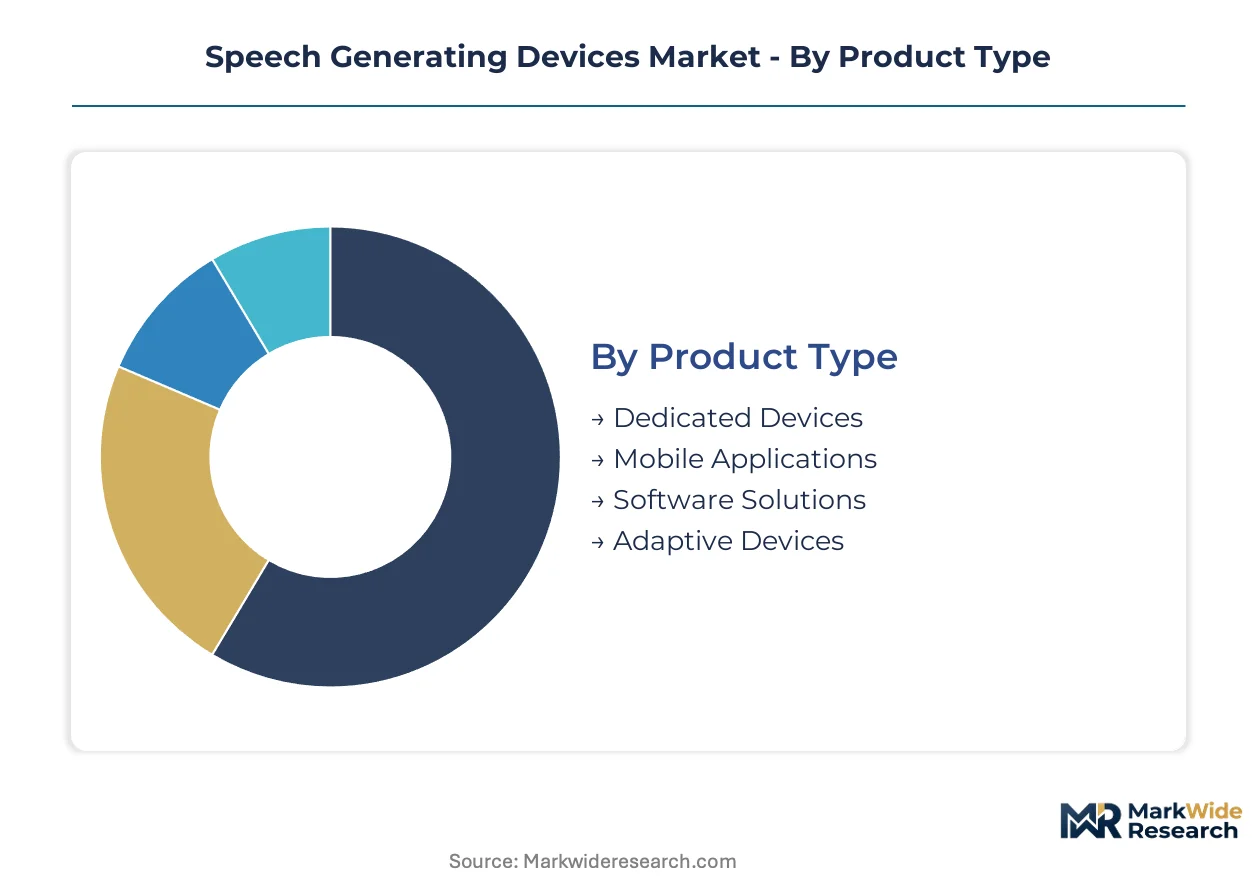
Speech generating devices serve heterogeneous user populations with divergent motor capabilities, cognitive profiles, and reimbursement pathways. Segmentation reveals how hardware specialization, deployment setting, input modality, and procurement channel each shape vendor strategy and margin structure.
Product Type:
Device categories span from FDA-validated dedicated systems to consumer-electronics software, with cost tiers ranging from sub-five-hundred-dollar tablet applications to five-figure eye-tracking platforms.
- Dedicated Devices:Purpose-built hardware with IEC 60601-1 electrical safety certification and dedicated voice-processing chipsets. Pediatric rehabilitation clinics in the United States concentrate procurement here, driven by Medicare coverage durability and IDEA-mandated school district replacement cycles.
- Mobile Applications:AAC software running on consumer tablets and smartphones. Price-sensitive school districts in Texas and California are migrating procurement toward this tier, compressing margins for legacy hardware vendors while accelerating deployment velocity.
- Software Solutions:Cloud-native platforms with subscription licensing and remote configuration capabilities. Telehealth reimbursement permanence is embedding these within virtual speech-language pathology workflows.
- Adaptive Devices:Modular hardware accommodating multiple input methods—switch scanning, head tracking, or eye gaze—within a single chassis. Medicaid waiver expansion for community-dwelling adults is extending addressable demand beyond institutional settings.
The dominant share belongs to Dedicated Devices, while Mobile Applications is closing the gap fastest.
End User:
Procurement authority fragments across institutional purchasers with divergent budget cycles, regulatory constraints, and clinical training infrastructures.
- Clinics:Outpatient speech-language pathology practices with direct patient relationships. Cloud-based configuration tools are shifting purchasing decisions from centralized hospital supply chains toward individual clinicians.
- Educational Institutions:US school districts operating under Individuals with Disabilities Education Act mandates. Predictive five-year hardware depreciation cycles and dedicated assistive technology budgets create stable replacement demand.
- Home Care:Family caregivers configuring systems for community-dwelling users. State-level Home and Community-Based Services waivers now cover portable hardware, extending reimbursement beyond institutional boundaries.
- Rehabilitation Centers:Inpatient and post-acute facilities serving stroke and traumatic brain injury populations. Aging demographics in Japan and Germany are expanding demand for text-to-speech interfaces among literate adults with acquired disabilities.
Educational Institutions command the largest installed base, though Home Care is expanding most quickly as Medicaid waivers broaden eligibility.
Technology:
Input modality selection tracks user motor function, cognitive status, and literacy level, with latency specifications determining conversational utility.
- Symbol-Based Technology:Graphical communication boards with picture or icon vocabulary sets. Pediatric users with autism spectrum disorder or intellectual disability constitute the core installed base, though personalization requirements create data migration friction during hardware replacement.
- Text-to-Speech:Keyboard or scanning input with algorithmic voice synthesis. Neural synthesis advances now preserve vocal identity through minimal training samples, accelerating adoption among literate adults with progressive conditions.
- Speech Recognition:Voice-activated control for users with residual speech but impaired intelligibility. Limited penetration due to accuracy constraints with dysarthric or apraxic speech patterns.
- Cloud-Based Solutions:Internet-dependent platforms with remote vocabulary management and teletherapy integration. Fastest-expanding technology segment as SaaS licensing displaces perpetual purchase models in North American education procurement.
Symbol-Based Technology retains the largest pediatric footprint, while Cloud-Based Solutions are gaining share fastest among adult populations.
Distribution Channel:
Channel strategy determines margin capture, clinician training investment, and replacement cycle visibility.
- Online Retail:Direct-to-consumer and caregiver-configured purchases. Subscription-based software licensing is normalizing here, compressing traditional distributor margins while accelerating deployment timelines.
- Direct Sales:Manufacturer relationships with institutional accounts. Extensive clinician training programs and institutional partnerships anchor vendor positioning in this channel.
- Medical Distributors:Traditional assistive technology supply chains. Fragmentation is accelerating as manufacturers build direct-to-clinic relationships and proprietary online portals.
- Specialized Stores:Brick-and-mortar AAC-focused retailers with hands-on evaluation capabilities. Concentrated in metropolitan areas with specialized rehabilitation hospital density.
Direct Sales commands premium positioning, while Online Retail is climbing the fastest as procurement authority decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways for augmentative communication devices anchor procurement decisions in the United States, while reimbursement policies in Germany and Japan shape parallel demand trajectories for literate adult populations with acquired disabilities.
United States
Medicare coverage policies for speech-generating equipment drive reimbursement-driven purchasing concentrated in pediatric rehabilitation clinics and school districts. The Individuals with Disabilities Education Act mandates dedicated assistive technology budgets that create predictable five-year hardware replacement cycles. Texas and California education procurement offices now require SaaS compatibility statements in competitive bidding documents, pressuring legacy vendors toward cloud-native architectures.
Germany
Aging demographics expand demand for text-to-speech interfaces among post-stroke aphasia patients in rehabilitation centers across Baden-Württemberg and Bavaria. EU Medical Device Regulation Class IIa classification mandates systematic clinical follow-up data collection, with German notified bodies enforcing stricter vigilance reporting timelines than southern European counterparts. Berlin-Brandenburg hosts specialized rehabilitation hospital clusters where IEC 60601-1 electrical safety certification determines device eligibility.
Japan
Literate adults with amyotrophic lateral sclerosis and degenerative conditions drive adoption of eye-tracking platforms with sub-100 millisecond latency specifications. METI standards harmonization with ISO 13485 quality management protocols streamlines multi-market access for manufacturers. The Kanto region around Tokyo concentrates specialized speech-language pathology practices that configure gaze-based systems for minimal residual motor function patients.
United Kingdom
NHS England local coverage determinations for augmentative communication equipment vary by clinical commissioning group jurisdiction, creating procurement fragmentation. The London-Southeast corridor anchors distributor networks transitioning toward direct-to-clinic manufacturer relationships. Scotland and Wales maintain distinct Medicaid-equivalent funding streams for community-dwelling adults that extend hardware reimbursement beyond institutional boundaries.
Canada
Health Canada medical device licensing aligns with FDA 510(k) premarket notification requirements, enabling parallel regulatory submissions for North American market access. Provincial assistive technology programs in Ontario and Quebec cover dedicated devices for pediatric autism spectrum disorder populations. The Greater Toronto Area hosts rehabilitation engineering centers that evaluate adaptive hardware accommodating multiple input methods within single chassis designs.
Speech Generating Devices Market Competitive Environment
Eye-tracking specialists and symbol-based hardware incumbents split the market into premium dedicated device and portable education-deployment segments. The vendor base concentrates around three strategic archetypes: gaze-technology pioneers, clinician-training anchored institutional partners, and compact-form-factor school specialists. Competitive positioning hardens through proprietary vocabulary library ecosystems and direct-to-clinic relationship investments that bypass fragmenting distributor networks.
Within the premium dedicated device tier, Tobii Dynavox and Prentke Romich Company exemplify contrasting positioning strategies. Tobii Dynavox occupies a position anchored in eye-tracking specialization, while Prentke Romich Company sits within the institutional partnership archetype through extensive clinician training program investments. Saltillo Corporation represents the portable-form-factor specialist archetype targeting school-based deployment segments. These three manufacturers collectively illustrate how hardware specialization, clinical validation depth, and procurement channel strategy determine margin capture in reimbursement-driven purchasing environments.
| Leading Market Players |
|---|
| Tobii Dynavox |
| Prentke Romich Company |
| Saltillo Corporation |
| Lingraphica |
| ZYGO-USA |
| Jabbla |
| Smartbox Assistive Technology |
| Attainment Company |
| Liberator Ltd |
| Others |
Value Chain & Pricing Dynamics
East Asian foundry concentration for custom voice-processing chipsets anchors margin capture in the premium dedicated device tier, while downstream pricing power fragments across subscription-based SaaS entrants and legacy hardware incumbents defending institutional procurement relationships.
Pricing Analysis
US-Mainland China price spreads exceed threefold for equivalent eye-tracking hardware configurations, reflecting FDA 510(k) validation costs and IEC 60601-1 certification tiers. Three-tier pricing structure across premium gaze-based platforms, mid-range adaptive devices, and economy tablet applications stratifies buyer segments. Cost compression in the education procurement tier intensifies because Texas and California school districts now mandate SaaS compatibility in competitive bids. Home Care Medicaid waiver recipients exhibit highest price sensitivity; Rehabilitation Centers with aging-population mandates show lowest.
Supply Chain Analysis
Contract manufacturing for portable AAC hardware concentrates with Taiwanese and South Korean EMS providers holding ISO 13485-certified medical device capacity. Custom voice-processing ASICs draw from concentrated East Asian foundries; lithium-ion battery cells feed from South Korean and Japanese suppliers; specialized eye-tracking camera modules source from German optics specialists. Single-source vulnerability for gaze-tracking sensor arrays creates exposure to allocation rationing during semiconductor supply shocks. Distribution runs through direct-to-clinic manufacturer portals that bypass fragmenting medical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as cloud-native AAC vendors embed device configuration within telehealth reimbursement workflows, collapsing the traditional hardware replacement cycle into continuous subscription relationships.
For Market Incumbents: Build proprietary vocabulary library moats through AI-powered personalization engines that resist standardized data migration during hardware replacement. Anchor institutional partnerships with speech-language pathologist certification programs that tablet-based substitutes cannot replicate. Defend against SaaS entrants by integrating remote configuration tools within existing clinician training infrastructures.
For New Entrants and Emerging Players: Pursue post-stroke aphasia adult segments in Japan and Germany where neural text-to-speech synthesis creates first-mover advantages in voice banking preservation. Target Medicaid waiver expansion corridors in US states extending community-based hardware reimbursement. Deploy telehealth-native configuration interfaces that accelerate deployment velocity beyond legacy distributor sales cycles.
For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native platform archetypes with embedded speech-language pathology workflows and recurring revenue visibility across the analysis window. Monitor FDA 510(k) clearance velocity for novel input modalities as inflection indicator; accelerated approval timelines signal incumbent vulnerability to technology substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth-Native Platform Development | Embeds AAC configuration within CMS-reimbursed virtual speech-language pathology sessions. |
| Neural Voice Banking Integration | Preserves vocal identity through minimal training samples for ALS and progressive condition users. |
| EU MDR Conformity Acceleration | Streamlines multi-country European access via German notified body relationships. |
| Direct-to-Clinic Portal Investment | Bypasses fragmenting medical distributor networks to capture institutional procurement authority. |
| Medicaid Waiver Reimbursement Strategy | Aligns hardware eligibility with state-level Home and Community-Based Services expansion. |
Study Parameters
Operator-level perspectives from speech-language pathologists, hospital biomedical engineers, GPO contracts managers, and Medicaid waiver program administrators anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) premarket notification databases, CMS local coverage determination filings, and IDEA-mandated school district procurement records. Bottom-up unit economics triangulated against top-down reimbursement flow analysis across Medicare, Medicaid, and private payer channels.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling product type, end user, input modality technology, and distribution channel dimensions. CAGRs derived from segmented replacement cycle analysis and reimbursement policy trajectory assessment. Forecast inputs incorporated telehealth reimbursement permanence indicators and EU MDR Class IIa vigilance reporting timeline differentials by notified body jurisdiction.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native platform moves by consumer electronics entrants or accelerated FDA clearance timelines for novel input modalities would shift outcomes. Quarterly review of state Medicaid waiver expansion announcements, school district SaaS procurement mandate adoption, and East Asian foundry allocation notices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Cervical Spacer Systems Market
Medical Devices
PDA Closure Devices Market
Medical Devices
Central Venous Catheter Market
Medical Devices
Arthroscopy Market
Medical Devices
Middle East and Africa Biomedical Sensors Market
Medical Devices
Russia Viscosupplementation Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Robotic Angiography Systems Market
Medical Devices
Hypodermic Syringes Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Global Portable Ventilators Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
Electrosurgery Devices Market