
 Global Orthopedic Power Tools Market | 2026-2036
Global Orthopedic Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Global Orthopedic Power Tools Market Foresight
Lithium-ion battery chemistry is realigning orthopedic power tool economics as cordless platforms displace pneumatic tethering in operating suites. Stryker Corporation leverages integrated battery ecosystems to sustain premium positioning across joint replacement workflows. Zimmer Biomet anchors its portfolio with modular handpiece architectures that dominate ambulatory settings. Medtronic competes through advanced surgical navigation compatibility that extends power tool utility into spine and trauma applications.
Orthopedic power tools comprise motorized surgical instruments designed to cut, drill, ream, or shape bone and hard tissue during operative procedures, typically operating at speeds from 500 to 80,000 RPM with sterilizable stainless steel or titanium attachments. Battery-powered technology leads segment evolution as lithium polymer cells deliver torque parity with pneumatic systems while eliminating hose contamination risks and improving OR turnover efficiency. Joint replacement application pools command the deepest margins due to instrument kit complexity and recurring consumable attachment demand, whereas arthroscopy represents the fastest-expanding application as minimally invasive sports medicine procedures migrate from hospital campuses to specialty surgical centers.
FDA 510(k) clearance pathways govern US market entry for powered surgical instruments, while the EU MDR imposes stricter clinical evidence and post-market surveillance obligations than predecessor directives. Japan's PMDA maintains distinct electromagnetic compatibility and biocompatibility testing protocols that shape product development cycles for Asia-Pacific distribution. Stakeholders must monitor battery chemistry safety standards and sterilization validation requirements as regulatory convergence pressures harmonization costs across multi-jurisdictional portfolios.
Market Dynamics
Lithium-ion battery chemistry is compressing the total cost of ownership for cordless surgical platforms while EU MDR sterilization mandates force hardware redesigns across European installed bases.
Growth Catalysts
- EU MDR traceability mandates:Reusable power tool systems face mandatory unique device identification and post-market surveillance, accelerating replacement cycles among German and French hospital networks.
- Battery torque parity:Lithium polymer cells now match pneumatic system performance, eliminating hose contamination risks and enabling faster operating room turnover in ambulatory surgery centers.
- China's aging demographics:Joint replacement procedure volumes in Shanghai and Beijing surgical hubs are climbing fastest among major economies, pulling capital equipment demand.
Market Restraints
- Cobalt and lithium price volatility:Battery chemistry raw material costs swing unpredictably, pressuring margins on cordless handpiece production.
- EU MDR clinical evidence requirements:Stricter than predecessor directives, these obligations extend regulatory timelines and inflate submission costs for reusable system manufacturers.
- Pneumatic infrastructure entrenchment:Existing hospital gas line investments in the United States create switching friction for battery platform adoption.
Strategic Opportunities
- India's surgical center expansion:Private hospital chains in Mumbai and Delhi are modernizing orthopedic suites, creating first-mover openings for battery-powered platforms.
- Surgical navigation convergence:Power tools integrating with optical tracking systems command premium positioning in spine and trauma workflows.
- Japan's PMDA electromagnetic compatibility pathway:Streamlined testing protocols for cordless devices reduce time-to-market for Asia-Pacific distribution strategies.
Industry Challenges
- Sterilization validation bottlenecks:Autoclave compatibility testing for battery-sealed handpieces extends product development timelines.
- Cross-jurisdictional harmonization costs:Divergent FDA 510(k), EU MDR, and PMDA electromagnetic standards force redundant engineering cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Orthopedic Power Tools Market |
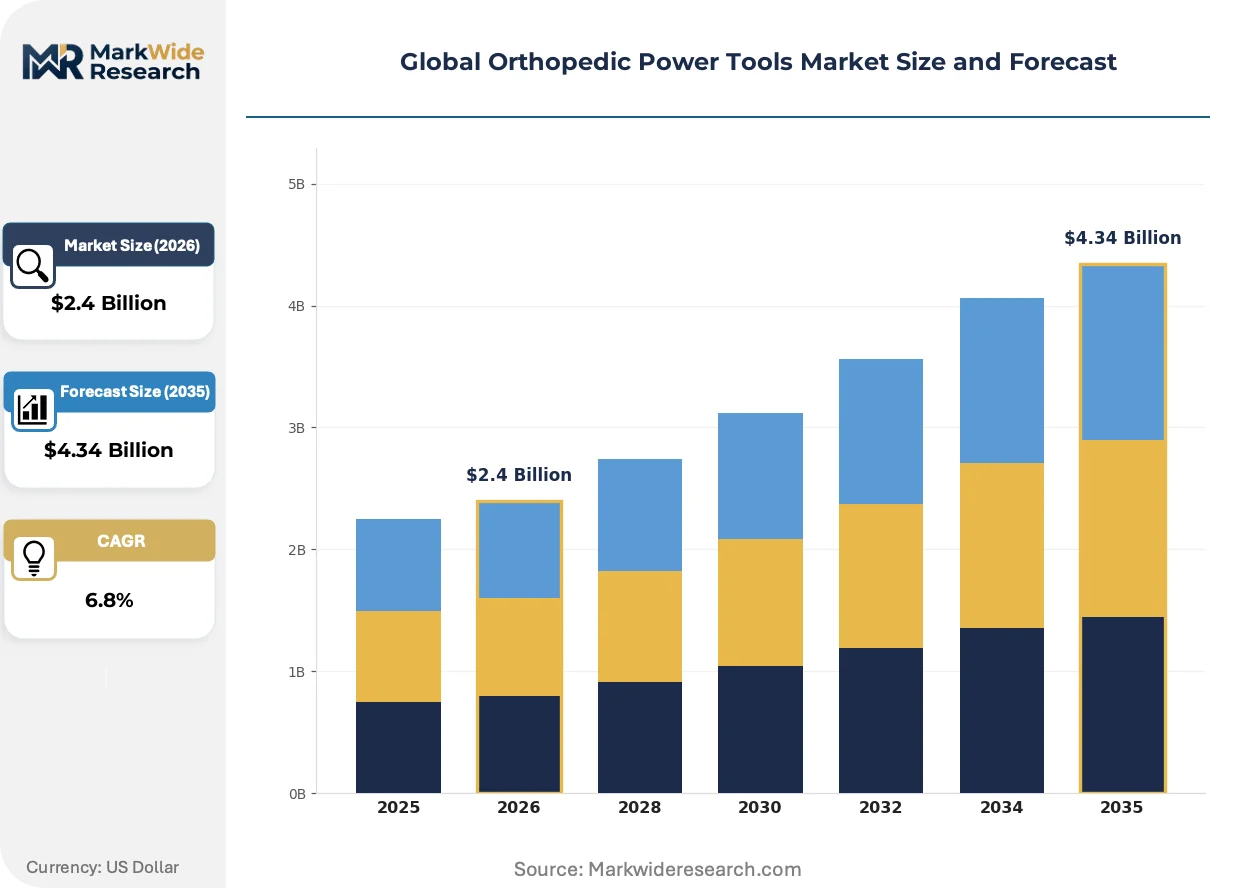
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drills, Saws, Reamers, Drivers, Burs Technology: Battery Powered, Pneumatic, Electric Corded, Hydraulic Application: Fracture Fixation, Joint Replacement, Spinal Surgery, Arthroscopy End User: Orthopedic Clinics, Ambulatory Surgery Centers, Specialty Surgical Centers, Research Institutes |
| Companies Covered | Stryker Corporation, Zimmer Biomet, Medtronic, CONMED Corporation, DePuy Synthes (Johnson & Johnson), B. Braun SE, Arthrex, NSK/Nakanishi Inc., De Soutter Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Orthopedic Power Tools Market Shifts & Advancements
Orthopedic power tool architecture is pivoting from pneumatic tethering toward sealed battery ecosystems, with regulatory pressure and outpatient migration compressing legacy platform lifecycles.
Brushless motor technology is electrifying handpiece design by eliminating carbon brush wear and enabling higher torque density in compact surgical instruments. Ambulatory surgery centers in the United States and Germany are adopting these platforms fastest, drawn by reduced maintenance intervals and elimination of compressor infrastructure. The shift is electrifying competitive positioning around total cost of ownership rather than upfront capital expenditure.
The EU Medical Device Regulation is tightening sterilization validation and post-market surveillance obligations beyond predecessor directive requirements. Manufacturers must now generate clinical evidence for reusable power tool systems and maintain traceability databases across European hospital networks. German and French procurement bodies are responding by bundling service contracts with hardware purchases to transfer compliance liability.
Hospital buying committees are consolidating vendor relationships around integrated battery ecosystems rather than discrete instrument purchases. Specialty surgical centers are displacing traditional distributor networks with direct manufacturer partnerships that bundle training and preventive maintenance. This pattern concentrates most visibly in United States metropolitan markets where health system consolidation has centralized orthopedic capital budgeting.
Global Orthopedic Power Tools Market Segmentation
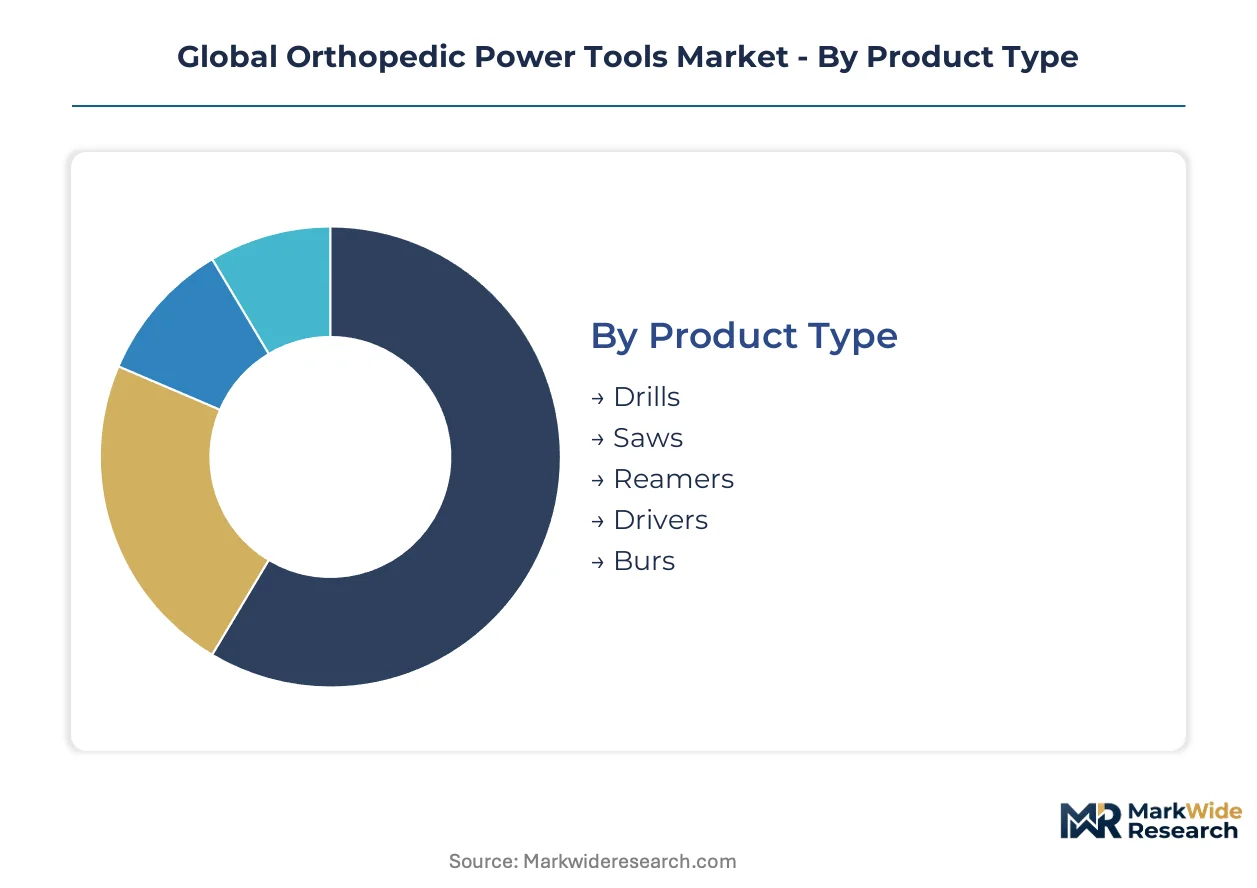
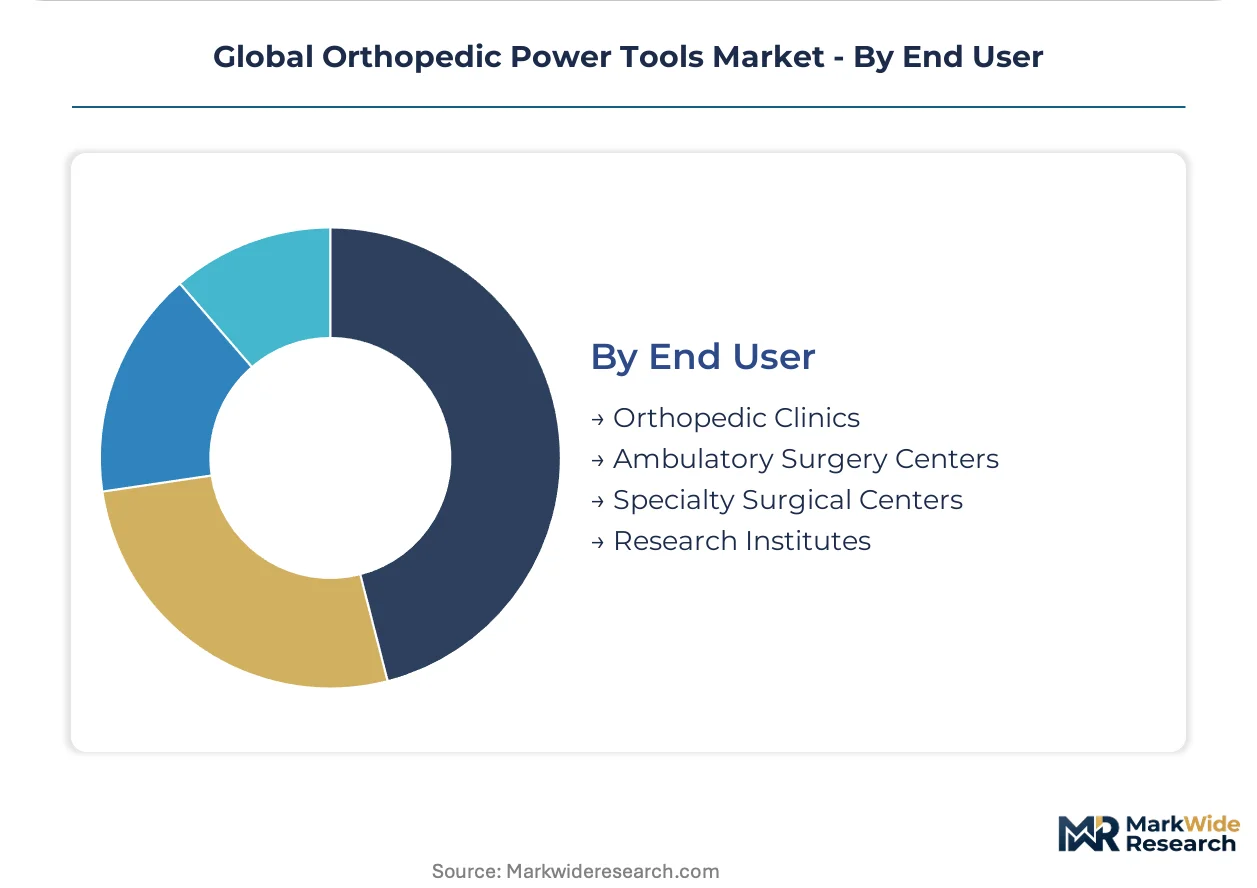
Orthopedic power tool procurement patterns diverge sharply between high-volume hospital networks and lean ambulatory operators, with technology choices and application mix driving fundamentally different equipment configurations. Understanding these segment boundaries clarifies where battery platform investments concentrate versus where pneumatic legacy systems retain commercial viability.
Product Type:
Joint replacement surgeons prioritize torque precision and attachment modularity, whereas trauma teams weight portability and sterilization turnaround above raw power specifications.
- Saws:Oscillating and sagittal blade configurations dominate knee and hip arthroplasty workflows, with German hospital procurement committees bundling these into comprehensive joint replacement kits. Demand concentrates in metropolitan surgical hubs where procedure volumes justify dedicated sterile processing infrastructure.
- Drills:High-torque cannulated designs enable precise tunneling for fracture fixation hardware, with Chinese orthopedic departments in Shanghai and Beijing expanding cordless drill procurement fastest among major economies. Battery torque parity has displaced pneumatic tethering in these settings.
- Reamers:Cylindrical cutting heads shape medullary canals for implant seating, with modular handpiece compatibility driving standardization across US health system networks.
- Drivers:Screw insertion tools with adjustable torque limiting prevent cortical stripping in osteoporotic bone, finding strongest uptake in ambulatory surgery centers prioritizing instrument versatility.
- Burs:Rotary cutting attachments for bone contouring and hardware removal, with arthroscopy suites representing the fastest-expanding end-use channel for high-speed bur configurations.
Volume sits with saws and drills; growth tilts toward burs as sports medicine procedures migrate to outpatient settings.
Technology:
Power source selection determines total cost of ownership calculations, with infrastructure sunk costs and sterilization compliance obligations creating divergent investment thresholds across customer tiers.
- Battery Powered:Lithium polymer cell architectures now deliver torque density matching pneumatic systems while eliminating hose contamination risks. Ambulatory surgery centers in the United States and Germany are adopting these platforms fastest, drawn by reduced maintenance intervals and faster operating room turnover.
- Pneumatic:Compressed gas systems retain installed base dominance in legacy hospital infrastructure, particularly where existing compressor investments and sterile hose inventories create switching friction. US metropolitan health systems with centralized orthopedic capital budgeting show slowest migration rates.
- Electric Corded:Mains-powered instruments persist in research institute and training environments where capital constraints outweigh mobility requirements, with limited penetration in commercial surgical settings.
- Hydraulic:High-force applications in spinal fusion and long-bone reaming leverage fluid power for sustained torque output, commanding niche positioning in specialized trauma centers.
Revenue concentrates in battery powered systems; expansion tilts toward this segment as EU MDR sterilization mandates accelerate replacement cycles.
Application:
Procedure reimbursement rates and implant attach rates shape capital equipment procurement budgets, with joint replacement workflows commanding premium instrument configurations.
- Joint Replacement:Arthroplasty procedures demand the most complex instrument kits, with reamer-saw-drill combinations and proprietary attachment ecosystems generating recurring consumable revenue. German and French hospital networks are bundling service contracts with hardware purchases to transfer EU MDR compliance liability.
- Arthroscopy:Minimally invasive sports medicine procedures are expanding fastest among application categories, with specialty surgical centers in the United States displacing hospital campuses as the primary venue. Compact battery handpieces dominate this channel.
- Fracture Fixation:Trauma applications prioritize rapid instrument availability and sterilization resilience, with drill-driver combinations representing the core equipment investment for emergency orthopedic suites.
- Spinal Surgery:Precision navigation compatibility and extended torque duration distinguish power tools for pedicle screw placement and vertebral preparation, with premium positioning in academic medical centers.
Margin concentration sits with joint replacement; volume expansion tilts toward arthroscopy as outpatient migration accelerates.
End User:
Facility scale and case mix determine whether procurement favors integrated vendor ecosystems or discrete instrument purchasing, with consolidation trends reshaping distribution channels.
- Ambulatory Surgery Centers:Lean operations prioritize cordless platforms and rapid sterilization turnaround, with direct manufacturer partnerships displacing traditional distributor relationships in United States metropolitan markets. These facilities represent the fastest-growing equipment demand channel.
- Specialty Surgical Centers:Focused orthopedic providers balance instrument versatility against capital efficiency, often standardizing on modular handpiece architectures that span multiple procedure types.
- Orthopedic Clinics:Office-based surgical suites concentrate on minor procedures and hardware removal, with limited power tool capital requirements compared to operative facilities.
- Research Institutes:Academic and training environments drive limited commercial volume, with procurement focused on demonstration units and legacy platform maintenance rather than fleet expansion.
Equipment volume sits with ambulatory surgery centers; procurement sophistication tilts toward specialty surgical centers negotiating integrated service bundles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthopedic power tool demand concentrates in surgical hubs serving aging populations with high procedure volumes. Procurement patterns diverge sharply between established hospital networks and emerging ambulatory centers. Regulatory frameworks in major economies reshape sterilization requirements and battery safety standards.
United States
FDA 510(k) clearance pathways govern powered surgical instrument approvals, with health system consolidation in metropolitan markets centralizing capital equipment budgets. Ambulatory surgery centers in Texas and Florida are displacing traditional hospital campuses as the fastest-growing equipment demand channel. Brushless motor platforms are penetrating these lean operations fastest due to reduced maintenance overhead.
Germany
EU MDR traceability mandates are accelerating replacement cycles across reusable power tool installed bases. Hospital procurement committees in Bavaria and North Rhine-Westphalia are bundling service contracts with hardware purchases to transfer compliance liability. German surgical centers maintain the deepest penetration of modular handpiece architectures in Europe.
China
Joint replacement procedure volumes in Shanghai and Beijing surgical hubs are climbing fastest among major economies, pulling capital equipment demand from domestic and multinational suppliers. NMPA registration requirements for powered surgical instruments are tightening electromagnetic compatibility testing protocols. Yangtze River Delta manufacturing clusters are expanding local production capacity for battery-powered platforms.
Japan
PMDA electromagnetic compatibility pathways for cordless devices are streamlining time-to-market for Asia-Pacific distribution strategies. Aging demographics in Kanto and Kansai regions are expanding orthopedic procedure volumes beyond historical surgical capacity. Japanese hospital networks prioritize sterilization validation documentation under revised biocompatibility frameworks.
India
Private hospital chains in Mumbai and Delhi are modernizing orthopedic suites, creating first-mover openings for battery-powered surgical platforms. CDSCO medical device registration requirements are converging toward international standards for powered instrument safety. Maharashtra and Karnataka surgical centers are adopting cordless platforms to bypass pneumatic infrastructure investments.
Global Orthopedic Power Tools Market Competitive Landscape
Integrated battery ecosystem development dominates the current landscape as manufacturers compete on total cost of ownership rather than upfront capital expenditure. The vendor base stratifies between diversified medtech conglomerates with full surgical workflow portfolios and specialized power tool manufacturers with focused instrument expertise. Three archetypes define competitive positioning: integrated platform providers bundling hardware with consumable attachments, modular architecture specialists enabling cross-procedure standardization, and navigation-compatible innovators targeting spine and trauma precision applications. M&A activity and strategic partnerships concentrate around surgical navigation convergence and ambulatory surgery center direct distribution channels.
Among diversified medtech conglomerates, Stryker Corporation and Zimmer Biomet exemplify integrated platform strategies, while Medtronic occupies a position bridging power tool hardware with surgical navigation systems. These anchors represent divergent bets on whether orthopedic capital equipment competition will resolve around battery ecosystem lock-in, modular flexibility, or precision navigation integration.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet |
| Medtronic |
| CONMED Corporation |
| DePuy Synthes (Johnson & Johnson) |
| B. Braun SE |
| Arthrex |
| NSK/Nakanishi Inc. |
| De Soutter Medical |
| Others |
Supply & Pricing Matrix
Precision motor engineering talent concentration in Baden-Württemberg and Osaka-Kobe manufacturing corridors creates labor-cost differentials that widen pricing-tier spreads between European premium platforms and Asian value-tier alternatives.
Pricing Analysis
Volume concentrates in mid-tier battery-powered handpieces while margins pool in premium navigation-integrated systems. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared platforms with full surgical navigation compatibility from CE-marked modular systems and domestically certified value alternatives. Pricing pressure stems from cobalt and lithium raw material volatility compressing margins on cordless production. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, whereas academic medical centers prioritize performance specifications over unit cost.
Supply Chain Analysis
China's NMPA local-content requirements and India's PLI scheme for medical devices are reshaping sourcing patterns for battery cell procurement and precision motor assembly. Manufacturing gravity centers on China, Germany, and Japan for brushless motor production, with South Korea and Taiwan feeding semiconductor components for navigation interfaces. Raw material dependencies include lithium carbonate, neodymium rare earth magnets, and surgical-grade stainless steel billet. Single-source vulnerability concentrates in advanced battery management ICs. Distribution runs through manufacturer-direct partnerships with hospital systems and GPO contracts in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthopedic power tools occupy a technology-transition phase as lithium-ion battery ecosystems displace pneumatic infrastructure across operating suites worldwide.
For Market Incumbents: To counter modular platform entrants from specialized instrument manufacturers, Stryker Corporation and Zimmer Biomet should deepen backward integration into battery cell supply through captive partnerships with Korean or Japanese cell producers. Locking in sterilization validation documentation under EU MDR traceability mandates creates switching costs for hospital procurement committees. For New Entrants and Emerging Players: Direct-to-ambulatory sales channels offer the most penetrable route for battery-powered platform specialists seeking to bypass entrenched distributor relationships. India's private hospital chains in Maharashtra and Karnataka present first-mover white space where pneumatic infrastructure investments remain minimal. Target modular handpiece architectures that span joint replacement and arthroscopy applications to maximize capital efficiency for lean surgical centers. For Investors and Strategic Acquirers: Re-rating potential sits with navigation-compatible power tool specialists given surgical tracking convergence in spine and trauma workflows. Long-term viability favors platforms with FDA 510(k) clearance and EU MDR technical documentation already filed. Watch battery chemistry safety standard harmonization across FDA, EU MDR, and PMDA jurisdictions as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Cordless Platforms | Accelerates US market entry before EU MDR compliance costs peak for competitors. |
| CE Marking Pathway Under MDR | Secures German and French hospital procurement contracts requiring traceability databases. |
| Hospital System Partnership | Stryker's integrated battery ecosystem bundles lock in multi-year service revenue. |
| Software Companion Development | Medtronic's navigation compatibility extends power tool utility into precision spine applications. |
| Reimbursement Strategy | Outpatient joint procedure coding alignment drives ambulatory surgery center equipment demand. |
Research Methodology
Multi-period observation of battery platform adoption rates, EU MDR compliance expenditure patterns, and ambulatory surgery center capital budgets anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing committee chairs, biomedical engineering directors, and GPO contracts managers. Secondary validation drew from FDA 510(k) device listings, EU MDR technical documentation databases, NMPA registration filings, and hospital procurement contract aggregators. Bottom-up equipment shipment modeling triangulated against top-down healthcare capital expenditure surveys.
Input-output matrix framing connected procedure volume projections to instrument attach rates across joint replacement, arthroscopy, fracture fixation, and spinal surgery categories. Segmentation dimensions spanned product type, power source technology, application workflow, and end-user facility tier. CAGRs derived from logistic diffusion curves fitted to battery platform replacement cycles and pneumatic installed base retirement patterns. Forecast inputs incorporated lithium-ion cell cost trajectories and EU MDR sterilization validation timelines.
Inputs from hospital procurement databases and regulatory filing repositories were available through the study window; gaps in real-time ambulatory surgery center equipment expenditure reporting introduce uncertainty bands around cordless platform penetration rates. Forecasts reflect documented assumptions regarding battery torque parity maintenance and MDR enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Feeding Tubes Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
Smart Wheelchairs Market
Medical Devices
Artificial Disc Market
Medical Devices
Brachytherapy Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Catheter Systems Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Electroencephalogram (EEG) Caps Market
Medical Devices
Carotid Artery Stents Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Global Venous Blood Collection Devices Market
Medical Devices
Respiratory Devices Market
Medical Devices
General Surgical Devices Market