
 Behcet's Syndrome Market | 2026-2036
Behcet's Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Behcet's Syndrome Market Intelligence
The FDA's orphan drug designation program is pivoting development economics toward rare inflammatory conditions. AbbVie leverages its immunology infrastructure to sustain clinical trial momentum across multiple indications. Novartis anchors its position through specialized access programs for refractory uveitis subsets. Pfizer competes on manufacturing scale for corticosteroid supply chains serving acute flare management.
Behcet's syndrome constitutes a systemic vasculitis characterized by recurrent oral and genital ulcers, ocular inflammation, and vascular complications, with diagnosis requiring clinical criteria rather than laboratory confirmation. Biologics command the highest margin pools among product types due to mechanism specificity in TNF-alpha and interleukin pathway inhibition. Intravenous administration dominates hospital revenue capture, while subcutaneous formulations are gaining fastest in home care settings where patient self-management reduces infusion center burden.
The FDA, EMA, and WHO guide orphan drug development, post-market surveillance, and international classification standards that shape trial design and reimbursement negotiations across jurisdictions. Regulatory stringency on immunosuppressant safety profiles directly influences label expansions and prescriber confidence in second-line biologic transitions. Stakeholders must monitor real-world evidence generation from specialty registries to anticipate payer preference shifts between anti-TNF and emerging interleukin-targeted alternatives.
Market Dynamics
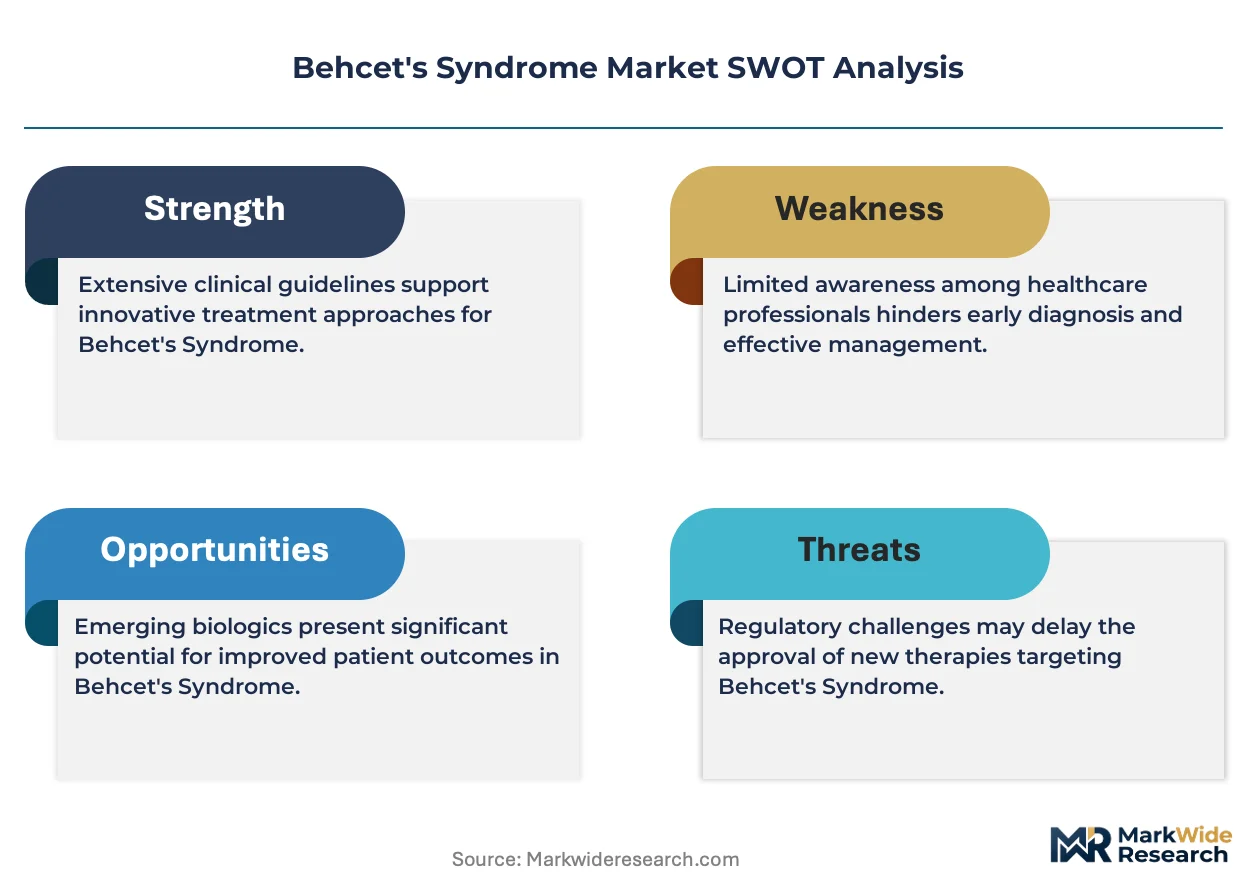
Hospital-based infusion centers are expanding biologic administration capacity to capture revenue from TNF-alpha and interleukin pathway inhibitors, while the FDA's orphan drug exclusivity framework incentivizes novel mechanism development for refractory vasculitis subsets.
Growth Catalysts
- Orphan drug exclusivity:The FDA's framework provides seven-year market exclusivity for novel mechanisms, redirecting R&D investment toward rare inflammatory conditions with unmet need.
- Home care migration:Subcutaneous biologic formulations enable patient self-administration, reducing infusion center burden and expanding addressable patient populations beyond tertiary referral networks.
- Specialty registry expansion:Real-world evidence generation from uveitis and vasculitis registries accelerates payer acceptance of second-line biologic transitions.
Market Restraints
- Biologic manufacturing concentration:Contract manufacturing for monoclonal antibodies concentrates in a limited supplier base, creating vulnerability to capacity constraints.
- Diagnostic complexity:Behcet's syndrome requires clinical criteria rather than laboratory confirmation, delaying treatment initiation and compressing addressable windows.
- Reimbursement heterogeneity:Payer prior authorization requirements for immunosuppressants vary across state Medicaid programs, fragmenting access.
Strategic Opportunities
- Interleukin-17 pathway inhibition:Emerging biologics targeting IL-17 and IL-23 pathways offer differentiation from saturated anti-TNF markets.
- Telemedicine integration:Remote monitoring platforms enable rural patient access to tertiary vasculitis expertise, expanding geographic reach.
- Japan's Sakigake designation:Japan's PMDA priority review system accelerates approval timelines for novel mechanisms in rare diseases.
Industry Challenges
- Specialized immunology talent scarcity:Clinical trial design for rare vasculitis requires expertise in adaptive protocols and biomarker stratification that outpaces training pipeline output.
- Cold chain integrity:Biologic stability requirements demand capital-intensive distribution infrastructure for temperature-controlled logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Behcet's Syndrome Market |
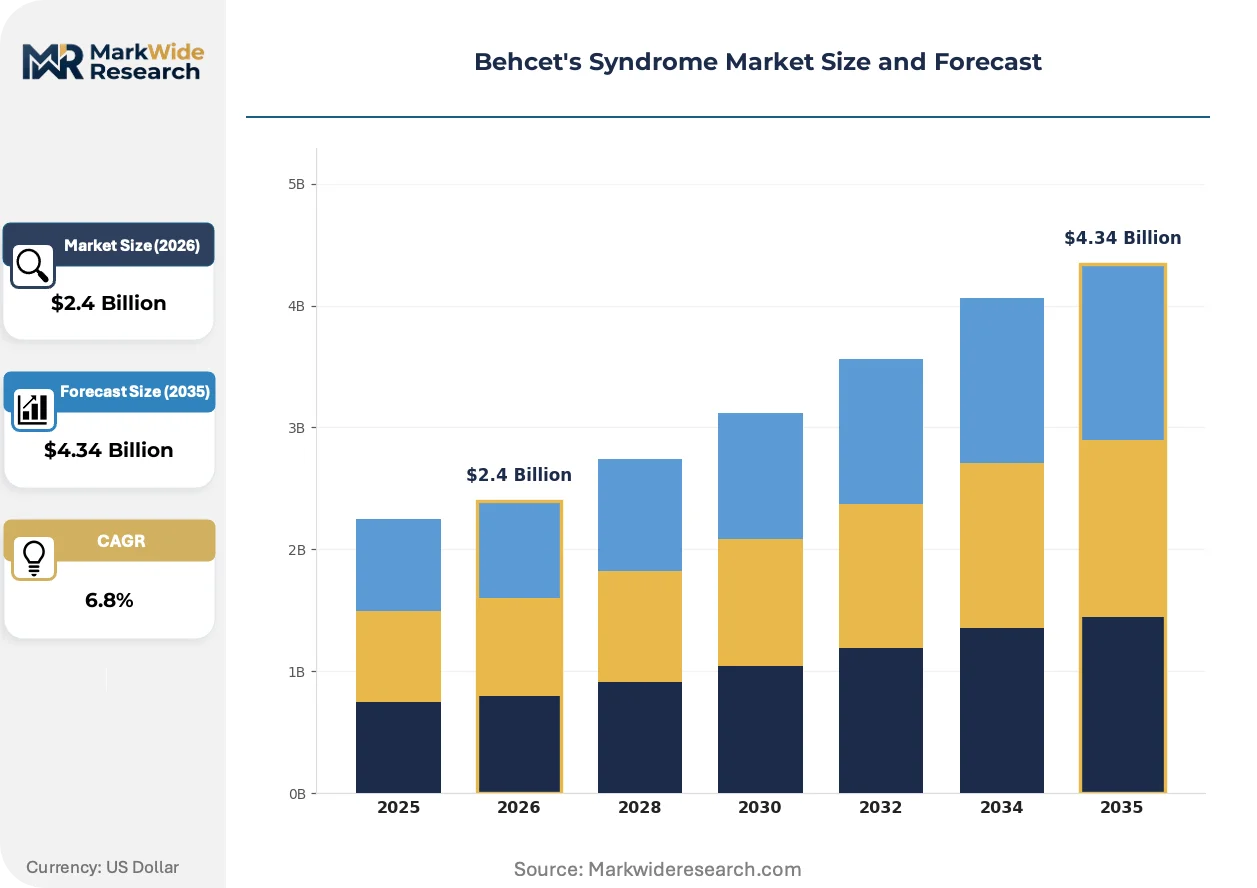
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunosuppressants, Biologics, Anti-TNF Agents Treatment Approach: Medical Therapy, Symptomatic Management, Corticosteroid Therapy, Disease-Modifying Therapy End User: Hospitals, Specialty Clinics, Home Care, Research Laboratories Route of Administration: Intravenous, Oral, Subcutaneous, Topical |
| Companies Covered | AbbVie, Novartis, Amgen, J Janssen Biotech, Abbott, Eisai, F. Hoffmann-La Roche Ltd., Pfizer, Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Behcet's Syndrome Market Strategic Shifts & Innovations
Mechanism specificity is displacing broad immunosuppression as the dominant therapeutic paradigm, with T-cell and cytokine pathway modulation commanding development priority across autoimmune portfolios.
Biosimilar development is expanding into TNF-alpha inhibitor categories previously protected by originator exclusivity, with manufacturers targeting adalimumab and infliximab reference products for cost-sensitive markets. Rheumatology practices in Germany and the United Kingdom are adopting biosimilar switching protocols at accelerating pace. This expansion is compressing originator pricing power and forcing portfolio diversification toward interleukin-targeted assets.
The EMA's adaptive licensing pathway is compressing development timelines for rare disease biologics, enabling conditional approval based on surrogate endpoints with post-authorization efficacy confirmation. Behcet's uveitis subsets with vision-threatening progression represent priority indications for this framework. European reference networks for rare diseases are coordinating patient access across member states.
Site-of-care economics are driving purchasing authority migration from hospital pharmacy departments to integrated delivery network formulary committees, with total cost-of-care metrics displacing drug-acquisition cost as the primary decision variable. United States health systems with captive specialty pharmacies are capturing margin through white-bag distribution models. This shift is visible most acutely in Medicare Advantage contracts with risk-based reimbursement structures.
Behcet's Syndrome Market Segmentation
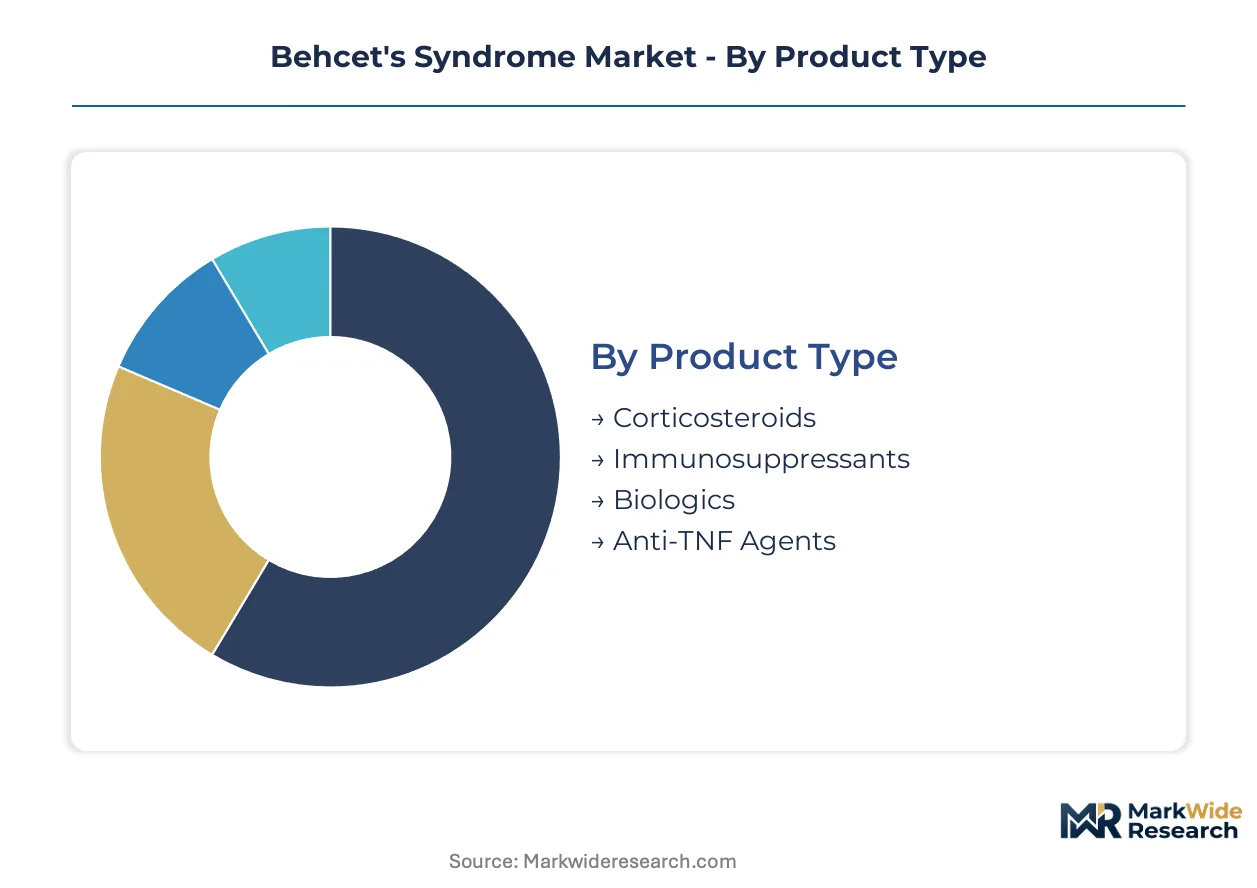
Behcet's syndrome treatment markets fragment across mechanism specificity and care delivery settings. Supply concentration in biologic manufacturing and site-of-care economics create divergent margin structures that reshape competitive positioning within each segment category.
Product Type:
Biologic manufacturing capacity concentrates among contract manufacturers with monoclonal antibody expertise, creating tiered supply security across mechanism classes.
- Biologics:Engineered proteins targeting TNF-alpha and interleukin pathways with high specificity. Demand concentrates in United States tertiary referral networks managing refractory vasculitis, where mechanism specificity justifies premium positioning against broad immunosuppression.
- Anti-TNF Agents:Monoclonal antibodies and fusion proteins blocking tumor necrosis factor-alpha signaling. Biosimilar competition from European manufacturers compresses originator pricing in Germany and United Kingdom markets while expanding volume access.
- Corticosteroids:Synthetic glucocorticoids for acute flare suppression.
- Immunosuppressants:Small-molecule agents including azathioprine and cyclosporine for maintenance therapy.
Today's leader: Biologics. Tomorrow's challenger: Anti-TNF Agents.
Treatment Approach:
Cost tier differentiation separates acute intervention from chronic disease modification, with reimbursement intensity scaling to outcome durability.
- Disease-Modifying Therapy:Long-term immunomodulation targeting underlying vasculitis pathophysiology rather than symptom suppression. United States Medicare Advantage contracts with risk-based structures prioritize these therapies for total cost-of-care reduction.
- Medical Therapy:Physician-directed pharmacologic intervention spanning all drug classes.
- Symptomatic Management:Topical and systemic agents addressing mucocutaneous manifestations without altering disease trajectory.
- Corticosteroid Therapy:Pulse dosing protocols for acute ocular and neurological flares.
Disease-Modifying Therapy commands current investment priority. Symptomatic Management retains volume relevance in cost-constrained access markets.
End User:
Site-of-care migration from institutional settings to patient-directed administration is redistributing purchasing authority across delivery channels.
- Hospitals:Inpatient and infusion center administration of intravenous biologics with pharmacy-controlled distribution. United States health systems with captive specialty pharmacies capture margin through white-bag models.
- Home Care:Subcutaneous self-administration enabling rural patient access beyond tertiary referral networks. FDA-approved subcutaneous formulations expand addressable populations while reducing infusion center burden.
- Specialty Clinics:Outpatient rheumatology and ophthalmology practices managing stable patients.
- Research Laboratories:Academic medical centers generating real-world evidence for payer negotiations.
Hospitals anchor current revenue capture. Home Care represents the steepest expansion trajectory as formulation innovation enables self-management.
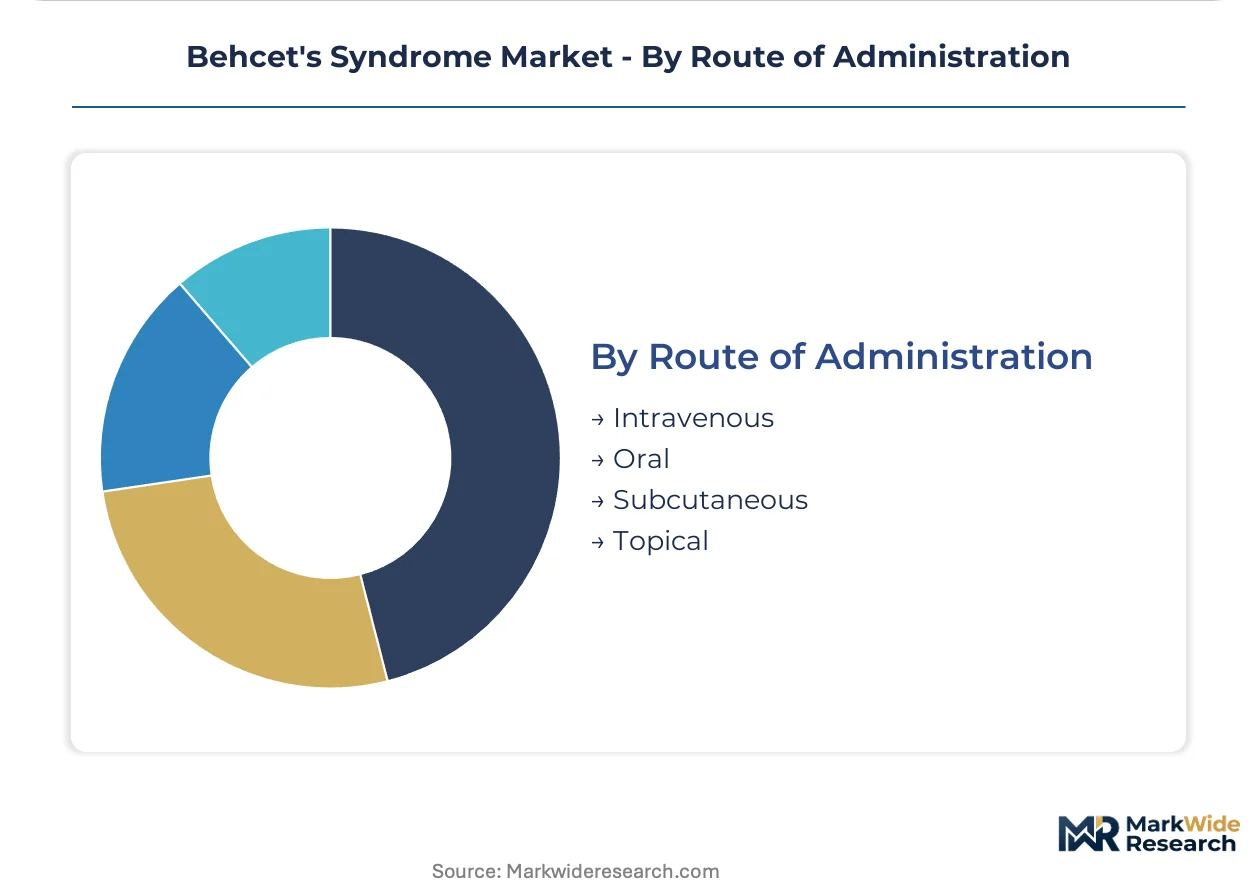
Route of Administration:
Margin structures diverge sharply between capital-intensive infusion infrastructure and distributed subcutaneous delivery.
- Intravenous:Hospital-based infusion requiring cold chain integrity and specialized nursing capacity. EMA's adaptive licensing pathway prioritizes IV formulations for Behcet's uveitis with vision-threatening progression.
- Subcutaneous:Prefilled syringe and autoinjector devices for patient self-administration. Japan's PMDA Sakigake designation accelerates approval timelines for novel subcutaneous mechanisms in rare diseases.
- Oral:Small-molecule immunosuppressants for maintenance therapy.
- Topical:Localized corticosteroid and anesthetic preparations for mucocutaneous ulcers.
Intravenous dominates biologic revenue today. Subcutaneous formulations are gaining share fastest as patient preference and site-of-care economics converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey pioneered systematic Behcet's research at Hacettepe University in the 1970s, establishing clinical criteria that remain foundational. The disease's concentration along the historic Silk Road corridor shapes geographic demand patterns today.
United States
Tertiary referral networks at Mayo Clinic, Cleveland Clinic, and Johns Hopkins manage the most severe vasculitis cases with biologic therapy. The FDA's orphan drug exclusivity framework provides seven-year market protection for novel mechanisms. Boston's Longwood Medical Area anchors clinical trial density for interleukin pathway inhibitors.
Japan
PMDA's Sakigake designation accelerates approval timelines for subcutaneous biologics in rare diseases. The country's aging population drives uveitis-related demand for self-administered formulations. Osaka's pharmaceutical corridor concentrates manufacturing partnerships for monoclonal antibody production.
Germany
Rheumatology practices adopt biosimilar switching protocols for TNF-alpha inhibitors at accelerating pace. The EMA's adaptive licensing pathway enables conditional approval based on surrogate endpoints. Berlin's Charité university hospital generates real-world evidence for payer negotiations.
United Kingdom
NHS specialized commissioning frameworks prioritize disease-modifying therapies for total cost-of-care reduction. NICE technology appraisals shape access to interleukin-targeted alternatives. London's Moorfields Eye Hospital anchors uveitis expertise and registry participation.
Turkey
Domestic prevalence rates exceed global averages, sustaining demand for corticosteroid supply chains and acute flare management. The Ministry of Health maintains national disease registries. Istanbul's Cerrahpaşa Medical Faculty continues longitudinal cohort studies initiated in the 1970s.
Behcet's Syndrome Market Key Industry Players
Capital-heavy biologic manufacturers compete with asset-light specialty distributors for margin capture across infusion and home care channels. The market structure consolidates around originator biologics with biosimilar pressure mounting in European markets. Three archetypes dominate: integrated immunology portfolios, ophthalmology-focused specialists, and acute-care supply chain operators. Competitive moves center on interleukin pathway diversification and site-of-care economics optimization.
Within the integrated immunology tier, AbbVie and Novartis exemplify archetypes leveraging existing infrastructure across multiple autoimmune indications. Pfizer occupies a position emphasizing manufacturing scale for cost-sensitive acute flare markets. Takeda Pharmaceutical Company Limited anchors the Asia-Pacific presence with specialized access programs.
| Leading Market Players |
|---|
| AbbVie |
| Novartis |
| Amgen |
| J Janssen Biotech |
| Abbott |
| Eisai |
| F. Hoffmann-La Roche Ltd. |
| Pfizer |
| Takeda Pharmaceutical Company Limited |
| Others |
Cost & Logistics Intelligence
Integrated delivery network formulary committees concentrate purchasing authority for biologic therapies, anchoring value-based contracting models that tie reimbursement to total cost-of-care outcomes rather than drug acquisition costs alone.
Pricing Analysis
Three-tier pricing structure across originator biologics, biosimilars, and generic immunosuppressants separates mechanism-specific premium positioning from cost-sensitive acute flare management. Price differentiation rests on FDA orphan exclusivity status and EMA adaptive licensing tier, with originator TNF-alpha inhibitors commanding premium positioning against adalimumab and infliximab biosimilars. Cost compression in European markets is intensifying because rheumatology practices in Germany and the United Kingdom accelerate switching protocols. Medicaid programs demonstrate highest price sensitivity due to fragmented prior authorization requirements, while Medicare Advantage risk-based contracts show lowest sensitivity when disease-modifying therapies reduce hospitalization incidence.
Supply Chain Analysis
Specialized biologics manufacturing talent scarcity in Switzerland, Ireland, and Singapore constrains monoclonal antibody production capacity expansion for TNF-alpha and interleukin pathway inhibitors. Raw material dependencies draw from Chinese heparin precursors, South Korean cell culture media, and German chromatography resins. Single-source vulnerability concentrates in contract manufacturing organizations with adaptive protocol expertise for rare disease trials. Distribution runs through hospital pharmacy-controlled white-bag models and captive specialty pharmacy networks in United States health systems, with cold chain integrity requirements limiting logistics flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Behcet's syndrome market compounds steadily as mechanism-specific biologics displace broad immunosuppression across refractory vasculitis subsets, with orphan drug exclusivity protecting development economics for novel interleukin pathway entrants.
For Market Incumbents: Extend interleukin-17 and interleukin-23 pipeline diversification to differentiate from saturated anti-TNF markets threatened by European biosimilar acceleration. Deepen backward integration into cell culture media production to secure supply continuity against Chinese precursor dependency. Prioritize subcutaneous formulation development to capture site-of-care migration from infusion centers toward patient self-administration. For New Entrants and Emerging Players: The gap between premium originator biologics and economy-tier corticosteroids offers white-space positioning for mid-priced oral small-molecule immunomodulators with disease-modifying claims. Target Turkey's acute flare management segment where domestic prevalence sustains corticosteroid volume demand underserved by biologic penetration. Pursue Japan's PMDA Sakigake designation pathway to accelerate approval timelines for novel subcutaneous mechanisms in rare diseases. For Investors and Strategic Acquirers: Large-cap immunology specialists are the most active acquirer in this space, seeking adaptive protocol capabilities and biomarker stratification expertise that outpaces training pipeline output. Five-to-ten year viability hinges on successful transition from anti-TNF to interleukin-targeted portfolios. Monitor real-world evidence generation velocity from European reference networks and United States specialty registries as the critical signal for payer preference shifts between mechanism classes.| Strategic Initiative | Industry Significance |
|---|---|
| Interleukin Pathway Pipeline Diversification | AbbVie and Novartis anchor positioning through IL-17 and IL-23 assets beyond saturated TNF-alpha markets. |
| Subcutaneous Formulation Development | Patient self-administration expands addressable populations beyond tertiary referral networks into rural access markets. |
| Real-World Evidence Registry Participation | Berlin's Charité and London's Moorfields Eye Hospital generate payer negotiation leverage through longitudinal uveitis cohorts. |
| Biosimilar Manufacturing Scale-Up | European rheumatology switching protocols in Germany and United Kingdom compress originator pricing power for infliximab and adalimumab. |
| Adaptive Licensing Pathway Engagement | EMA's conditional approval framework accelerates timelines for Behcet's uveitis subsets with vision-threatening progression. |
Research Approach
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and formulary directors; secondary validation through FDA orphan drug filings, EMA adaptive licensing submissions, and ClinicalTrials.gov protocol registries; and hospital procurement database analysis — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Data-stream reconciliation applied analytical frameworks across the analysis window, modeling treatment line, administration route, patient population severity, and regional regulatory cluster dimensions. CAGRs were derived from mechanism-specific adoption curves and site-of-care migration patterns, with inputs including biologic manufacturing capacity constraints and payer prior authorization intensity by state Medicaid program.
Caveats apply where FDA label expansion decisions, EMA conditional approval conversions, or biosimilar launch sequencing could materially shift the outlook. Material deviation in orphan drug exclusivity litigation outcomes or interleukin pathway clinical trial readouts warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Epidermal Nevus Syndrome Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Anal Cancer Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Peptide-Based Metabolic Disorders Therapeutics Market
Specialty Medicine
Relapsing-Remitting Multiple Sclerosis (MS) Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Acute Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
North America Sports Medicine Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
China Ulcerative Colitis Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Malignant Glioma Therapeutics Market
Specialty Medicine
Exanthema Market
Specialty Medicine
Rhabdomyosarcoma Market