
 Diode Laser Hair Removal Equipment Market | 2026-2036
Diode Laser Hair Removal Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Diode Laser Hair Removal Equipment Market Insights
The EU Green Deal's push for energy-efficient medical devices is consolidating purchasing criteria across European dermatology chains. Alma Lasers leverages its vertically integrated manufacturing footprint in Israel to sustain cost advantages in diode module production. Cynosure Lutronic anchors its competitive position through specialized service contracts that lock in clinic loyalty across North American metropolitan markets.
Diode laser hair removal equipment employs semiconductor-generated coherent light typically at 800–810 nm wavelengths to target melanin in hair follicles without collateral dermal damage. The technology relies on integrated cooling systems—sapphire contact cooling or cryogen spray—to protect epidermal tissue during pulse delivery. Stationary systems dominate installed base value due to higher per-unit pricing and clinical throughput capacity, while handheld devices represent the fastest-expanding segment as home-use protocols gain regulatory clearance in selective jurisdictions. Multi-function systems command premium positioning by combining hair removal with skin rejuvenation capabilities, concentrating margin pools in full-service aesthetic practices.
The FDA's 510(k) clearance pathway and the EU MDR's enhanced clinical evidence requirements shape product development timelines and market access costs for manufacturers targeting dual jurisdiction sales. China's NMPA has tightened registration standards for imported laser aesthetic devices, compelling foreign suppliers to establish local clinical trial partnerships. Stakeholders must monitor evolving home-use classification debates at major regulators, as reclassification would fundamentally reshape channel economics and liability structures.
Market Dynamics
EU MDR's tightened clinical evidence requirements are compressing product development timelines while simultaneously consolidating purchasing power among dermatology chains capable of absorbing compliance costs.
Growth Catalysts
- EU Green Deal energy mandates:Germany's dermatology centers are retrofitting equipment fleets to meet efficiency thresholds, triggering replacement cycles for legacy systems.
- ANVISA protocol updates:Brazil's aesthetic device certification acceleration is driving clinic-level investment in stationary diode systems with verified safety profiles.
- Multi-function platform adoption:Full-service aesthetic practices are consolidating capital expenditure into combined hair removal and skin rejuvenation systems to maximize treatment room utilization.
Market Restraints
- Diode module supply concentration:Semiconductor laser chip fabrication clusters in East Asia create vulnerability to regional logistics disruptions.
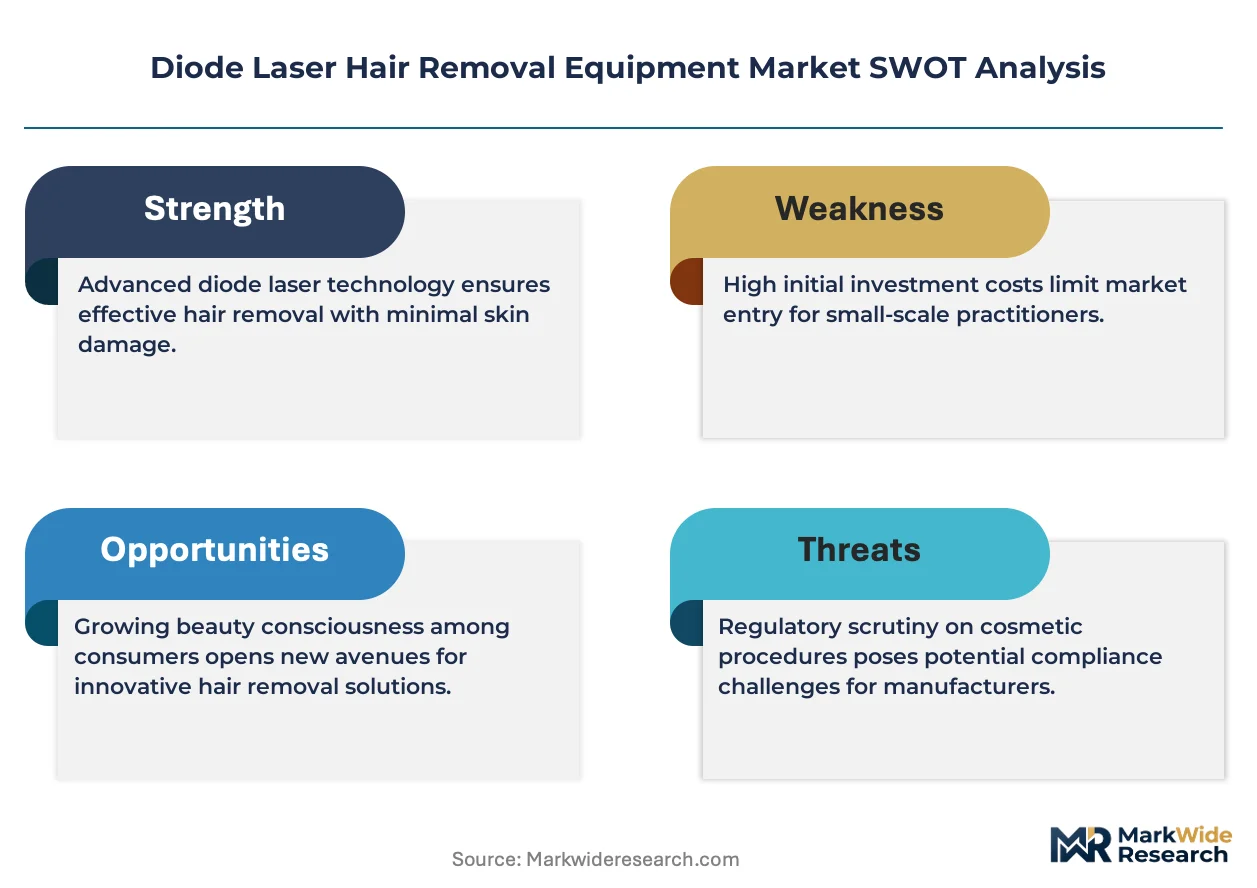
- EU MDR clinical evidence costs:Enhanced pre-market conformity requirements add substantial documentation burden for manufacturers targeting dual US-EU sales.
- Intense pulsed light substitution:IPL devices compete on lower capital cost for budget-conscious clinic segments, pressuring diode laser pricing floors.
Strategic Opportunities
- Home-use regulatory clearance pathways:Selective jurisdictions are establishing classification frameworks for handheld diode devices, opening direct-to-consumer channels.
- NMPA registration partnerships:China's tightened standards for imported laser devices create first-mover advantage for suppliers establishing local clinical trial infrastructure.
- Service contract unbundling:Independent service providers are capturing maintenance revenue from installed base expansion, decoupling hardware from recurring revenue streams.
Industry Challenges
- Laser safety officer certification gaps:Clinic staffing shortages for qualified operators constrain treatment capacity expansion and equipment utilization rates.
- Legacy cooling system integration:Sapphire contact cooling and cryogen spray architectures require specialized technical support networks that strain regional service coverage.
- 510(k) predicate device navigation:FDA clearance pathway complexity extends time-to-market for novel wavelength or pulse-duration configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diode Laser Hair Removal Equipment Market |
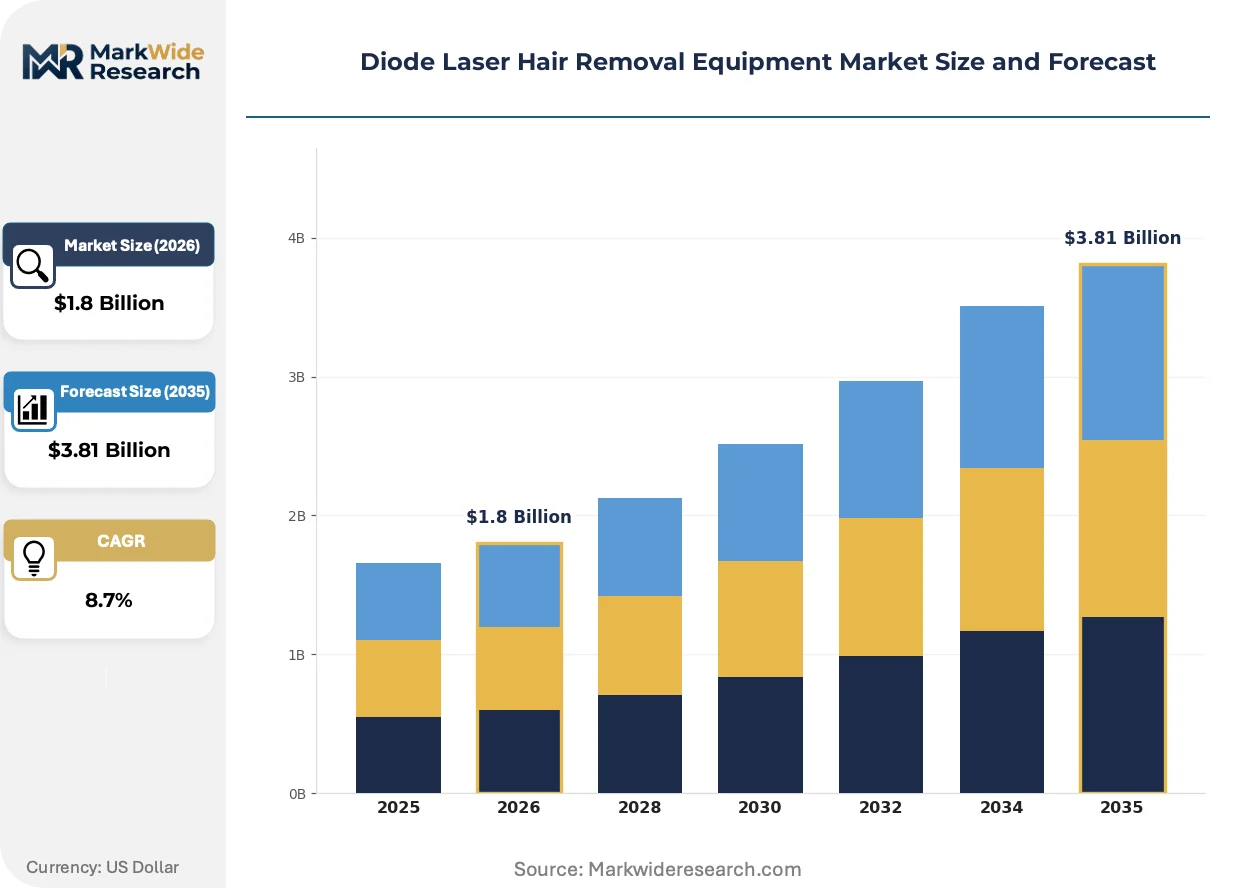
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Stationary Systems, Portable Units, Multi-Function Systems Technology: Diode Lasers, Pulsed Light Technology, Alexandrite Lasers, Nd:YAG Lasers End User: Clinics, Beauty Salons, Dermatology Centers, Home Users Application: Body Hair Reduction, Facial Hair Removal, Skin Rejuvenation, Tattoo Removal |
| Companies Covered | Cynosure Lutronic, Lumenis, Alma Lasers, Cutera, Syneron Candela, Sciton, Fotona, Quanta System, ADSS Laser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diode Laser Hair Removal Equipment Market Trends and Innovations
Semiconductor cooling integration and regulatory harmonization efforts are compressing equipment form factors while expanding addressable treatment protocols beyond traditional hair removal applications.
Triple-wavelength diode platforms combining 755 nm, 808 nm, and 1064 nm outputs are consolidating treatment versatility into single chassis designs. High-volume dermatology chains in metropolitan US markets are standardizing on these systems to reduce device count per treatment room. The technology is consolidating margin pools away from standalone single-wavelength units toward premium-positioned multi-function platforms.
China's NMPA has implemented stricter registration standards for imported laser aesthetic devices, compelling foreign manufacturers to establish domestic clinical trial partnerships. The policy is extending product launch timelines by 18-24 months for non-compliant suppliers. European and Israeli equipment vendors are responding by acquiring Chinese CRO capabilities or licensing to local distributors with established regulatory relationships.
Clinic procurement teams are compressing vendor rosters to concentrate purchasing leverage with manufacturers offering integrated training and service ecosystems. Independent aesthetic practices are consolidating supplier relationships from three to one primary equipment partner, trading price transparency for operational simplicity. This concentration is most visible in North American metropolitan markets where labor costs elevate downtime penalties.
Diode Laser Hair Removal Equipment Market Segmentation
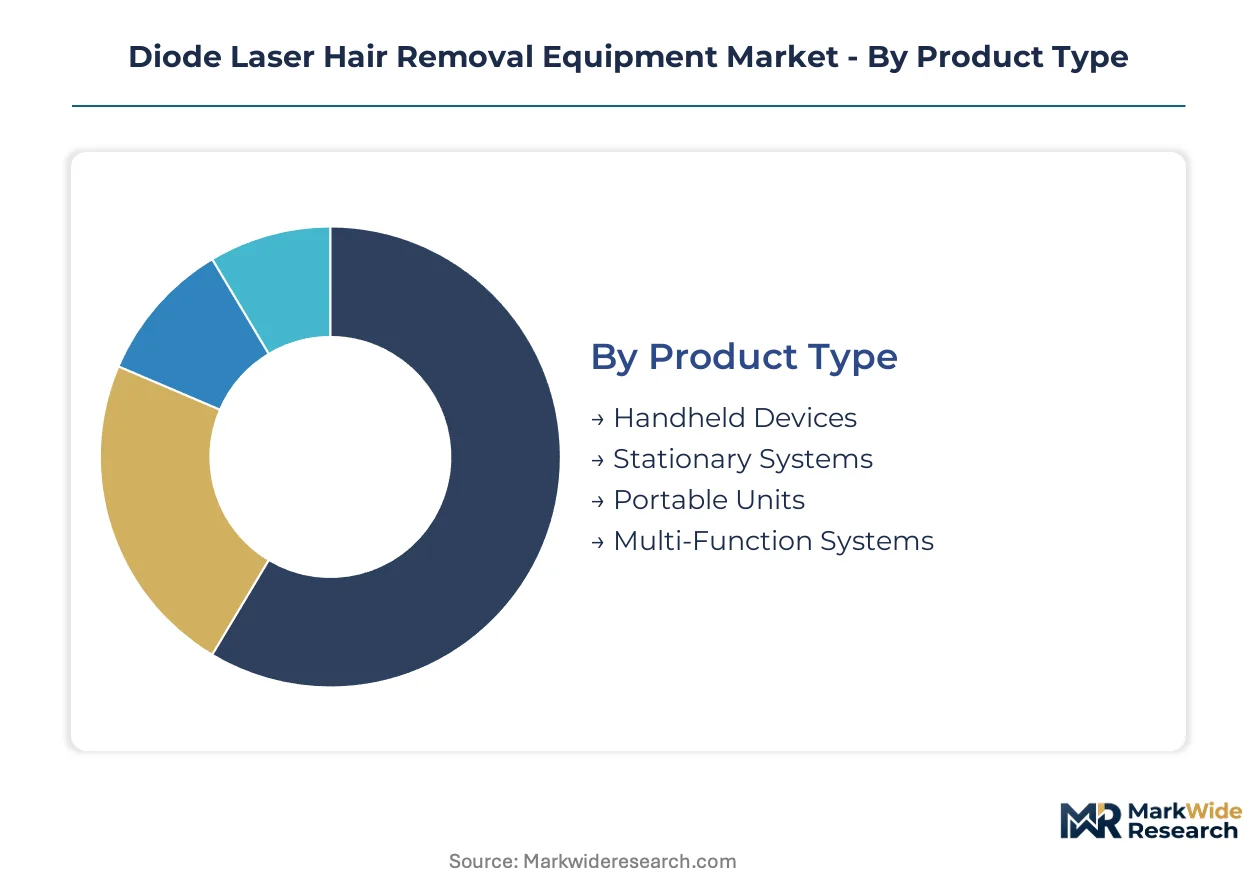
Segmentation in diode laser hair removal equipment reveals how capital deployment, regulatory pathways, and end-use economics fragment purchasing behavior across clinical and consumer channels. Equipment specifications, cooling architectures, and clearance status create tiered entry barriers that reshape competitive dynamics within each category.
Product Type:
Stationary systems demand the highest upfront capital commitment, requiring dedicated treatment room infrastructure and specialized electrical configurations that filter out smaller operators.
- Stationary Systems:Floor-mounted chassis integrate sapphire contact cooling, high-capacity power supplies, and multi-handpiece docking stations for continuous clinical throughput. Dermatology centers in Germany and Brazil anchor procurement volumes as EU MDR and ANVISA certification requirements elevate barriers to entry for lower-cost alternatives.
- Multi-Function Systems:Combined hair removal and skin rejuvenation platforms command premium positioning through triple-wavelength diode architectures and interchangeable handpieces. Full-service aesthetic practices in metropolitan US markets concentrate demand to maximize treatment room utilization rates and amortize capital expenditure across revenue streams.
- Handheld Devices:Battery-operated or corded compact units target home-use protocols with reduced fluence outputs and simplified cooling mechanisms. Selective regulatory clearances in North American and European jurisdictions are opening direct-to-consumer distribution channels.
- Portable Units:Wheeled or transportable designs bridge clinical and mobile service applications with mid-range power specifications. Independent aesthetic practitioners and pop-up clinic operators drive niche procurement for flexible deployment models.
Stationary systems absorb the bulk of installed capacity; handheld devices are expanding most quickly.
Technology:
Wavelength specificity and melanin absorption profiles determine clinical efficacy across diverse skin phototypes, concentrating R&D investment in semiconductor architectures with tunable pulse parameters.
- Diode Lasers:Semiconductor-generated coherent light at 800–810 nm wavelengths delivers targeted follicular heating with integrated epidermal cooling. The technology anchors professional installed bases due to established safety profiles and predictable treatment outcomes across Fitzpatrick skin types I-IV.
- Nd:YAG Lasers:1064 nm long-pulse outputs penetrate deeper dermal layers with minimal epidermal absorption, enabling safe application on darker skin phototypes. Clinics serving diverse patient demographics in Brazil and the United States prioritize this wavelength to expand addressable client bases.
- Alexandrite Lasers:755 nm outputs offer rapid coverage of large treatment areas with high melanin absorption coefficients. Lighter skin type applications in European dermatology chains sustain demand despite higher capital costs per unit.
- Pulsed Light Technology:Broadband non-coherent emission across 500–1200 nm competes on lower equipment pricing for budget-conscious salon segments. IPL substitution pressure constrains diode laser pricing floors in emerging market entry-tier procurement.
Diode lasers retain the dominant installed base; Nd:YAG configurations are climbing the fastest as clinics diversify service capabilities.
End User:
Capital scale and regulatory compliance capacity stratify purchasing authority, with certified medical facilities commanding premium equipment specifications that exclude non-clinical operators.
- Dermatology Centers:Physician-supervised facilities with laser safety officer certification leverage highest-specification stationary systems for complex case management. EU MDR conformity requirements and FDA 510(k) clearances filter procurement toward established manufacturers with documented clinical evidence packages.
- Clinics:Med-spa and aesthetic medicine practices balance equipment versatility against capital constraints through multi-function platform adoption. North American metropolitan markets exhibit concentrated vendor consolidation as procurement teams reduce supplier rosters for operational simplicity.
- Beauty Salons:Non-medical operators face jurisdiction-dependent scope-of-practice limitations that restrict allowable device specifications. IPL and lower-fluence alternatives dominate this channel where regulatory oversight permits aesthetic but not medical claims.
- Home Users:Direct-to-consumer demand concentrates in handheld formats with simplified protocols and reduced energy outputs. Regulatory classification debates at FDA and EU competent authorities determine market access viability for this segment.
Dermatology centers command the highest equipment specifications; home users represent the steepest expansion trajectory pending regulatory clearance harmonization.
Application:
Treatment protocol diversification drives platform configuration choices, with combination capabilities commanding premium positioning against single-purpose alternatives.
- Body Hair Reduction:Large-area treatment requirements prioritize high-repetition-rate diode systems with integrated skin cooling for patient comfort. Brazilian clinic investment in certified stationary systems reflects ANVISA protocol emphasis on verified safety profiles for extensive treatment zones.
- Skin Rejuvenation:Photothermal collagen stimulation protocols leverage shared hardware platforms with hair removal systems to improve capital utilization. Multi-function system adoption concentrates in full-service practices seeking to maximize per-room revenue generation.
- Facial Hair Removal:Precision handpiece requirements and sensitive anatomical targeting elevate specifications for smaller treatment windows. Dermatology centers prioritize ergonomic design and cooling integration for patient retention in high-visibility facial applications.
- Tattoo Removal:Q-switched or picosecond pulse architectures extend platform versatility beyond standard diode capabilities. This application commands specialized configurations that diverge from core hair removal hardware specifications.
Body hair reduction absorbs the bulk of installed capacity; skin rejuvenation is gaining share fastest as practices consolidate multi-function platform investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of diode laser modules concentrates in Israeli and German manufacturing clusters, while consumption spreads across dermatology networks in Brazil, the United States, and European metropolitan markets. This geographic split shapes regulatory compliance strategies and service infrastructure investments.
United States
Metropolitan dermatology chains in New York, Los Angeles, and Miami are standardizing on triple-wavelength platforms to maximize treatment room throughput. FDA 510(k) clearance pathways filter procurement toward established suppliers with documented predicate device histories. The Northeast corridor exhibits concentrated vendor consolidation as procurement teams reduce supplier rosters from three to one primary equipment partner.
Germany
Dermatology centers in Berlin, Munich, and Hamburg are retrofitting equipment fleets to meet EU Green Deal energy efficiency thresholds. EU MDR tightened clinical evidence requirements compress product development timelines while consolidating purchasing power among chain operators capable of absorbing compliance documentation costs. Bavaria anchors manufacturing integration with vertically organized diode module production facilities.
Brazil
Clinic-level investment in certified stationary systems is accelerating across São Paulo and Rio de Janeiro as ANVISA updates aesthetic device certification protocols. Verified safety profiles for extensive treatment zones command procurement priority in a market serving diverse skin phototypes. The Southeast region concentrates installed base value due to higher per-unit pricing and clinical throughput capacity.
China
Foreign manufacturers face extended product launch timelines as NMPA implements stricter registration standards for imported laser aesthetic devices. European and Israeli equipment vendors are acquiring Chinese CRO capabilities or licensing to local distributors with established regulatory relationships. The Yangtze River Delta clusters domestic clinical trial infrastructure for compliance navigation.
Israel
Vertically integrated manufacturing footprints sustain cost advantages in diode module production for export-oriented suppliers. Tel Aviv and Haifa anchor semiconductor laser chip fabrication clusters that supply professional installed bases globally. The country's regulatory alignment with FDA and EU MDR frameworks facilitates dual jurisdiction market access strategies.
Diode Laser Hair Removal Equipment Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with captive supply chains and diversified conglomerates with multi-modality portfolios. Market concentration is moderate, with established dermatology equipment manufacturers holding defensible positions through service contract ecosystems and regulatory clearance histories. Three archetypes dominate: Israeli-integrated diode specialists, US-based multi-platform conglomerates, and European precision-engineering houses. Competitive moves center on M&A for CRO capabilities in China and service contract unbundling to capture recurring maintenance revenue.
Among Israeli-integrated manufacturers, Alma Lasers exemplifies the vertically organized archetype with in-house diode module production. Cynosure Lutronic occupies a position within the US-based multi-platform tier, anchoring competitive presence through specialized service contract structures. Lumenis sits within the diversified technology conglomerate category, representing scale-driven portfolio breadth across aesthetic and surgical applications.
| Leading Market Players |
|---|
| Cynosure Lutronic |
| Lumenis |
| Alma Lasers |
| Cutera |
| Syneron Candela |
| Sciton |
| Fotona |
| Quanta System |
| ADSS Laser |
| Others |
Pricing and Supply Chain Analysis
Triple-wavelength diode platform consolidation is compressing per-treatment hardware costs while concentrating margin capture among Israeli and German manufacturers with in-house semiconductor fabrication. This production-method transition simultaneously reshapes cost economics and supply concentration, as vertically organized producers exploit captive diode module supply to sustain pricing power against assembly-only competitors.
Pricing Analysis
Margin tightening in economy-tier stationary systems reflects IPL substitution pressure from budget-conscious salon segments. Three-tier pricing structure across premium multi-function platforms, standard single-wavelength units, and economy IPL-alternatives stratifies the installed base. Cost-down pressure on mid-range configurations accelerates because Brazilian and Chinese clinics prioritize verified ANVISA and NMPA certification over brand premium. Beauty salons exhibit highest price sensitivity; metropolitan dermatology chains absorbing EU MDR compliance costs show lowest.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gating restricts qualified supplier pools to Israeli, German, and select US manufacturing clusters with documented clinical evidence packages. Semiconductor laser chips, sapphire cooling substrates, and high-voltage pulse power supplies anchor raw material dependencies. Single-source vulnerability concentrates in East Asian diode wafer fabrication exposed to regional logistics disruption. Distribution runs through authorized dealer networks with mandatory technician certification rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity for medical-grade laser chips operates at effective supply constraint, propping equipment pricing despite IPL competition. Diode module fabrication bottlenecks limit rapid capacity expansion.
For Market Incumbents: Hedge against Nd:YAG wavelength substitution by securing long-term sapphire substrate supply agreements with Israeli crystal growers. Deepen backward integration into diode chip fabrication to defend margin position against Chinese assembly competitors exploiting NMPA registration partnerships. Prioritize service contract unbundling to capture recurring maintenance revenue from installed base expansion. For New Entrants and Emerging Players: Capture white-space in handheld home-use protocols where FDA and EU regulatory classification debates remain unresolved. Brazil's ANVISA certification acceleration creates penetrable entry path for mid-tier stationary systems with verified safety documentation. Pursue direct-to-consumer channel development pending clearance harmonization. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of Chinese CRO capabilities by Israeli and European equipment vendors navigating NMPA registration timelines. Long-term viability favors suppliers with demonstrated dual-jurisdiction clearance histories and captive semiconductor production. Watch FDA home-use reclassification debates as inflection indicator for channel economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements compress development timelines for German dermatology chains. |
| Hospital System Partnership | Metropolitan dermatology network consolidation in the US reduces vendor rosters to single-equipment partners. |
| Software Companion Development | Treatment protocol automation addresses laser safety officer certification gaps constraining clinic capacity. |
| Backward Integration | In-house diode module production sustains cost advantages for Israeli manufacturers against assembly competitors. |
| Reimbursement Strategy | Skin rejuvenation indication expansion maximizes per-room revenue generation in full-service aesthetic practices. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with dermatology equipment procurement managers, biomedical engineers at hospital purchasing committees, laser safety officers, and aesthetic clinic operators combined with FDA 510(k) databases, EU MDR notified body documentation, and ANVISA certification registries. Bottom-up equipment shipment data triangulated against top-down dermatology center capital expenditure surveys.
Data-stream reconciliation across product type, technology wavelength, end-user facility tier, and regional regulatory cluster segmentation generated volume and value outputs. CAGRs derived from installed base replacement cycle analysis and clinic expansion patterns across the projection horizon. NMPA registration timeline data and EU Green Deal energy efficiency retrofit schedules informed regional growth differentials.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA home-use classification shifts and diode wafer fabrication capacity expansion. Forecasts reflect assumptions regarding ANVISA protocol stability and EU MDR documentation burden persistence. A model refresh is warranted upon material change in semiconductor supply chain regionalization or major regulator reclassification rulings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neurosurgical Products Market
Medical Devices
Global Obstetrics Devices Market
Medical Devices
IV Therapy and Vein Access Devices Market
Medical Devices
Sinus Dilation Devices Market
Medical Devices
Gastroretentive Drug Delivery Systems Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Global Coronary Artery Bypass Graft Devices Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Colposcopes Market
Medical Devices
Video Dermatoscope Market
Medical Devices
Global Sphygmomanometer Market
Medical Devices
Pacemaker/Defibrillator Lead Extraction Kits Market
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Wireless Breast Pump Market