
 Laparoscopic Electrodes Market | 2026-2036
Laparoscopic Electrodes Market Size, Share, and Industry Trends Forecast 2026-2036
Laparoscopic Electrodes Market Intelligence
A shift from single-source supplier contracts toward multi-source procurement for disposable electrodes is rebalancing purchasing power within hospital networks. Medtronic leverages its extensive distribution network to maintain a significant presence in major markets like the United States and Germany. B. Braun Melsungen AG differentiates through its focus on material science and biocompatible coatings for its electrode tips. CONMED Corporation competes by offering a broad portfolio covering both monopolar and bipolar electrode technologies.
Laparoscopic electrodes are surgical instruments for cutting, coagulation, and dissection of tissue in minimally invasive procedures. These devices feature tungsten or stainless steel tips with precise insulation to prevent unintended thermal damage. Monopolar electrodes dominate in volume for routine procedures, while bipolar electrodes command higher margins in complex surgeries. Hospitals remain the largest end-user segment, with ambulatory surgery centers showing significant adoption of disposable devices.
Regulatory compliance is critical, with devices requiring clearance from bodies like the U.S. FDA through its 510(k) pathway. In Europe, adherence to the Medical Device Regulation (MDR) and obtaining CE marking are mandatory for market access, demanding extensive clinical data. Manufacturers must now decide whether to invest in reusable, sterilizable systems or focus on the expanding market for single-use, disposable electrodes to align with evolving hospital procurement models.
Market Dynamics
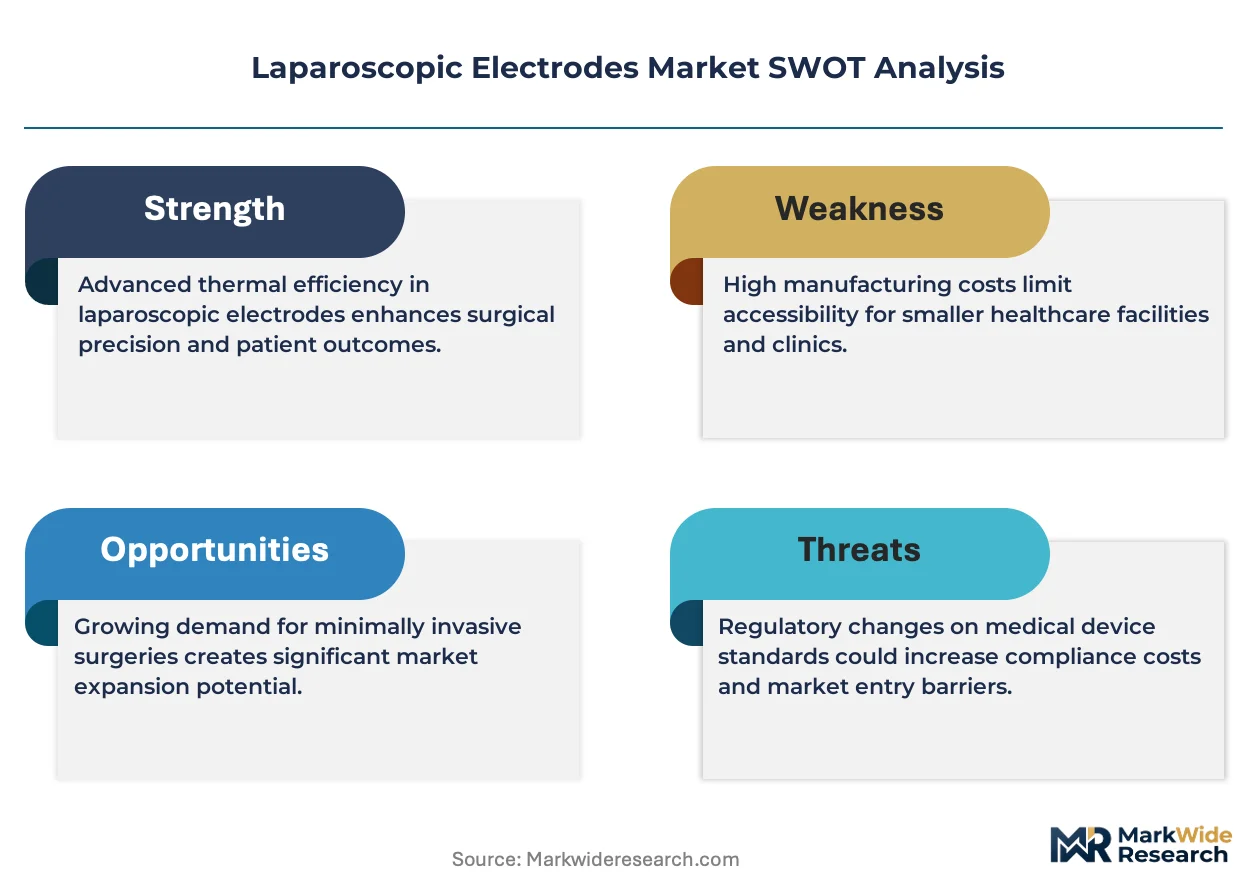
The central dynamic shaping the market is the tension between the expanding utility of single-use, disposable electrodes and the stringent regulatory frameworks, such as the EU's MDR, which elevate the cost and complexity of bringing any new device to market.
Growth Catalysts
- Advances in Material Science:The development of novel biocompatible coatings and tungsten alloys for electrode tips enhances performance in cutting and coagulation, improving surgical outcomes and encouraging adoption in specialized procedures like advanced gynecological surgery.
- Minimally Invasive Procedure Volume:A sustained increase in the number of laparoscopic surgeries performed in hospital-based general surgery, particularly in the United States, directly expands the core consumer base for both monopolar and bipolar electrodes.
- Streamlined Regulatory Pathways:The U.S. FDA's 510(k) clearance pathway provides a relatively predictable and efficient route to market for devices that can demonstrate substantial equivalence, fostering innovation and competition among manufacturers.
Market Restraints
- High Input Material Costs:The price of medical-grade tungsten and stainless steel, critical for manufacturing durable and precise electrode tips, contributes significantly to production costs, limiting margin flexibility, especially for disposable devices.
- Stringent European Regulations:The EU's Medical Device Regulation (MDR) imposes extensive clinical data and post-market surveillance requirements, creating a high barrier to entry and increasing compliance overhead for manufacturers seeking CE marking.
- Threat from Alternative Technologies:Energy devices based on ultrasonic or advanced bipolar sealing technologies present a substitution risk in certain high-value procedures, competing directly with traditional laparoscopic electrodes for capital budget allocation in hospitals.
Strategic Opportunities
- Emerging Market Penetration:Significant opportunity exists in Latin American and Southeast Asian countries, where healthcare infrastructure investment and rising surgeon proficiency with minimally invasive techniques are creating new demand for laparoscopic instruments.
- Integration of Smart Features:Incorporating sensor technology for real-time tissue impedance monitoring into electrode tips offers a pathway to differentiate products, enhance safety by preventing thermal spread, and command higher price points.
- Expansion into Ambulatory Surgery Centers:The growing procedural volume in ambulatory surgery centers (ASCs) presents a key opportunity for disposable electrodes, as these facilities prioritize operational efficiency and rapid patient turnover.
Industry Challenges
- Dual Regulatory Compliance Burden:Manufacturers face the operational challenge of simultaneously managing compliance with the FDA's requirements in the U.S. and the more data-intensive CE marking process under the EU's MDR, straining internal resources.
- Sterilization and Logistics Complexity:Hospitals struggle with the operational trade-offs between managing the complex, resource-intensive sterilization logistics for reusable electrodes and ensuring supply chain consistency for single-use disposables.
- Surgeon Training on Advanced Systems:A skills gap in the proficient use of advanced bipolar electrode systems in some markets can slow the adoption of these higher-margin products, limiting revenue growth for manufacturers specializing in complex surgical tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laparoscopic Electrodes Market |
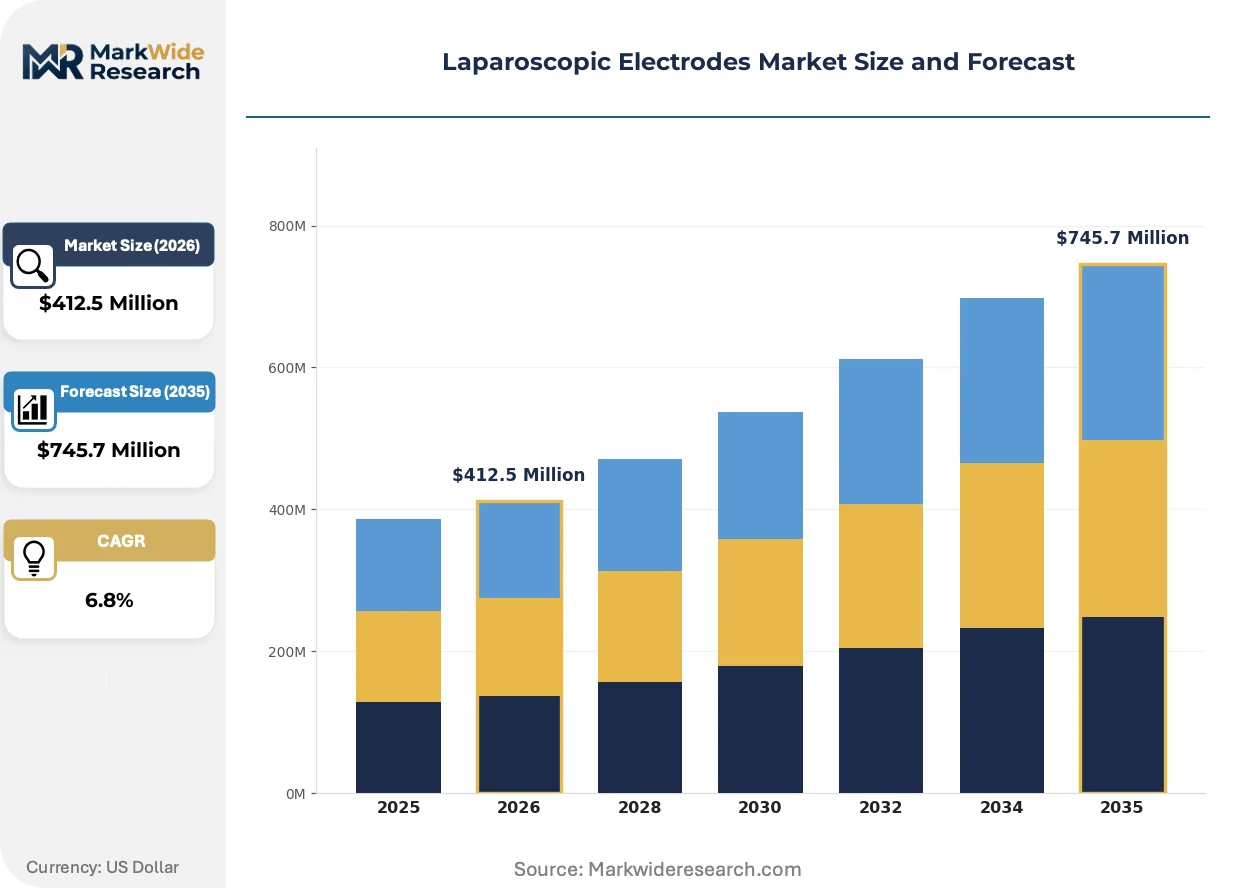
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Electrodes, Passive Electrodes, Monopolar Electrodes, Bipolar Electrodes Application: Surgery, Diagnostics, Research, Training End User: Hospitals, Clinics, Research Laboratories, Ambulatory Surgery Centers Technology: Conventional, Advanced, Self-Contained, Disposable |
| Companies Covered | Medtronic, B. Braun Melsungen AG, CONMED Corporation, LaproSurge, Erbe Elektromedizin GmbH, Symmetry Surgical, Unimax Medical Systems, Lagis Enterprise Co., Ltd., Bharat Surgical Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laparoscopic Electrodes Market Strategic Shifts & Innovations
Technological evolution in material science and smart device integration is converging with new hospital procurement models. This intersection is creating distinct performance tiers between standard disposable electrodes and advanced reusable systems designed for complex, specialized surgeries.
Sensor-integrated electrodes feature embedded micro-sensors that provide real-time data on tissue characteristics like impedance. These advanced devices are seeing steady adoption within large academic hospitals for complex oncological and bariatric surgeries. This technology is automating energy delivery to tissue, which minimizes the need for surgeon estimation and reduces the risk of collateral thermal damage.
The European Union's Medical Device Regulation (MDR) has fundamentally altered market access requirements. It mandates more rigorous clinical evidence and continuous post-market surveillance for all devices, including long-established electrode designs. This regulation affects all manufacturers targeting the European market, forcing many to rationalize their portfolios and invest substantially in recertification to maintain their CE marking.
A notable behavioral shift involves hospital networks moving from exclusive, single-vendor agreements to multi-source strategies for disposable medical supplies. This change disrupts the market share of incumbent suppliers and creates openings for specialized firms offering differentiated electrode tip geometries or material benefits. The trend is particularly visible in the United States and Germany, where group purchasing organizations prioritize cost control and supply chain diversification.
Laparoscopic Electrodes Market Segmentation
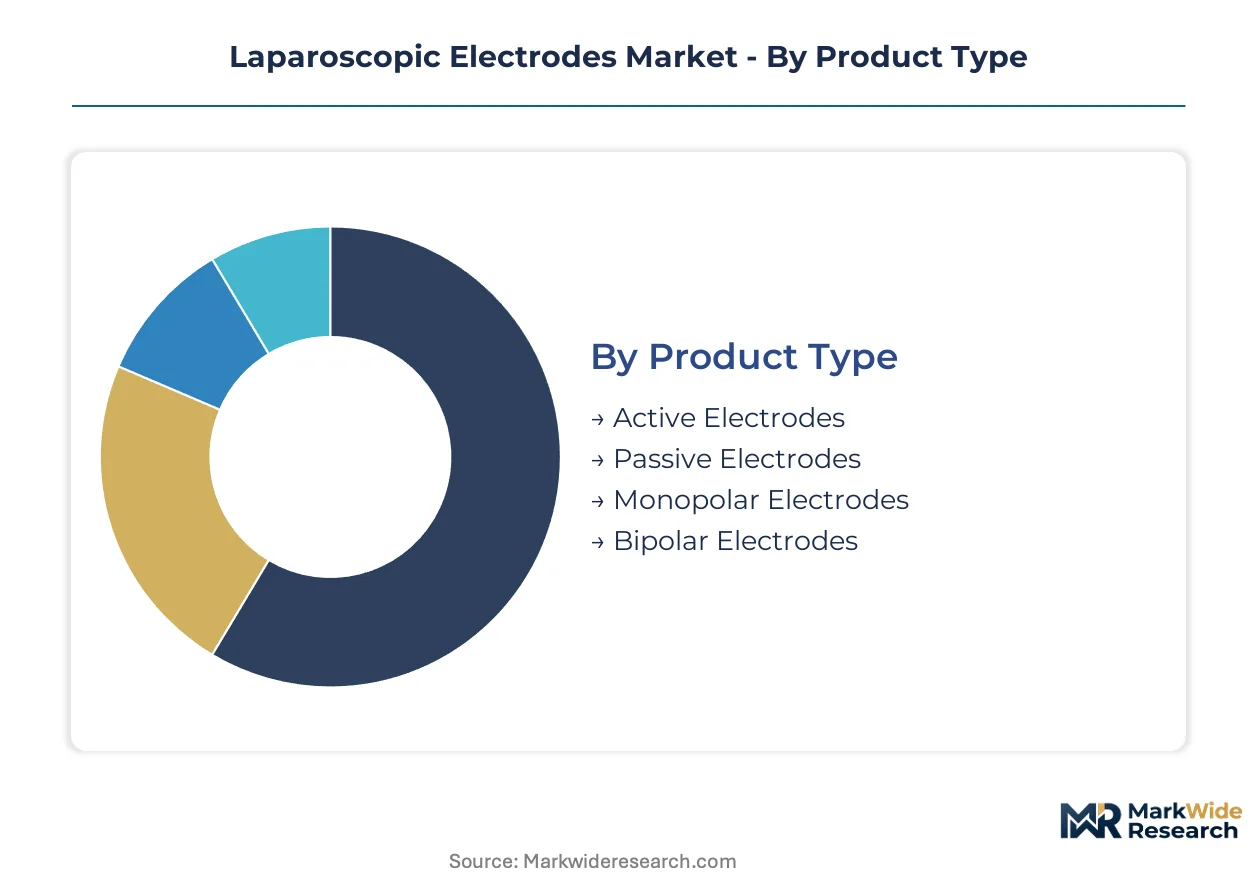
Understanding the segmentation of the laparoscopic electrodes market is crucial for manufacturers to align product development with specific clinical needs and for healthcare providers to optimize procurement strategies. This detailed breakdown reveals where innovation is most impactful and where demand for various electrode types is concentrated across different surgical environments.
Product Type:
The demand for laparoscopic electrodes often follows the natural upgrade and replacement cycles within surgical facilities, influencing the adoption of newer product types.
- Monopolar Electrodes:These devices feature a single active electrode and require a separate patient return electrode pad, primarily used for cutting and coagulation in routine procedures. Demand concentrates in hospital-based general surgery in the United States, driven by their versatility and established use in a high volume of minimally invasive procedures.
- Bipolar Electrodes:Bipolar electrodes incorporate both active and return electrodes at the surgical site, confining the current to a small tissue area, which minimizes thermal spread. These devices command higher margins in complex surgeries like advanced gynecological procedures, where precise tissue sealing is critical.
- Active Electrodes:Active electrodes directly deliver energy to tissue for cutting or coagulation, forming the functional tip of both monopolar and bipolar systems.
- Passive Electrodes:Passive electrodes, also known as return electrodes, safely disperse electrical current from the patient's body in monopolar systems, preventing burns.
Monopolar Electrodes sit at the top of the volume ranking, with Bipolar Electrodes climbing the fastest.
Application:
The volume of procedures performed dictates the specific application requirements for laparoscopic electrodes, driving demand across various surgical settings.
- Surgery:Laparoscopic electrodes are essential for a wide range of minimally invasive surgical interventions, including general surgery, gynecology, and bariatric procedures. The sustained increase in laparoscopic surgeries performed in hospitals, particularly in the United States, expands the core consumer base.
- Diagnostics:In diagnostic laparoscopy, electrodes are used for tissue sampling or precise lesion removal, requiring fine control and minimal collateral damage. Demand for these applications is gaining traction in academic hospitals due to the need for advanced imaging and precise tissue manipulation.
- Research:Research applications utilize laparoscopic electrodes for developing new surgical techniques and evaluating device performance in laboratory settings.
- Training:Training programs employ laparoscopic electrodes in simulation environments, allowing surgeons to practice techniques without patient risk.
While Surgery represents the largest segment, Diagnostics is gaining procedural share.
End User:
Different end-user types exhibit distinct procurement patterns and clinical needs, directly influencing the design and distribution of laparoscopic electrodes.
- Hospitals:Hospitals represent the largest end-user segment, performing the majority of complex and routine laparoscopic surgeries, and drive significant volume demand for both monopolar and bipolar electrodes. These facilities often manage large procurement contracts and face dual regulatory compliance burdens for device use.
- Ambulatory Surgery Centers:ASCs are increasingly adopting disposable laparoscopic electrodes due to their focus on operational efficiency, rapid patient turnover, and streamlined sterilization processes. This segment presents a key opportunity for manufacturers of single-use devices, especially in the United States.
- Clinics:Clinics performing minor outpatient procedures use laparoscopic electrodes for less invasive interventions, prioritizing ease of use and cost-effectiveness.
- Research Laboratories:Research laboratories utilize these instruments for preclinical studies, device testing, and the development of new surgical approaches.
Hospitals drive the majority of purchases, as Ambulatory Surgery Centers expand their footprint for specific procedures.
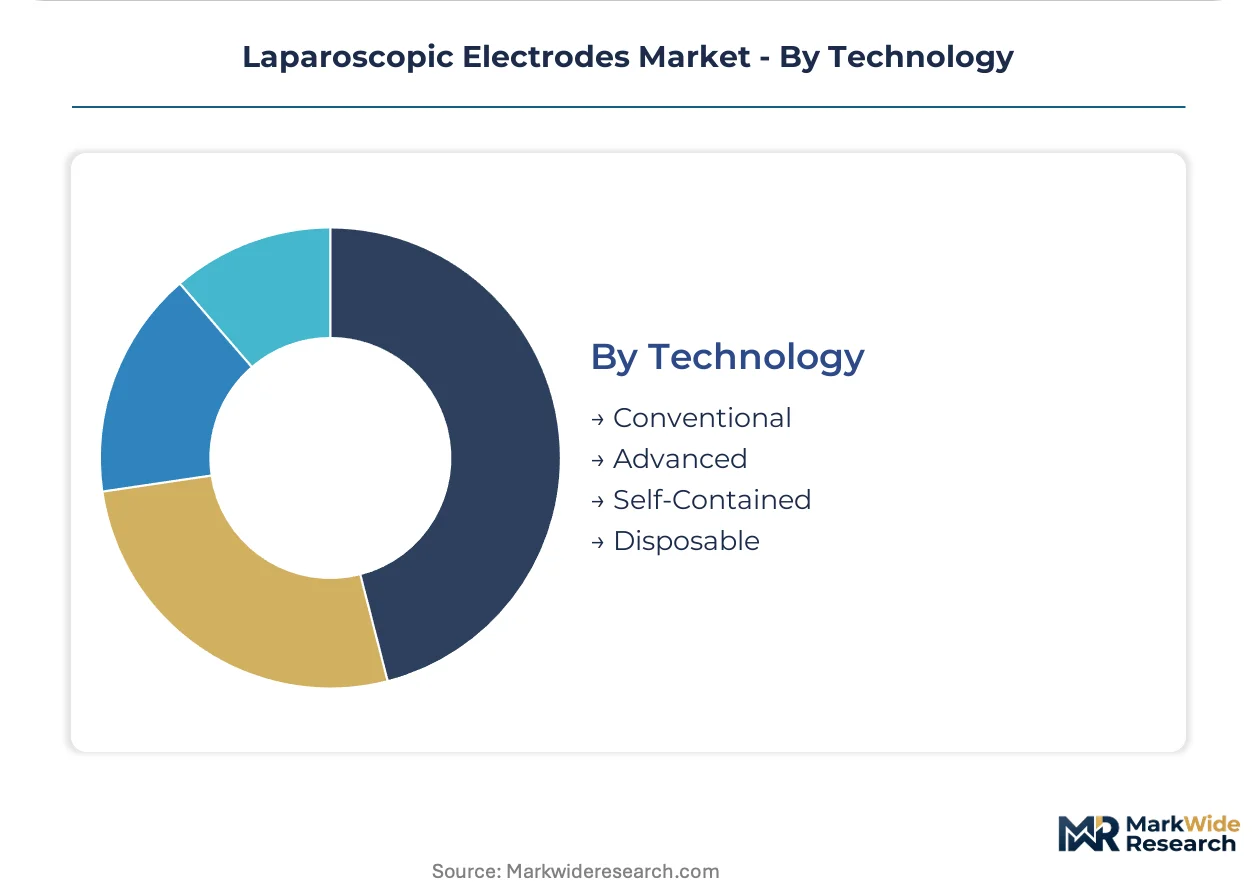
Technology:
Technology choices in laparoscopic electrodes reflect a balance between initial investment, long-term operational costs, and desired clinical performance.
- Disposable:Disposable laparoscopic electrodes are designed for single-use, eliminating sterilization costs and reducing cross-contamination risks, aligning with evolving hospital procurement models. The market for these devices is expanding, particularly in ambulatory surgery centers and for routine procedures.
- Advanced:Advanced technologies include sensor-integrated electrodes for real-time tissue impedance monitoring and specialized materials for enhanced cutting or coagulation performance. These systems see adoption in large academic hospitals for complex oncological and bariatric surgeries, commanding higher price points.
- Conventional:Conventional electrodes rely on established designs and materials like stainless steel, offering reliable performance for standard laparoscopic procedures.
- Self-Contained:Self-contained electrodes often integrate power sources or suction capabilities directly into the handle, simplifying setup for specific surgical tasks.
The shift towards Disposable solutions is pronounced, even as Conventional technology continues to serve foundational needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, with its advanced healthcare infrastructure, drives significant demand for laparoscopic electrodes. This region benefits from a high volume of minimally invasive procedures and rapid adoption of surgical technologies. Strict regulatory frameworks, like the U.S. FDA's 510(k) pathway, influence market access.
United States
The United States leads in laparoscopic electrode consumption due to increased minimally invasive procedures and robust adoption in general surgery. U.S. FDA's 510(k) clearance pathway provides an efficient route for innovative devices. Medical device clusters in California actively develop next-generation surgical instruments.
Germany
Germany's market for laparoscopic electrodes is shaped by sophisticated healthcare systems and the influence of group purchasing organizations. Adherence to the EU's Medical Device Regulation (MDR) mandates extensive clinical data for market access. The medical technology hub in Munich focuses on advanced material science and biocompatible coatings.
Japan
Demand in Japan stems from an aging population requiring precise surgical interventions and high adoption of advanced medical technologies. PMDA clearance processes ensure device safety and efficacy, influencing product design. Tokyo's academic hospitals are at the forefront of integrating sensor-integrated electrodes.
China
China presents a rapidly expanding market for laparoscopic electrodes, fueled by government investment in healthcare infrastructure and a growing number of trained surgeons. NMPA approval processes are critical for market entry, with local manufacturers competing on cost. Shanghai's medical device industrial parks are becoming key centers for domestic production and innovation.
India
India's market expansion is driven by increasing healthcare access and rising surgeon proficiency in minimally invasive techniques across urban centers. CDSCO guidelines govern device registration and import, ensuring product quality and patient safety. Bengaluru's medical technology ecosystem supports the development and adoption of cost-effective laparoscopic solutions.
Laparoscopic Electrodes Market Key Industry Players
Global majors compete with regional champions across product portfolios and regulatory expertise, shaping a tiered market structure. This landscape features large, diversified corporations, specialized material science innovators, and broad portfolio providers, each catering to distinct clinical needs and procurement models. Companies frequently engage in portfolio diversification, geographic expansion, and strategic partnerships to maintain market position and capture emerging opportunities in both established and developing regions.
At the scale-driven end, Medtronic, a global entity, represents a diversified player leveraging extensive distribution networks for significant market presence, particularly in major markets like the United States and Germany. B. Braun Melsungen AG, a German-based company, exemplifies specialization through its focus on material science and biocompatible coatings for its electrode tips, differentiating its product offerings for precise surgical applications. CONMED Corporation, an Inc.-structured firm, occupies a position as a broad portfolio provider, offering comprehensive solutions across both monopolar and bipolar electrode technologies to meet varied surgical needs in hospitals and ambulatory settings.
| Leading Market Players |
|---|
| Medtronic |
| B. Braun Melsungen AG |
| CONMED Corporation |
| LaproSurge |
| Erbe Elektromedizin GmbH |
| Symmetry Surgical |
| Unimax Medical Systems |
| Lagis Enterprise Co., Ltd. |
| Bharat Surgical Co |
| Others |
Cost & Logistics Intelligence
Hospital networks, with their multi-source procurement strategies, drive a transactional, per-unit pricing model for disposable electrodes. This shift rebalances purchasing power, influencing manufacturer margins and product development cycles.
Pricing Analysis
High input material costs for medical-grade tungsten and stainless steel directly affect electrode pricing. The dominant pricing model is per-unit transactional, especially for disposable electrodes. Price differentiation stems from material science advancements and regulatory compliance levels, such as CE marking or U.S. FDA 510(k) clearance. Pricing softness in the disposable segment reflects increasing competition and hospital procurement's focus on cost control. Ambulatory Surgery Centers are highly price-sensitive, prioritizing cost-effectiveness, while large academic hospitals prioritize advanced features and are less sensitive to price for specialized devices.
Supply Chain Analysis
Adherence to stringent frameworks like the EU's MDR and U.S. FDA 510(k) clearance acts as a significant supply chain gate, limiting market access. Production of medical-grade components concentrates in Germany, the United States, and China. The supply chain relies on specialized tungsten alloys and medical-grade stainless steel for electrode tips. A structural risk is single-source vulnerability for specialized biocompatible coatings. Downstream distribution runs through established medical device distributors and direct sales forces to hospitals and ASCs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laparoscopic electrodes market presents a margin-expansion story, driven by the shift towards higher-value bipolar electrodes and sensor-integrated devices. This allows for premium pricing in complex surgical procedures.
For Market Incumbents:To counter the substitution risk from alternative energy devices, Medtronic and CONMED Corporation must invest in advanced bipolar sealing technologies. Deepen vertical integration into material science for biocompatible coatings, securing supply for high-performance electrode tips. Pursue strategic partnerships with academic hospitals to drive adoption of sensor-integrated systems.
For New Entrants and Emerging Players:Enter via specialized electrode tip geometries or novel material benefits targeting emerging markets like India and Southeast Asia. Focus on cost-effective disposable solutions for ambulatory surgery centers, emphasizing operational efficiency. Leverage efficient regulatory pathways, such as the U.S. FDA's 510(k), to accelerate market entry for differentiated products.
For Investors and Strategic Acquirers:Medical device conglomerates are the most active acquirers in this space, seeking to consolidate product portfolios and expand geographic reach. Long-term viability over the next decade favors companies with strong intellectual property in sensor integration and advanced materials. Target acquisition archetypes include specialized firms with niche product lines or strong regulatory compliance expertise. The signal to watch is an increasing rate of M&A activity involving advanced technology electrode manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Sensor-Integrated Electrodes | Enhances safety and precision in complex surgeries, commanding premium pricing from academic hospitals. |
| Expand Manufacturing in Southeast Asia | Reduces production costs and improves market access in rapidly growing healthcare economies. |
| Secure CE Marking for Advanced Designs | Ensures continued market access to the highly regulated and lucrative European medical device market. |
| Develop Multi-Source Procurement Partnerships | Diversifies supply chain for disposable electrodes, reducing dependency and improving cost control for hospitals. |
| Offer Comprehensive Training Programs | Addresses the surgeon skills gap for advanced bipolar systems, accelerating adoption in new markets. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. Interviews engaged clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary data sources included U.S. FDA 510(k) clearances, EU MDR documentation, and hospital procurement databases. This approach facilitated bottom-up and top-down triangulation for robust data synthesis.
Segment-weighting across product type, application, end-user, and technology dimensions formed the analytical framework over the projection horizon. The model incorporated industry-specific forecast inputs such as minimally invasive procedure volumes and regulatory approval timelines. CAGR derivation involved assessing historical growth trends and projected market shifts. The framework also considered regional healthcare infrastructure investments.
Inputs from hospital procurement data and regulatory filings were available through the study window; gaps in emerging market procedure volumes introduce uncertainty bands. Forecasts reflect documented assumptions regarding technological advancements and healthcare spending. A model refresh is warranted upon material change in global medical device regulations or raw material costs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Goggle Market
Medical Devices
Brazil Respiratory Devices Market
Medical Devices
Global Advanced Drug Delivery Systems Market
Medical Devices
Sweden Respiratory Devices Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Global Embolic Protection Device Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
Pocket Otoscope Market
Medical Devices
Cervical Retractors Market
Medical Devices
UK Artificial Organs and Bionic Implants Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
Europe Nurse Call Systems Market
Medical Devices
Drainage Catheters Market
Medical Devices
Support Surfaces Market