
 Catheter Tip Syringe Market | 2026-2036
Catheter Tip Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Catheter Tip Syringe Market Outlook
Modular packaging of catheter tip syringes with enteral feeding accessories is pivoting procurement patterns across acute and homecare channels. Cardinal Health, Inc. leverages broad distribution networks to sustain hospital contract penetration. Becton, Dickinson and Company anchors its position through sterile disposable specialization. Terumo Corporation differentiates via polymer engineering capabilities that extend product performance thresholds.
A catheter tip syringe is a specialized medical syringe featuring a tapered, conical tip designed for secure connection to enteral feeding tubes, urinary catheters, and other non-Luer medical devices, typically manufactured from polypropylene or glass with graduated barrel markings for precise volumetric delivery. The sterile disposable segment dominates procurement volumes in hospitals due to infection control mandates, while the homecare end-user category captures expanding demand as enteral nutrition shifts beyond institutional settings. Polypropylene material formulations lead manufacturing output for their chemical resistance and disposability, though glass variants retain niche positions in pharmaceutical compounding applications.
The FDA regulates catheter tip syringes as Class II medical devices under 510(k) premarket notification pathways, while ISO 7886 standards govern syringe performance and biocompatibility testing protocols. The EU Medical Device Regulation imposes strengthened clinical evidence requirements on enteral device manufacturers seeking CE marking access. Stakeholders must monitor evolving material compliance thresholds and homecare reimbursement structures to align portfolio investments with shifting site-of-care economics.
Market Dynamics
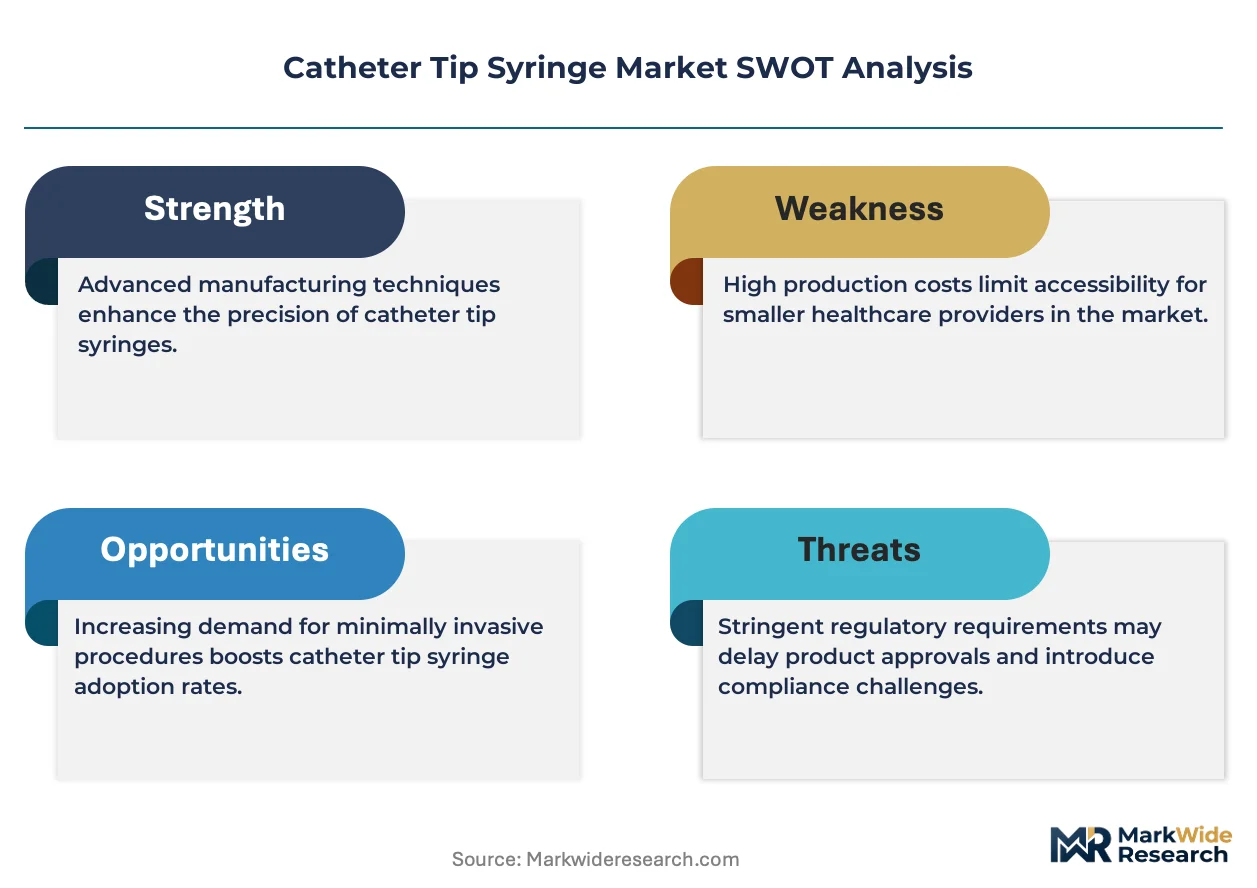
The catheter tip syringe market is undergoing structural compression as site-of-care economics force manufacturers to reconcile hospital infection control mandates with homecare reimbursement constraints. FDA 510(k) pathway revisions for enteral devices are simultaneously extending validation timelines and raising competitive barriers for sterile disposable portfolios.
Growth Catalysts
- Aging Demographics:Chronic disease prevalence in the United States sustains hospital and home-based consumption of enteral feeding accessories. Medicare reimbursement for home enteral nutrition is expanding addressable patient populations.
- ISO 7886 Compliance:Harmonized international performance standards reduce regulatory fragmentation for polypropylene syringe manufacturers seeking multi-market access. Biocompatibility testing protocols now align across major jurisdictions.
- Polymer Engineering:Advanced polypropylene formulations with enhanced chemical resistance are displacing glass variants in pharmaceutical compounding. Material science investments extend product performance thresholds for high-frequency enteral delivery.
Market Restraints
- Propylene Feedstock Volatility:Crude oil price fluctuations transmit directly to polypropylene resin costs. Manufacturers lack pricing power to pass input volatility through to contracted hospital procurement.
- Regulatory Friction:FDA 510(k) premarket notification updates for enteral devices impose extended validation timelines. Small manufacturers face disproportionate compliance burden relative to revenue scale.
- Substitution Threat:Oral medication administration systems compete for low-acuity enteral applications. Nasogastric tube pumps with integrated reservoirs reduce discrete syringe consumption in institutional settings.
Strategic Opportunities
- Homecare Channel Expansion:Durable medical equipment suppliers are capturing enteral feeding kit assembly. Modular packaging of syringes with extension sets and feeding bags creates recurring revenue streams.
- EU MDR Tailwind:Strengthened clinical evidence requirements for CE marking favor manufacturers with existing ISO 13485 quality systems. Competitors with validated sterility assurance levels command premium positioning.
- Smart Packaging Convergence:RFID-enabled syringe barrels combined with enteral pump connectivity are enabling dose verification workflows. Hospital systems adopting closed-loop medication administration drive specification requirements.
Industry Challenges
- Sterility Assurance Talent Scarcity:Aseptic processing engineers with ISO 14644 cleanroom expertise command premium compensation. Workforce gaps constrain capacity expansion for high-volume sterile disposable lines.
- Legacy Equipment Integration:New polymer formulations must maintain compatibility with existing enteral pump connector standards. Validation requirements for material changes extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catheter Tip Syringe Market |
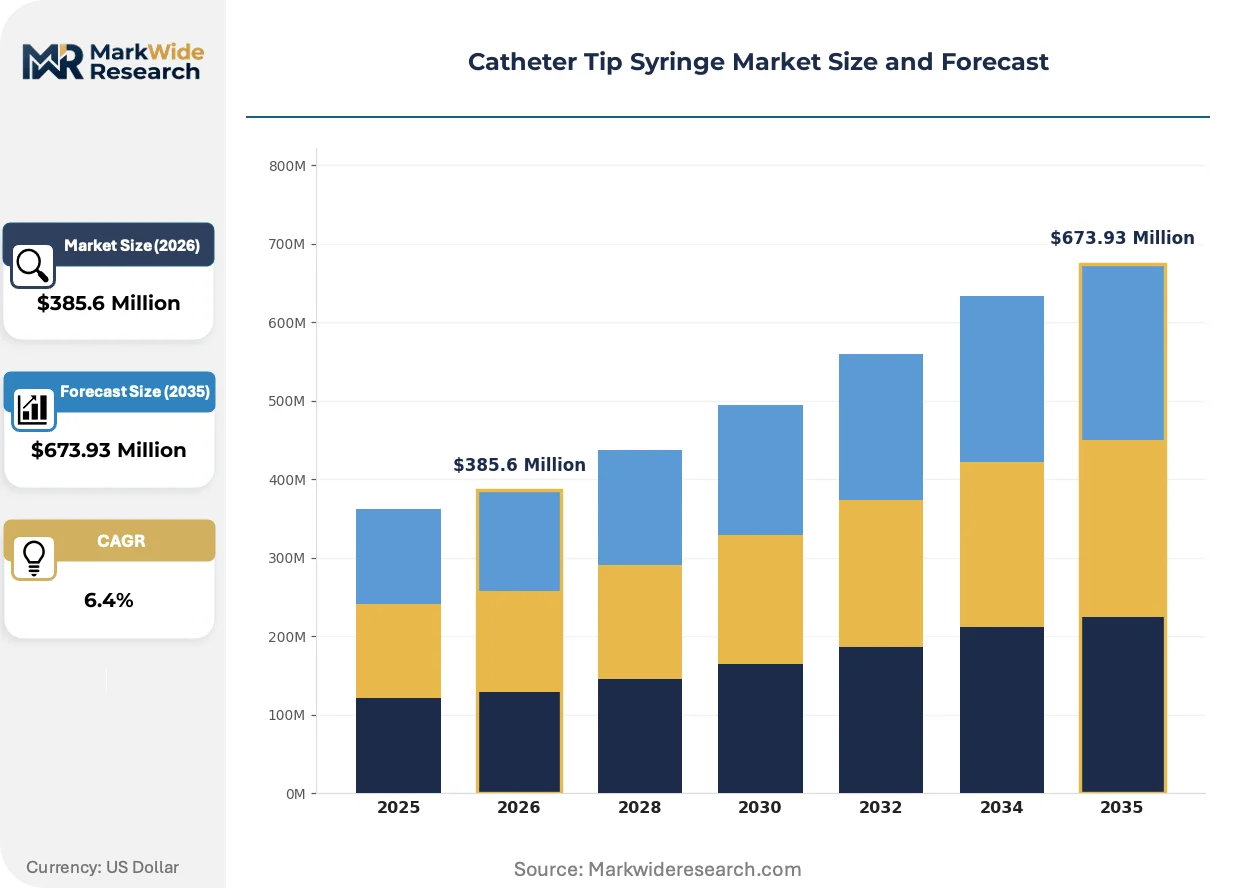
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Sterile, Non-Sterile End User: Hospitals, Clinics, Homecare, Diagnostic Centers Size: 30 ML, 50 ML, 10 ML, 20 ML Material: Plastic, Glass, Rubber, Polypropylene |
| Companies Covered | Cardinal Health, Inc., Medline Industries, Inc., Becton, Dickinson and Company, Terumo Corporation, Wessex Medical Ltd, GBUK Enteral Ltd., Medela Inc., Miktell Ltd., NeoMed, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catheter Tip Syringe Market Strategic Shifts
Material science breakthroughs and regulatory harmonization efforts are compressing product development cycles while expanding performance specifications for enteral delivery systems. Three convergent forces are restructuring competitive positioning.
Antimicrobial polypropylene additives with silver-ion or chlorhexidine integration are electrifying sterile disposable design priorities. Hospital infection control committees are mandating these formulations for high-risk enteral applications. The technology is compressing commodity pricing for standard polypropylene syringes while creating certification-driven segmentation.
The EU Medical Device Regulation's strengthened clinical evidence requirements are forcing enteral device manufacturers to rebuild technical documentation portfolios. Manufacturers with legacy CE marks under the Medical Device Directive face compressed transition timelines. The regulation is concentrating market access among firms with dedicated regulatory affairs functions and established notified body relationships.
Hospital procurement committees are consolidating enteral feeding contracts around single-source kit suppliers. Discrete syringe purchasing is giving way to bundled agreements covering extension sets, feeding bags, and medication delivery accessories. The United States acute care channel exhibits the most pronounced consolidation, with integrated delivery networks leveraging volume commitments for price positioning.
Catheter Tip Syringe Market Segmentation
Catheter tip syringe procurement patterns diverge sharply across clinical settings and material specifications. Manufacturers must align production capacity with infection control mandates in acute care while capturing homecare reimbursement economics.
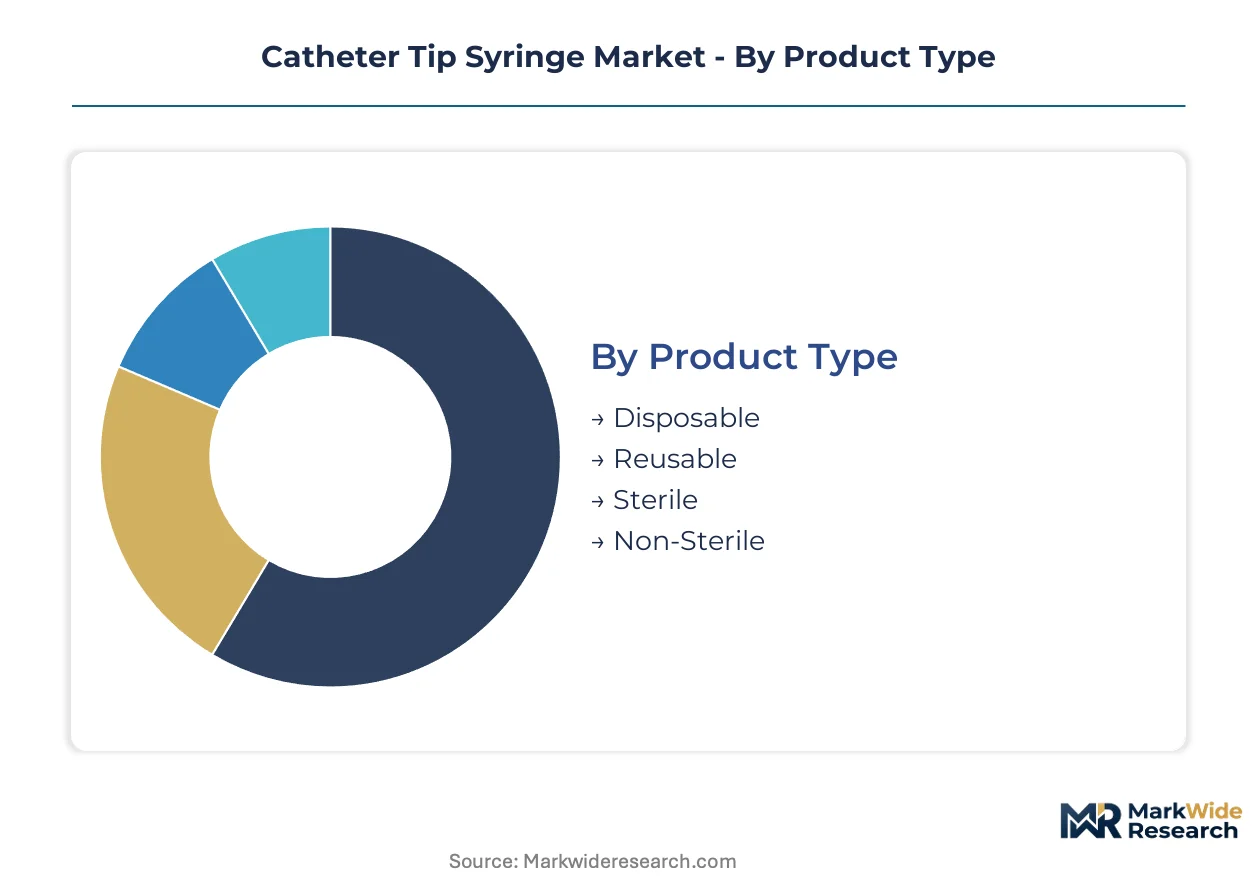
Product Type:
Replacement cycles for catheter tip syringes vary dramatically by sterility classification and institutional protocols. Hospital infection control committees drive accelerated turnover for single-use variants.
- Sterile:Gamma-irradiated or ethylene oxide-sterilized syringes dominate acute care procurement. FDA 510(k) validation requirements for sterile enteral devices sustain premium positioning in United States hospital systems.
- Disposable:Polypropylene single-use syringes capture the highest procurement volumes across Medicare-funded homecare programs. Material disposability aligns with enteral feeding infection prevention protocols.
- Reusable:Glass-barrel variants with autoclavable construction serve pharmaceutical compounding facilities. Limited demand concentrates in specialized pharmacy operations with sterilization infrastructure.
- Non-Sterile:Bulk-packaged syringes for non-enteral applications including irrigation and wound management. Price-sensitive procurement in long-term care facilities drives specification.
Sterile sits at the top of the volume ranking, with Disposable climbing the fastest.
End User:
Site-of-care economics fragment demand patterns across reimbursement structures and regulatory oversight intensity.
- Hospitals:Integrated delivery networks consolidate enteral feeding contracts around single-source kit suppliers. Infection control mandates specify sterile disposable syringes with antimicrobial additives.
- Homecare:Medicare reimbursement expansion for home enteral nutrition is displacing institutional consumption. Durable medical equipment suppliers capture recurring revenue through modular feeding kit assembly.
- Clinics:Outpatient gastroenterology practices balance cost containment with liability exposure. Intermediate sterilization protocols govern procurement specifications.
- Diagnostic Centers:Radiology and endoscopy suites require specialized syringes for contrast administration and lavage procedures. Lower volume throughput permits non-sterile alternatives.
Hospitals command the dominant revenue share, though Homecare is gaining share fastest as enteral delivery migrates beyond institutional walls.
Size:
Enteral feeding protocols and medication viscosity requirements dictate barrel capacity selection across clinical applications.
- 60 ML:Large-volume syringes for bolus feeding and flush procedures in homecare settings. Medicare reimbursement structures favor this capacity for standard enteral nutrition delivery.
- 30 ML:Mid-capacity specification balances medication precision with feeding efficiency. Hospital pharmacy compounding operations standardize on this format for unit-dose preparation.
- 10 ML:Small-volume precision for pediatric enteral applications and medication administration. Neonatal intensive care units specify this capacity for micro-dose delivery.
- 20 ML:Intermediate specification serving diagnostic lavage and irrigation procedures. Outpatient clinic procurement favors this capacity for procedural flexibility.
60 ML leads absolute unit volume, while 10 ML shows the steepest expansion trajectory from pediatric and precision-dose applications.
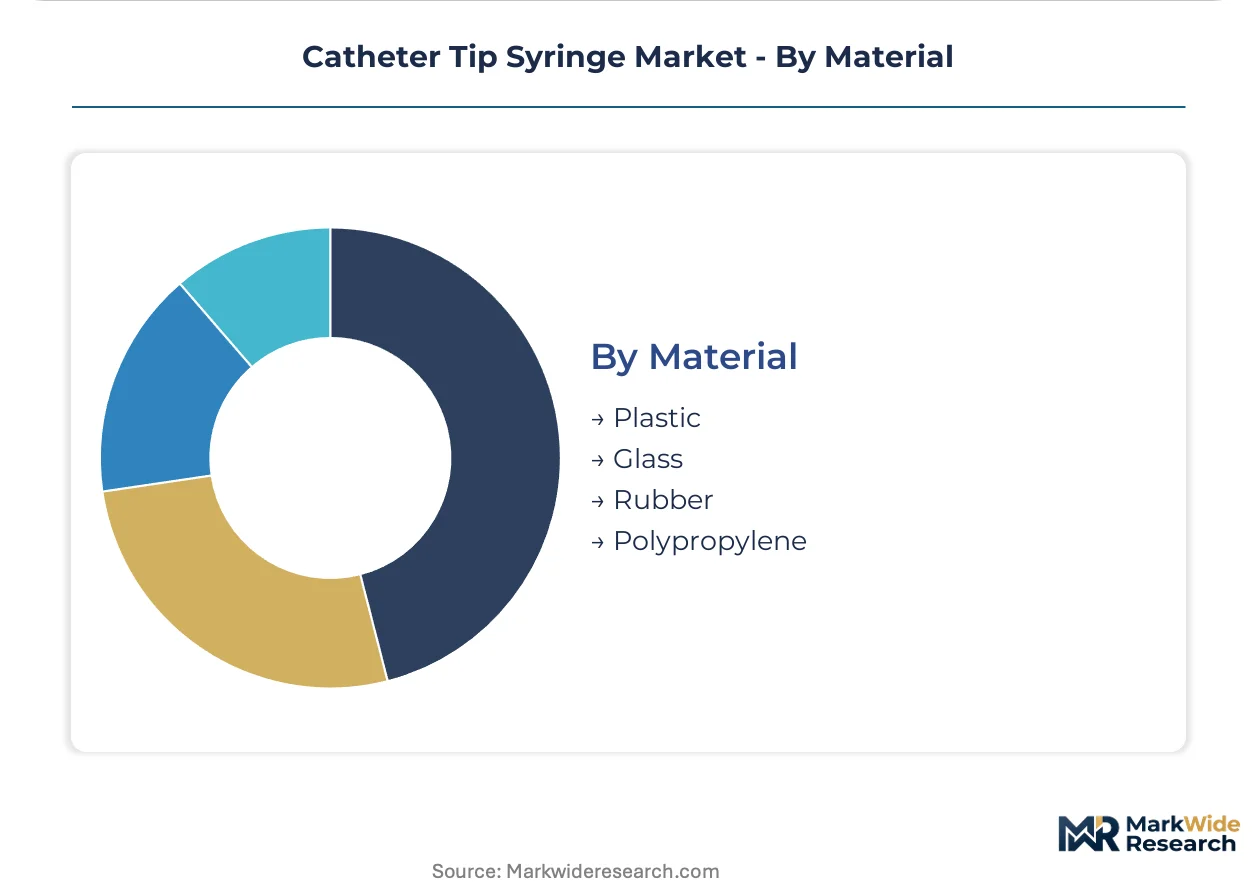
Material:
Polymer engineering investments and chemical resistance requirements are restructuring material selection hierarchies.
- Polypropylene:Dominant thermoplastic formulation offers chemical resistance and gamma sterilization compatibility. Advanced additives with silver-ion integration are displacing standard grades in high-risk enteral applications.
- Plastic:General-purpose polymer blends serve cost-sensitive diagnostic and irrigation applications. Lower specification variants compete on price in non-sterile market tiers.
- Glass:Borosilicate barrels retain niche positioning for pharmaceutical compounding and high-precision medication measurement. Autoclavable construction supports reusable protocols in specialized pharmacy operations.
- Rubber:Elastomer components including plunger tips and gaskets enable seal integrity across temperature ranges. Formulation compatibility with enteral nutrition solutions governs supplier qualification.
Polypropylene dominates manufacturing output, with Glass holding steady in compounding pharmacy niches despite polymer displacement pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catheter tip syringe manufacturing first scaled in the United States during the post-war expansion of disposable medical devices, with polymer processing expertise later diffusing to Western Europe and East Asia as enteral feeding protocols standardized across OECD healthcare systems.
United States
Medicare reimbursement for home enteral nutrition sustains the largest addressable patient population outside institutional settings. FDA 510(k) pathway revisions for enteral devices extend validation timelines while raising competitive barriers for sterile disposable portfolios. Cardinal Health and Becton, Dickinson anchor manufacturing and distribution clusters across Ohio and New Jersey, serving integrated delivery networks with consolidated contract structures.
Germany
Precision polymer engineering capabilities concentrate demand for high-performance enteral delivery systems among hospital pharmacy compounding operations. EU Medical Device Regulation strengthened clinical evidence requirements force manufacturers to rebuild technical documentation portfolios for CE marking continuity. Baden-Württemberg's medical technology corridor hosts specialized sterilization infrastructure serving Central European hospital procurement.
Japan
Aging demographics and chronic disease prevalence sustain hospital and home-based consumption of enteral feeding accessories. PMDA harmonization with ISO 7886 performance standards reduces regulatory fragmentation for polypropylene syringe manufacturers seeking multi-market access. Tokyo-Osaka industrial clusters concentrate polymer formulation expertise for gamma sterilization-compatible devices.
United Kingdom
NHS procurement consolidation drives bundled enteral feeding kit agreements displacing discrete syringe purchasing. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance obligations for manufacturers maintaining dual market access. Yorkshire and East Midlands manufacturing zones specialize in high-volume sterile disposable production for national health service contracts.
China
Domestic enteral device manufacturing scales to serve hospital modernization programs across tier-two and tier-three cities. NMPA medical device classification rules for enteral feeding systems align with international biocompatibility testing protocols. Jiangsu and Zhejiang provinces concentrate injection molding capacity for polypropylene syringe export manufacturing.
Catheter Tip Syringe Market Competitive Environment
The competitive structure tilts toward diversified health care conglomerates with captive distribution networks. Hospital infection control mandates and homecare reimbursement constraints compress margins for pure-play manufacturers lacking scale economies. Three archetypes dominate: sterile disposable specialists with validated gamma irradiation infrastructure, diversified medical device portfolios leveraging cross-selling into integrated delivery networks, and regional polymer engineering firms serving pharmaceutical compounding niches. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers reconcile FDA validation timelines with EU MDR transition deadlines.
Among diversified health care suppliers, Cardinal Health, Inc. and Becton, Dickinson and Company exemplify the scale-driven archetype with broad distribution networks sustaining hospital contract penetration. Terumo Corporation occupies a distinct position representing polymer engineering capabilities that extend product performance thresholds for high-frequency enteral delivery applications.
| Leading Market Players |
|---|
| Cardinal Health, Inc. |
| Medline Industries, Inc. |
| Becton, Dickinson and Company |
| Terumo Corporation |
| Wessex Medical Ltd |
| GBUK Enteral Ltd. |
| Medela Inc. |
| Miktell Ltd. |
| NeoMed, Inc. |
| Others |
Value Chain & Pricing Dynamics
Hospital infection control committees mandating antimicrobial polypropylene formulations are forcing manufacturers to absorb resin cost volatility rather than pass through pricing. Contracted procurement through integrated delivery networks compresses margin flexibility while elevating certification-driven tiering.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs catheter tip syringe procurement. Premium tiers command positioning through FDA 510(k) validated sterility assurance and silver-ion additive integration, while economy tiers serve non-sterile irrigation applications. Cost compression in standard polypropylene grades is intensifying because propylene feedstock volatility transmits directly from crude oil benchmarks. Homecare durable medical equipment suppliers exhibit the highest price sensitivity due to Medicare reimbursement constraints, whereas hospital pharmacy compounding operations show lowest sensitivity given liability exposure.
Supply Chain Analysis
Domestic-content mandates in China's NMPA medical device procurement rules are reshaping sourcing patterns for multinational manufacturers serving hospital modernization programs. Polypropylene resin supply concentrates in the United States, Germany, and China, with gamma sterilization infrastructure clustering in Ohio, Baden-Württemberg, and Jiangsu province. Manufacturing draws from propylene monomer, antimicrobial additive masterbatch, and ethylene oxide sterilization gas as critical inputs. Single-source vulnerability in medical-grade polymer compounding creates exposure. Distribution runs through diversified health care conglomerates with captive hospital contracting networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between FDA 510(k) validation timelines in the United States and EU MDR transition deadlines in Europe creates cost and access differentials for manufacturers with dual regulatory capabilities.
For Market Incumbents: Hedge against substitution threats from nasogastric tube pumps by deepening sterile disposable specialization and capturing homecare kit assembly revenue. Backward integration into antimicrobial additive compounding secures margin control. Capacity expansion in Zhejiang province addresses China's domestic-content procurement rules.
For New Entrants and Emerging Players: The price-point gap between premium antimicrobial syringes and economy non-sterile alternatives creates white-space for mid-tier entrants with validated ISO 13485 systems. Target Medicare-funded homecare channels in the United States where bundled kit procurement is displacing discrete syringe purchasing. Pursue notified body relationships for EU MDR CE marking as a competitive moat.
For Investors and Strategic Acquirers: Asymmetric upside sits with polymer engineering specialists possessing gamma sterilization infrastructure and existing FDA 510(k) clearances. Long-term viability hinges on regulatory affairs capabilities spanning multiple jurisdictions. Watch FDA premarket notification pathway revisions as the inflection signal for competitive barrier elevation.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Additive Integration | Silver-ion polypropylene formulations satisfy hospital infection control committee mandates for high-risk enteral applications. |
| EU MDR Technical Documentation Rebuild | Strengthened clinical evidence requirements concentrate market access among firms with dedicated regulatory affairs functions. |
| Homecare Kit Assembly Expansion | Modular packaging of syringes with extension sets captures recurring revenue from Medicare reimbursement expansion. |
| Gamma Sterilization Capacity Addition | Validated sterility assurance levels command premium positioning in hospital procurement consolidation. |
| Smart Packaging Convergence | RFID-enabled syringe barrels with enteral pump connectivity enable closed-loop medication administration workflows. |
Study Parameters
Direct dialogue with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and enteral device regulatory affairs specialists grounded qualitative insights. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare reimbursement schedules, hospital procurement contract disclosures, and ISO 7886 performance standard documentation. Bottom-up and top-down triangulation reconciled manufacturer capacity data with end-user consumption patterns.
Bottom-up modeling aggregated segment-level volume and value trajectories across sterility classification, end-user site-of-care, barrel capacity, and material formulation dimensions. Top-down cross-checks validated aggregate market scale against macro healthcare expenditure trends and enteral nutrition demographic drivers. CAGRs were derived from regression analysis of historical procurement patterns and projected reimbursement evolution across the analysis window. Forecast inputs incorporated polymer feedstock cost indices and regulatory timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for antimicrobial additive integration or smart packaging convergence would alter the outlook. Forecasts reflect assumptions around FDA 510(k) pathway stability, EU MDR transition timelines, and Medicare reimbursement continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Global Isothermal Boxes for Vaccines Market
Medical Supplies
Transfusion Bottles Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
United States Intravenous Solutions Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Medical Swabs Market
Medical Supplies
Global Hospital Linen Supply and Management Services Market
Medical Supplies
Ampoules and Syringes Market
Medical Supplies
Menthol Patches Market
Medical Supplies
Tattoo Needles Market
Medical Supplies
Hospital Gowns Market