
 Laser Aesthetic Devices Market | 2026-2036
Laser Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Aesthetic Devices Market Outlook
Semiconductor diode arrays are expanding their share against flashlamp-pumped systems across cost-sensitive clinic tiers. Alma Lasers leverages in-house crystal fabrication to sustain margin structure in Alexandrite platforms. Cynosure anchors its position through geographic density in North American dermatology networks, while Lumenis competes on technology leadership in fractional CO2 modalities.
Laser aesthetic devices are medical-grade systems that generate coherent light at specific wavelengths, fluences, and pulse durations to selectively target chromophores in skin tissue for therapeutic or cosmetic effect; most platforms integrate active cooling mechanisms to protect epidermal layers while delivering energy to dermal or follicular structures. These systems serve primary commercial purposes in non-invasive and minimally invasive procedures where precision ablation, photothermolysis, or selective photocoagulation replaces surgical intervention. Laser hair removal occupies the largest volume pool among product categories, though skin resurfacing commands premium pricing due to higher capital equipment thresholds and consumable attachment economics. Nd:YAG technology leads in darker skin type applications where melanin absorption risks constrain shorter-wavelength alternatives, while diode platforms dominate in high-throughput clinic settings seeking shorter treatment intervals.
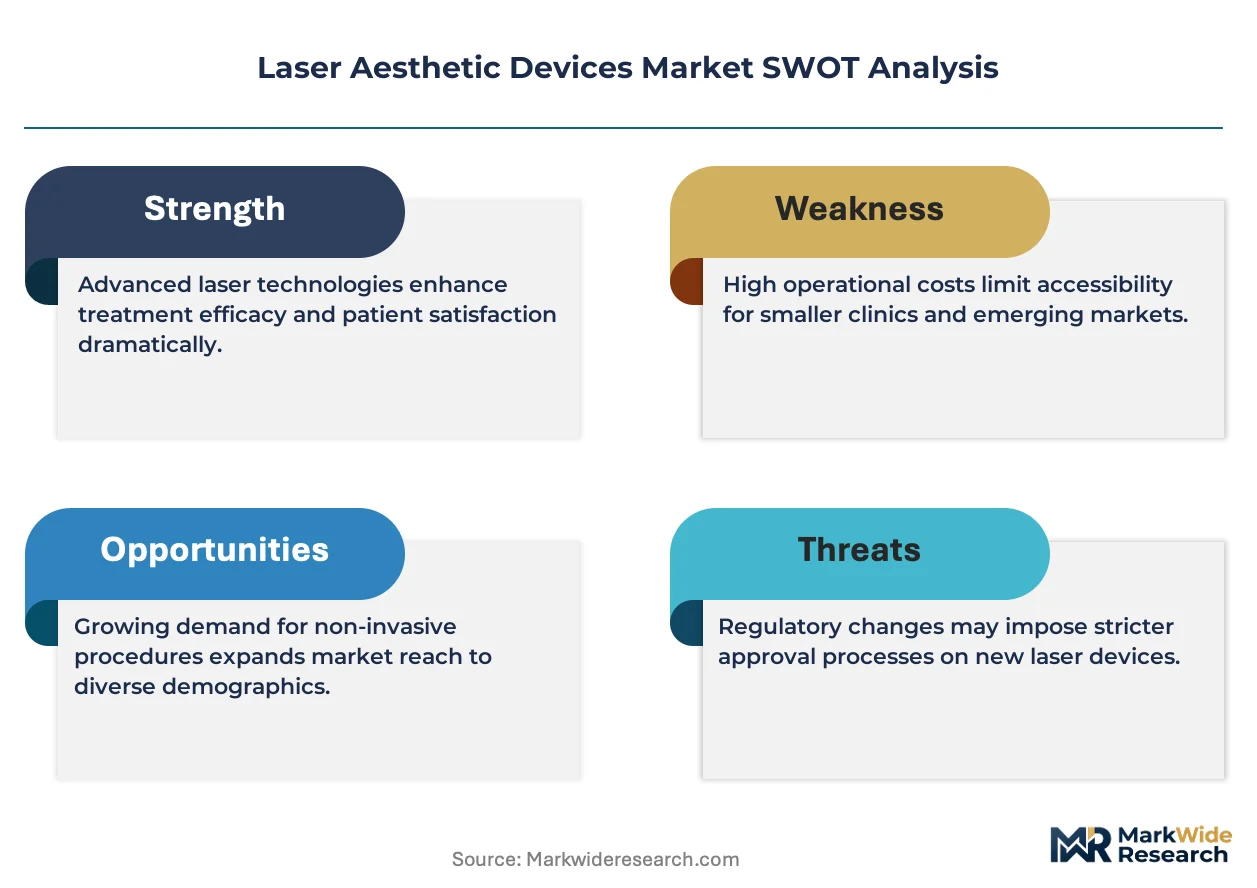
FDA 510(k) clearance requirements shape product development timelines and indication breadth for devices entering the United States, with substantial equivalence demonstrations consuming significant pre-market resources. The EU Medical Device Regulation imposes stricter clinical evidence standards and post-market surveillance obligations on manufacturers distributing in Europe, elevating compliance costs for smaller platform developers. Stakeholders must monitor how evolving home-use regulatory categories in major markets reshape channel economics and service revenue models.
Market Dynamics
Semiconductor diode arrays are compressing capital costs across mid-tier dermatology clinics, forcing flashlamp-pumped system manufacturers to defend installed base through service contract bundling and consumable lock-in strategies.
Growth Catalysts
- FDA 510(k) pathway compression:Substantial equivalence demonstrations for diode and Nd:YAG platforms now require fewer predicate comparisons, accelerating clearance timelines for multi-wavelength systems targeting expanded indications.
- China's clinic-grade procurement surge:Domestic manufacturers in NMPA-regulated zones are capturing share in skin resurfacing and hair removal through localized production and reduced import duty exposure.
- Melanin-safe wavelength expansion:Long-pulse Nd:YAG technology at 1064 nm enables safe treatment of Fitzpatrick skin types IV-VI, opening addressable patient populations previously excluded from laser hair removal protocols.
Market Restraints
- Flashlamp crystal supply concentration:Synthetic sapphire and alexandrite rod production clusters in limited geographies, exposing manufacturers to input cost volatility and single-source dependency.
- EU MDR clinical evidence escalation:Stricter post-market surveillance obligations elevate compliance expenditures for fractional CO2 and ablative platform developers, disadvantaging smaller entrants.
- Home-use IPL substitution:Lower-cost intense pulsed light devices for consumer channels capture routine hair removal volume, pressuring clinic throughput for maintenance treatments.
Strategic Opportunities
- India's dermatology network expansion:Tier-2 and Tier-3 cities underpenetrated by clinic-grade systems present first-mover advantages for diode platforms with localized service infrastructure.
- Combination therapy protocols:Convergence of fractional radiofrequency with non-ablative laser wavelengths creates premium positioning for practices seeking differentiated acne scar and skin tightening offerings.
- IRA aesthetic procedure tax incentives:United States-based medical spa structures may benefit from evolving deductibility frameworks for physician-supervised laser treatments.
Industry Challenges
- Laser safety officer certification scarcity:Qualified medical physicists and certified laser operators remain concentrated in metropolitan dermatology hubs, constraining clinic expansion into secondary markets.
- Multi-platform integration complexity:Legacy EMR and practice management systems require costly middleware development to accommodate real-time treatment logging from connected laser devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Aesthetic Devices Market |
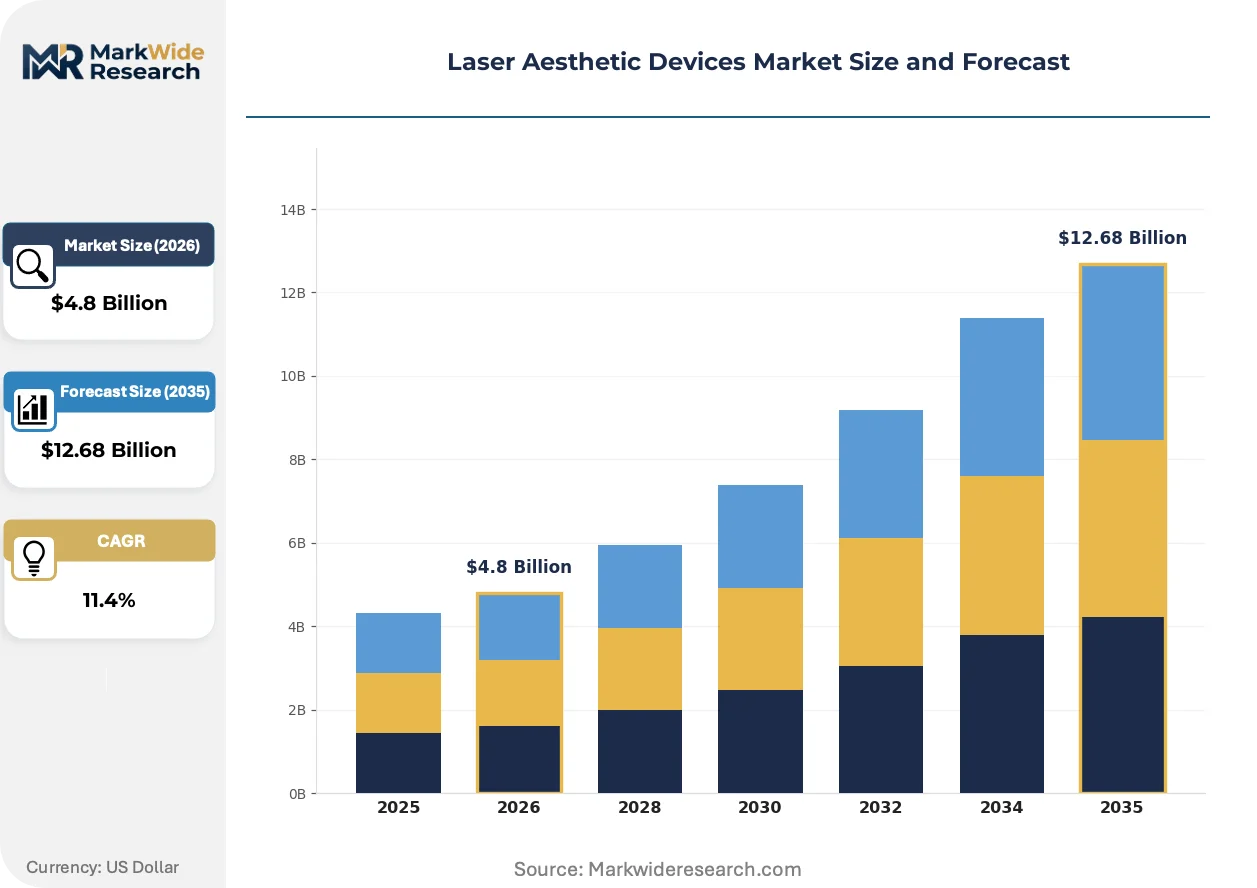
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Hair Removal, Skin Resurfacing, Tattoo Removal, Wrinkle Reduction Technology: Alexandrite Laser, Diode Laser, Nd:YAG Laser, CO2 Laser End User: Clinics, Dermatology Centers, Beauty Salons, Home Users Application: Medical Aesthetics, Cosmetic Procedures, Skin Rejuvenation, Body Contouring |
| Companies Covered | Cynosure, Lumenis, Candela Medical, Cutera, Alma Lasers, Sciton, Solta Medical, Lutronic, Venus Concept, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Aesthetic Devices Market Strategic Shifts
Active cooling mechanisms and real-time skin temperature monitoring are becoming standard specifications rather than premium differentiators, compressing margins for manufacturers lacking proprietary thermal management intellectual property.
Picosecond pulse duration technology is integrating into mainstream tattoo removal and pigmented lesion platforms, delivering photomechanical disruption at lower fluences than nanosecond alternatives. United States dermatology networks are adopting these systems at accelerated replacement cycles to capture melanoma screening adjacencies. The structural consequence is compressing residual value for Q-switched Nd:YAG inventories while elevating training and certification requirements for operators.
EU Medical Device Regulation post-market surveillance mandates are forcing manufacturers to maintain clinical follow-up registries for ablative fractional devices, increasing ongoing compliance labor. European notified bodies are prioritizing technical documentation reviews for systems with novel wavelength combinations or automated skin type detection algorithms. German and French dermatology associations are responding by consolidating procurement through group purchasing organizations to amortize elevated device costs across hospital networks.
Subscription-based equipment access models are displacing traditional capital purchase structures in United States medical spa channels, with vendors retaining ownership and bundling maintenance, training, and consumable supply. This reconfiguration transfers balance sheet risk to manufacturers while capturing recurring revenue streams. The shift is most visible in high-turnover hair removal segments where treatment interval compression demands continuous uptime guarantees.
Laser Aesthetic Devices Market Segmentation
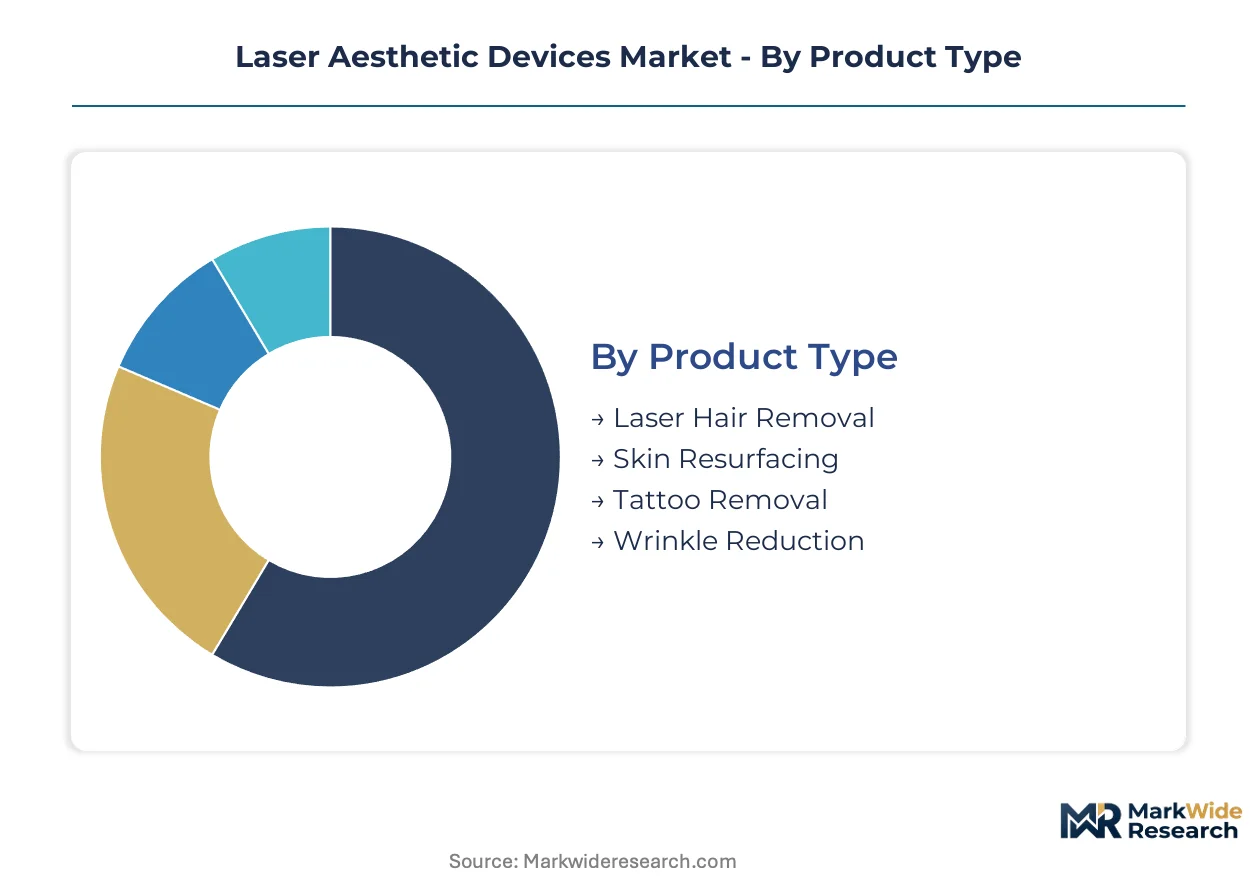
Segmentation in laser aesthetic devices reveals divergent margin structures and procurement patterns across therapeutic applications and technology platforms. Device manufacturers configure wavelength specifications, cooling systems, and handpiece attachments to match the procedural volume and capital intensity of distinct customer tiers.
Product Type:
Standalone systems dominate high-volume clinic deployments, while combination platforms embed multiple modalities for space-constrained dermatology suites.
- Laser Hair Removal:Diode and alexandrite wavelengths at 755-1064 nm target melanin in hair follicles through selective photothermolysis. United States dermatology centers deploy these systems in dedicated treatment rooms with high patient throughput. Diode platforms are compressing per-treatment costs through faster pulse repetition rates.
- Skin Resurfacing:Ablative and non-ablative fractional lasers deliver controlled thermal injury to stimulate collagen remodeling. Premium pricing reflects higher capital thresholds and consumable attachment economics. United States medical spas prioritize CO2 fractional systems for wrinkle and scar protocols.
- Tattoo Removal:Q-switched and picosecond Nd:YAG platforms fragment ink particles through photomechanical disruption.
- Wrinkle Reduction:Non-ablative laser and hybrid radiofrequency-laser systems target dermal collagen contraction.
Laser hair removal leads volumes today; skin resurfacing is gaining share fastest through premium positioning in medical spa channels.
Technology:
Cost tier stratification separates premium crystal-based platforms from semiconductor diode arrays in mid-market clinic procurement.
- Diode Laser:Semiconductor arrays at 800-810 nm offer compact footprints and reduced cooling requirements compared to solid-state alternatives. China's domestic manufacturers are capturing clinic-grade procurement through localized production and NMPA pathway efficiency. Diode platforms dominate high-throughput settings seeking shorter treatment intervals.
- Nd:YAG Laser:Neodymium-doped yttrium aluminum garnet crystals emit at 1064 nm with long-pulse capability for darker skin types. United States dermatology networks specify these systems for Fitzpatrick type IV-VI patient populations previously excluded from laser protocols. Melanin-safe wavelength expansion is opening addressable demographics.
- Alexandrite Laser:Chromium-doped chrysoberyl rods deliver 755 nm pulses with high melanin absorption for lighter skin types.
- CO2 Laser:Gas discharge systems at 10,600 nm provide ablative tissue removal for resurfacing applications.
Diode platforms lead volumes today; Nd:YAG systems are expanding most quickly through melanin-safe indication breadth.
End User:
Customer type determines service contract structures, with institutional buyers demanding uptime guarantees and training bundling.
- Clinics:Multi-specialty aesthetic practices prioritize platform versatility across hair removal, vascular lesion, and skin rejuvenation protocols. United States clinic networks negotiate group purchasing arrangements for diode and Nd:YAG systems. Subscription-based equipment access models are displacing traditional capital purchases in this tier.
- Dermatology Centers:Physician-supervised facilities require FDA 510(k) cleared devices with documented clinical evidence for medical indications. These centers specify fractional CO2 and picosecond platforms for scar and pigmented lesion protocols. German and French dermatology associations are consolidating procurement through hospital network purchasing organizations.
- Beauty Salons:Non-medical aesthetic venues operate under lighter regulatory frameworks with lower-wattage systems.
- Home Users:Consumer channels absorb lower-cost IPL and diode devices for routine hair removal maintenance.
Clinics lead volumes today; dermatology centers are climbing the fastest through premium technology adoption.
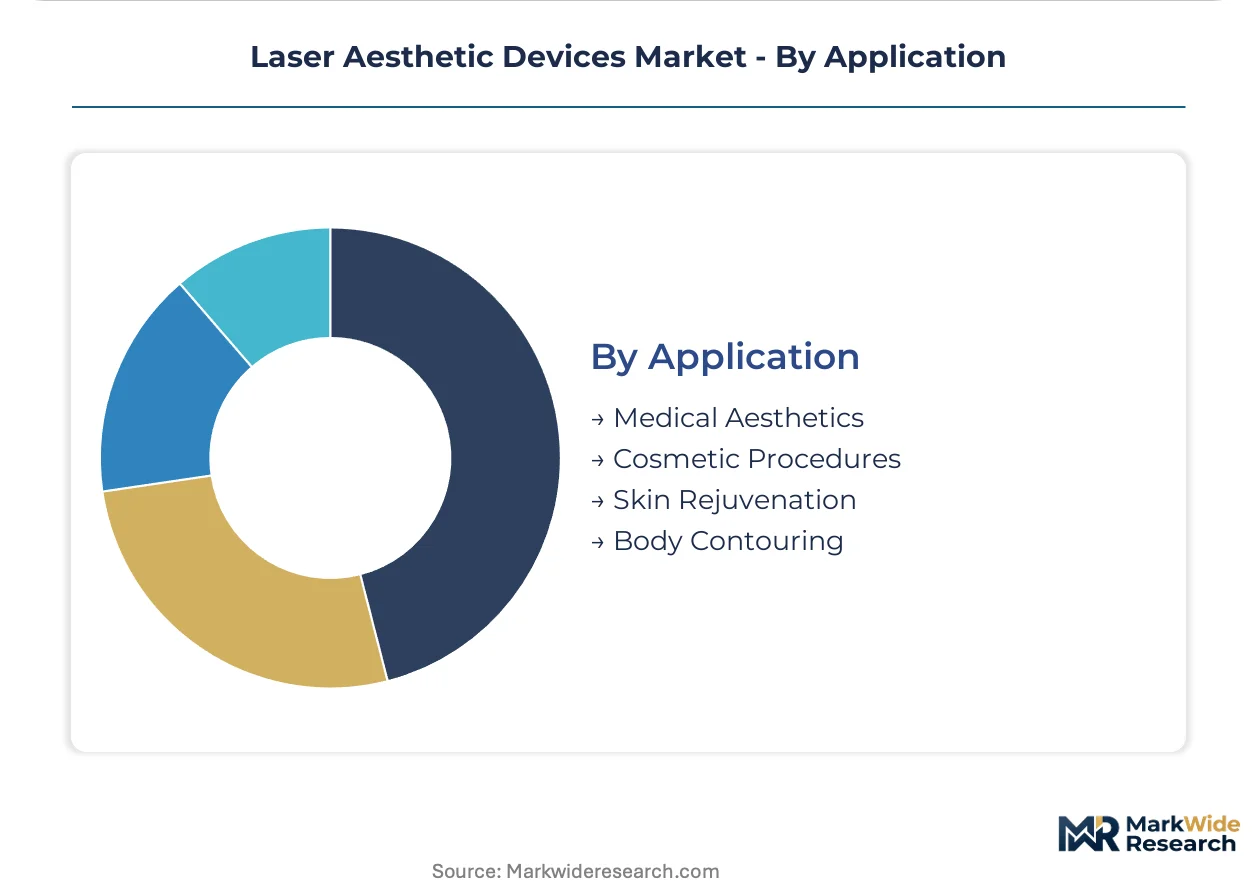
Application:
Application scope separates reimbursable medical procedures from elective cosmetic services with distinct pricing and regulatory pathways.
- Cosmetic Procedures:Elective aesthetic treatments including laser hair removal, non-ablative skin tightening, and body contouring generate recurring revenue through maintenance protocols. United States medical spa channels are expanding diode laser deployment for cosmetic hair removal. Home-use IPL substitution is pressuring clinic throughput in this segment.
- Medical Aesthetics:Physician-supervised treatments for scar revision, vascular lesions, and post-surgical recovery carry higher regulatory scrutiny and documentation requirements. United States dermatology networks are adopting picosecond platforms at accelerated replacement cycles for melanoma screening adjacencies.
- Skin Rejuvenation:Collagen stimulation and photodamage repair procedures span both medical and cosmetic regulatory categories.
- Body Contouring:Laser-assisted fat reduction and skin tightening applications integrate with cryolipolysis and radiofrequency modalities.
Cosmetic procedures lead volumes today; medical aesthetics is expanding most quickly through clinical evidence requirements and reimbursement evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States dermatology networks concentrate the highest-value procurement for multi-platform laser systems, with FDA 510(k) clearance pathways compressing commercialization timelines for diode and Nd:YAG manufacturers.
United States
Medical spa channels in California and Florida drive subscription-based equipment access models for high-throughput hair removal. FDA maintains streamlined substantial equivalence reviews for multi-wavelength platforms. Dallas and Miami metropolitan clusters host dense concentrations of dermatology networks consolidating procurement through group purchasing organizations.
Germany
Hospital network purchasing organizations in Bavaria and North Rhine-Westphalia amortize elevated device costs across dermatology departments. EU MDR post-market surveillance obligations elevate compliance expenditures for fractional CO2 platform developers. Berlin-Brandenburg hosts notified bodies prioritizing technical documentation reviews for automated skin type detection algorithms.
China
Domestic manufacturers capture clinic-grade procurement in skin resurfacing through NMPA pathway efficiency and reduced import duty exposure. The country's national medical products regulator accelerates reviews for locally produced diode arrays. Yangtze River Delta manufacturing clusters concentrate synthetic sapphire rod production for solid-state laser platforms.
India
Tier-2 and Tier-3 cities present first-mover advantages for diode platforms with localized service infrastructure. CDSCO regulates medical device imports with escalating clinical evidence requirements for laser platforms. Maharashtra and Karnataka host emerging dermatology network expansions targeting underpenetrated aesthetic procedure markets.
Brazil
Physician-supervised medical spa structures in São Paulo and Rio de Janeiro absorb premium fractional CO2 and picosecond platforms. ANVISA imposes stringent registration requirements for imported laser devices, favoring established manufacturers with regulatory infrastructure. Southeast regional clusters concentrate qualified laser safety officer certification programs.
Laser Aesthetic Devices Market Competitive Environment
Technology licensing dominates the current landscape as manufacturers seek proprietary thermal management intellectual property without captive crystal fabrication investments. The vendor base stratifies across three tiers: premium integrated platform developers, mid-market diode specialists, and regional service-anchored distributors. Two strategic archetypes define positioning—vertically integrated crystal fabricators defending margin structures, and asset-light assemblers leveraging semiconductor supply chain commoditization. Portfolio diversification and geographic density in dermatology networks constitute the dominant competitive moves.
Within the premium integrated tier, Alma Lasers and Lumenis occupy positions exemplifying divergent technology leadership strategies—Alma through in-house crystal fabrication capabilities, Lumenis through fractional CO2 modality specialization. Cynosure anchors the geographic density archetype with concentrated presence in North American dermatology networks. These three entities represent the competitive spectrum from manufacturing integration to channel control, with each archetype responding differently to semiconductor diode array cost compression and FDA pathway acceleration.
| Leading Market Players |
|---|
| Cynosure |
| Lumenis |
| Candela Medical |
| Cutera |
| Alma Lasers |
| Sciton |
| Solta Medical |
| Lutronic |
| Venus Concept |
| Others |
Value Chain & Pricing Dynamics
Clinic subscription models for diode laser platforms are displacing capital purchases across United States medical spa networks, forcing manufacturers to absorb balance sheet risk while capturing recurring revenue through bundled service contracts and consumable supply arrangements.
Pricing Analysis
Input-cost pass-through from synthetic sapphire and alexandrite rod volatility feeds directly into premium platform pricing, with in-house crystal fabricators like Alma Lasers insulating margin structures against flashlamp crystal supply shocks. Three-tier pricing structure across premium, standard, and economy levels separates fractional CO2 systems with real-time temperature monitoring from diode arrays with passive cooling. Cost compression in mid-tier diode platforms is intensifying because Chinese domestic manufacturers exploit NMPA pathway efficiency and reduced import duty exposure. High-throughput clinic networks exhibit greatest price sensitivity, while dermatology centers purchasing through hospital network GPOs prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke patterns for laser aesthetic device fulfillment, with Yangtze River Delta clusters concentrating synthetic sapphire rod production for solid-state platforms. Manufacturing draws from neodymium-doped yttrium aluminum garnet crystals, semiconductor diode arrays, and chromium-doped chrysoberyl rods as core inputs. Single-source vulnerability in flashlamp crystal production exposes manufacturers to geopolitical disruption and input cost spikes. Distribution runs through direct sales forces for institutional dermatology networks, supplemented by regional service-anchored distributors for mid-tier clinic penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FDA 510(k) pathway compression in the United States contrasts with EU MDR clinical evidence escalation, creating divergent compliance cost structures that favor capital-light assemblers in North America and integrated platform developers in Europe.
For Market Incumbents: Extend service contract bundling and consumable lock-in strategies to defend installed base against semiconductor diode array cost compression. Deepen backward integration into crystal fabrication or captive supply of synthetic sapphire rods to mitigate flashlamp supply concentration risks. Fortify geographic density in North American dermatology networks before Chinese domestic manufacturers achieve NMPA pathway scale for export markets. For New Entrants and Emerging Players: Launch via subscription-based equipment access models targeting India's Tier-2 and Tier-3 cities where qualified laser safety officer scarcity constrains incumbent expansion. Penetrate melanin-safe wavelength segments with localized Nd:YAG service infrastructure. Exploit underpenetrated diode platform demand in Maharashtra and Karnataka dermatology networks through partnership with emerging clinic chains. For Investors and Strategic Acquirers: Asymmetric upside sits with asset-light assemblers leveraging semiconductor supply chain commoditization rather than vertically integrated crystal fabricators facing capital intensity headwinds. Long-term viability across the projection horizon favors manufacturers with proprietary thermal management intellectual property and automated skin type detection algorithms. Watch NMPA export pathway acceleration for Chinese domestic manufacturers as inflection indicator for global pricing pressure.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Substantial equivalence compression accelerates multi-wavelength platform commercialization timelines for diode and Nd:YAG systems. |
| In-House Crystal Fabrication | Captive synthetic sapphire and alexandrite rod production insulates margin structures against flashlamp input cost volatility. |
| Subscription Equipment Access | Recurring revenue models transfer balance sheet risk to manufacturers while capturing medical spa channel loyalty. |
| Localized Service Infrastructure | India's Tier-2 and Tier-3 city penetration demands qualified laser safety officer training programs and maintenance networks. |
| Picosecond Platform Integration | Photomechanical disruption technology at lower fluences compresses residual value for Q-switched Nd:YAG inventories. |
Study Parameters
Multiple input streams — primary interviews with dermatology network procurement directors, biomedical engineers, GPO contracts managers, and laser safety officers; secondary validation through FDA 510(k) filings, NMPA registration databases, EU MDR notified body technical documentation, and hospital procurement records — were reconciled through bottom-up and top-down triangulation.
Historical shipment data cross-referenced against expert panel input shaped the analytical framework across the analysis window, with segmentation dimensions spanning product type, technology platform, end-user tier, and application scope. CAGRs were derived from procedure volume elasticity, replacement cycle compression, and geographic adoption curve modeling.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR post-market surveillance mandate escalation or NMPA export pathway liberalization for Chinese domestic manufacturers. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Cervical Implants Market
Medical Devices
Global Wearable Pregnancy Devices Market
Medical Devices
Digital Magnifiers Market
Medical Devices
Supraglottic Airway Devices Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
US Wearable Medical Devices Market
Medical Devices
Veterinary Ventilators Market
Medical Devices
Disposable Lancets Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
Cochlear Implant Systems Market
Medical Devices
Wearable Cardioverter Defibrillators Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Europe C-Arms Market
Medical Devices
United States Minimally Invasive Surgery Device Market
Medical Devices
Global Syringe Pumps Market