
 Global Retinoscopes Market | 2026-2036
Global Retinoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Retinoscopes Market Foresight
Equipment leasing and pay-per-use financing is fragmenting the competitive landscape for retinoscope procurement. Welch Allyn leverages its established hospital contracting networks to sustain installed-base loyalty across North American eye clinics. HEINE Optotechnik GmbH & Co. KG anchors premium manual instrument demand through optical precision manufacturing in Germany. Keeler Ltd. competes on compact portable designs that dominate mobile screening programs in the United Kingdom and Commonwealth markets.
A retinoscope is a handheld diagnostic instrument that projects a light beam through the patient's pupil to assess refractive error by observing the movement of the retinal reflection; modern units employ LED sources delivering 5700K color temperature with adjustable beam divergence from 1.5 to 3.5 degrees for precise streak or spot projection. Pediatric eye exams command the largest volume share as school-based vision screening mandates proliferate across national health systems. LED retinoscopes represent the fastest-expanding product category as mercury-containing halogen bulb restrictions tighten under REACH and RoHS frameworks. Wireless connectivity technology remains nascent but captures disproportionate R&D investment from manufacturers seeking differentiation in training institution sales.
FDA 510(k) clearance requirements govern commercial entry for automated retinoscope systems in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence standards for digital imaging variants seeking CE marking. India's CDSCO enforces BIS electrical safety certification for imported ophthalmic diagnostic equipment, creating compliance layering for multinational suppliers. Stakeholders must monitor evolving reimbursement codes for automated refraction in public health systems, as coverage decisions will determine capital allocation between manual and technology-enhanced retinoscope platforms.
Market Dynamics
LED illumination technology is rendering obsolete halogen-based retinoscope architectures across diagnostic equipment portfolios, forcing manufacturers to reconfigure supply chains around semiconductor light sources and mercury-free compliance frameworks.
Growth Catalysts
- School-based vision screening mandates:National health systems in India and China now require annual pediatric eye examinations, creating institutional procurement pipelines for handheld diagnostic instruments.
- REACH and RoHS mercury restrictions:European chemical safety frameworks are accelerating the phase-out of halogen bulb-containing devices across ophthalmology practices.
- Mobile screening program expansion:Compact portable retinoscope designs dominate community health outreach initiatives in Commonwealth markets, driving volume demand for battery-operated units.
Market Restraints
- Optical component supply concentration:Precision lens grinding capabilities concentrate in German and Japanese manufacturing clusters, creating single-source dependencies for high-accuracy instruments.
- FDA 510(k) clearance timelines:Automated retinoscope systems face extended premarket notification review periods, delaying commercial entry for digital imaging variants in the United States.
- Smartphone-based refraction apps:Consumer-grade diagnostic software threatens low-end manual retinoscope segments in price-sensitive markets.
Strategic Opportunities
- Tier-one hospital ophthalmology departments in China:National vision health program expansion creates capital equipment procurement windows for premium diagnostic platforms.
- Wireless connectivity integration:Bluetooth-enabled retinoscopes enable real-time data transmission to electronic health record systems, capturing disproportionate R&D investment from manufacturers targeting training institutions.
- Equipment leasing and pay-per-use financing:Alternative procurement models fragment traditional capital purchase patterns, opening access for smaller clinics and mobile screening operators.
Industry Challenges
- Skilled refractionist shortage:Manual retinoscope operation requires specialized training that outpaces workforce development in rural screening programs.
- CE marking clinical evidence requirements:The EU Medical Device Regulation demands strengthened documentation for digital imaging variants, compressing certification timelines for innovative products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Retinoscopes Market |
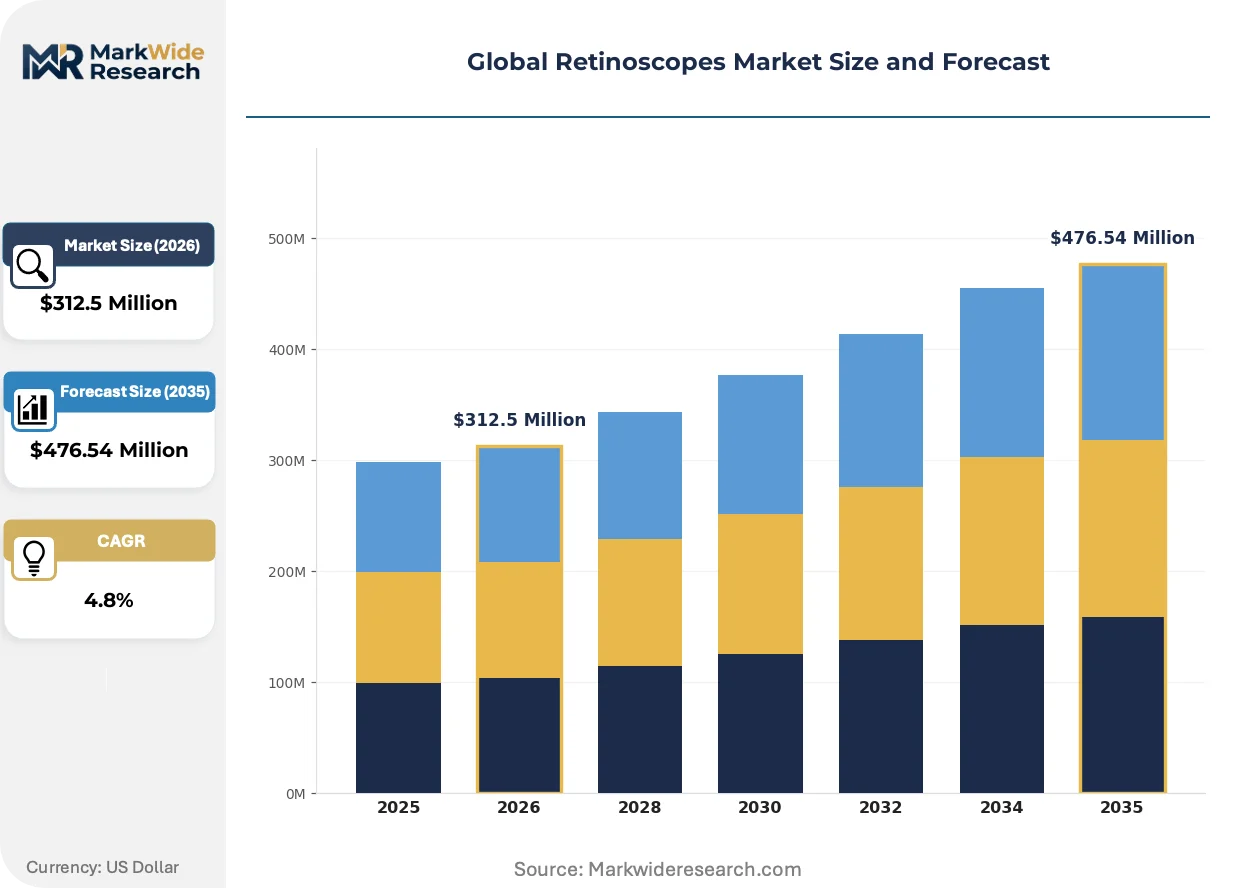
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Streak Retinoscopes, Spot Retinoscopes, LED Retinoscopes, Desktop Retinoscopes Application: Pediatric Eye Exams, Refractive Assessment, Low Vision Screening, Binocular Vision Testing End User: Eye Clinics, Optical Centers, Research Laboratories, Training Institutions Technology: Manual, Automated, Digital Imaging, Wireless Connectivity |
| Companies Covered | Welch Allyn, HEINE Optotechnik GmbH & Co. KG, Keeler Ltd., Zumax Medical Co., Ltd., US Ophthalmic, NEITZ INSTRUMENTS Co., Ltd., Rudolf Riester GmbH, Unitech Vision, Suzhou Kangjie Medical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Retinoscopes Market Shifts & Advancements
Diagnostic instrument architecture is pivoting toward semiconductor-based illumination and connected data workflows, compressing product lifecycles for legacy optical platforms while opening new service revenue streams.
LED-based retinoscope systems delivering 5700K color temperature with adjustable beam divergence from 1.5 to 3.5 degrees are rendering obsolete halogen bulb architectures across hospital ophthalmology departments and pediatric clinics. European and North American diagnostic equipment purchasers are completing fleet replacements ahead of regulatory deadlines. This transition is compressing aftermarket service revenues for bulb-based platforms while shifting manufacturer margins toward solid-state component supply chains.
The EU Medical Device Regulation imposes strengthened clinical evidence standards for digital imaging variants seeking CE marking, forcing manufacturers to expand post-market surveillance infrastructure. Automated retinoscope systems now require documented performance validation across diverse patient populations. Digital imaging retinoscope platforms face the most acute compliance burden, with notified bodies demanding expanded technical documentation for software-enabled diagnostic functions.
Pay-per-use financing and equipment leasing arrangements are displacing traditional capital purchase contracts in North American eye clinics and United Kingdom screening programs. Hospital procurement departments now prioritize operational expenditure flexibility over asset ownership. This shift concentrates vendor selection power within hospital contracting networks and rewards suppliers with established service infrastructure.
Global Retinoscopes Market Segmentation
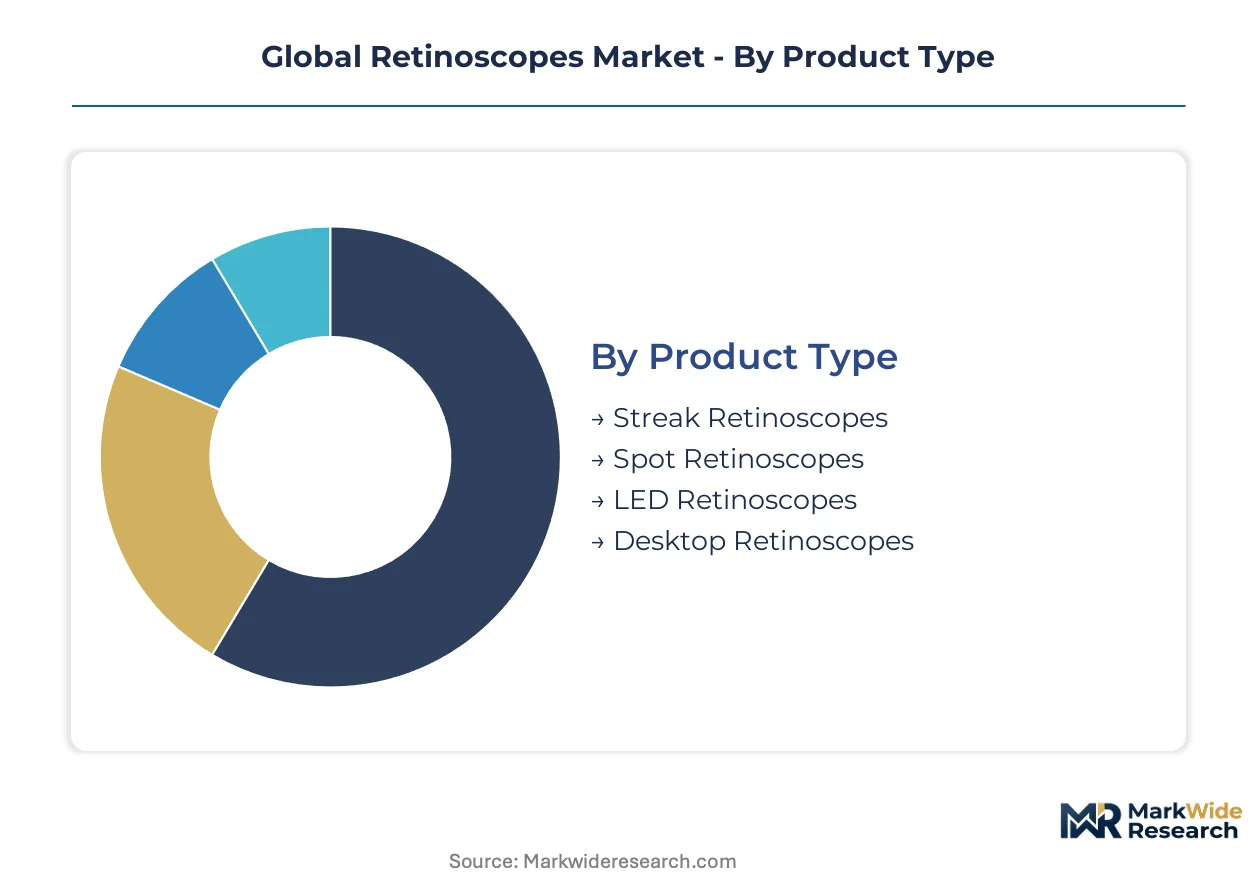
Retinoscope procurement patterns diverge sharply across clinical settings, with pediatric screening mandates and mercury-free compliance frameworks reshaping product mix priorities. Technology migration from halogen to LED and manual to connected platforms fragments vendor strategies across price-performance tiers.
Product Type:
Mature halogen architectures coexist with emerging solid-state designs as regulatory deadlines force fleet turnover decisions.
- Streak Retinoscopes:These instruments project a linear light beam that enables rapid assessment of astigmatism axis and power through observation of retinal reflex movement. Demand concentrates in India's pediatric eye clinics where school-based screening mandates require high-throughput refraction capabilities. The streak configuration dominates volume procurement for mobile screening programs.
- LED Retinoscopes:Semiconductor illumination delivering 5700K color temperature eliminates mercury-containing bulbs while reducing heat generation and extending operational lifespan. China's tier-one hospital ophthalmology departments prioritize these units as national vision health programs expand procurement budgets for modernized diagnostic fleets.
- Spot Retinoscopes:Circular beam projection suits spherical refraction assessment in optical centers across Germany and Japan.
- Desktop Retinoscopes:Fixed-mount designs serve research laboratories requiring precise positioning stability for longitudinal studies.
LED Retinoscopes handle the majority of throughput in replacement cycles; LED Retinoscopes are expanding most quickly on share as REACH and RoHS deadlines approach.
Application:
Volume distribution tracks national screening program mandates rather than disease prevalence alone.
- Pediatric Eye Exams:Annual vision screening requirements in Indian and Chinese school systems generate institutional procurement pipelines for handheld diagnostic instruments. These programs command the largest volume share as ministries of health integrate refraction services into primary care infrastructure.
- Refractive Assessment:Optical centers in the United Kingdom and Commonwealth markets deploy compact portable units for community outreach. The segment climbs fastest as pay-per-use financing opens access for independent practitioners.
- Low Vision Screening:Geriatric populations in Japan drive specialized protocol adoption for age-related macular degeneration monitoring.
- Binocular Vision Testing:Training institutions in Germany require precise accommodation measurement capabilities for orthoptic certification programs.
Pediatric Eye Exams anchor installed-base volume; Refractive Assessment gains share fastest through equipment leasing proliferation.
End User:
Procurement authority concentrates in hospital contracting networks while alternative financing fragments traditional purchasing patterns.
- Eye Clinics:North American outpatient facilities prioritize operational expenditure flexibility through pay-per-use arrangements over capital asset ownership. Welch Allyn's established contracting networks sustain loyalty across these accounts.
- Training Institutions:Wireless connectivity integration captures disproportionate R&D investment as manufacturers target educational sales with Bluetooth-enabled data transmission to electronic health record systems.
- Optical Centers:India's urban markets adopt battery-operated portable designs for storefront refraction services.
- Research Laboratories:Precision manufacturing from German optical clusters supplies validation-grade instrumentation for clinical trial endpoints.
Eye Clinics manage the highest absolute unit throughput; Training Institutions show the steepest expansion trajectory as curriculum modernization accelerates.
Technology:
Capability layering creates distinct compliance burdens and margin structures across the architecture spectrum.
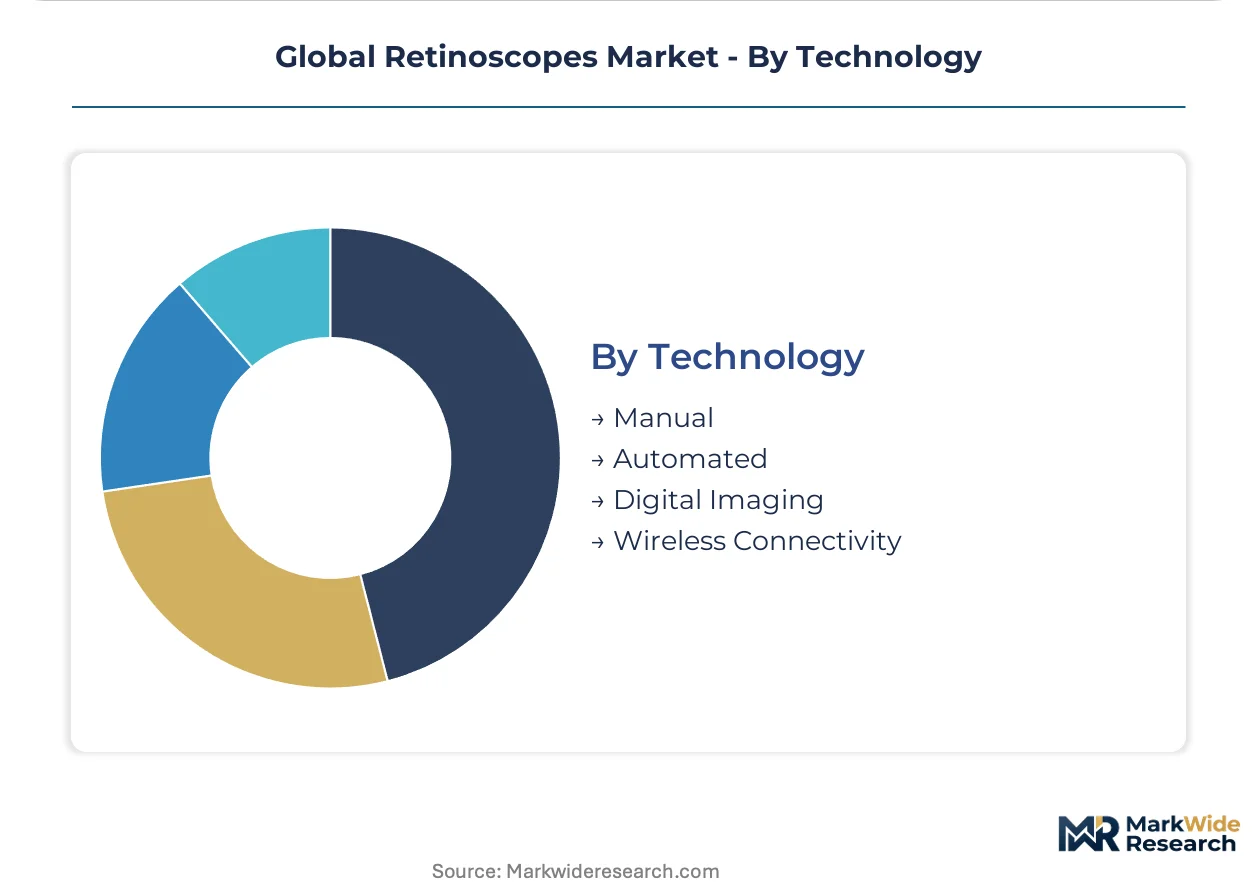
- Manual:Handheld optical instruments requiring skilled refractionist operation dominate Commonwealth mobile screening programs. Workforce development gaps in rural India constrain deployment velocity despite low unit costs.
- Digital Imaging:Software-enabled diagnostic functions face acute EU Medical Device Regulation compliance burdens with expanded technical documentation requirements. FDA 510(k) clearance timelines delay United States commercial entry.
- Automated:Self-aligning systems reduce operator skill dependencies in China's high-volume hospital departments.
- Wireless Connectivity:Bluetooth modules enable real-time EHR integration for training institution workflows in the United Kingdom.
Manual technology retains the largest installed base; Digital Imaging scales fastest where regulatory pathways clarify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National vision health programs and mercury-free equipment mandates are redirecting procurement flows toward LED-based diagnostic platforms across hospital systems and school screening networks.
United States
FDA 510(k) clearance timelines constrain commercial entry for automated retinoscope systems, extending premarket notification review periods for digital imaging variants. Hospital procurement departments in the United States prioritize operational expenditure flexibility through equipment leasing arrangements over traditional capital purchases. The Greater Boston medical technology cluster anchors service infrastructure for premium diagnostic instrument maintenance and calibration.
China
National vision health program expansion creates capital equipment procurement windows for tier-one hospital ophthalmology departments seeking modernized diagnostic fleets. The National Medical Products Administration enforces strengthened clinical evidence standards for software-enabled diagnostic functions under updated medical device registration pathways. The Yangtze River Delta manufacturing base concentrates semiconductor light source supply chains for LED illumination module production.
Germany
REACH and RoHS frameworks accelerate the phase-out of halogen bulb-containing devices across ophthalmology practices, forcing fleet replacement decisions ahead of regulatory deadlines. The EU Medical Device Regulation imposes expanded technical documentation requirements for digital imaging retinoscope platforms seeking CE marking. Precision lens grinding capabilities concentrate in the Baden-Württemberg optical manufacturing cluster, creating single-source dependencies for high-accuracy instruments.
India
School-based vision screening mandates generate institutional procurement pipelines for handheld diagnostic instruments as ministries of health integrate refraction services into primary care infrastructure. The Central Drugs Standard Control Organization enforces BIS electrical safety certification for imported ophthalmic diagnostic equipment, creating compliance layering for multinational suppliers. Pediatric eye clinics in Maharashtra and Karnataka drive adoption amid rising childhood myopia screening requirements.
United Kingdom
Pay-per-use financing models fragment traditional capital purchase patterns across Commonwealth mobile screening programs, opening access for smaller clinics and independent practitioners. MHRA conformity assessment procedures align with EU MDR standards for digital imaging variants while maintaining distinct UKCA marking requirements post-Brexit. Compact portable retinoscope designs dominate community health outreach initiatives in Greater London and the Midlands.
Global Retinoscopes Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement networks that reward established hospital contracting relationships and optical precision manufacturing heritage. The vendor base stratifies into three tiers: multinational diagnostic equipment conglomerates with integrated service infrastructure, mid-scale specialists with regional manufacturing footprints, and emerging portable instrument developers targeting mobile screening applications. Dominant competitive moves include backward integration into semiconductor light source supply chains and geographic expansion through distributor partnerships in Asia-Pacific screening program markets.
Within the precision manufacturing tier, HEINE Optotechnik GmbH & Co. KG and Rudolf Riester GmbH exemplify German optical engineering heritage. Welch Allyn anchors the channel-control archetype through established North American hospital contracting networks. Keeler Ltd. occupies a position within the Commonwealth-market specialist segment, while Zumax Medical Co., Ltd. and Suzhou Kangjie Medical Co., Ltd. represent Chinese manufacturing-scale players. NEITZ INSTRUMENTS Co., Ltd. sits within the Japanese precision instrument tradition.
| Leading Market Players |
|---|
| Welch Allyn |
| HEINE Optotechnik GmbH & Co. KG |
| Keeler Ltd. |
| Zumax Medical Co., Ltd. |
| US Ophthalmic |
| NEITZ INSTRUMENTS Co., Ltd. |
| Rudolf Riester GmbH |
| Unitech Vision |
| Suzhou Kangjie Medical Co., Ltd. |
| Others |
Supply & Pricing Matrix
REACH and RoHS mercury restrictions operating as a regulatory chokepoint determine both the compression of halogen-to-LED pricing spreads and the reconfiguration of semiconductor-dependent supply chains across ophthalmic diagnostic manufacturing.
Pricing Analysis
Certification level (FDA 510(k)-grade versus CE-marked versus BIS-certified) creates the primary spread across retinoscope procurement tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium tiers bundling wireless connectivity modules and extended calibration service contracts. Cost compression in economy manual units is intensifying because smartphone-based refraction apps threaten low-end segments in price-sensitive Indian and Southeast Asian markets. Mobile screening program operators in Commonwealth markets exhibit highest price sensitivity, while tier-one hospital ophthalmology departments in China show lowest sensitivity due to national vision health program budget allocations.
Supply Chain Analysis
Semiconductor light source feedstock for LED illumination modules draws from Taiwan, South Korea, and the Yangtze River Delta manufacturing base in China. Precision lens grinding for high-accuracy optical components rests on German and Japanese manufacturing clusters, while battery cell supply for portable units sources from South Korean and Chinese producers. Single-source vulnerability concentrates in Baden-Württemberg optical manufacturing for validation-grade instruments. Distribution runs through hospital contracting networks in North America, GPO-affiliated procurement consortia in the United Kingdom, and ministry of health tender systems in India and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment leasing proliferation and pay-per-use financing fragmentation have shifted bargaining power toward consolidated hospital procurement networks and away from fragmented independent practitioners.
For Market Incumbents: Build installed-base moats through backward integration into semiconductor light source supply chains and captive calibration service infrastructure. Secure multi-year hospital system partnership agreements in China's tier-one ophthalmology departments before NMPA registration pathways tighten for software-enabled diagnostic functions. Counter smartphone-based refraction substitution threats by embedding wireless EHR connectivity as standard rather than premium-tier features. For New Entrants and Emerging Players: Pursue white-space capture in India's pediatric eye clinic segment where school-based screening mandates outpace established vendor deployment capacity. Target battery-operated portable retinoscope demand for Maharashtra and Karnataka mobile screening programs where workforce development gaps constrain manual instrument utilization. Deploy distributor partnerships with regional optical equipment specialists rather than direct hospital contracting approaches. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors precision manufacturing specialists with semiconductor illumination expertise over legacy halogen-dependent portfolios. Long-term viability over a decade horizon hinges on regulatory navigation capabilities across FDA, EU MDR, and CDSCO frameworks. Acquisition target archetype: mid-scale German or Japanese optical instrument developers with established CE marking documentation and dormant FDA 510(k) submission pipelines. Monitor NMPA software-enabled diagnostic registration pathway clarifications as the inflection signal for digital imaging variant scalability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR clinical evidence requirements compress certification timelines for digital imaging variants seeking market entry. |
| Hospital System Partnership | Welch Allyn's established North American contracting networks demonstrate loyalty-sustaining power against leasing fragmentation. |
| Software Companion Development | Bluetooth-enabled EHR integration captures disproportionate R&D investment targeting training institution sales. |
| Backward Integration into LED Modules | Semiconductor light source supply chain control secures margin protection as halogen phase-out accelerates under REACH. |
| Reimbursement Strategy | Coverage decisions for automated refraction in public health systems determine capital allocation between manual and technology-enhanced platforms. |
Research Methodology
A standing panel of ophthalmology department procurement managers, biomedical equipment engineers, GPO contracts specialists, and mobile screening program operators provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, CDSCO import registration filings, and hospital procurement contract repositories. Bottom-up unit shipment estimates triangulated against top-down diagnostic equipment spending data from national health accounts.
Scenario-bracketing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning illumination technology architecture, connectivity capability tier, end-user procurement authority, and regional regulatory cluster. CAGRs derived from installed-base replacement cycle analysis overlaid with mandate-driven volume inflections. Forecast inputs incorporated REACH and RoHS compliance deadline phasing, school-based screening mandate rollout schedules, and semiconductor supply capacity expansion trajectories.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles, currency volatility affecting import-dependent markets, or trade policy shifts impacting semiconductor supply would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway timelines and technology substitution elasticities. Cross-checking against hospital procurement database benchmarks and national health expenditure accounts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Biodegradable Stents Market
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
United Kingdom Contraceptive Devices Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Global Refractive Surgery Devices Market
Medical Devices
MRI Coils Market
Medical Devices
Ultrasonic Dissection Devices Market
Medical Devices
Polyglyconate Sutures Market
Medical Devices
Magnetic Ablation Catheter Market
Medical Devices
Struts Implants Market
Medical Devices
X-Ray Stretchers Market
Medical Devices
North America Laser Hair Removal Market
Medical Devices
Penile Implants Market