
 Pathology Devices Market | 2026-2036
Pathology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pathology Devices Market Outlook
Recurring software subscription layers for AI-powered analysis is consolidating the traditional capital-equipment model in pathology, shifting revenue toward per-slide or per-case monetization. Danaher Corporation leverages its life sciences portfolio to anchor integrated workflow solutions across staining and imaging. Siemens Healthineers sustains R&D intensity in digital pathology platforms that compete on diagnostic throughput. Thermo Fisher Scientific controls distribution reach into research institutions through its analytical instruments channel.
Pathology devices comprise instruments, consumables, and software systems designed to analyze tissue specimens, bodily fluids, and cellular samples at resolutions typically ranging from 0.5 to 40 micrometers for diagnostic or research purposes. These systems serve primarily to detect disease states, guide treatment selection, and support pharmaceutical development through reproducible biomarker quantification. Digital pathology and whole-slide imaging now occupy the highest-margin tier of the product landscape, while liquid biopsy instruments represent the fastest-expanding segment as non-invasive cancer monitoring gains clinical traction. Immunohistochemistry remains mature but indispensable, with reagent recurring revenue pools stabilizing profitability for installed-base vendors.
The FDA regulates digital pathology algorithms as software-as-a-medical-device, while the EMA enforces IVDR compliance for diagnostic platforms across European member states, and CLIA standards govern laboratory quality in US hospital settings. These frameworks elevate barriers for unvalidated AI tools while accelerating clearance timelines for platforms with prospective clinical evidence. Stakeholders must weigh regulatory jurisdiction against deployment scale when prioritizing market entry sequences for next-generation diagnostic systems.
Market Dynamics
AI-powered diagnostic platforms are compressing turnaround times for cancer diagnosis while simultaneously fragmenting procurement authority between hospital laboratories and centralized reference networks.
Growth Catalysts
- EMA IVDR compliance acceleration:Platforms with prospective clinical evidence gain faster clearance timelines across European member states, rewarding validated AI tools with market access advantages.
- Liquid biopsy instrument demand:Non-invasive cancer monitoring protocols are expanding requisition volumes for circulating tumor DNA analysis in oncology departments.
- German reference laboratory consolidation:Centralized procurement of whole-slide imaging systems in Bavaria and Baden-Württemberg is concentrating vendor relationships and standardizing platform ecosystems.
Market Restraints
- FDA SaMD validation costs:Software-as-a-medical-device oversight requires extensive clinical evidence packages that extend development timelines for algorithm developers.
- Fluorophore supply concentration:Specialized reagent manufacturing clusters in Switzerland and Japan create vulnerability for immunohistochemistry workflow continuity.
- Digital storage infrastructure:Whole-slide image files exceeding one gigabyte per specimen strain hospital IT budgets and cloud migration timelines.
Strategic Opportunities
- India diagnostic network expansion:Tier-two and tier-three cities present underpenetrated demand for affordable digital pathology workstations as cancer screening programs scale.
- AI-staining convergence:Integration of automated tissue processing with real-time quality control algorithms eliminates manual review bottlenecks in high-volume laboratories.
- Subscription monetization models:Per-slide or per-case software licensing is displacing capital equipment purchases, creating recurring revenue streams for platform vendors.
Industry Challenges
- Computational pathology expertise scarcity:Dual-trained professionals capable of validating AI outputs against histological ground truth command premium compensation and extended recruitment cycles.
- Legacy LIS integration complexity:Proprietary data formats from incumbent scanner vendors obstruct seamless interoperability with third-party analysis modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pathology Devices Market |
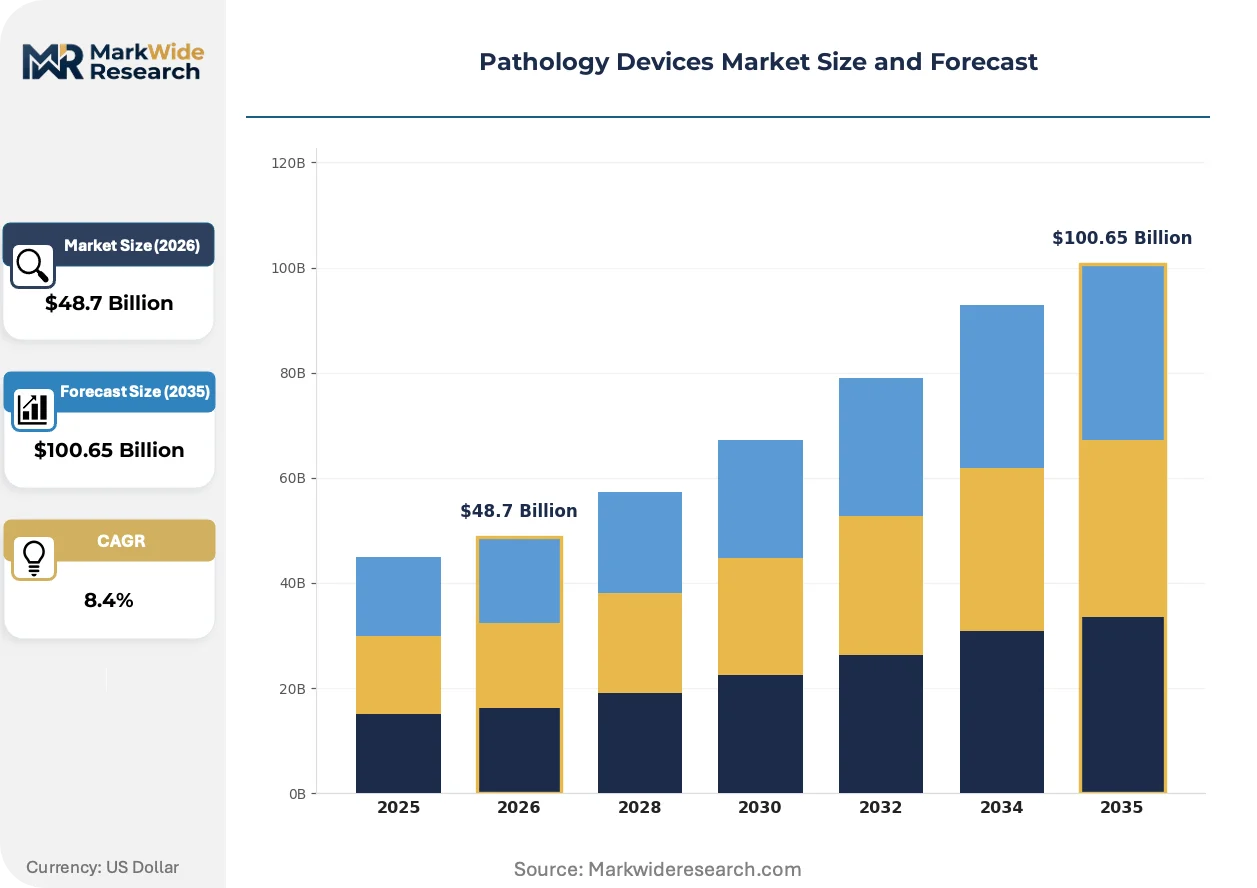
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Pathology, Immunohistochemistry, Liquid Biopsy, Cytopathology End User: Hospital Laboratories, Research Institutions, Diagnostic Centers, Contract Laboratories Technology: Telepathology, AI-Powered Analysis, Whole Slide Imaging, Fluorescence Microscopy Application: Cancer Diagnosis, Disease Monitoring, Drug Development, Biomarker Discovery |
| Companies Covered | Abbott Laboratories, Siemens Healthineers, Becton Dickinson and Company, Beckman Coulter Inc, Hamamatsu Photonics, Danaher Corporation, Thermo Fisher Scientific, Bio-Rad Laboratories, F Hoffmann-La Roche AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pathology Devices Market Strategic Shifts
Cloud-native pathology platforms are redistributing computational workloads from on-premise servers to distributed architectures, enabling real-time collaboration between pathologists across institutional boundaries.
Multiplex immunofluorescence is overtaking chromogenic immunohistochemistry in immuno-oncology biomarker panels. Academic medical centers in Massachusetts and California are deploying seven-color and nine-color protocols for simultaneous PD-L1, CD8, and tumor-infiltrating lymphocyte quantification. This technology is overtaking single-marker sequential staining by compressing tissue consumption and standardizing scoring reproducibility across clinical trials.
The EU AI Act risk classification framework is elevating documentation requirements for diagnostic algorithms deployed in clinical decision support roles. Manufacturers must maintain post-market performance monitoring systems and algorithm change control protocols. High-risk pathology AI systems face conformity assessment procedures that extend commercialization timelines by twelve to eighteen months relative to lower-risk categories.
Hospital laboratory directors are unbundling scanner hardware from analysis software during contract renegotiations. Reference laboratories in Texas and Florida are demanding API-accessible image repositories that permit multi-vendor algorithm deployment without platform lock-in. This purchasing pattern shift is most visible in consolidated health systems where procurement committees now separate capital equipment from recurring software commitments.
Pathology Devices Market Segmentation
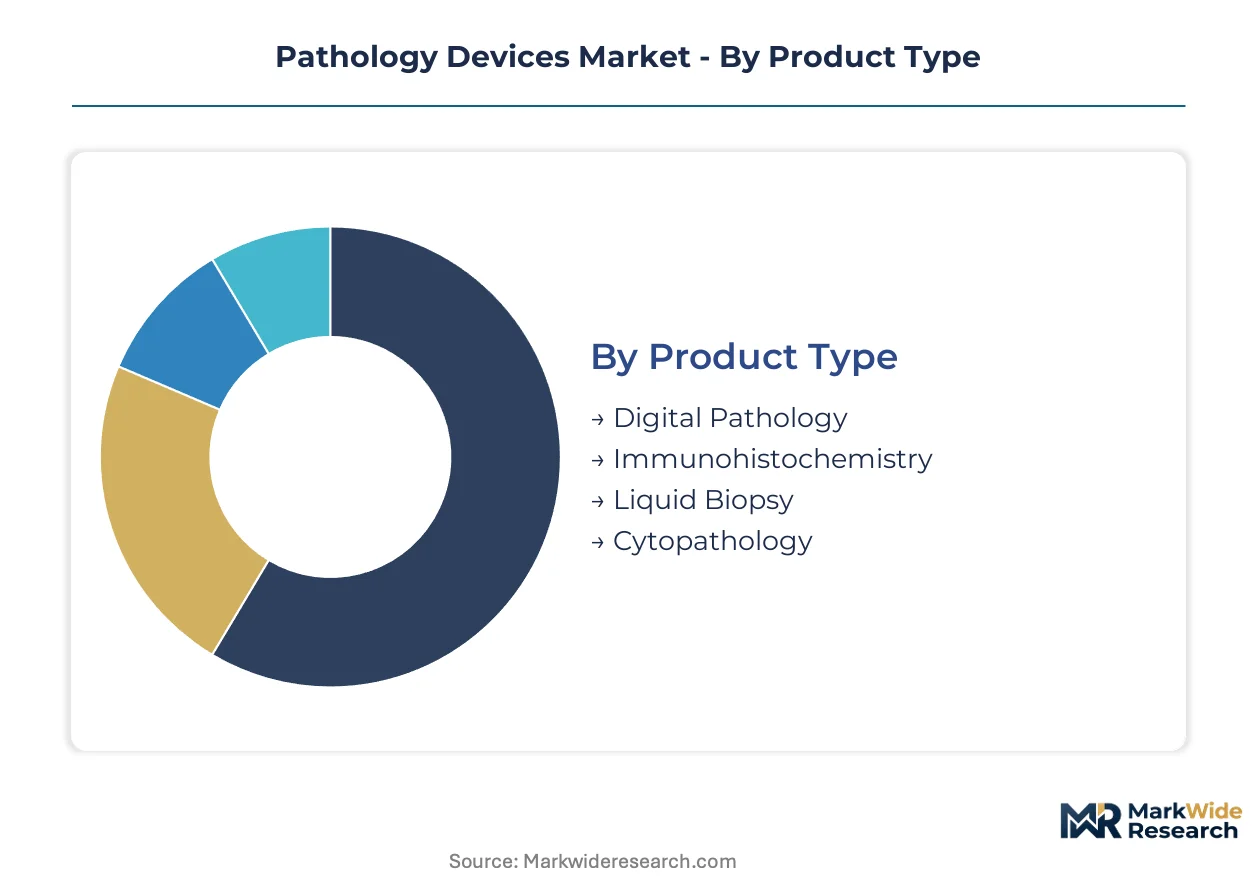
Pathology device purchasing splits between high-volume consumables and premium platform investments, with procurement committees now separating hardware capital from recurring software commitments. Understanding these segment boundaries reveals where vendor margins concentrate and where pricing power erodes.
Product Type:
Volume concentration sits with mature reagent categories while premium capture flows to integrated digital platforms.
- Digital Pathology:Whole-slide imaging systems and cloud-native platforms enable remote diagnosis and AI-assisted quantification at 0.5 micrometer resolution. Hospital laboratories in Germany are consolidating procurement around standardized scanner ecosystems to reduce interoperability friction.
- Immunohistochemistry:Chromogenic staining reagents and automated processors constitute the highest-volume consumable tier with recurring revenue stability. Swiss and Japanese fluorophore supply clusters create vulnerability for workflow continuity in high-throughput laboratories.
- Liquid Biopsy:Circulating tumor DNA analysis instruments are expanding most quickly as non-invasive cancer monitoring protocols gain oncology adoption.
- Cytopathology:Cellular sample preparation systems serve cervical cancer screening programs and fine-needle aspiration workflows.
Today's leader: Immunohistochemistry. Tomorrow's challenger: Digital Pathology.
End User:
Procurement authority fragments between centralized reference networks and hospital-based laboratories with diverging technical requirements.
- Hospital Laboratories:Integrated health systems demand API-accessible image repositories that permit multi-vendor algorithm deployment without platform lock-in. Texas and Florida reference laboratories are unbundling scanner hardware from analysis software during contract renegotiations.
- Research Institutions:Academic medical centers in Massachusetts and California deploy seven-color multiplex immunofluorescence for simultaneous PD-L1, CD8, and tumor-infiltrating lymphocyte quantification in clinical trials.
- Diagnostic Centers:Independent facilities concentrate on high-volume screening workflows with standardized reporting protocols.
- Contract Laboratories:Third-party providers serve pharmaceutical clients with GLP-compliant biomarker quantification and regulatory submission support.
Contract laboratories extract premium pricing for regulatory-grade documentation; hospital laboratories drive volume scale.
Technology:
Computational intensity separates established imaging modalities from emerging AI-native architectures.
- AI-Powered Analysis:Deep learning algorithms for cancer detection and biomarker scoring face FDA software-as-a-medical-device validation requirements that extend development timelines. EU AI Act risk classification elevates documentation burdens for clinical decision support systems.
- Whole Slide Imaging:Scanner hardware generates files exceeding one gigabyte per specimen, straining hospital IT budgets and cloud migration timelines.
- Telepathology:Real-time consultation platforms redistribute pathologist expertise across institutional boundaries.
- Fluorescence Microscopy:Multiplex immunofluorescence protocols are displacing single-marker sequential staining by compressing tissue consumption.
Whole Slide Imaging anchors installed-base revenue; AI-Powered Analysis commands the steepest expansion trajectory.
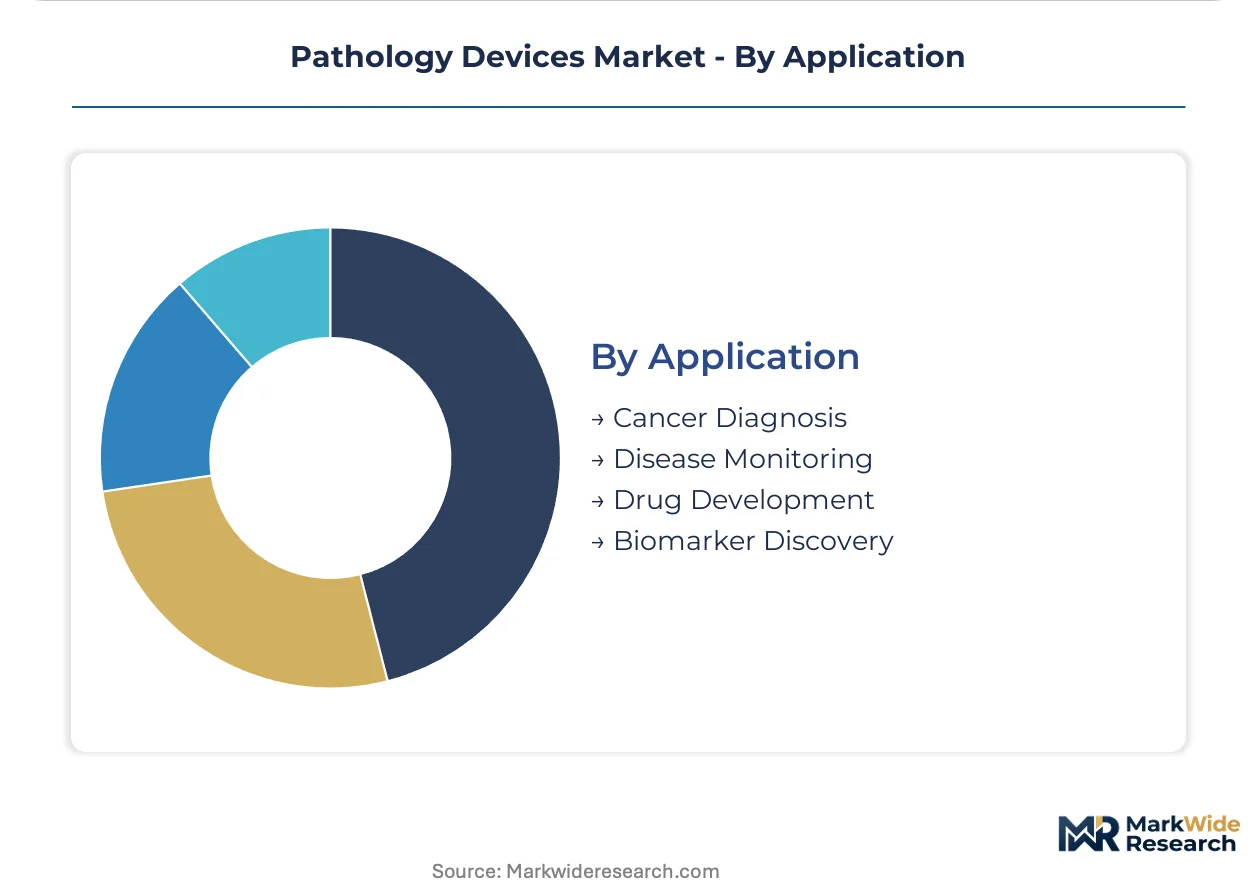
Application:
Clinical utility concentrates in oncology while pharmaceutical sponsorship sustains research-oriented segments.
- Cancer Diagnosis:AI-powered platforms compress turnaround times for histopathological confirmation while fragmenting procurement authority between hospital and reference laboratory networks.
- Drug Development:Pharmaceutical sponsors fund biomarker quantification for clinical trial patient stratification and companion diagnostic development.
- Disease Monitoring:Serial tissue sampling workflows support therapeutic response assessment in chronic conditions.
- Biomarker Discovery:Research applications drive demand for high-plex imaging and spatial transcriptomics integration.
Cancer Diagnosis commands current spending priority; Drug Development offers the most durable contract visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting pathology device manufacturing toward jurisdictions with streamlined medical device approval pathways, as FDA software-as-a-medical-device validation costs push algorithm developers to establish European development centers.
United States
Hospital laboratories in Texas and Florida are unbundling scanner hardware from analysis software, demanding API-accessible image repositories that permit multi-vendor algorithm deployment. FDA oversight of software-as-a-medical-device requires extensive clinical evidence packages that extend development timelines for domestic algorithm developers. Academic medical centers in Massachusetts and California deploy seven-color multiplex immunofluorescence for simultaneous PD-L1 and CD8 quantification in clinical trials.
Germany
Reference laboratories in Bavaria and Baden-Württemberg are consolidating procurement of whole-slide imaging systems, concentrating vendor relationships and standardizing platform ecosystems. EMA IVDR compliance acceleration rewards platforms with prospective clinical evidence through faster clearance timelines across European member states. The country's diagnostic network expansion concentrates manufacturing partnerships around Munich and Heidelberg clusters.
China
Tier-two and tier-three cities present underpenetrated demand for affordable digital pathology workstations as cancer screening programs scale nationwide. NMPA medical device regulations are evolving to accommodate AI-powered diagnostic platforms while maintaining stringent clinical evidence requirements. Manufacturing clusters in the Yangtze River Delta are developing cost-competitive whole-slide imaging hardware for domestic and export markets.
India
Diagnostic network expansion into tier-two and tier-three cities is driving demand for affordable digital pathology workstations as national cancer screening initiatives gain momentum. CDSCO medical device regulations are aligning with international standards to accelerate market access for validated diagnostic platforms. Manufacturing and service hubs in Maharashtra and Karnataka are developing localized support infrastructure for imported imaging systems.
Japan
Specialized fluorophore manufacturing clusters create supply concentration for immunohistochemistry workflow continuity in high-throughput laboratories across the archipelago. PMDA regulatory frameworks maintain rigorous clinical evidence standards for digital pathology algorithm approval while supporting innovation in multiplex imaging technologies. Precision manufacturing capabilities in Hamamatsu and surrounding regions anchor optical component supply for global scanner vendors.
Pathology Devices Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated life sciences conglomerates commanding premium platform positions while regional reagent suppliers capture recurring consumable volumes. The vendor landscape organizes into three strategic archetypes: diversified conglomerates leveraging cross-divisional workflows, precision optics specialists dominating scanner hardware, and reagent-focused players securing installed-base profitability. Competitive positioning hardens through backward integration into fluorophore manufacturing and strategic partnerships for AI algorithm development.
Among diversified life sciences conglomerates, Danaher Corporation and Thermo Fisher Scientific exemplify the integrated workflow archetype, combining analytical instruments with distribution reach into research institutions. Siemens Healthineers occupies a position within the medical imaging tier, sustaining development intensity in digital pathology platforms. These three entities represent contrasting strategic postures: portfolio breadth against diagnostic throughput specialization against research channel control.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Siemens Healthineers |
| Becton Dickinson and Company |
| Beckman Coulter Inc |
| Hamamatsu Photonics |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| F Hoffmann-La Roche AG |
| Others |
Value Chain & Pricing Dynamics
Cloud-native platform migration simultaneously compresses IT infrastructure costs for hospital laboratories and concentrates procurement leverage among reference networks capable of negotiating enterprise-scale software commitments. This dual shift rewards vendors with recurring revenue architectures while squeezing margins for hardware-dependent incumbents.
Pricing Analysis
Distributor margins for whole-slide imaging hardware range between fifteen and twenty-five percent, while direct-to-hospital software subscriptions bypass channel markups entirely. Three-tier pricing structure across premium, standard, and economy levels stratifies by scanner resolution, AI module inclusion, and post-deployment support intensity. Cost compression in economy-tier hardware is intensifying because Chinese manufacturers are exporting cost-competitive base units into India and Southeast Asia. Hospital laboratories exhibit the highest price sensitivity, whereas pharmaceutical contract research organizations prioritize regulatory-grade documentation over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Japanese fluorophore manufacturers supplying chromogenic and fluorescent reagents to immunohistochemistry processors worldwide. Optical component manufacturing draws from precision clusters in Japan, Germany, and Switzerland, while scanner assembly rests on CMOS sensor supply from Taiwan and South Korea. Tariff exposure runs through US-China technology trade restrictions affecting cloud infrastructure hardware. Distribution runs through specialized life sciences distributors with cold-chain capabilities for reagent logistics and direct field service organizations for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pathology devices rests on the shift from capital equipment sales toward per-slide software monetization, compressing customer acquisition costs while extending lifetime value through subscription renewals.
For Market Incumbents: Extend installed-base profitability by backward integration into fluorophore manufacturing and captive supply of high-plex reagents. Consolidate procurement relationships with German reference laboratories before standardization decisions lock out secondary vendors. Defend against cloud-native entrants by embedding AI modules directly into existing scanner ecosystems rather than permitting third-party algorithm deployment. For New Entrants and Emerging Players: Regional distributors in India's tier-two cities present the most penetrable channel for affordable digital pathology workstations, bypassing entrenched relationships with multinational conglomerates. Target hospital laboratory procurement committees in Texas and Florida by offering API-accessible platforms that unbundle hardware from software. Pursue white-label partnerships with established life sciences distributors to accelerate field presence without direct sales force investment. For Investors and Strategic Acquirers: Valuations sit cheapest among reagent-focused specialists with installed-base profitability but limited platform integration capabilities. The five-to-ten-year viability window favors vendors with demonstrated FDA software-as-a-medical-device clearance pathways over pre-clinical algorithm developers. Monitor EMA IVDR compliance acceleration timelines as the inflection signal for European market access advantages.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Accelerates market access for AI-powered diagnostic platforms in US hospital networks. |
| CE Marking Pathway under IVDR | Enables faster clearance timelines for validated platforms across European member states. |
| Hospital System Partnership | Secures multi-year enterprise contracts for integrated staining-to-imaging workflows. |
| Software Companion Development | Creates recurring revenue streams through per-slide analysis licensing models. |
| Reimbursement Strategy | Aligns platform value proposition with CMS and private payer coverage decisions. |
Study Parameters
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market informing demand-side validation. Interviews with hospital laboratory directors, reference pathology network procurement leads, biomedical engineers, and GPO contracts managers combined with secondary analysis of FDA 510(k) filings, EMA IVDR submission databases, CMS Medicare reimbursement data, and hospital procurement contract repositories. Bottom-up scanner shipment tracking and top-down healthcare expenditure triangulation anchored market sizing across the analysis window.
Rate-of-change decomposition separated volume growth from price-mix effects across product type, end user, technology, and application dimensions. Modeled variables included digital pathology platform adoption curves, immunohistochemistry reagent consumption per installed base unit, and liquid biopsy instrument placement velocity. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion constraints, with AI-powered analysis and whole-slide imaging treated as separate technology trajectories.
Revisions become necessary when regulatory clearance timelines shift materially, reimbursement coverage decisions alter hospital procurement priorities, or supply chain disruptions affect fluorophore availability. Forecasts reflect documented assumptions regarding EMA IVDR implementation pace and FDA software-as-a-medical-device enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Breast Cancer Core Needle Biopsy Market
Medical Devices
Struts Implants Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Global Injectable Drug Delivery Devices Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
Intracranial Stents Total Addressable Market
Medical Devices
Subdural Electrodes Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Europe Mobility Aids Market
Medical Devices
US Medical Device Manufacturers Market
Medical Devices
India Biopsy Devices Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
Pelvic Reconstruction Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market