
 3D Printed Medical Implants Market | 2026-2036
3D Printed Medical Implants Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printed Medical Implants Market Intelligence
Orthopedic centers is expanding their share of 3D printed implant procurement as patient-specific joint reconstruction gains clinical traction. Stryker Corporation leverages its integrated digital surgical workflow to anchor high-volume hip and knee implant production. Materialise NV specializes in certified medical 3D printing software that controls pre-surgical planning and implant design validation across European and North American hospital networks.
3D printed medical implants are patient-matched devices fabricated through additive manufacturing processes such as selective laser melting or electron beam melting from biocompatible materials including titanium alloys and polyether ether ketone. These implants replace or support damaged biological structures with geometries unattainable through conventional subtractive machining. Orthopedic implants lead current revenue contribution due to established reimbursement for custom joint replacements, while cranial implants represent the fastest-growing category as trauma centers adopt titanium lattice structures for complex skull defect reconstruction. Dental implants occupy a mature margin pool where digital intraoral scanning has streamlined chairside-to-lab workflows.
FDA 510(k) and de novo pathways govern U.S. market entry for 3D printed implants, while EMA's Medical Device Regulation enforces post-market clinical follow-up across Europe. ISO 10993 biocompatibility standards and ASTM F42 additive manufacturing guidelines shape material qualification and process validation requirements globally. Stakeholders must monitor evolving software-as-a-medical-device classifications that could reclassify design automation tools used in implant personalization.
Market Dynamics
Patient-matched implant geometries are compressing the gap between surgical planning and manufacturing execution, forcing orthopedic centers to rebuild procurement workflows around digital surgical ecosystems rather than traditional device catalogs.
Growth Catalysts
- FDA 510(k) Pathway Modernization:Streamlined clearance protocols for patient-specific devices accelerate commercialization timelines for titanium lattice cranial implants.
- Selective Laser Melting:This powder-bed fusion process enables porous titanium structures with bone-ingrowth surfaces impossible through conventional machining, driving adoption in trauma reconstruction.
- German Additive Manufacturing Hubs:Concentrated industrial clusters in Bavaria and Baden-Württemberg integrate hospital networks with certified production facilities for same-week implant turnaround.
Market Restraints
- Titanium Alloy Supply Concentration:Sponge and powder production clusters in China and Russia create input cost volatility and geopolitical exposure for implant fabricators.
- EMA Post-Market Surveillance:MDR-mandated clinical follow-up extends liability windows and compliance costs for European orthopedic device sponsors.
- Subtractive Machining Substitutes:Five-axis CNC milling retains cost advantages for standard geometries, limiting additive penetration in high-volume joint replacement.
Strategic Opportunities
- India's CDSCO Fast-Track:Emerging regulatory frameworks for custom medical devices open underpenetrated surgical markets in tier-1 hospital networks.
- AI-Driven Topology Optimization:Convergence of generative design software with electron beam melting compresses implant development cycles from months to days.
- Direct Hospital Contracting:Bypassing traditional distributor networks lets manufacturers capture margin and lock in multi-year digital surgical partnerships.
Industry Challenges
- Additive Manufacturing Technician Scarcity:Qualified operators for medical-grade laser and electron beam systems command premium wages and extended recruitment timelines.
- ISO 10993 Biological Evaluation:Evolving biocompatibility testing protocols for powder-bed fusion surfaces delay certification and increase validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printed Medical Implants Market |
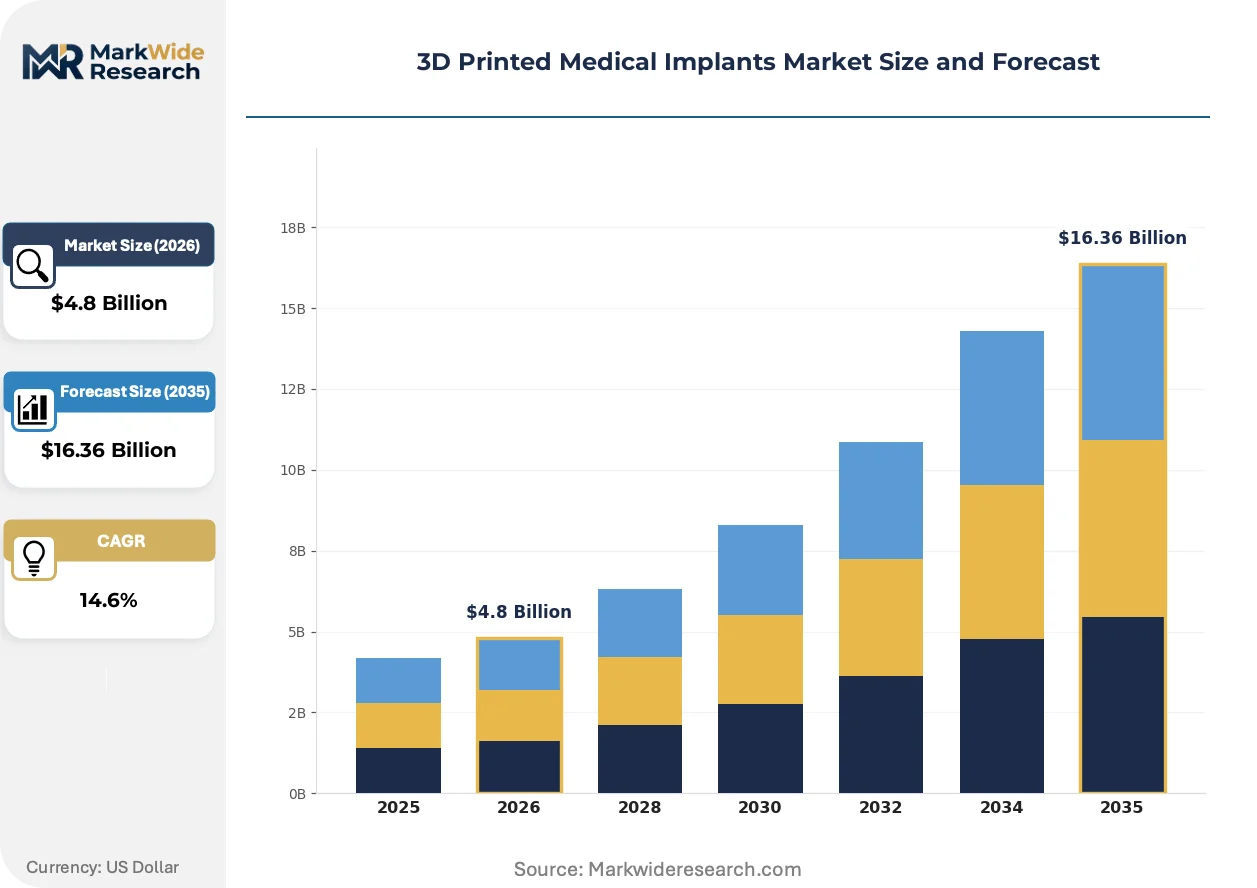
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Implants, Orthopedic Implants, Cranial Implants, Spinal Implants, Maxillofacial Implants, Vascular Stents Material: Titanium, Bioceramics, Polyether Ether Ketone, Stainless Steel, Cobalt Chrome, Hydroxyapatite Application: Trauma Repair, Joint Reconstruction, Bone Defect Filling, Neurological Restoration, Cardiovascular Surgery, Cosmetic Surgery End User: Hospitals, Specialty Clinics, Ambulatory Surgery Centers, Orthopedic Centers, Dental Clinics, Research Institutes |
| Companies Covered | Medtronic plc, GE Additive (General Electric Company), Stryker Corporation, Stratasys Ltd., 3D Systems Corporation, Johnson & Johnson (DePuy Synthes), Smith & Nephew plc, Materialise NV, Zimmer Biomet Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printed Medical Implants Market Strategic Shifts & Innovations
Digital thread integration is collapsing the boundaries between diagnostic imaging, surgical simulation, and implant fabrication, creating closed-loop ecosystems where design iterations occur intraoperatively.
Multi-material extrusion systems are unifying structural and bioactive phases within single implant architectures. Trauma centers in the United States and Germany are piloting these platforms for load-bearing osteosynthesis plates with integrated antibiotic elution layers. This convergence is compressing the traditional separation between mechanical fixation and pharmaceutical delivery into unified therapeutic devices.
EMA's Medical Device Regulation is enforcing device-specific clinical evidence requirements that diverge from FDA predicate-based pathways. European orthopedic centers now demand prospective registries for 3D-printed implants that U.S. institutions rarely require. Cranial reconstruction specialists in France and the Netherlands are responding by embedding post-market surveillance into initial commercial contracts.
Surgeons are bypassing traditional group purchasing organizations to negotiate directly with implant design software vendors. Academic medical centers in China and the United States are leading this disintermediation, securing site licenses for patient-specific planning tools that bundle hardware procurement. This behavioral shift concentrates buying power within high-volume surgical departments rather than distributing it across hospital supply chains.
3D Printed Medical Implants Market Segmentation
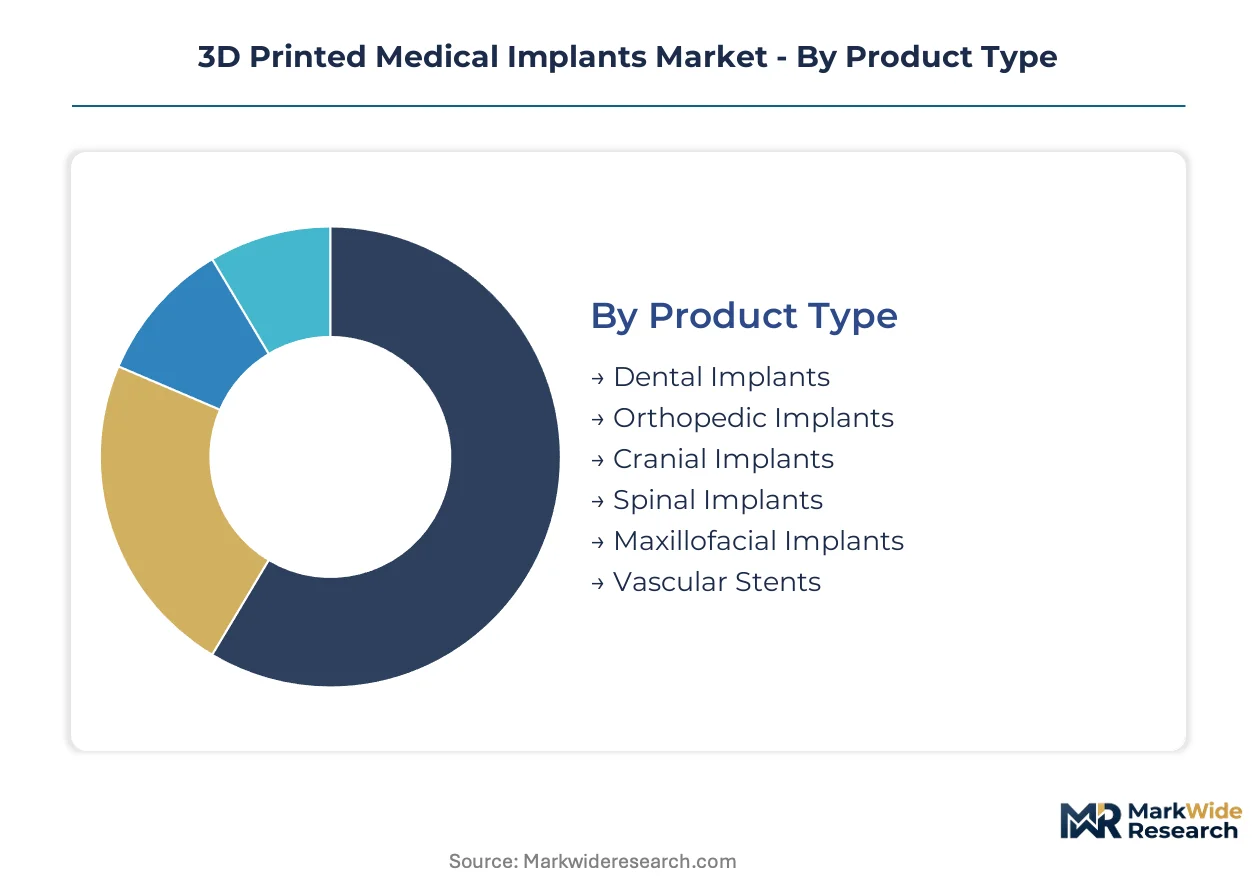
Segmentation in 3D printed medical implants reveals how additive manufacturing value pools concentrate across anatomical sites, material classes, and procurement channels. Each dimension exposes distinct technical barriers, reimbursement pathways, and customer concentration patterns that shape competitive positioning.
Product Type:
Orthopedic implants command premium pricing through established joint replacement reimbursement codes, while cranial implants exploit trauma center demand for patient-matched geometries.
- Orthopedic Implants:Titanium alloy hip and knee components fabricated via selective laser melting achieve porous bone-ingrowth surfaces. Demand concentrates in German and United States orthopedic centers rebuilding procurement around digital surgical workflows.
- Cranial Implants:Titanium lattice structures reconstruct complex skull defects from CT-derived patient geometries. Trauma centers in France and the Netherlands are expanding adoption fastest as EMA post-market surveillance requirements embed into initial contracts.
- Dental Implants:Chairside-to-lab digitization has streamlined production of titanium root-form fixtures and abutments.
- Spinal Implants:Interbody fusion cages with tailored lordotic angles address deformity correction.
- Maxillofacial Implants:Patient-specific mandibular plates and orbital floor reconstructions serve trauma and oncology reconstruction.
- Vascular Stents:Nitinol and cobalt-chrome lattice structures remain experimental outside select cardiac centers.
Mature deployment sits with orthopedic and dental implants. Newer deployment is concentrated in cranial reconstruction.
Material:
Titanium powder supply chains determine cost structures, while polymer and ceramic alternatives carve niches in load-bearing and osteoconductive applications.
- Titanium:Ti-6Al-4V ELI powder processed through electron beam melting yields fatigue-resistant orthopedic and cranial structures. Supply concentration in Chinese and Russian sponge production creates input volatility for fabricators.
- Polyether Ether Ketone:Radiolucent spinal cages and cranial plates avoid MRI artifact and match bone modulus. German additive manufacturing hubs in Bavaria are scaling PEEK fusion deposition for same-week implant turnaround.
- Bioceramics:Alumina and zirconia serve dental crown frameworks and joint bearing surfaces.
- Stainless Steel:316L variants persist in temporary fracture fixation plates.
- Cobalt Chrome:Wear-resistant articulating surfaces remain relevant for hip resurfacing.
- Hydroxyapatite:Bioactive coatings accelerate osseointegration on titanium substrates.
Volume manufacturing clusters around titanium powder-bed fusion. PEEK extrusion is expanding most quickly in spinal applications.
Application:
Reimbursement codes separate high-volume joint reconstruction from emerging neurological and cardiovascular indications.
- Joint Reconstruction:Hip and knee arthroplasty with patient-matched acetabular cups and tibial trays. United States orthopedic centers anchor demand through bundled payment contracts.
- Trauma Repair:Complex pelvic and acetabular fracture plates with anatomic pre-contouring. German trauma networks integrate CT-to-implant workflows for emergency reconstruction.
- Bone Defect Filling:Custom scaffolds for tumor resection and infection voids.
- Neurological Restoration:Cranial plates and deep brain stimulation electrode guides.
- Cardiovascular Surgery:Patient-matched aortic valve frames remain investigational.
- Cosmetic Surgery:Mandibular and chin implants for aesthetic augmentation.
Joint reconstruction captures the steepest expansion trajectory in absolute value. Trauma repair is gaining share fastest as emergency workflows digitize.
End User:
Procurement authority is shifting from centralized hospital supply chains to high-volume surgical departments with direct software licensing.
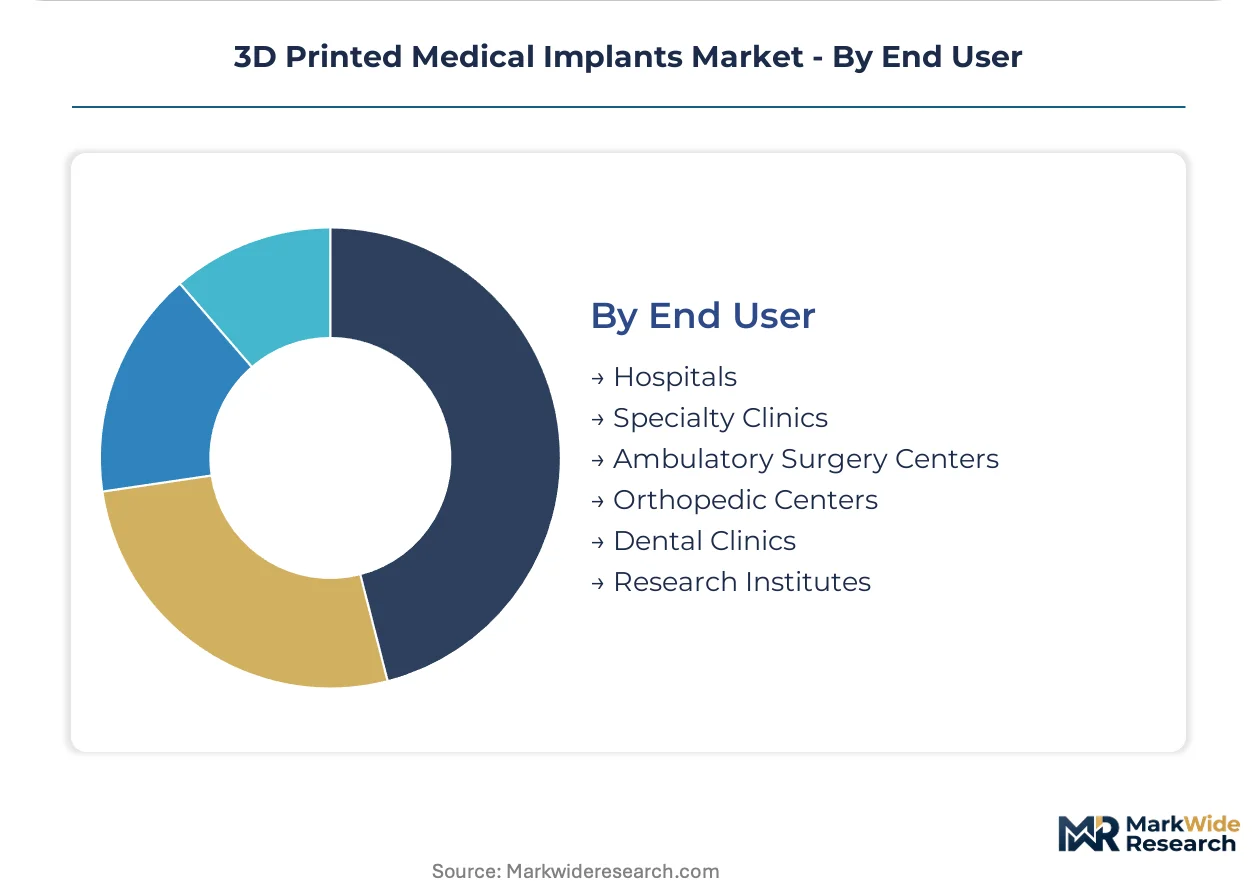
- Hospitals:Academic medical centers in China and the United States are bypassing group purchasing organizations to negotiate site licenses for patient-specific planning tools.
- Orthopedic Centers:Dedicated joint replacement facilities in Germany and the United States are rebuilding procurement around digital surgical ecosystems.
- Specialty Clinics:Craniofacial and spine-focused practices with in-house design capabilities.
- Dental Clinics:Chairside milling and printing for immediate implant provision.
- Ambulatory Surgery Centers:Limited to standardized dental and minor orthopedic procedures.
- Research Institutes:Preclinical validation of multi-material and bioactive architectures.
Procurement consolidation is strongest in orthopedic centers. Hospital direct contracting is expanding most quickly as software bundling reshapes vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical additive manufacturing clusters concentrate in tax-advantaged zones offering R&D credits and accelerated depreciation for capital equipment. Bavaria's Medical Valley and North Carolina's Research Triangle Park anchor production networks that integrate hospital systems with certified fabrication facilities.
United States
FDA 510(k) and de novo pathways streamline patient-specific device clearances, compressing commercialization timelines for titanium lattice cranial implants. Academic medical centers in Boston and Durham bypass group purchasing organizations to negotiate direct site licenses for surgical planning software. North Carolina's Research Triangle Park hosts concentrated electron beam melting capacity serving trauma centers across the Southeast.
Germany
EMA's Medical Device Regulation enforces post-market clinical follow-up that extends liability windows for implant sponsors. Bavaria's Medical Valley integrates hospital networks with certified production facilities achieving same-week implant turnaround for complex pelvic reconstructions. Baden-Württemberg's precision engineering clusters supply qualified technicians for medical-grade laser systems at premium wage levels.
China
NMPA regulatory frameworks for custom medical devices are stabilizing, opening tier-1 hospital networks to domestic and foreign implant fabricators. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou scale selective laser melting capacity for orthopedic and dental applications. Government-funded additive manufacturing centers in Shenzhen pilot multi-material extrusion for load-bearing osteosynthesis plates.
India
CDSCO fast-track pathways for custom medical devices are reducing regulatory friction for patient-matched implant imports. Maharashtra's Mumbai-Pune corridor attracts trauma centers digitizing emergency reconstruction workflows for complex acetabular fractures. Tamil Nadu's medical device parks offer tax holidays that concentrate dental implant milling and printing operations serving Southeast Asian export markets.
France
ANSM enforces device-specific clinical evidence requirements that diverge from FDA predicate-based pathways, mandating prospective registries for 3D-printed implants. Cranial reconstruction specialists in Paris and Lyon embed post-market surveillance into initial commercial contracts. Île-de-France's hospital networks pilot topology-optimized mandibular plates for oncology reconstruction with integrated antibiotic elution.
3D Printed Medical Implants Market Key Industry Players
Top-tier vendors anchor integrated digital surgical ecosystems, while mid-scale fabricators compete on material specialization and regional proximity to hospital networks. The competitive structure stratifies across three archetypes: diversified medtech conglomerates with captive additive manufacturing capacity, pure-play 3D printing equipment suppliers, and software-centric patient-specific design platforms. Dominant competitive moves include direct hospital contracting that bypasses traditional distributors, and strategic partnerships between implant fabricators and radiology AI vendors to compress scan-to-implant timelines.
Within the diversified medtech tier, Stryker Corporation and Johnson & Johnson exemplify conglomerates rebuilding procurement relationships around bundled digital surgical workflows. Materialise NV occupies a distinct position as a software-centric platform controlling pre-surgical planning and implant design validation across European and North American hospital networks. These three anchors represent contrasting strategic postures: hardware-integrated volume manufacturing, diversified orthopedic portfolios, and certified medical 3D printing software specialization.
| Leading Market Players |
|---|
| Medtronic plc |
| GE Additive (General Electric Company) |
| Stryker Corporation |
| Stratasys Ltd. |
| 3D Systems Corporation |
| Johnson & Johnson (DePuy Synthes) |
| Smith & Nephew plc |
| Materialise NV |
| Zimmer Biomet Holdings Inc. |
| Others |
Cost & Logistics Intelligence
Selective laser melting and electron beam melting adoption simultaneously compresses per-unit production costs and concentrates fabrication capacity within certified hospital-integrated hubs. Powder-bed fusion economics reward scale concentration, tilting procurement power toward orthopedic centers with captive additive manufacturing partnerships.
Pricing Analysis
Short lead-time premiums dominate pricing differentiation as trauma centers pay substantial markups for same-week cranial implant turnaround versus standard four-week production slots. Three-tier pricing structure across premium, standard, and economy levels separates emergency reconstruction workflows from scheduled joint replacement volumes. Cost compression in standard-tier orthopedic implants intensifies because five-axis CNC milling retains cost advantages for geometrically simple geometries. Price sensitivity concentrates in ambulatory surgery centers and tier-2 hospital networks, while academic medical centers demonstrate low elasticity for patient-matched emergency reconstruction.
Supply Chain Analysis
Reverse logistics for titanium powder reclamation and build-plate refurbishment flow through specialized service bureaus in Germany and the United States, creating secondary supply channels for qualified feedstock. Ti-6Al-4V ELI powder production concentrates in China and Russia for sponge supply, with German and American fabricators drawing from concentrated upstream sources. Single-source vulnerability in electron beam melting machine supply from European OEMs creates equipment acquisition bottlenecks. Distribution runs through direct hospital contracting and GPO-negotiated frameworks, with software licensing increasingly bundling hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient-matched additive manufacturing is displacing subtractive machining for complex anatomical reconstructions, compressing the technology-transition window from years to months.
For Market Incumbents: Hedge against electron beam melting equipment supply concentration by qualifying secondary laser powder-bed fusion suppliers in Germany and the United States. Secure titanium powder offtake agreements with non-Chinese sponge producers to reduce geopolitical exposure. Defensive certification investment in ISO 10993 biological evaluation protocols extends compliance moats against mid-scale fabricators. For New Entrants and Emerging Players: The premium-to-economy price-point gap in spinal interbody fusion cages offers white-space entry for PEEK extrusion specialists serving tier-2 orthopedic centers. India's CDSCO fast-track pathway for custom medical devices represents the most penetrable regulatory geography. Direct hospital software licensing partnerships bypass entrenched distributor relationships and lock in multi-year procurement commitments. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified medtech conglomerates seeking captive additive manufacturing capacity. Long-term viability hinges on software-as-a-medical-device classification clarity across FDA and EMA jurisdictions. The signal to watch is EMA MDR post-market surveillance cost absorption rates, which will separate sustainable business models from compliance-burdened competitors.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined clearance protocols accelerate titanium lattice cranial implant commercialization timelines. |
| CE Marking Pathway | EMA MDR compliance embeds post-market surveillance into initial European commercial contracts. |
| Hospital System Partnership | Direct contracting with academic medical centers concentrates procurement authority within surgical departments. |
| Software Companion Development | Patient-specific planning tools bundle hardware procurement and lock in multi-year vendor relationships. |
| Reimbursement Strategy | Custom joint replacement codes anchor orthopedic implant pricing through bundled payment contracts. |
Research Approach
FDA 510(k) and de novo clearance databases, EMA Medical Device Regulation submissions, and ISO 10993 biological evaluation standards formed the secondary backbone for regulatory pathway mapping. Primary interviews with orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers validated procurement workflow assumptions. Triangulation across bottom-up implant volume modeling and top-down market sizing anchored forecast outputs.
Bottom-up modeling segmented demand across product type, material class, application, and end-user procurement channel dimensions. Electron beam melting and selective laser melting adoption curves, titanium powder price volatility indices, and hospital digital surgical ecosystem penetration rates fed analytical frameworks. CAGRs were derived from regression analysis against historical clearance trajectories and reimbursement code expansion patterns.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time titanium sponge inventory data introduce uncertainty bands around cost projection scenarios. Practitioners should monitor NMPA custom medical device framework stabilization and CDSCO fast-track implementation for early demand inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Ileostomy Market
Medical Devices
IV Equipment Market
Medical Devices
IV Fluid Monitoring Device Market
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
Urology Guidewires Market
Medical Devices
Digital Reading Micropipettes Market
Medical Devices
Oxygen Delivery Units Market
Medical Devices
Ultrasound Biometry Devices Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
Global Gastric Balloons Market
Medical Devices
Global Wearable Injector Devices Market
Medical Devices
Active Wheelchair Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
Active Implantable Devices Market
Medical Devices
Thermal Ablation Devices Market