
 Endovenous Laser Therapy Market | 2026-2036
Endovenous Laser Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Endovenous Laser Therapy Market Analysis
Multi-source procurement of laser fibers and diode modules is broadening as vein treatment centers diversify supplier relationships beyond single-device vendors. AngioDynamics leverages its vascular access heritage to anchor hospital contracts for endovenous systems. Medtronic sustains R&D intensity across energy-based surgical platforms. Alma Lasers competes through aesthetic-to-medical crossover distribution channels.
Endovenous laser therapy delivers thermal ablation of incompetent saphenous veins via intraluminal laser energy at wavelengths typically ranging from 810 nm to 1470 nm, causing collagen denaturation and vessel fibrosis without surgical stripping. Diode laser systems occupy the dominant technology position due to proven efficacy in truncal vein closure and compact console footprints suited for office-based labs. Fiber laser platforms represent the fastest-growing technology segment as manufacturers target reduced post-procedural bruising through precision energy delivery. Ambulatory surgical centers capture expanding margin pools by shifting procedures from hospital outpatient departments to lower-cost settings.
FDA 510(k) clearance requirements shape device design standards and clinical validation burdens for manufacturers seeking US market entry. The EU Medical Device Regulation imposes enhanced conformity assessment procedures on laser fiber sterilization and biocompatibility testing. Stakeholders must monitor reimbursement parity between thermal ablation modalities and emerging non-thermal alternatives to protect procedure volumes.
Market Dynamics
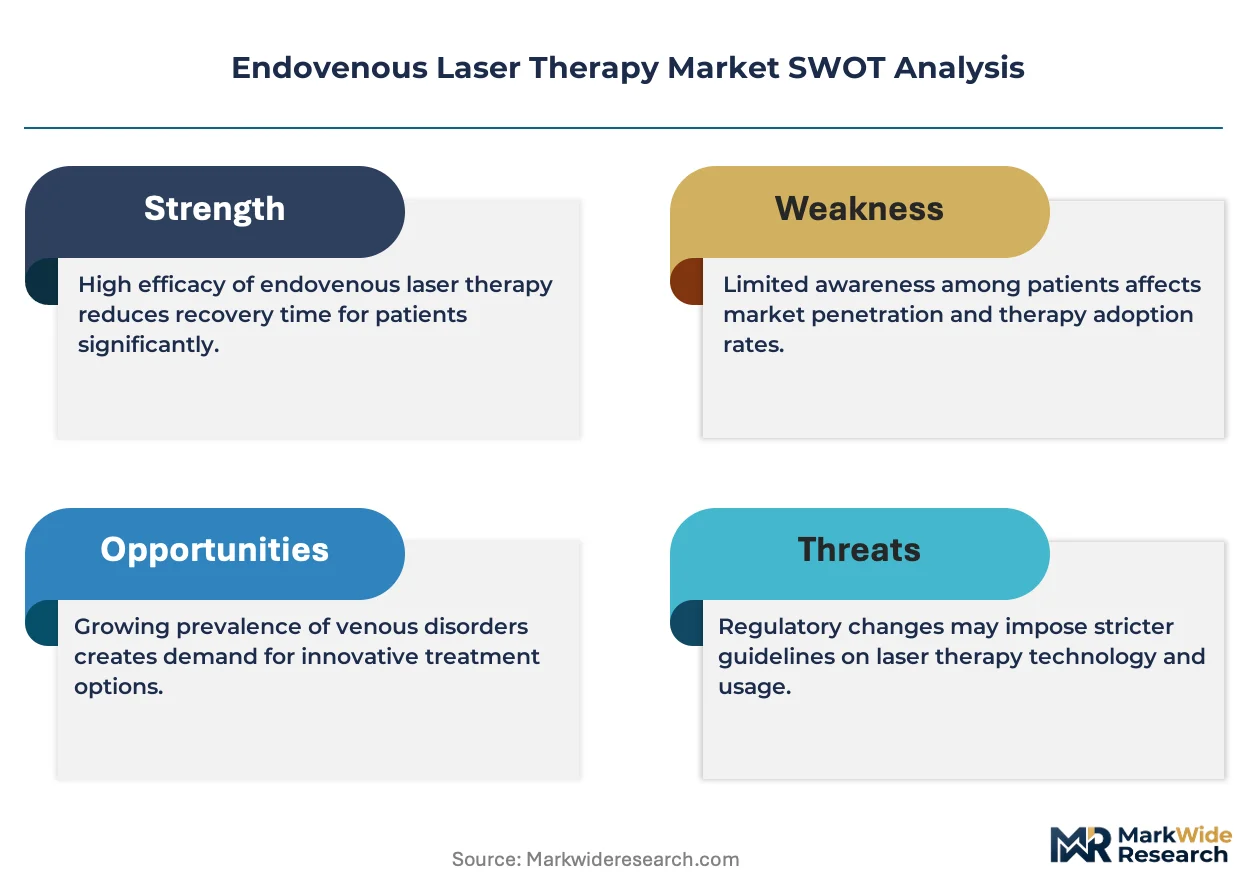
The migration of vein procedures from hospital outpatient departments to ambulatory surgical centers is compressing reimbursement rates while expanding procedure volumes, forcing device economics toward compact, office-compatible laser platforms.
Growth Catalysts
- Wavelength diversification:Manufacturers are introducing 1470 nm and 1940 nm diode systems that reduce periprocedural pain and accelerate patient return-to-work timelines.
- FDA 510(k) pathway streamlining:Predicate device referencing for laser fiber iterations has shortened clearance timelines, accelerating product refresh cycles for established vendors.
- Germany's outpatient surgical expansion:The country's statutory health insurance framework now covers endovenous thermal ablation in physician-owned surgical centers, diverting volume from inpatient settings.
Market Restraints
- Reimbursement compression:Medicare Physician Fee Schedule adjustments have narrowed margins on thermal ablation relative to sclerotherapy, pressuring capital equipment ROI timelines.
- Fiber optic supply concentration:High-purity silica fiber production clusters in China and Japan, creating single-source vulnerability for laser catheter manufacturers.
- Radiofrequency ablation substitution:ClosureFAST-style segmental thermal ablation systems compete directly on procedural speed and learning curve, capturing share in hospital-based practices.
Strategic Opportunities
- India's underpenetrated tier-2 cities:Vascular surgery training programs in Hyderabad and Chennai are expanding, creating first-mover positioning for compact diode systems.
- EU MDR conformity assessment:Enhanced biocompatibility documentation requirements favor established manufacturers with dedicated regulatory affairs infrastructure, creating barriers for new entrants.
- Aesthetic-medical crossover distribution:Dermatology chains with existing laser hair removal infrastructure can repurpose diode consoles for vein procedures with fiber kit conversions.
Industry Challenges
- Interventional radiology training pipelines:Fellowship programs produce fewer venous disease specialists than expanding procedure demand requires, stretching operator capacity.
- EU MDR technical documentation:Clinical evaluation report requirements for laser fiber biocompatibility testing have extended recertification timelines by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endovenous Laser Therapy Market |
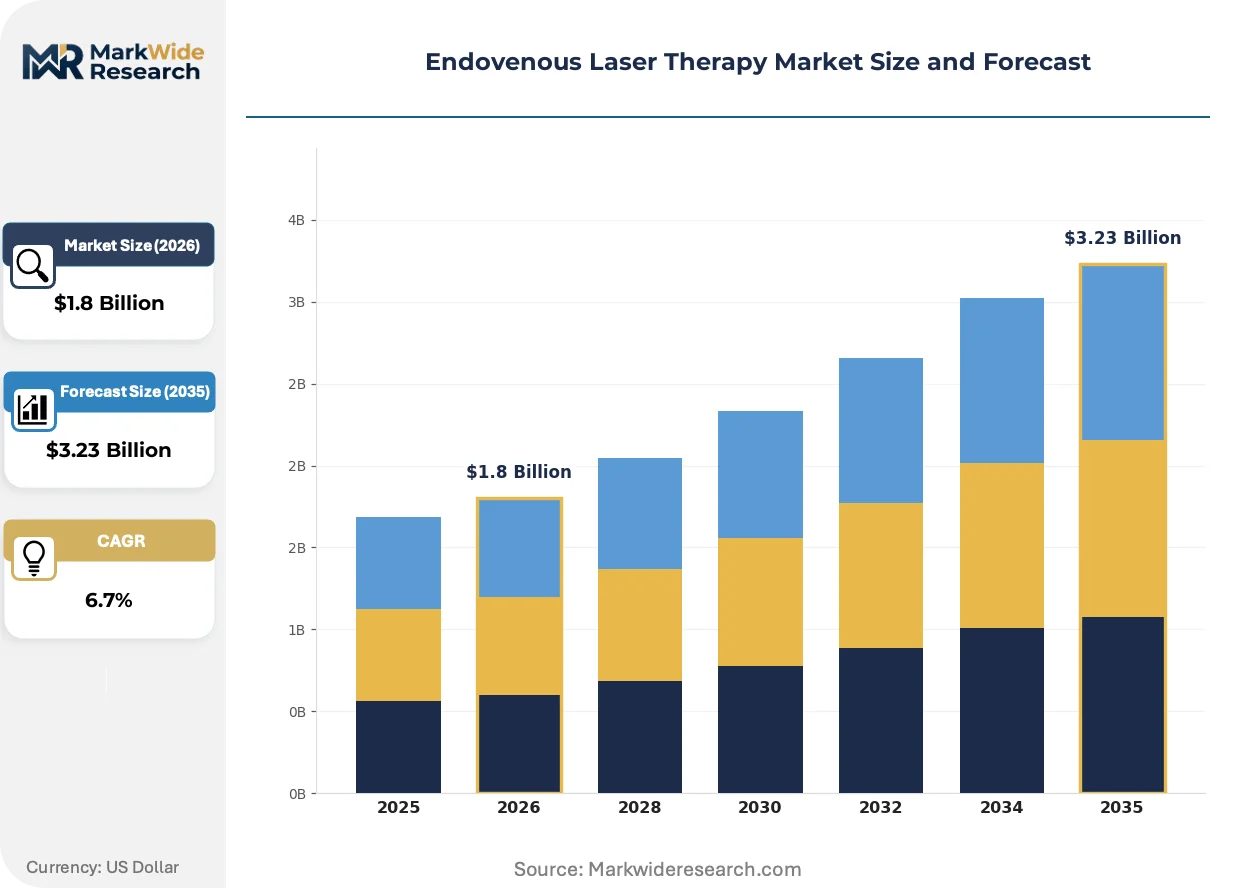
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Fiber Optic Lasers, Accessories, Consumables Application: Varicose Veins, Spider Veins, Venous Insufficiency, Aesthetic Procedures End User: Hospitals, Ambulatory Surgical Centers, Dermatology Clinics, Vein Treatment Centers Technology: Diode Laser, Nd:YAG Laser, Fiber Laser, Pulsed Laser |
| Companies Covered | AngioDynamics, Dornier MedTech, Alma Lasers, Medtronic, biolitec, Syneron Medical, Lumenis, Quanta System, intros Medical Laser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endovenous Laser Therapy Market Emerging Trajectories
Energy delivery precision and procedural workflow compression dominate current development trajectories, with manufacturers racing to reduce post-treatment ecchymosis and same-day patient throughput constraints.
Fiber laser platforms are absorbing market attention from conventional diode systems through tunable pulse duration and radial fiber designs that distribute thermal energy more uniformly along the vessel wall. Ambulatory surgical centers in Texas and Florida are piloting these systems at replacement cycles accelerated by two years versus historical console refresh patterns. The technology is absorbing procedural volume from hospital-based labs as administrators prioritize equipment footprints under fifteen kilograms.
EU Medical Device Regulation enhanced conformity assessment procedures now mandate sterilization validation for single-use laser fibers at the manufacturing site rather than contract sterilizer level. This structural shift has forced three fiber suppliers to relocate ethylene oxide processing capabilities in-house. German notified bodies are experiencing eighteen-month backlog queues, delaying product launches for manufacturers dependent on TÜV SÜD or BSI certification.
Vein treatment centers are consolidating purchasing decisions under centralized procurement officers rather than individual physician preference, compressing vendor relationship fragmentation that previously allowed premium pricing. Large dermatology platforms in California and New York now mandate three-quote minimums for laser fiber contracts exceeding fifty thousand dollars annually. This concentration is most visible in the southeastern United States, where private equity-backed vein clinic rollups have standardized on two preferred device vendors across forty-plus locations.
Endovenous Laser Therapy Market Segmentation
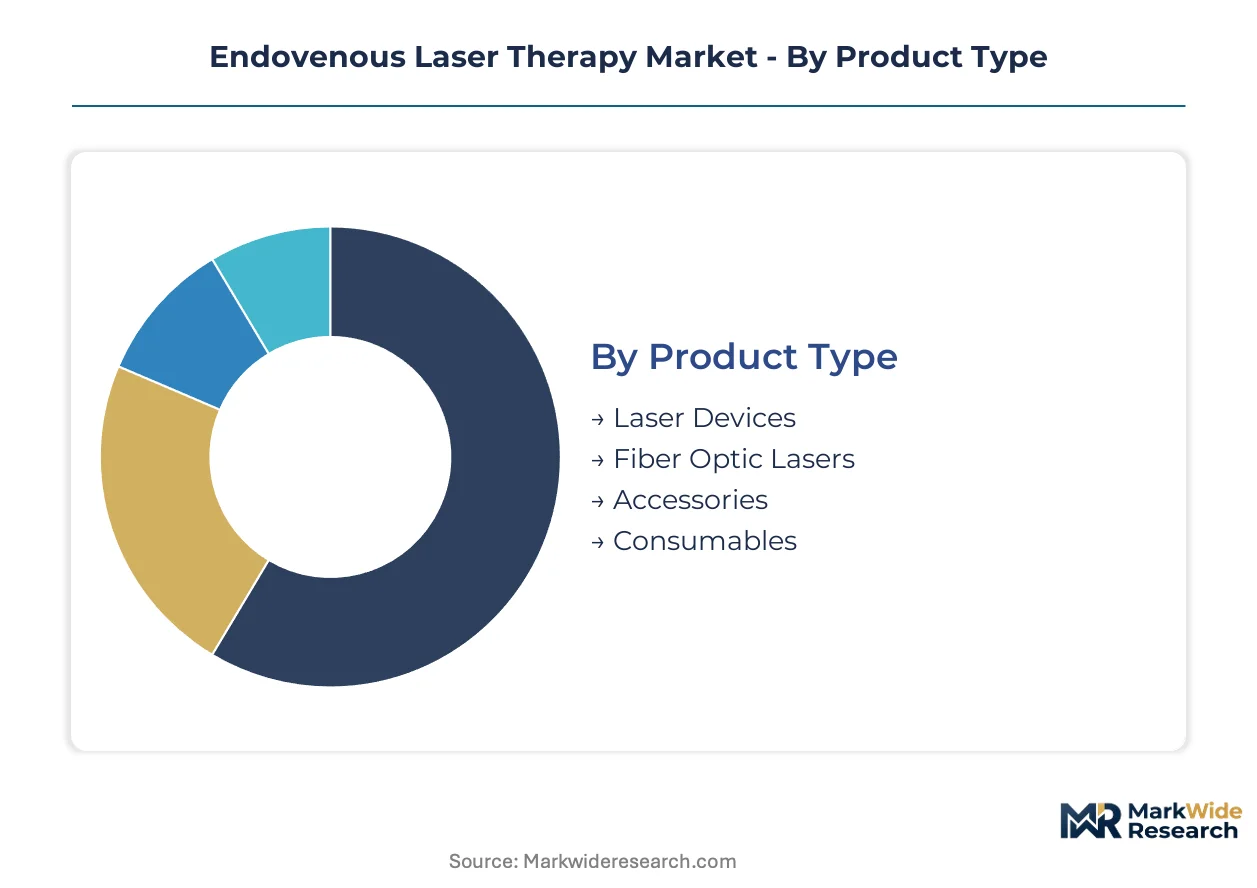
Segmentation in endovenous laser therapy reveals how procurement decisions, reimbursement pathways, and clinical workflows diverge across settings. Understanding these fractures helps vendors align product specifications with buyer economics and regulatory constraints.
Product Type:
Replacement cycles for laser consoles are compressing as ambulatory surgical centers prioritize compact footprints and fiber compatibility over console longevity.
- Laser Devices:Diode-based consoles dominate installed bases through proven truncal vein closure efficacy. Demand clusters in physician-owned surgical centers across Texas and Florida seeking sub-fifteen-kilogram equipment for office-based labs.
- Fiber Optic Lasers:Tunable pulse duration and radial fiber designs distribute thermal energy more uniformly, reducing post-procedural ecchymosis. German outpatient surgical centers are absorbing these systems at accelerated replacement cycles.
- Accessories:Sheath introducers and pullback devices complete procedure sets for integrated system vendors.
- Consumables:Single-use laser fibers and sterile drapes generate recurring revenue streams tethered to procedure volume.
Volume placements concentrate in laser devices; the faster expansion belongs to fiber optic lasers.
Application:
Reimbursement parity between thermal ablation and sclerotherapy shapes procedure mix across Medicare-covered indications.
- Varicose Veins:Great saphenous vein incompetence drives the bulk of thermal ablation volume. Medicare Physician Fee Schedule coverage anchors hospital outpatient department demand in the United States.
- Spider Veins:Cosmetic indication outside reimbursement nets, paid through patient self-pay channels. Aesthetic dermatology chains in California bundle these with laser hair removal services.
- Venous Insufficiency:CEAP clinical class C4-C6 disease qualifies for statutory health insurance coverage in Germany's physician-owned surgical centers.
- Aesthetic Procedures:Non-reimbursed vein treatments leverage existing diode console infrastructure with fiber kit conversions.
Procedure economics favor varicose vein treatments; aesthetic applications are climbing fastest as dermatology platforms cross-sell.
End User:
Site-of-service migration from hospital outpatient departments to lower-cost settings restructures capital equipment purchasing authority.
- Hospitals:Interventional radiology departments maintain high-volume truncal vein programs. Vascular access heritage anchors multi-year service contracts with integrated device vendors.
- Ambulatory Surgical Centers:Lower-cost settings capture expanding margin pools through streamlined workflows. Texas and Florida lead site-of-service shifts with favorable state licensing frameworks.
- Dermatology Clinics:Aesthetic-to-medical crossover channels repurpose existing laser infrastructure for vein procedures.
- Vein Treatment Centers:Private equity-backed rollups in the southeastern United States standardize procurement across forty-plus locations under centralized purchasing officers.
Capital commitments concentrate in ambulatory surgical centers; vein treatment centers are scaling fastest through rollup consolidation.
Technology:
Wavelength diversification at 1470 nm and 1940 nm targets reduced periprocedural pain and faster return-to-work timelines.
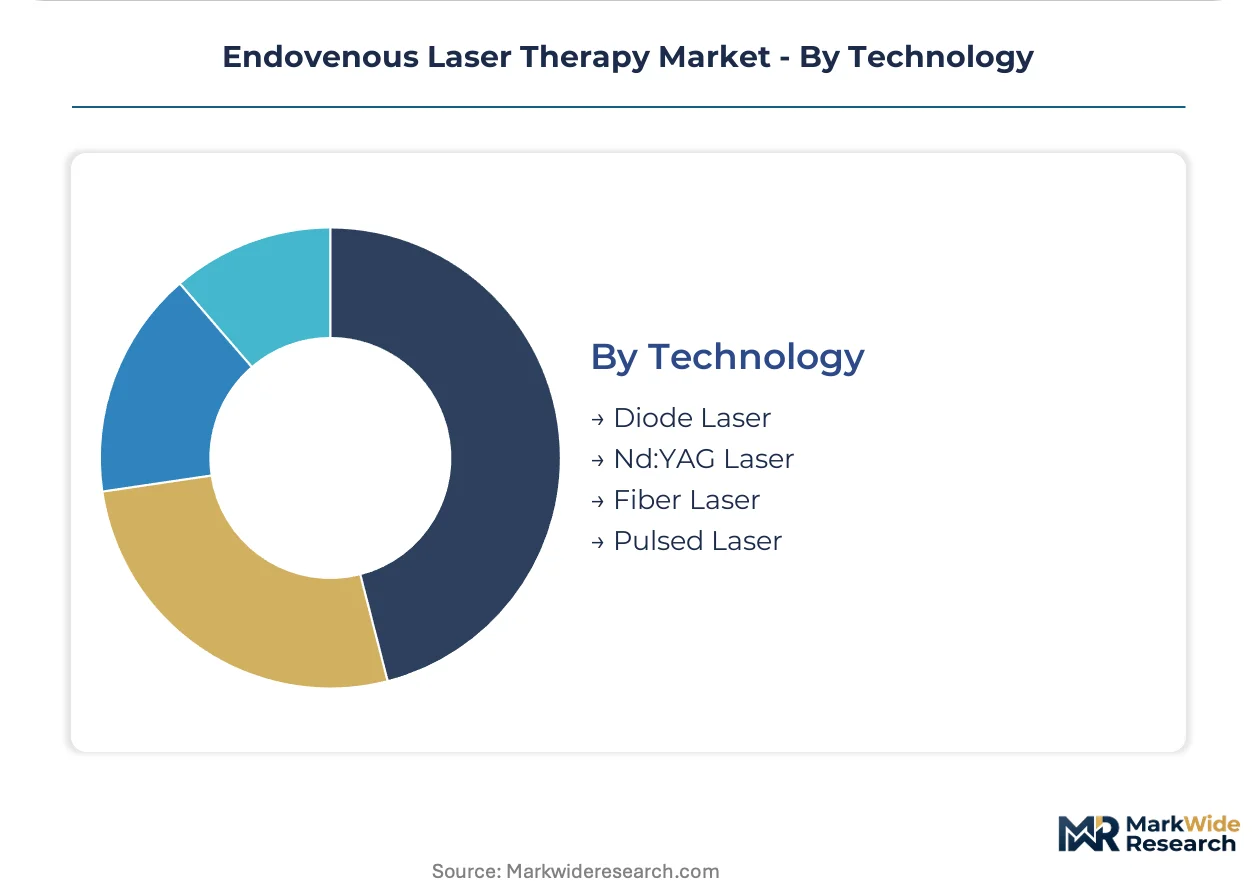
- Diode Laser:810-1470 nm systems occupy dominant technology position through compact console footprints and proven efficacy. Office-based labs across the United States favor these for space-constrained environments.
- Fiber Laser:Precision energy delivery reduces post-treatment bruising through tunable pulse parameters. German notified body certification backlogs have delayed launches for manufacturers dependent on TÜV SÜD.
- Nd:YAG Laser:1064 nm wavelength penetrates deeper tissue for recalcitrant perforator veins.
- Pulsed Laser:Selective photothermolysis targets smaller-caliber vessels without thermal diffusion to surrounding tissue.
Installed base dominance rests with diode systems; fiber laser platforms are expanding most quickly through radial fiber designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silica fiber production clusters in China and Japan anchor the global supply chain for laser catheter manufacturing. Germany's outpatient surgical expansion and the United States' site-of-service migration are reshaping demand geography. Regulatory divergence between FDA 510(k) pathways and EU MDR conformity assessments is fragmenting product launch timelines.
United States
Medicare Physician Fee Schedule adjustments are narrowing margins on thermal ablation procedures. FDA 510(k) clearance pathways for laser fiber iterations have shortened regulatory timelines for established vendors. Ambulatory surgical centers in Texas and Florida are capturing volume from hospital outpatient departments through favorable state licensing frameworks.
Germany
Statutory health insurance coverage for endovenous thermal ablation in physician-owned surgical centers is diverting volume from inpatient settings. EU Medical Device Regulation enhanced conformity assessment procedures mandate sterilization validation at manufacturing sites. German notified bodies are experiencing eighteen-month backlog queues, delaying product launches for manufacturers dependent on TÜV SÜD certification.
China
Domestic production of high-purity silica fiber is reducing import dependency for laser catheter manufacturers. NMPA regulatory harmonization with international standards is streamlining market entry for multinational device vendors. Vascular surgery training programs in Shanghai and Beijing are expanding operator capacity for minimally invasive vein procedures.
India
Vascular surgery training programs in Hyderabad and Chennai are expanding, creating first-mover positioning for compact diode systems. CDSCO medical device registration requirements are evolving toward risk-based classification alignment. Tier-2 cities remain underpenetrated for endovenous procedures, presenting greenfield installation opportunities.
Japan
PMDA regulatory review timelines for laser-based medical devices remain lengthy relative to FDA pathways. METI industrial policy is supporting domestic manufacturing of precision optical components for medical applications. Tokyo and Osaka metropolitan areas concentrate demand for aesthetic-to-medical crossover vein treatments.
Endovenous Laser Therapy Market Vendor Landscape
Procurement consolidation dominates the current landscape as vein treatment centers centralize purchasing decisions under dedicated officers. The vendor base organizes around three strategic archetypes: integrated surgical device conglomerates, aesthetic laser crossover specialists, and vascular access heritage players. M&A activity and geographic licensing agreements represent the primary competitive moves, with private equity-backed clinic rollups driving standardization across multi-location networks.
Among vascular access heritage players, AngioDynamics occupies a position exemplifying hospital contract anchoring. Medtronic represents the scale-driven conglomerate archetype with sustained R&D intensity across energy-based surgical platforms. Alma Lasers sits within the aesthetic-to-medical crossover tier, leveraging existing diode console infrastructure for vein procedure expansion. These three companies illustrate how divergent origin points converge on endovenous market participation through distinct channel strategies.
| Leading Market Players |
|---|
| AngioDynamics |
| Dornier MedTech |
| Alma Lasers |
| Medtronic |
| biolitec |
| Syneron Medical |
| Lumenis |
| Quanta System |
| intros Medical Laser |
| Others |
Supply Flow & Price Mechanics
Private equity-backed vein clinic rollups in the southeastern United States anchor procurement concentration, compressing vendor pricing power toward multi-year service bundles rather than equipment premiums. This buyer consolidation feeds back into supply chain decisions as manufacturers prioritize fiber compatibility over proprietary console lock-in.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier diode systems from unbundled economy alternatives. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) predicate lineage and radial fiber compatibility. Cost compression in standard-tier consoles is intensifying because ambulatory surgical centers prioritize sub-fifteen-kilogram footprints over legacy feature sets. Hospital-based interventional radiology departments exhibit lowest price sensitivity due to multi-year service contract anchoring.
Supply Chain Analysis
High-purity silica fiber production rests on Japanese and Chinese specialty glass manufacturers, with ethylene oxide sterilization capacity clustering in Germany. Laser catheter assembly draws from diode module suppliers in South Korea and optical component fabricators in Japan. Single-source vulnerability concentrates in specialty fiber drawing towers, where two Japanese producers control premium-grade output. Distribution runs through integrated device vendors with direct sales forces to ambulatory surgical centers and GPO-mediated channels to hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The endovenous laser therapy market is becoming a vertical-integration race as manufacturers pursue captive fiber production to escape sterilization bottlenecks and tariff exposure.
For Market Incumbents: Anticipate radiofrequency ablation substitution by accelerating radial fiber laser R&D and securing backward integration into silica fiber drawing capacity. Anchor hospital contracts through vascular access heritage service infrastructure while defending ambulatory surgical center share via compact console refreshes. For New Entrants and Emerging Players: Begin with India's tier-2 cities where vascular surgery training expansion outpaces equipment penetration. Target compact diode systems for Hyderabad and Chennai clinics through distributor partnerships with existing aesthetic laser channels. For Investors and Strategic Acquirers: The window for entry favors aesthetic-to-medical crossover specialists with installed diode console bases and fiber kit conversion capabilities. Watch EU MDR notified body backlog resolution as inflection indicator for German market re-entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Radial Fiber Laser Development | Tunable pulse duration reduces post-procedural ecchymosis, accelerating replacement cycles in Texas and Florida. |
| EU MDR Conformity Assessment | German notified body eighteen-month queues favor established manufacturers with dedicated regulatory infrastructure. |
| Hospital System Partnership | Vascular access heritage anchors multi-year service contracts against radiofrequency ablation substitution. |
| Backward Integration into Fiber Production | In-house silica fiber drawing escapes ethylene oxide sterilization bottlenecks and single-source vulnerability. |
| Reimbursement Strategy | Medicare Physician Fee Schedule parity monitoring protects thermal ablation volumes against sclerotherapy competition. |
Methodological Framework
Multi-period observation of ambulatory surgical center equipment replacement cycles and fiber procurement patterns anchored the trend analysis, supplemented by interviews with interventional radiologists, vein clinic procurement officers, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, CMS Medicare Physician Fee Schedule data, hospital procurement databases, and EU MDR notified body certification records. Bottom-up procedure volume estimates triangulated against top-down equipment installed base calculations.
Input-output matrices modeled laser console placements against fiber consumption rates across the analysis window, with segmentation by wavelength technology, end-user setting, and geographic regulatory cluster. CAGRs derived from logistic diffusion curves fitted to ambulatory surgical center adoption patterns and replacement cycle compression trends. Forecast inputs incorporated EU MDR recertification timeline assumptions and Medicare reimbursement adjustment trajectories.
Underlying measurement precision varies by segment; ambulatory surgical center volume estimates carry tighter precision than aesthetic procedure self-pay channels. Forecasts reflect documented assumptions regarding wavelength diversification adoption curves and site-of-service migration velocity. Reimbursement parity shifts, notified body backlog resolution, and fiber supply concentration disruptions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Hepatocellular Carcinoma (HCC) Treatment Market
Medical Treatment
Thyroid Gland Disorders Treatment Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Congenital Hyperinsulinism Treatment Market
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Scalp Care Treatment Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
North America Breast Reconstruction Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Non-Invasive Surgery Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Hypothermia Management Market
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Nasal Allergy Treatment Market