
 Global Drone Logistics and Transportation Market | 2026-2036
Global Drone Logistics and Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drone Logistics and Transportation Market Intelligence
The rigorous process for achieving Beyond Visual Line of Sight (BVLOS) type certification is reorganizing market access for drone operators. Zipline International Inc. leverages its extensive operational experience in medical delivery in Africa and the US to secure these advanced approvals. Meanwhile, Wing Aviation LLC positions its technology for urban package delivery demonstrations in Australia and the United States. Matternet Inc. specializes in integrated station-to-station networks for healthcare facilities in Switzerland and Germany.
Drone logistics and transportation is the use of unmanned aerial vehicles (UAVs) for the autonomous movement of goods. Key system parameters include payload capacity, often under 5 kg for last-mile delivery, and operational flight endurance. Medical supply transport applications show mature operational models, while package delivery represents the largest long-term volume opportunity. E-commerce platforms and logistics providers are the principal end users driving investment in new delivery networks.
Regulatory frameworks from the US Federal Aviation Administration (FAA) and Japan's Civil Aeronautics Law revisions define critical operational boundaries for BVLOS flights. In parallel, the EU's U-space regulations establish a standardized traffic management system to integrate drones safely into European airspace. Success for operators will depend on developing platforms that comply with these evolving, often disparate, international air safety and data privacy standards.
Market Dynamics
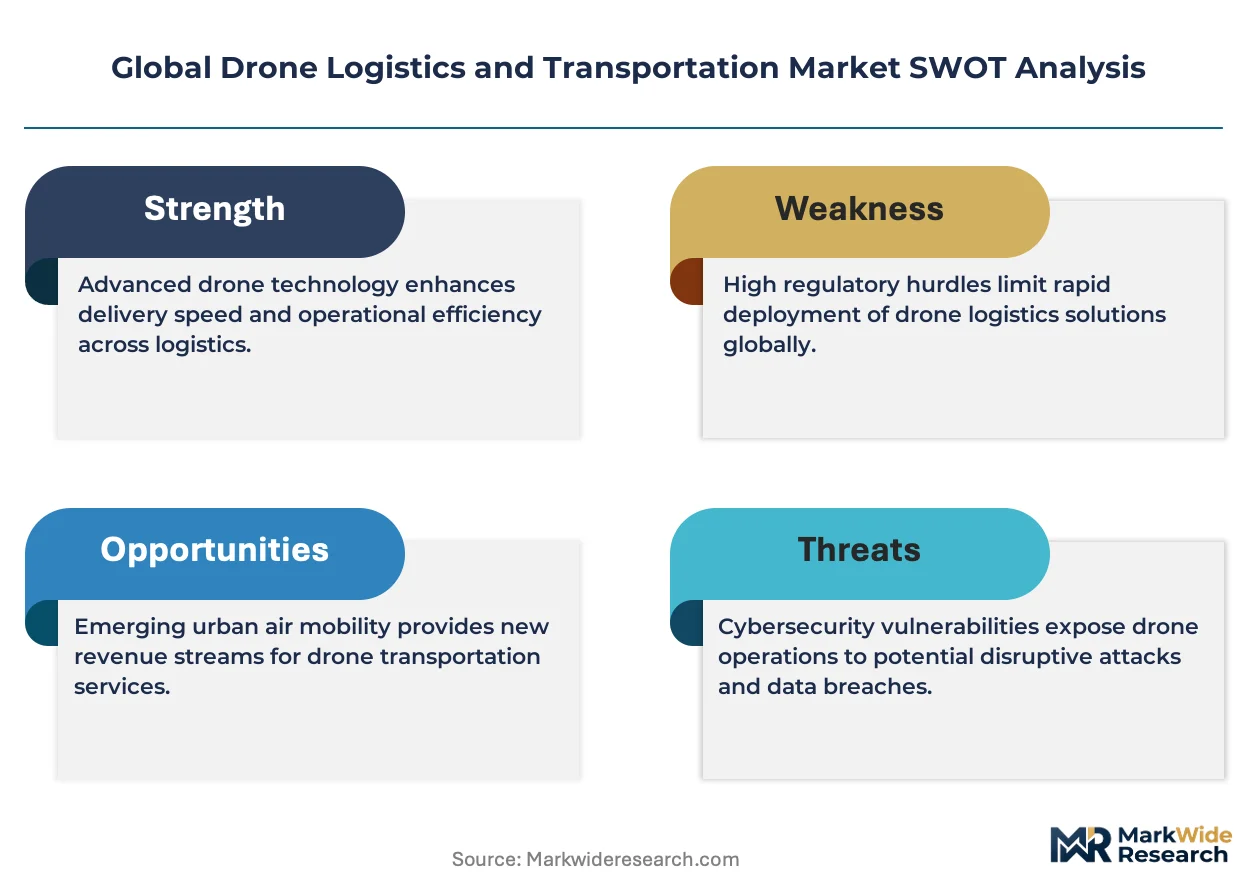
The global race to establish and harmonize regulatory frameworks for Beyond Visual Line of Sight operations is the central force shaping the market. This regulatory progress directly governs market access, operational scale, and the viability of commercial drone delivery networks.
Growth Catalysts
- Favorable Regulatory Frameworks:Japan's implementation of a legal structure for Level 4 drone flights provides a clear, replicable model for commercialization, encouraging investment and deployment within its borders.
- High-Value Medical Applications:Urgent demand within the healthcare sector for transporting time-sensitive materials like lab samples and pharmaceuticals creates a strong, non-discretionary use case that justifies investment in drone networks.
- Enabling Technology Maturation:Advances in onboard detect-and-avoid sensors and automated air traffic management platforms provide the technical safety case required by regulators like the FAA for approving complex BVLOS operations.
Market Restraints
- Onboard Power Limitations:The energy density of current battery technology restricts flight endurance and payload capacity, limiting operational range and the economic viability of transporting heavier goods over long distances.
- Fragmented Regulatory Approvals:Disparate and evolving air safety standards between authorities like the US FAA and the EU's U-space framework create compliance challenges for operators seeking to scale operations across multiple countries.
- High Capital Costs:Significant upfront investment is required for type-certified aircraft, certified ground control stations, and the rigorous engineering documentation needed to achieve airworthiness and operational approvals.
Strategic Opportunities
- Industrial Logistics Niche:Transporting spare parts, tools, and inspection equipment to remote industrial sites, such as offshore energy platforms or mines, presents a high-value opportunity underserved by traditional logistics.
- Archipelago Connectivity:Southeast Asian nations with challenging inter-island geography offer a significant market for drone logistics to bypass congested or nonexistent ground and sea infrastructure for essential goods.
- 5G Network Integration:The convergence of drone command systems with low-latency 5G cellular networks enables reliable, high-bandwidth connectivity essential for managing dense drone traffic in complex urban environments.
Industry Challenges
- Specialized Talent Scarcity:A shortage of pilots, maintenance technicians, and software engineers with certifications and experience in BVLOS systems and type-certified aircraft constrains operational scaling for service providers.
- Legacy System Integration:Integrating autonomous drone networks with the existing warehouse management and enterprise resource planning systems of large logistics and e-commerce clients poses a significant technical hurdle.
- Public Acceptance and Noise:Addressing community concerns over noise pollution, data privacy, and perceived safety risks is critical to securing local flight permissions and avoiding operational roadblocks in residential areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drone Logistics and Transportation Market |
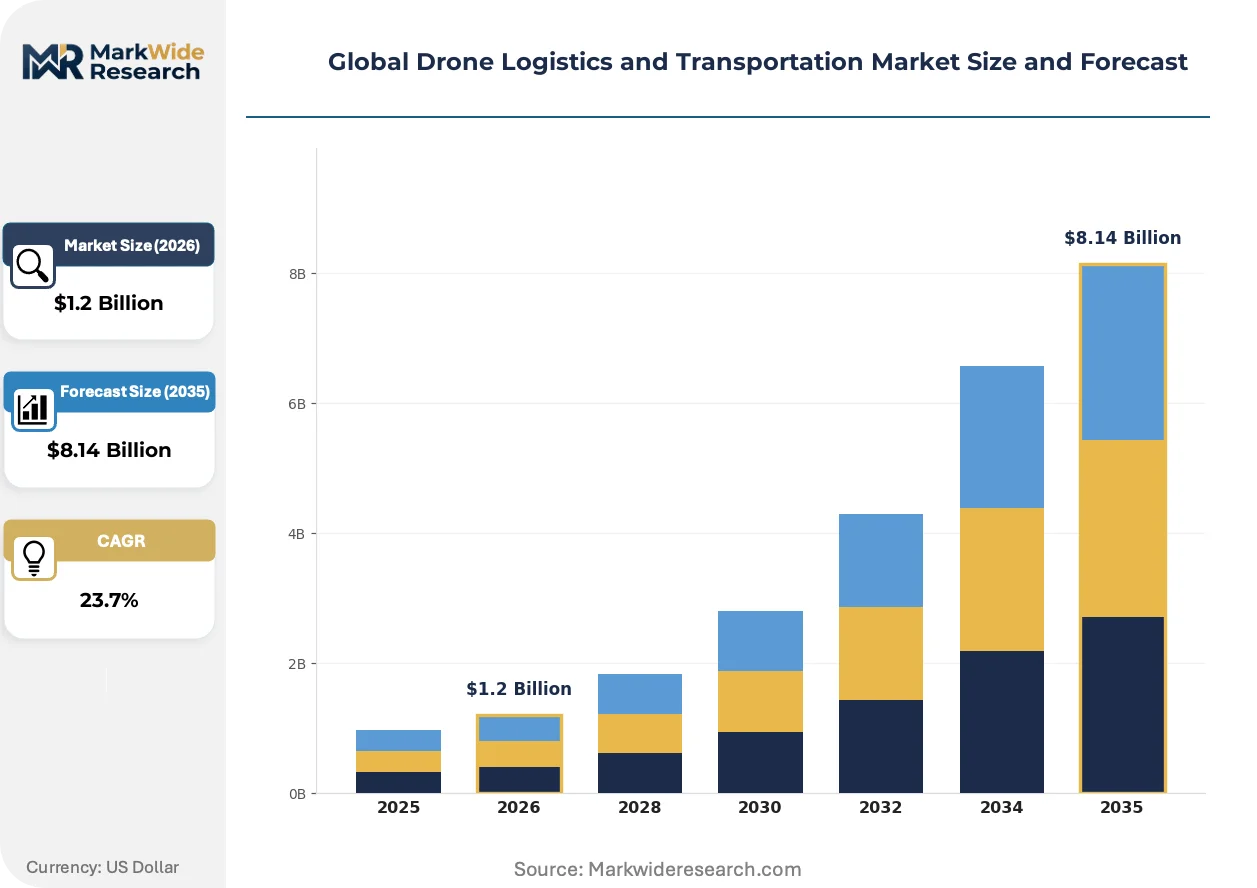
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $8.14 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing Drones, Multirotor Drones, Hybrid Drones, Single-Rotor Drones, Micro Drones Application: Package Delivery, Medical Supply Transport, Agricultural Monitoring, Infrastructure Inspection, Emergency Response End User: E-Commerce Platforms, Logistics Providers, Pharmaceutical Companies, Agriculture Firms, Public Safety Agencies Deployment Model: On-Premises Control, Cloud-Based Management, Hybrid Systems, Mobile Command Centers, Dedicated Network Operations |
| Companies Covered | Zipline International Inc., Wing Aviation LLC, Matternet Inc., Drone Delivery Canada Corp., United Parcel Service of America, Inc., Flytrex Inc., Hardis Group, Amazon.com, Inc., Volocopter GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drone Logistics and Transportation Market Strategic Shifts & Innovations
The market is reshaping as it transitions from pilot programs to the deployment of scalable, economically viable delivery networks. This evolution is driven by a confluence of maturing automation technology, clearer regulatory pathways, and new commercial models.
Autonomous ground infrastructure provides automated docking, charging, and package-handling capabilities. Logistics providers and healthcare networks are adopting these systems to improve operational efficiency. This automated support infrastructure is displacing the manual battery swapping and ground crew intervention that created significant labor costs and bottlenecks in early drone delivery models.
The European Union's U-space regulation establishes a common framework for managing drone traffic, mandating a set of digital services for safe airspace integration. This policy forces the development of a standardized technical ecosystem for drone operations. Consequently, operators targeting European markets must invest in aircraft and systems compatible with certified U-space Service Providers.
A notable behavioral shift involves end-users moving from ad-hoc, project-based drone services to long-term, network-level contracts. The transactional model for one-off flights is being superseded by integrated partnerships between operators and clients for dedicated, scheduled routes. This trend is most advanced in the medical logistics sector in Switzerland and Germany, where permanent links connect hospital campuses.
Global Drone Logistics and Transportation Market Segmentation
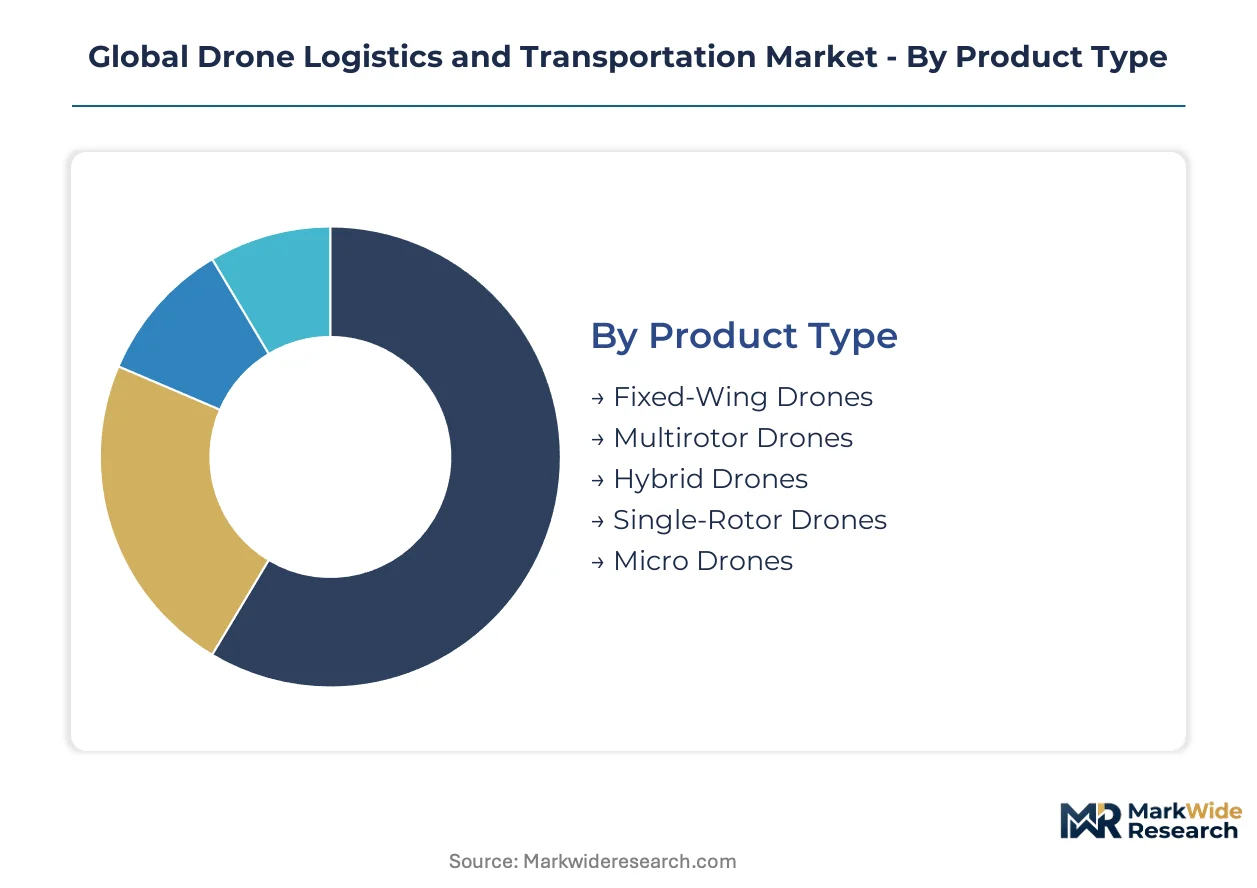
The global drone logistics and transportation market segments reveal distinct operational requirements and commercial opportunities. Understanding these divisions helps operators and investors identify areas of high growth potential and specific technological needs for market entry. Each segment addresses unique challenges in goods movement.
Product Type:
The market faces substitution pressure from traditional logistics methods, particularly for payload capacities exceeding drone limitations. Drone product types are continually evolving to address these operational constraints.
- Fixed-Wing Drones:These UAVs feature a rigid wing structure that generates lift through forward motion, enabling longer flight durations and higher payload capacities compared to multirotor designs. Demand concentrates in long-range medical deliveries and industrial inspections where extended reach is critical.
- Multirotor Drones:Characterized by multiple propellers, these drones offer superior vertical takeoff and landing (VTOL) capabilities and precise hovering, making them ideal for last-mile package delivery in urban environments. E-commerce platforms in dense population centers drive their deployment.
- Hybrid Drones:Combining features of fixed-wing and multirotor designs, hybrid drones offer both VTOL capabilities and efficient forward flight for varied operational profiles. Their versatility suits diverse logistics tasks.
- Single-Rotor Drones:These drones resemble small helicopters, providing efficient lift and stability for specialized heavy-lift applications or confined space operations. Industrial logistics often utilize this design.
- Micro Drones:Extremely small and lightweight, micro drones are typically used for highly localized, short-distance deliveries or internal warehouse logistics. They address niche, on-demand transport needs.
Multirotor Drones retains volume leadership; Hybrid Drones holds the steepest expansion curve.
Application:
Application segments are differentiated by the specific operational context and the value proposition of drone delivery. Each application demands tailored drone capabilities and regulatory compliance.
- Package Delivery:This application involves the autonomous transport of consumer goods, small parcels, and e-commerce orders directly to customers or distribution points. The largest long-term volume opportunity exists within this segment, driven by convenience and speed.
- Medical Supply Transport:Drones deliver time-sensitive materials such as lab samples, pharmaceuticals, vaccines, and blood products to hospitals, clinics, and remote locations. Operational models are mature in regions like Switzerland and Germany due to urgent healthcare demand.
- Agricultural Monitoring:Drones provide aerial surveillance for crop health, livestock management, and field analysis, though direct logistics remain a developing area. Precision agriculture benefits from their data collection capabilities.
- Infrastructure Inspection:UAVs are used to inspect critical infrastructure like power lines, pipelines, and bridges, reducing human risk and improving efficiency. This application supports maintenance logistics by identifying needs.
- Emergency Response:Drones assist in disaster relief by delivering essential supplies, medical aid, or communication equipment to inaccessible areas. Public safety agencies are key end users.
Package Delivery currently dominates the market; Medical Supply Transport exhibits strong operational maturity.
End User:
End-user segments are distinguished by their primary business objectives and the scale of their logistics operations. Each user type drives specific requirements for drone system integration and service models.
- E-Commerce Platforms:These companies leverage drone logistics to enhance last-mile delivery speed and customer satisfaction for online purchases. They are principal drivers of investment in new delivery networks.
- Logistics Providers:Traditional logistics firms integrate drone services to optimize their supply chains, reduce delivery times, and access remote areas. They seek efficient, scalable drone solutions for diverse cargo.
- Pharmaceutical Companies:These firms utilize drones for secure and rapid transport of high-value, temperature-sensitive medical products to healthcare facilities. Regulatory compliance for cold chain is paramount.
- Agriculture Firms:Agricultural businesses employ drones for tasks ranging from crop spraying to monitoring, with increasing interest in direct farm-to-market transport of fresh produce. Operational efficiency is a key driver.
- Public Safety Agencies:Government entities use drones for emergency response, search and rescue, and critical infrastructure support. Reliability and rapid deployment are essential.
E-Commerce Platforms are driving significant investment; Logistics Providers are integrating drone capabilities for operational efficiency.
Deployment Model:
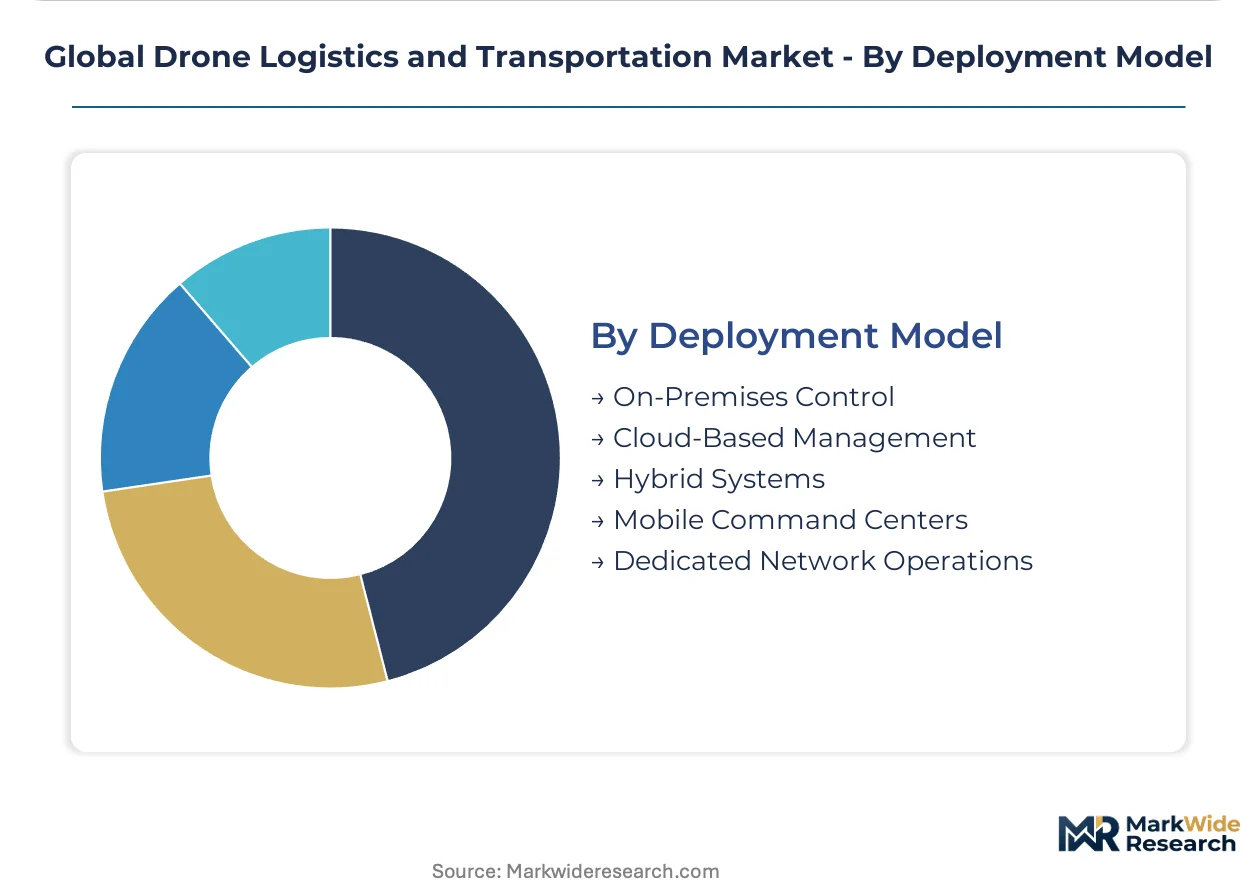
Deployment models reflect the operational architecture and control mechanisms for drone fleets, influencing scalability, security, and integration with existing IT infrastructure. Cloud-based systems offer greater flexibility.
- Cloud-Based Management:This model uses remote servers and internet connectivity to manage drone operations, flight planning, and data processing, offering scalability and accessibility. It enables real-time monitoring of distributed fleets.
- Dedicated Network Operations:Operators establish proprietary infrastructure and control centers specifically for drone logistics, often for high-volume or specialized routes. This model ensures robust control and security for critical operations.
- On-Premises Control:Drone operations are managed using local hardware and software installed at the user's facility, offering direct control and data sovereignty. This model suits smaller-scale or sensitive operations.
- Hybrid Systems:These models combine elements of both on-premises and cloud-based control, balancing local data processing with cloud scalability. They offer flexibility for varying operational needs.
- Mobile Command Centers:Portable units equipped for drone launch, recovery, and control, often deployed for temporary or rapidly changing operational environments. Emergency response scenarios frequently use these.
Cloud-Based Management offers significant scalability; Dedicated Network Operations provide robust control for specialized services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Policy harmonization efforts and government incentives are accelerating the commercialization of drone logistics across diverse geographies. These initiatives provide the necessary regulatory certainty for operators to scale advanced BVLOS operations. Countries with proactive legal frameworks are attracting significant investment in drone delivery networks.
Japan
Demand for efficient logistics in remote areas and for time-sensitive deliveries drives drone adoption. Japan's Civil Aeronautics Law revisions establish a legal framework for Level 4 drone flights. Tokyo and its surrounding prefectures are seeing pilot projects for urban package delivery and medical supply transport.
United States
E-commerce platforms and healthcare providers seek faster last-mile delivery and critical medical transport solutions. The US Federal Aviation Administration (FAA) focuses on securing advanced BVLOS operational approvals. Companies like Zipline and Wing Aviation are conducting extensive trials in various states, including North Carolina and Texas.
Germany
Healthcare logistics and industrial applications are creating a strong market for drone services. The EU's U-space regulations and German aviation authorities define the framework for drone integration. Cities such as Berlin and Munich are hubs for developing urban air mobility concepts and specialized medical drone routes.
Switzerland
High-value medical supply transport and inter-hospital logistics represent primary demand drivers. Swissmedic and the national aviation authority have enabled advanced operational models for medical drones. Matternet operates integrated station-to-station networks connecting healthcare facilities across major Swiss cities.
China
Rapid urbanization and a vast e-commerce market are fueling demand for scalable drone delivery solutions. Chinese regulators are developing policies to support large-scale commercial drone operations and airspace integration. Major technology companies in Shenzhen and Hangzhou are heavily investing in drone logistics infrastructure and pilot programs.
Global Drone Logistics and Transportation Market Key Industry Players
Player mix skews toward specialized logistics providers and technology developers rather than solely traditional aerospace manufacturers. The market structure is currently fragmented, with numerous startups focusing on niche applications and regional deployments, while larger players position for broader scale. Strategic archetypes include dedicated medical logistics operators, urban package delivery innovators, and platform providers for drone traffic management and airspace integration. Companies are primarily engaged in strategic partnerships to pool resources for regulatory approvals and technology licensing to accelerate market entry and expand their operational footprint.
Specialists in advanced BVLOS operations include Zipline International Inc., which exemplifies a medical logistics operator with extensive operational experience in challenging environments. Wing Aviation LLC represents an innovator in urban package delivery, focusing on last-mile solutions and demonstrating its technology in various global markets. Matternet Inc. further highlights the specialized medical logistics archetype, developing integrated station-to-station networks for healthcare facilities with a strong European presence. These providers are actively working to establish scalable, commercially viable drone delivery services by navigating complex regulatory landscapes and building robust operational models.
| Leading Market Players |
|---|
| Zipline International Inc. |
| Wing Aviation LLC |
| Matternet Inc. |
| Drone Delivery Canada Corp. |
| United Parcel Service of America, Inc. |
| Flytrex Inc. |
| Hardis Group |
| Amazon.com, Inc. |
| Volocopter GmbH |
| Others |
Cost & Logistics Intelligence
Operational efficiency from high-volume drone networks directly influences supply concentration, establishing competitive price floors for last-mile delivery services. This dynamic shapes both service provider revenue models and end-user adoption rates.
Pricing Analysis
BVLOS operational certification creates the primary spread in drone logistics pricing, distinguishing advanced operators from basic line-of-sight services. The dominant pricing model is a hybrid of per-flight transactional fees and long-term subscription contracts for dedicated routes. Price differentiation stems from payload capacity, operational range, and guaranteed delivery times. Pricing pressure intensifies from traditional logistics providers seeking to maintain market share, while medical supply transport exhibits lower price sensitivity compared to high-volume e-commerce applications.
Supply Chain Analysis
Short lead times are critical for specialized drone components, impacting the rapid deployment of new fleets and maintenance schedules. Supply concentration for advanced drone manufacturing centers in China, the United States, and specific European nations. Raw material dependencies include high-energy density battery cells, lightweight composite materials, and sophisticated sensor arrays. Regulatory fragmentation across national airspaces presents a significant structural risk for global supply chains; downstream distribution typically runs through direct-to-customer models or dedicated hub-and-spoke networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drone logistics market presents a fragmentation opportunity, driven by diverse end-user demands for specialized payload capacities and operational ranges. This shift creates distinct niches for focused service providers.
For Market Incumbents: Shield core medical delivery routes by securing long-term, outcome-based contracts with healthcare networks like those in Switzerland and Germany. Invest in advanced BVLOS certification across multiple geographies to counter emerging localized competitors and regulatory arbitrage. Expand into industrial logistics niches, such as offshore platform resupply, to mitigate reliance on urban package delivery. Control critical ground infrastructure development to create operational barriers to entry.
For New Entrants and Emerging Players: Unaddressed industrial logistics for remote site delivery represents a significant service-layer gap where incumbents under-serve due to complex operational requirements. Target archipelago connectivity in Southeast Asian nations, bypassing traditional infrastructure limitations. Focus on developing hybrid drone platforms that combine VTOL with longer-range capabilities. A go-to-market angle could involve offering specialized, high-value cargo transport with guaranteed service level agreements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized BVLOS platform developers and integrated U-space compatible software providers. Long-term viability rests on operators achieving regulatory scale and cost-efficient autonomous ground operations. Acquisition targets should include companies with proven operational experience in medical supply transport or unique intellectual property in detect-and-avoid systems. The signal to watch is the widespread adoption of standardized U-space regulations across major economic blocs.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | Securing BVLOS certifications from authorities like the FAA enables expanded operational reach for commercial drone services. |
| Ground Infrastructure Development | Investing in automated docking and charging stations improves operational efficiency and reduces labor costs for drone fleets. |
| Strategic Partnership | Collaborating with e-commerce platforms or logistics providers ensures high-volume demand and integrated network access. |
| Platform Integration | Developing systems compatible with EU's U-space regulations allows seamless integration into European airspace management. |
| Niche Market Entry | Targeting industrial logistics for remote sites provides high-value revenue streams underserved by traditional transport methods. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to establish a robust market perspective. Primary interviews with drone service executives, logistics managers, regulatory experts, and e-commerce fulfillment leads provided qualitative insights. This was triangulated with secondary data from FAA regulatory documents, EU U-space specifications, company financial reports, and academic studies on drone technology. A combination of bottom-up and top-down approaches validated market sizing and growth projections.
The analytical framework spanned the projection horizon, modeling market dynamics across various product types, applications, end users, and deployment models. Geographic regions and payload capacity tiers were also key segmentation dimensions. Compound annual growth rates were derived from historical trends, regulatory milestones, and technological adoption curves. Key forecast inputs included BVLOS approval rates and e-commerce growth projections.
Material uncertainties — unforeseen regulatory shifts, rapid battery technology breakthroughs, or shifts in public acceptance — sit outside the modeled envelope. Forecasts reflect assumptions documented at the time of analysis regarding market evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Russia Freight and Logistics Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
Middle Mile Delivery Market
Logistics and Shipping
Chile Third-Party Logistics (3PL) Market
Logistics and Shipping
United States Cold Chain Logistics Market
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
Iraq Logistics Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
Air Cargo Market
Logistics and Shipping
Saudi Arabia Freight and Logistics Market
Logistics and Shipping
Brazil Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
United States Courier, Express and Parcel (CEP) Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market