
 APAC Contract Logistics Market | 2026-2036
APAC Contract Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Contract Logistics Market Insights
The gap between premium technology-integrated contract logistics and commodity freight forwarding is restructuring competitive tiers across APAC. Deutsche Post DHL Group leverages its regional automation footprint to anchor high-margin warehousing contracts. CJ Logistics sustains dominance in South Korean automotive inbound logistics through dedicated just-in-time delivery corridors. Nippon Express differentiates via cold-chain specialization serving Japanese pharmaceutical exporters.
Contract logistics encompasses integrated outsourcing of transportation, warehousing, inventory management, and value-added services under multi-year agreements with measurable service-level parameters including order accuracy rates and inventory turnover benchmarks. The primary commercial purpose centers on converting fixed supply chain infrastructure costs into variable operating expenditures while improving fulfillment velocity. Warehousing services command the largest revenue pool within service-type segmentation due to escalating real estate costs in Shanghai, Singapore, and Tokyo gateway markets. eCommerce companies represent the fastest-expanding end-user category as platform operators require distributed fulfillment nodes to meet same-day delivery commitments. Hybrid delivery models are displacing purely centralized networks across mid-market retailers seeking cost flexibility without sacrificing regional coverage density.
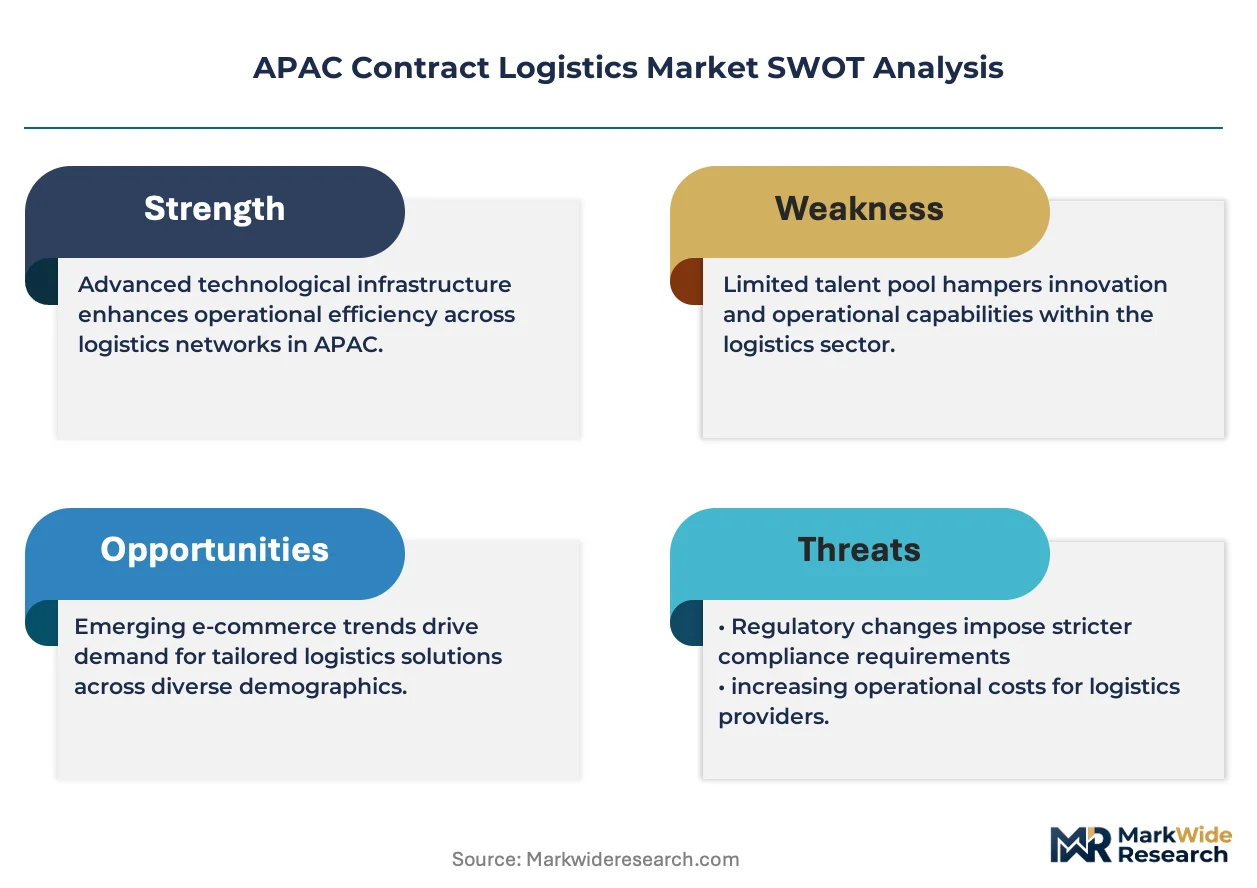
China's SAMR enforces national logistics data security standards that restrict cross-border warehouse management system architectures. Japan's METI promotes supply chain resilience guidelines incentivizing dual-sourcing of contract logistics providers. India's BIS certification requirements for cold-chain equipment shape pharmaceutical logistics procurement criteria. Stakeholders must evaluate regulatory fragmentation alongside technology integration roadmaps when selecting regional operating partners.
Market Dynamics
China's MIIT digital infrastructure mandates are forcing warehouse automation compliance across the APAC contract logistics sector, compressing technology adoption timelines and reshaping competitive positioning between integrated providers and commodity freight operators.
Growth Catalysts
- Automotive OEM expansion:Southeast Asian vehicle manufacturers are expanding outsourced logistics partnerships to manage inbound just-in-time component flows and finished vehicle distribution through dedicated delivery corridors.
- MIIT warehouse automation mandates:China's Ministry of Industry and Information Technology requirements for digital infrastructure integration are accelerating robotics deployment and warehouse management system upgrades.
- eCommerce fulfillment node proliferation:Platform operators across Vietnam's northern manufacturing corridor near Hanoi and Hai Phong are demanding distributed fulfillment infrastructure to meet same-day delivery commitments.
Market Restraints
- Escalating gateway real estate costs:Industrial warehouse rents in Shanghai, Singapore, and Tokyo are compressing operating margins for third-party logistics providers unable to pass through occupancy cost increases.
- SAMR data architecture restrictions:China's State Administration for Market Regulation enforces national logistics data security standards that limit cross-border warehouse management system architectures and increase compliance overhead.
- Cold-chain equipment certification timelines:India's BIS certification requirements for pharmaceutical cold-chain equipment extend procurement cycles and constrain rapid network expansion.
Strategic Opportunities
- Vietnam northern corridor concentration:Manufacturing clustering near Hanoi and Hai Phong creates demand for integrated contract logistics services spanning inbound materials handling, warehousing, and export consolidation.
- METI supply chain resilience incentives:Japan's Ministry of Economy, Trade and Industry guidelines promoting dual-sourcing of contract logistics providers open secondary supplier positions for qualified regional operators.
- Hybrid delivery model adoption:Mid-market retailers across South Korea and Taiwan are adopting distributed fulfillment networks combining centralized inventory with regional micro-fulfillment nodes.
Industry Challenges
- Warehouse automation integration complexity:Legacy facility footprints across Southeast Asia require substantial retrofitting to accommodate autonomous mobile robots and automated storage and retrieval systems.
- Pharmaceutical cold-chain technician scarcity:Qualified personnel for temperature-controlled logistics operations remain concentrated in Japan and South Korea, limiting network expansion into emerging ASEAN markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Contract Logistics Market |
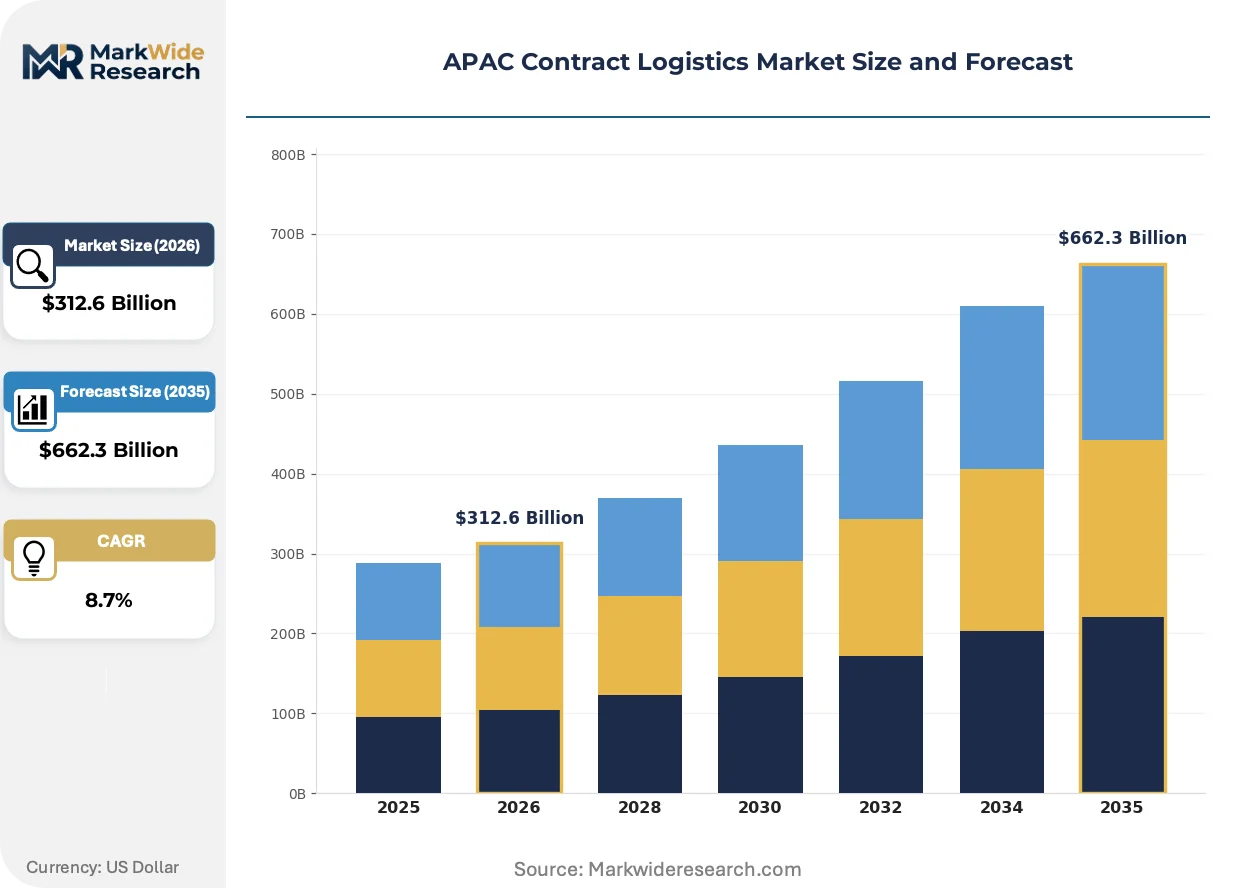
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Order Fulfillment, Value-Added Services End User: Automotive OEMs, eCommerce Companies, Retailers, Pharmaceuticals Delivery Model: Centralized, Decentralized, Hybrid, Just-in-Time Technology: Warehouse Management Systems, RFID, Automation, IoT |
| Companies Covered | DSV, Deutsche Post DHL Group, Kuehne + Nagel, CEVA Logistics, Nippon Express, CJ Logistics, Logisteed Ltd, DB Schenker, Toll Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Contract Logistics Market Trends and Innovations
Automation convergence with regulatory data mandates is actively restructuring operational requirements across APAC contract logistics, compressing technology investment timelines while opening capability differentiation between integrated and commodity service tiers.
Autonomous mobile robots integrated with warehouse management systems are decentralizing fulfillment operations across mid-market retail networks. eCommerce platform operators in Vietnam and Thailand are deploying these systems at accelerated pace to enable same-day delivery commitments without centralized mega-warehouse dependency. The structural consequence is fragmenting inventory positioning toward regional micro-fulfillment nodes.
METI supply chain resilience guidelines in Japan are mandating dual-sourcing frameworks for critical logistics infrastructure. Pharmaceutical exporters and automotive component suppliers must now qualify secondary contract logistics providers, expanding vendor rosters beyond incumbent relationships. Cold-chain specialization and dedicated automotive corridors face the most immediate compliance pressure.
Buyer procurement patterns are compressing contract duration and shifting toward performance-indexed pricing structures. Retail and consumer electronics verticals across South Korea and Australia are unbundling long-term warehousing agreements into shorter-cycle engagements tied to order accuracy rates and inventory turnover benchmarks. This rotation is most visible among omnichannel retailers seeking cost flexibility without sacrificing regional coverage density.
APAC Contract Logistics Market Segmentation
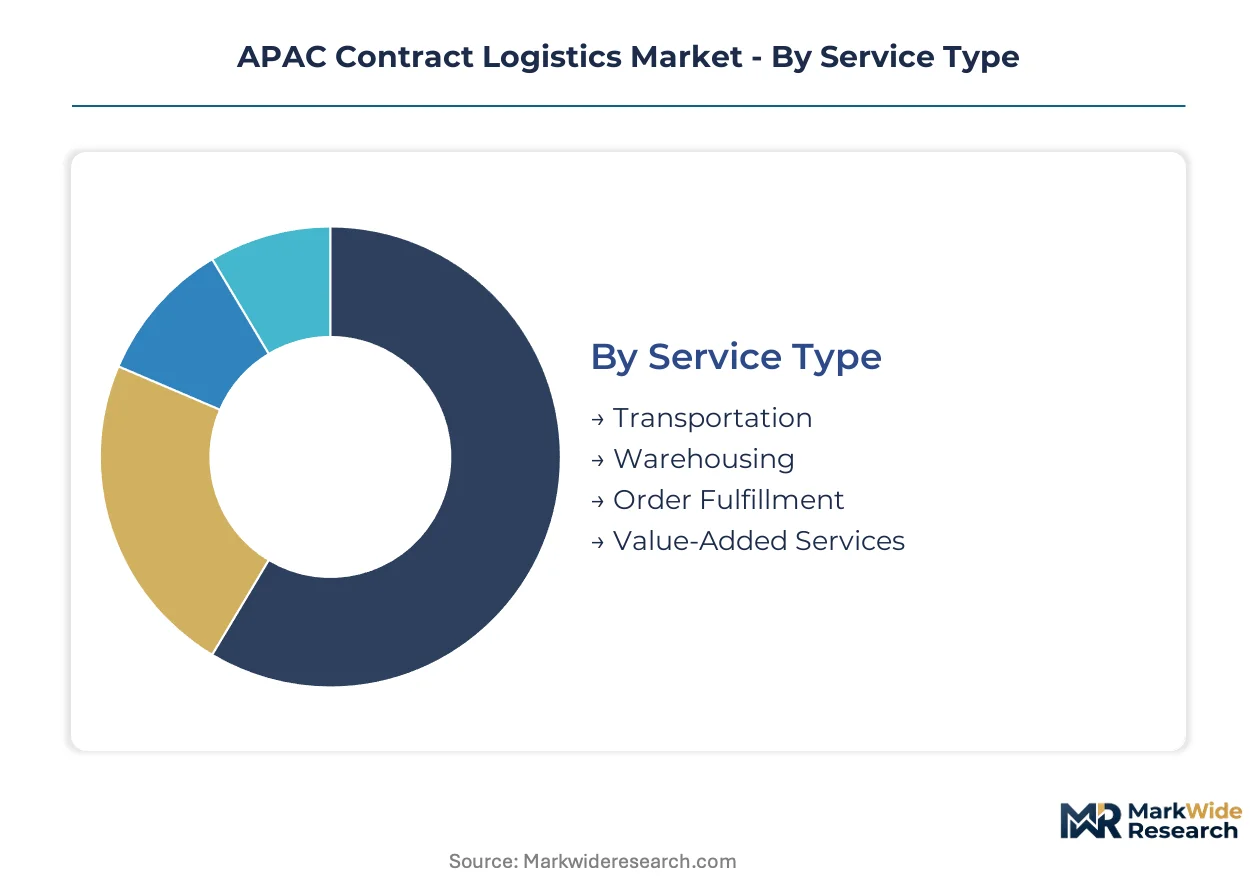
APAC contract logistics providers structure service portfolios around distinct operational capabilities and customer risk profiles. Segment boundaries increasingly blur as automation mandates and eCommerce velocity requirements force capability convergence across traditional service categories.
Service Type:
Warehousing commands premium pricing power against transportation commoditization.
- Warehousing:Dedicated and multi-client facilities with automated storage and retrieval systems anchor revenue pools. Shanghai, Singapore, and Tokyo gateway markets concentrate demand as industrial rents escalate and MIIT compliance mandates accelerate robotics deployment.
- Transportation:Fleet-based and brokered freight services span road, rail, and intermodal corridors. Vietnam's northern manufacturing corridor near Hanoi and Hai Phong drives dedicated lane contracting as automotive OEMs expand outsourced inbound logistics partnerships.
- Order Fulfillment:Pick-pack-ship operations with same-day delivery SLAs. eCommerce platform operators across Southeast Asia deploy these services at accelerated pace to meet delivery commitments without centralized mega-warehouse dependency.
- Value-Added Services:Kitting, labeling, quality inspection, and returns processing. Retailers seeking cost flexibility without sacrificing regional coverage density unbundle these capabilities from core warehousing contracts.
Today's leader: Warehousing. Tomorrow's challenger: Order Fulfillment.
End User:
Automotive and pharmaceutical verticals sustain contract duration against retail compression.
- Automotive OEMs:Inbound just-in-time component flows and finished vehicle distribution through dedicated delivery corridors. Southeast Asian vehicle manufacturers are expanding outsourced logistics partnerships to manage complex supplier networks and assembly sequencing.
- eCommerce Companies:Distributed fulfillment nodes with performance-indexed pricing tied to order accuracy rates. Platform operators require regional micro-fulfillment infrastructure to enable same-day delivery commitments across fragmented urban markets.
- Retailers:Omnichannel inventory positioning combining centralized stock with forward deployment. Mid-market operators across South Korea and Taiwan adopt hybrid delivery models seeking cost flexibility without coverage density sacrifice.
- Pharmaceuticals:Temperature-controlled logistics with BIS certification compliance for Indian cold-chain equipment. Japanese pharmaceutical exporters drive demand for METI-aligned dual-sourcing frameworks and specialized handling protocols.
eCommerce companies are gaining share fastest as procurement patterns compress contract duration and rotate toward shorter-cycle engagements.
Delivery Model:
Hybrid architectures displace pure centralized networks as inventory positioning fragments.
- Hybrid:Combines centralized inventory with regional micro-fulfillment nodes. Mid-market retailers across South Korea and Taiwan adopt this structure to balance cost flexibility against coverage density requirements.
- Just-in-Time:Synchronized inbound flows with assembly sequencing for automotive component suppliers. CJ Logistics sustains dominance in South Korean automotive inbound logistics through dedicated corridor investments.
- Decentralized:Distributed fulfillment nodes without central hub dependency. eCommerce platform operators in Vietnam and Thailand deploy autonomous mobile robots to enable same-day delivery commitments.
- Centralized:Single mega-warehouse serving broad geographic catchments. Legacy footprint across Southeast Asia requires substantial retrofitting to accommodate automation mandates and velocity pressures.
Hybrid delivery models are climbing the fastest as buyer procurement unbundles long-term agreements into flexible network configurations.
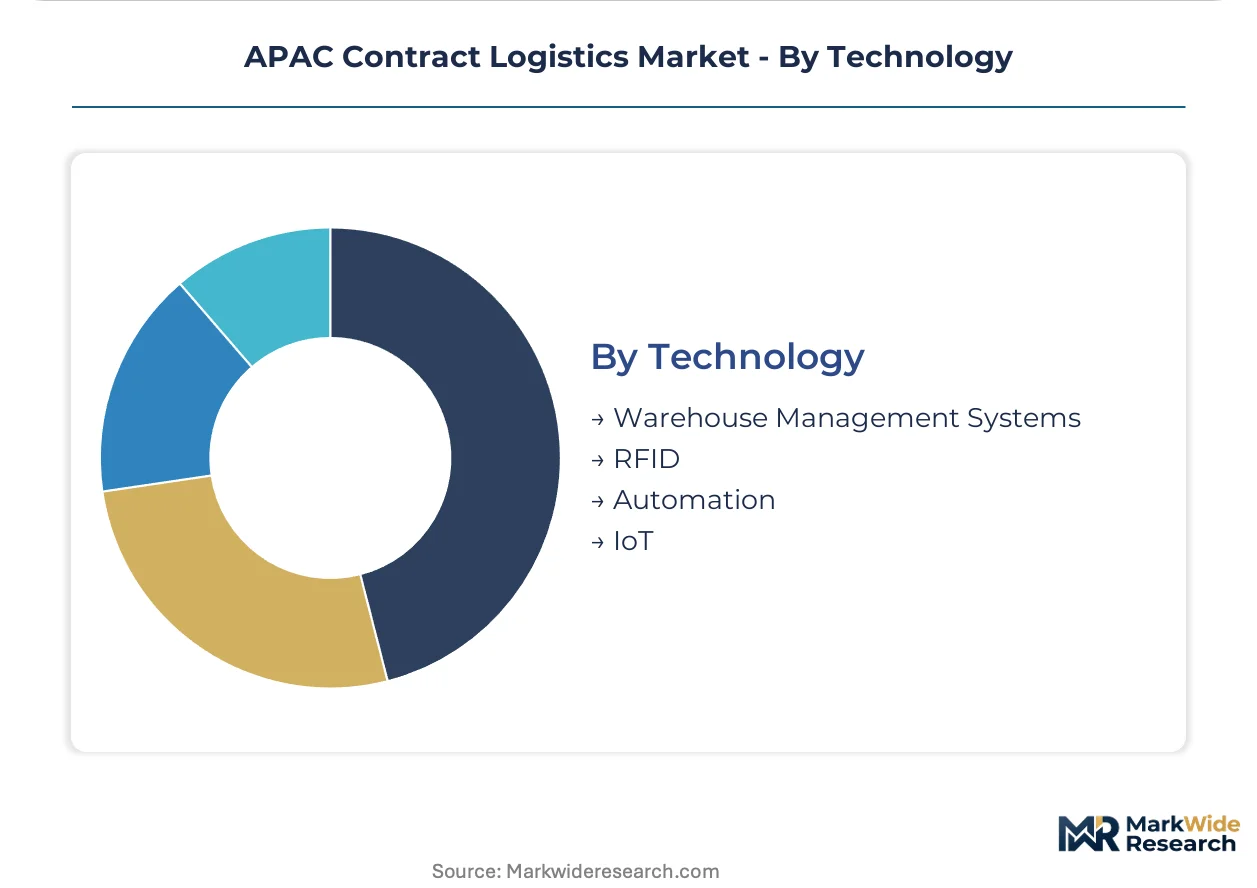
Technology:
Automation convergence with regulatory data mandates compresses investment timelines.
- Automation:Autonomous mobile robots and automated storage and retrieval systems integrated with warehouse management systems. MIIT digital infrastructure mandates force compliance across China-based operations and reshape competitive positioning between integrated and commodity tiers.
- Warehouse Management Systems:Software platforms for inventory tracking, labor management, and slotting optimization. SAMR data architecture restrictions limit cross-border system architectures and increase compliance overhead for multinational operators.
- IoT:Sensor networks for real-time asset tracking and environmental monitoring. Pharmaceutical cold-chain applications concentrate in Japan and South Korea where qualified technician availability supports network reliability.
- RFID:Radio-frequency identification for inventory visibility and cycle counting. Deployment accelerates as robotics integration requires precise location data for autonomous navigation.
Automation represents the steepest expansion trajectory as legacy facility retrofitting demands accelerate across Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's warehouse automation mandates outpace Vietnam's infrastructure buildout, while Japan's dual-sourcing requirements reshape procurement patterns across the region. South Korea maintains automotive logistics dominance through dedicated corridor investments. Australia's eCommerce fulfillment networks lag regional automation adoption timelines.
China
MIIT digital infrastructure mandates force robotics deployment across Shanghai and Shenzhen logistics hubs. SAMR data security standards restrict cross-border warehouse management architectures and elevate compliance costs for multinational operators. Yangtze River Delta manufacturing clusters demand integrated inbound-outbound contract logistics services.
Japan
METI supply chain resilience guidelines mandate dual-sourcing frameworks for pharmaceutical and automotive exporters. Cold-chain specialization concentrates in Osaka and Nagoya corridors where qualified technician availability supports network reliability. Kanto region eCommerce operators compress contract durations toward performance-indexed pricing structures.
Vietnam
Automotive OEM expansion in the northern manufacturing corridor near Hanoi and Hai Phong drives dedicated lane contracting for just-in-time component flows. Foreign logistics providers face localization requirements for warehouse automation equipment procurement. Southern Delta region remains underserved for temperature-controlled pharmaceutical distribution.
South Korea
CJ Logistics anchors automotive inbound logistics through just-in-time delivery corridors serving Hyundai and Kia assembly networks. Seoul Capital Area eCommerce platforms deploy hybrid delivery models combining centralized inventory with regional micro-fulfillment nodes. Busan-Ulsan port logistics face automation retrofitting pressure from legacy facility footprints.
India
BIS certification requirements for cold-chain equipment extend pharmaceutical logistics procurement cycles and constrain rapid network expansion. Delhi-NCR and Mumbai logistics hubs concentrate demand for value-added warehousing services including kitting and returns processing. Gujarat manufacturing corridors attract contract logistics investment for export consolidation capabilities.
APAC Contract Logistics Market Competitive Landscape
Top-tier vendors anchor premium technology-integrated contract logistics, while commodity freight operators face margin compression from automation mandates. Market structure concentrates around integrated providers with regional automation footprints and specialized corridor operators with automotive or cold-chain expertise. Three archetypes dominate: pan-Asian integrated networks, country-specialized corridor operators, and eCommerce-focused fulfillment platforms. Competitive moves center on warehouse automation retrofitting partnerships and multi-year automotive corridor contracts.
Within the integrated network tier, Deutsche Post DHL Group and Kuehne + Nagel occupy positions defined by regional automation compliance capabilities and multi-country warehouse management system architectures. CJ Logistics exemplifies the corridor-specialist archetype through dedicated automotive logistics infrastructure. These three companies represent distinct competitive positioning vectors: technology-integrated scale, automotive vertical depth, and cross-border network density.
| Leading Market Players |
|---|
| DSV |
| Deutsche Post DHL Group |
| Kuehne + Nagel |
| CEVA Logistics |
| Nippon Express |
| CJ Logistics |
| Logisteed Ltd |
| DB Schenker |
| Toll Group |
| Others |
Pricing and Supply Chain Analysis
eCommerce platform operators in Vietnam and Thailand anchor demand concentration, driving unbundled service procurement that separates warehousing from transportation and value-added services. This buyer archetype's preference for performance-indexed contracts compresses margins for providers lacking automation-enabled cost structures.
Pricing Analysis
Bundled multi-year contracts with automotive OEMs sustain premium pricing, while unbundled eCommerce fulfillment services face acute cost compression. Price differentiation rests on MIIT compliance certification and automation integration density. Pricing pressure intensifies in commodity transportation tiers as robotics deployment widens capability gaps. Retailers exhibit highest price sensitivity; pharmaceutical cold-chain buyers accept premium positioning for BIS-certified infrastructure.
Supply Chain Analysis
Direct-to-automotive-OEM channels handle hyperscale demand through dedicated just-in-time corridors anchored in South Korea and Vietnam. Distribution runs through Shanghai, Singapore, and Tokyo gateway hubs where real estate scarcity elevates occupancy costs. Raw material dependencies include warehouse automation equipment from Japan and Germany, plus cold-chain refrigeration systems from South Korea. Single-source vulnerability concentrates in qualified pharmaceutical cold-chain technician pools across Japan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APAC contract logistics has entered late-cycle quality phase as eCommerce fulfillment demands MIIT-compliant automation specifications. Buyers now prioritize robotics integration over pure cost minimization.
For Market Incumbents: Deploy warehouse automation retrofitting partnerships to defend corridor positions against technology-enabled entrants. CJ Logistics demonstrates defensive value through dedicated automotive infrastructure that emerging competitors cannot replicate rapidly. Accelerate certification investment for SAMR data architecture compliance before multinational rivals achieve equivalent coverage. For New Entrants and Emerging Players: Autonomous mobile robot integration offers viable entry wedge into Vietnam's northern manufacturing corridor where foreign providers face localization requirements. Target pharmaceutical cold-chain expansion in India's southern Delta region, currently underserved for temperature-controlled distribution. Lead with performance-indexed pricing tied to order accuracy benchmarks rather than cost-plus structures. For Investors and Strategic Acquirers: Pan-Asian integrated networks are the most active acquirer in this space, seeking automation-compliant regional footprints. Five-to-ten year viability favors corridor-specialist operators with automotive or cold-chain vertical depth over commodity freight forwarding. Monitor MIIT enforcement intensity as inflection signal for competitive tier consolidation pace.| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Automation Partnership | MIIT compliance mandates force robotics deployment across China-based operations. |
| Automotive Corridor Investment | CJ Logistics anchors Hyundai-Kia networks through dedicated just-in-time infrastructure. |
| Cold-Chain Certification Program | BIS compliance opens Indian pharmaceutical logistics procurement to qualified operators. |
| Hybrid Delivery Model Launch | Seoul Capital Area eCommerce platforms combine centralized inventory with micro-fulfillment nodes. |
| Dual-Sourcing Framework Adoption | METI guidelines mandate secondary logistics provider qualification for Japanese exporters. |
Research Methodology
Bottom-up eCommerce fulfillment modeling reconciled against top-down warehouse automation deployment tracking forms the analytical core. Primary interviews with logistics procurement officers at automotive OEMs, pharmaceutical supply chain directors, eCommerce platform operations heads, and third-party logistics facility managers combined with secondary validation from MIIT policy filings, SAMR regulatory notices, METI supply chain guidelines, and BIS certification databases. Trade flow analysis across Vietnam's northern manufacturing corridor and Shanghai-Singapore-Tokyo gateway markets triangulates demand estimates.
Historical trendline analysis of contract duration compression and pricing model evolution informs projection framework construction. Segmentation dimensions span service type, end-user vertical, delivery model architecture, and technology integration tier. CAGRs derive from facility automation adoption curves and eCommerce fulfillment node proliferation rates across the projection horizon. Forecast inputs include industrial real estate cost trajectories in gateway markets and regulatory compliance timeline assumptions for cross-border data architecture.
The model holds under sustained MIIT enforcement and gradual automotive outsourcing expansion; deviation in regulatory acceleration or trade corridor disruption would shift competitive tier boundaries. Forecasts reflect base-case assumptions regarding technician availability for cold-chain operations and robotics integration timelines for legacy Southeast Asian facilities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
IoT Spend by Logistics Industry Market
Logistics and Shipping
Asia-Pacific Container Drayage Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
New York Freight and Logistics Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
Mexico Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Sea Freight Forwarding Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
Germany Third-Party Logistics (3PL) Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
Canada Courier, Express, and Parcel (CEP) Market