
 United States Courier, Express and Parcel (CEP) Market | 2026-2036
United States Courier, Express and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
United States Courier, Express and Parcel (CEP) Market Intelligence
Asset-light leasing and contract fleet arrangements are narrowing the capital barrier for regional challengers. Veho leverages its crowdsourced driver model to sustain last-mile density without fixed fleet ownership. FedEx anchors its national position through integrated air-ground infrastructure that controls time-definite lanes. Amazon Logistics differentiates by operating captive vertical capacity that extends from fulfillment center to doorstep.
Courier, express and parcel services encompass time-sensitive logistics operations involving documents, parcels, pallets and freight, utilizing ground, air and intermodal networks with defined service-level commitments for pickup and delivery windows. The primary commercial purpose is enabling reliable inventory flow and customer fulfillment across geographically dispersed supply chains. Same-day delivery and express service command premium positioning where margin pools concentrate, while standard shipping occupies the high-volume, rate-competitive tier. E-commerce end users are driving the fastest capacity expansion, whereas healthcare logistics requires specialized cold-chain and chain-of-custody compliance that limits participant entry.
The Federal Motor Carrier Safety Administration governs driver hours and vehicle safety standards, while the FAA regulates air cargo operations and unmanned aerial vehicle trials for last-mile delivery. The Department of Transportation's infrastructure investment priorities shape highway capacity and intermodal terminal access that directly affect network speed and cost structures. Stakeholders must monitor how state-level autonomous vehicle legislation and federal drone integration rules will redraw the feasible geography for unattended delivery and remote depot operations.
Market Dynamics
The Federal Motor Carrier Safety Administration's electronic logging device mandate and hours-of-service rules are compressing driver utilization rates and forcing network redesign across ground-based parcel operations.
Growth Catalysts
- E-commerce fulfillment density:The Texas Triangle megaregion is absorbing record distribution center construction, creating hub-and-spoke economies that reduce per-package handling costs.
- Healthcare cold-chain mandates:FDA chain-of-custody requirements for temperature-sensitive biologics are carving out premium service tiers with specialized compliance infrastructure.
- Unmanned aerial vehicle trials:FAA Section 333 exemptions and Part 135 certification pathways are opening last-mile air corridors for remote and suburban delivery.
Market Restraints
- Diesel price volatility:Fuel represents 25-30% of line-haul operating costs, and fleet operators lack pricing power to pass through spikes in standard shipping tiers.
- Driver labor scarcity:FMCSA medical certification and commercial driver's license requirements constrain eligible workforce pools in rural corridors.
- Airport slot congestion:Memphis and Louisville hub concentration creates single-point vulnerability for time-definite express networks.
Strategic Opportunities
- Autonomous vehicle corridors:Texas and Arizona state legislation permitting driverless trucking on designated interstate segments enables pilot freight lanes.
- Reverse logistics monetization:E-commerce return volumes are generating dedicated pickup density that supports standalone route economics.
- Healthcare home delivery:Medicare reimbursement shifts toward home-based care are expanding addressable market for pharmaceutical last-mile services.
Industry Challenges
- Telematics integration complexity:Legacy warehouse management systems require expensive API bridging to connect with real-time fleet tracking platforms.
- OSHA warehouse safety compliance:Powered industrial truck operator certification and ergonomic standards are extending onboarding timelines for seasonal labor surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Courier, Express and Parcel (CEP) Market |
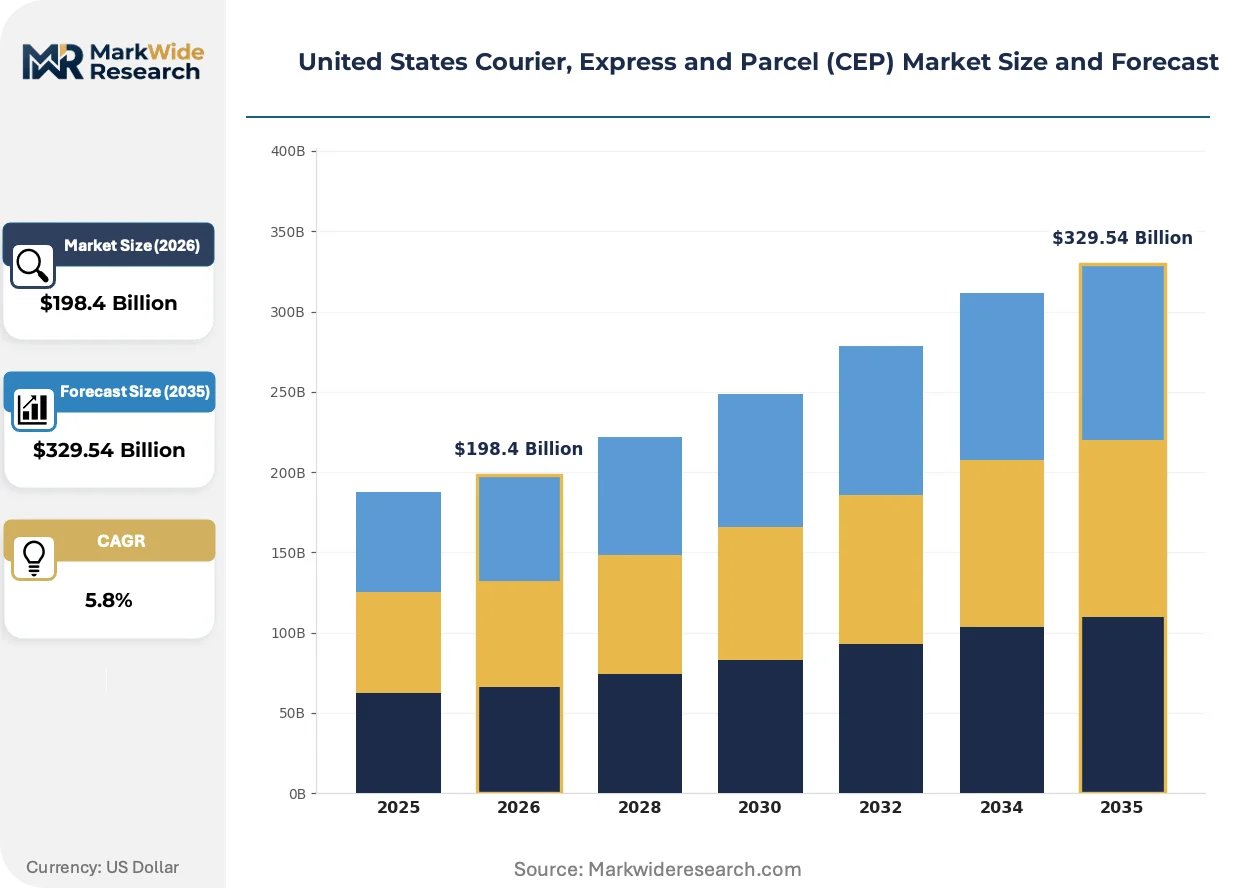
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $329.54 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Overnight Shipping, Standard Shipping, Express Service Delivery Model: Door-to-Door, Drop-off Service, Scheduled Delivery, Curbside Pickup End User: E-commerce, Retail, Manufacturing, Healthcare Package Type: Documents, Parcels, Pallets, Freight |
| Companies Covered | DHL Express, Veho, FedEx, OnTrac, LaserShip, UPS, Amazon Logistics, Gofo, USPS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Courier, Express and Parcel (CEP) Market Strategic Shifts & Innovations
Dynamic route optimization and predictive delivery windows are compressing the gap between customer expectation and operational feasibility across parcel networks.
Machine learning dispatch algorithms are collapsing the planning horizon for same-day delivery from hours to minutes. Grocery and pharmacy chains are deploying these systems to promise two-hour windows without pre-positioned inventory. The structural consequence is collapsing the distinction between forward distribution and responsive fulfillment, forcing asset-heavy operators to match software-driven agility.
FAA drone integration pilot programs are establishing beyond-visual-line-of-sight corridors for package delivery in designated test zones. The industrial consequence is creating regulatory precedent for unmanned aerial vehicle operations at scale. Rural and exurban last-mile segments are most affected, with operators negotiating local airspace agreements to secure first-mover positioning.
Subscription-based delivery memberships are consolidating individual purchase decisions into prepaid annual commitments. Retailers are displacing per-transaction shipping revenue with bundled access fees that obscure marginal cost visibility. This pattern is most visible in apparel and consumer electronics verticals, where free shipping thresholds have trained buyers to consolidate orders or upgrade to paid loyalty tiers.
United States Courier, Express and Parcel (CEP) Market Segmentation
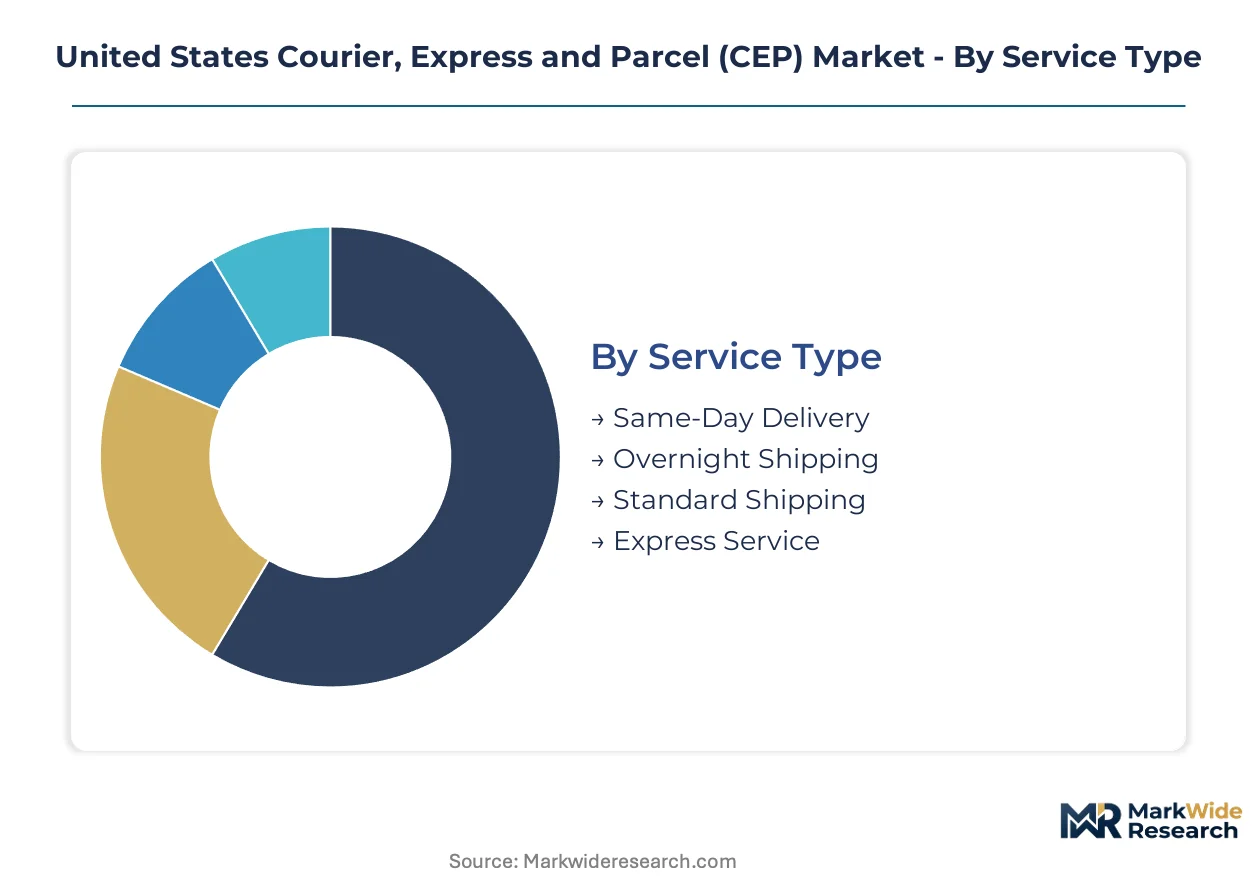
CEP operators configure service portfolios around velocity tiers and handling requirements. Segmentation reveals where infrastructure investments concentrate and which customer contracts command premium positioning.
Service Type:
Velocity-based service tiers span urgent document transport to deferred freight consolidation, each demanding distinct network architecture and pricing power.
- Same-Day Delivery:Urban micro-fulfillment networks with courier density enable two-hour windows for metropolitan corridors. E-commerce grocery and pharmacy chains in the Texas Triangle megaregion are absorbing capacity fastest as they compete on immediacy.
- Overnight Shipping:Time-definite next-morning commitments require integrated air-ground infrastructure with hub concentration at Memphis and Louisville. FedEx and UPS anchor national coverage through controlled airport slots and dedicated feeder aircraft.
- Standard Shipping:Deferred ground transport with three-to-seven-day windows occupies the rate-competitive volume tier. Amazon Logistics leverages captive vertical capacity to undercut independent carrier pricing in this segment.
- Express Service:Premium positioning with guaranteed delivery windows and proactive exception management. Healthcare cold-chain mandates are carving out specialized compliance infrastructure for temperature-sensitive biologics.
Established volume favors Standard Shipping; emerging adoption favors Same-Day Delivery.
Delivery Model:
Last-mile configuration choices reflect trade-offs between labor efficiency and customer convenience preferences.
- Door-to-Door:Residential delivery with signature or unattended drop options remains the default expectation for e-commerce fulfillment. Driver utilization rates compress under FMCSA hours-of-service constraints.
- Drop-off Service:Consolidated pickup points at retail partners and locker banks reduce per-stop delivery cost. CVS and Walgreens partnerships are expanding access density in suburban corridors.
- Scheduled Delivery:Appointment-based windows for large-format freight and white-glove handling. Appliance and furniture retailers absorb this capacity in the Texas Triangle distribution cluster.
- Curbside Pickup:Contactless handoff with geofenced arrival notifications. Grocery chains deployed this model at scale during pandemic restrictions and retained operational infrastructure.
Door-to-Door retains volume dominance; Curbside Pickup is climbing the fastest as retailers optimize labor allocation.
End User:
Demand concentration varies sharply by vertical, with e-commerce driving capacity expansion and healthcare imposing specialized compliance barriers.
- E-commerce:Direct-to-consumer order profiles with high return volumes and seasonal surge patterns. Amazon, Walmart, and Target account for disproportionate network utilization during peak periods.
- Retail:Store replenishment and ship-from-store fulfillment bridging inventory positions. Omnichannel integration is collapsing the distinction between forward distribution and responsive fulfillment.
- Manufacturing:Just-in-time component delivery and spare parts logistics with penalty cost for delay. Automotive and electronics supply chains concentrate demand in the Texas Triangle and Great Lakes corridors.
- Healthcare:FDA chain-of-custody requirements for temperature-sensitive biologics and controlled substances. Limited participant entry preserves premium margin pools for compliant operators.
E-commerce commands capacity expansion; Healthcare offers the steepest expansion trajectory for specialized infrastructure.
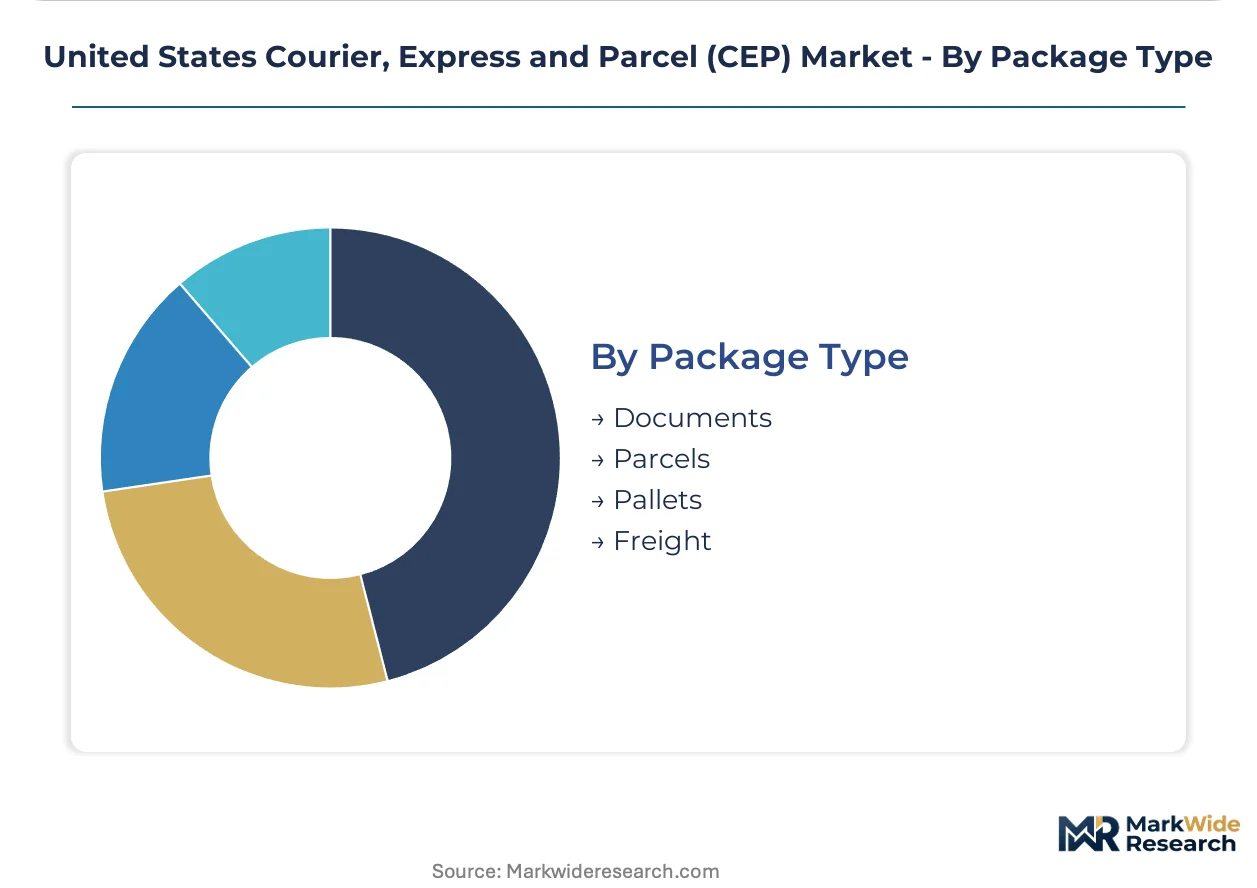
Package Type:
Physical handling requirements determine network compatibility and equipment specialization.
- Documents:Lightweight envelope and small pouch transport with highest velocity requirements. Digital substitution has compressed this segment to legal filings and certified originals.
- Parcels:Standard carton profiles up to 150 pounds representing the core CEP volume. Sortation automation at regional hubs processes this category at lowest unit cost.
- Pallets:Unitized freight requiring liftgate equipment and dock-height access. Less-than-truckload carriers compete with parcel networks for this intermediate weight class.
- Freight:Heavy and bulky shipments exceeding parcel network limits. Dedicated trucking and intermodal rail absorb this category outside integrated CEP infrastructure.
Parcels dominate operational scale; Freight is gaining share fastest as e-commerce extends into large-format categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates sharply in the Texas Triangle megaregion, where distribution center density compresses per-package handling costs below levels achievable in the Pacific Northwest or Northeast Corridor.
Southwest
The Texas Triangle anchors national fulfillment expansion with Dallas-Fort Worth, Houston, and Austin absorbing record distribution center construction. FMCSA hours-of-service rules reshape fleet economics across interstate corridors linking these hubs. Phoenix and Tucson serve as secondary nodes where autonomous vehicle pilot programs on designated highway segments enable driverless freight trials.
Southeast
Atlanta and Charlotte distribution clusters capture overflow demand from e-commerce fulfillment networks seeking lower land costs than Northeast markets. Port of Savannah container volume growth drives inland drayage and transload capacity expansion. Florida's Miami-Dade corridor specializes in time-definite express lanes serving Latin American trade lanes.
Midwest
Chicago's intermodal rail terminals and O'Hare air cargo infrastructure position the region as a consolidation point for standard shipping tiers. Ohio's Columbus and Cincinnati hubs host major sortation facilities serving the Great Lakes manufacturing corridor. FMCSA electronic logging device mandates particularly constrain driver utilization across rural interstate segments.
Northeast Corridor
Last-mile density in the New York metropolitan area sustains premium same-day delivery economics despite elevated real estate costs. Boston and Philadelphia serve as healthcare logistics nodes where FDA chain-of-custody requirements for temperature-sensitive biologics create specialized infrastructure demand. Port of New York and New Jersey congestion drives alternative routing through Baltimore.
Pacific Coast
Los Angeles-Long Beach port complex throughput shapes drayage and transload capacity allocation across the Southwest. Seattle and Portland anchor Pacific Northwest fulfillment networks serving Alaska and Hawaii lanes. California's state-level autonomous vehicle legislation permits testing corridors that may eventually reshape long-haul line-haul economics.
United States Courier, Express and Parcel (CEP) Market Key Industry Players
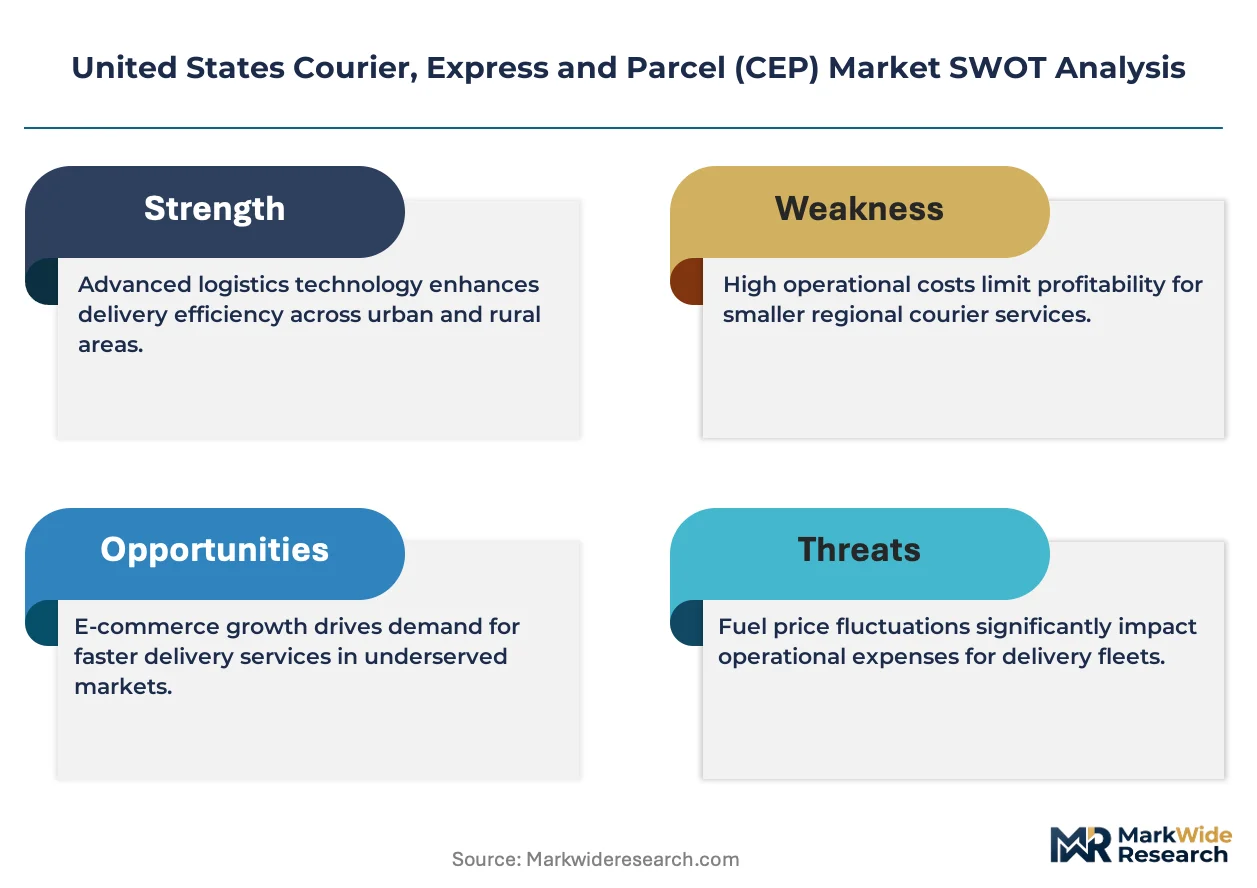
Platform integrators command the system tier; component specialists sit upstream in niche service lanes. The United States CEP market structures around three tiers: national integrators with controlled air-ground infrastructure, regional carriers with density-focused ground networks, and asset-light platforms leveraging crowdsourced labor. Strategic moves concentrate on captive vertical capacity expansion and dynamic routing algorithm deployment.
Within the integrated infrastructure tier, FedEx and UPS anchor national coverage through Memphis and Louisville hub concentration. Veho exemplifies the asset-light challenger model, sustaining last-mile density without fixed fleet ownership through crowdsourced driver arrangements. Amazon Logistics occupies a distinct position with captive vertical capacity extending from fulfillment center to doorstep, enabling aggressive rate positioning in standard shipping tiers.
| Leading Market Players |
|---|
| DHL Express |
| Veho |
| FedEx |
| OnTrac |
| LaserShip |
| UPS |
| Amazon Logistics |
| Gofo |
| USPS |
| Others |
Cost & Logistics Intelligence
Diesel price volatility functions as the primary cost shock vector, compressing margins across ground-based tiers while simultaneously accelerating fleet operators toward density-focused hub configurations that can absorb fuel spikes through stop-compression economics.
Pricing Analysis
E-commerce retailers anchor pricing structure across three-tier differentiation separating same-day express from deferred standard shipping. Price differentiation rests on velocity guarantees and specialized handling certification, with healthcare cold-chain compliance commanding substantial premiums. Pricing pressure intensifies in standard shipping as Amazon Logistics leverages captive vertical capacity to undercut independent carrier rates. Small and mid-sized merchants exhibit highest price sensitivity, while pharmaceutical distributors demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Export-control restrictions on autonomous vehicle technology and drone components limit equipment sourcing from Chinese manufacturers, forcing domestic operators toward alternative suppliers. Fleet equipment and telematics hardware draw from Mexico, Canada, and domestic assembly plants. Diesel fuel, sorting automation components, and last-mile delivery vehicles constitute critical input dependencies. Single-source vulnerability concentrates in Memphis and Louisville airport slot access for time-definite express networks. Distribution runs through hub-and-spoke sortation facilities feeding line-haul corridors into micro-fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States CEP market sits at a platform-economics inflection where dynamic routing algorithms and crowdsourced labor marketplaces are displacing fixed-asset competitive moats, with interoperability between warehouse management systems and real-time fleet tracking emerging as the decisive ecosystem battleground.
For Market Incumbents: Harden hub-and-spoke infrastructure control through dedicated airport slot retention at Memphis and Louisville, while accelerating API bridge investments to neutralize software-driven challengers. Consolidate position in healthcare cold-chain certification to defend premium tier pricing against rate compression in standard shipping segments. For New Entrants and Emerging Players: Pursue rural and exurban last-mile corridors where FMCSA driver scarcity constrains incumbent capacity expansion, leveraging crowdsourced driver marketplaces to achieve density without fixed fleet ownership. Target pharmaceutical home delivery as the most penetrable vertical given Medicare reimbursement shifts toward home-based care. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized compliance infrastructure and autonomous vehicle pilot operators over pure-play software platforms. Acquisition focus should center on FDA-certified cold-chain operators and Texas Triangle distribution real estate. Watch FAA drone integration rulemaking as the critical inflection signal for unmanned aerial vehicle scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Dynamic Route Optimization Deployment | Machine learning dispatch algorithms collapse same-day planning horizons from hours to minutes for grocery and pharmacy chains. |
| Healthcare Cold-Chain Certification Investment | FDA chain-of-custody compliance creates defensible premium service tiers with limited participant entry. |
| Crowdsourced Driver Marketplace Expansion | Asset-light labor models sustain last-mile density without fixed fleet ownership or FMCSA utilization constraints. |
| Autonomous Freight Corridor Pilot | Texas and Arizona state legislation enables driverless trucking trials that may reshape long-haul line-haul economics. |
| Reverse Logistics Network Buildout | E-commerce return volumes generate dedicated pickup density supporting standalone route economics for specialized operators. |
Research Approach
The analysis maps same-day delivery, overnight express, standard ground, and healthcare logistics segments, each validated through fleet operations directors, e-commerce fulfillment managers, pharmaceutical supply chain leads, and FMCSA compliance officers. Primary interview findings triangulate against FMCSA regulatory filings, FAA drone integration program updates, Department of Transportation infrastructure investment disclosures, and customs trade data for vehicle and equipment imports. Bottom-up carrier capacity modeling and top-down e-commerce volume projections reconcile through iterative validation.
Assumptions held fixed include FMCSA hours-of-service rules and FAA unmanned aerial vehicle regulatory timelines, while diesel price trajectories and autonomous vehicle legislative adoption rates varied across sensitivity scenarios. Segmentation modeling spans service velocity tiers, delivery model configurations, end-user verticals, and package handling requirements. CAGRs derive from trend extrapolation of e-commerce penetration curves and healthcare logistics outsourcing patterns, with Texas Triangle distribution construction permitting serving as a regional demand proxy.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Amazon Logistics or accelerated FAA drone certification would shift outcomes. Material shifts in diesel price volatility, FMCSA driver utilization regulations, or state-level autonomous vehicle legislation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
Smart Shipping Containers Market
Logistics and Shipping
South Africa Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Delivery Tracking Platform Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Freight Forwarding Market
Logistics and Shipping
France Freight and Logistics Market
Logistics and Shipping
Singapore Freight and Logistics Market
Logistics and Shipping
Renewable Resources Logistics Market
Logistics and Shipping
South Africa Freight and Logistics Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Latin America Logistics Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
Logistics Outsourcing Market