
 Air Cargo Market | 2026-2036
Air Cargo Market Size, Share, and Industry Trends Forecast 2026-2036
Air Cargo Market Analysis
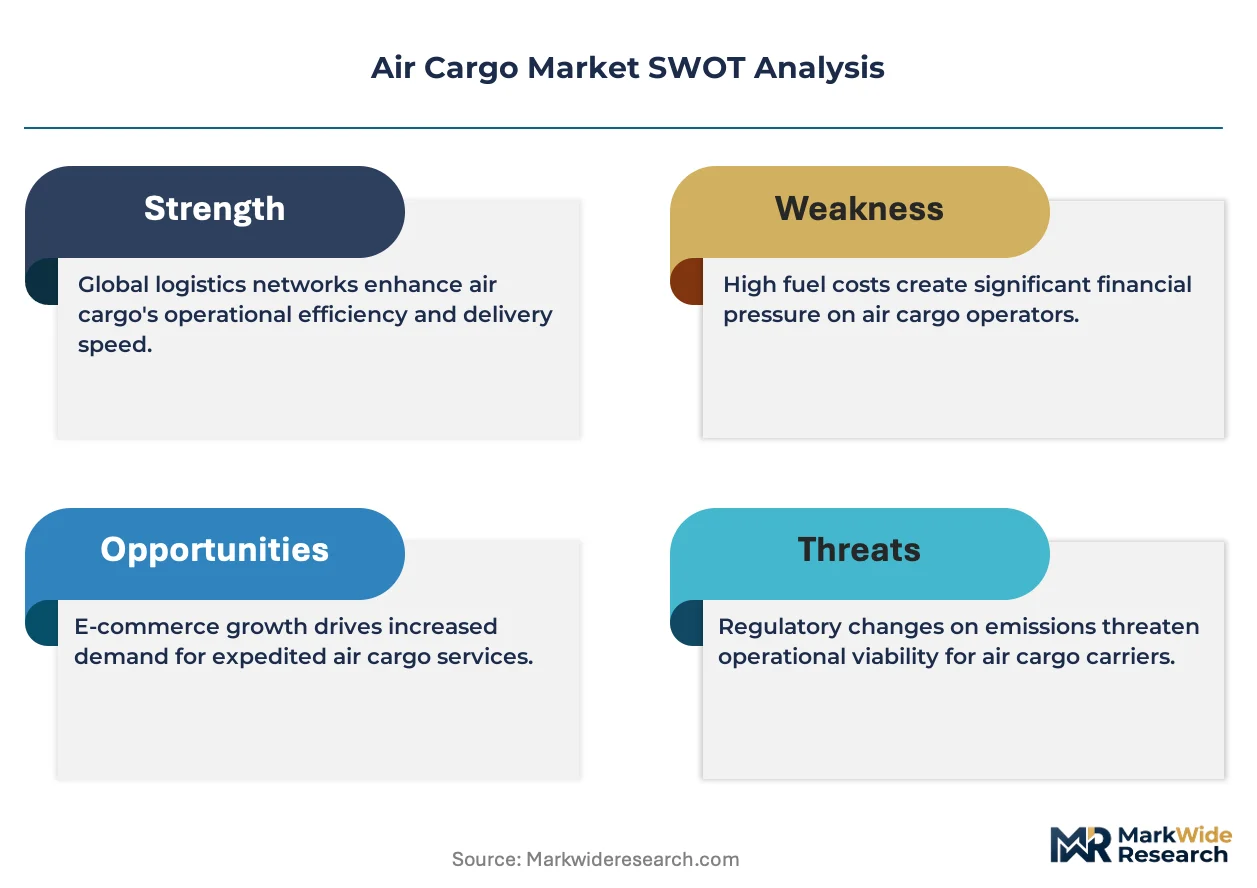
Freight forwarding as a managed service layer is consolidating control over how airlines price and allocate capacity. FedEx Express leverages its integrated express network to dominate time-definite shipments across North America and Europe. DHL Aviation anchors intra-Asia connectivity through its Leipzig and Hong Kong hubs. Cargolux specializes in outsized and project cargo, sustaining premium yields on routes linking Luxembourg to oil-and-gas extraction zones.
Air cargo comprises the commercial transport of goods via fixed-wing aircraft, utilizing dedicated freighters, belly-hold space on passenger flights, or combi configurations with payload capacities ranging from 10 to 150 tonnes depending on aircraft type. Its primary purpose is bridging time-critical supply chains for goods where surface transport latency exceeds inventory carrying cost thresholds. Express delivery commands the highest margin pool within service type segmentation due to contractual reliability premiums and last-mile integration. Perishable goods within cargo type segmentation represents the fastest-growing category, driven by temperature-controlled pharmaceutical shipments and fresh food trade lanes. Freight forwarding retains structural importance as the intermediary layer capturing value from carrier fragmentation and customs complexity.
The International Civil Aviation Organization's Carbon Offsetting and Reduction Scheme for International Aviation binds carriers to emissions accountability, while the Federal Aviation Administration governs pilot duty limits and aircraft certification standards affecting freighter utilization rates in the United States. The European Union's Emissions Trading System extends carbon cost exposure to intra-European air cargo movements, reshaping network economics for hub carriers. Stakeholders must monitor sustainable aviation fuel certification pathways and slot allocation reforms at congested airports to preserve operational flexibility.
Market Dynamics
E-commerce fulfillment networks are reshaping capacity allocation as pharmaceutical cold chains and just-in-time manufacturing impose stricter reliability requirements on freighter utilization. The International Civil Aviation Organization's carbon offsetting standards are accelerating fleet renewal decisions toward fuel-efficient widebodies.
Growth Catalysts
- Pharmaceutical cold chain expansion:Temperature-controlled biologics shipments are absorbing dedicated freighter capacity on trans-Pacific and trans-Atlantic lanes. The FDA's Drug Supply Chain Security Act mandates end-to-end traceability, elevating air cargo's value proposition for high-value therapies.
- Sustainable aviation fuel mandates:The European Union's ReFuelEU Aviation regulation requires escalating SAF blends for departures from EU airports. Carriers are retrofitting older freighters to extend service life while meeting these fuel specifications.
- Perishable trade lane densification:Fresh food e-commerce in East Asia is driving demand for narrow-body freighter conversions. China's customs modernization programs are compressing clearance times for agricultural imports.
Market Restraints
- Jet fuel price volatility:Fuel represents 25-35% of operating costs for freighter operators. Price spikes immediately compress margins on long-haul routes where fuel burn is highest.
- Slot scarcity at primary hubs:Frankfurt, Hong Kong, and Anchorage face overnight curfews and congestion limits. Peak-hour freighter movements require advance scheduling that reduces operational flexibility.
- Surface transport substitution:High-speed rail and refrigerated trucking are capturing time-sensitive cargo within 1,500-kilometer corridors. China's rail-sea intermodal networks are displacing intra-Asian air freight for non-pharmaceutical goods.
Strategic Opportunities
- Secondary city freighter networks:Vietnam, Indonesia, and the Philippines lack direct wide-body freighter service. Narrow-body conversions can establish point-to-point lanes bypassing congested primary hubs.
- Blockchain-IoT cargo tracking convergence:Real-time condition monitoring combined with immutable documentation is reducing insurance premiums and claims disputes. Pharmaceutical shippers are mandating these integrated systems for contract renewal.
- EU Green Deal funding windows:The Sustainable and Smart Mobility Strategy provides financing for SAF production facilities and electric ground handling equipment. Hub airports in the Netherlands and Germany are accessing these instruments for infrastructure modernization.
Industry Challenges
- Pilot certification bottlenecks:Freighter type ratings for new-generation widebodies require simulator time that training centers cannot scale rapidly. The FAA's extended duty rest rules are compressing crew utilization rates on ultra-long-haul rotations.
- Legacy warehouse management integration:Automated cargo terminals require API connectivity with carrier booking systems. Forwarders operating on 1990s-era platforms face multimillion-dollar migration costs.
- Temperature excursion liability:Pharmaceutical shipments demand continuous cold chain documentation. Single-point sensor failures can trigger total loss claims that exceed shipment value.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Cargo Market |
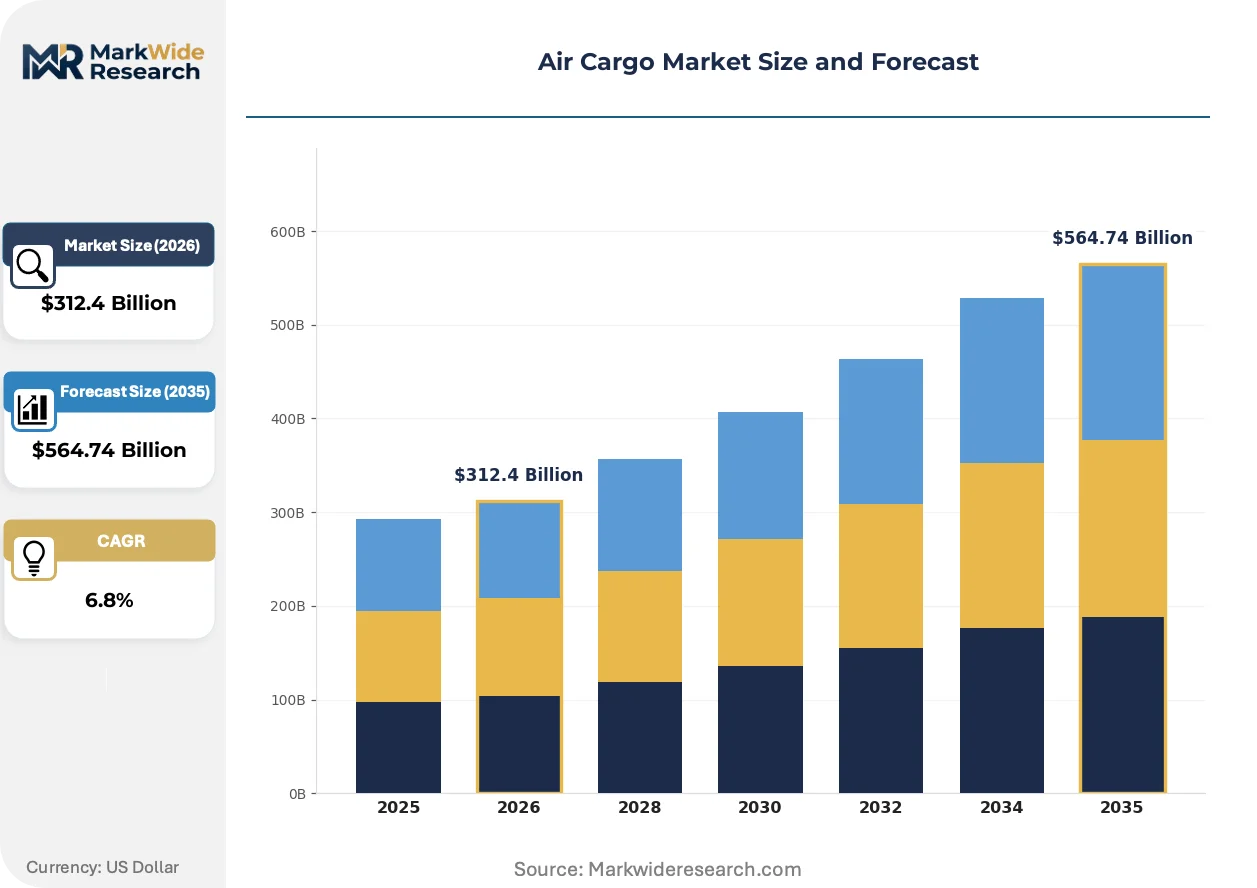
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Freight Forwarding, Charter Services, Logistics Management Cargo Type: General Cargo, Dangerous Goods, Perishable Goods, Oversized Cargo End User: E-commerce, Pharmaceuticals, Automotive, Retail Delivery Mode: Door-to-Door, Airport-to-Airport, Air-to-Sea, Intermodal |
| Companies Covered | Emirates SkyCargo, Cathay Pacific Cargo, FedEx Express, Atlas Air, Korean Air Cargo, UPS Airlines, DHL Aviation, Cargolux, Qatar Airways Cargo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Cargo Market Emerging Trajectories
Digital freight platforms and autonomous ground handling are compressing turnaround times while predictive analytics are reshaping how carriers price capacity. These technologies are converging to create differentiated service tiers.
Autonomous cargo handling systems are consolidating operational control at major hubs. Dnata and Swissport are deploying autonomous dollies and automated storage retrieval systems at Dubai and Zurich. This technology is consolidating ground handling market share toward technology-capable operators while displacing labor-intensive third-party providers.
The European Union's Emissions Trading System is extending carbon cost exposure to all intra-European air cargo movements. Hub carriers are reconfiguring networks to minimize ETS-liable flight hours. Short-haul freighter operations between Germany, France, and the Netherlands are absorbing the highest compliance cost increases.
Direct carrier contracting is displacing traditional freight forwarder intermediation for large pharmaceutical and electronics shippers. Amazon Air and similar captive fleets are capturing volume that previously flowed through forwarder-consolidated bookings. This pattern is most visible in North American domestic lanes and trans-Pacific routes serving East Asian manufacturing clusters.
Air Cargo Market Segmentation
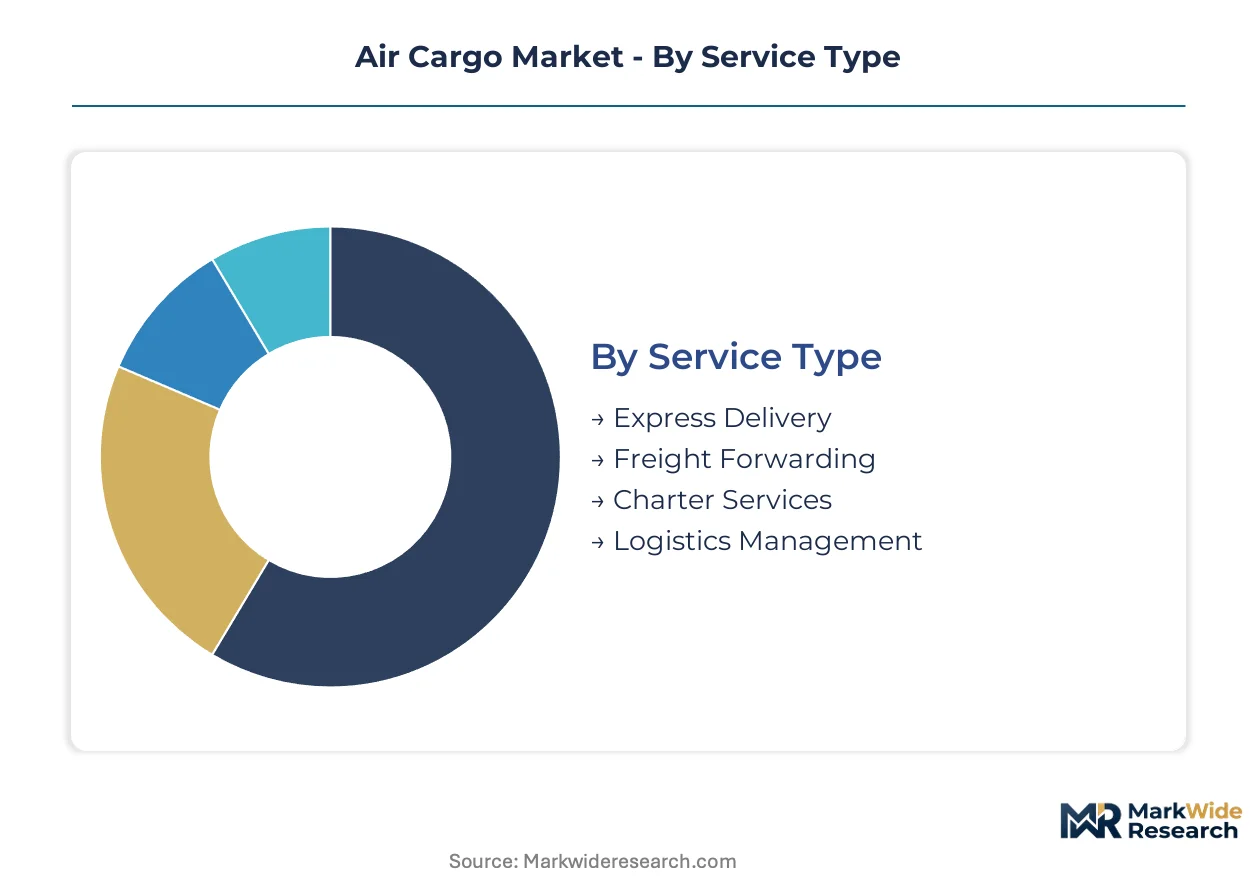
Segmentation in air cargo reveals how capital deployment and service specialization create distinct competitive arenas. Carrier investment decisions, forwarder margin structures, and shipper requirements diverge sharply across service tiers and cargo categories.
Service Type:
Capital intensity varies dramatically here: express networks demand integrated fleet and facility ownership, while freight forwarding requires minimal fixed assets.
- Express Delivery:Integrated operators control dedicated freighter fleets, sortation hubs, and last-mile delivery infrastructure. Pharmaceutical and electronics shippers in Germany and the United States pay reliability premiums for time-definite guarantees. The FDA's Drug Supply Chain Security Act traceability mandates are accelerating adoption of these closed-loop networks for high-value biologics.
- Freight Forwarding:Non-asset-based intermediaries aggregate fragmented carrier capacity and manage customs documentation complexity. Forwarders in the Netherlands and Singapore capture value from airline fragmentation and regulatory navigation without balance-sheet aircraft exposure.
- Charter Services:Project cargo and humanitarian relief demand ad hoc wide-body deployment.
- Logistics Management:Fourth-party providers orchestrate multi-modal supply chains through control tower operations.
Express Delivery absorbs the bulk of installed capacity; Freight Forwarding is expanding most quickly.
Cargo Type:
Handling infrastructure requirements separate these segments: temperature-controlled biologics demand pharmaceutical-grade cold chain investment that general cargo facilities cannot support.
- Perishable Goods:Temperature-controlled pharmaceuticals and fresh food trade lanes require continuous cold chain documentation and specialized container fleets. Demand concentrates in the United Arab Emirates and Switzerland, where Emirates SkyCargo and Swissport have built GDP-certified pharmaceutical handling infrastructure. The EU's Good Distribution Practice guidelines mandate qualified equipment and validated processes.
- General Cargo:Standardized palletized freight fills belly-hold capacity on passenger flights and dedicated freighter decks. E-commerce fulfillment networks in China and the United States absorb the majority of volume on trans-Pacific lanes.
- Dangerous Goods:Lithium batteries, chemicals, and radioactive materials require IATA-compliant segregation and fire suppression systems.
- Oversized Cargo:Oil-and-gas equipment and aerospace components demand nose-loading freighters and specialized ground handling.
General Cargo absorbs the bulk of installed capacity; Perishable Goods is climbing the fastest.
End User:
Procurement sophistication and contract scale distinguish these segments: pharmaceutical shippers mandate certified handling while automotive buyers negotiate multi-year capacity agreements.
- Pharmaceuticals:Temperature-controlled biologics and cell therapies require end-to-end cold chain validation. Shippers in Switzerland and the United States specify GDP-compliant lanes and real-time condition monitoring. The FDA and Swissmedic enforce serialization and traceability standards that elevate air cargo over ocean alternatives.
- E-commerce:Platform operators in China and the United States are building captive air networks to bypass forwarder markups. Alibaba and Amazon Air have converted passenger aircraft and ordered dedicated freighters to control peak-season capacity.
- Automotive:Just-in-time production lines depend on time-definite component delivery from Mexico and Germany.
- Retail:Seasonal inventory replenishment drives demand for flexible capacity allocation.
E-commerce absorbs the bulk of installed capacity; Pharmaceuticals is gaining share fastest.
Delivery Mode:
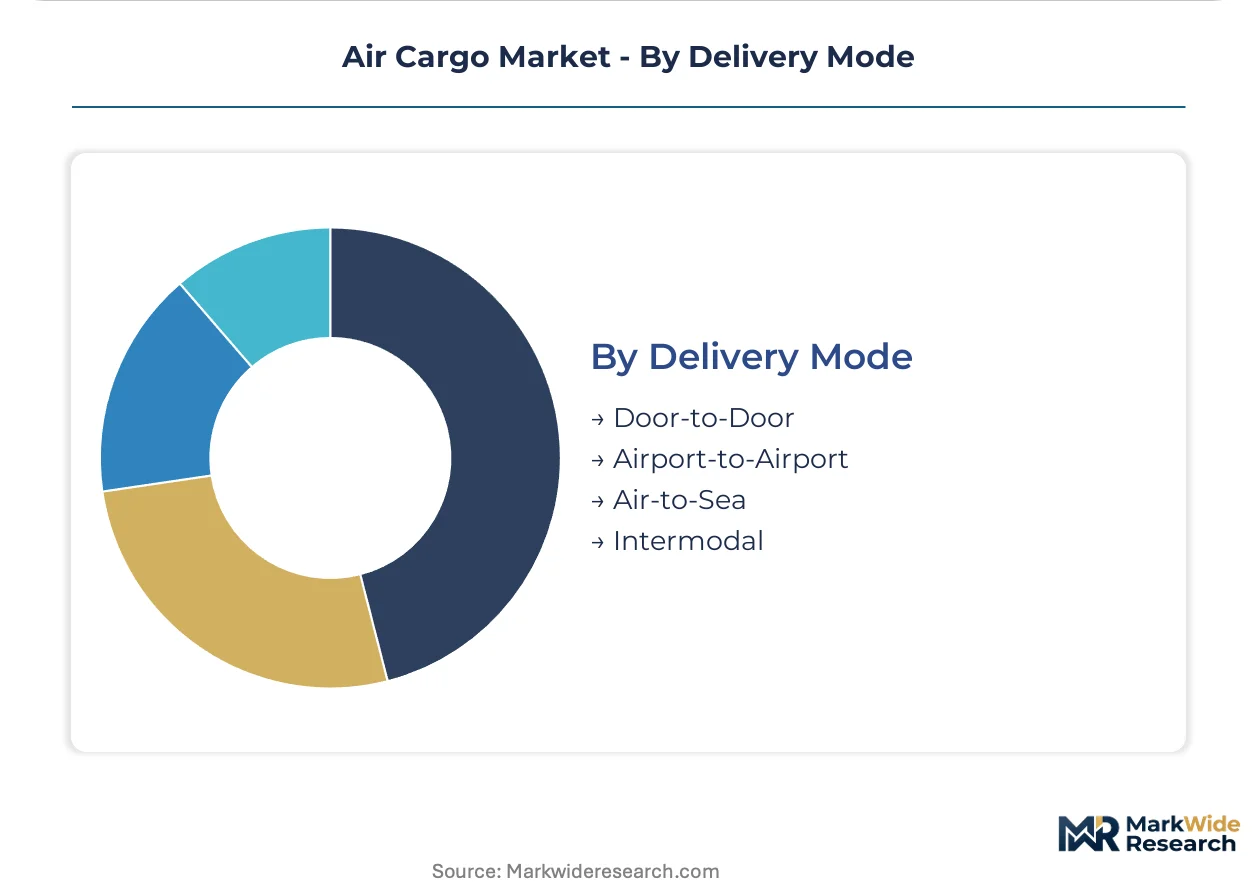
Asset control and margin capture differentiate these approaches: door-to-door service requires integrated ground infrastructure that airport-to-airport providers avoid.
- Door-to-Door:Integrated operators manage pickup, air transport, customs clearance, and final delivery through owned networks. FedEx and DHL Express dominate this segment in North America and Europe, capturing premium pricing through end-to-end control. The FAA and EASA govern crew duty limits and aircraft certification affecting network reliability.
- Airport-to-Airport:Airlines sell capacity to forwarders and direct shippers without ground handling responsibility. Frankfurt, Hong Kong, and Dubai anchor this segment through hub-and-spoke freighter operations.
- Air-to-Sea:Cost-sensitive shippers combine air freight legs with ocean carriage for mid-urgency cargo.
- Intermodal:Rail-sea-air combinations compete for intra-Asian flows where pure air cost exceeds inventory carrying thresholds.
Airport-to-Airport absorbs the bulk of installed capacity; Door-to-Door is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freighter production concentrates at Boeing and Airbus assembly lines in the United States and France, while cargo consumption fragments across pharmaceutical clusters in Switzerland, e-commerce fulfillment zones in China, and energy logistics corridors in the UAE.
United States
Pharmaceutical cold chains and express delivery networks absorb the majority of dedicated freighter capacity. The FAA governs pilot duty limits and aircraft certification standards that directly affect freighter utilization rates on transcontinental routes. Memphis and Louisville anchor express hub operations where integrated operators manage sortation infrastructure for time-definite shipments.
Germany
Automotive just-in-time supply chains and pharmaceutical distribution generate consistent demand for temperature-controlled air freight. The EU Emissions Trading System extends carbon cost exposure to intra-European movements, reshaping network economics for carriers operating from Frankfurt. Leipzig serves as DHL Aviation's primary European hub, consolidating intra-Asia connectivity through dedicated freighter rotations.
China
E-commerce fulfillment networks and fresh food trade lanes are driving narrow-body freighter conversions for domestic and regional routes. Customs modernization programs compress clearance times for agricultural imports at Shanghai and Shenzhen. The country's dual carbon goals are accelerating inquiries into sustainable aviation fuel certification for cargo operations at major international gateways.
United Arab Emirates
Pharmaceutical and perishable cargo flows concentrate in Dubai's logistics free zones, where Emirates SkyCargo operates dedicated cold chain infrastructure. The national aviation regulator aligns with ICAO carbon offsetting standards while preserving operational flexibility for hub carriers. Dubai International and Al Maktoum airports coordinate slot allocations to accommodate peak-season freighter movements from European and Asian origins.
Switzerland
Temperature-controlled biologics shipments from Basel and Geneva pharmaceutical clusters sustain premium yields on trans-Atlantic lanes. Swissmedic enforces serialization and traceability standards that elevate air cargo over ocean alternatives for high-value therapies. Zurich anchors specialized ground handling infrastructure where GDP-certified facilities support continuous cold chain documentation requirements.
Air Cargo Market Vendor Landscape
Capital-heavy integrated carriers compete with asset-light freight forwarders for control over capacity allocation and pricing. The market structures around three tiers: global express networks owning dedicated freighter fleets, specialized all-cargo airlines serving niche trade lanes, and non-asset-based intermediaries aggregating fragmented carrier supply. Strategic moves concentrate on hub consolidation at secondary airports, sustainable aviation fuel procurement partnerships, and direct contracting relationships with pharmaceutical shippers that bypass traditional forwarder markups.
Within the integrated express tier, FedEx Express and UPS Airlines exemplify end-to-end network control through owned fleet and facility infrastructure. Among specialized all-cargo operators, Cargolux occupies a position serving outsized and project cargo segments with premium yield characteristics. DHL Aviation anchors the European hub-and-spoke model from its Leipzig base, representing the integrator strategy applied to intra-Asia connectivity.
| Leading Market Players |
|---|
| Emirates SkyCargo |
| Cathay Pacific Cargo |
| FedEx Express |
| Atlas Air |
| Korean Air Cargo |
| UPS Airlines |
| DHL Aviation |
| Cargolux |
| Qatar Airways Cargo |
| Others |
Supply Flow & Price Mechanics
Express-dedicated freighter premiums versus belly-hold commodity rates create a bifurcated pricing architecture that simultaneously rewards integrated network control and penalizes fragmented capacity sourcing. This divergence manifests in carrier investment patterns at Dubai and Leipzig, where hub consolidation captures pharmaceutical reliability premiums, while general cargo forwarders absorb fuel surcharge volatility on spot-market belly space.
Pricing Analysis
Margin tightening in general cargo belly-hold reflects chronic overcapacity on passenger wide-bodies recovering from pandemic fleet reductions. Three-tier pricing structure across express guaranteed, standard freight, and deferred economy levels segments buyer price sensitivity, with e-commerce platforms least sensitive to rate fluctuations and commodity manufacturers most responsive. Cost-down pressure on narrow-body regional freighters accelerates because Chinese domestic e-commerce networks are converting retired passenger aircraft at scale.
Supply Chain Analysis
Freighter feedstock costs hinge on passenger aircraft retirement cycles and conversion slot availability at facilities in China, Israel, and the United States. Supply chains draw from airframe OEMs in France and the United States, engine manufacturers in the United Kingdom and United States, and specialized cargo handling equipment producers in Germany and the Netherlands. Distribution runs through bilateral slot negotiations at congested hubs rather than open capacity markets, creating tariff-like barriers at Frankfurt and Hong Kong.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous ground handling systems are displacing labor-intensive legacy operations, compressing turnaround times and reshaping hub economics across major cargo airports.
For Market Incumbents: Extend dedicated freighter fleet utilization through narrow-body conversion programs targeting secondary Southeast Asian cities. Consolidate ground handling market share by deploying automated storage retrieval systems at Zurich and Dubai before regulatory mandates accelerate. Lock in sustainable aviation fuel offtake agreements with European producers to hedge ReFuelEU Aviation compliance cost exposure. For New Entrants and Emerging Players: Blockchain-IoT cargo tracking convergence offers a technology-first wedge into pharmaceutical shipper procurement cycles. Target temperature-controlled biologics lanes between Switzerland and the United Arab Emirates where GDP-certified infrastructure remains concentrated among incumbent handlers. Lead with real-time condition monitoring platforms that reduce insurance premiums for high-value pharmaceutical shipments. For Investors and Strategic Acquirers: Exit pathways concentrate in specialized all-cargo operators with outsized cargo capabilities and premium yield profiles on oil-and-gas extraction routes. Long-term viability favors carriers with secured SAF procurement pipelines and established pharmaceutical cold chain certifications. Watch for ICAO carbon offsetting standard enforcement intensity as the signal indicating accelerated fleet renewal capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Narrow-Body Freighter Conversion | Secondary city point-to-point networks bypass congested primary hubs in Vietnam and Indonesia. |
| Sustainable Aviation Fuel Partnership | ReFuelEU Aviation compliance secures operational continuity for EU departure routes. |
| Blockchain-IoT Integration | Swiss pharmaceutical shippers mandate immutable documentation for contract renewal eligibility. |
| Secondary Hub Consolidation | Leipzig and Dubai capture transshipment volume from slot-constrained Frankfurt and Hong Kong. |
| Direct Shipper Contracting | Amazon Air and Alibaba bypass forwarder markups on trans-Pacific manufacturing corridors. |
Methodological Framework
Independent corroboration across carrier network planners, pharmaceutical logistics directors, and ground handling operations managers underwrites the qualitative findings. Primary interviews with freighter conversion specialists, customs modernization officials, and sustainable aviation fuel procurement leads combined with secondary validation from ICAO regulatory filings, FAA certification databases, and EU ETS transaction records. Bottom-up capacity deployment analysis and top-down trade flow estimation triangulate market sizing.
Rate-of-change decomposition across service type, cargo category, end-user industry, and delivery mode dimensions structures the analytical framework. CAGRs derive from fleet delivery schedules, e-commerce growth trajectories, and pharmaceutical cold chain expansion curves. Modeling incorporates jet fuel price scenarios, slot allocation reform timelines, and surface transport substitution elasticities across the projection horizon.
Several conditions sit outside the modeled scope, including geopolitical airspace closures, pandemic-scale passenger fleet groundings, and radical sustainable aviation fuel cost breakthroughs. Forecasts reflect assumptions about regulatory enforcement intensity and carrier compliance investment pacing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
Germany Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Fifth-Party Logistics Market
Logistics and Shipping
United States Contract Logistics Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
India Contract Logistics Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market
Logistics and Shipping
China Freight Forwarding Market
Logistics and Shipping
Asia-Pacific less-Than Container Load (LCL) Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
Slovakia Freight and Logistics Market
Logistics and Shipping
United States Digital Freight Forwarding Market
Logistics and Shipping
China Automotive Logistics Market