
 Saudi Arabia Freight and Logistics Market | 2026-2036
Saudi Arabia Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Freight and Logistics Market Outlook
E-commerce fulfillment demand is bifurcating the buyer base between omnichannel retailers and traditional manufacturers. Almajdouie leverages its domestic heavy-lift infrastructure to anchor project cargo flows from Jubail Industrial City. DHL Group sustains cross-border express volumes through regulatory alignment with Saudi Customs Authority digital clearance platforms. Bahri dominates maritime corridors linking King Abdullah Port to Red Sea and Arabian Gulf transshipment nodes.
Freight and logistics encompasses the physical movement, storage, and documentation of goods across multimodal networks, typically measured by ton-kilometer throughput, warehouse utilization rates, and customs clearance velocity. The sector orchestrates supply chain continuity for industries ranging from petrochemicals to consumer retail, with cold chain specifications and hazardous materials handling protocols defining operational parameters. Transportation services absorb the largest value pool as highway fleet electrification and rail freight expansion redraw modal economics. Warehousing is gaining structural margin as bonded zone expansions near King Khalid International Airport and Jeddah Islamic Port attract third-party operators seeking proximity to consumption clusters. IoT-enabled fleet tracking is displacing manual dispatch systems among mid-sized carriers competing for contract logistics mandates from automotive assemblers in the Eastern Province.
The General Authority of Civil Aviation governs air cargo security standards and freighter slot allocations at Saudi airports, while the Saudi Standards, Metrology and Quality Organization sets palletization and packaging compliance thresholds for cross-border shipments. The National Transport and Logistics Strategy imposes fleet modernization timelines and driver certification requirements that filter market access for smaller trucking operators. Stakeholders must weigh capital deployment between autonomous yard vehicle pilots and conventional warehouse automation as regulatory sandboxes for emerging technologies take shape.
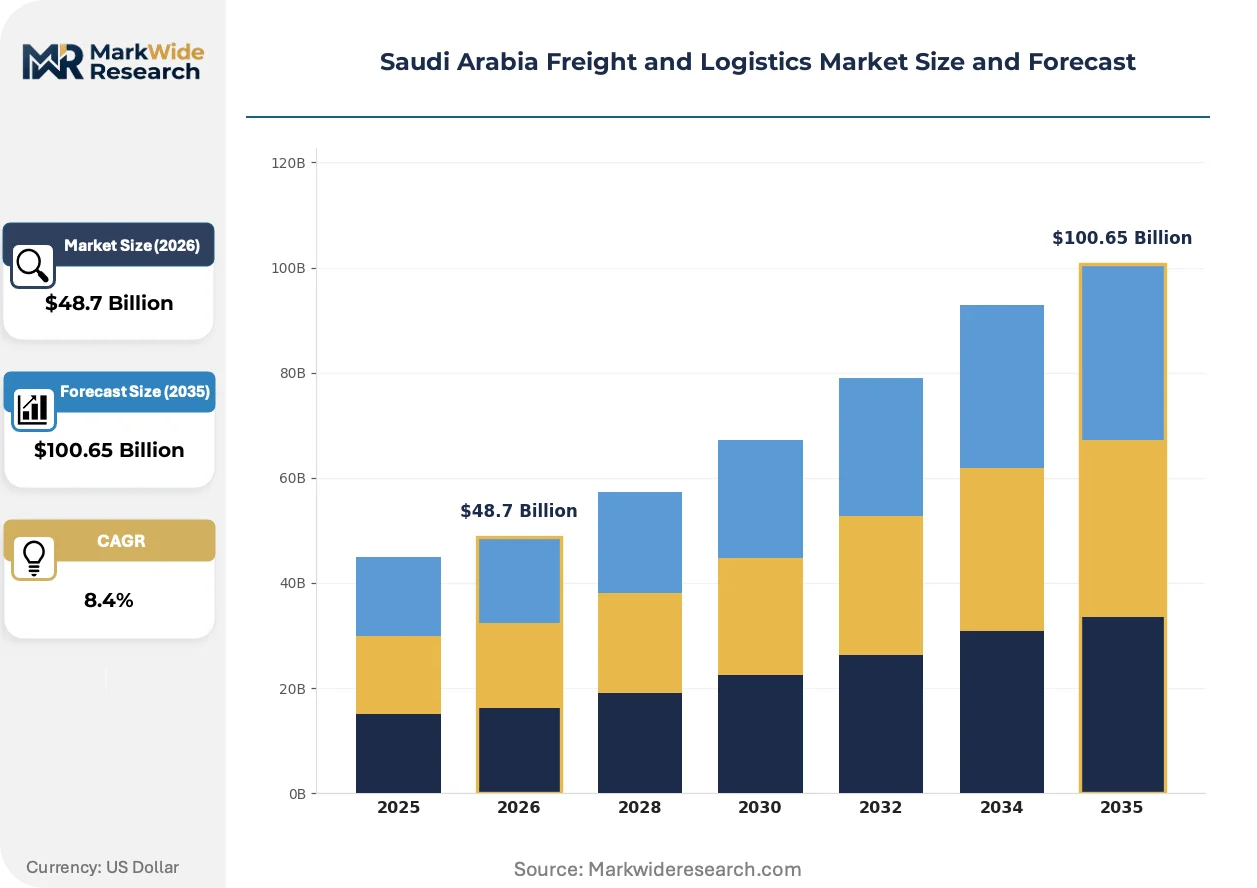
Market Dynamics
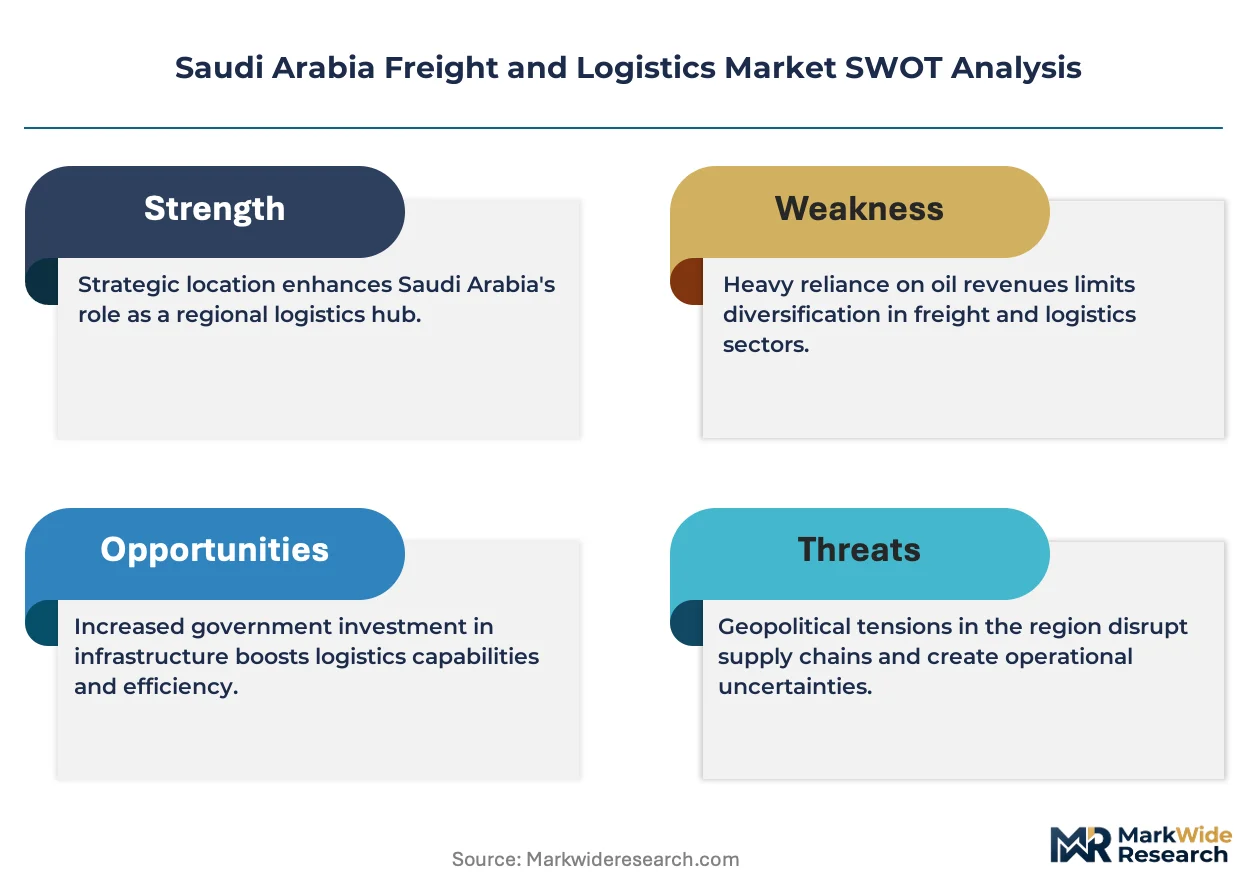
Vision 2030 infrastructure mandates are compressing project timelines across Saudi Arabia's freight and logistics sector, forcing carriers to pre-position capacity ahead of demand rather than respond to it. The National Transport and Logistics Strategy imposes fleet modernization deadlines that filter out smaller operators unable to absorb electrification capex.
Growth Catalysts
- E-commerce fulfillment density:Omnichannel retailers are pulling investment toward automated warehousing in Riyadh and Jeddah consumption clusters. Last-mile networks are densifying around these hubs.
- SFDA cold chain mandates:Pharmaceutical temperature-control requirements are expanding specialized refrigerated fleet capacity. Compliance investments are creating barrier-to-entry advantages for certified carriers.
- Red Sea transshipment positioning:King Abdullah Port's capacity upgrades are anchoring maritime corridor flows between Arabian Gulf and East African markets. Regional hub status is consolidating feeder route economics.
Market Restraints
- Driver certification scarcity:The National Transport and Logistics Strategy imposes mandatory retraining timelines that constrict qualified labor supply. Smaller fleet operators face operational suspension risks.
- Industrial zone concentration risk:Jubail Industrial City and Ras Al-Khair generate disproportionate project cargo volumes. Pipeline disruptions or industrial output fluctuations transmit directly to carrier utilization rates.
- Bonded zone land cost inflation:Proximity premiums near King Khalid International Airport and Jeddah Islamic Port are compressing third-party operator margins. Warehouse automation capex requirements compound the pressure.
Strategic Opportunities
- Neom logistics corridor development:The linear city's construction phase is generating demand for heavy-lift and modular transport specialization. Project cargo expertise developed here transfers to future gigaprojects.
- Hydrogen fuel cell pilot lanes:The Ministry of Energy's clean hydrogen initiatives are creating regulatory sandboxes for zero-emission trucking corridors. Early fleet adopters gain preferential route access.
- Cross-border digital clearance integration:Saudi Customs Authority platform alignment with UAE and Bahrain systems is compressing Gulf Cooperation Council transit times. Integrated operators capture time-sensitive express volumes.
Industry Challenges
- Telematics integration complexity:IoT-enabled fleet tracking deployment requires retrofitting legacy dispatch systems across fragmented mid-sized carrier bases. Data standardization gaps persist between proprietary platforms.
- Autonomous yard vehicle pilot scaling:Regulatory sandboxes for emerging technologies lack certification precedents. Operators face uncertainty on liability frameworks and insurance coverage during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Freight and Logistics Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Transportation, Freight Forwarding, Customs Brokerage End User: E-Commerce, Manufacturing, Retail, Automotive Technology: IoT, Blockchain, Cloud Computing, Automation Distribution Channel: Direct Shipping, Third-Party Logistics, Contract Logistics, Express Delivery |
| Companies Covered | SMSA Express Transportation, Aramex, Almajdouie, BAFCO International Shipping and Logistics, DB Schenker, Bahri, DHL Group, Kuehne+Nagel, Binzagr Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Freight and Logistics Market Strategic Shifts
Digital freight matching platforms are compressing spot market transaction cycles across Saudi Arabia's highway networks. Automation investments are bifurcating operator capabilities between technology-enabled scale players and conventional asset-heavy models.
Blockchain-enabled bill-of-lading documentation is supplanting paper-based customs clearance workflows at Saudi Arabian ports. Petrochemical exporters and automotive assemblers in the Eastern Province are piloting distributed ledger verification to compress documentary release times. The structural consequence is collapsing working capital requirements for cross-border shippers while raising interoperability demands on legacy enterprise resource planning systems.
The National Transport and Logistics Strategy mandates fleet electrification timelines that accelerate battery-electric and hydrogen fuel cell truck adoption. Commercial vehicle importers must certify zero-emission readiness to maintain operating licenses beyond statutory deadlines. Heavy-duty segments serving mining and construction verticals face the steepest compliance gradients given payload-range trade-offs in desert operating conditions.
Contract logistics buyers are unbundling transportation and warehousing procurement to optimize unit economics across volatile fuel and real estate cost environments. Automotive assemblers in Jubail Industrial City are segmenting carrier selection by lane density rather than awarding integrated national mandates. The shift is most visible among multinational manufacturers with established regional supply chain finance capabilities seeking to arbitrage modal cost fluctuations.
Saudi Arabia Freight and Logistics Market Segmentation
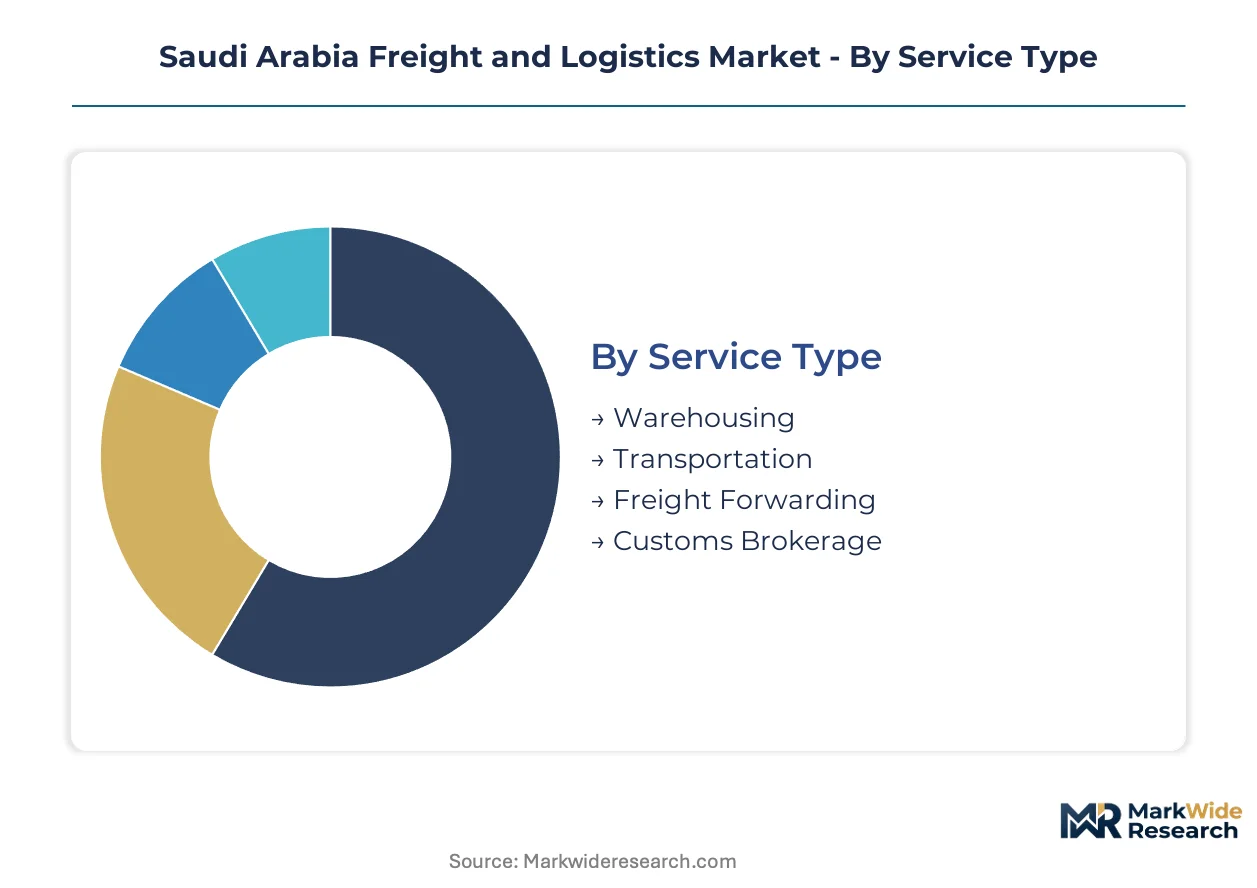
Service type concentration determines margin capture in Saudi Arabia's freight and logistics market. End-user demand patterns and technology deployment intensity further stratify competitive positioning across carrier portfolios.
Service Type:
Margin pools concentrate in value-added warehousing and integrated freight forwarding where bonded zone proximity commands rate premiums.
- Warehousing:Climate-controlled facilities and automated storage retrieval systems define operational specifications. Riyadh and Jeddah consumption clusters are pulling speculative development near King Khalid International Airport and Jeddah Islamic Port, with bonded zone land cost inflation compressing third-party operator returns.
- Transportation:Fleet assets span highway trucking, rail freight, and coastal shipping modalities. The National Transport and Logistics Strategy electrification mandates are filtering market access as smaller operators face capital constraints on battery-electric and hydrogen fuel cell conversions.
- Freight Forwarding:Documentation coordination and multimodal routing optimization. SFDA cold chain mandates are expanding specialized pharmaceutical forwarding certifications.
- Customs Brokerage:Saudi Customs Authority platform integration and clearance velocity management. Digital clearance alignment with UAE and Bahrain systems is compressing Gulf Cooperation Council transit documentation cycles.
Transportation holds installed capacity. Warehousing is rotating up the share rankings.
End User:
Application intensity varies by inventory velocity requirements and regulatory compliance burden.
- E-Commerce:Omnichannel fulfillment networks demanding same-day and next-day delivery density. Automated last-mile sorting hubs in Riyadh and Jeddah are absorbing venture capital deployment ahead of demand maturation.
- Manufacturing:Just-in-time component feeding and finished goods distribution. Jubail Industrial City petrochemical and automotive assemblers are segmenting carrier selection by lane density rather than awarding integrated national mandates.
- Retail:Seasonal inventory pre-positioning and promotional surge capacity. Temperature-sensitive food retail is expanding refrigerated fleet contracting.
- Automotive:Knock-down kit inbound logistics and vehicle distribution outbound. Eastern Province assembly plants are piloting IoT-enabled yard management for chassis tracking.
E-Commerce commands rate premiums per shipment. Manufacturing anchors contract volume stability.
Technology:
Deployment maturity separates technology-enabled scale players from conventional asset-heavy models.
- IoT:Fleet telematics and warehouse sensor networks generating real-time visibility. Retrofitting legacy dispatch systems across fragmented mid-sized carrier bases faces data standardization gaps between proprietary platforms.
- Blockchain:Distributed ledger documentation for bill-of-lading verification. Petrochemical exporters are piloting documentary release compression at King Abdullah Port.
- Cloud Computing:Software-as-a-service transportation management and warehouse management systems. Subscription pricing is displacing perpetual license models among third-party logistics operators.
- Automation:Autonomous yard vehicles and robotic picking systems. Regulatory sandboxes lack certification precedents, creating liability framework uncertainty during transition periods.
IoT holds installed base penetration. Automation is climbing the fastest on capital deployment metrics.
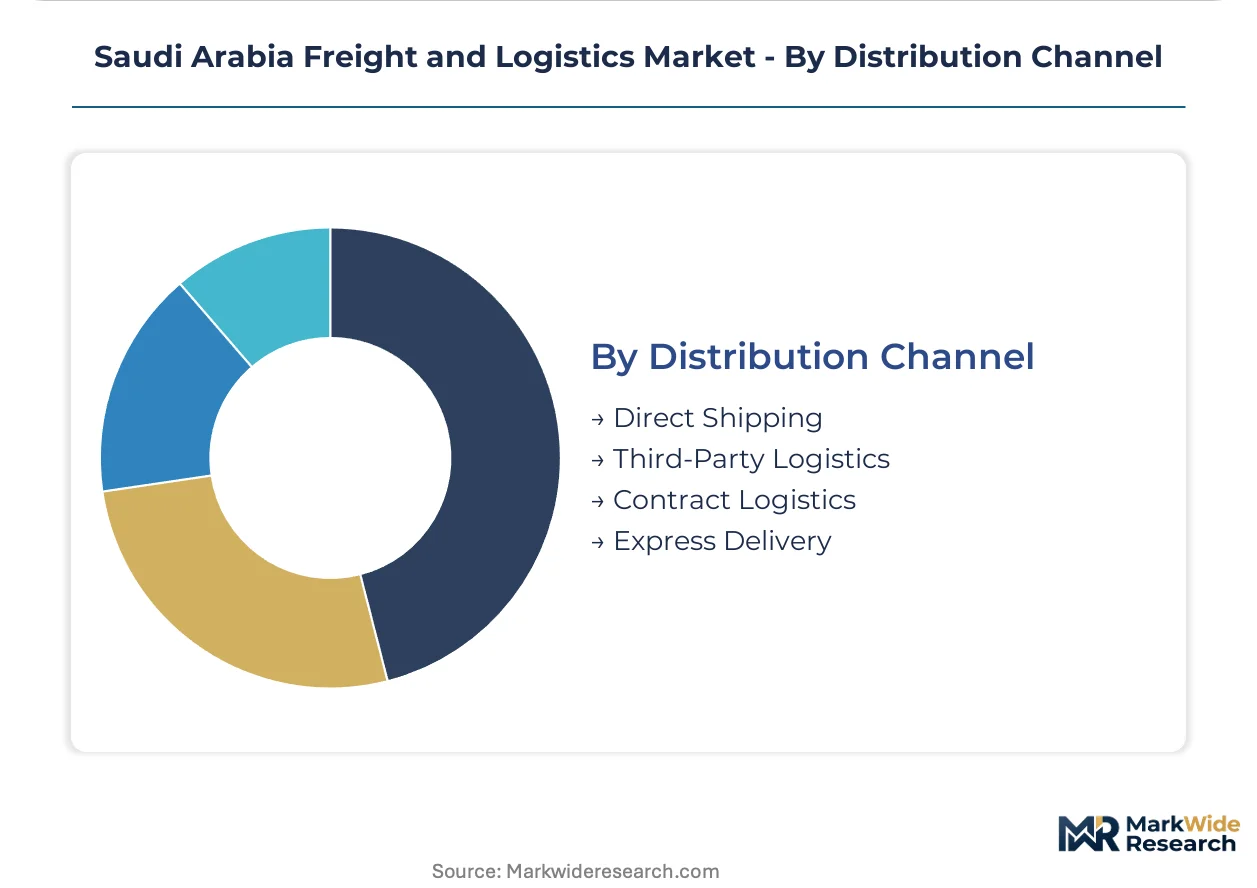
Distribution Channel:
Channel selection reflects shipper sophistication and cargo time-sensitivity requirements.
- Direct Shipping:Asset-owning carriers contracting directly with large-volume shippers. Mining and construction verticals favor direct relationships for heavy-lift project cargo.
- Third-Party Logistics:Outsourced supply chain management combining transportation and warehousing. Unbundling trends are separating procurement decisions for volatile cost arbitrage.
- Contract Logistics:Long-term dedicated facility and fleet arrangements. Automotive assemblers in Jubail Industrial City are shortening contract durations to retain modal flexibility.
- Express Delivery:Time-definite small parcel networks with premium rate structures. Cross-border digital clearance integration is compressing Gulf Cooperation Council transit times for integrated operators.
Third-Party Logistics anchors contract value. Express Delivery is gaining share fastest on e-commerce volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier routing decisions concentrate in corridors linking consumption clusters to industrial zones and transshipment nodes. The National Transport and Logistics Strategy redistributes capacity investments across sub-regional logistics hubs.
Riyadh
E-commerce fulfillment networks and automated warehousing investments dominate capital deployment. King Khalid International Airport bonded zone expansions attract third-party operators seeking proximity to consumption clusters. Land cost inflation near the airport compresses operator margins while automation capex requirements intensify.
Eastern Province
Jubail Industrial City petrochemical flows and Ras Al-Khair mining outputs anchor project cargo volumes. The National Transport and Logistics Strategy fleet modernization deadlines filter smaller operators unable to absorb electrification investments. Heavy-lift infrastructure serves modular transport for gigaproject construction phases.
Western Region
Jeddah Islamic Port capacity upgrades reshape maritime corridor economics for Red Sea transshipment. Last-mile networks densify around Jeddah consumption clusters as omnichannel retailers pre-position inventory. Saudi Customs Authority digital clearance platforms compress documentary release cycles.
NEOM Northwest
The linear city's construction phase generates demand for specialized heavy-lift and modular transport capabilities. Hydrogen fuel cell pilot lanes create regulatory sandboxes for zero-emission trucking corridors under Ministry of Energy clean hydrogen initiatives. Project cargo expertise developed here transfers to subsequent gigaprojects.
Saudi Arabia Freight and Logistics Market Competitive Environment
Concentration sits with diversified logistics conglomerates and specialized regional carriers. The market structure tiers between asset-heavy national operators and technology-enabled international forwarders. Two strategic archetypes dominate: integrated multimodal providers with bonded zone warehousing assets, and express specialists leveraging customs platform integration. Capacity pre-positioning ahead of Vision 2030 infrastructure timelines and fleet electrification compliance investments represent the dominant competitive moves.
Within the integrated multimodal tier, Almajdouie anchors project cargo flows through domestic heavy-lift infrastructure, while Bahri occupies a position linking maritime corridors to Red Sea and Arabian Gulf transshipment nodes. Among international forwarders, DHL Group exemplifies regulatory alignment with Saudi Customs Authority digital clearance platforms.
| Leading Market Players |
|---|
| SMSA Express Transportation |
| Aramex |
| Almajdouie |
| BAFCO International Shipping and Logistics |
| DB Schenker |
| Bahri |
| DHL Group |
| Kuehne+Nagel |
| Binzagr Company |
| Others |
Value Chain & Pricing Dynamics
SFDA cold chain certification gates both carrier qualification and rate differentiation simultaneously. Operators without pharmaceutical-grade refrigerated fleet capacity face exclusion from premium forwarding tiers while certified incumbents command sustained margin premiums on temperature-controlled lanes.
Pricing Analysis
The National Transport and Logistics Strategy dictates the pricing tier structure through fleet electrification compliance deadlines. Three-tier pricing structure across premium certified, standard compliant, and economy non-compliant fleet tiers separates carriers by emission readiness. Cost compression in economy tiers is intensifying because smaller operators face operational suspension risks from driver certification scarcity. E-commerce retailers demonstrate highest price sensitivity per shipment, while pharmaceutical manufacturers accept premium rates for validated cold chain integrity.
Supply Chain Analysis
Container availability fluctuations on Asia-Saudi trade lanes feed directly into inbound component costs for automotive assemblers. Manufacturing inputs draw from China, Germany, and Japan for knock-down kit feeding to Jubail Industrial City plants. Supply chain risk centers on Red Sea maritime chokepoint exposure affecting King Abdullah Port throughput. Distribution runs through bonded zone consolidation at King Khalid International Airport and Jeddah Islamic Port before final-mile injection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among omnichannel retailers consolidating fulfillment procurement across fewer integrated logistics providers. This consolidation compresses rate negotiation leverage for fragmented mid-sized carriers.
For Market Incumbents: Consolidate bonded zone warehousing positions near King Khalid International Airport and Jeddah Islamic Port before land cost inflation accelerates further. Acquire specialized cold chain fleet assets to defend against emerging pharmaceutical-certified entrants. Pre-position heavy-lift capacity for Neom corridor construction phases to anchor project cargo relationships.
For New Entrants and Emerging Players: Differentiate on hydrogen fuel cell fleet readiness to capture preferential route access under Ministry of Energy clean hydrogen pilots. Target express delivery white space in secondary cities outside Riyadh-Jeddah concentration clusters. Lead with Saudi Customs Authority digital platform integration as primary go-to-market credential.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to monetize captive logistics assets. Long-term viability hinges on electrification compliance readiness and customs platform integration depth. Monitor King Abdullah Port transshipment volume trends as inflection indicator for Red Sea corridor economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Zone Capacity Expansion | Proximity premiums near King Khalid International Airport justify automation capex for third-party operators. |
| Cold Chain Certification Investment | SFDA pharmaceutical mandates create barrier-to-entry advantages for refrigerated fleet specialists. |
| Hydrogen Fuel Cell Fleet Pilot | Ministry of Energy regulatory sandboxes grant preferential corridor access to early zero-emission adopters. |
| Cross-Border Digital Clearance Integration | Saudi Customs Authority platform alignment with UAE and Bahrain systems compresses Gulf Cooperation Council transit documentation. |
| Autonomous Yard Vehicle Deployment | Regulatory sandbox participation at Neom logistics corridors builds liability framework precedents for scaling. |
Study Parameters
Initial hypotheses were tested against primary input from fleet operations directors, customs brokerage managers, pharmaceutical supply chain leads, and e-commerce fulfillment executives and refined through secondary validation. Primary fieldwork combined structured interviews with Saudi Customs Authority platform users and bonded zone operators. Secondary sources encompassed General Authority of Civil Aviation freighter slot allocation records, National Transport and Logistics Strategy compliance filings, and King Abdullah Port throughput statistics. Bottom-up carrier capacity modeling and top-down consumption cluster demand estimation were triangulated against Vision 2030 infrastructure spend projections.
Variance decomposition across service type, end user, technology deployment, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level capacity buildout trajectories and demand elasticity estimates. Forecast inputs incorporated fleet electrification compliance cost curves and bonded zone land availability constraints.
Material uncertainties — Vision 2030 project timeline acceleration, Red Sea maritime security disruptions, and SFDA mandate enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory sandbox expansion and customs platform interoperability progression. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
Middle Mile Delivery Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Sea Freight Forwarding Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Vietnam Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
Chile Third-Party Logistics (3PL) Market
Logistics and Shipping
Vietnam Freight and Logistics Market