
 India 3PL Market | 2026-2036
India 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
India 3PL Market Foresight
Software-defined freight orchestration is restructuring contract structures across Indian logistics. Delhivery Ltd. leverages proprietary routing algorithms to dominate last-mile density in metropolitan zones. Mahindra Logistics Ltd. anchors industrial freight through captive automotive relationships. TVS Supply Chain Solutions Ltd. specializes in engineering-led aftermarket parts distribution.
Third-party logistics encompasses outsourced transportation, warehousing, and inventory management executed under service-level agreements with defined KPI thresholds such as order-cycle times and fill-rate percentages. Its primary commercial purpose is converting fixed distribution assets into variable costs for shippers. Transportation and warehousing together absorb the dominant share of 3PL revenue as e-commerce fulfillment demands expand cold-chain and express infrastructure. Value-added services including kitting, labeling, and reverse logistics capture widening margin pools as brands outsource post-purchase operations.
BIS standards govern warehouse safety equipment and vehicle dimensions, while GST Council directives determine interstate tax treatment that shapes hub location strategy. CEA regulations on cold-storage energy efficiency and DGFT documentation requirements for bonded warehousing further constrain operating models. Stakeholders must monitor how state-level logistics park approvals and upcoming data-localization mandates for supply-chain platforms reshape network design decisions.
Market Dynamics
Software-defined freight orchestration is restructuring contract structures across Indian logistics, converting fixed distribution assets into variable costs while compressing order-cycle times through algorithmic route optimization. The Production-Linked Incentive scheme and GST harmonization are simultaneously reshaping compliance requirements and hub location strategy.
Growth Catalysts
- PLI scheme incentives:Manufacturing subsidies under India's Production-Linked Incentive framework are expanding contract logistics demand as new production facilities require integrated warehousing and transportation networks.
- E-commerce fulfillment density:Express delivery expectations from digital retail platforms are driving cold-chain infrastructure investment and last-mile network expansion into tier-two cities.
- GST Council harmonization:Interstate tax simplification is consolidating warehouse footprints and enabling hub-and-spoke distribution models previously constrained by state-level tax friction.
Market Restraints
- Diesel price volatility:Road freight operators face margin compression from fuel cost fluctuations that cannot be fully passed through in fixed-rate contracts.
- Land acquisition constraints:Logistics park development encounters regulatory delays and fragmented land titles, particularly in Maharashtra and Karnataka corridors.
- Driver availability shortage:Long-haul trucking suffers from declining workforce participation and inadequate training infrastructure for specialized vehicle categories.
Strategic Opportunities
- Tier-three city penetration:Underdeveloped distribution infrastructure in smaller urban centers offers first-mover advantage for express delivery networks.
- CEA energy efficiency mandates:Cold-storage operators can capture regulatory tailwinds by deploying solar-integrated refrigeration systems compliant with Central Electricity Authority standards.
- AI-IoT convergence:Predictive inventory positioning through sensor networks and machine learning algorithms enables dynamic safety-stock optimization for automotive aftermarket parts.
Industry Challenges
- Warehouse management system integration:Legacy ERP platforms at mid-market shippers resist API-based connectivity with modern 3PL visibility tools.
- BIS certification timelines:Safety equipment standards for material handling equipment create procurement delays that compress implementation schedules.
- Specialized cold-chain talent:Temperature-controlled logistics requires certified operators in short supply, particularly for pharmaceutical and perishable verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India 3PL Market |
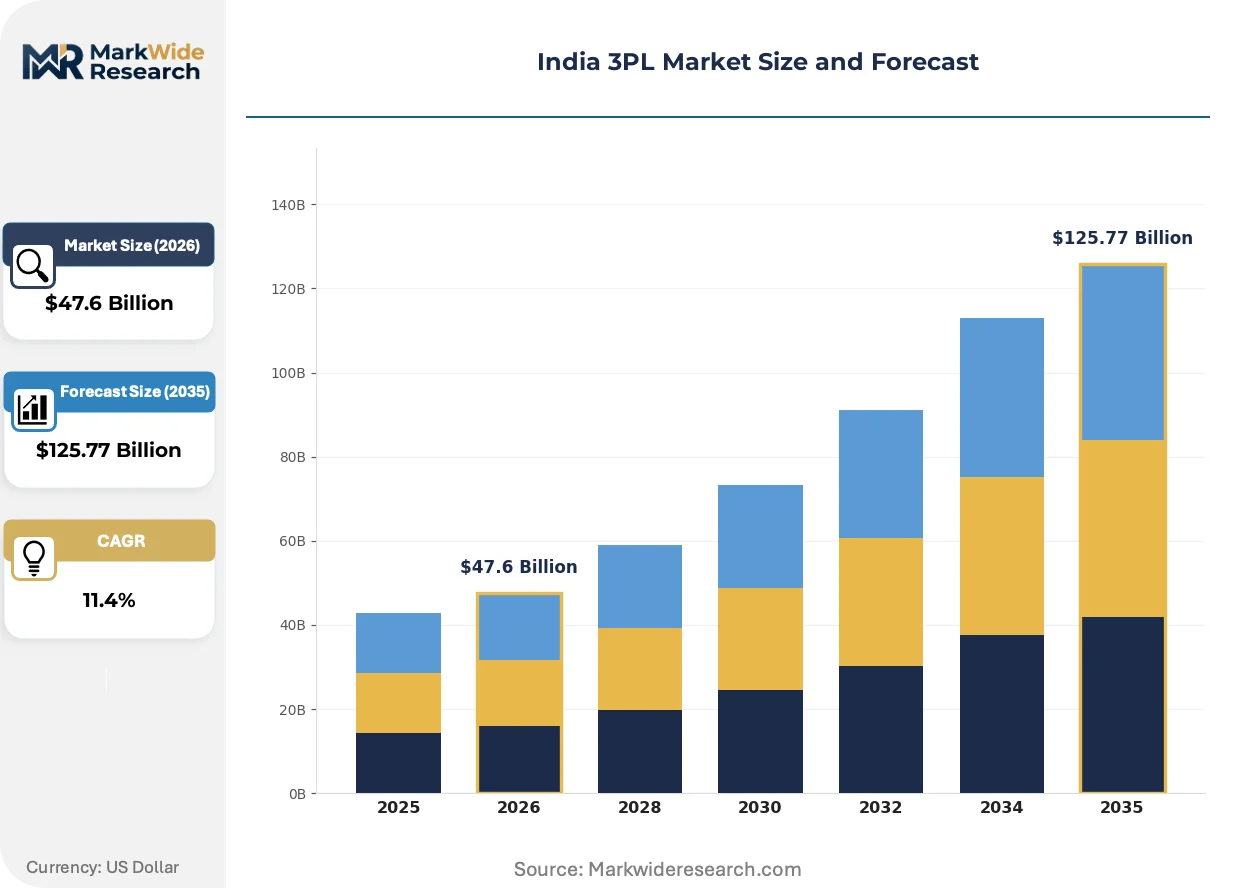
| Market Size in 2026 | $47.6 Billion |
| Market Size in 2035 | $125.77 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Value-Added Services End User: Retail, E-commerce, Manufacturing, Automotive Delivery Model: Direct Delivery, Store Delivery, Same-Day Delivery, Scheduled Delivery Technology: Warehouse Management System, Transportation Management System, RFID, IoT |
| Companies Covered | TVS Supply Chain Solutions Ltd., Kuehne + Nagel India Pvt. Ltd., Allcargo Logistics Ltd., Safexpress Pvt. Ltd., FedEx, DHL Supply Chain India, Delhivery Ltd., Snowman Logistics, Mahindra Logistics Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India 3PL Market Shifts & Advancements
Digital freight matching and autonomous warehouse robotics are compressing labor dependency while reconfiguring asset-light operating models. The convergence of regulatory data mandates and cloud infrastructure is accelerating platform-based logistics orchestration.
Proprietary routing algorithms are expanding into contract structuring as 3PL providers embed dynamic pricing engines that adjust rates based on real-time capacity utilization. E-commerce platforms and automotive OEMs are adopting these tools fastest, compressing traditional annual rate negotiations into quarterly or monthly adjustments tied to service-level performance.
BIS standards for warehouse safety equipment and vehicle dimensions are tightening compliance verification requirements. The Central Electricity Authority's cold-storage energy efficiency regulations are forcing refrigeration asset upgrades. Pharmaceutical and food processing verticals face the steepest retrofit costs as they reconcile legacy infrastructure with mandatory energy consumption benchmarks.
Shippers are consolidating vendor relationships around integrated service providers capable of spanning first-mile pickup through last-mile delivery. Small and mid-market retailers are abandoning point-solution freight brokers in favor of full-stack 3PL partnerships. Tamil Nadu and Gujarat manufacturing clusters exhibit this behavioral shift most prominently as export-oriented firms seek bonded warehousing and customs clearance integration.
India 3PL Market Segmentation
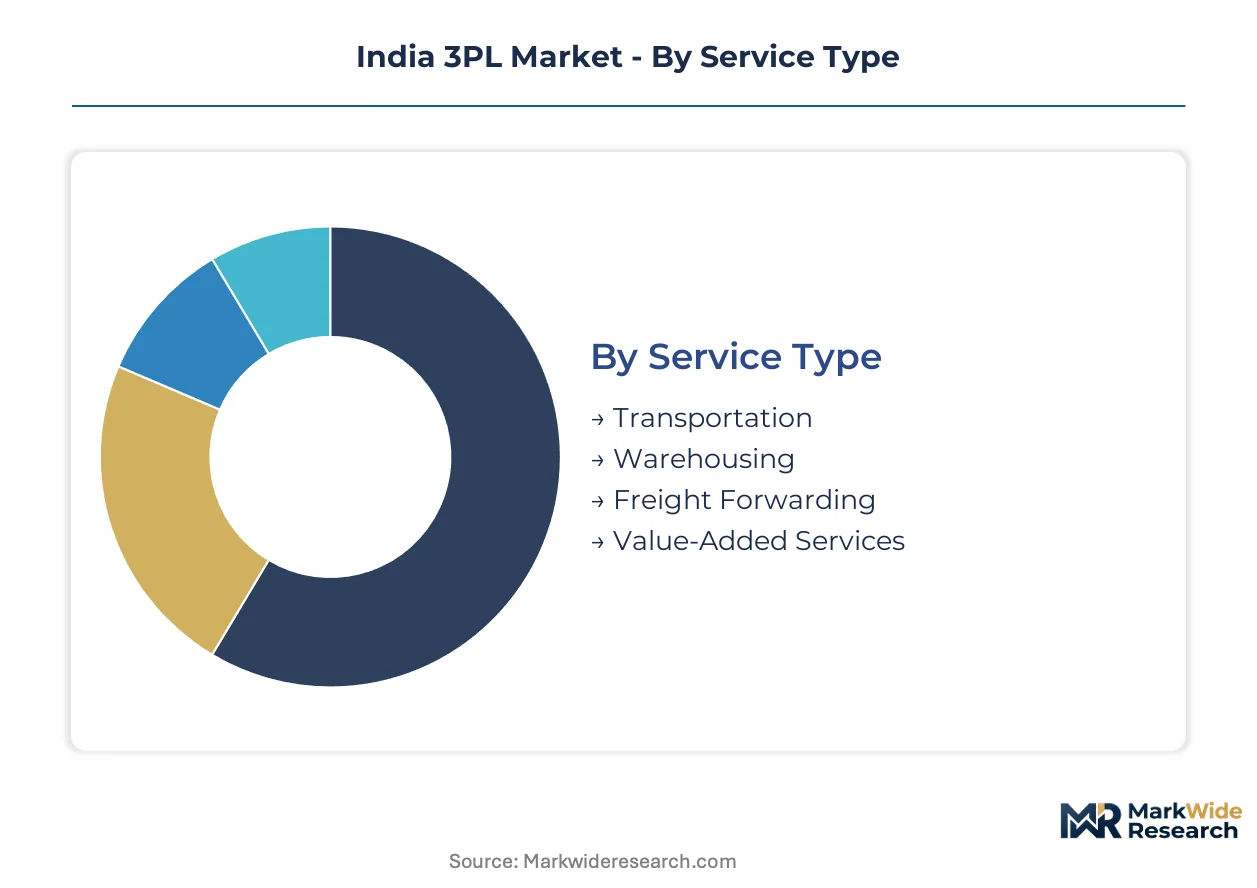
3PL service configuration in India follows distinct procurement patterns based on shipper maturity and vertical requirements. Segment boundaries blur as integrated providers bundle transportation with warehousing under unified SLA frameworks.
Service Type:
Standalone transportation contracts dominate spot-market procurement, while embedded warehousing arrangements anchor multi-year enterprise relationships.
- Transportation:Full-truckload and express parcel movements constitute the revenue foundation, with dedicated fleet contracts absorbing fuel volatility through index-linked pricing mechanisms. E-commerce platforms in Maharashtra and Karnataka corridors drive contracted lane density for next-day delivery commitments.
- Warehousing:Multi-client distribution centers convert fixed real estate into variable storage costs through shared-space models. GST harmonization has consolidated hub footprints around Nagpur, Chennai, and Delhi-Mumbai Industrial Corridor nodes.
- Freight Forwarding:Customs brokerage and international documentation services support export-oriented manufacturing clusters.
- Value-Added Services:Kitting, labeling, and returns processing capture margin expansion from brand outsourcing of post-purchase operations.
Volume placements concentrate in Transportation; the faster expansion belongs to Value-Added Services.
End User:
Customer type determines contract duration and technology integration depth, with digital-native sectors demanding API-first visibility architectures.
- E-commerce:Express fulfillment networks require cold-chain and same-day infrastructure investment across tier-two cities. Platform consolidation around mega-sales events creates demand spikes that strain contracted capacity.
- Automotive:Just-in-sequence delivery to assembly plants mandates engineering-led aftermarket parts distribution with zero-defect tolerance. OEM captive relationships anchor long-term contract logistics partnerships.
- Retail:Traditional brick-and-mortar replenishment operates on weekly replenishment cycles with lower technology penetration.
- Manufacturing:PLI scheme beneficiaries require integrated inbound material flow and finished goods distribution.
Contract values peak with Automotive; E-commerce is expanding most quickly.
Delivery Model:
Speed tier selection reflects urban density and inventory positioning strategy, with metropolitan zones enabling cost-effective rapid fulfillment.
- Same-Day Delivery:Hyperlocal micro-fulfillment networks position inventory within 15-kilometer radii of demand clusters. Bengaluru and Mumbai density supports viable unit economics for premium service tiers.
- Scheduled Delivery:Appointment-based windows reduce failed delivery rates for bulky goods and B2B shipments. Industrial corridors favor predictable arrival windows over velocity.
- Direct Delivery:Shipper-to-consignee movements bypass intermediate sortation for time-definite requirements.
- Store Delivery:Click-and-collect integration with retail footprints leverages existing real estate for last-mile density.
Scheduled Delivery captures current volume leadership; Same-Day Delivery shows the steepest expansion trajectory.
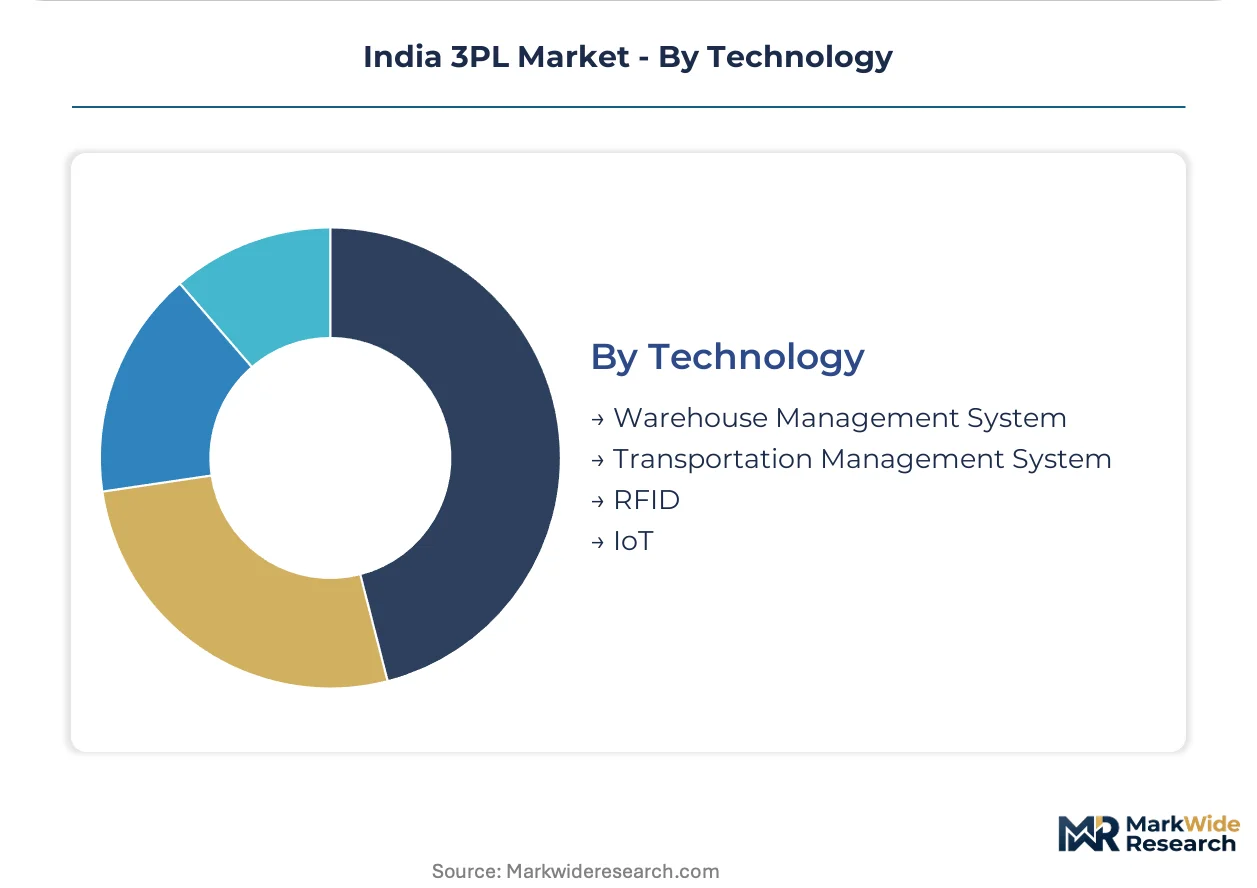
Technology:
Adoption maturity splits between foundational execution systems and emerging sensor networks, with mid-market shippers lagging on API integration.
- Warehouse Management System:Inventory tracking, labor optimization, and slotting algorithms form the operational backbone. BIS certification timelines for material handling equipment create procurement friction during implementation.
- IoT:Cold-chain temperature monitoring and vehicle telematics enable predictive intervention and insurance premium reduction. CEA energy efficiency mandates accelerate solar-integrated refrigeration deployment.
- Transportation Management System:Route optimization and carrier selection engines compress freight spend for large shippers.
- RFID:Item-level tracking penetrates high-value verticals while unit economics constrain broad retail adoption.
Warehouse Management System installations dominate current deployments; IoT sensor networks are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors India's 3PL activity through the Delhi-Mumbai Industrial Corridor, where express fulfillment networks and automotive parts distribution concentrate. The Maharashtra logistics cluster processes the highest freight tonnage nationally. State-level logistics park approvals from Maharashtra, Karnataka, Tamil Nadu, and Gujarat reshape network design decisions.
Maharashtra
E-commerce express delivery and automotive just-in-sequence requirements drive warehousing demand around Mumbai and Pune. BIS warehouse safety equipment standards govern material handling procurement across Nagpur distribution hubs. The Delhi-Mumbai Industrial Corridor anchors multi-client fulfillment centers serving consumer brands.
Karnataka
Technology sector supply chains and pharmaceutical cold-chain requirements expand Bengaluru's logistics footprint. CEA energy efficiency mandates accelerate solar-integrated refrigeration deployment in the city's temperature-controlled facilities. The Electronic City-Jigani corridor hosts engineering-led aftermarket parts distribution for automotive OEMs.
Tamil Nadu
Export-oriented manufacturing clusters generate bonded warehousing and customs clearance integration demand. DGFT documentation requirements for SEZ-linked facilities shape operating models around Chennai port. The Sriperumbudur-Oragadam automotive belt anchors captive contract logistics relationships.
Gujarat
Pharmaceutical and chemical processing verticals require specialized cold-chain infrastructure around Ahmedabad and Vadodara. GST Council harmonization enables hub consolidation at Mundra port logistics zones. The Sanand-Vithalapur manufacturing corridor attracts PLI scheme beneficiaries seeking integrated inbound-outbound networks.
Telangana
Life sciences and electronics manufacturing subsidies expand Hyderabad's 3PL service requirements. State logistics park approvals prioritize cold-storage energy efficiency compliance in the Genome Valley pharmaceutical cluster. The Shamshabad airport freight zone processes temperature-sensitive exports under FSSAI traceability mandates.
India 3PL Market Competitive Landscape
Capital-heavy asset owners compete with asset-light platform operators across India's 3PL sector. Integrated providers with captive fleet and warehouse networks anchor long-term automotive and retail contracts. Digital-native platforms capture e-commerce spot freight through algorithmic pricing. Dominant competitive moves include M&A consolidation of regional warehousing assets and strategic partnerships with express delivery networks.
Within the integrated logistics tier, TVS Supply Chain Solutions Ltd. and Mahindra Logistics Ltd. exemplify engineering-led distribution models anchored by automotive relationships. Delhivery Ltd. occupies the technology-native position, representing algorithmic freight orchestration. Among global forwarders with Indian operations, DHL Supply Chain India and Kuehne + Nagel India Pvt. Ltd. sit within the international contract logistics archetype.
| Leading Market Players |
|---|
| TVS Supply Chain Solutions Ltd. |
| Kuehne + Nagel India Pvt. Ltd. |
| Allcargo Logistics Ltd. |
| Safexpress Pvt. Ltd. |
| FedEx |
| DHL Supply Chain India |
| Delhivery Ltd. |
| Snowman Logistics |
| Mahindra Logistics Ltd. |
| Others |
Supply & Pricing Matrix
Algorithmic freight orchestration compresses cost structures while concentrating pricing power among platform-scale operators with proprietary routing networks. Diesel price volatility and land acquisition constraints in Maharashtra and Karnataka corridors simultaneously inflate fixed costs and reward asset-heavy incumbents with captive fleet capacity.
Pricing Analysis
Throughput-linked service-level agreements anchor contract values to order-cycle performance and fill-rate thresholds rather than static per-kilometer rates. Price differentiation hinges on cold-chain certification tiers under FSSAI traceability mandates and express delivery velocity commitments. Cost compression in standard freight tiers intensifies as digital freight matching platforms erode spot-market premiums. Mid-market retailers exhibit acute price sensitivity; pharmaceutical and automotive OEMs absorb premium pricing for zero-defect tolerance and temperature-controlled infrastructure.
Supply Chain Analysis
Hub-and-spoke distribution through Nagpur, Chennai, and Delhi-Mumbai Industrial Corridor nodes consolidates inventory positioning for GST-harmonized interstate movements. The network draws from captive fleet operators in Maharashtra, third-party warehousing in Karnataka, and bonded facilities at Tamil Nadu SEZs. Single-source vulnerability concentrates in long-haul trucking capacity where driver availability shortages constrain lane expansion. Distribution runs through multi-client distribution centers converting fixed real estate into variable storage costs under shared-space models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Land acquisition bottlenecks in logistics corridors prop contract pricing for warehouse-adjacent providers with approved park access. Tier-three city infrastructure gaps sustain premium capture for first-mover express networks.
For Market Incumbents: Deepen captive fleet integration to insulate margin structures from diesel volatility through index-linked fuel mechanisms. Expand cold-storage footprints in Genome Valley and Sriperumbudur-Oragadam belts ahead of CEA energy efficiency mandate enforcement. Consolidate regional warehousing assets to defend density economics against asset-light platform entrants. For New Entrants and Emerging Players: Begin with tier-three city express delivery networks where underdeveloped distribution infrastructure permits rapid lane density accumulation without incumbent saturation. Target pharmaceutical verticals requiring FSSAI-certified cold-chain operators in short supply. Lead with API-first visibility architectures to differentiate from legacy ERP-dependent competitors. For Investors and Strategic Acquirers: Re-rating potential sits with solar-integrated refrigeration operators given CEA regulatory tailwinds and sustainability-linked capital flows. Long-term viability favors integrated providers spanning first-mile pickup through last-mile delivery with bonded warehousing capabilities. Monitor state logistics park approval velocity as inflection indicator for warehouse-adjacent asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Route Optimization Deployment | Proprietary routing engines compress order-cycle times and enable dynamic pricing tied to real-time capacity utilization. |
| Solar-Integrated Cold Storage Expansion | CEA energy efficiency compliance captures regulatory premiums while reducing refrigeration operating cost exposure. |
| Tier-Three City Network Buildout | First-mover express infrastructure in underpenetrated urban centers establishes density economics ahead of competitor entry. |
| Multi-Client Distribution Center Consolidation | Shared-space warehousing models convert fixed real estate into variable costs for GST-harmonized hub operations. |
| API-First Visibility Platform Integration | Direct ERP connectivity resolves legacy system friction that constrains mid-market shipper adoption of 3PL services. |
Research Methodology
Independent corroboration across logistics park developers, fleet operators, and pharmaceutical supply chain directors underwrites the qualitative findings. Primary interviews with warehouse management system vendors, cold-storage facility managers, and e-commerce fulfillment executives combined with secondary validation from DGFT bonded warehousing notifications, GST Council directives, and CEA energy efficiency circulars. Bottom-up service-type segmentation triangulates against top-down corridor-level freight tonnage estimates.
Rate-of-change decomposition isolates volume drivers from pricing dynamics across the projection horizon. The analytical framework models transportation, warehousing, freight forwarding, and value-added service segments alongside end-user verticals spanning e-commerce, automotive, retail, and manufacturing. CAGRs derive from logistics infrastructure investment pipelines, PLI scheme facility commissioning schedules, and interstate warehouse footprint consolidation patterns.
Underlying measurement precision varies by segment; express delivery and cold-chain verticals carry tighter precision than fragmented road freight spot markets. Forecasts reflect assumptions regarding GST harmonization continuity, diesel price trajectory, and logistics park approval velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
China Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
Unit Load Device Market
Logistics and Shipping
Retail Logistics Market
Logistics and Shipping
Asia Pacific (APAC) Contract Logistics Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Europe Automotive Logistics Market
Logistics and Shipping
United States Freight and Logistics Market
Logistics and Shipping
Poland Third Party Logistics (3PL) Market
Logistics and Shipping
Less-Than-Truckload Market