
 North America Pharmaceutical Logistics Market | 2026-2036
North America Pharmaceutical Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pharmaceutical Logistics Market Analytics
A shortage of qualified cold-chain technicians is unwinding capacity expansion timelines across the region. DHL Supply Chain & Global Forwarding leverages its certified pharmaceutical facilities to anchor temperature-assured network coverage. UPS Healthcare sustains dominance in clinical trial logistics through specialized packaging and monitoring infrastructure. FedEx Logistics competes on time-definite delivery guarantees for high-value biologics shipments.
North America pharmaceutical logistics encompasses the temperature-controlled storage, handling, and distribution of finished drug products, active pharmaceutical ingredients, and clinical materials, requiring validated cold-chain systems that maintain 2-8°C, -20°C, or cryogenic conditions through continuous digital monitoring. The primary purpose is ensuring product integrity, patient safety, and regulatory compliance from manufacturing through final delivery. Cold chain services capture the largest margin pools given infrastructure intensity and certification barriers, while clinical trials applications expand fastest as decentralized trial models multiply collection and delivery nodes. Multimodal delivery is gaining share as shippers optimize cost-speed trade-offs across air, land, and sea legs.
FDA enforcement of the Drug Supply Chain Security Act and EPA refrigerant regulations under the AIM Act shape facility investments and equipment replacement cycles. Health Canada and the FDA jointly influence cross-border verification protocols for imports moving through Detroit, Buffalo, and Pacific Northwest corridors. Stakeholders must decide whether to build in-house cold-chain capabilities or outsource to third-party logistics providers as serialization deadlines tighten and biologics portfolios expand.
Market Dynamics
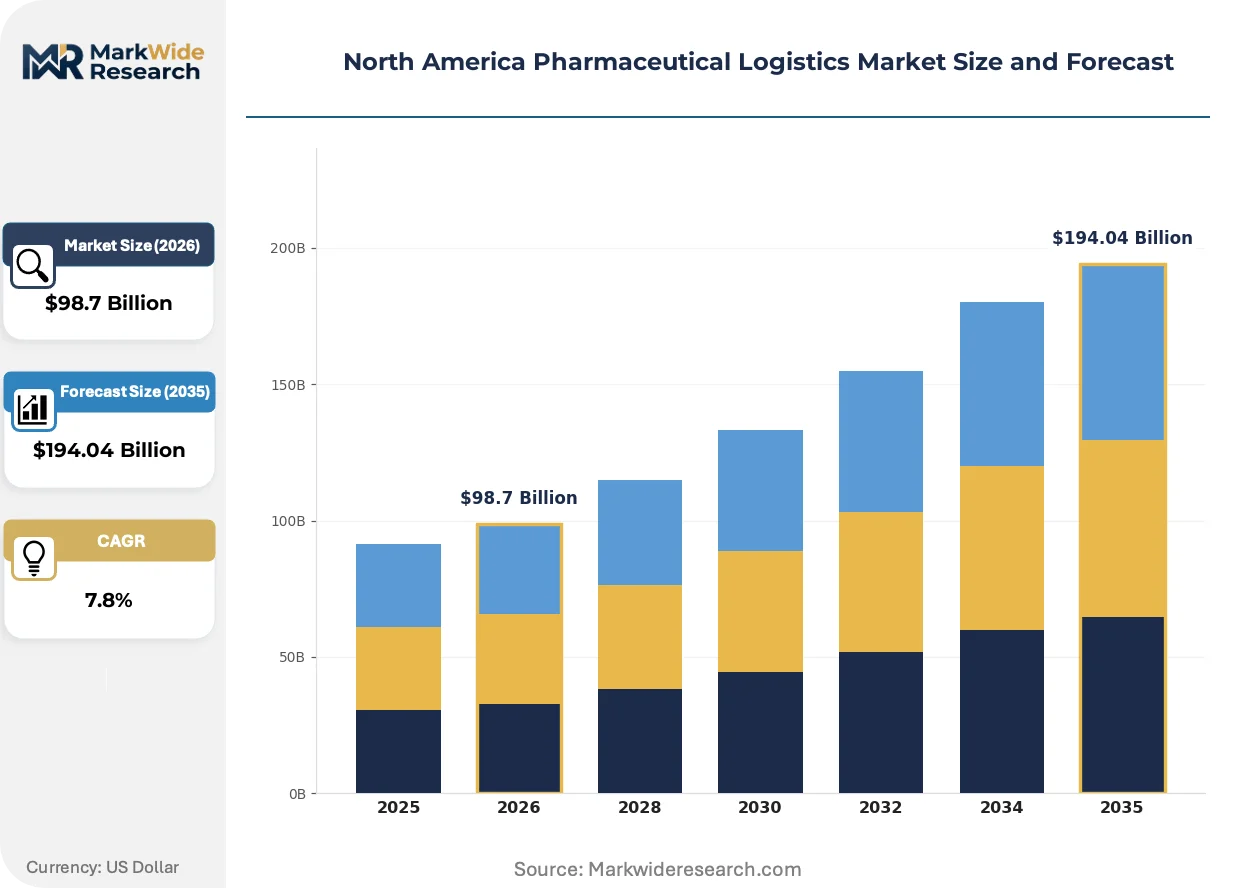
FDA serialization mandates under the Drug Supply Chain Security Act are forcing wholesale infrastructure replacement across the North American pharmaceutical value chain. Cold-chain biologics growth is compounding this pressure as shippers retrofit networks for validated temperature assurance.
Growth Catalysts
- Biologics pipeline expansion:Cell and gene therapy manufacturers in Massachusetts and New Jersey now require continuous 2-8°C and cryogenic distribution from clinical sites to infusion centers, pulling specialized logistics investment.
- Drug Supply Chain Security Act:FDA track-and-trace deadlines through 2023-2033 are mandating interoperable electronic systems for lot-level verification, driving software and hardware upgrades.
- Decentralized clinical trials:Direct-to-patient delivery models multiply collection nodes across the United States and Canada, expanding addressable logistics volume.
Market Restraints
- Qualified technician scarcity:Cold-chain validation engineers and GDP-certified operators are concentrated in legacy pharmaceutical clusters, constraining geographic expansion timelines.
- Refrigerant phase-down costs:EPA AIM Act hydrofluorocarbon restrictions are forcing equipment replacement cycles before depreciation schedules complete, compressing facility margins.
- Cross-border verification friction:Health Canada and FDA protocol misalignment at Detroit and Buffalo corridors delays temperature-assured shipments, adding dwell time risk.
Strategic Opportunities
- Cell therapy logistics white space:Cryogenic chain-of-custody services for CAR-T treatments remain underdeveloped in the US Midwest and Canadian Prairie provinces, offering first-mover positioning.
- Real-time visibility convergence:Integration of IoT sensors with blockchain verification is creating new service tiers for high-value biologics shippers seeking audit-ready documentation.
- Hospital consolidation tailwind:US health system M&A is concentrating purchasing power, creating demand for integrated inventory management and vendor-managed cold storage.
Industry Challenges
- GDP certification timelines:EU Good Distribution Practice alignment for cross-Atlantic shipments requires 12-18 month facility qualification cycles, delaying revenue recognition.
- Legacy WMS integration:Warehouse management systems at established pharmaceutical distributors lack API connectivity to modern temperature monitoring platforms, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pharmaceutical Logistics Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $194.04 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cold Chain, Warehousing, Transportation, Freight Forwarding Application: Clinical Trials, Distribution, Reverse Logistics, Inventory Management Delivery Mode: Air, Sea, Land, Multimodal End User: Pharmaceutical Companies, Distributors, Hospitals, Retail Pharmacies |
| Companies Covered | DHL Supply Chain & Global Forwarding, UPS Healthcare, Kuehne + Nagel International AG, FedEx Logistics, C.H. Robinson, Deutsche Post DHL Group, Expeditors International of Washington Inc., CEVA Logistics, DB Schenker, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pharmaceutical Logistics Market Evolving Landscape
Digital verification technologies are compressing the time between temperature excursion detection and corrective action across North American pharmaceutical networks. This shift is reshaping how logistics providers contract for liability and how manufacturers allocate inventory risk.
Active temperature-controlled containers with integrated phase-change materials are supplanting passive insulated shippers for international biologics lanes. Large molecule manufacturers shipping from Puerto Rico to the US mainland are adopting these systems to eliminate lane-specific packaging qualification. The technology is compressing total cost of ownership calculations by reducing product loss rates and eliminating single-use shipper waste.
FDA enforcement of the Drug Supply Chain Security Act is mandating unit-level traceability by November 2023 for manufacturers and 2024 for wholesale distributors. This regulation is forcing replacement of legacy ERP systems and serial number aggregation infrastructure. Small and mid-size generic manufacturers in New Jersey and Pennsylvania are consolidating through third-party logistics partnerships to spread compliance costs.
Hospital and pharmacy buyers are consolidating vendor relationships around integrated cold-chain and serialization service bundles. This procurement compression is displacing point-solution providers who lack temperature-assured warehousing credentials. The shift is most visible in the Northeast US, where integrated delivery networks are reducing logistics vendor counts from twelve to three partners.
North America Pharmaceutical Logistics Market Segmentation
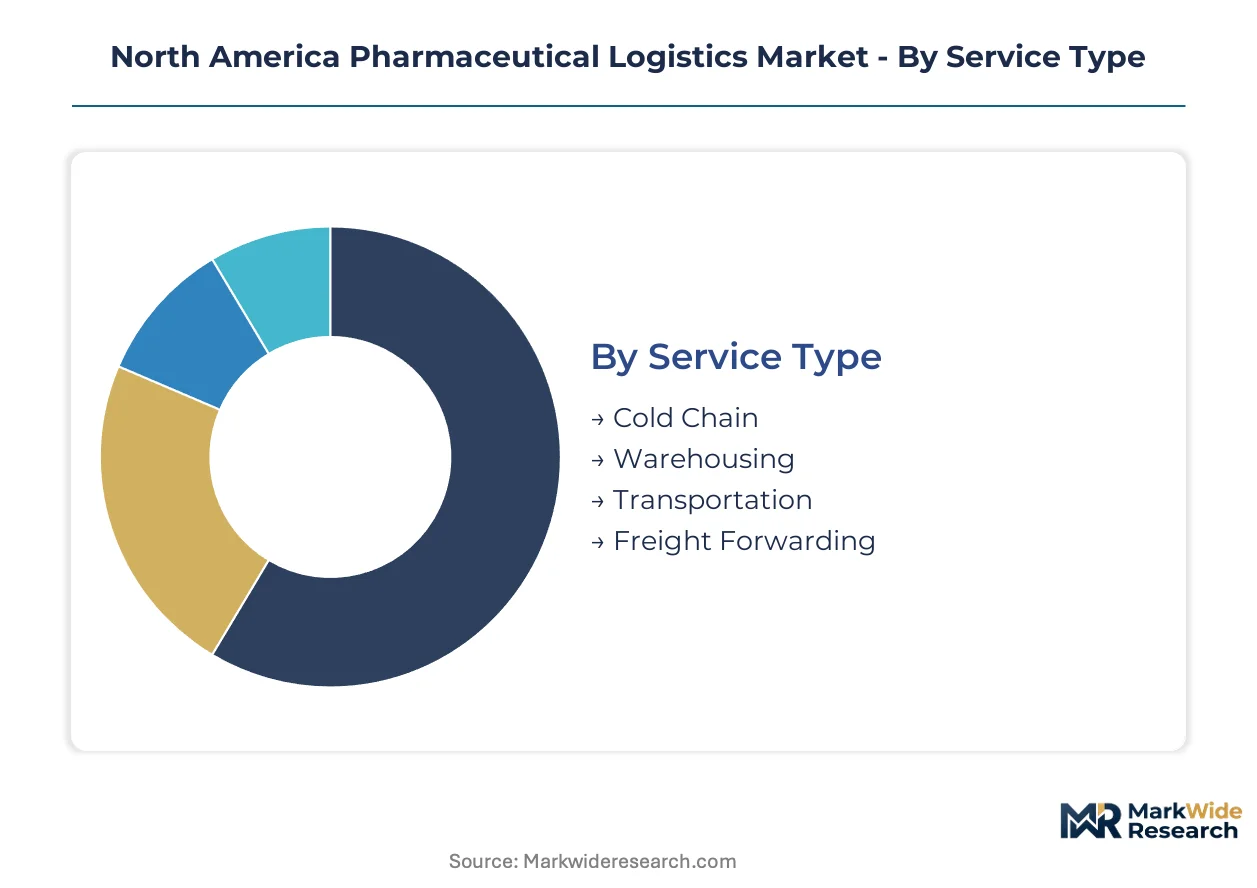
Service differentiation in pharmaceutical logistics hinges on temperature assurance capabilities and serialization compliance infrastructure. Each segment category carries distinct margin profiles and capital intensity requirements that reshape competitive positioning across the value chain.
Service Type:
Cold chain services command the widest margin spreads given certification barriers and equipment intensity, while transportation and freight forwarding operate on thinner spreads with higher asset velocity.
- Cold Chain:Validated 2-8°C, -20°C, and cryogenic storage and distribution systems with continuous digital monitoring and GDP compliance. Demand concentrates in Massachusetts and New Jersey biologics clusters, where cell therapy manufacturers require uninterrupted chain-of-custody documentation from clinical sites to infusion centers.
- Warehousing:Temperature-controlled facilities with serialized inventory management and lot-level track-and-trace capabilities. FDA Drug Supply Chain Security Act deadlines are forcing wholesale infrastructure replacement across wholesale distributors in the Northeast and Puerto Rico production hubs.
- Transportation:Dedicated and shared fleet services with real-time temperature monitoring and excursion alert systems.
- Freight Forwarding:Cross-border customs brokerage and documentation for temperature-assured international shipments.
The dominant share belongs to cold chain services, while freight forwarding is closing the gap fastest as Puerto Rico-to-mainland biologics volumes expand.
Application:
Clinical applications attract premium pricing through specialized handling protocols, while distribution and inventory management scale through operational efficiency.
- Clinical Trials:Direct-to-patient and site-to-laboratory logistics with protocol-specific packaging and chain-of-custody requirements. Decentralized trial models across the United States and Canada are multiplying collection nodes and delivery endpoints, expanding addressable service volume.
- Distribution:Finished drug product movement from manufacturing through wholesale to dispensary channels.
- Reverse Logistics:Returns processing, recall management, and expired product disposition with full traceability documentation.
- Inventory Management:Vendor-managed stock programs and hospital consolidation support services.
Distribution retains the largest revenue base, though clinical trials is climbing the fastest as decentralized protocols reshape site geography.
Delivery Mode:
Modal selection reflects cost-speed trade-offs that vary by product value, temperature sensitivity, and regulatory urgency.
- Air:Time-definite express services for high-value biologics and emergency supply situations. Active temperature-controlled containers with phase-change materials are supplanting passive shippers for Puerto Rico-to-mainland lanes, eliminating lane-specific packaging qualification cycles.
- Multimodal:Optimized combinations across air, land, and sea legs with single-source accountability.
- Land:Dedicated and less-than-truckload ground transportation for regional distribution networks.
- Sea:Ocean freight for non-urgent, high-volume pharmaceutical movements with containerized cold storage.
Air freight captures the highest value per kilogram, while multimodal solutions are gaining share fastest as shippers optimize total landed cost.
End User:
Customer concentration and purchasing power determine contract structures and service bundling intensity.
- Pharmaceutical Companies:Integrated logistics partnerships covering clinical through commercial product lifecycles. US health system M&A is concentrating purchasing power, creating demand for combined inventory management and vendor-managed cold storage at integrated delivery networks.
- Hospitals:Direct receiving and point-of-use storage for infusion center biologics and emergency pharmaceuticals.
- Distributors:Wholesale and specialty pharmacy intermediaries requiring serialization-ready infrastructure.
- Retail Pharmacies:Last-mile delivery and patient-facing cold storage for specialty medications.
Pharmaceutical companies anchor contract value, while hospitals are expanding their logistics footprint fastest as infusion center networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across North America diverge sharply by geography. The United States dominates biologics distribution through dense infusion center networks, while Canada concentrates clinical trial logistics around Toronto and Montreal research corridors. Mexico serves growing pharmaceutical manufacturing demand with cross-border temperature-assured lanes into Texas and California.
United States
Massachusetts and New Jersey biologics clusters drive specialized cold-chain investment for cell and gene therapies. FDA Drug Supply Chain Security Act deadlines through 2033 force wholesale distributors to replace legacy track-and-trace infrastructure. Puerto Rico's pharmaceutical production hubs anchor temperature-controlled freight forwarding volumes to mainland distribution centers.
Canada
Decentralized clinical trial models multiply collection nodes across Ontario and Quebec, expanding direct-to-patient logistics services. Health Canada verification protocols for cross-border shipments create friction at Detroit and Buffalo corridors, adding dwell time risk for temperature-assured products. Toronto's research corridor concentrates GDP-certified warehousing capacity for biologics imports.
Mexico
Pharmaceutical manufacturing expansion in Baja California and Mexico City generates demand for validated cold storage at border crossings into California and Texas. The national pharmaceutical regulator enforces Good Distribution Practice alignment for exports to the United States, extending facility qualification timelines. Tijuana and Mexicali clusters specialize in temperature-controlled assembly and packaging for US-bound finished products.
North America Pharmaceutical Logistics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in North American pharmaceutical logistics. The top tier commands temperature-assured network coverage and serialization-ready infrastructure, while mid-size operators compete on regional density and vertical specialization. Two archetypes dominate: global integrators with certified pharmaceutical facilities, and regional specialists with clinical trial logistics expertise. Competitive moves center on M&A for cold-chain capacity and strategic partnerships for real-time visibility technology.
Within the global integrator tier, DHL Supply Chain & Global Forwarding and UPS Healthcare exemplify the infrastructure-heavy positioning required for biologics distribution. FedEx Logistics occupies a position emphasizing time-definite delivery guarantees for high-value shipments. These three represent the archetype of scale-driven investment in temperature-controlled containers and digital monitoring platforms that define competitive differentiation in this market.
| Leading Market Players |
|---|
| DHL Supply Chain & Global Forwarding |
| UPS Healthcare |
| Kuehne + Nagel International AG |
| FedEx Logistics |
| C.H. Robinson |
| Deutsche Post DHL Group |
| Expeditors International of Washington Inc. |
| CEVA Logistics |
| DB Schenker |
| Others |
Value Network & Pricing Analysis
Facility utilization rates above 85% at Massachusetts and New Jersey biologics hubs compress marginal costs for certified cold-chain providers while erecting price floors that exclude undercapitalized entrants. Scale advantages in GDP-compliant warehousing cascade into contract structures that favor multi-year partnerships over transactional spot arrangements.
Pricing Analysis
Long-term offtake agreements dominate contract structures for high-value biologics lanes, with pharmaceutical manufacturers locking in 3-5 year terms to secure cryogenic capacity. Price differentiation stems from GDP certification tier and temperature assurance granularity, with 2-8°C services commanding narrower spreads than cryogenic chain-of-custody offerings. Cost compression in standard cold storage is intensifying because refrigerant phase-down investments compress facility margins. Generic distributors exhibit highest price sensitivity, while cell therapy manufacturers prioritize reliability over rate negotiation.
Supply Chain Analysis
Just-in-time inventory strategies prevail among biologics manufacturers in Puerto Rico and New Jersey, with safety stock minimized to reduce temperature excursion risk. Supply concentration centers on the United States, Canada, and Mexico, with Puerto Rico anchoring pharmaceutical production for mainland distribution. The chain draws from specialized refrigerants, validated packaging materials, and GDP-certified labor pools. Single-source vulnerability at Detroit and Buffalo border crossings threatens cross-border temperature-assured shipments. Distribution runs through integrated delivery networks consolidating vendor relationships in the Northeast corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs durable defensive moats in this market, as FDA serialization mandates and GDP certification timelines impose 12-18 month qualification barriers that insulate incumbents from price-based disruption.
For Market Incumbents: Compound network density through targeted capacity additions in the US Midwest and Canadian Prairie provinces where cryogenic infrastructure remains underdeveloped. Certification investment in EU Good Distribution Practice alignment captures cross-Atlantic biologics flows. Vertical integration into real-time IoT monitoring platforms defends against technology-enabled entrants threatening audit-ready documentation services. For New Entrants and Emerging Players: Cell therapy logistics white space in the US Midwest offers the most penetrable entry point, with CAR-T treatment cryogenic chain-of-custody services concentrated in legacy coastal clusters. Direct-to-patient clinical trial delivery models across decentralized protocols present a second attack vector. A go-to-market angle anchored in blockchain-verified temperature documentation bypasses incumbent middleware limitations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized cold-chain operators with proprietary GDP-certified facility networks over asset-light freight forwarders. Long-term viability rests on regulatory compliance infrastructure rather than transportation scale. Acquisition targets should display concentrated exposure to biologics rather than small-molecule generics. The signal to watch is Health Canada-FDA protocol harmonization progress at Detroit and Buffalo corridors, which would eliminate dwell time premiums currently captured by integrated providers.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Capacity Expansion | Captures CAR-T therapy growth in underserved Midwest and Prairie provinces. |
| Blockchain Verification Integration | Creates audit-ready documentation tiers for FDA Drug Supply Chain Security Act compliance. |
| EU GDP Certification Investment | Unlocks cross-Atlantic biologics flows with 12-18 month facility qualification cycles. |
| Direct-to-Patient Clinical Trial Infrastructure | Multiplies collection nodes across decentralized trial protocols in United States and Canada. |
| Refrigerant Transition Partnership | Spreads EPA AIM Act hydrofluorocarbon replacement costs across manufacturer networks. |
Research Methodology
Cross-validation between primary interviews with cold-chain operations directors and secondary analysis of FDA Drug Supply Chain Security Act enforcement patterns anchors the qualitative findings. Stakeholder engagement encompassed logistics procurement managers at integrated delivery networks, GDP-certified facility operators, clinical trial supply chain leads, and Health Canada regulatory affairs specialists. Secondary sources included FDA guidance documents, EPA AIM Act implementation records, Health Canada verification protocols, and pharmaceutical trade flow databases. Bottom-up facility capacity assessments and top-down market sizing triangulate volume estimates.
Sensitivity analysis around refrigerant phase-down timelines and serialization compliance deadlines shapes the analytical framework. Segmentation dimensions modeled include temperature range, application type, delivery mode, and end-user concentration across the projection horizon. CAGRs derive from facility investment pipelines, biologics pipeline expansion rates, and clinical trial site geography shifts. Forecast inputs incorporate qualified technician supply constraints and cross-border verification friction at Detroit and Buffalo corridors.
Forecasts assume regulatory continuity in FDA, EPA, and Health Canada regimes; material policy shifts would require re-modeling. Specific risks include accelerated refrigerant restrictions, Health Canada-FDA protocol misalignment, and qualified cold-chain technician scarcity. Revision becomes warranted when cross-border dwell time at temperature-assured corridors exceeds validated stability budgets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Container Drayage Market
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
North America Same Day Delivery Market
Logistics and Shipping
China Same Day Delivery Market
Logistics and Shipping
Tanker Cargo Ship Market
Logistics and Shipping
Spain 3PL Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
Asean Freight Forwarding Market
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
China International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Germany Freight Forwarding Market
Logistics and Shipping
UK Freight Forwarding Market