
 Canada Project Logistics Market | 2026-2036
Canada Project Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Project Logistics Market Outlook
Modularization of heavy-lift cargo into standardized, pre-assembled sub-units is hardening as the dominant packaging configuration for Canadian energy and mining clients. Kuehne + Nagel leverages its North American heavy-haul network to anchor project cargo flows through Vancouver and Montreal gateways. Trans Global Projects Group specializes in out-of-gauge movements for western Canadian resource developments, while CJ Smart Cargo competes on digital freight visibility across multi-modal delivery modes.
Canada project logistics encompasses the engineered planning, coordination, and execution of oversized, high-value, or time-critical shipments for industrial capital projects, typically involving lift plans with crane capacity exceeding 500 tonnes and route surveys for dimensional cargoes exceeding standard highway limits. Its primary purpose is synchronizing the physical movement of project components with construction schedules to minimize idle capital and demurrage exposure. Freight forwarding commands the largest service-type revenue pool given its bundling of documentation, carrier procurement, and cargo insurance, while transport management is gaining fastest as operators deploy IoT solutions for real-time load monitoring across remote northern corridors. Road delivery dominates modal share for last-mile project site access, though rail absorbs bulk volumes for mining equipment destined to Quebec's Plan Nord territory.
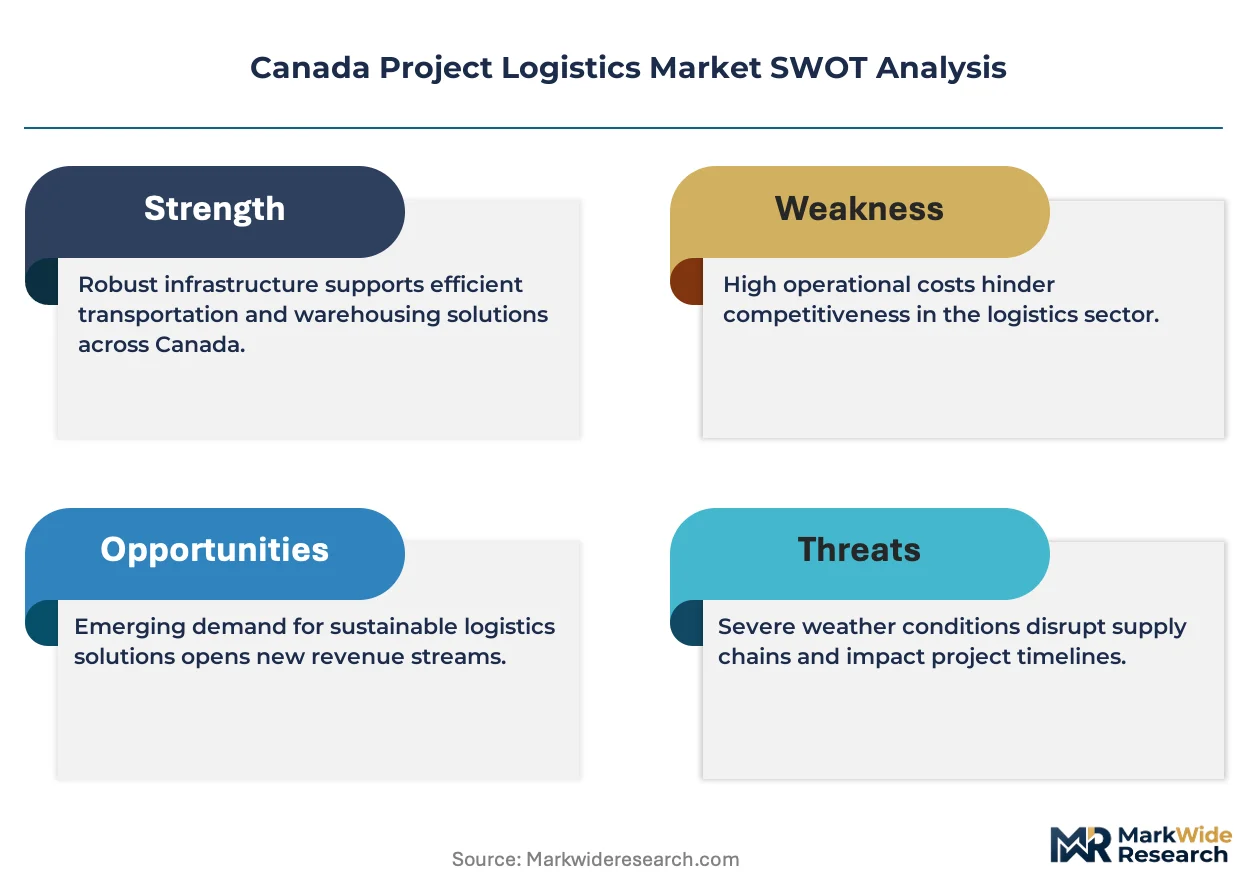
Health Canada and Transport Canada jointly govern dangerous goods transit permits and overweight vehicle exemptions for cross-provincial project movements, while provincial regulators in Alberta and British Columbia administer road-use agreements that directly shape route economics and seasonal windows. The Canadian Environmental Assessment Act and emerging federal clean fuel regulations tighten carbon-accounting requirements for logistics procurement, pushing operators toward lower-emission transport modes. Stakeholders must weigh capital commitments to electrified fleet segments against the operational flexibility demanded by remote project sites lacking charging infrastructure.
Market Dynamics
Modularization of heavy-lift cargo into standardized sub-units is compressing project timelines and forcing logistics providers to retool for factory-to-site assembly flows rather than traditional breakbulk handling. This structural shift favors operators with integrated engineering capabilities and penalizes pure transport brokers.
Growth Catalysts
- Clean Fuel Regulations:Federal carbon-accounting mandates under the Canadian Environmental Assessment Act are accelerating procurement of lower-emission transport modes for Alberta oil sands corridors.
- Ontario Manufacturing Belt:Capital equipment imports for EV battery gigafactories are generating sustained demand for out-of-gauge road movements and specialized heavy-haul permits.
- IoT Load Monitoring:Real-time cargo tracking across remote northern corridors is reducing demurrage exposure and enabling just-in-time delivery synchronization with construction schedules.
Market Restraints
- Seasonal Access Windows:Provincial road-use agreements in British Columbia and Alberta restrict overweight vehicle movements to winter ice-road periods, compressing annual utilization rates for specialized fleets.
- Diesel Price Volatility:Remote project sites lack grid connectivity for electrification, locking operators into fossil fuel exposure with limited hedge mechanisms.
- Permit Fragmentation:Cross-provincial dangerous goods transit requires separate approvals from Health Canada and Transport Canada, creating administrative friction that delays mobilization.
Strategic Opportunities
- Plan Nord Territory:Quebec's northern mining developments remain underserved by integrated project logistics providers, offering first-mover advantages for operators establishing rail-heavy-haul intermodal hubs.
- Digital Freight Platforms:Multi-modal visibility tools are penetrating the broker-heavy Canadian market, creating white space for technology-enabled challengers to displace traditional forwarding relationships.
- Carbon Border Adjustments:Emerging federal trade mechanisms will reward logistics procurement with documented emissions reductions, favoring operators with verified low-carbon transport options.
Industry Challenges
- Crane Operator Certification:Lift plans exceeding 500 tonnes require specialized rigging expertise that remains concentrated among a shrinking pool of certified technicians across Western Canada.
- Legacy Fleet Conversion:Electrified heavy-haul equipment faces charging infrastructure gaps at remote project sites, forcing operators to maintain dual fossil-electric asset bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Project Logistics Market |
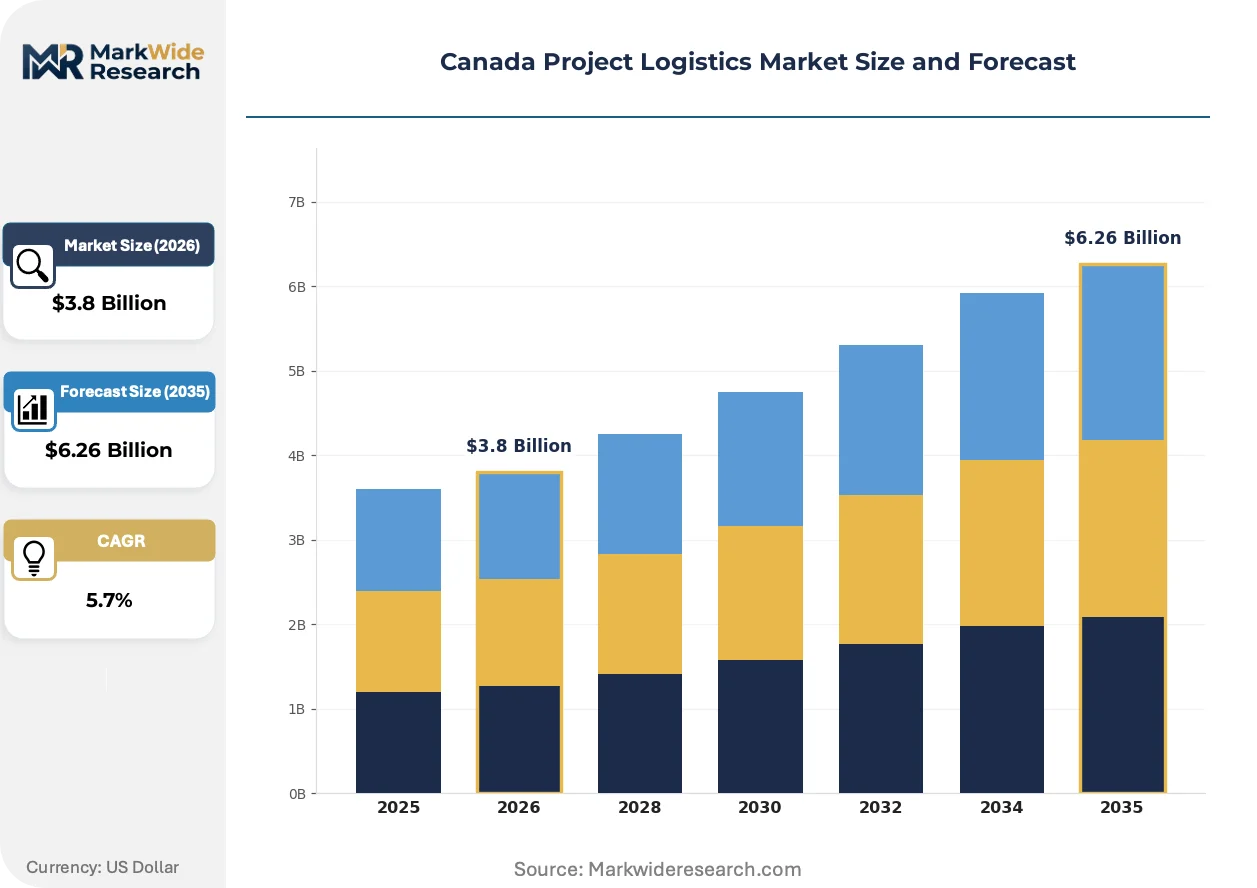
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Forwarding, Transport Management, Customs Brokerage, Warehousing End User: Construction, Oil & Gas, Mining, Manufacturing Technology: GPS Tracking, IoT Solutions, Transportation Management Systems, Drones Delivery Mode: Road, Rail, Air, Sea |
| Companies Covered | COSCO Shipping Logistics, Chirey Group, Translink International Logistics Group, Kerry Logistics Network Limited, Trans Global Projects Group, Sinotrans (HK) Logistics Ltd., Kuehne + Nagel, CJ Smart Cargo, Tiba Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Project Logistics Market Strategic Shifts
Digital integration and prefabrication methods are converging to transform how capital projects source, track, and receive critical components. Three developments are reshaping competitive requirements for Canadian operators.
Prefabricated modular construction units are displacing traditional stick-built approaches at Alberta oil sands and Saskatchewan mining sites. Energy sector EPC contractors are specifying factory-integrated sub-assemblies for 60% of new capital projects. This shift is modularizing logistics demand into higher-frequency, lower-dimensional shipments that favor operators with light-manufacturing packaging capabilities.
Transport Canada's evolving overweight vehicle exemption framework is tightening dimensional cargo documentation requirements for cross-provincial movements. The regulatory change is forcing logistics providers to invest in 3D laser scanning and structural engineering certifications. Western Canadian operators serving the oil sands corridor are responding by embedding survey engineers directly within dispatch teams.
Construction procurement teams are unbundling freight forwarding from transport management, creating separate vendor relationships for documentation and physical execution. This pattern is fragmenting account control and compressing contract durations. Ontario's manufacturing belt exhibits the most pronounced unbundling, with EV battery developers splitting logistics spend across three or more specialized providers.
Canada Project Logistics Market Segmentation
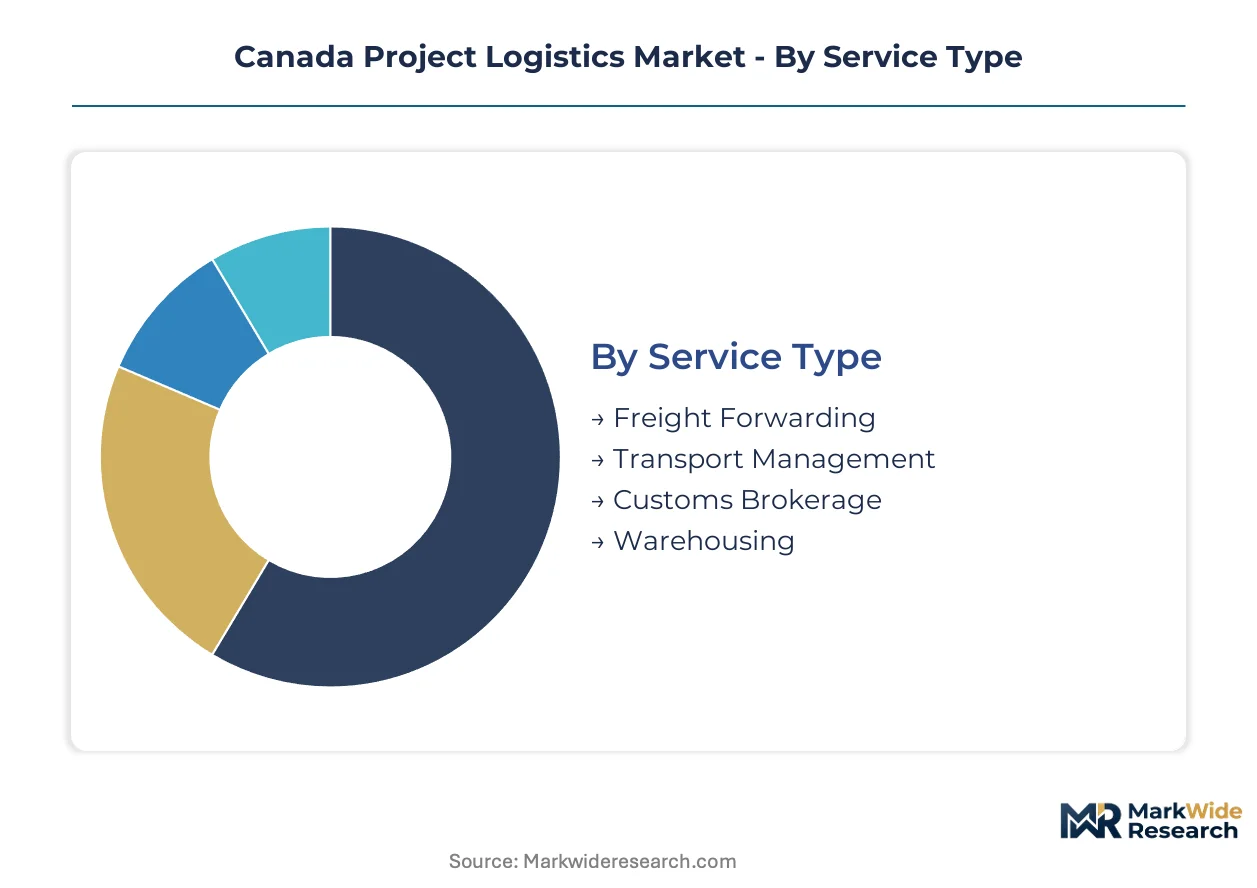
Canada project logistics demands precise segment alignment with capital project economics. Service configurations, end-use requirements, and technology specifications determine operator competitiveness across Alberta's oil sands corridors and Ontario's manufacturing belt.
Service Type:
Technical sophistication varies sharply across service tiers, with bundled offerings commanding premium positioning against unbundled execution layers.
- Freight Forwarding:Bundles documentation, carrier procurement, and cargo insurance into single-contract relationships. Demand concentrates in Western Canada's oil sands developments where cross-border documentation complexity and multimodal coordination requirements favor integrated providers over fragmented broker networks.
- Transport Management:Deploys IoT-enabled load monitoring and route optimization across remote northern corridors. Ontario's EV battery gigafactories are driving fastest adoption as just-in-time assembly schedules demand real-time visibility that traditional forwarding cannot deliver.
- Customs Brokerage:Manages cross-provincial dangerous goods permits and federal compliance documentation for project imports.
- Warehousing:Provides laydown yard management and component staging for modular construction sequences.
Mature deployment sits with Freight Forwarding. Newer deployment is concentrated in Transport Management.
End User:
Capital intensity and project scale create divergent logistics requirements across industrial verticals.
- Oil & Gas:Drives out-of-gauge movements for modular processing equipment and pipeline components. Alberta's oil sands corridor generates sustained demand for heavy-haul permits and seasonal ice-road access windows that compress annual utilization rates.
- Construction:Synchronizes prefabricated module delivery with site assembly schedules. Urban infrastructure stimulus in Ottawa and Toronto is expanding demand for crane-capacity coordination and road-use agreement navigation.
- Mining:Requires bulk equipment movements to Quebec's Plan Nord territory and Saskatchewan potash developments.
- Manufacturing:Supports EV battery gigafactory capital equipment imports through Ontario's manufacturing belt.
Volume concentration rests with Oil & Gas. Steepest expansion trajectory belongs to Construction.
Technology:
Digital capability layers determine competitive differentiation in remote corridor operations and urban project coordination.
- IoT Solutions:Enables real-time cargo tracking, environmental monitoring, and predictive maintenance across disconnected northern routes. Saskatchewan mining clients are prioritizing sensor networks that reduce demurrage exposure during seasonal access windows.
- Transportation Management Systems:Integrates dispatch, permit management, and carrier procurement into unified platforms. British Columbia operators serving cross-provincial movements are deploying TMS to fragment Health Canada and Transport Canada approval workflows.
- GPS Tracking:Provides location visibility for standard dimensional cargoes on established highway corridors.
- Drones:Conducts route surveys and structural clearance verification for dimensional cargo movements.
Established deployment centers on GPS Tracking. Emerging deployment clusters around IoT Solutions.
Delivery Mode:
Modal selection reflects the tension between infrastructure availability and cargo dimensional constraints.
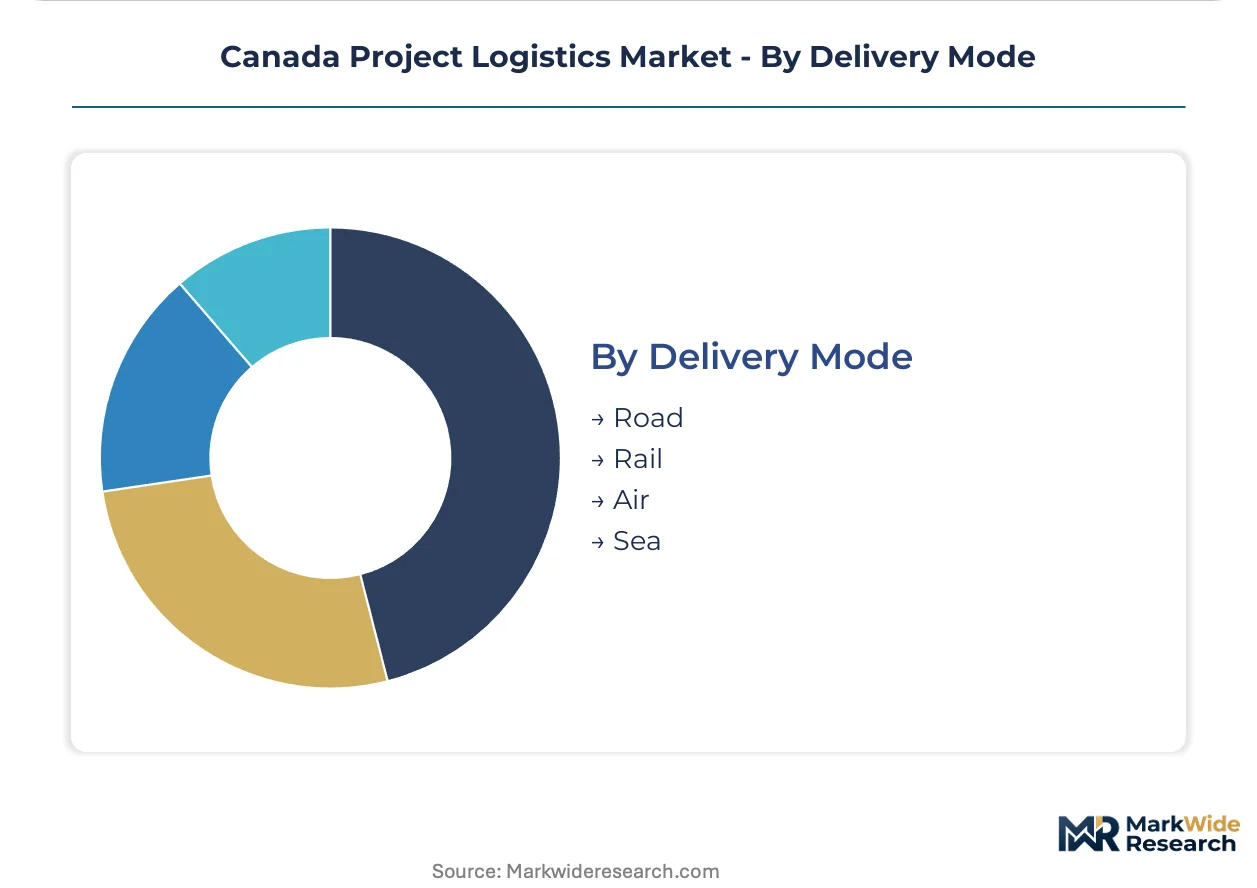
- Road:Dominates last-mile project site access for oversized components exceeding standard highway limits. Ontario's manufacturing belt relies on specialized heavy-haul permits for EV battery production line equipment that cannot transfer to rail.
- Rail:Absorbs bulk mining equipment volumes for Quebec's Plan Nord territory where road infrastructure remains undeveloped. Saskatchewan potash expansions are driving intermodal hub development connecting CP Rail networks to final site access.
- Air:Handles time-critical spare parts and emergency components for remote project sites.
- Sea:Moves international project cargo through Vancouver and Montreal gateway ports.
Volume leadership belongs to Road. Infrastructure-constrained expansion is concentrating in Rail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's Advanced Manufacturing Supercluster designation concentrates EV battery capital equipment demand in the Windsor-Toronto corridor, driving specialized heavy-haul permit volumes.
Ontario
EV battery gigafactory construction dominates project logistics demand, with Stellantis and LG Energy Solution facilities requiring out-of-gauge production line imports. Transport Canada administers cross-provincial overweight vehicle exemptions that shape permit lead times. The Windsor-Toronto corridor generates sustained demand for crane-capacity coordination and just-in-time module delivery synchronization.
Quebec
Plan Nord mining developments drive bulk equipment movements to remote northern territories lacking permanent road infrastructure. Provincial regulators administer seasonal access windows and rail-heavy-haul intermodal agreements. Montreal serves as the eastern gateway for international project cargo, with port congestion creating staging demand at regional warehousing facilities.
Alberta
Oil sands modular construction compresses project timelines into winter ice-road access windows, forcing fleet utilization concentration into Q1-Q2 periods. Health Canada and Transport Canada jointly govern dangerous goods transit permits for bitumen processing equipment. The Edmonton-Calgary corridor anchors heavy-haul operator density and certified crane technician pools.
British Columbia
LNG export terminal construction generates dimensional cargo flows through Vancouver port infrastructure. Provincial road-use agreements restrict overweight movements to prescribed seasonal corridors, compressing annual mobilization windows. The Vancouver gateway handles Asian-sourced modular components for western Canadian energy projects.
Saskatchewan
Potash mining expansions drive rail-absorbed bulk equipment volumes connecting CP Rail networks to final site access. Federal clean fuel regulations under the Canadian Environmental Assessment Act reshape procurement criteria for transport operators. The Saskatoon-Regina corridor concentrates intermodal hub development for prairie resource projects.
Canada Project Logistics Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across service tiers, creating a bifurcated structure where integrated forwarding networks hold account control while technology-enabled challengers fragment transport management relationships. The vendor base organizes around three strategic archetypes: global forwarding networks with heavy-haul capabilities, regional project cargo specialists, and digital freight platforms penetrating visibility gaps. Consolidation pressure favors operators with embedded engineering capabilities over pure transport brokers. Dominant competitive moves include M&A to acquire crane certification expertise and strategic partnerships to extend digital platform reach into remote northern corridors.
Among global forwarding networks, Kuehne + Nagel and COSCO Shipping Logistics exemplify the diversified archetype with integrated North American heavy-haul capabilities. Trans Global Projects Group occupies a specialist position focused on out-of-gauge western Canadian resource developments. These three represent the competitive tension between scale-driven bundling and focused execution expertise.
| Leading Market Players |
|---|
| COSCO Shipping Logistics |
| Chirey Group |
| Translink International Logistics Group |
| Kerry Logistics Network Limited |
| Trans Global Projects Group |
| Sinotrans (HK) Logistics Ltd. |
| Kuehne + Nagel |
| CJ Smart Cargo |
| Tiba Group |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up heavy-haul specialists anchor supply concentration in Western Canada's oil sands corridor, compressing pricing discipline through fleet consolidation while federal carbon-accounting rules reshape procurement premiums. This ownership pattern concentrates route-access assets among fewer operators, tightening margin structures for modular construction logistics.
Pricing Analysis
Margin tightening in transport management reflects unbundling of freight forwarding relationships across Ontario's EV battery supply chain. Project-based pricing dominates capital equipment movements, with differentiation driven by crane certification tier and real-time visibility integration. Cost-down pressure accelerates as EPC contractors consolidate vendor panels, squeezing pure transport brokers. Tier-one oil sands developers exhibit lowest price sensitivity; mid-tier construction procurement teams show highest elasticity.
Supply Chain Analysis
Domestic-content mandates under Canada's Clean Fuel Regulations reshape sourcing toward lower-emission fleet assets, though charging infrastructure gaps tether operators to dual fossil-electric bases. Equipment manufacturing draws from Germany, China, and the United States for specialized crane and heavy-haul chassis components. Single-source vulnerability concentrates in certified rigging technician pools across Alberta and British Columbia. Distribution runs through Vancouver and Montreal gateway ports connecting to rail-heavy-haul intermodal hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada project logistics sits in a technology-transition phase where IoT-enabled load monitoring displaces traditional dispatch coordination, forcing capability reinvestment across operator tiers.
For Market Incumbents: To counter digital freight platform penetration in visibility-starved northern corridors, embed survey engineers within dispatch teams to tighten dimensional cargo documentation compliance under Transport Canada's evolving exemption framework. Prioritize backward integration into crane certification training programs to capture scarce rigging expertise concentrated in Western Canada. For New Entrants and Emerging Players: Enter via Quebec's Plan Nord territory where integrated project logistics providers remain underserved, targeting rail-heavy-haul intermodal hub development for bulk mining equipment flows. Lead with carbon-accounting documentation capabilities that satisfy federal procurement criteria under emerging clean fuel regulations. For Investors and Strategic Acquirers: Consolidation of winter ice-road access permits among Alberta operators is the leading indicator that fleet utilization concentration will intensify seasonal revenue volatility. Long-term viability favors operators with embedded engineering capabilities over pure transport brokers; watch for Transport Canada dimensional documentation enforcement as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Real-time cargo tracking reduces demurrage exposure across Alberta's compressed ice-road windows. |
| Crane Certification Investment | Specialized rigging expertise scarcity in Western Canada creates defensive moat for certified operators. |
| Rail-Heavy-Haul Intermodal Hub | Quebec's Plan Nord territory offers first-mover positioning for bulk mining equipment flows. |
| Carbon Accounting Documentation | Federal clean fuel regulations reward verified low-carbon transport options in procurement scoring. |
| 3D Laser Scanning Capability | Transport Canada's tightened dimensional requirements force structural engineering certification investment. |
Study Parameters
Document review covered Transport Canada exemption frameworks, Health Canada dangerous goods transit protocols, and provincial road-use agreements, complemented by interviews with heavy-haul fleet managers, EPC contractor logistics directors, crane certification instructors, and mining procurement leads. Secondary validation drew from Canadian Environmental Assessment Act filings, CP Rail network expansion disclosures, and federal infrastructure stimulus procurement databases. Bottom-up segment sizing triangulated against top-down capital project pipeline tracking.
Model outputs span service type, end-use vertical, technology deployment, and delivery mode dimensions across the projection horizon. CAGRs derive from regression analysis against historical capital expenditure flows and seasonal access window constraints. Industry-specific inputs include winter ice-road utilization rates and cross-provincial permit approval timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated electrification mandates or prolonged provincial permitting delays. Forecasts reflect documented assumptions regarding federal carbon regulation enforcement intensity and modular construction adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
US Retail Logistics Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Nigeria Air Freight Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
LAMEA Last Mile Delivery Market
Logistics and Shipping
Nordics Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
Military Logistics Market
Logistics and Shipping
Hong Kong Freight and Logistics Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
United States Contract Logistics Market
Logistics and Shipping
North America Cross Border Road Freight Transport Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market