
 US Hazardous Goods Logistics Market | 2026-2036
US Hazardous Goods Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
US Hazardous Goods Logistics Market Analytics
DOT hazmat registration fee restructuring is pivoting small fleet operators toward third-party logistics partnerships. Schneider Logistics leverages dedicated tanker networks to sustain Gulf Coast chemical corridor coverage. Kenan Advantage Group anchors bulk liquid transport capacity through specialized terminal infrastructure. Deutsche Post DHL Group differentiates via integrated compliance documentation systems that streamline cross-border hazardous shipments.
US Hazardous Goods Logistics encompasses the specialized transportation, handling, and storage of substances classified under 49 CFR as posing risks to health, safety, or property, requiring placarded vehicles, certified handlers, and chain-of-custody documentation. The sector serves industrial supply chains where material incompatibility, temperature sensitivity, or radiological half-life dictates equipment selection and routing protocols. Road transport dominates chemical and explosive movements due to last-mile flexibility and DOT routing regulations, while air freight commands premium positioning for time-critical pharmaceutical biologics subject to IATA Dangerous Goods standards. Waste management services face structural margin pressure from EPA cradle-to-grave liability rules, though site remediation contracts tied to brownfield redevelopment offer countercyclical stability.
FAA, EPA, and PHMSA collectively enforce a layered compliance architecture that determines carrier certification tiers, facility permitting timelines, and insurance underwriting requirements. DOT hazmat safety permits function as market access gates, with revocation authority concentrating enforcement leverage in regional field offices. Stakeholders must weigh capital deployment toward autonomous vehicle pilot programs against the regulatory lag in codifying self-driving truck standards for Class 3 flammable liquid transport.
Market Dynamics
DOT hazmat safety permit revocation authority concentrates enforcement leverage in regional field offices, forcing carriers to consolidate compliance infrastructure around PHMSA-certified training centers and placarded fleet standardization.
Growth Catalysts
- EPA cradle-to-grave liability rules:Petrochemical manufacturers in Texas and Louisiana are expanding outsourced logistics contracts as manifest documentation requirements tighten, pulling specialized carriers into long-term service agreements.
- Cold-chain biological transport:Gulf Coast chemical corridor demand for temperature-controlled pharmaceutical movements is concentrating capacity investment in dedicated reefer tanker networks.
- 49 CFR placarding automation:Digital hazmat classification systems are reducing loading dock dwell times for Class 3 flammable liquid shipments.
Market Restraints
- DOT hazmat registration fee restructuring:Small fleet operators face working capital pressure as per-vehicle fees escalate, pushing marginal carriers toward asset-light brokerage models.
- Specialized driver scarcity:Tanker endorsements and HAZMAT certifications create multi-month hiring pipelines that constrain fleet expansion velocity.
- Insurance underwriting concentration:Three national carriers control excess liability coverage for radioactive materials transport, creating capacity bottlenecks during renewal cycles.
Strategic Opportunities
- Brownfield site remediation:EPA Superfund redevelopment contracts tied to urban logistics hub construction offer countercyclical waste transport revenue streams.
- Autonomous vehicle pilot corridors:Interstate 10 freight corridors through Arizona and New Mexico present testing grounds for self-driving tanker convoys pending PHMSA rulemaking.
- Cross-border harmonization:US-Mexico-Canada Agreement alignment on dangerous goods documentation is compressing customs clearance times for maquiladora chemical flows.
Industry Challenges
- Certified handler attrition:OSHA 29 CFR 1910.120 HAZWOPER training requirements face completion rate gaps as experienced technicians exit the workforce.
- Legacy TMS integration:Terminal operating systems at Gulf Coast bulk liquid facilities require custom API development to connect with cloud-based dispatch platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hazardous Goods Logistics Market |
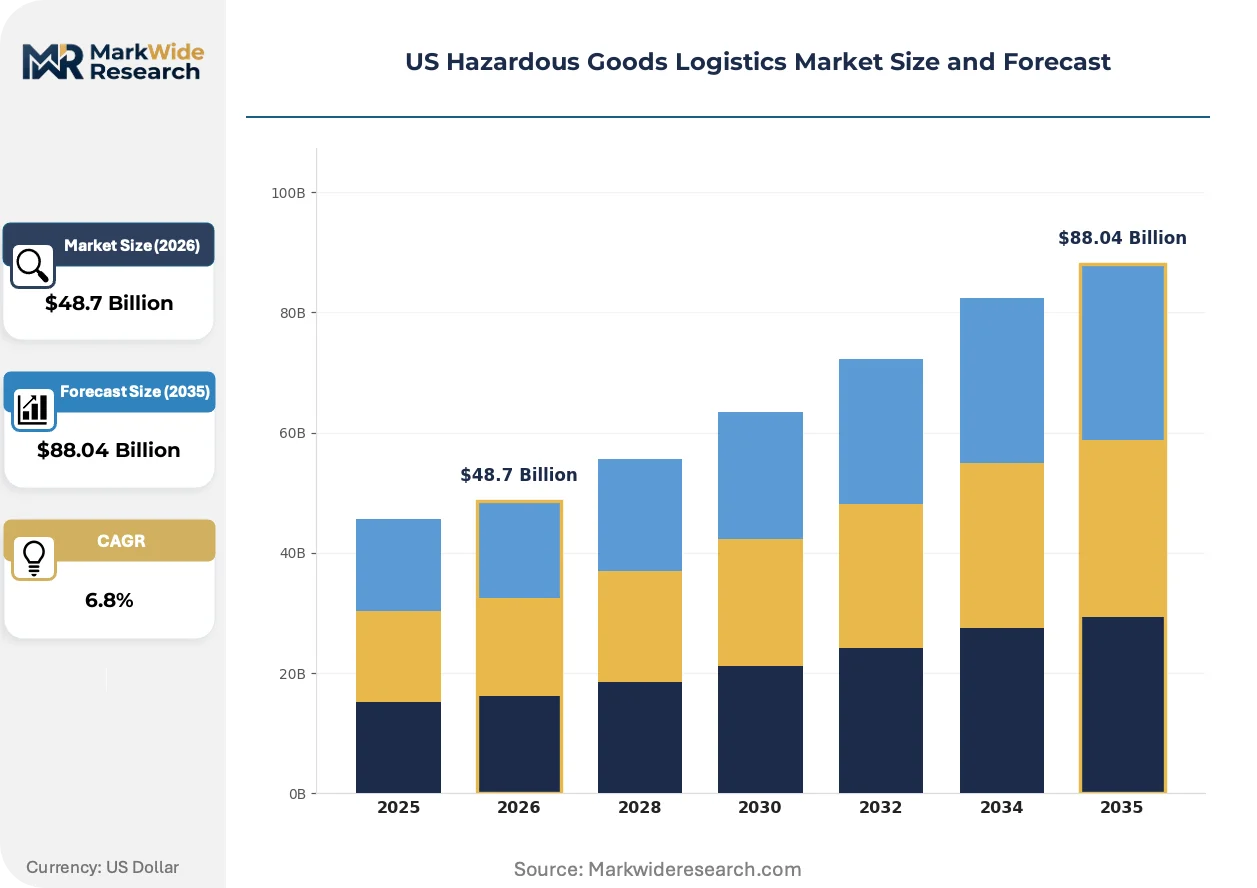
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemicals, Explosives, Biological Materials, Radioactive Substances Delivery Mode: Air Freight, Sea Freight, Road Transport, Rail Transport Service Type: Packaging, Storage, Waste Management, Site Remediation End User: Manufacturing, Pharmaceuticals, Energy, Construction |
| Companies Covered | XPO Logistics, Schneider Logistics, Deutsche Post DHL Group, Kenan Advantage Group, GEODIS, Kuehne + Nagel, Landstar System Inc., APL Logistics, DSV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hazardous Goods Logistics Market Evolving Landscape
Digital chain-of-custody documentation and sensor-enabled cargo monitoring are compressing incident response times while expanding audit trail granularity for enforcement actions.
Blockchain-verified hazmat manifesting is modularizing compliance documentation across multimodal handoffs. Petrochemical shippers operating Texas-to-Louisiana corridors are piloting distributed ledger systems that synchronize EPA, DOT, and carrier records in real time. This architecture is modularizing liability transfer points and reducing detention billing disputes at intermodal terminals.
FAA Part 135 dangerous goods air transport rules are tightening lithium battery packaging standards for cargo operators. Express carriers serving pharmaceutical biologics are retrofitting cold-chain containers with real-time temperature logging to satisfy IATA DG documentation requirements. Pharmaceutical distributors with time-critical radiopharmaceutical shipments are absorbing premium freight costs to maintain shelf-life integrity.
Consolidated procurement of hazmat logistics services is displacing fragmented spot-market contracting among mid-size chemical manufacturers. Third-party logistics providers with dedicated tanker networks are capturing multi-year commitments previously split across regional carriers. This concentration is most visible among Gulf Coast specialty chemical producers seeking unified compliance accountability.
US Hazardous Goods Logistics Market Segmentation
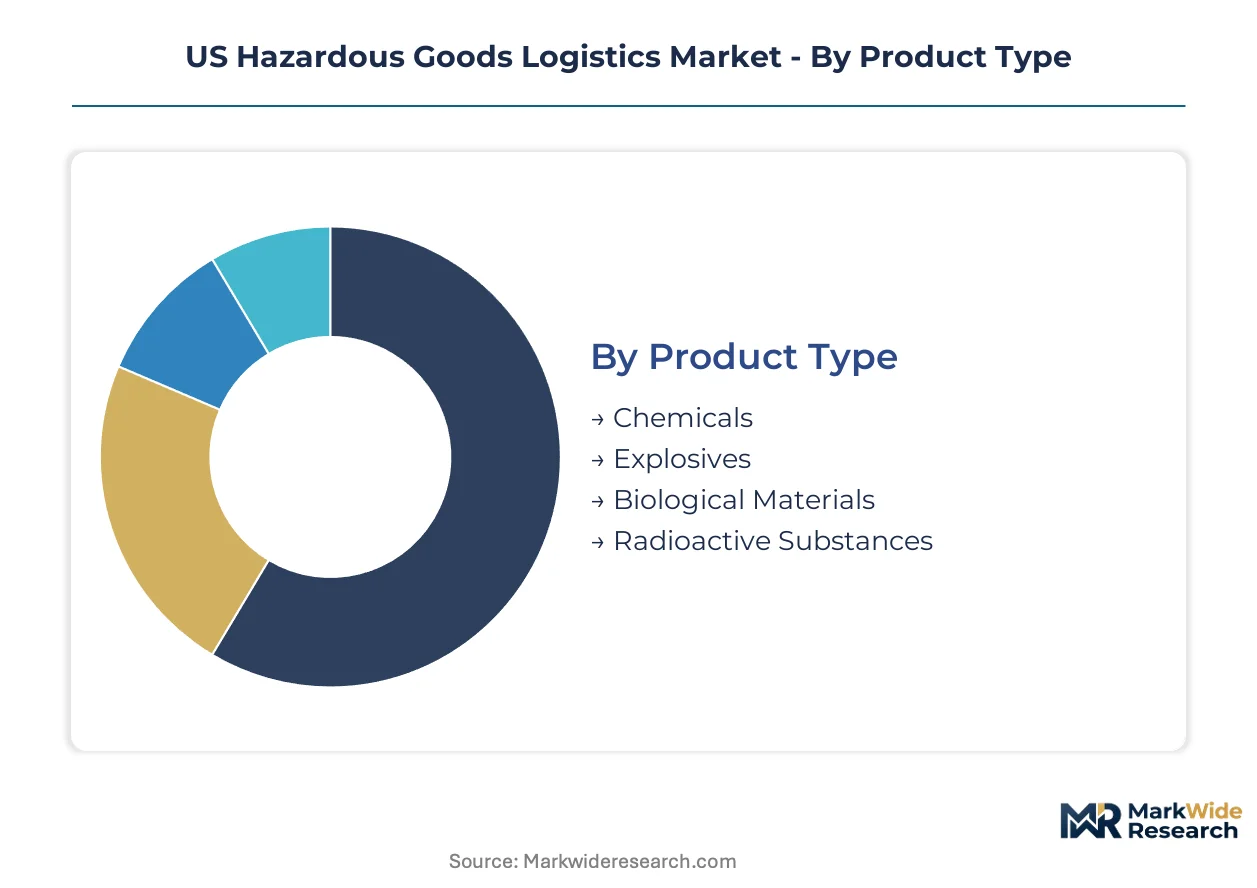
Regulatory complexity fragments the US hazardous goods logistics landscape across material hazard classes, transport modes, and service specializations. Each segment carries distinct compliance burdens, capital requirements, and margin profiles that shape carrier positioning strategies.
Product Type:
Chemicals dominate shipment volumes while radioactive substances command the steepest premium tiers due to specialized equipment and insurance requirements.
- Chemicals:Class 3 flammable liquids and corrosive materials constitute the bulk of tonnage moved through Gulf Coast petrochemical corridors. Texas and Louisiana refineries are consolidating outsourced logistics contracts as EPA manifest documentation rules tighten, pulling dedicated tanker fleets into long-term service agreements.
- Radioactive Substances:Transport of radiopharmaceuticals and industrial isotopes requires Type B packaging certification and real-time chain-of-custody tracking. Three national underwriters control excess liability coverage, creating renewal bottlenecks that constrain carrier entry.
- Explosives:Blasting agents and detonators move under 49 CFR strict routing protocols with mandatory rest stop prohibitions.
- Biological Materials:Temperature-controlled pharmaceutical biologics concentrate demand for cold-chain reefer tankers in the Gulf Coast corridor.
Mature deployment sits with Chemicals. Newer deployment is concentrated in Biological Materials as pharmaceutical cold-chain requirements expand.
Delivery Mode:
Cost tier separation runs from premium air freight for time-critical shipments to economy rail for bulk chemical movements.
- Road Transport:Tanker trucks provide last-mile flexibility for chemical and explosive deliveries under DOT routing regulations. Specialized driver scarcity—tanker endorsements plus HAZMAT certifications create multi-month hiring pipelines—constrains fleet expansion velocity across Texas and Louisiana corridors.
- Air Freight:FAA Part 135 dangerous goods rules govern lithium battery and radiopharmaceutical movements. Express carriers serving pharmaceutical distributors absorb premium freight costs to maintain shelf-life integrity for time-critical biologics.
- Rail Transport:Bulk liquid chemicals move via placarded tank cars with centralized traffic control routing.
- Sea Freight:IMO dangerous goods code compliance structures international chemical container movements through US ports.
Road Transport anchors domestic volume. Air Freight is gaining share fastest as pharmaceutical cold-chain requirements intensify.
Service Type:
Application focus separates infrastructure-heavy storage and remediation from transactional packaging services.
- Waste Management:EPA cradle-to-grave liability rules impose structural margin pressure on hazardous waste transport. Site remediation contracts tied to brownfield redevelopment offer countercyclical revenue stability as urban logistics hub construction accelerates.
- Storage:PHMSA-certified facilities with secondary containment and fire suppression systems serve as consolidation points for chemical manufacturers.
- Packaging:UN-certified container fabrication and IATA-compliant air freight preparation support multimodal handoffs.
- Site Remediation:EPA Superfund redevelopment contracts concentrate in former industrial zones undergoing logistics facility conversion.
Waste Management shows the steepest expansion trajectory as manifest documentation requirements intensify.
End User:
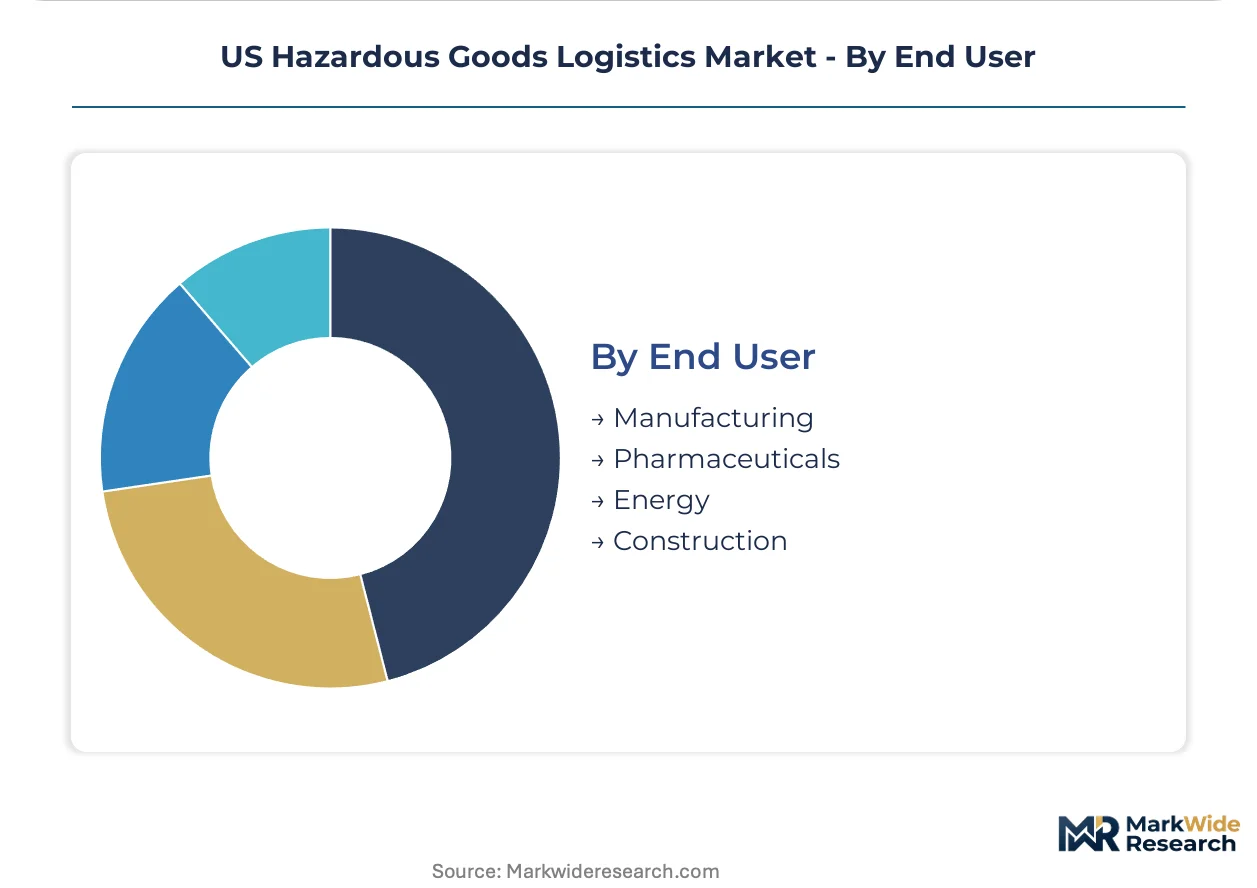
Customer type stratification reflects divergent compliance sophistication and contract duration preferences.
- Energy:Oilfield chemical logistics and radioactive source transport for well logging operations concentrate in Permian Basin and Gulf Coast production zones. Consolidated procurement is displacing fragmented spot-market contracting among mid-size chemical manufacturers.
- Pharmaceuticals:Radiopharmaceutical distributors require time-definite delivery windows measured in hours. Real-time temperature logging retrofits satisfy IATA dangerous goods documentation for cold-chain biologics.
- Manufacturing:Specialty chemical producers seek unified compliance accountability through multi-year third-party logistics commitments.
- Construction:Explosives procurement for infrastructure projects follows seasonal demand patterns with strict storage duration limits.
Energy commands the largest contract values. Pharmaceuticals is climbing the fastest as biologics cold-chain requirements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zone 115 in Harris County, Texas, anchors the nation's largest concentration of hazardous goods logistics infrastructure. Gulf Coast chemical corridors generate outbound shipment volumes that exceed all other US regions combined. EPA Region 6 maintains the densest inspector presence for cradle-to-grave manifest enforcement.
Texas Gulf Coast
Petrochemical manufacturers in Houston and Beaumont-Port Arthur are consolidating outsourced logistics contracts as EPA manifest documentation rules tighten. DOT hazmat safety permit holders in this corridor face concentrated PHMSA audit activity. Specialized tanker fleets serving Port of Houston chemical terminals are absorbing multi-year service agreements from refiners seeking unified compliance accountability.
Louisiana Chemical Corridor
Baton Rouge and Lake Charles refineries are pulling cold-chain reefer tanker capacity into dedicated pharmaceutical biologics movements. Louisiana Department of Environmental Quality permit timelines for secondary containment facilities are extending, constraining storage expansion velocity. Mississippi River barge-to-truck intermodal points at Geismar and Taft are seeing detention billing disputes compress through blockchain-verified manifesting pilots.
California Industrial Zones
Los Angeles Basin pharmaceutical distributors are absorbing premium freight costs for time-critical radiopharmaceutical shipments subject to FAA Part 135 dangerous goods rules. CalEPA hazardous waste manifest requirements exceed federal stringency, pushing waste management carriers toward asset-light brokerage models. Bay Area biologics cold-chain demand is concentrating investment in temperature-controlled air freight preparation facilities.
Midwest Manufacturing Belt
Ohio River Valley specialty chemical producers are displacing fragmented spot-market contracting with consolidated third-party logistics procurement. Illinois EPA hazardous waste transporter licensing creates multi-month certification pipelines that constrain carrier entry. Chicago-area intermodal terminals are retrofitting legacy operating systems with custom API development to connect cloud-based dispatch platforms.
Northeast Corridor
New Jersey pharmaceutical clusters are driving express carrier retrofitting of cold-chain containers with real-time temperature logging for IATA DG compliance. Pennsylvania Department of Environmental Protection Superfund redevelopment contracts are generating countercyclical waste transport revenue around former industrial sites converting to logistics hubs. Port of Philadelphia chemical container movements face IMO dangerous goods code documentation bottlenecks during peak seasons.
US Hazardous Goods Logistics Market Competitive Landscape
US-based asset-heavy carriers anchor one tier; European integrated logistics groups hold compliance documentation differentiation. The market structure reflects consolidation pressure from specialized driver scarcity and insurance underwriting concentration. Three strategic archetypes dominate: dedicated tanker network operators, integrated cross-border compliance platforms, and asset-light hazardous materials brokers. M&A activity concentrates on acquiring PHMSA-certified training infrastructure; strategic partnerships target autonomous vehicle pilot corridor development.
Among US-based dedicated tanker operators, Schneider Logistics and Kenan Advantage Group exemplify the asset-heavy archetype with Gulf Coast corridor concentration. Deutsche Post DHL Group represents the integrated compliance platform model, leveraging documentation systems that streamline cross-border movements. These three companies occupy positions that reflect the market's bifurcation between regional infrastructure control and multinational regulatory harmonization capability.
| Leading Market Players |
|---|
| XPO Logistics |
| Schneider Logistics |
| Deutsche Post DHL Group |
| Kenan Advantage Group |
| GEODIS |
| Kuehne + Nagel |
| Landstar System Inc. |
| APL Logistics |
| DSV |
| Others |
Value Network & Pricing Analysis
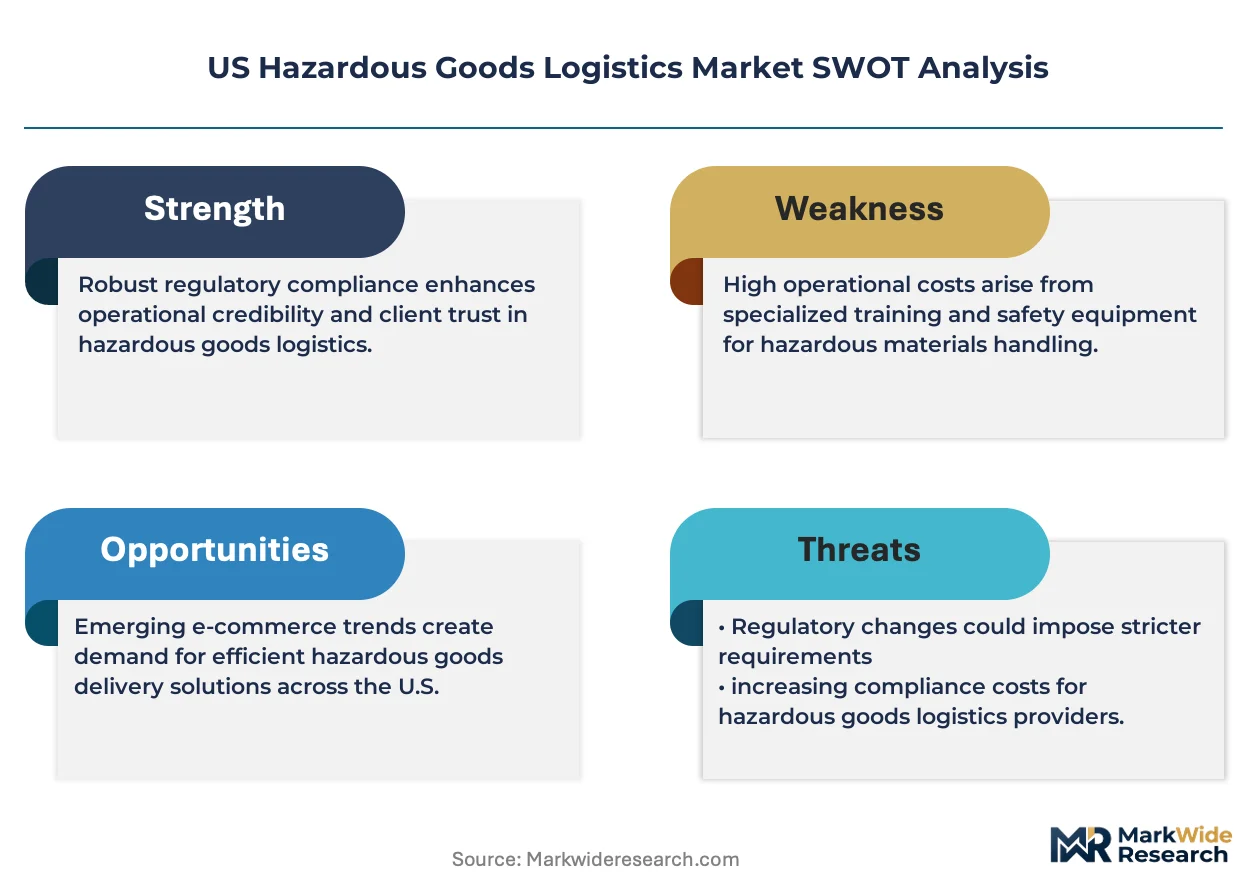
Diesel fuel price indices cascade through hazardous goods transport economics, compressing margins for Class 3 flammable liquid haulers while amplifying pricing power for carriers with dedicated tanker networks. EPA manifest documentation requirements add compliance cost layers that concentrate in spot-market brokerage tiers.
Pricing Analysis
Expedited lead-time premiums separate pharmaceutical biologics movements from standard chemical haulage, with radiopharmaceutical distributors absorbing freight surcharges measured against shelf-life degradation risks. Three-tier pricing structure across dedicated contract, committed capacity, and spot brokerage levels stratifies by DOT certification tier and insurance coverage depth. Cost compression in small fleet operations intensifies as per-vehicle registration fees escalate under PHMSA restructuring. Mid-size chemical manufacturers exhibit highest price sensitivity, while radiopharmaceutical distributors prioritize time-definite reliability over rate negotiation.
Supply Chain Analysis
Reverse logistics for empty container returns and decontaminated tanker repositioning consumes 15-20% of fleet operating hours in Gulf Coast corridors. Equipment manufacturing concentrates in Ohio, Indiana, and Texas, with specialized tanker fabrication drawing from regional steel and aluminum sheet suppliers. Single-source vulnerability pervades excess liability insurance for radioactive materials, where three national underwriters control market access. Distribution runs through PHMSA-certified terminals with secondary containment, consolidating chemical flows before last-mile placarded truck deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-verified manifesting systems are displacing paper-based EPA documentation, compressing liability transfer latency from hours to minutes. This transition favors carriers with integrated digital infrastructure over legacy operators dependent on manual chain-of-custody processes.
For Market Incumbents: Extend dedicated tanker network coverage through PHMSA-certified training center acquisitions, countering specialized driver scarcity that constrains fleet expansion velocity. Deepen terminal infrastructure control in Port of Houston chemical corridors to capture multi-year refinery service agreements. Autonomous vehicle pilot programs present defensive R&D positioning against regulatory lag in self-driving hazmat standards.
For New Entrants and Emerging Players: Enter via cold-chain reefer tanker specialization for pharmaceutical biologics, where Gulf Coast corridor demand outpaces dedicated capacity supply. Brownfield site remediation contracts tied to urban logistics hub construction offer asset-light entry with countercyclical revenue stability. Target EPA Region 6 waste management brokerage, where manifest documentation complexity pushes small fleet operators toward third-party partnerships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-heavy carriers with Gulf Coast corridor concentration in Texas and Louisiana, where petrochemical outsourcing trends sustain contract duration expansion. PHMSA-certified training infrastructure commands scarcity premiums during consolidation waves. Monitor DOT hazmat safety permit revocation patterns as early signals of enforcement leverage redistribution among regional field offices.
| Strategic Initiative | Industry Significance |
|---|---|
| PHMSA-Certified Training Center Acquisition | Captures specialized driver pipeline control as HAZMAT certification scarcity intensifies hiring bottlenecks. |
| Blockchain Manifesting System Deployment | Compresses EPA documentation latency while modularizing liability transfer points across multimodal handoffs. |
| Cold-Chain Reefer Tanker Fleet Expansion | Addresses Gulf Coast pharmaceutical biologics demand concentration with temperature-controlled capacity. |
| Brownfield Remediation Contract Pursuit | Generates countercyclical waste transport revenue through EPA Superfund redevelopment site servicing. |
| Autonomous Vehicle Pilot Corridor Development | Positions for PHMSA rulemaking completion on self-driving Class 3 flammable liquid transport standards. |
Research Methodology
Document review covered DOT hazmat safety permit registries, EPA manifest enforcement records, and PHMSA incident databases, complemented by interviews with fleet operations directors, chemical manufacturer logistics procurement leads, and insurance underwriters specializing in excess liability coverage. Secondary validation drew from FMCSA carrier safety measurement data, SEC 10-K filings of publicly traded logistics operators, and American Chemistry Council freight movement reports. Bottom-up segment sizing triangulated against top-down macroeconomic freight indices.
Historical carrier capacity deployment patterns cross-referenced against panel input from chemical shipper procurement committees anchored forecast trajectories across the projection horizon. Segmentation modeling incorporated hazard class, transport mode, service specialization, and end-use industry dimensions. CAGRs derived from weighted regression across contract duration trends, regulatory compliance cost escalation rates, and petrochemical production capacity announcements.
Revisions become necessary when PHMSA autonomous vehicle rulemaking accelerates, EPA manifest documentation requirements expand beyond cradle-to-grave liability, or insurance underwriting concentration shifts among national carriers. Practitioners should monitor DOT hazmat safety permit revocation rates, specialized driver training completion gaps, and blockchain manifesting adoption curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Fleet of Containers Market
Logistics and Shipping
US Cross-Border Road Freight Transport Market
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
Australia Freight and Logistics Market
Logistics and Shipping
WAN Connected Returnable Transport Asset Tracking Market
Logistics and Shipping
On-Demand Logistics Market
Logistics and Shipping
Vietnam Express Delivery Services Market
Logistics and Shipping
Logistics Visualization System Market
Logistics and Shipping
Germany Automotive 3PL Market
Logistics and Shipping
North America Logistics Market
Logistics and Shipping
GCC Freight and Logistics Market
Logistics and Shipping
ASEAN Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
Nigeria Air Freight Market