
 United Kingdom Contract Logistics Market | 2026-2036
United Kingdom Contract Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Contract Logistics Market Analytics
E-commerce fulfillment buyers is rotating share toward pharmaceutical and automotive contract logistics clients as these sectors prioritize temperature-controlled chains and just-in-time sequencing. DHL Supply Chain anchors European pharmaceutical distribution from its UK hub network, leveraging certified GDP-compliant facilities. GXO Logistics specializes in automated warehousing for consumer goods, competing on robotics density and labor efficiency. Wincanton sustains its position in automotive sequencing through dedicated contracts with OEM assembly plants.
Contract logistics encompasses the outsourcing of supply chain execution activities—transportation, warehousing, inventory management, and value-added services—under multi-year agreements where providers assume operational responsibility against defined service levels. Cold chain infrastructure, bonded storage, and real-time inventory visibility systems constitute core technical capabilities within this model. Warehousing and value-added services capture expanding margin pools as clients outsource kitting, labeling, and returns processing alongside basic storage. Transportation segments face compression from fuel cost volatility and driver availability constraints, while last-mile delivery models within the delivery model dimension absorb disproportionate capital as urban emission zones tighten.
The UK's Health and Safety Executive enforces warehouse safety standards under the Workplace (Health, Safety and Welfare) Regulations, directly shaping facility design and automation investment thresholds. HMRC's customs frameworks and the Driver and Vehicle Standards Agency's operator licensing requirements govern cross-border flows and fleet compliance costs respectively. Stakeholders must monitor how the UK's evolving carbon border mechanisms and potential divergence from EU vehicle standards reshape network design decisions.
Market Dynamics
Post-Brexit customs complexity is fragmenting fulfillment networks across the United Kingdom, forcing providers to rebuild infrastructure around HMRC's Border Target Operating Model rather than legacy EU-integrated flows.
Growth Catalysts
- E-commerce order surge:Online retailers are exhausting in-house capacity and outsourcing fulfillment to specialized third-party operators with automated sortation and returns processing capabilities.
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics and vaccines require GDP-certified warehousing, pulling investment into validated refrigeration and real-time monitoring infrastructure.
- Midlands logistics corridor concentration:East Midlands Airport and M1 motorway clustering create network effects that attract national distribution centers seeking air-road intermodal efficiency.
Market Restraints
- Fuel cost volatility:Diesel price swings compress transportation margins and destabilize contract rate structures that lack fuel surcharge flexibility.
- Driver availability constraints:HGV operator licensing bottlenecks and demographic retirement waves tighten fleet capacity faster than training pipelines can replenish.
- Bonded warehousing capital intensity:HMRC customs facility certification demands specialized security infrastructure that locks capital into lower-yielding assets compared to standard warehousing.
Strategic Opportunities
- Urban emission zone compliance services:London's ULEZ and expanding clean air zones create demand for electric last-mile fleet substitution and micro-fulfillment node placement.
- Automotive just-in-time sequencing:OEM assembly plants near Birmingham and Derby require synchronized inbound parts delivery that contract logistics providers can capture through dedicated line-side operations.
- Returns processing specialization:Apparel and electronics e-commerce generate high reverse-logistics volumes that specialized inspection, refurbishment, and resale services can monetize.
Industry Challenges
- Automation technician scarcity:Warehouse robotics deployment outpaces the supply of maintenance engineers capable of servicing autonomous mobile robots and goods-to-person systems.
- Legacy WMS integration friction:Replacing outdated warehouse management systems with cloud-native platforms requires costly data migration and operational continuity safeguards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Contract Logistics Market |
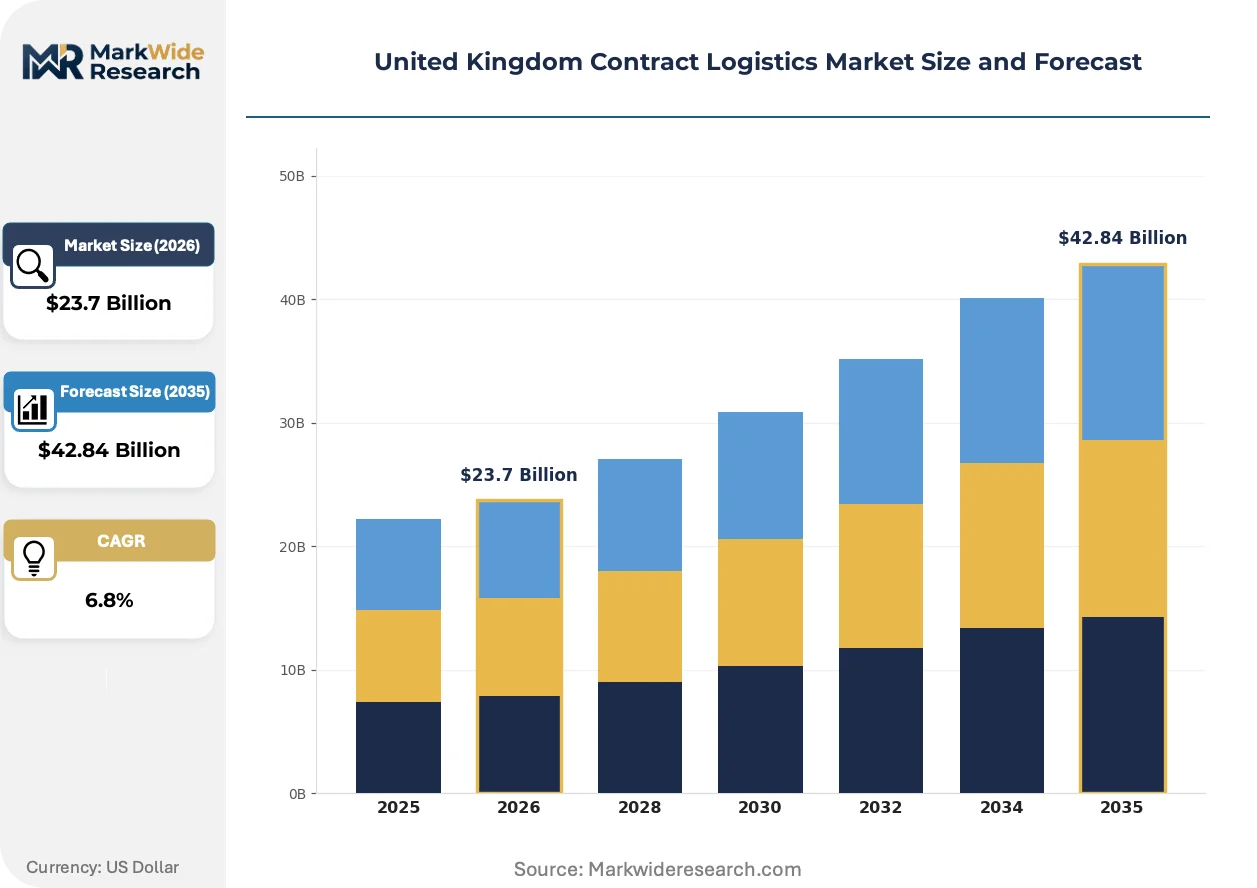
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Value-Added Services, Freight Forwarding End User: E-commerce, Automotive, Consumer Goods, Pharmaceuticals Delivery Model: Direct Delivery, Cross-Docking, Distribution Center Management, Last Mile Capacity: Small Scale, Medium Scale, Large Scale, Customized Solutions |
| Companies Covered | DHL Supply Chain, XPO Logistics, GXO Logistics, Kuehne+Nagel, CEVA Logistics, DB Schenker, UPS Supply Chain Solutions, FedEx Supply Chain, Wincanton, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Contract Logistics Market Evolving Landscape
Automation density and regulatory compliance are converging to reshape how contract logistics providers compete on speed, accuracy, and carbon accountability.
Autonomous mobile robots are fragmenting traditional warehouse labor models by enabling goods-to-person picking that reduces floor travel time. E-commerce fulfillment centers are deploying these systems at accelerating rates to manage SKU proliferation and order volatility. The technology is fragmenting the market into high-automation specialists and labor-dependent regional players with diverging cost structures.
HMRC's Border Target Operating Model is mandating phased customs controls on EU imports that reshape inventory positioning strategies. Full customs declarations and safety and security declarations now apply to most goods, increasing documentation burdens and inspection risk. Pharmaceutical and food importers are responding by shifting stock into UK-based bonded warehouses to defer duty exposure and reduce border delays.
Carbon reporting mandates from the UK's Streamlined Energy and Carbon Reporting framework are penetrating supplier selection criteria. Large corporate buyers now require Scope 3 emissions disclosure from logistics partners, favoring providers with electric fleet deployment and renewable-powered facilities. This pressure is most visible in London and Birmingham metropolitan contracts where municipal procurement policies embed emissions thresholds.
United Kingdom Contract Logistics Market Segmentation
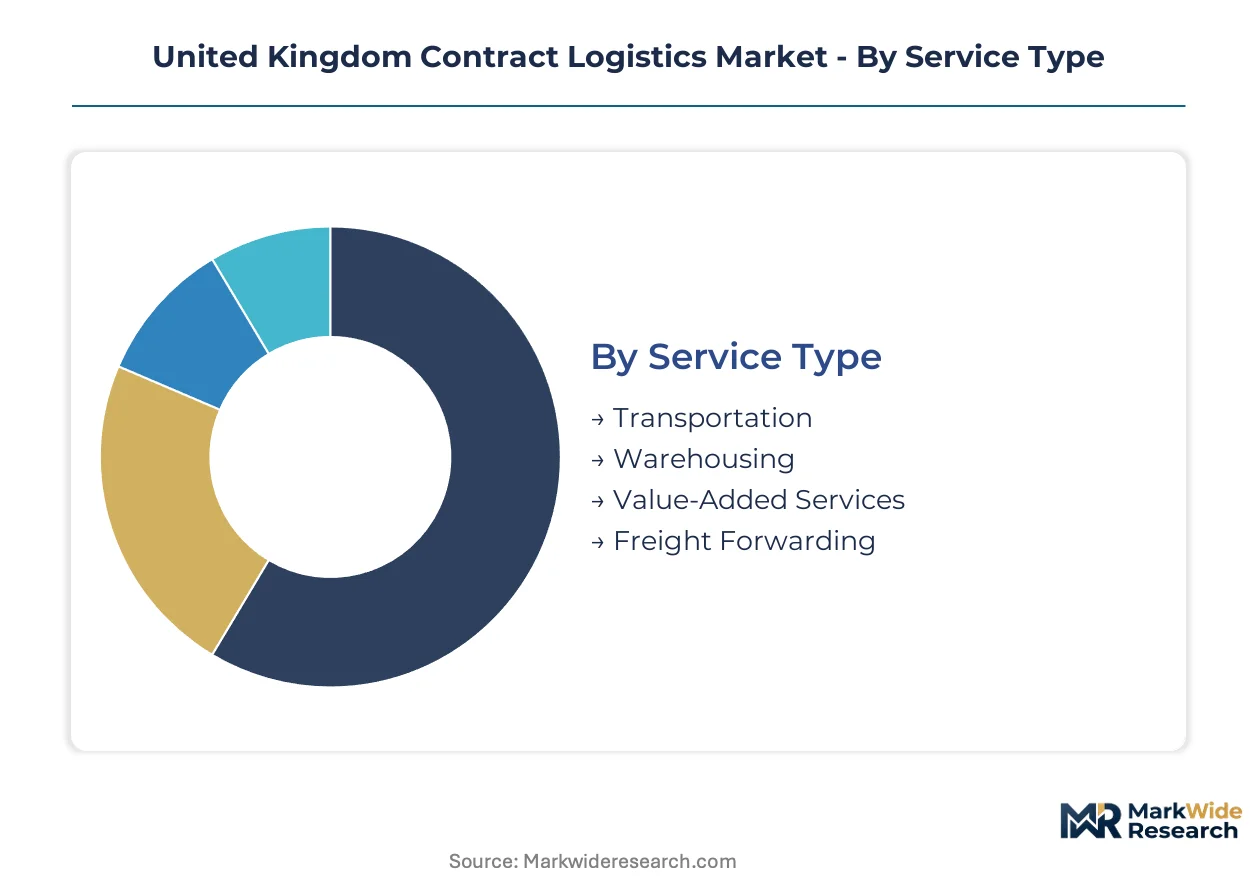
Segmentation in United Kingdom contract logistics reveals how regulatory frameworks and operational scale reshape provider specialization. Service type and end-user concentration determine where capital flows and which capabilities command premium positioning.
Service Type:
HMRC's Border Target Operating Model and the UK's post-Brexit customs regime differentiate service profitability through compliance infrastructure requirements.
- Warehousing:GDP-certified cold storage and bonded facilities under HMRC supervision anchor pharmaceutical and import-deferment demand. Midlands logistics corridor clustering around East Midlands Airport concentrates investment in temperature-controlled and customs-approved capacity.
- Value-Added Services:Kitting, labeling, returns processing, and quality inspection absorb expanding margin pools as e-commerce clients outsource reverse logistics complexity. Apparel and electronics sectors drive adoption of specialized refurbishment and resale infrastructure.
- Transportation:Fleet operations face Driver and Vehicle Standards Agency licensing constraints and fuel cost volatility that compress margins without flexible surcharge mechanisms.
- Freight Forwarding:Customs brokerage and documentation management absorb post-Brexit complexity for EU-UK trade flows.
Established volume favors warehousing; emerging adoption favors value-added services.
End User:
Customer procurement patterns split between high-compliance regulated sectors and high-velocity consumer-facing operations with diverging service level requirements.
- E-commerce:Order volatility and SKU proliferation strain in-house fulfillment networks, driving outsourcing to automated third-party operators with returns processing capabilities. Midlands distribution clustering supports national reach with air-road intermodal efficiency.
- Pharmaceuticals:Temperature-sensitive biologics require validated cold chains under Health and Safety Executive warehouse safety standards and GDP certification. Real-time monitoring infrastructure and regulatory documentation absorb disproportionate capital investment.
- Automotive:Just-in-time sequencing for OEM assembly plants near Birmingham and Derby demands synchronized inbound parts delivery with minimal line-side inventory.
- Consumer Goods:Volume-driven storage and distribution prioritize labor efficiency and robotics density over specialized compliance infrastructure.
Pharmaceuticals command premium pricing through regulatory barriers; e-commerce represents the steepest expansion trajectory through volume absorption.
Delivery Model:
Urban emission zone tightening under London's ULEZ and expanding clean air policies fragment last-mile economics from trunk haul efficiency.
- Last Mile:Electric fleet substitution and micro-fulfillment node placement absorb capital to comply with municipal emissions thresholds in London and Birmingham metropolitan contracts.
- Distribution Center Management:National hub operations concentrate in the Midlands logistics corridor for air-road intermodal access.
- Direct Delivery:Point-to-point trunk haul faces diesel price volatility and driver availability constraints under DVSA operator licensing requirements.
- Cross-Docking:Rapid freight consolidation minimizes inventory holding for time-sensitive automotive and retail flows.
Distribution center management captures established volume; last mile gains share fastest through regulatory compulsion.
Capacity:
Scale economics separate standardized automation investments from bespoke engineering for specialized compliance requirements.
- Large Scale:Automated sortation and goods-to-person robotics at national distribution centers achieve labor efficiency through capital density.
- Customized Solutions:Bonded warehousing and pharmaceutical cold chains require facility-specific security and validation engineering under HMRC and GDP standards.
- Medium Scale:Regional distribution balances automation investment with flexibility for multi-client operations.
- Small Scale:Urban micro-fulfillment nodes serve last-mile emission compliance with limited SKU depth.
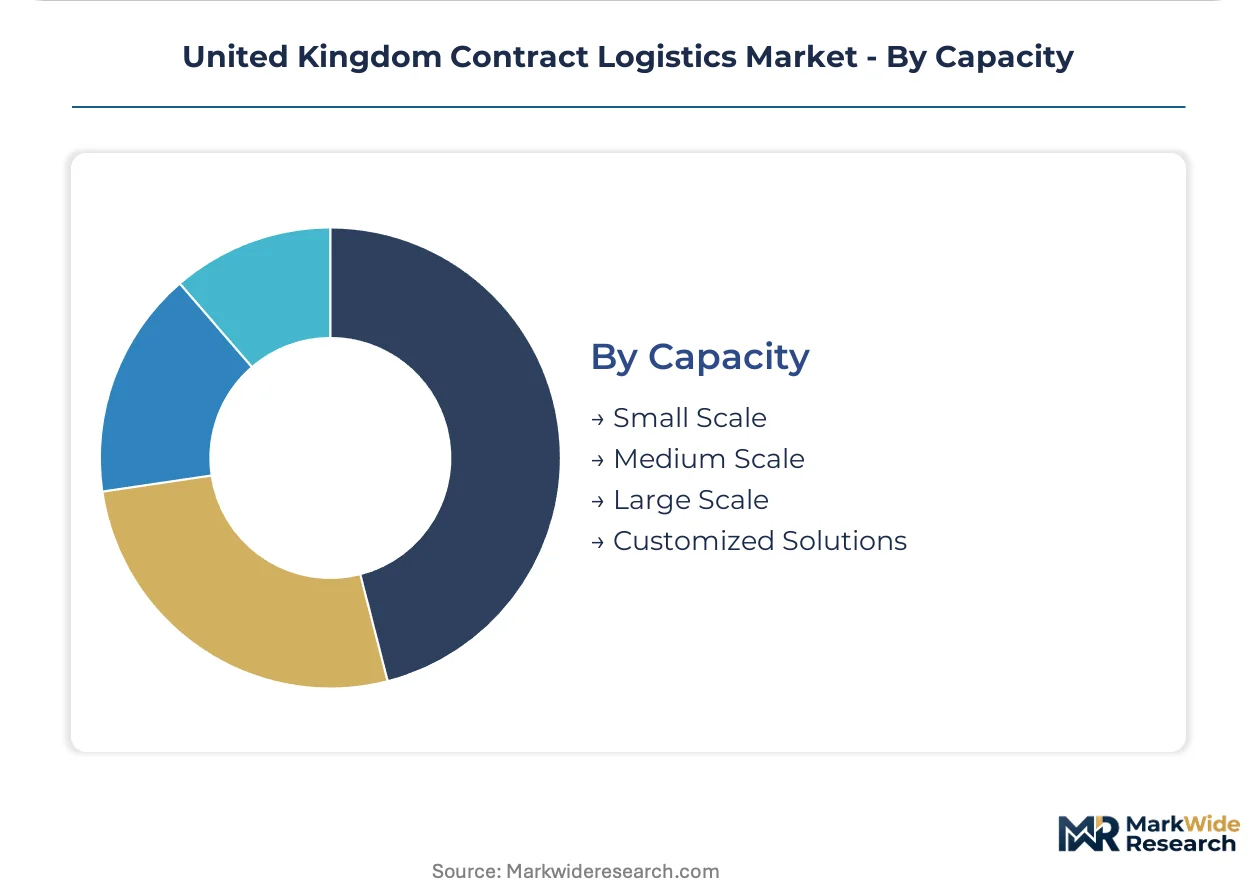
Large scale dominates throughput economics; customized solutions expand through regulatory specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The East Midlands Airport cargo terminal and M1 motorway corridor anchor the United Kingdom's distribution infrastructure, creating intermodal efficiency for national fulfillment networks.
London and the Southeast
E-commerce fulfillment demand concentrates around Heathrow's air cargo capacity and the Thames Valley distribution belt. Transport for London's Ultra Low Emission Zone (ULEZ) compels electric fleet substitution and micro-fulfillment node placement. Dartford and Tilbury port clusters absorb containerized imports requiring rapid deconsolidation.
Midlands Logistics Corridor
Pharmaceutical cold chain investment clusters around East Midlands Airport's temperature-controlled cargo facilities under Health and Safety Executive warehouse safety standards. Birmingham and Derby automotive assembly plants pull just-in-time sequencing operations into dedicated line-side facilities. Coventry's central positioning supports national distribution center concentration.
North England
Liverpool and Manchester port complexes handle transatlantic container flows requiring bonded warehousing under HMRC's Border Target Operating Model. Yorkshire distribution parks serve Scottish market penetration with overnight trunk haul capability. Teesport's freeport status attracts customs-deferment inventory positioning.
Scotland
Aberdeen's energy sector logistics demand anchors specialized supply chain services for North Sea operations. Edinburgh and Glasgow distribution nodes handle pharmaceutical and whisky exports requiring GDP-certified cold chains. Grangemouth port facilities provide Scottish import gateway capacity with customs clearance infrastructure.
United Kingdom Contract Logistics Market Competitive Landscape
Concentration sits with diversified European logistics conglomerates and specialized UK domestic operators. The market structure balances global network reach against regional regulatory expertise. Three archetypes dominate: pan-European integrated providers with pharmaceutical certification, technology-forward automation specialists, and automotive-dedicated sequencing operators. Competitive moves center on customs infrastructure acquisition and robotics density expansion.
Within the integrated logistics tier, DHL Supply Chain and Kuehne+Nagel represent pan-European network operators with GDP-compliant pharmaceutical capabilities. GXO Logistics exemplifies automation-focused warehousing specialists competing on robotics deployment density. Wincanton occupies a position as a UK-domestic automotive sequencing provider with dedicated OEM relationships.
| Leading Market Players |
|---|
| DHL Supply Chain |
| XPO Logistics |
| GXO Logistics |
| Kuehne+Nagel |
| CEVA Logistics |
| DB Schenker |
| UPS Supply Chain Solutions |
| FedEx Supply Chain |
| Wincanton |
| Others |
Value Network & Pricing Analysis
Midlands distribution center clustering around East Midlands Airport and the M1 corridor concentrates national fulfillment capacity, creating scale-driven price floors that favor large-scale operators over regional competitors. This geographic concentration shapes both procurement leverage for warehouse automation and the threshold volumes required to justify GDP-certified cold chain investment.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical GDP-certified contracts from standard consumer goods warehousing, with certification grade and automation density driving price differentiation. Pricing pressure intensifies in transportation segments as diesel volatility compresses margins without flexible fuel surcharge mechanisms. E-commerce fulfillment buyers exhibit highest price sensitivity due to SKU proliferation and returns processing complexity, while pharmaceutical clients accept premium pricing for validated cold chain assurance.
Supply Chain Analysis
The United Kingdom produces specialized customs brokerage and bonded warehousing capacity under HMRC's Border Target Operating Model, drawing from EU-originated component flows and transatlantic container imports through Liverpool and Tilbury. Raw material dependencies span warehouse automation hardware from Germany and China, refrigeration equipment from Denmark and Japan, and fleet vehicles from European OEMs. Single-source vulnerability concentrates in autonomous mobile robot maintenance engineering. Distribution runs through Midlands national hubs with last-mile fragmentation into London ULEZ-compliant electric fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom contract logistics market sits at a platform-economics inflection where warehouse management system interoperability determines multi-client facility utilization. Real-time inventory visibility APIs are displacing proprietary data silos as the dominant ecosystem architecture.
For Market Incumbents: Consolidate market position through backward integration into customs brokerage capabilities under HMRC's evolving Border Target Operating Model. Acquire specialized GDP-certified cold chain assets to defend against pharmaceutical-focused entrants. Automation technician training pipelines represent a critical capacity lever as warehouse robotics deployment outpaces maintenance labor supply.
For New Entrants and Emerging Players: GDP certification fast-track programs for pharmaceutical cold chain operations open white-space penetration in temperature-sensitive biologics distribution. Target urban micro-fulfillment node placement for London ULEZ compliance as the most penetrable delivery model segment. Go-to-market positioning should emphasize electric last-mile fleet substitution bundled with real-time carbon reporting for Scope 3 disclosure requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automation-forward warehousing specialists with cloud-native WMS platforms over legacy labor-dependent operators. Long-term viability across the projection horizon hinges on robotics density and API-first interoperability. Acquisition target archetypes include customs-certified bonded warehouse operators and automotive sequencing specialists near Birmingham-OEM corridors. The signal to watch is HMRC customs infrastructure investment announcements as inflection indicators for inventory positioning strategy shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Customs Infrastructure Acquisition | HMRC Border Target Operating Model compliance secures bonded warehousing revenue streams. |
| Robotics Density Expansion | Autonomous mobile robot deployment reduces floor travel time in e-commerce fulfillment centers. |
| Pharmaceutical Cold Chain Certification | GDP-compliant facilities capture temperature-sensitive biologics distribution premiums. |
| Electric Last-Mile Fleet Substitution | London ULEZ compliance enables metropolitan contract retention and renewal. |
| Warehouse Management System Modernization | Cloud-native platforms replace legacy systems to support multi-client interoperability. |
Research Methodology
Cross-validation between primary interviews with contract logistics operators and secondary analysis of HMRC customs filings anchors the qualitative findings. Stakeholder consultations included warehouse operations directors, pharmaceutical supply chain managers, automotive procurement leads, and e-commerce fulfillment executives. Secondary sources encompassed Health and Safety Executive warehouse safety standards, Driver and Vehicle Standards Agency licensing data, and customs trade flow records. Bottom-up facility capacity assessments and top-down market sizing triangulated volume estimates.
Sensitivity analysis across automation adoption rates and customs processing time assumptions stress-tested projection robustness throughout the forecast period. Segmentation dimensions modeled encompassed service type, end-user industry, delivery model, and facility scale tier. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points. Industry-specific inputs included East Midlands Airport cargo throughput trends and ULEZ zone expansion schedules.
Decision-makers should treat outputs as directional under assumptions of continued e-commerce penetration and stable HMRC customs framework implementation; material deviation in Brexit trade policy or fuel cost volatility would warrant model refresh. Recalibration cycles align with material shifts in Border Target Operating Model phases and carbon reporting mandate enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Slovakia Freight and Logistics Market
Logistics and Shipping
North America FMCG Logistics Market
Logistics and Shipping
United Kingdom Cold Chain Logistics Market
Logistics and Shipping
Asean Freight and Logistics Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
Netherlands Freight and Logistics Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
India E-Commerce Logistics Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Japan Dangerous Goods Logistics Market
Logistics and Shipping
GCC Dangerous Goods Logistics Market
Logistics and Shipping
Argentina Freight and Logistics Market
Logistics and Shipping
Ukraine Freight and Logistics Market
Logistics and Shipping
Outbound Logistics Market