
 Iraq Logistics Market | 2026-2036
Iraq Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Iraq Logistics Market Insights
CE marking alignment for cross-border freight equipment is realigning the cost-of-entry calculus for new logistics operators entering Iraq. Al Marasi International General Trading & Maritime Services Company leverages its maritime heritage to dominate port-to-inland corridors. Mateen Express sustains competitive density through its express distribution network across southern Iraq. Crown Logistics Ltd anchors its position through specialized oilfield supply chain contracts.
Iraq logistics encompasses the planning, execution, and control of goods movement across multimodal networks including road, rail, air, and maritime channels, typically operating with GPS-enabled fleet tracking and temperature-controlled warehousing for sensitive cargo. The sector's primary purpose is bridging production sites—particularly oilfields and construction zones—with consumption centers through efficient inventory flow management. Transportation services currently occupy the largest revenue pool given Iraq's road-dependent freight economy, while IoT Solutions represent the fastest-growing technology segment as operators deploy real-time cargo monitoring to reduce transit losses. Warehousing is maturing around Basra and Baghdad industrial zones where bonded storage facilities address customs clearance bottlenecks.
Iraq's General Company for Ports of Iraq and the country's national customs authority enforce import documentation and vessel safety standards that shape market access for international freight forwarders. The central bank's trade finance regulations influence payment settlement timelines for cross-border logistics contracts. Stakeholders must monitor how customs digitization and port automation investments reshape operational requirements for third-party logistics providers serving Iraq's reconstruction and energy sectors.
Market Dynamics
Customs digitization and port automation investments are compressing clearance timelines and forcing third-party logistics providers to retool their operational architectures around real-time data exchange with Iraq's national customs authority.
Growth Catalysts
- Basra Port Expansion:Deep-water berth upgrades and container terminal automation are expanding vessel handling capacity and attracting direct calls from mainline shipping operators previously transshipping through Jebel Ali.
- Oilfield Supply Chain Demands:Exploration activity in southern Iraq's supergiant fields is generating specialized freight requirements for heavy-lift equipment and just-in-time drilling consumables.
- CE Marking Alignment:Equipment certification harmonization with European standards is reducing technical barriers for cross-border fleet procurement and trailer interoperability.
Market Restraints
- Fuel Price Volatility:Diesel cost swings directly compress margins for road-dominant freight operators who cannot pass through surcharges on fixed government contracts.
- Single-Point Port Dependency:Umm Qasr handles over 80% of containerized imports, creating congestion vulnerability during customs system outages or labor disputes.
- Document Processing Friction:Iraq's national customs authority maintains paper-heavy inspection protocols that delay bonded warehouse releases despite digitization mandates.
Strategic Opportunities
- Northern Corridor Development:Kurdistan Region road rehabilitation and Turkish border crossing upgrades offer alternative routing for European-origin cargo avoiding Basra bottlenecks.
- Temperature-Controlled Pharma Distribution:Cold chain infrastructure gaps present first-mover potential for operators deploying GDP-compliant warehousing serving import-dependent healthcare procurement.
- IoT-Enabled Cargo Monitoring:Real-time GPS and environmental sensor convergence allows premium service tiering for high-value oilfield equipment and pharmaceutical shipments.
Industry Challenges
- Certified Fleet Technician Scarcity:Advanced diagnostics training for Euro-5 engine compliance and telematics maintenance outpaces vocational pipeline output.
- Warehouse Management System Integration:Legacy inventory platforms at state-owned enterprises resist API connectivity with modern third-party logistics dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iraq Logistics Market |
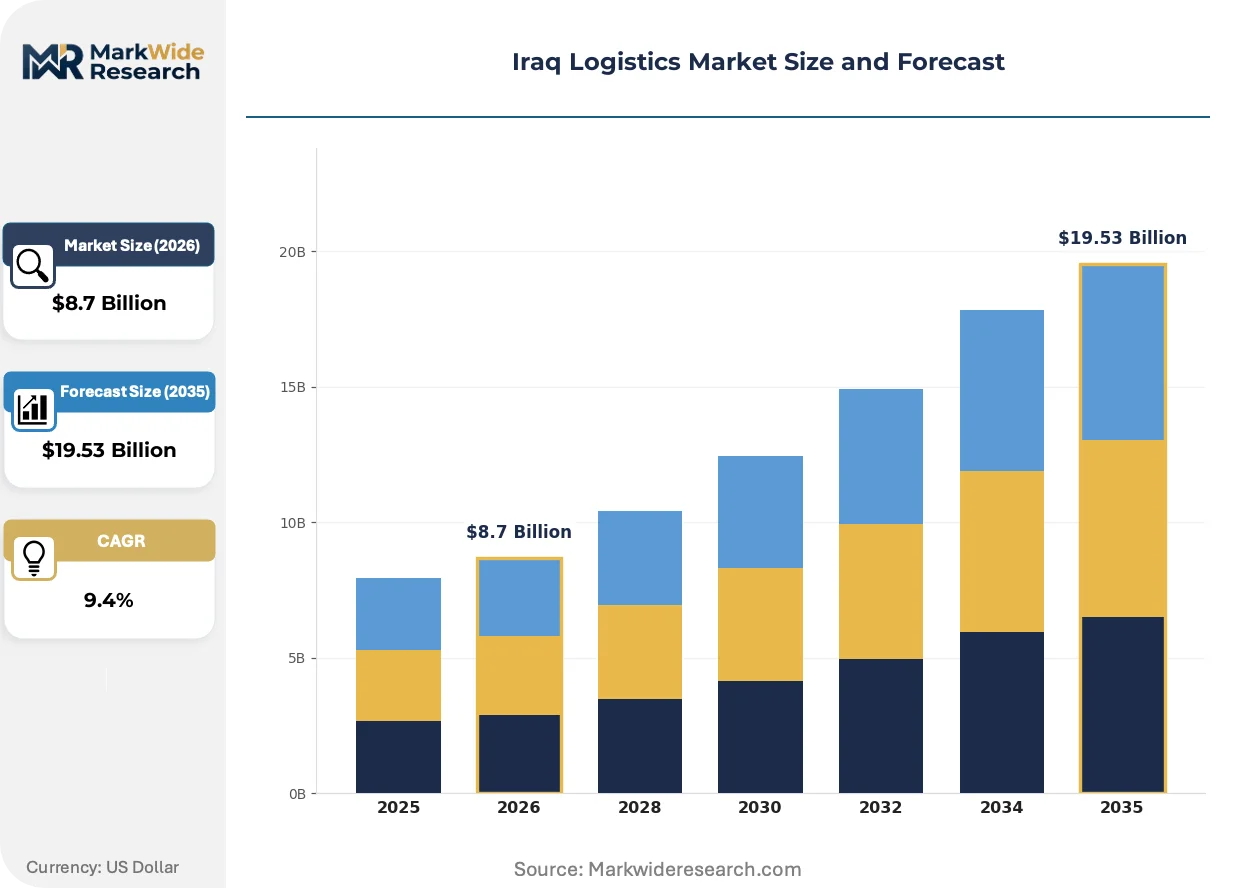
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Distribution End User: Oil & Gas, Construction, Retail, Manufacturing Technology: GPS Tracking, Fleet Management, Warehouse Management, IoT Solutions Distribution Channel: Direct Shipping, Third-Party Logistics, Rail Transport, Air Freight |
| Companies Covered | Al Marasi International General Trading & Maritime Services Company, Mateen Express, Crown Logistics Ltd, Almas Group Logistics, Daleel Al-Sahraa, Global Dynamix Ltd, AZKA Shipping & Logistics, PIRIS ROAD, Zarawa Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iraq Logistics Market Trends and Innovations
Telematics penetration and customs platform interoperability are compressing information asymmetries between shippers and carriers, while procurement departments at oil majors demand granular shipment visibility as a contract prerequisite.
GPS-enabled fleet tracking combined with predictive maintenance algorithms is rewriting how operators schedule preventive servicing and optimize load consolidation across multi-drop routes serving Baghdad industrial zones. Basra-based hauliers are deploying these systems fastest to meet oilfield contractor key performance indicators. The technology is compressing asset utilization gaps between integrated operators and fragmented owner-driver networks.
Iraq's customs authority is mandating advance cargo declaration through its national single window platform, forcing freight forwarders to restructure documentation workflows and pre-position data entry capacity at origin ports. This regulatory shift is accelerating pre-arrival clearance adoption among European and East Asian exporters. Smaller customs brokers lacking digital integration capabilities are losing contract renewals to technology-enabled competitors.
Long-term service agreements with embedded key performance indicator penalties are displacing spot-rate contracting for oil and gas logistics procurement. Integrated operators with captive warehousing and fleet assets are capturing multi-year awards that previously fragmented across transactional vendors. This behavioral shift is most pronounced in southern Iraq where international oil company procurement departments centralize supply chain governance.
Iraq Logistics Market Segmentation
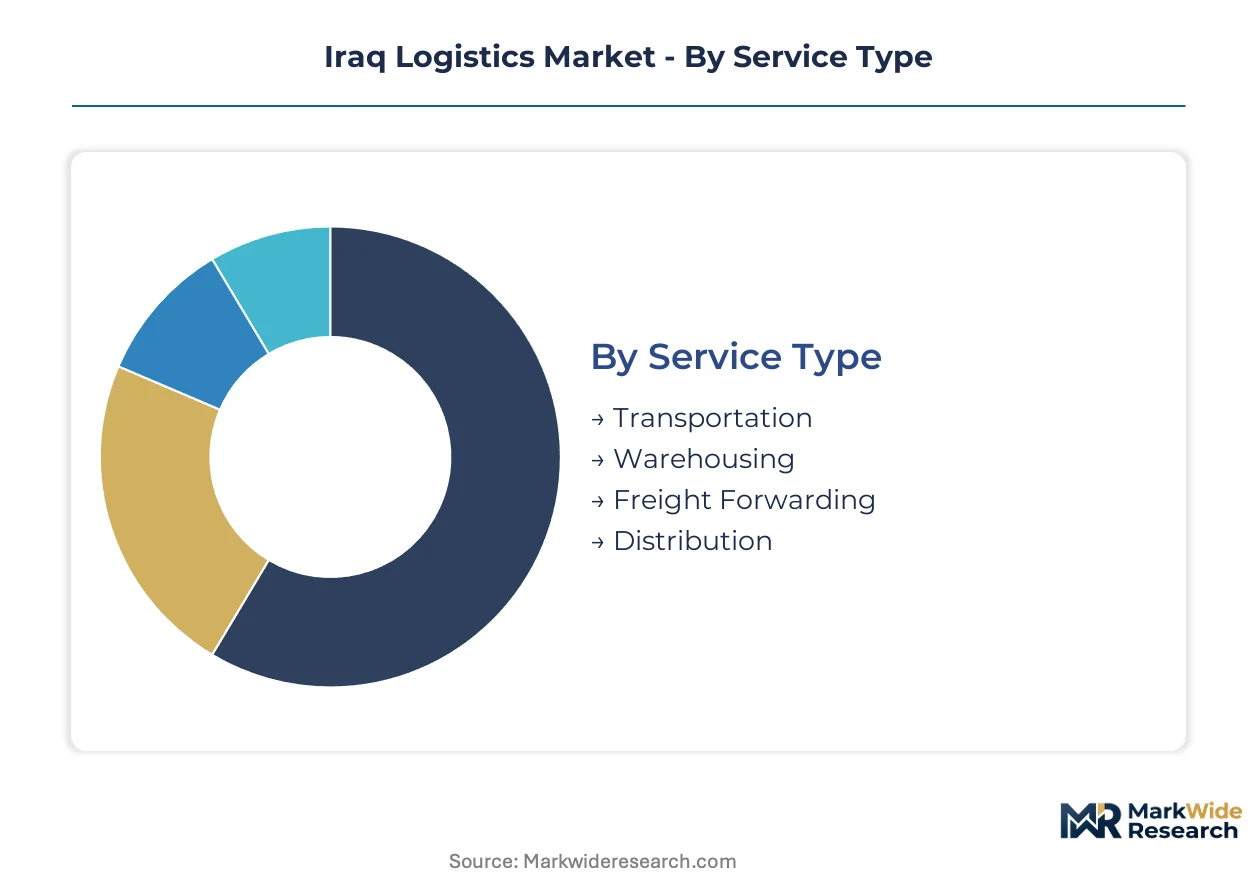
Logistics segmentation in Iraq reflects the country's reconstruction priorities and hydrocarbon dependency. Each service tier commands distinct capital commitments and regulatory exposure. Understanding these divides reveals where operational leverage concentrates.
Service Type:
Transportation and warehousing absorb the heaviest upfront investment, with fleet procurement and bonded facility construction requiring multi-year capital deployment.
- Transportation:Road haulage dominates with GPS-enabled fleet tracking now standard for cross-border and oilfield corridors. Diesel price volatility and customs checkpoint delays compress margins for operators serving Baghdad-Basra routes.
- Warehousing:Temperature-controlled facilities around Basra and Baghdad industrial zones address customs clearance bottlenecks through bonded storage. Construction costs for cold chain compliance run higher than ambient alternatives.
- Freight Forwarding:Customs digitization mandates from Iraq's national customs authority are forcing documentation workflow restructuring. Pre-arrival clearance adoption separates technology-enabled brokers from legacy competitors.
- Distribution:Express networks concentrate in southern Iraq where oilfield just-in-time demands sustain premium service tiers. Multi-drop route optimization remains underdeveloped outside integrated operator portfolios.
Most installed capacity flows through Transportation. Expansion is steepest in Warehousing as bonded facilities multiply around port zones.
End User:
Oil and gas procurement generates the highest contract values, with international oil company supply chain governance centralizing vendor selection.
- Oil & Gas:Supergiant field exploration in southern Iraq drives specialized heavy-lift requirements and drilling consumables logistics. Long-term service agreements with embedded key performance indicator penalties now displace spot-rate contracting.
- Construction:Reconstruction materials flow through Umm Qasr port, creating demand for project cargo handling and site delivery coordination. Cement and steel imports face seasonal surges that strain drayage capacity.
- Retail:Consumer goods distribution networks remain fragmented, with Baghdad retail clusters served by owner-driver networks lacking telematics integration. Modern trade format expansion is slowly consolidating procurement.
- Manufacturing:Industrial corridor development in Basra province generates inbound raw materials logistics, though local production scale remains limited. Factory-to-warehouse movements rely heavily on third-party fleet augmentation.
Procurement volume concentrates in Oil & Gas. Customer acquisition costs are climbing fastest in Construction as project timelines compress.
Technology:
Fleet management and warehouse management systems demand the steepest software integration investments, with legacy state-owned enterprise platforms resisting API connectivity.
- GPS Tracking:Real-time vehicle monitoring is now baseline for oilfield contractor compliance, with predictive maintenance algorithms optimizing preventive servicing schedules. Asset utilization gaps between integrated operators and fragmented networks are compressing.
- Fleet Management:Euro-5 engine diagnostics and telematics maintenance outpace vocational training pipeline output, creating certified technician scarcity. Advanced platforms consolidate load consolidation across multi-drop routes.
- Warehouse Management:Bonded facility operators require customs platform interoperability for real-time inventory visibility. Legacy inventory systems at state-owned enterprises create integration friction.
- IoT Solutions:Environmental sensors and GPS convergence enable premium service tiering for high-value cargo. This segment is expanding most quickly as operators deploy real-time cargo monitoring to reduce transit losses.
Deployment penetration runs deepest in GPS Tracking. Technology refresh cycles are accelerating fastest in IoT Solutions as sensor costs decline.
Distribution Channel:
Third-party logistics and rail transport require the most infrastructure coordination, with multimodal handoffs demanding systems integration.
- Direct Shipping:Mainline vessel operators are establishing direct calls at Basra following deep-water berth upgrades, bypassing previous Jebel Ali transshipment. Port-to-inland corridor control determines competitive positioning.
- Third-Party Logistics:Integrated operators with captive warehousing and fleet assets capture multi-year awards that previously fragmented. Customs digitization is forcing operational architecture retooling around real-time data exchange.
- Rail Transport:Network rehabilitation and Turkish border crossing upgrades offer alternative routing for European-origin cargo. Modal share remains limited by track condition variability.
- Air Freight:Pharmaceutical and oilfield emergency shipments sustain niche demand, with temperature-controlled pharma distribution presenting first-mover potential for GDP-compliant operators.
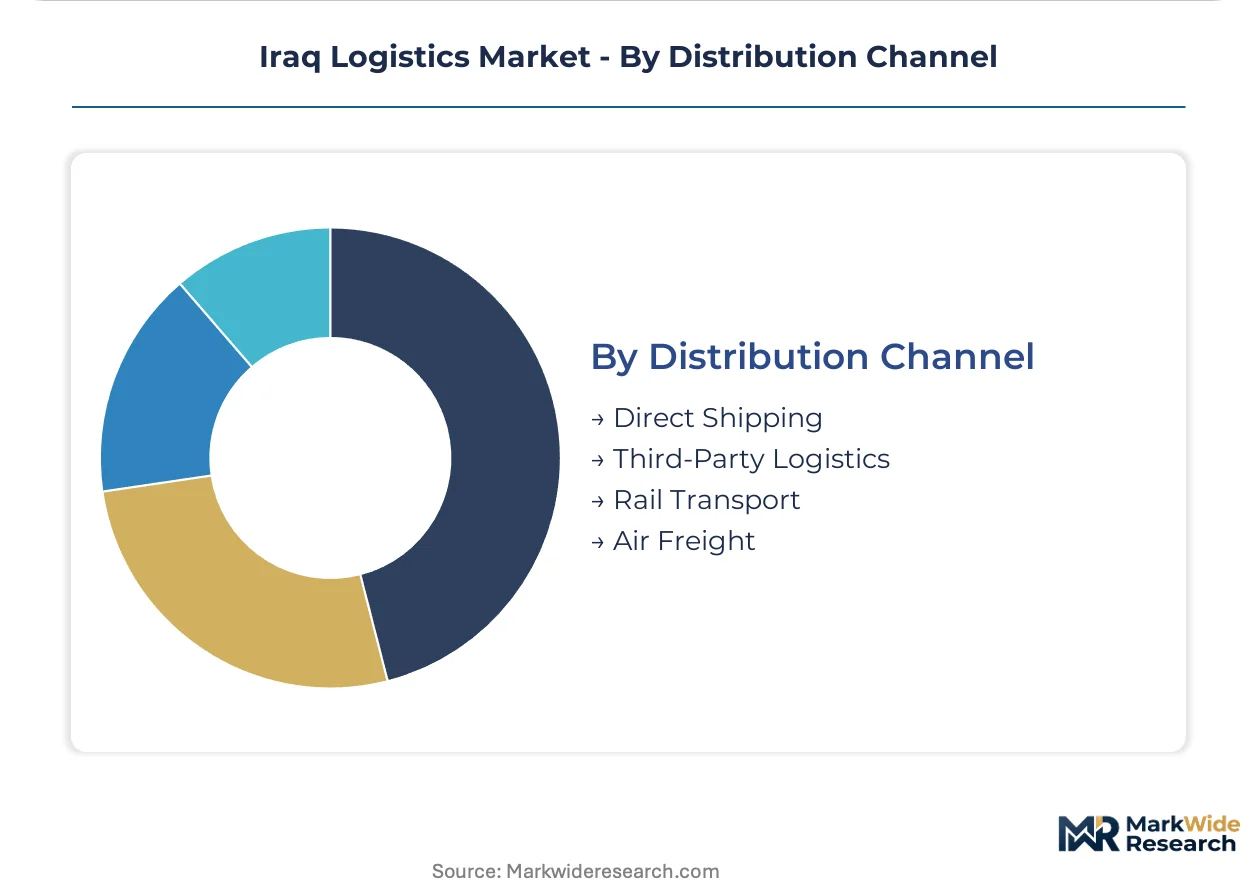
Freight volume concentrates in Third-Party Logistics. Infrastructure investment is flowing most heavily into Direct Shipping as port automation expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics talent and operational expertise concentrates around port cities and oilfield corridors, with workforce density highest in southern Iraq's maritime zones and Baghdad's distribution networks.
Basra Governorate
Umm Qasr port handles over 80% of containerized imports, driving demand for bonded warehousing and drayage operators. Iraq's General Company for Ports of Iraq enforces vessel safety standards and customs documentation requirements that shape third-party logistics licensing. Basra's industrial zones host temperature-controlled facilities serving oilfield supply chains and construction materials distribution.
Baghdad Governorate
Retail distribution networks and construction materials procurement sustain road haulage demand across the capital's industrial corridors. The central bank's trade finance regulations influence payment settlement timelines for cross-border logistics contracts serving Baghdad-based manufacturers. Sadr City and Taji industrial clusters concentrate last-mile delivery capacity for consumer goods.
Kurdistan Region
Road rehabilitation and Turkish border crossing upgrades offer alternative routing for European-origin cargo avoiding southern port bottlenecks. The Kurdistan Regional Government's infrastructure investment programs accelerate customs facility modernization at Ibrahim Khalil and Haji Omaran crossings. Erbil and Sulaymaniyah logistics parks serve pharmaceutical and electronics import distribution.
Dhi Qar Governorate
Supergiant oilfield exploration in the Gharraf and West Qurna fields generates specialized heavy-lift freight requirements and drilling consumables logistics. Ministry of Oil procurement regulations mandate just-in-time delivery performance standards for contractor eligibility. Nasiriyah serves as the operational hub for southern oilfield supply chain coordination.
Muthanna Governorate
Samawa's strategic position along the Baghdad-Basra highway corridor supports transshipment and cross-docking operations for construction materials. National customs authority digitization mandates are forcing documentation workflow restructuring among freight forwarders operating border-adjacent facilities. The governorate's warehousing capacity expands to capture overflow from congested Basra port zones.
Iraq Logistics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Iraq's logistics market, with integrated operators capturing multi-year oilfield contracts while fragmented owner-driver networks dominate retail distribution. Market structure shows moderate consolidation around port-to-inland corridor controllers and oilfield supply chain specialists. Three archetypes define competitive positioning: maritime heritage operators leveraging port access, express distribution network builders, and oilfield logistics contractors with specialized heavy-lift capabilities. Capacity expansion through bonded warehousing construction and fleet telematics deployment represent the dominant competitive moves.
Among maritime heritage operators, Al Marasi International General Trading & Maritime Services Company occupies a position exemplifying port-to-inland corridor control, while Mateen Express represents the express distribution archetype with network density across southern Iraq. Crown Logistics Ltd anchors the oilfield logistics specialist tier through its positioning around energy sector supply chain contracts. These three companies illustrate how competitive advantage in Iraq's logistics market derives from sector-specific operational focus rather than generalized service breadth.
| Leading Market Players |
|---|
| Al Marasi International General Trading & Maritime Services Company |
| Mateen Express |
| Crown Logistics Ltd |
| Almas Group Logistics |
| Daleel Al-Sahraa |
| Global Dynamix Ltd |
| AZKA Shipping & Logistics |
| PIRIS ROAD |
| Zarawa Logistics |
| Others |
Pricing and Supply Chain Analysis
Captive warehousing and fleet ownership among integrated operators anchors both supply position and pricing power in Iraq's logistics corridors. Oilfield contractors with multi-year service agreements leverage in-house assets to resist rate compression from fragmented owner-driver networks.
Pricing Analysis
Bundled service contracts combining transportation, warehousing, and customs clearance command premium positioning against unbundled spot-rate alternatives. Three-tier pricing structure across premium, standard, and economy levels separates oilfield just-in-time deliveries from construction materials haulage and retail distribution. Cost compression in the standard tier intensifies because diesel price volatility erodes margins on fixed government contracts. Retail distribution networks show highest price sensitivity, while oil and gas procurement departments prioritize performance guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Umm Qasr port, which handles over 80% of containerized imports. Equipment and spare parts draw from China, Turkey, and the UAE. Euro-5 engine diagnostics and telematics hardware face certified technician scarcity. Tariff exposure runs through customs digitization mandates requiring pre-arrival clearance infrastructure. Distribution runs through third-party logistics operators with bonded warehousing at port zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iraq's logistics market functions as a geographic-arbitrage play where operators exploit cost differentials between congested southern port corridors and emerging northern border crossings with Turkey.
For Market Incumbents: To counter customs digitization mandates from Iraq's national customs authority, deepen API connectivity with state-owned enterprise legacy platforms and expand bonded warehousing capacity around Basra industrial zones. Channel control through port-to-inland corridor dominance remains the priority defensive lever. For New Entrants and Emerging Players: CE marking alignment in Iraq opens a window for European equipment suppliers to capture fleet procurement contracts previously blocked by technical barriers. Temperature-controlled pharma distribution presents the most penetrable white-space target, with GDP-compliant warehousing as the specific go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for fragmented owner-driver networks because oil and gas procurement centralization is displacing spot-rate contracting. Long-term viability centers on operators with captive fleet and warehousing assets. The signal to watch is international oil company supply chain governance mandates requiring granular shipment visibility.| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Warehousing Expansion | Addresses customs clearance bottlenecks at Umm Qasr port for oilfield supply chains. |
| Fleet Telematics Deployment | Meets international oil company key performance indicator requirements for shipment visibility. |
| Cold Chain Infrastructure Buildout | Captures first-mover advantage in GDP-compliant pharmaceutical distribution. |
| Customs Platform Integration | Enables pre-arrival clearance adoption mandated by Iraq's national customs authority. |
| Northern Corridor Development | Exploits Turkish border crossing upgrades for European-origin cargo routing. |
Research Methodology
Multiple input streams — primary interviews with logistics operators, customs brokers, and oilfield procurement managers; secondary validation through customs authority documentation, port authority statistics, and trade finance regulations; plus fleet telematics deployment records — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from industry participants to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include service type, end-use sector, technology deployment, and regional corridor configuration. CAGRs were derived from demand elasticity analysis against oilfield exploration activity and reconstruction materials import flows.
Revisions become necessary when customs digitization timelines slip, port automation investments stall, or fuel subsidy regimes shift materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Asia-Pacific Courier Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
Spain Pharmaceutical Logistics Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
LAOS Freight and Logistics Market
Logistics and Shipping
China Third-Party Logistics (3PL) Market
Logistics and Shipping
Dry Van Container Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
Delivery Tracking Platform Market
Logistics and Shipping
Vietnam Freight and Logistics Market
Logistics and Shipping
Digital Freight Forwarder Market
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
Chile Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
France Parcel Market