
 Russia Freight and Logistics Market | 2026-2036
Russia Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Freight and Logistics Market Analytics
Modular service bundling is repositioning buyer choice in Russian logistics, as shippers unbundle single-provider contracts into specialized rail, road, and warehousing combinations. RZD Logistics leverages its rail network dominance to anchor long-haul freight movements across the Eurasian corridor. Delovye Linii competes through dense last-mile road coverage and flexible pickup scheduling. FESCO Transportation Group specializes in intermodal sea-rail solutions, particularly for container flows through Far Eastern ports.
Russia freight and logistics encompasses the planning, execution, and control of goods movement via rail, road, sea, and air modes, typically operating across distances exceeding 9,000 kilometers between European and Asian gateways with transit times ranging from 7 to 21 days depending on corridor and customs processing. Its primary commercial purpose is to bridge production centers with consumption markets while managing inventory costs and delivery reliability. Rail freight retains structural leadership in bulk and container volumes, supported by the Trans-Siberian and Baikal-Amur Mainline networks. Third-party logistics is expanding fastest as manufacturers outsource fleet and warehouse management to reduce capital intensity. Warehousing margins concentrate around temperature-controlled facilities serving food and pharmaceutical supply chains.
Russia's Federal Customs Service and the Ministry of Transport shape market access through tariff regulations and infrastructure investment priorities, while the Eurasian Economic Union's unified customs code simplifies cross-border documentation for member-state freight flows. The country's technical regulations on vehicle emissions and rail safety standards directly influence fleet renewal cycles and terminal equipment procurement. Stakeholders must monitor how sanctions-related trade route adjustments reshape corridor economics and carrier viability.
Market Dynamics
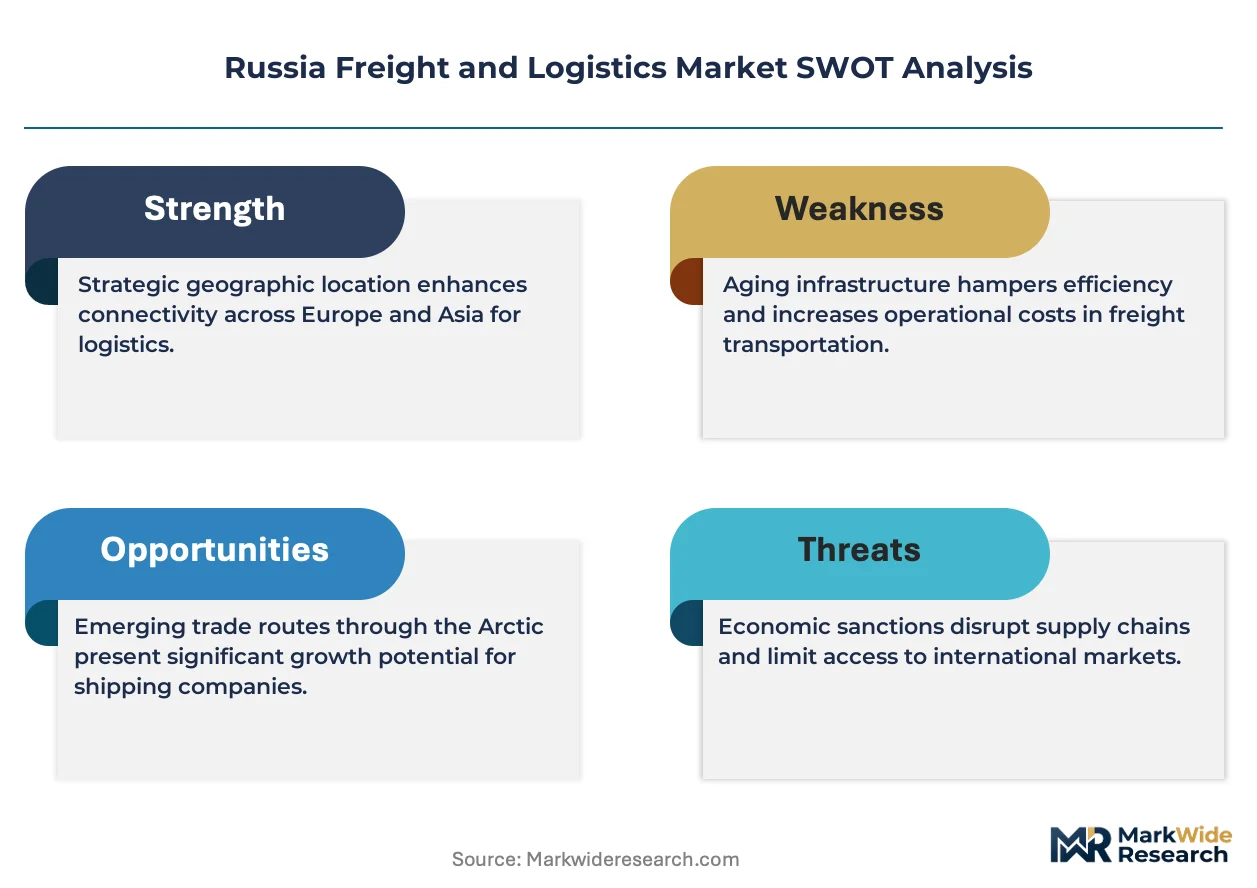
Russia's freight and logistics sector is experiencing a fundamental restructuring as Western sanctions redirect cargo flows toward Eastern corridors, forcing carriers to rebuild networks around Chinese and Indian trade gateways while abandoning traditional European routing patterns.
Growth Catalysts
- Eastern Pivot Infrastructure:The Baikal-Amur Mainline expansion and Far Eastern port capacity upgrades are creating dedicated corridors for China-bound container traffic, reducing reliance on European gateways.
- Import Substitution Mandates:Russia's Ministry of Transport localization requirements for fleet and equipment procurement are stimulating domestic manufacturing of rail wagons and refrigerated trucks.
- Digital Customs Integration:The Eurasian Economic Union's unified electronic declaration system is compressing border clearance times at Kazakhstan and Belarus transit points.
Market Restraints
- Spare Parts Scarcity:European and American OEMs have suspended component shipments, forcing fleet operators to cannibalize existing vehicles or source lower-grade alternatives from Chinese suppliers.
- Corridor Concentration Risk:Over 60 percent of reoriented container volume now funnels through three Far Eastern ports, creating chokepoint vulnerability during ice season.
- SWIFT Disconnection Friction:Cross-border payment processing delays through alternative settlement systems are extending carrier working capital cycles by two to three weeks.
Strategic Opportunities
- Arctic Northern Sea Route:Year-round navigation trials and icebreaker fleet expansion are positioning this corridor as a viable Asia-Europe alternative for time-sensitive electronics and automotive components.
- Pharmaceutical Cold Chain:Temperature-controlled warehouse capacity in the Moscow region remains underdeveloped relative to biologics distribution requirements, creating build-to-suit development potential.
- Rail-Sea Intermodal Convergence:Integration of block train scheduling with Vladivostok and Nakhodka port automation is enabling seven-day transit guarantees to Central Asian destinations.
Industry Challenges
- Telematics Integration Deficits:Fleet operators struggle to harmonize legacy Soviet-era rail signaling with modern GPS tracking and predictive maintenance platforms.
- Certification Bottlenecks:Eurasian Economic Union technical regulations for vehicle emissions and safety equipment are undergoing phased implementation, creating compliance timeline uncertainty for importers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Freight and Logistics Market |
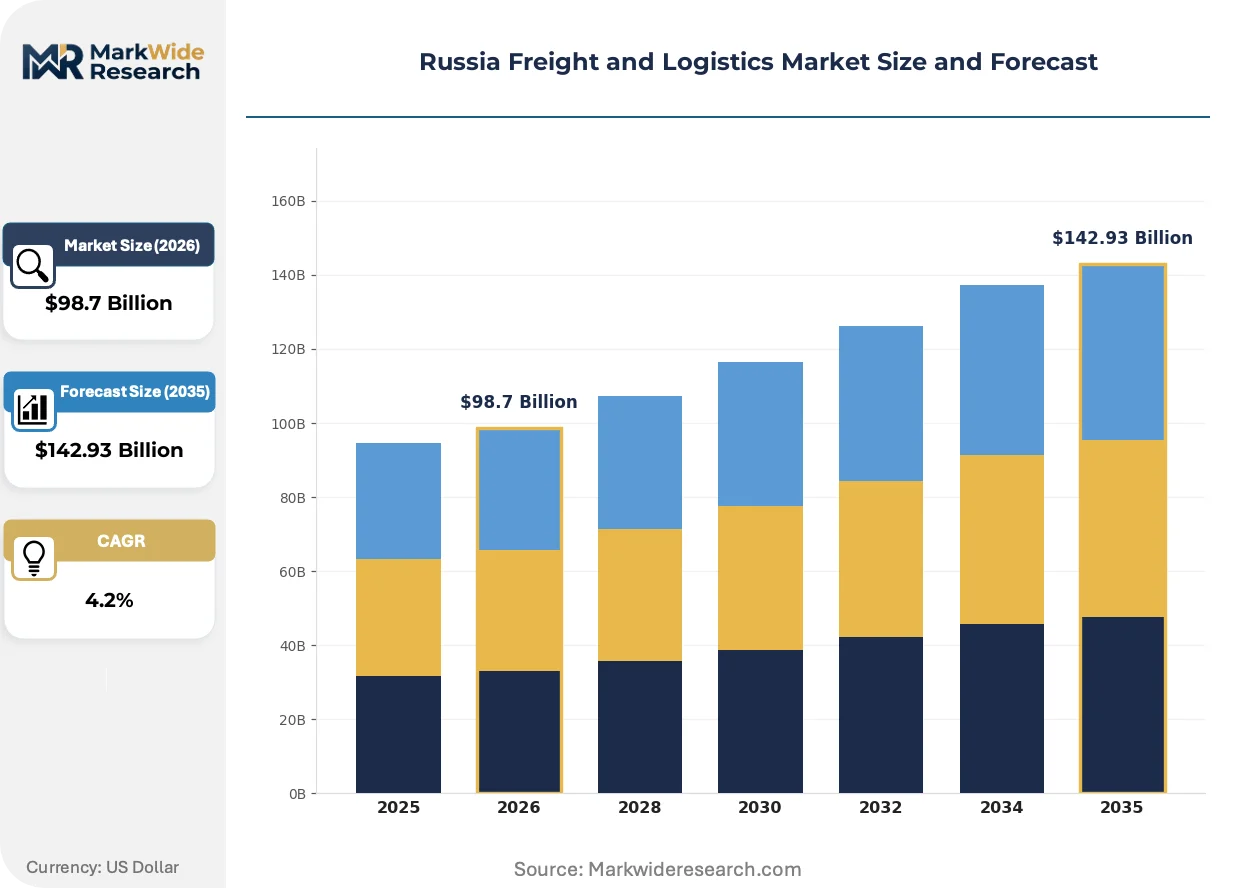
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $142.93 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Modal Type: Rail, Road, Sea, Air Service Type: Third-Party Logistics, Freight Forwarding, Transportation Management, Warehousing Customer Segment: Manufacturing, Retail, E-Commerce, Government Technology: Telematics, Automation, RFID, Blockchain |
| Companies Covered | Globaltrans Investment, Delovye Linii, FESCO Transportation Group, RZD Logistics, Kuehne + Nagel, DB Schenker, DHL, CDEK, Delo Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Freight and Logistics Market Evolving Landscape
Digital platform adoption is compressing traditional brokerage layers as shippers gain direct access to carrier capacity through automated matching systems, while infrastructure investment prioritizes corridor redundancy over point-to-point speed optimization.
Blockchain-based cargo documentation is unifying customs declarations, bills of lading, and insurance certificates into single-source digital twins. Large agricultural exporters and automotive assemblers in the Tatarstan and Samara regions are piloting these systems to reduce documentary fraud exposure. The technology is unifying previously fragmented compliance workflows across rail, road, and port handoffs, eliminating redundant inspection stops.
Russia's Federal Customs Service has mandated phased implementation of electronic veterinary and phytosanitary certificates for all food and agricultural imports, effective across Eurasian Economic Union member states. This regulatory shift is accelerating terminal operator investment in automated inspection lanes and laboratory co-location facilities. Perishable importers through Belarusian and Kazakh border points are consolidating volumes to amortize new compliance infrastructure costs.
Consolidation among mid-sized shippers is altering tendering behavior as procurement departments abandon annual rate contracts in favor of quarterly mini-bids indexed to fuel and foreign exchange volatility. Food retailers and construction material distributors in the Urals Federal District are driving this transition, substituting long-term carrier relationships with platform-mediated spot market access. This pattern is most visible in Yekaterinburg and Chelyabinsk, where regional distribution center construction has outpaced dedicated fleet investment.
Russia Freight and Logistics Market Segmentation
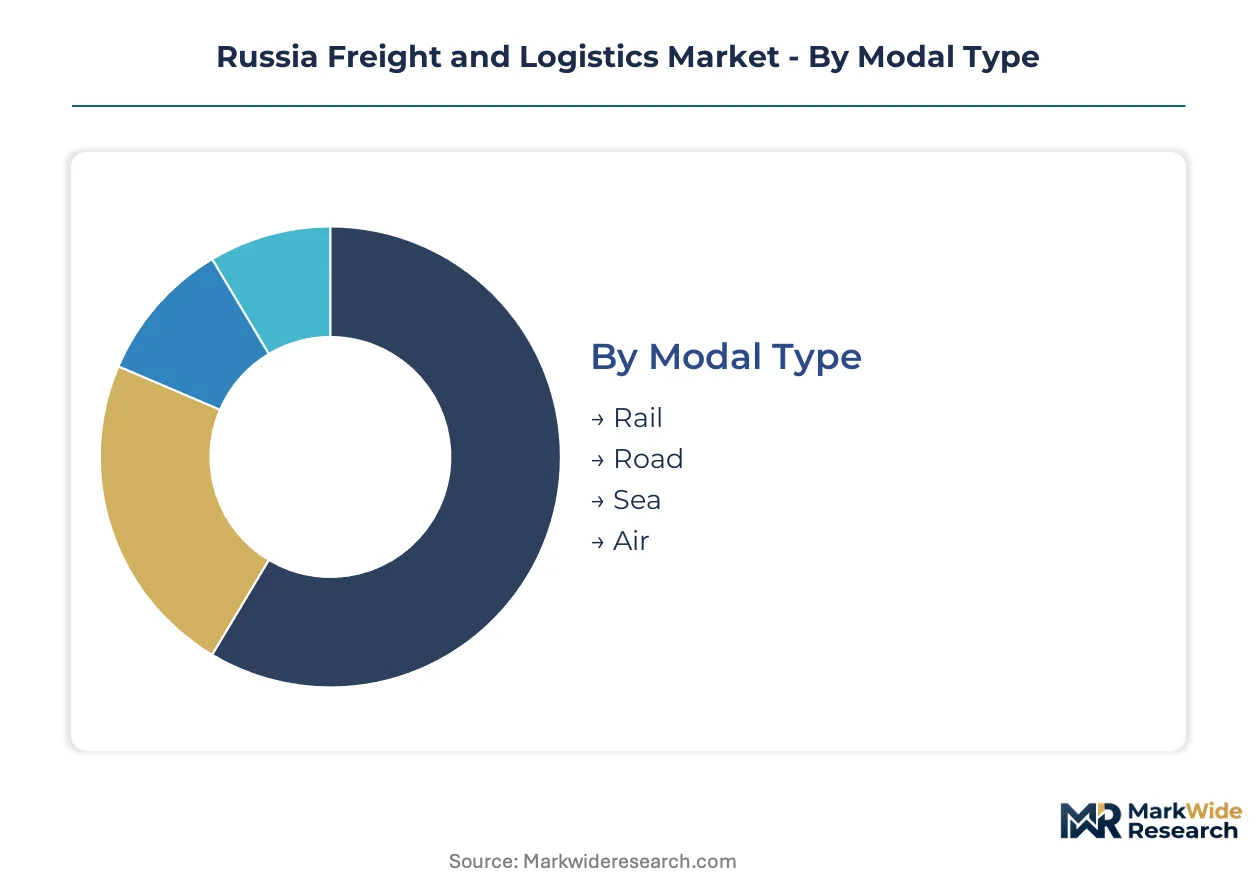
Russia's freight and logistics market fragments across modal capabilities, service sophistication, and customer verticals. Understanding these divisions reveals where infrastructure investment concentrates and which carrier strategies align with specific cargo requirements.
Modal Type:
Rail infrastructure replacement cycles and corridor modernization are redistributing modal share across Russia's vast territory.
- Rail:The Trans-Siberian and Baikal-Amur Mainline networks handle bulk commodities and containerized freight across distances exceeding 9,000 kilometers. RZD Logistics anchors this segment through dedicated block trains serving Far Eastern ports, with demand concentrating around coal, metals, and China-bound container flows.
- Road:Flexible routing and last-mile penetration dominate short-haul and regional distribution, particularly for perishables and construction materials. Fleet operators in the Central Federal District face acute pressure from European OEM spare parts embargoes, accelerating Chinese truck import substitution.
- Sea:Far Eastern ports including Vladivostok, Nakhodka, and Vostochny absorb redirected container volumes formerly routed through European gateways. Ice-class vessel requirements and seasonal navigation windows constrain year-round utilization.
- Air:Time-critical electronics, pharmaceuticals, and automotive components move through Moscow's Sheremetyevo and Domodedovo hubs. Capacity constraints and payment processing friction through alternative settlement systems limit expansion.
Rail sits at the top of the volume ranking, with road climbing the fastest as e-commerce fulfillment demands flexible last-mile capabilities.
Service Type:
Customer procurement patterns are shifting from bundled annual contracts toward modular service combinations indexed to freight volatility.
- Third-Party Logistics:Outsourced fleet and warehouse management reduces capital intensity for manufacturers. Food retailers in the Urals Federal District and automotive assemblers in Tatarstan drive demand for integrated inventory and distribution control.
- Freight Forwarding:Customs brokerage and multimodal coordination services navigate Eurasian Economic Union documentation requirements. Digital platform adoption compresses traditional brokerage margins as shippers access carrier capacity directly.
- Transportation Management:Route optimization and carrier selection software penetrates mid-sized shippers consolidating procurement through quarterly mini-bids. Yekaterinburg and Chelyabinsk distribution centers deploy these systems to amortize volatile fuel and foreign exchange exposure.
- Warehousing:Temperature-controlled facilities serving pharmaceutical and food supply chains command premium margins. Moscow region cold storage remains underdeveloped relative to biologics distribution requirements, creating build-to-suit development potential.
Third-party logistics holds the largest revenue share, though warehousing is gaining share fastest as pharmaceutical cold chain requirements intensify.
Customer Segment:
End-use demand concentration determines corridor investment priority and service level differentiation across Russia's logistics networks.
- Manufacturing:Automotive assemblers in Samara and Tatarstan, plus metals producers in the Urals, generate bulk rail and containerized freight flows. Import substitution mandates redirect component sourcing toward Chinese and Indian suppliers, altering inbound logistics patterns.
- Retail:Food and construction material distributors in the Central and Urals Federal Districts drive regional distribution center expansion. Consolidation among mid-sized retailers shifts tendering from annual contracts toward platform-mediated spot market access.
- E-Commerce:Cross-border parcel volumes and domestic fulfillment networks expand across the Moscow–St. Petersburg corridor. Same-day and next-day delivery promises strain last-mile road capacity in metropolitan zones.
- Government:Defense, emergency supply, and infrastructure project logistics operate through prioritized rail and air corridors. Federal transport infrastructure modernization programs redirect public investment toward Eastern pivot corridors.
Manufacturing anchors volume throughput, while e-commerce is expanding most quickly as consumer delivery expectations tighten.
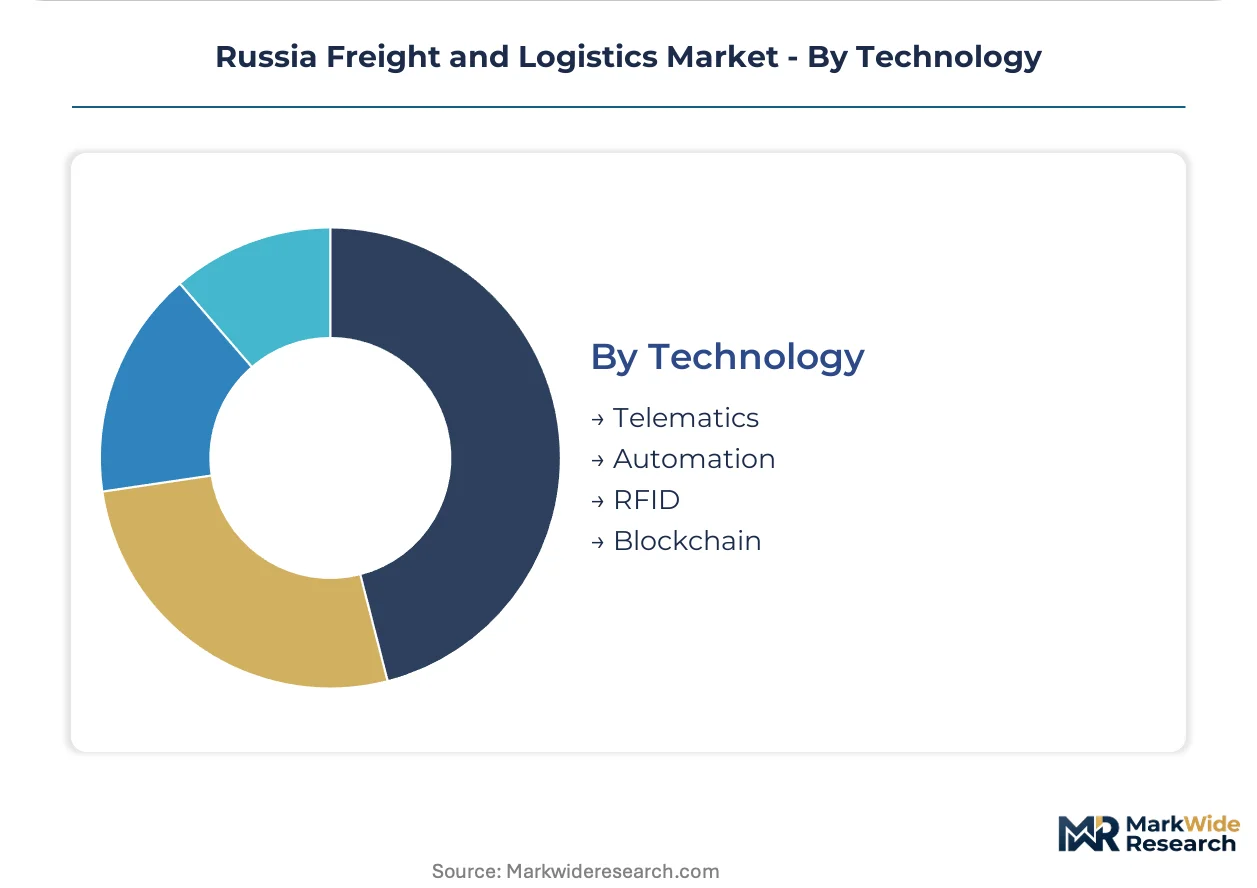
Technology:
Digital adoption maturity varies sharply between legacy Soviet-era infrastructure and modern integrated platforms.
- Telematics:GPS tracking and predictive maintenance platforms struggle to harmonize with legacy rail signaling systems. Fleet operators cannibalize existing vehicles for components or source lower-grade Chinese alternatives, degrading data reliability.
- Automation:Port terminal automation at Vladivostok and Nakhodka enables seven-day transit guarantees to Central Asian destinations. Automated inspection lanes and laboratory co-location facilities respond to electronic veterinary and phytosanitary certificate mandates.
- RFID:Cargo identification and inventory tracking penetrates warehousing and cross-dock operations. Perishable importers through Belarusian and Kazakh border points consolidate volumes to amortize compliance infrastructure costs.
- Blockchain:Unified digital twins combining customs declarations, bills of lading, and insurance certificates reduce documentary fraud exposure. Large agricultural exporters pilot these systems across fragmented rail-road-port handoff workflows.
Telematics dominates current deployment, with blockchain showing the steepest expansion trajectory as customs integration requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's freight infrastructure originated along the Trans-Siberian Railway corridor in the late 19th century, establishing the geographic spine that still channels east-west cargo flows today. Modern investment patterns follow this historical alignment while pivoting capacity toward eastern gateways.
Moscow Region
Automotive assemblers and pharmaceutical distributors generate concentrated demand for temperature-controlled warehousing and just-in-time rail delivery. The Ministry of Transport's logistics park development program subsidizes multimodal terminal construction in the capital periphery. Domodedovo and Sheremetyevo airports anchor time-critical air freight for electronics and biologics, though payment processing friction constrains capacity expansion.
St. Petersburg
Container traffic through the Baltic Sea gateway has contracted sharply as European trade routes atrophy under sanctions pressure. The Federal Customs Service maintains specialized clearance facilities for project cargo and heavy machinery at Ust-Luga port. Industrial clusters in the Leningrad Oblast redirect inbound component flows toward Chinese and Indian supplier bases, altering traditional sourcing logistics.
Far Eastern Federal District
Vladivostok, Nakhodka, and Vostochny ports absorb redirected container volumes exceeding prior design capacity, creating seasonal chokepoints during ice formation. The government's Eastern Polygon infrastructure program channels investment toward Baikal-Amur Mainline expansion and port automation. Khabarovsk Krai distribution centers consolidate volumes for Central Asian re-export markets.
Urals Federal District
Metals producers and machinery manufacturers in Yekaterinburg and Chelyabinsk generate bulk rail freight and specialized heavy-lift requirements. Regional retailers drive construction of distribution centers with platform-mediated procurement replacing annual carrier contracts. The Eurasian Economic Union's unified customs code compresses transit times through Kazakh border points for westbound cargo.
Siberian Federal District
Coal and mineral exporters along the Trans-Siberian corridor maintain steady rail volume despite Western market access constraints. Novosibirsk serves as a consolidation hub for agricultural shipments from Altai Krai and Kemerovo Oblast. Temperature-controlled warehousing investment lags behind food processing expansion, creating capacity bottlenecks for dairy and meat distribution.
Russia Freight and Logistics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service integration depth, with specialized temperature-controlled and multimodal offerings commanding pricing power over standard trucking. State-affiliated rail operators and privately held road carriers divide the market along modal lines, while international forwarders retrench to advisory roles. Three archetypes dominate: rail-network incumbents with infrastructure control, flexible road operators with dense last-mile coverage, and intermodal specialists bridging sea-rail handoffs. Competitive dynamics center on corridor-specific capacity expansion and digital platform deployment to bypass traditional brokerage layers.
Within the rail-dominant tier, RZD Logistics and Globaltrans Investment occupy positions anchored to Trans-Siberian and Baikal-Amur network control. Among diversified intermodal operators, FESCO Transportation Group and Delo Group exemplify strategies converging Far Eastern port access with block train scheduling. The road freight segment features Delovye Linii as a representative of flexible pickup scheduling and dense regional coverage models. These named entities serve as structural anchors for understanding how modal specialization and geographic footprint determine competitive positioning.
| Leading Market Players |
|---|
| Globaltrans Investment |
| Delovye Linii |
| FESCO Transportation Group |
| RZD Logistics |
| Kuehne + Nagel |
| DB Schenker |
| DHL |
| CDEK |
| Delo Group |
| Others |
Value Network & Pricing Analysis
Blockchain-based cargo documentation adoption across Russian customs corridors is compressing brokerage margins while concentrating pricing power among carriers with integrated digital platforms. This technology shift simultaneously lowers transaction costs for compliant operators and raises barriers for legacy freight forwarders lacking Eurasian Economic Union certification integration.
Pricing Analysis
Contract-based long-term offtake agreements dominate bulk rail freight, while spot-market platform access governs fragmented road segments. Price differentiation rests on temperature-controlled certification grade and corridor-specific delivery reliability, with pharmaceutical cold chain operators commanding substantial premiums over standard container movements. Pricing pressure stems from European OEM spare parts embargoes degrading fleet utilization rates. Small regional distributors exhibit acute price sensitivity, whereas automotive assemblers in Tatarstan prioritize transit-time guarantees over rate minimization.
Supply Chain Analysis
Eurasian Economic Union technical regulations for rail safety equipment and vehicle emissions certification are gating market access for foreign component suppliers. Domestic manufacturing draws from Chinese steel inputs, Indian automotive parts, and domestic rail wagon production. Supply chain risk centers on single-source vulnerability for ice-class vessel components through Far Eastern ports. Distribution runs through RZD Logistics-controlled rail terminals, Delovye Linii regional hubs, and FESCO-managed port-rail intermodal facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's freight and logistics sector offers margin expansion through digital platform deployment and premium cold chain tier development, with cost compression from import substitution in rolling stock manufacturing enabling reinvestment.
For Market Incumbents: Acquire temperature-controlled warehousing assets in the Moscow region to capture pharmaceutical biologics distribution premiums. Defend against platform-mediated spot market encroachment by integrating predictive maintenance telematics with RZD Logistics block train scheduling. Invest in Baikal-Amur Mainline capacity additions to secure China-bound container corridor control. For New Entrants and Emerging Players: Begin with underdeveloped pharmaceutical cold storage build-to-suit development in Novosibirsk and Yekaterinburg, where regional biologics processing expansion outpaces logistics infrastructure. Target mid-sized food retailers in the Urals Federal District with platform-based quarterly procurement mini-bids indexed to fuel volatility. Establish go-to-market presence through Eurasian Economic Union customs brokerage automation partnerships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional road carriers lacking digital platform integration but holding dense last-mile coverage in Siberian Federal District population centers. Long-term viability favors operators with captive rail terminal access or Arctic Northern Sea Route ice-class capabilities. Monitor Far Eastern port automation completion rates as the inflection signal for intermodal margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | Automated carrier-shipper matching compresses traditional brokerage layers across Moscow-St. Petersburg corridor. |
| Cold Chain Capacity Expansion | Temperature-controlled warehousing investment captures pharmaceutical distribution premiums in underdeveloped Moscow periphery. |
| Eastern Corridor Infrastructure | Baikal-Amur Mainline expansion secures dedicated China-bound container routing away from European gateways. |
| Import Substitution Manufacturing | Domestic rail wagon and refrigerated truck production reduces European OEM spare parts dependency. |
| Arctic Shipping Route Development | Icebreaker fleet expansion positions Northern Sea Route as viable Asia-Europe alternative for time-sensitive cargo. |
Research Methodology
Direct dialogue with RZD Logistics operations executives, Delovye Linii regional managers, freight forwarders at Vladivostok port, pharmaceutical distribution procurement leads, and Eurasian Economic Union customs officials grounded qualitative assessment. Secondary validation drew from Federal Customs Service electronic declaration statistics, Ministry of Transport infrastructure investment disclosures, Trans-Siberian Railway volume reports, and container terminal operator filings. Bottom-up carrier capacity modeling and top-down trade flow analysis provided triangulation.
Modal share projections and service-type revenue distributions across the analysis window reflect segment-specific demand elasticity and infrastructure investment lag structures. Segmentation dimensions encompassed rail-road-sea-air modal type, third-party logistics versus freight forwarding service tier, manufacturing-retail-e-commerce customer vertical, and telematics-automation-blockchain technology adoption stage. CAGRs derived from corridor-specific volume trends indexed to Eastern pivot trade reorientation and import substitution manufacturing localization.
Several conditions sit outside the modeled scope, including sanctions regime modifications affecting payment system access, unforeseen Arctic ice formation patterns disrupting seasonal navigation, and abrupt Eurasian Economic Union technical regulation phase-in schedule changes. Forecasts reflect assumptions regarding sustained Eastern trade corridor investment prioritization and gradual digital customs integration. A model refresh is warranted upon material change in Federal Transport Infrastructure Modernization Program funding allocation or Far Eastern port capacity utilization thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
Estonia Freight and Logistics Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
Empty Container Repositioning Optimization Platforms Market
Logistics and Shipping
ASEAN Domestic Courier Market
Logistics and Shipping
Tank Container Shipping Market
Logistics and Shipping
Saudi Arabia Third-Party Logistics (3PL) Market
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Shipping Supplies Market
Logistics and Shipping
Smart Container Market
Logistics and Shipping
GCC Air Freight and Logistics Market
Logistics and Shipping
Ukraine Freight and Logistics Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
Europe Courier, Express and Parcel (CEP) Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Multicarrier Shipping Software Market