
 Chile Third-Party Logistics (3PL) Market | 2026-2036
Chile Third-Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Third-Party Logistics (3PL) Market Outlook
Mining supply chains is decoupling from captive logistics models toward outsourced transportation and warehousing arrangements. Deutsche Post DHL leverages its air freight dominance to serve copper concentrate exporters moving through Santiago and Antofagasta. Kuehne + Nagel anchors its Chilean presence on temperature-controlled pharmaceutical corridors linking the Biobío manufacturing belt to Pacific ports. Andes Logistics specializes in last-mile distribution for retail clients across the congested Santiago urban core.
Third-party logistics encompasses the outsourcing of supply chain execution—including freight forwarding, inventory storage, order fulfillment, and distribution coordination—to external providers operating under service-level agreements. Warehouse Management Systems coordinate real-time inventory tracking across multi-client facilities, while Transport Management Systems optimize route planning for Chile's elongated north-south geography. Fulfillment services capture expanding margin pools as e-commerce penetration deepens in Santiago and Valparaíso, though standard delivery remains the volume base for bulk agricultural and mining inputs. IoT Solutions represent the fastest-growing technology segment, driven by cold-chain monitoring requirements for salmon and fruit exports through Puerto Montt and San Antonio.
Chile's National Customs Service enforces advanced manifest regulations that shape clearance speed and documentation standards for cross-border 3PL operators. The Ministry of Transport and Telecommunications governs trucking weight limits and driver hour rules that directly constrain fleet utilization rates across the Atacama-to-Los Lagos corridor. Stakeholders must monitor whether proposed amendments to port concession laws alter competitive access for logistics providers serving Valparaíso and San Antonio container terminals.
Market Dynamics
Chile's mining sector is dismantling decades-old captive logistics infrastructure, forcing specialized 3PL operators to build dedicated copper concentrate handling capabilities across the Atacama-to-Antofagasta corridor.
Growth Catalysts
- Customs digitization:The National Customs Service's advanced manifest regulations compress border-clearance cycles, enabling faster inventory turns for cross-border freight operators.
- Cold-chain export surge:Salmon and fruit exporters through Puerto Montt and San Antonio drive demand for temperature-controlled warehousing and IoT-enabled monitoring systems.
- E-commerce fulfillment expansion:Santiago's urban density creates last-mile specialization opportunities as online retail penetration deepens in the Metropolitan Region.
Market Restraints
- Fuel price volatility:Diesel cost swings directly compress trucking margins across Chile's 4,300-kilometer north-south freight corridor.
- Port access concentration:Container terminal concessions at Valparaíso and San Antonio limit competitive entry for new logistics providers.
- Driver hour regulations:Ministry of Transport and Telecommunications enforcement of rest-period rules constrains fleet utilization rates.
Strategic Opportunities
- Biobío pharmaceutical corridor:Temperature-controlled distribution linking manufacturing clusters to Pacific ports remains underdeveloped relative to Santiago-centric infrastructure.
- IoT-warehouse convergence:Cold-chain sensor networks integrated with Warehouse Management Systems create service differentiation for perishable exporters.
- Los Lagos regional expansion:Salmon processing centers around Puerto Montt lack sufficient specialized 3PL capacity relative to export volume growth.
Industry Challenges
- Warehouse management system integration:Legacy inventory platforms at agricultural cooperatives resist real-time data exchange with multi-client 3PL facilities.
- Specialized cold-chain technician scarcity:Refrigeration mechanics and temperature-controlled logistics coordinators face acute supply constraints in regional Chilean labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Third-Party Logistics (3PL) Market |
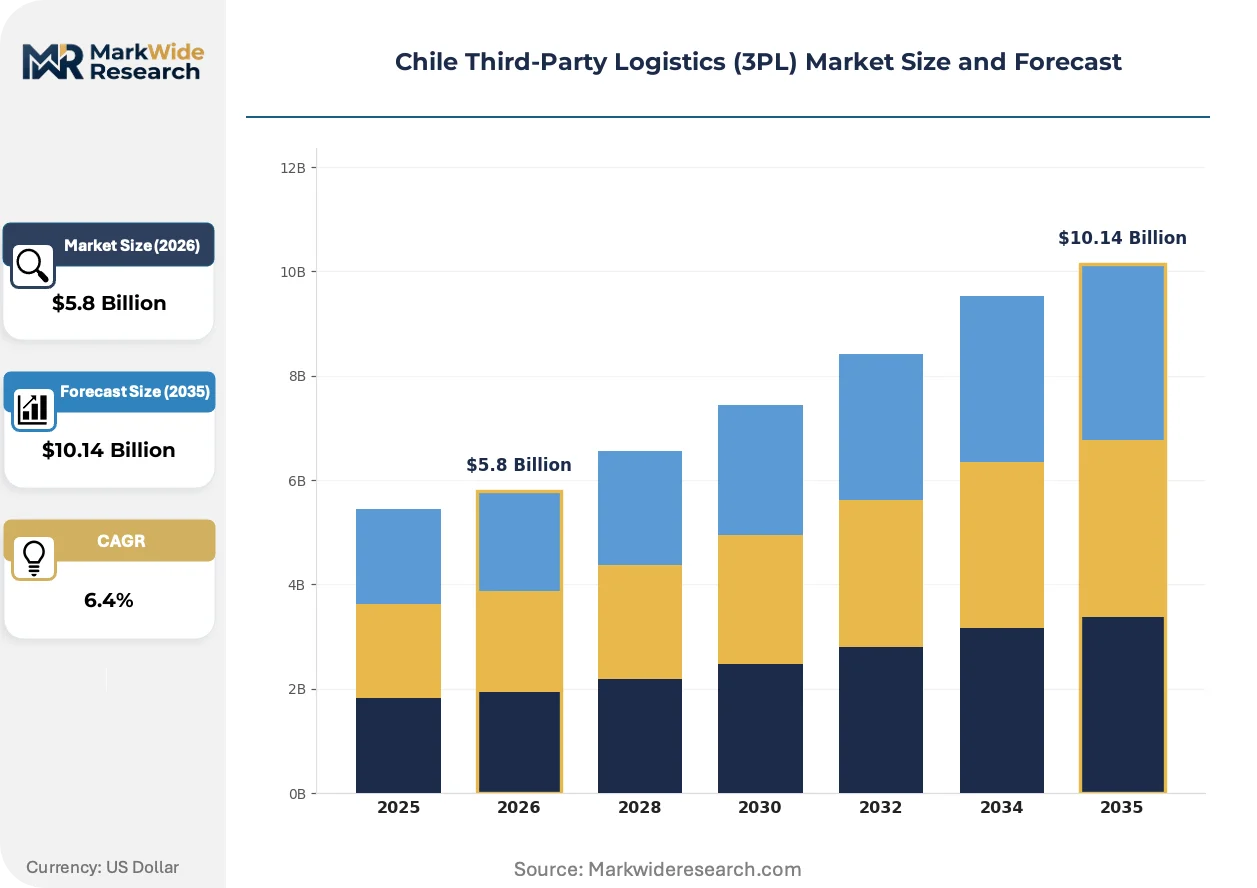
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Fulfillment End User: Retailers, Manufacturing, E-commerce, Healthcare Technology: Warehouse Management Systems, Transport Management Systems, Cloud Computing, IoT Solutions Delivery Model: Same-Day Delivery, Next-Day Delivery, Standard Delivery, Cross-Docking |
| Companies Covered | Agunsa, Deutsche Post DHL, Andes Logistics, DSV, Sitrans Servicios Integrados de Transportes, Ransa Logistics, Latam Logistics, ChileTrans Logistics, Kuehne + Nagel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Third-Party Logistics (3PL) Market Strategic Shifts
Digital freight platforms and automated warehouse systems are compressing traditional operator margins while creating new service tiers around real-time visibility and predictive inventory management.
IoT-enabled cold-chain monitoring is overtaking manual temperature logging for perishable exports. Salmon processors and fruit exporters now mandate continuous sensor telemetry from harvest to port. This shift is compressing insurance premiums and enabling faster claim resolution for temperature excursions.
The National Customs Service's electronic manifest submission requirements now mandate pre-arrival documentation for all containerized cargo. This regulatory compression forces 3PL operators to invest in integrated customs brokerage platforms. Cross-border freight specialists serving Santiago and Antofagasta are consolidating compliance functions to maintain clearance speed advantages.
Consolidation of buying power among large mining houses is compressing contract renewal cycles and unbundling transportation from warehousing services. Codelco and Anglo American now tender freight and storage separately, forcing 3PL providers to defend discrete service lines rather than bundled contracts. This pattern concentrates most acutely in the Calama-to-Antofagasta copper belt.
Chile Third-Party Logistics (3PL) Market Segmentation
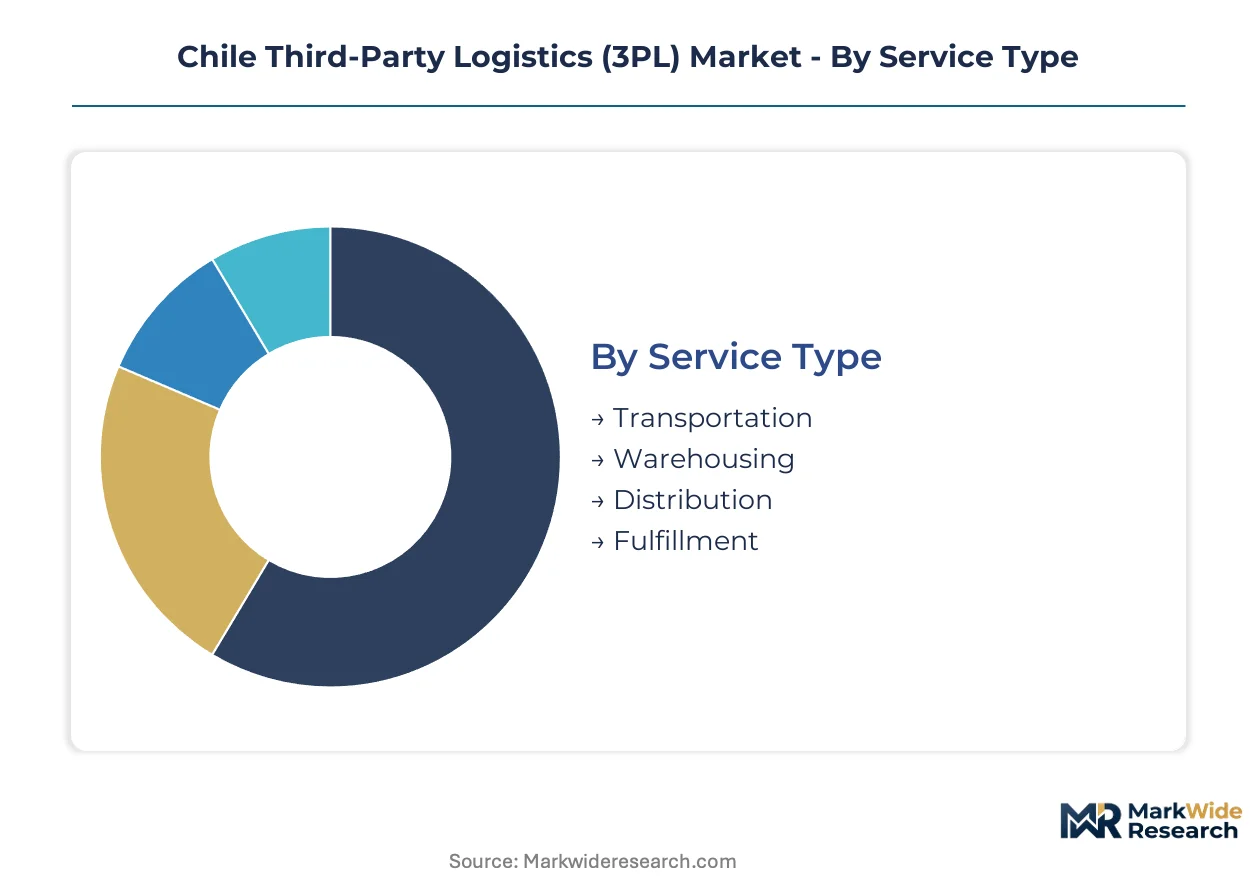
Chile's 3PL operators differentiate service portfolios across four distinct dimensions. Service type and technology adoption patterns reveal where infrastructure investments concentrate, while end-user verticals and delivery models expose margin structure variations across Santiago's urban core versus regional mining corridors.
Service Type:
Replacement cycles for legacy logistics infrastructure are accelerating as mining houses dismantle captive operations and pharmaceutical exporters demand temperature-controlled capabilities.
- Transportation:Fleet assets span dedicated heavy-haul corridors serving Calama-to-Antofagasta copper concentrate movements and refrigerated units for Biobío-to-San Antonio pharmaceutical lanes. Mining sector outsourcing is compressing contract renewal cycles and unbundling freight from warehousing services.
- Warehousing:Multi-client facilities coordinate real-time inventory tracking through integrated Warehouse Management Systems, with cold-storage capacity expanding fastest around Puerto Montt salmon processing clusters. Chile's elongated geography forces regional hub strategies rather than centralized national distribution.
- Distribution:Last-mile networks concentrate in Santiago Metropolitan Region density, serving retail replenishment and e-commerce fulfillment across congested urban cores. Regional expansion into Los Lagos remains underdeveloped relative to export volume growth.
- Fulfillment:E-commerce penetration in Santiago and Valparaíso drives specialized picking, packing, and returns processing capabilities. Standard delivery maintains volume dominance for bulk agricultural and mining inputs.
Volume placements concentrate in Transportation; the faster expansion belongs to Fulfillment.
End User:
Customer-type concentration shapes facility location decisions and technology deployment priorities across Chile's north-south corridor.
- Retailers:Department store and supermarket chains demand urban last-mile density with same-day capabilities in Santiago, driving consolidation of regional distribution centers toward the Central Valley corridor.
- Manufacturing:Pharmaceutical producers in Biobío and food processors across O'Higgins require temperature-controlled warehousing with continuous cold-chain documentation for export compliance.
- E-commerce:Pure-play online retailers and omnichannel department stores are expanding fulfillment center footprints in Santiago Metropolitan Region to compress delivery windows.
- Healthcare:Hospital networks and pharmaceutical distributors mandate validated cold-chain handling with sensor telemetry from warehouse to clinic, particularly for vaccine and biologic distribution.
Manufacturing commands the largest facility footprints; Healthcare is climbing the fastest on cold-chain infrastructure requirements.
Technology:
Technology refresh cycles are compressing as National Customs Service digitization mandates force platform upgrades across operator portfolios.
- Warehouse Management Systems:Multi-client facilities require real-time inventory visibility across agricultural cooperatives, mining suppliers, and pharmaceutical distributors. Legacy platforms at regional cooperatives resist data exchange standardization.
- Transport Management Systems:Route optimization algorithms address Chile's 4,300-kilometer north-south geography and Ministry of Transport hour-limit enforcement. Fuel price volatility directly compresses margins on long-haul lanes.
- Cloud Computing:Scalable infrastructure supports seasonal agricultural export surges and mining production fluctuations without captive data center investment.
- IoT Solutions:Cold-chain sensor networks monitor salmon from Puerto Montt harvest to San Antonio port departure, with continuous telemetry now mandated by major export insurers. This segment is gaining share fastest on perishable export compliance requirements.
Transport Management Systems anchor current deployments; IoT Solutions show the steepest expansion trajectory on cold-chain monitoring mandates.
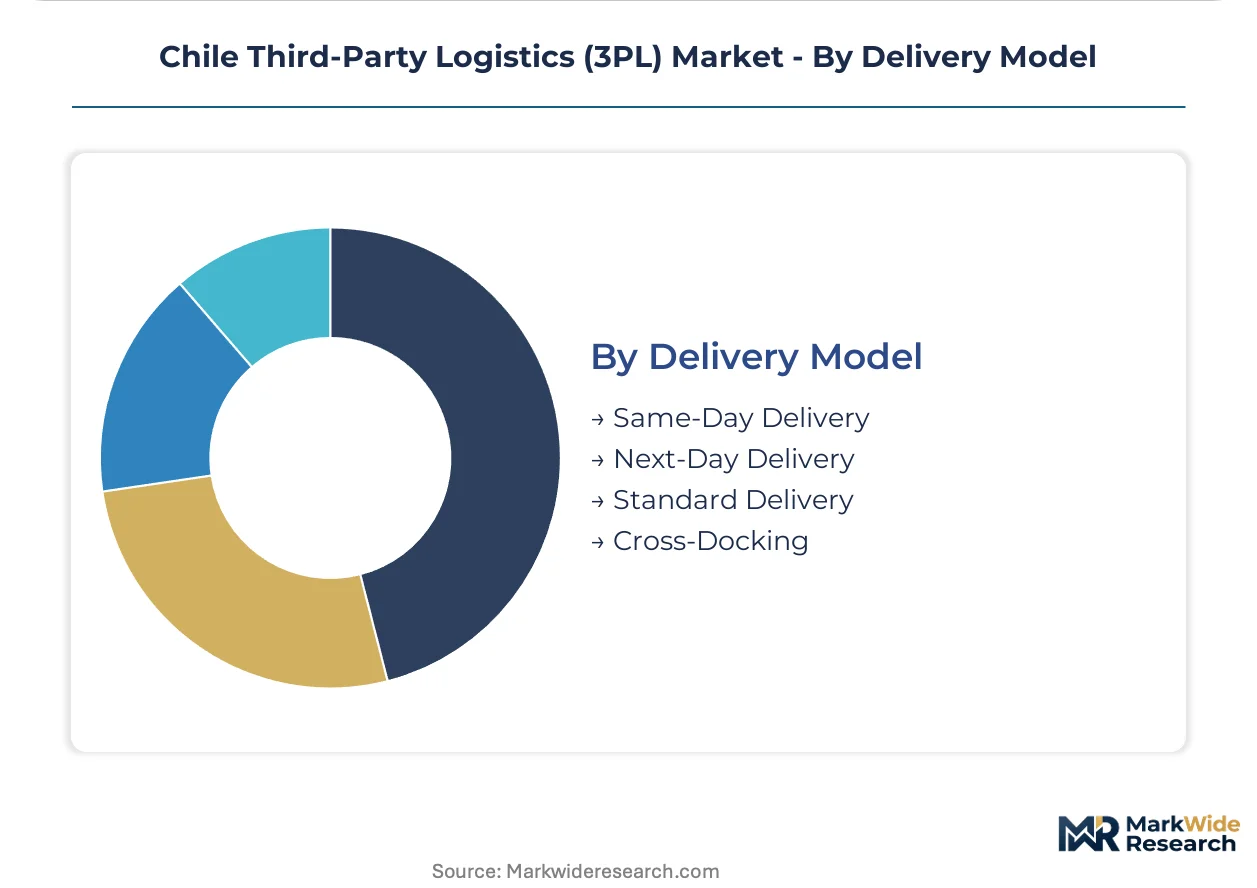
Delivery Model:
Speed-tier differentiation separates premium service margins from commodity bulk handling across Chile's logistics corridors.
- Same-Day Delivery:Santiago urban density enables point-to-point courier networks for e-commerce and healthcare urgent replenishment. Limited geographic scope constrains scalability beyond metropolitan boundaries.
- Next-Day Delivery:Regional distribution center positioning in Valparaíso and Concepción supports broader coverage with compressed windows for retail and manufacturing customers.
- Standard Delivery:Bulk agricultural inputs and mining supplies move on consolidated schedules with lowest cost per ton-kilometer. This tier absorbs fuel price volatility most directly.
- Cross-Docking:Minimal inventory holding reduces working capital for fast-moving consumer goods and perishable exports, requiring precise coordination between inbound and outbound fleets at hub facilities.
Standard Delivery captures tonnage dominance; Same-Day Delivery is expanding most quickly on Santiago e-commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Santiago Metropolitan Region anchors Chile's 3PL infrastructure concentration, where distribution hubs cluster near the Central Valley agricultural and industrial corridor. Tax incentives under the Zona Franca regime accelerate bonded warehousing development around Pudahuel and Quilicura logistics parks.
Santiago Metropolitan Region
E-commerce fulfillment demand and retail distribution density concentrate 3PL investment in Santiago's urban core. The Ministry of Transport and Telecommunications enforces driver hour regulations that constrain last-mile fleet utilization across congested metropolitan arteries. Distribution centers in Pudahuel and Quilicura process cross-border freight cleared through the National Customs Service's digitized manifest systems.
Valparaíso Region
Container terminal throughput at Valparaíso and San Antonio ports drives freight forwarding and customs brokerage specialization. Port concession laws govern competitive access for logistics providers seeking bonded warehouse space near marine terminals. The Biobío-to-Valparaíso pharmaceutical corridor requires temperature-controlled warehousing with continuous cold-chain documentation for export compliance.
Antofagasta Region
Copper concentrate movements from Calama mining clusters generate dedicated heavy-haul transportation demand. Codelco and Anglo American tender freight and warehousing services separately, compressing contract renewal cycles for specialized operators. Logistics providers along the Atacama-to-Antofagasta corridor invest in copper concentrate handling capabilities as mining houses dismantle captive infrastructure.
Los Lagos Region
Salmon processing centers around Puerto Montt generate specialized cold-chain logistics demand that outpaces regional 3PL capacity expansion. Export insurers now mandate continuous IoT sensor telemetry from harvest to port departure for temperature-sensitive seafood. The gap between processing volume growth and specialized warehousing availability creates infrastructure bottlenecks for perishable exporters.
Biobío Region
Pharmaceutical manufacturing clusters in Concepción and surrounding industrial zones drive temperature-controlled distribution requirements. Temperature-controlled corridors linking Biobío production facilities to Pacific ports remain underdeveloped relative to Santiago-centric infrastructure. Regional logistics providers face acute scarcity of refrigeration mechanics and cold-chain logistics coordinators in labor markets outside the capital.
Chile Third-Party Logistics (3PL) Market Competitive Environment
Top-tier vendors anchor air freight and global forwarding capabilities, while mid-tier specialists dominate mining corridor transportation and regional cold-chain warehousing. The market exhibits tiered concentration around international freight forwarders with Santiago headquarters, domestic heavy-haul operators serving northern mining belts, and urban last-mile specialists. Strategic archetypes include global integrators with customs brokerage platforms, mining-dedicated heavy-haul contractors, and perishable-focused cold-chain operators. Competitive moves concentrate on unbundling bundled service contracts and integrating IoT sensor networks with warehouse management platforms.
Among global integrators, Deutsche Post DHL and Kuehne + Nagel occupy positions representing air freight dominance and pharmaceutical corridor specialization respectively. Andes Logistics exemplifies the urban last-mile archetype focused on Santiago's congested metropolitan distribution challenges. These three entities represent distinct strategic postures: global network coverage with customs digitization capabilities, temperature-controlled export corridor development, and metropolitan density optimization for retail replenishment cycles.
| Leading Market Players |
|---|
| Agunsa |
| Deutsche Post DHL |
| Andes Logistics |
| DSV |
| Sitrans Servicios Integrados de Transportes |
| Ransa Logistics |
| Latam Logistics |
| ChileTrans Logistics |
| Kuehne + Nagel |
| Others |
Value Chain & Pricing Dynamics
Large mining houses like Codelco and Anglo American command pricing leverage through unbundled tender structures that separate freight from warehousing services, compressing contract renewal cycles and forcing 3PL providers into transactional rate negotiations rather than bundled value-based arrangements.
Pricing Analysis
Lead-time premiums for same-day Santiago urban delivery command 40-60% markups over standard bulk schedules, while spot inventory availability in Puerto Montt cold-storage corridors enables surge pricing during salmon harvest peaks. Three-tier pricing structure across premium cold-chain, standard dry freight, and economy bulk mining transport reflects certification grade and IoT telemetry inclusion. Cost compression in standard delivery tiers is intensifying because diesel volatility erodes long-haul margins across the 4,300-kilometer north-south corridor. E-commerce retailers exhibit highest price sensitivity, while pharmaceutical exporters prioritize validated cold-chain handling over rate minimization.
Supply Chain Analysis
Diesel fuel supply rests on Chilean state refinery capacity and imported Argentine spot markets, with refrigerated unit compressors and copper concentrate container linings sourced from Chinese and German manufacturers. Warehouse Management System software licenses flow predominantly from US and European enterprise vendors, while cold-chain sensor hardware centers on South Korean and Taiwanese component suppliers. Single-source vulnerability concentrates in specialized refrigeration mechanic labor pools, where Biobío and Los Lagos regional markets face acute scarcity. Distribution runs through bonded Zona Franca facilities near Santiago's Pudahuel corridor, with final-mile fragmentation across congested metropolitan arteries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized cold-chain technician scarcity props pricing power for qualified 3PL operators, as salmon and pharmaceutical export growth outpaces regional training pipeline capacity.
For Market Incumbents: Deploy IoT-warehouse convergence as the primary defensive lever against margin compression. Integrate cold-chain sensor telemetry directly into Warehouse Management System platforms to differentiate from commodity freight competitors. Secure refrigeration mechanic apprenticeship pipelines with Biobío technical institutes before labor scarcity intensifies. Backward integration into customs brokerage capabilities protects against National Customs Service digitization mandates that threaten pure-play forwarders. For New Entrants and Emerging Players: Digital freight platforms offer the lowest barrier entry path for asset-light market penetration. Target Los Lagos salmon processing clusters where specialized 3PL capacity lags export volume growth by substantial margins. Pursue white-space opportunities in Biobío pharmaceutical corridor temperature-controlled distribution, where Santiago-centric infrastructure leaves regional coverage gaps. Partner with Puerto Montt processing cooperatives for harvest-season surge capacity rather than year-round asset ownership. For Investors and Strategic Acquirers: The window for entry favors cold-chain specialists with established IoT compliance capabilities over generic freight forwarders. Long-term viability hinges on regulatory alignment with National Customs Service pre-arrival documentation mandates and export insurer telemetry requirements. Monitor Codelco and Anglo American tender unbundling patterns as inflection indicators for contract structure shifts across the Calama-to-Antofagasta copper belt.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Sensor Integration | IoT telemetry mandates from Puerto Montt salmon export insurers compress insurance premiums and accelerate claim resolution. |
| Customs Brokerage Platform Investment | National Customs Service electronic manifest requirements force pre-arrival documentation capabilities for clearance speed. |
| Refrigeration Technician Pipeline Development | Biobío and Los Lagos labor scarcity threatens cold-chain service quality for pharmaceutical and seafood exporters. |
| Zona Franca Bonded Warehouse Expansion | Tax incentives near Pudahuel and Quilicura logistics parks accelerate working capital efficiency for cross-border operators. |
| Mining Corridor Heavy-Haul Specialization | Calama-to-Antofagasta copper concentrate movements require dedicated handling as captive logistics dismantles. |
Study Parameters
Independent corroboration across 3PL operations executives, National Customs Service policy leads, and salmon export logistics managers underwrites the qualitative findings in this study. Primary interviews with fleet dispatch coordinators, cold-chain warehouse supervisors, and pharmaceutical distribution planners combined with secondary validation from Chilean Ministry of Transport enforcement records, customs modernization white papers, and Zona Franca incentive program documentation. Bottom-up service line sizing and top-down macroeconomic anchoring triangulate volume estimates across transportation, warehousing, and fulfillment segments.
Comparable-period anchoring to historical mining logistics outsourcing waves and e-commerce penetration trajectories shaped the projection framework across the analysis window. Segmentation modeling spans service type, end-user vertical, technology adoption tier, and delivery speed tier, with additional granularity on regional corridor differentiation between Santiago Metropolitan density and northern mining belts. CAGRs derive from weighted average of demand driver elasticities and capacity expansion constraints, with fuel price volatility and customs clearance speed as primary forecast inputs.
The model holds under continued National Customs Service digitization enforcement and stable mining production volumes; deviation in port concession law amendments or diesel subsidy policy shifts would revise trajectory. Forecasts reflect documented assumptions on technician labor supply and cold-storage construction lead times. A small set of named triggers—salmon export quota changes, driver hour regulation enforcement intensity, and IoT insurance mandate expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
North America Shipping Agency Market
Logistics and Shipping
Latin America Logistics Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
Halal Logistics Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
First and Last Mile Delivery Market
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
France Freight and Logistics Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market