
 Transportation by Drone Market | 2026-2036
Transportation by Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation by Drone Market Analytics
Beyond-visual-line-of-sight certification is reorganizing competitive hierarchies in commercial drone logistics. Zipline International Inc. dominates medical supply corridors across Rwanda and Ghana with fixed-wing infrastructure. Amazon.com, Inc. leverages its fulfillment density to anchor urban drone delivery pilots in California and Texas. Matternet, Inc. specializes in hospital-to-laboratory specimen transport, competing on precision landing systems.
Transportation by drone denotes the autonomous or remotely piloted movement of goods via unmanned aerial vehicles operating at altitudes typically below 400 feet, utilizing GPS waypoint navigation, sense-and-avoid sensors, and payload modules rated from 0.5 kg to 500 kg depending on platform class. Its primary commercial purpose is to bypass ground infrastructure constraints for time-critical or geographically isolated deliveries. Freight delivery occupies the largest revenue pool due to e-commerce volume density, while medical supply segments command premium pricing through cold-chain payload requirements. Multi-rotor platforms lead urban applications for vertical takeoff precision, though hybrid architectures are gaining traction for intercity routes where endurance thresholds exceed battery-only limitations.
The FAA's Part 135 certification and the EU's U-space regulatory framework collectively shape airspace access, liability allocation, and operator qualification standards across North America and Europe. China's CAAC drone traffic management trials and Japan's METI logistics drone roadmap are establishing parallel compliance benchmarks that manufacturers must navigate for multi-jurisdiction certification. Stakeholders must monitor evolving payload-weight thresholds and noise ordinances as municipalities begin drafting zoning overlays that could fragment operational permissions.
Market Dynamics
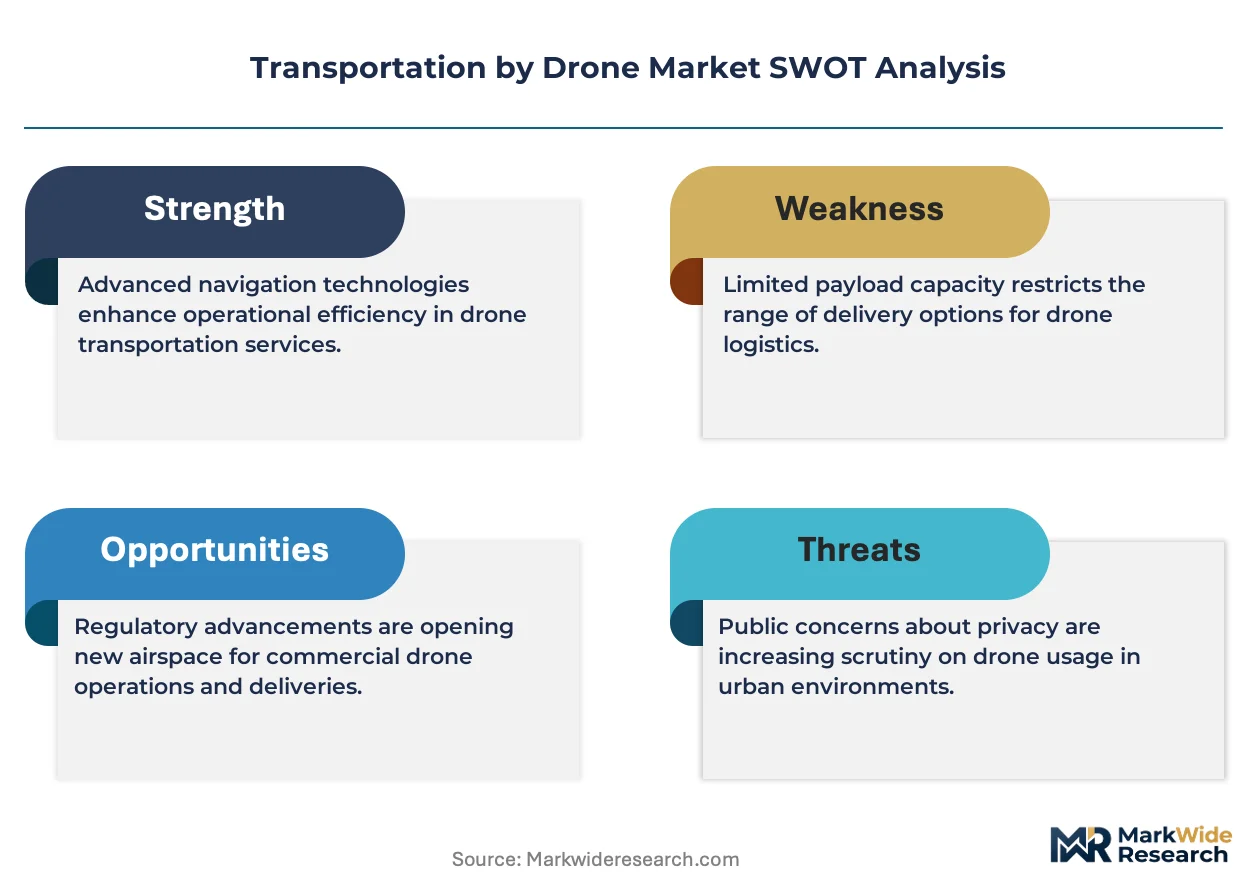
Beyond-visual-line-of-sight certification is reorganizing competitive hierarchies by forcing operators to invest in redundant detect-and-avoid systems and command center infrastructure before securing airspace access.
Growth Catalysts
- Part 135 Certification Pathway:The FAA's air carrier framework for drone operators is creating standardized operational compliance that accelerates insurer acceptance and hospital procurement cycles.
- Rural Healthcare Networks:Hospital system consolidation across the United States is driving fleet deployment decisions to close last-mile gaps in suburban and remote corridors.
- Hybrid Propulsion Architectures:Fixed-wing platforms with vertical takeoff capability are extending range thresholds beyond battery-only limitations for intercity medical routes.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell manufacturing concentrates in China, exposing operators to input cost volatility and export control friction.
- Municipal Zoning Fragmentation:Noise ordinances and altitude restrictions vary across jurisdictions, complicating route planning for multi-city networks.
- Pilot Substitution Economics:Ground-based delivery services in dense urban cores retain cost advantages for non-urgent payloads under five kilograms.
Strategic Opportunities
- EU U-Space Deployment:The European regulatory framework for unmanned traffic management is opening controlled airspace corridors that reduce insurance premiums for cross-border operators.
- Cold-Chain Specimen Transport:Laboratory networks are expanding temperature-controlled payload requirements that command premium pricing above standard freight rates.
- Japan METI Logistics Roadmap:The country's drone delivery infrastructure program is subsidizing pilot zones in mountainous prefectures with limited road access.
Industry Challenges
- Certification Timeline Compression:FAA Part 135 approval cycles average 18-24 months, delaying revenue generation for capital-intensive fleet deployments.
- Legacy System Integration:Hospital inventory management platforms require custom API development to synchronize with autonomous dispatch systems.
- Specialized Maintenance Workforce:Avionics technicians with unmanned systems expertise remain scarce relative to fleet expansion plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation by Drone Market |
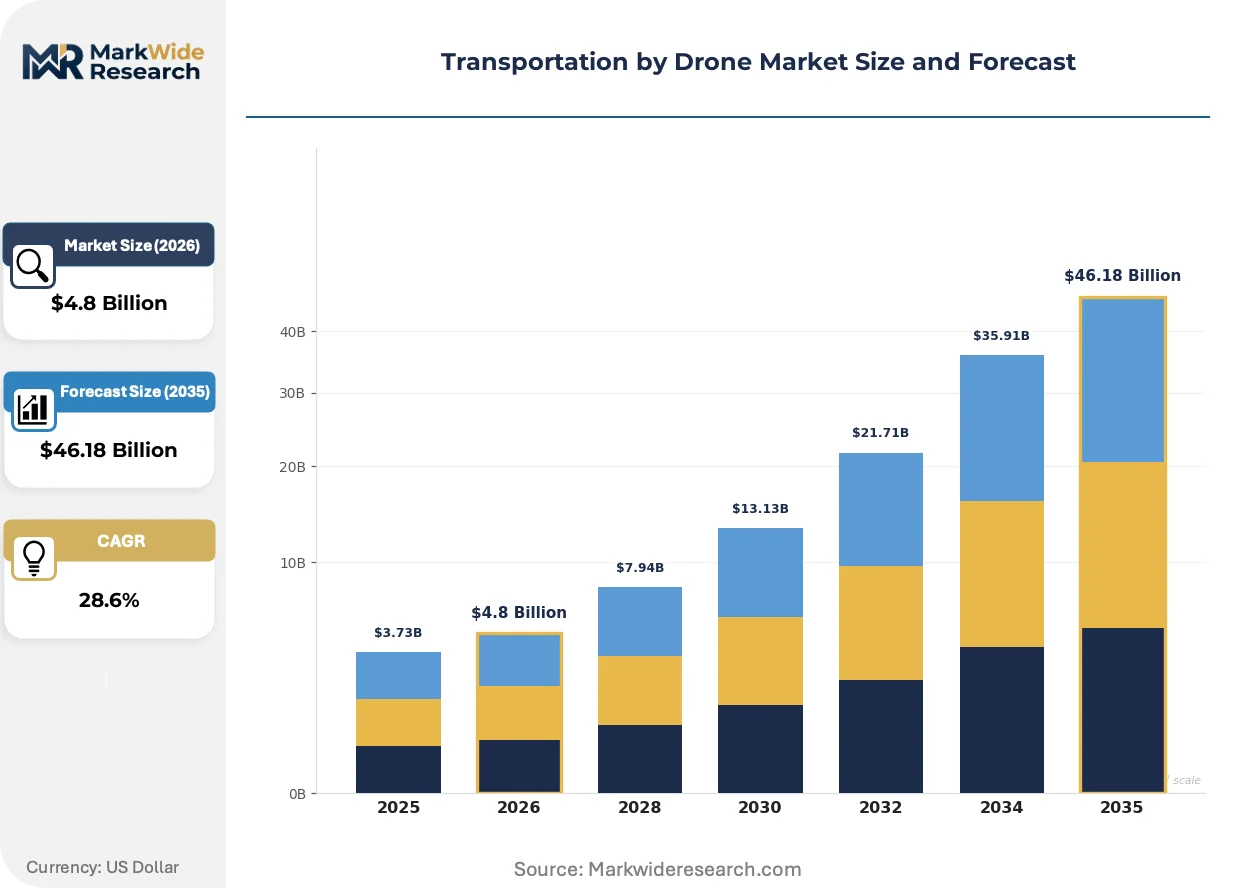
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Freight Delivery, Medical Supply, Food Delivery, News Coverage Technology: Fixed Wing, Multi-Rotor, Hybrid, Solar-Powered End User: Retailers, Healthcare Providers, Government Agencies, Logistics Companies Application: Urban Mobility, Agriculture Monitoring, Infrastructure Inspection, Disaster Relief |
| Companies Covered | Zipline International Inc., Matternet, Inc., Wing Aviation LLC, Drone Delivery Canada Corp., Flytrex Inc., Elroy Air, Dronamics, United Parcel Service of America, Inc., Amazon.com, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation by Drone Market Evolving Landscape
Autonomous navigation architectures are compressing the cost structure of precision landing systems while regulatory sandboxes in multiple jurisdictions are accelerating operational data collection.
Hybrid fixed-wing platforms are decomposing the traditional trade-off between endurance and vertical precision. Hospital laboratory networks are adopting these systems for 50-100 kilometer specimen corridors. The technology is decomposing route economics by eliminating ground transfer legs that previously dominated inter-facility logistics costs.
The EU's U-space regulatory framework is mandating standardized detect-and-avoid capabilities for operations above 120 meters. This requirement is forcing component suppliers to prioritize sense-and-avoid sensor integration over payload capacity optimization. Medical supply operators in Germany and Switzerland are responding by consolidating procurement specifications to reduce certification duplication across national borders.
Hospital procurement departments are consolidating vendor qualification around cold-chain performance guarantees rather than equipment ownership models. Third-party logistics providers are displacing in-house fleet operations for non-critical supply categories. This shift is most visible in the United States, where health system consolidation has centralized purchasing authority at regional headquarters.
Transportation by Drone Market Segmentation
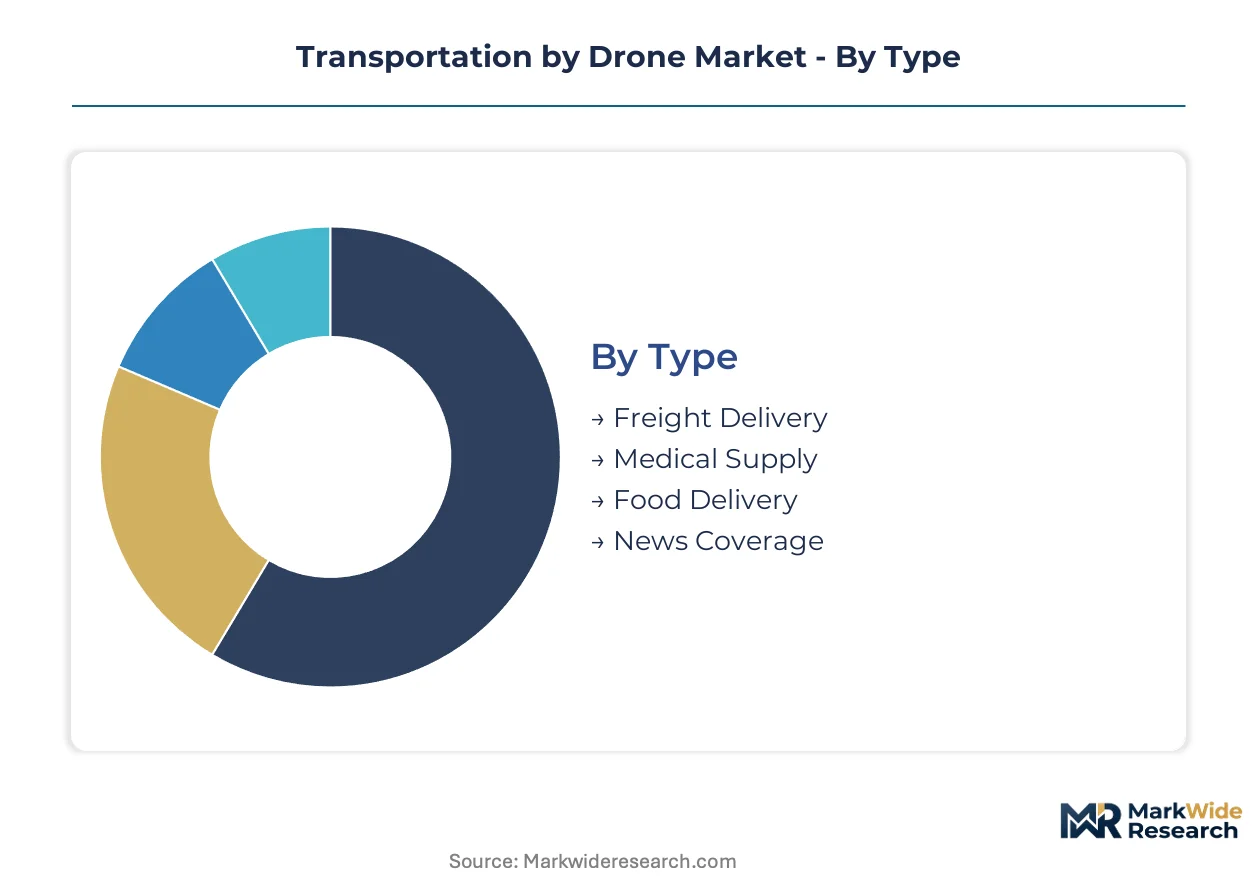
Drone logistics operators configure fleet specifications against payload requirements, airspace classifications, and customer procurement cycles. Segmentation choices determine certification pathways, insurance premiums, and hardware depreciation schedules across commercial deployments.
Type:
FAA Part 135 certification thresholds diverge sharply between routine freight operations and temperature-controlled medical payloads, reshaping fleet investment priorities.
- Freight Delivery:E-commerce fulfillment networks drive volume concentration in suburban corridors, with payload modules rated 2-5 kilograms for last-mile density. Amazon's California and Texas pilot zones anchor demand as operator certification accelerates insurer acceptance.
- Medical Supply:Cold-chain requirements command premium pricing through temperature-controlled payload modules and precision landing systems. Hospital system consolidation across the United States is centralizing procurement authority at regional headquarters.
- Food Delivery:Quick-service restaurant chains in dense urban cores test 10-15 minute delivery windows against ground-based alternatives.
- News Coverage:Broadcast media operators deploy rapid-response units for live event documentation and emergency situation monitoring.
Established volume favors Freight Delivery; emerging adoption favors Medical Supply.
Technology:
Platform architecture selection hinges on endurance thresholds, vertical precision requirements, and detect-and-avoid sensor integration costs.
- Fixed Wing:Extended-range platforms dominate intercity medical corridors with 50-100 kilometer endurance. Zipline International's Rwanda and Ghana infrastructure demonstrates route economics that eliminate ground transfer legs.
- Multi-Rotor:Vertical takeoff precision controls urban last-mile applications below 400 feet altitude. Battery-only limitations constrain range to 10-25 kilometers for payload modules under 5 kilograms.
- Hybrid:Fixed-wing platforms with VTOL capability are gaining traction where endurance thresholds exceed battery-only constraints.
- Solar-Powered:Experimental architectures target ultra-endurance applications in remote monitoring and extended logistics corridors.
Procurement concentration favors Multi-Rotor; technology transition favors Hybrid.
End User:
Customer procurement sophistication varies from standardized freight contracts to customized API integration requirements.
- Retailers:E-commerce volume density anchors fleet deployment decisions in suburban fulfillment zones.
- Healthcare Providers:Laboratory networks expand temperature-controlled specimen transport requirements with cold-chain performance guarantees.
- Government Agencies:Disaster relief and public safety applications drive procurement through federal emergency management frameworks.
- Logistics Companies:Third-party providers displace in-house fleet operations for non-critical supply categories.
Contract standardization favors Logistics Companies; specification complexity favors Healthcare Providers.
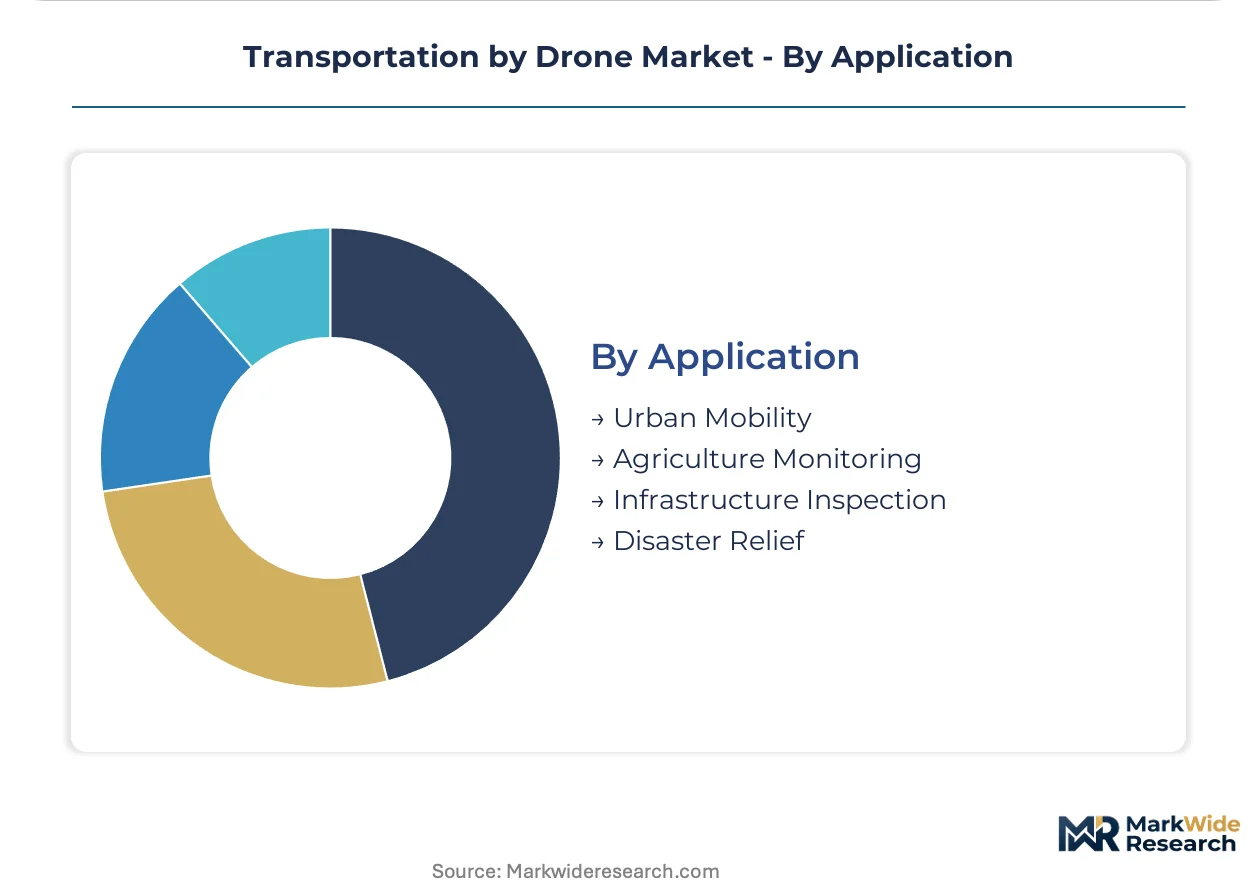
Application:
Municipal zoning overlays and noise ordinances fragment operational permissions across use case categories.
- Urban Mobility:Dense population centers impose altitude restrictions and sense-and-avoid mandates that elevate certification costs.
- Agriculture Monitoring:Rural corridors offer expanded airspace access with reduced detect-and-avoid infrastructure requirements.
- Infrastructure Inspection:Utility and transportation asset operators deploy beyond-visual-line-of-sight platforms for linear corridor coverage.
- Disaster Relief:Emergency exemptions temporarily suspend standard altitude and route restrictions during declared events.
Regulatory clarity favors Agriculture Monitoring; operational complexity favors Urban Mobility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Drone logistics infrastructure concentrates where regulatory sandboxes and healthcare network consolidation intersect. The United States, Rwanda, Germany, Japan, and Australia each demonstrate distinct deployment models shaped by local airspace governance and end-user procurement sophistication.
United States
Suburban last-mile gaps and hospital system consolidation drive fleet deployment decisions across Texas and California. The FAA's Part 135 certification framework accelerates insurer acceptance for commercial operators. Amazon's pilot zones in Lockeford and College Station anchor demand concentration for e-commerce fulfillment networks.
Rwanda
Rural healthcare corridors with limited road infrastructure sustain fixed-wing medical supply networks. The Rwanda Civil Aviation Authority's beyond-visual-line-of-sight exemptions enabled early commercial scale. Zipline's distribution centers outside Kigali and Muhanga demonstrate route economics that eliminate ground transfer legs for blood product delivery.
Germany
Laboratory network consolidation across Baden-Württemberg and Bavaria expands temperature-controlled specimen transport requirements. The EU's U-space regulatory framework mandates standardized detect-and-avoid capabilities above 120 meters. Medical supply operators in Mannheim and Munich consolidate procurement specifications to reduce certification duplication.
Japan
Mountainous prefectures with aging populations and limited road access create natural demand for aerial logistics. METI's drone delivery infrastructure program subsidizes pilot zones in Fukushima and Kanagawa. Hybrid platform trials between Tokyo medical centers and offshore islands test endurance thresholds beyond battery-only constraints.
Australia
Vast distances between remote communities and centralized healthcare facilities sustain intercity medical route development. The Civil Aviation Safety Authority's remotely piloted aircraft systems regulations provide standardized operational compliance. Queensland's drone delivery trials connect rural clinics with urban pathology laboratories across 100-kilometer corridors.
Transportation by Drone Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the drone logistics value chain. The market structures around three tiers: vertically integrated platform operators, specialized payload system developers, and third-party logistics enablers. Fixed-wing specialists, multi-rotor urban delivery providers, and hybrid architecture pioneers represent the dominant strategic archetypes. Competitive moves concentrate on regulatory certification acceleration and detect-and-avoid sensor integration partnerships rather than capacity expansion.
Within the medical supply specialization tier, Zipline International Inc. and Matternet, Inc. exemplify divergent platform strategies. Zipline anchors fixed-wing infrastructure across African healthcare networks. Matternet occupies a position in precision landing systems for hospital-to-laboratory specimen corridors. Among e-commerce-integrated operators, Amazon.com, Inc. represents the fulfillment density archetype leveraging existing warehouse networks for urban pilot deployment.
| Leading Market Players |
|---|
| Zipline International Inc. |
| Matternet, Inc. |
| Wing Aviation LLC |
| Drone Delivery Canada Corp. |
| Flytrex Inc. |
| Elroy Air |
| Dronamics |
| United Parcel Service of America, Inc. |
| Amazon.com, Inc. |
| Others |
Value Network & Pricing Analysis
FAA Part 135 certification gates both supplier qualification and price differentiation simultaneously, forcing operators to absorb detect-and-avoid infrastructure costs before accessing premium medical supply contracts. This regulatory threshold stratifies the vendor base into certified carriers commanding cold-chain premiums versus uncertified operators competing on standard freight rates.
Pricing Analysis
FAA Part 135 certification dictates the pricing tier structure across the drone logistics market. Three-tier pricing separates certified medical carriers from suburban freight operators and experimental pilot programs. Price differentiation rests on cold-chain performance guarantees and BVLOS operational authority. Pricing pressure stems from lithium-ion cell cost volatility concentrated in Chinese manufacturing. Ground-based couriers retain cost advantages for sub-five-kilogram urban payloads, compressing margins in dense metropolitan zones.
Supply Chain Analysis
Inventory lead times for detect-and-avoid sensors extend 16-24 weeks, constraining fleet expansion timelines for certified operators. Component manufacturing concentrates in China for battery cells, Taiwan for semiconductors, and Germany for precision avionics. Raw material dependencies include lithium carbonate, rare-earth magnets, and carbon-fiber composites. Single-source vulnerability runs through Chinese cathode material suppliers. Distribution feeds from Shenzhen and Hamburg through regional assembly hubs to operator maintenance depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone logistics is approaching a platform-economics inflection where U-space interoperability standards in Europe will force consolidation around common detect-and-avoid architectures, rewarding early standardization investments.
For Market Incumbents: Shield certification moats through accelerated FAA Part 135 renewal investments before the 18-24 month approval backlog lengthens further. Deepen backward integration into battery pack assembly to offset Chinese cell price volatility. Lock hospital procurement committees into multi-year cold-chain service contracts before third-party logistics providers consolidate regional purchasing authority. For New Entrants and Emerging Players: Differentiate on hybrid platform architectures serving 50-100 kilometer intercity medical corridors where battery-only range constraints exclude multi-rotor competitors. Target Japan's METI-subsidized mountainous prefectures and Australia's Queensland rural health networks as penetrable geographies with limited road infrastructure. Lead with laboratory specimen transport rather than competing against Amazon's fulfillment density in suburban e-commerce. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across BVLOS-certified fleet operators as redundant command center infrastructure becomes mandatory. Long-term viability favors platform-as-a-service models over hardware ownership. Acquire detect-and-avoid sensor specialists with FAA TSO-C154c certification rather than airframe manufacturers facing commodity competition. Watch EU U-space corridor activation as the signal for cross-border operator consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| BVLOS Certification Acceleration | Part 135 approval compresses insurer acceptance timelines for hospital procurement cycles. |
| Hybrid Platform Development | VTOL-fixed-wing architectures unlock intercity medical routes beyond battery-only constraints. |
| Cold-Chain Service Bundling | Temperature-controlled payload guarantees displace equipment ownership in hospital procurement. |
| Detect-and-Avoid Partnership | Sense-and-avoid sensor integration partnerships reduce certification duplication across jurisdictions. |
| Regional Logistics Acquisition | Third-party logistics consolidation captures health system purchasing authority centralization. |
Research Methodology
A standing panel of FAA certification consultants, hospital supply chain directors, and detect-and-avoid sensor engineers provided ongoing calibration. Primary interviews with drone fleet operators, aviation insurance underwriters, and municipal zoning officers combined with secondary validation against FAA Part 135 exemption dockets, EU U-space regulatory filings, and METI pilot zone disclosures. Bottom-up fleet deployment counts triangulated against top-down healthcare procurement database analysis.
Consistency checks validated volume and value outputs against customs records for Chinese battery cell exports and German avionics shipments. The analytical framework modeled payload type, platform architecture, end-user procurement sophistication, and application airspace classification across the projection horizon. CAGRs derived from operator fleet expansion plans weighted by certification timeline probability. Industry-specific inputs included hospital system consolidation velocity and municipal noise ordinance adoption rates.
The analysis sits within stated boundaries; outcomes outside sustained FAA certification throughput or lithium supply contract stability would require recalibration. Forecasts reflect documented assumptions about BVLOS regulatory progression and cold-chain payload adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Intelligent Airways Transportation Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Ride-Hailing Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Smart Parking Technologies Market
Smart Transportation Solutions
Closed Platform Screen Doors Market
Smart Transportation Solutions
E-Bike Rental Market
Smart Transportation Solutions
Road Weather Information Systems (RWIS) Market
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Traffic Signal Controller Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Global IoT in Transportation Market
Smart Transportation Solutions
Global Ridesharing Market
Smart Transportation Solutions
Global Parking Meter Apps Market
Smart Transportation Solutions
Middle East and Africa Passenger Information System Market