
 United States Cold Chain Logistics Market | 2026-2036
United States Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Cold Chain Logistics Market Outlook
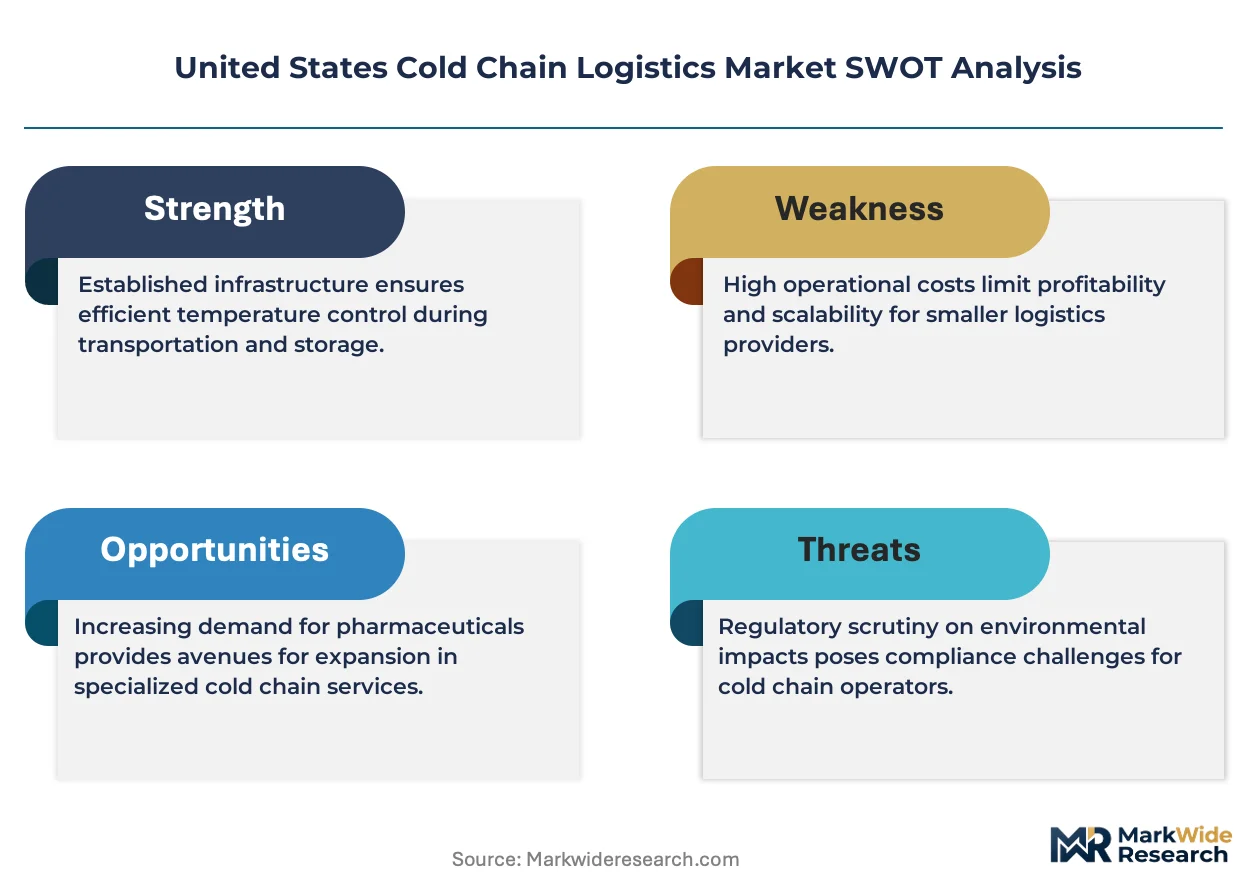
Asset-light leasing models for refrigerated trailer fleets is rewriting competitive entry barriers for mid-size 3PL operators. Americold Realty Trust, Inc. anchors national capacity through its controlled network of temperature-controlled warehouses across strategic rail and highway nodes. Lineage, Inc. differentiates through automated high-bay cold storage architecture that compresses energy intensity per pallet position. FedEx Corporation extends pharmaceutical-grade capabilities through validated packaging protocols and time-definite delivery lanes.
United States cold chain logistics encompasses the temperature-controlled movement and storage of perishable goods, requiring continuous maintenance between 2°C and 8°C for pharmaceuticals and sub-zero environments for frozen food matrices, utilizing vapor-compression refrigeration, phase-change materials, and real-time IoT telemetry to prevent thermal excursions. The biologics segment within pharmaceuticals commands premium handling protocols due to protein instability, while insulated boxes and refrigerated containers represent the dominant packaging formats for last-mile vaccine and cell-therapy distribution. E-commerce end users are driving fastest segment growth as grocery delivery platforms mandate shorter fulfillment windows with precise temperature handoffs.
FDA enforcement of Current Good Manufacturing Practice for finished pharmaceuticals, combined with USDA FSIS sanitary transportation rules and evolving OSHA warehouse safety standards, compels infrastructure upgrades and documented chain-of-custody systems. The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is forcing equipment replacement cycles toward lower-global-warming-potential alternatives. Stakeholders must monitor state-level building code variations for ammonia refrigeration systems and assess whether captive cold storage investment or third-party outsourcing better aligns with emerging biologics pipeline volumes.
Market Dynamics
The FDA's Drug Supply Chain Security Act is compressing documentation timelines for temperature excursions, forcing 3PL operators to rebuild chain-of-custody systems around real-time telemetry rather than batch-record reconciliation. This regulatory pressure is accelerating capital deployment into IoT-enabled warehouse management platforms.
Growth Catalysts
- Biologics pipeline expansion:Cell therapy and monoclonal antibody production is concentrating in the Interstate 95 corridor, generating demand for validated 2°C-to-8°C distribution lanes with continuous monitoring.
- AIM Act refrigerant phaseout:The EPA's hydrofluorocarbon reduction mandate is retrofitting existing cold storage infrastructure toward ammonia and CO2-based systems, opening upgrade cycles for equipment providers.
- California Central Valley agricultural output:Specialty crop exports are requiring precision cold chain handoffs from harvest through port drayage, expanding refrigerated container positioning at Oakland and Long Beach terminals.
Market Restraints
- Ammonia refrigeration permitting:State-level building code variations for industrial ammonia systems create 18-to-24-month approval timelines in jurisdictions with dense urban adjacency, constraining greenfield warehouse development.
- Qualified technician scarcity:The intersection of HVAC-R certification and pharmaceutical cGMP training produces a shallow labor pool for automated high-bay cold storage operations, elevating wage pressure in major metropolitan markets.
- Energy price volatility:Cold storage facilities consume 2.5 to 4.0 kilowatt-hours per pallet position annually, exposing operators to regional electricity rate spikes that compress margin on fixed-price logistics contracts.
Strategic Opportunities
- Cell therapy last-mile infrastructure:Cryogenic liquid nitrogen shippers and validated parcel packaging are creating white space for specialized couriers serving CAR-T manufacturing sites in the Boston-Cambridge cluster.
- USDA FSIS sanitary transportation gaps:Smaller protein processors in the Midwest lack compliant refrigerated fleet capacity, opening asset-light leasing models for regional 3PL operators with HACCP-certified trailers.
- OSHA warehouse automation incentives:Robotic pallet handling and automated storage retrieval systems reduce ergonomic injury exposure while compressing labor intensity per cubic foot in high-throughput distribution centers.
Industry Challenges
- cGMP documentation integration:Pharmaceutical shippers require electronic batch records that interoperate with 3PL warehouse management systems, forcing middleware development or ERP replacement cycles.
- Multi-temperature zone complexity:Grocery e-commerce fulfillment centers must simultaneously manage ambient, chilled, and frozen pick paths within single facilities, complicating slotting algorithms and order consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Cold Chain Logistics Market |
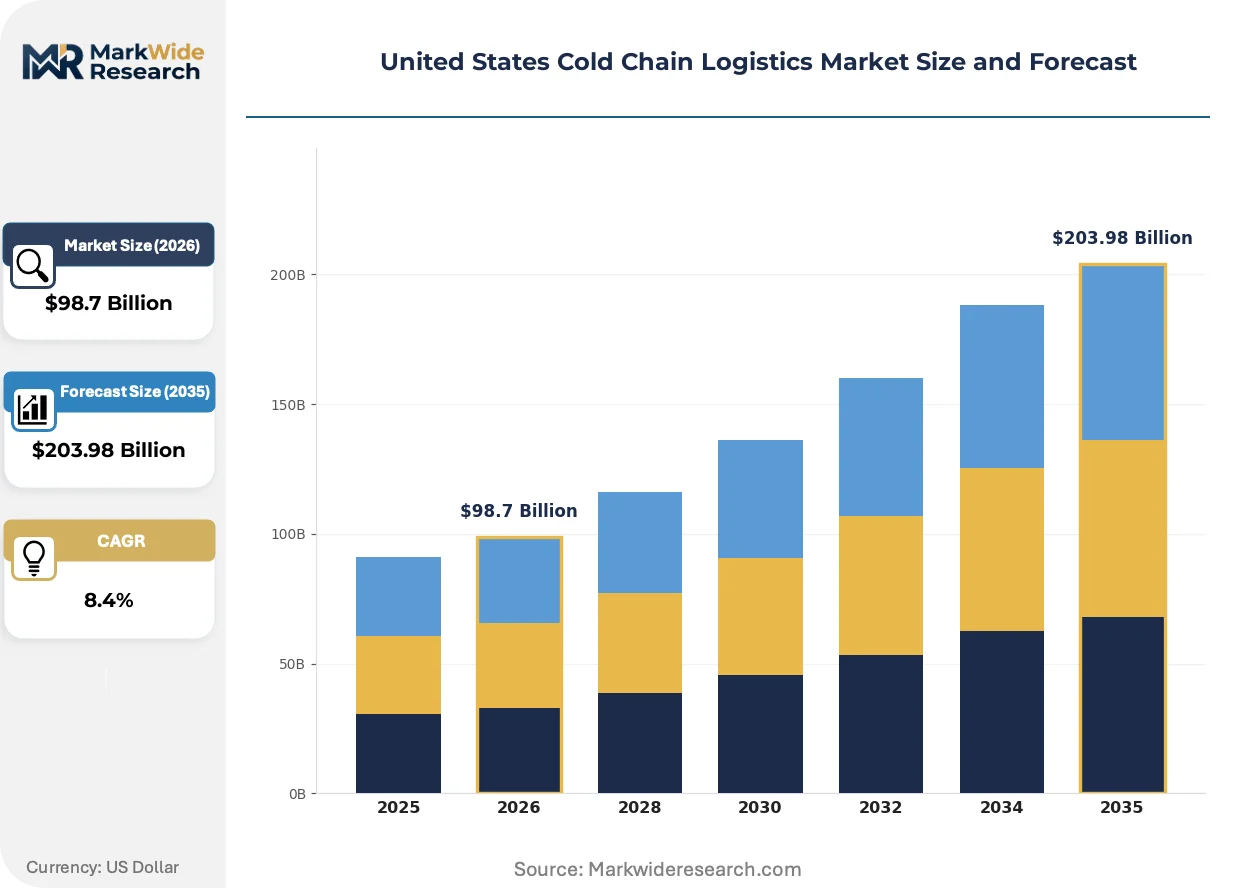
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Perishables, Pharmaceuticals, Biologics, Chemicals Transportation Mode: Refrigerated Trucks, Air Freight, Rail Transport, Sea Freight End User: Food & Beverage Industry, Healthcare Providers, Retail Chains, E-Commerce Packaging Type: Insulated Boxes, Refrigerated Containers, Pallet Shippers, Cold Packs |
| Companies Covered | C.H. Robinson Worldwide, Inc., Ryder System, Inc., Lineage, Inc., Interstate Cold Storage, Inc., Green Rabbit by Performance Food Group, Inc., Americold Realty Trust, Inc., FedEx Corporation, Kuehne+Nagel Group, United States Cold Storage, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Cold Chain Logistics Market Strategic Shifts
Real-time visibility platforms are displacing reactive temperature monitoring, embedding predictive analytics into pharmaceutical distribution workflows. This shift is compressing excursion response times from hours to minutes.
Phase-change material (PCM) insulation is migrating from passive shipping containers to active thermal regulation systems. Biologics distributors are adopting PCM-lined totes for 96-hour temperature stability in last-mile vaccine delivery. The technology is migrating from international air freight lanes into domestic ground parcel networks, enabling direct-to-patient cell therapy shipments without dry ice handling.
The EPA's AIM Act hydrofluorocarbon phasedown is accelerating equipment replacement cycles toward lower-global-warming-potential refrigerants. Cold storage operators face stranded asset risk in R-404A and R-507A systems, driving retrofit investment into ammonia and transcritical CO2 architectures. California's Title 24 building energy codes are tightening envelope insulation standards, compressing payback periods for thermal efficiency upgrades in new warehouse construction.
Meal kit and prepared food platforms are unbundling traditional wholesale distribution, contracting directly with cold chain 3PLs for temperature-controlled fulfillment. This channel disintermediation is fragmenting order profiles from pallet-scale to case-scale and individual-unit picking, forcing warehouse layout reconfiguration toward high-velocity, low-cube order consolidation. The shift is most visible in the Northeast corridor, where urban density supports sub-two-hour delivery windows for perishable prepared meals.
United States Cold Chain Logistics Market Segmentation
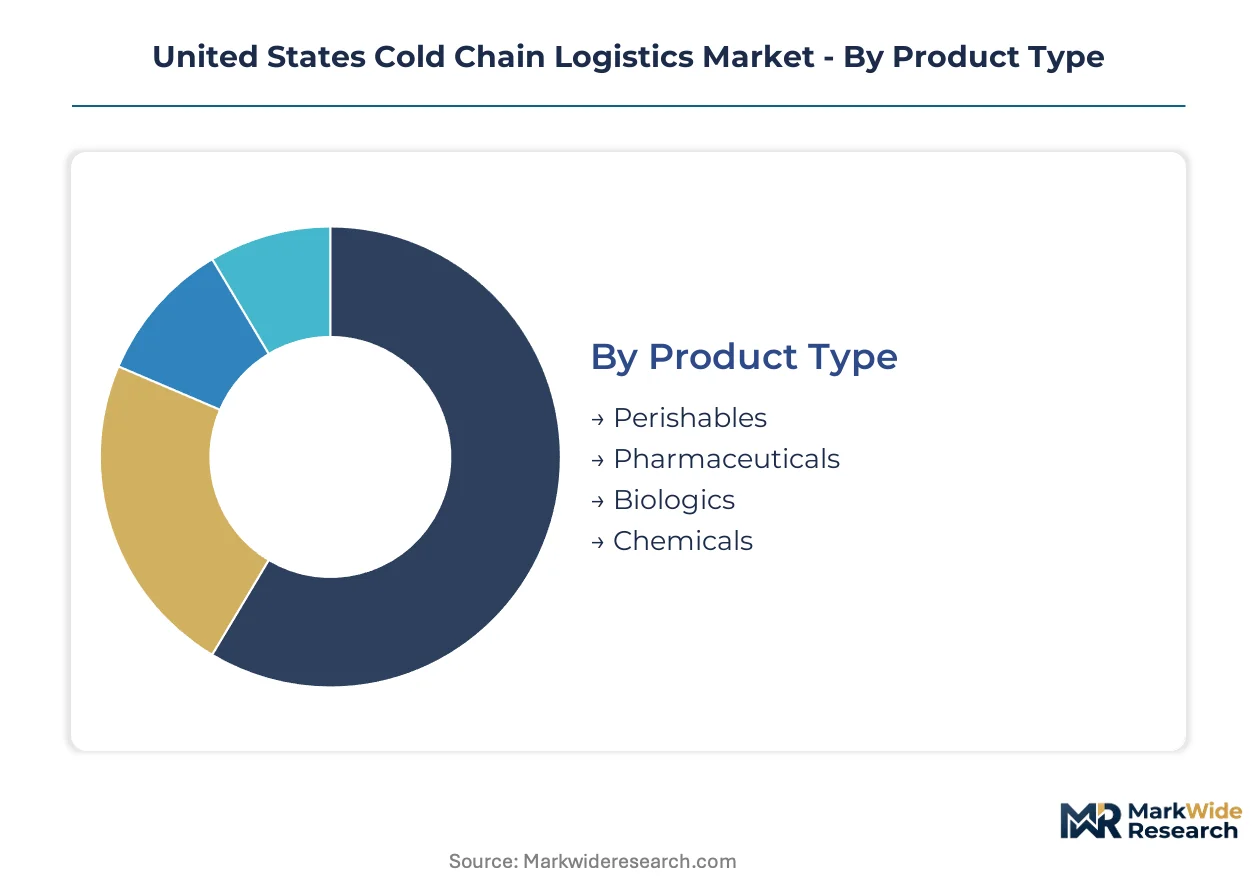
Cold chain logistics demands precise matching of infrastructure to product thermal requirements. Each segment category reflects distinct equipment specifications, regulatory burdens, and geographic concentration patterns that determine operator profitability and competitive positioning.
Product Type:
Temperature tolerance spans from ambient-sensitive produce to cryogenic cell therapies requiring liquid nitrogen maintenance.
- Perishables:Fresh produce, dairy, and meat products require continuous 0°C to 4°C circulation with high humidity control to prevent desiccation. California's Central Valley agricultural corridor generates concentrated outbound volume through Oakland and Long Beach port terminals, with harvest seasonality creating capacity squeezes in Q3.
- Pharmaceuticals:Finished drug products and vaccines maintain 2°C to 8°C stability through validated distribution lanes with FDA Drug Supply Chain Security Act documentation requirements. Interstate 95 pharmaceutical manufacturing clusters in New Jersey and Massachusetts drive premium lane pricing for continuous monitoring services.
- Biologics:Protein-based therapeutics with narrow thermal windows.
- Chemicals:Temperature-sensitive industrial and laboratory reagents.
Established volume favors Perishables; emerging adoption favors Biologics.
Transportation Mode:
Modal selection balances speed against cost per pallet-mile, with pharmaceutical shippers prioritizing time-definite delivery over freight economics.
- Refrigerated Trucks:Diesel-powered and electric reefers dominate domestic ground distribution with real-time telematics integration for pharmaceutical chain-of-custody documentation. The Interstate 95 and I-5 corridors concentrate fleet positioning to serve pharmaceutical and agricultural demand clusters.
- Air Freight:Temperature-controlled cargo holds and active container systems enable intercontinental biologics movement with 24-to-48-hour transit windows. Memphis and Louisville hub airports anchor pharmaceutical air freight concentration for time-critical cell therapy distribution.
- Rail Transport:Intermodal refrigerated containers for bulk agricultural commodities.
- Sea Freight:Reefer containers for international produce and frozen protein trade.
Rail and sea freight carry the heaviest tonnage; air freight commands the steepest expansion trajectory from biologics pipeline growth.
End User:
Customer scale determines order profile complexity, from pallet-scale restaurant distribution to individual-unit e-commerce picking.
- Food & Beverage Industry:Restaurant chains, foodservice distributors, and protein processors require high-throughput pallet movement with HACCP-compliant handling protocols. USDA FSIS sanitary transportation rules mandate dedicated fleet segregation for raw versus ready-to-eat products.
- E-Commerce:Grocery delivery platforms and meal kit services are compressing fulfillment windows to sub-two-hour delivery with multi-temperature zone consolidation. Urban density in the Northeast corridor supports micro-fulfillment center placement for last-mile cold chain handoffs.
- Healthcare Providers:Hospital systems and specialty pharmacies with validated receiving protocols.
- Retail Chains:Supermarket operators with distribution center networks.
Food & Beverage Industry anchors current revenue concentration; E-Commerce is climbing the fastest from channel disintermediation.
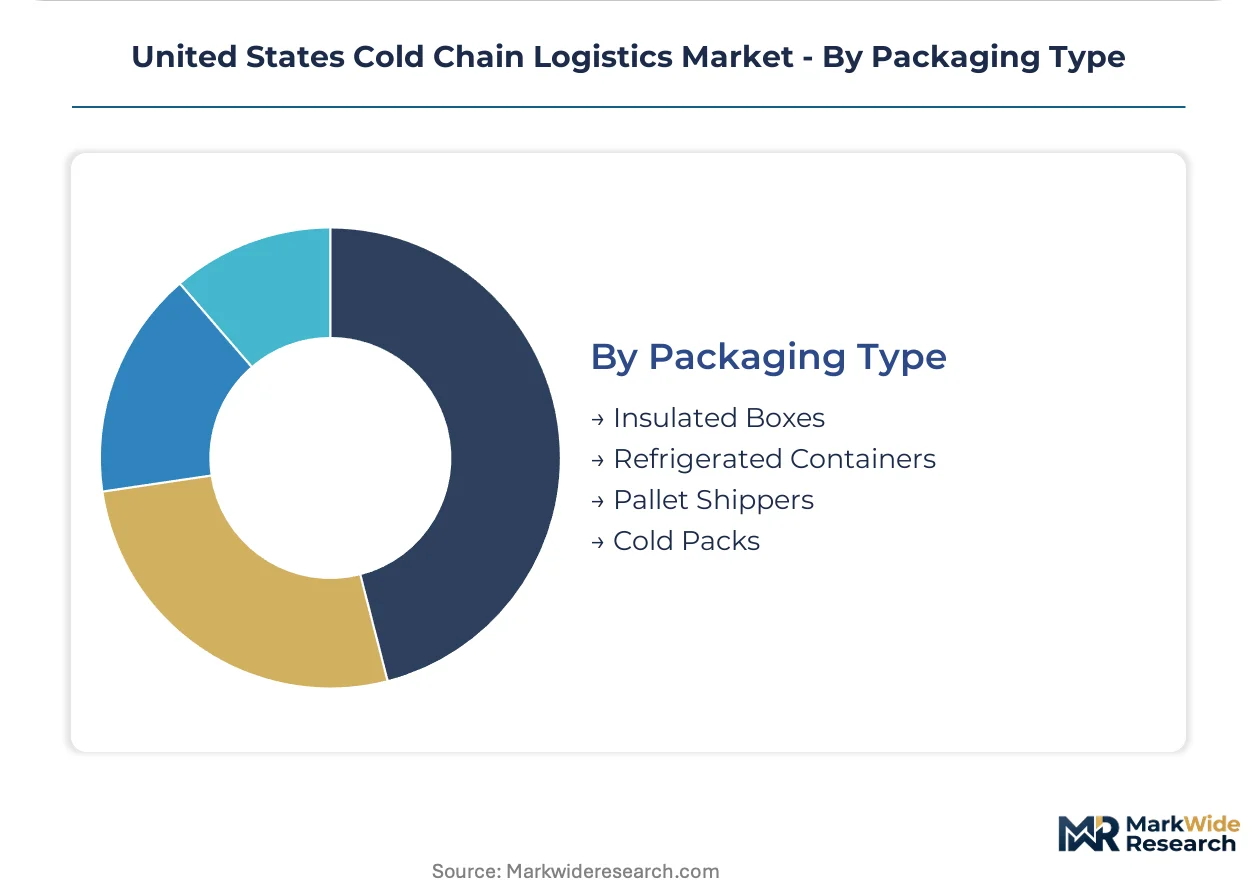
Packaging Type:
Thermal protection technology ranges from passive insulation to active mechanical refrigeration systems.
- Insulated Boxes:Expanded polystyrene and vacuum-insulated panels with phase-change material coolants provide 48-to-96-hour temperature stability for parcel-scale pharmaceutical shipments. Direct-to-patient cell therapy distribution in the Boston-Cambridge cluster is expanding validated packaging demand.
- Refrigerated Containers:Active compressor-based units for international sea and air freight with precise temperature setpoint control. Port drayage operators at Long Beach and Savannah are positioning refrigerated container fleets for specialty crop export growth.
- Pallet Shippers:Large-format passive thermal protection for bulk pharmaceutical distribution.
- Cold Packs:Gel and phase-change material inserts for short-duration protection.
Refrigerated Containers dominate international volume; Insulated Boxes are gaining share fastest from last-mile pharmaceutical fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium lane pricing concentrates along the Interstate 95 pharmaceutical corridor, while California's Central Valley agricultural output commands seasonal capacity premiums. The Northeast corridor generates validated 2°C-to-8°C distribution premiums, whereas Midwest protein processing clusters face refrigerated fleet scarcity.
California
Specialty crop exports through Oakland and Long Beach terminals drive refrigerated container demand, with harvest seasonality creating Q3 capacity squeezes. The California Air Resources Board enforces zero-emission drayage truck mandates by 2035, accelerating electric reefer deployment. The Central Valley agricultural corridor anchors outbound volume for almonds, berries, and leafy greens.
New Jersey
Pharmaceutical manufacturing clusters generate continuous monitoring premiums for biologics distribution lanes. FDA Drug Supply Chain Security Act compliance requirements tighten temperature documentation standards for finished drug products. The Port of Newark-Elizabeth positions refrigerated containers for temperature-sensitive imports.
Massachusetts
Cell therapy manufacturing in the Boston-Cambridge cluster demands cryogenic liquid nitrogen shippers and validated parcel packaging. The state's clean energy mandates accelerate ammonia refrigeration adoption in new cold storage construction. Worcester County hosts automated high-bay distribution centers serving regional biologics pipelines.
Texas
Cross-border produce trade with Mexico concentrates refrigerated truck demand at Laredo and McAllen border crossings. The Texas Commission on Environmental Quality enforces refrigerant management rules under federal AIM Act alignment. The Dallas-Fort Worth Metroplex anchors regional distribution for protein processors lacking compliant fleet capacity.
Illinois
Midwest agricultural processing generates intermodal refrigerated container volume through Chicago rail hubs. The Illinois Environmental Protection Agency enforces ammonia refrigeration safety standards for industrial cold storage facilities. The I-55 corridor connects grain elevators to barge terminals on the Mississippi River system.
United States Cold Chain Logistics Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in equipment and packaging niches. The market structure consolidates around national warehouse operators with controlled rail-highway node networks, while mid-size 3PL operators compete through asset-light leasing models. Three archetypes dominate: temperature-controlled real estate investment trusts, integrated parcel carriers with pharmaceutical validation, and specialized biologics couriers. Competitive moves center on automated high-bay architecture deployment and refrigerant system retrofits toward lower-global-warming-potential alternatives.
Among national warehouse operators, Americold Realty Trust, Inc. and Lineage, Inc. exemplify scale-driven platform consolidation. Americold anchors capacity through strategic node positioning, while Lineage represents automated architecture differentiation. FedEx Corporation occupies the integrated carrier tier with time-definite pharmaceutical capabilities.
| Leading Market Players |
|---|
| C.H. Robinson Worldwide, Inc. |
| Ryder System, Inc. |
| Lineage, Inc. |
| Interstate Cold Storage, Inc. |
| Green Rabbit by Performance Food Group, Inc. |
| Americold Realty Trust, Inc. |
| FedEx Corporation |
| Kuehne+Nagel Group |
| United States Cold Storage, Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in California's Central Valley during Q3 harvest windows compresses refrigerated container availability at Oakland and Long Beach terminals, forcing produce exporters to absorb premium positioning fees while 3PL operators exploit scarcity pricing for outbound agricultural lanes.
Pricing Analysis
The customization-premium spread between validated pharmaceutical distribution and standard perishable freight exceeds three-to-one on a pallet-mile basis. Pharmaceutical shippers absorb premium-mid-economy pricing differentiation driven by FDA Drug Supply Chain Security Act documentation requirements and continuous IoT telemetry mandates. Cost compression in standard refrigerated trucking intensifies because diesel price volatility and driver wage inflation erode fixed-contract margins. Protein processors exhibit highest price sensitivity due to thin commodity margins, while cell therapy manufacturers demonstrate lowest sensitivity given product value density and regulatory non-negotiability.
Supply Chain Analysis
Tariff exposure between Mexico and the United States concentrates refrigerated truck demand at Laredo and McAllen border crossings, amplifying congestion risk during peak produce seasons. Equipment manufacturing draws from China, Germany, and the United States for compressor systems, IoT sensors, and refrigeration unit assemblies. Ammonia refrigerant supply hinges on domestic production clusters in Louisiana and Texas, creating single-source vulnerability for cold storage retrofit cycles. Distribution runs through controlled node networks anchored by rail-highway interchanges, with last-mile fragmentation accelerating toward urban micro-fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward grocery e-commerce platforms and consolidated pharmaceutical distributors, fragmenting order profiles from pallet-scale to individual-unit picking while compressing fulfillment windows.
For Market Incumbents: Entrench automated high-bay architecture at Worcester County and Central Valley nodes to defend against asset-light 3PL entrants exploiting refrigerated trailer leasing models. Prioritize ammonia refrigeration certification investment ahead of EPA AIM Act enforcement timelines to lock in greenfield permitting advantages. Vertical control over cryogenic liquid nitrogen distribution secures cell therapy corridor positioning against specialized courier competition. For New Entrants and Emerging Players: Build out USDA FSIS-compliant refrigerated fleet capacity serving Midwest protein processors lacking HACCP-certified equipment, the most penetrable whitespace in domestic cold chain coverage. Target regional 3PL positioning around Chicago rail hubs where intermodal refrigerated container demand outstrips qualified operator supply. Pursue direct contracting with meal kit platforms seeking temperature-controlled fulfillment disintermediated from traditional wholesale distribution. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated warehouse operators with pharmaceutical validation credentials and long-term biologics pipeline contracts. Long-term viability across the analysis window favors platform consolidators with controlled node networks over pure-play transportation assets. Monitor EPA refrigerant phasedown enforcement velocity as the critical inflection signal for stranded asset risk in legacy R-404A and R-507A systems.| Strategic Initiative | Industry Significance |
|---|---|
| Automated High-Bay Architecture Deployment | Lineage's compression of energy intensity per pallet position sets operational benchmarks for national competitors. |
| Ammonia Refrigeration Retrofit | EPA AIM Act compliance forces equipment replacement cycles toward lower-global-warming-potential alternatives. |
| Cell Therapy Last-Mile Infrastructure | Cryogenic liquid nitrogen shippers and validated parcel packaging capture premium margins in Boston-Cambridge cluster. |
| IoT-Enabled Warehouse Management Integration | FDA Drug Supply Chain Security Act documentation requirements compress excursion response times from hours to minutes. |
| Asset-Light Refrigerated Fleet Leasing | Mid-size 3PL operators rewrite competitive entry barriers by reducing capital intensity for regional market penetration. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cold storage facility managers, pharmaceutical distribution executives, refrigerated fleet operators, and agricultural export coordinators. Secondary validation drew from FDA enforcement action databases, EPA refrigerant phaseout schedules, USDA FSIS sanitary transportation rulemakings, and California Air Resources Board zero-emission mandates. Bottom-up capacity modeling across temperature-controlled warehouse square footage and top-down pharmaceutical shipment value flows were triangulated against Interstate 95 and I-5 corridor traffic patterns.
Calibration against historical capacity utilization rates at Oakland and Long Beach terminals, plus pharmaceutical air freight volumes through Memphis and Louisville hubs, anchored volume projections across the modeling period. Segmentation dimensions included product thermal requirements, transportation mode economics, end-user order profile complexity, and packaging technology sophistication. CAGRs were derived from regression analysis of biologics pipeline expansion rates, e-commerce grocery penetration curves, and refrigerant equipment replacement cycles.
Stress conditions across energy price volatility, ammonia permitting timeline extensions, and qualified technician wage inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement velocity and biologics commercialization timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Manufacturing Logistics Market
Logistics and Shipping
Central and Eastern Europe Freight and Logistics Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
Vietnam Logistics Market
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
Chile Air Freight Transport Market
Logistics and Shipping
China Local Courier Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
Italy Cold Chain Logistics Market
Logistics and Shipping
Vietnam Freight and Logistics Market
Logistics and Shipping
Singapore Freight and Logistics Market