
 Middle Mile Delivery Market | 2026-2036
Middle Mile Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Middle Mile Delivery Market Foresight
The US EPA Phase 3 greenhouse gas standards for heavy-duty vehicles is realigning fleet procurement timelines and capital allocation across the middle mile. Kuehne + Nagel International AG leverages its intermodal density across North American rail corridors to sustain cost advantages in long-haul lanes. DHL Supply Chain anchors European pharmaceutical distribution networks with temperature-validated cross-dock infrastructure. FedEx Corporation competes through proprietary routing software that optimizes hub-and-spoke sortation velocity.
Middle mile delivery denotes the transportation and handling of goods between origin hubs—ports, fulfillment centers, or manufacturing plants—and last-mile distribution nodes, typically spanning 100 to 1,000 miles with palletized or parcelized freight moving through sortation facilities and cross-docks. Its primary purpose is consolidating fragmented inbound flows into optimized outbound loads that match downstream delivery windows. Trucking retains dominant share in transport mode due to door-to-door flexibility, though intermodal rail captures margin in corridors exceeding 500 miles where fuel cost differentials justify drayage handoffs. Automation tools within the technology segment attract capital fastest, as robotic sortation and autonomous yard tractors compress dwell times at cross-docking nodes.
The US EPA and the Federal Motor Carrier Safety Administration jointly shape equipment standards and driver availability, while the European Union's Green Deal and F-Gas Regulation pressurize refrigerated intermodal assets toward lower-emission refrigerants. California's Advanced Clean Trucks rule functions as a de facto national standard for fleet operators serving multi-state e-commerce platforms. Stakeholders must monitor regulatory fragmentation between federal efficiency mandates and state-level zero-emission timelines when committing to tractor and trailer replacement cycles.
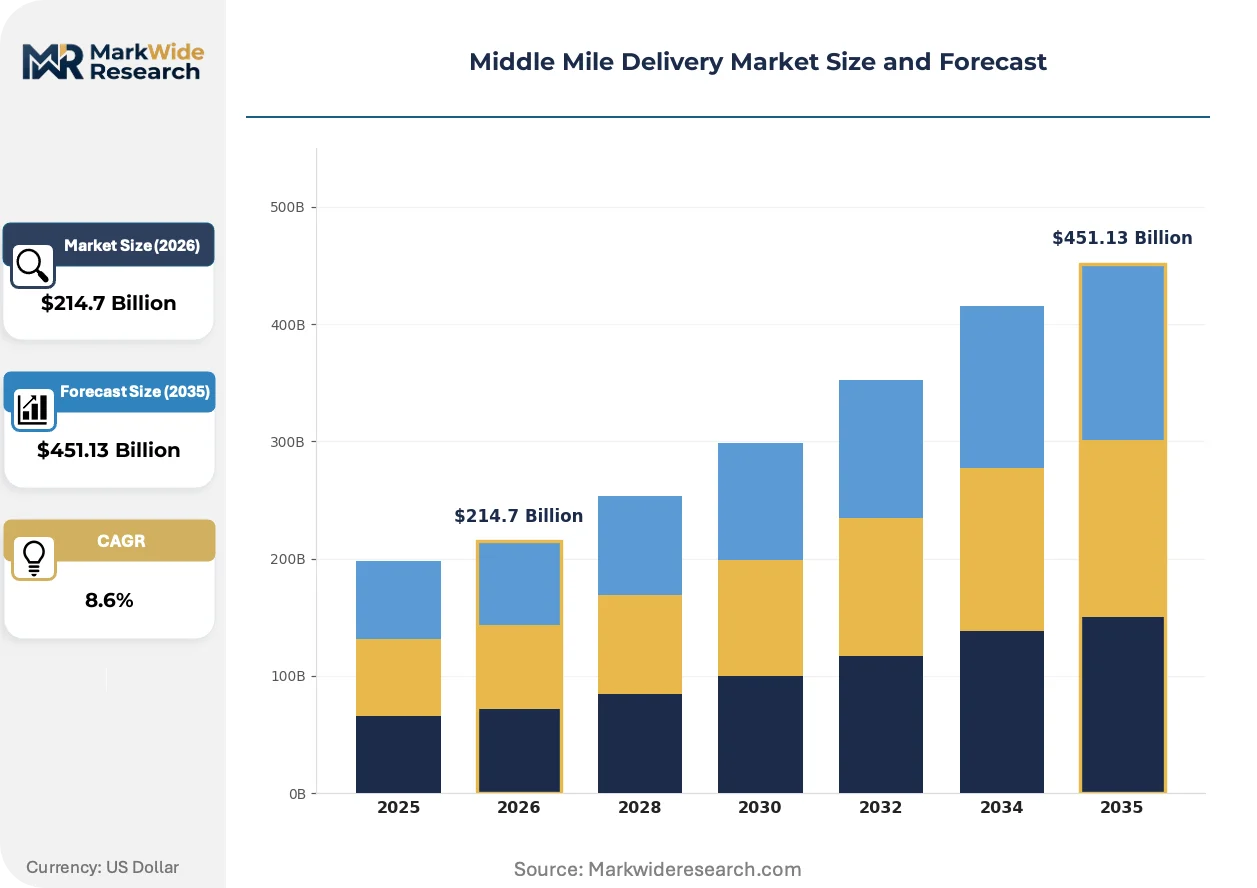
Market Dynamics
The EPA Phase 3 greenhouse gas standards for heavy-duty vehicles are compressing fleet replacement cycles and forcing capital reallocation toward electrified line-haul corridors. This regulatory pressure intersects with e-commerce velocity demands to reshape asset deployment across the 100-to-1,000-mile freight band.
Growth Catalysts
- Cross-docking infrastructure:E-commerce platforms are accelerating adoption of cross-docking and intermodal services to compress dwell times at sortation nodes.
- California's Advanced Clean Trucks rule:This state-level mandate functions as a de facto national standard for fleet operators serving multi-state distribution networks.
- Texas-California freight corridor:Drayage-to-intermodal handoffs dominate volume flows in this corridor, pulling investment into electrified yard equipment and automated gate systems.
Market Restraints
- Battery energy density limitations:Current lithium-ion chemistry constrains range for electric Class 8 tractors below 300 miles, forcing hybrid configurations on longer corridors.
- Charging infrastructure gaps:The I-10 and I-20 corridors lack sufficient megawatt charging stations to support continuous electrified operations.
- Driver availability constraints:The Federal Motor Carrier Safety Administration's hours-of-service rules compound recruitment challenges for overnight line-haul routes.
Strategic Opportunities
- Autonomous yard tractors:Convergence of lidar perception systems with electric drivetrains enables unmanned trailer repositioning at cross-dock facilities.
- Temperature-validated intermodal:Pharmaceutical distribution networks in Europe require compliant refrigerated rail assets, creating premium service tiers.
- Rail electrification corridors:BNSF and Union Pacific are piloting catenary-powered segments along the Los Angeles-Chicago lane.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems require costly API rewrites to ingest real-time data from electric powertrains and autonomous subsystems.
- Refrigerant compliance timelines:The EU F-Gas Regulation mandates phase-out of high-GWP refrigerants in intermodal reefers before 2030, compressing retrofit schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle Mile Delivery Market |
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $451.13 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fulfillment Centers, Cross-Docking, Warehousing, Sorting Facilities Transport Mode: Trucking, Rail, Air Freight, Intermodal Technology: Routing Software, Tracking Systems, Automation Tools, Inventory Management Customer Type: E-Commerce Platforms, Retail Chains, Wholesalers, Manufacturers |
| Companies Covered | Kuehne + Nagel International AG, DB Schenker, United Parcel Service (UPS), Nippon Express, C.H. Robinson Worldwide Inc., DHL Supply Chain, DSV Panalpina A/S, CEVA Logistics, FedEx Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle Mile Delivery Market Shifts & Advancements
Automation tools within middle mile nodes are attracting capital fastest as operators seek to compress dwell times and reduce labor dependency at cross-docking facilities. Three distinct vectors are reshaping competitive positioning.
Robotic sortation systems are modularizing parcel handling workflows at high-velocity cross-docks. E-commerce fulfillment networks are deploying these systems at 40% of new greenfield facilities. This technology is modularizing the traditional fixed-conveyor infrastructure into reconfigurable cell-based layouts that adapt to seasonal volume swings.
The EPA and NHTSA joint rulemaking on heavy-duty vehicle efficiency is mandating annual fleet-wide improvements through 2032. Equipment manufacturers must certify powertrain combinations against stricter test cycles. California-based fleet operators are pre-buying compliant tractors ahead of federal deadlines to secure allocation.
Shippers are consolidating vendor relationships around integrated line-haul providers who control both asset and network visibility. This pattern displaces the traditional broker-heavy procurement model in the retail vertical. The Texas-California lane exhibits this concentration most acutely, with top-10 shippers awarding multi-year dedicated contracts.
Middle Mile Delivery Market Segmentation
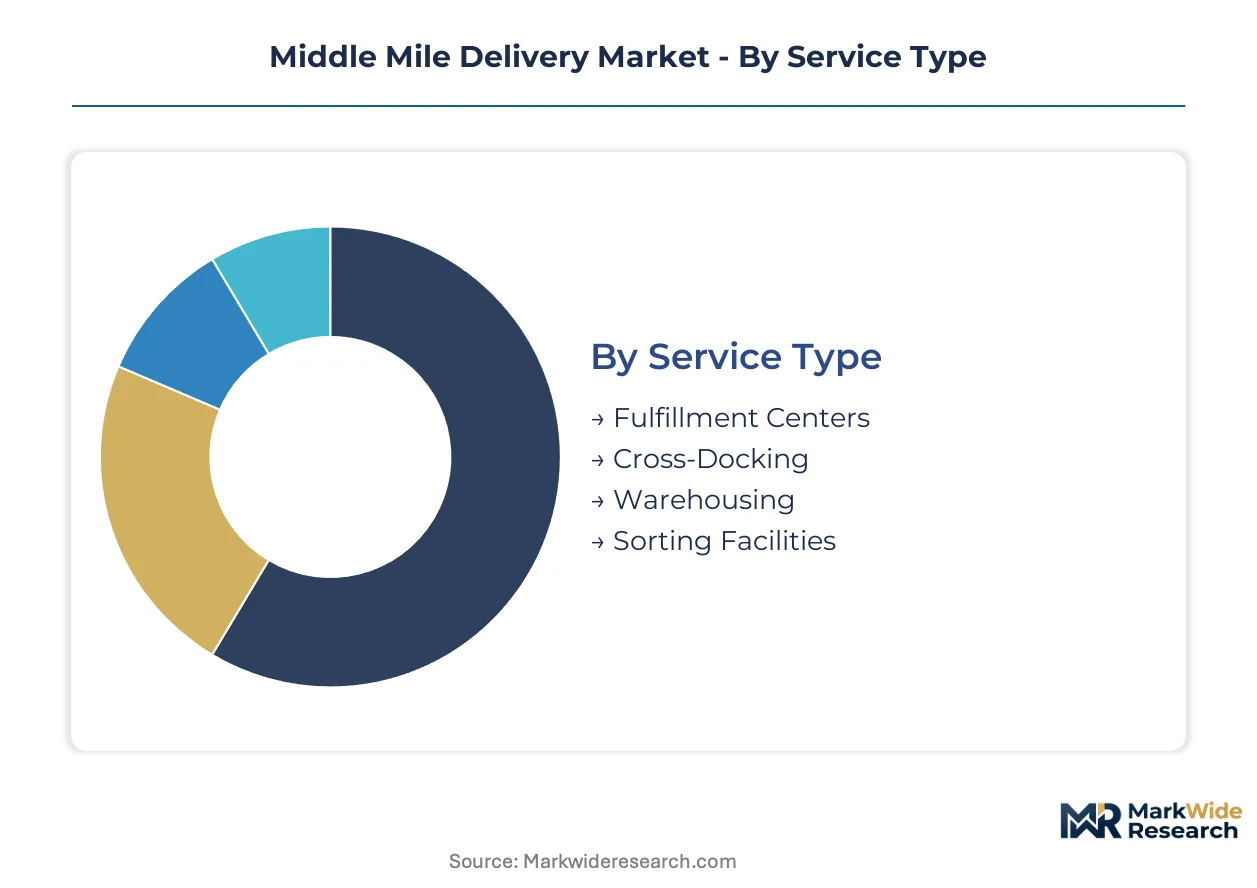
Middle mile delivery operators configure assets differently depending on freight velocity requirements and corridor distance. Segmentation reveals where capital concentrates most heavily and which service tiers command premium pricing.
Service Type:
Capital intensity varies sharply across facility types, with automated sortation infrastructure demanding the highest upfront investment per square foot.
- Cross-Docking:Goods transfer directly between inbound and outbound vehicles with minimal storage dwell. E-commerce platforms concentrate demand in the Texas-California corridor where drayage-to-intermodal handoffs compress transit windows. The EPA Phase 3 standards are accelerating electrification of yard tractors at these high-velocity nodes.
- Sorting Facilities:Parcel-level consolidation hubs deploy robotic cell-based layouts that reconfigure for seasonal volume swings. Investment concentrates in greenfield e-commerce fulfillment networks where modular automation replaces fixed conveyor infrastructure.
- Fulfillment Centers:Inventory-holding nodes buffer stock for last-mile distribution.
- Warehousing:Longer-term storage assets serve wholesale and manufacturing replenishment cycles.
Most installed capacity flows through Cross-Docking. Expansion is steepest in Sorting Facilities.
Transport Mode:
Operating cost structures diverge by distance threshold, with mode selection hinging on fuel differentials and corridor-specific infrastructure availability.
- Trucking:Door-to-door flexibility dominates the 100-to-500-mile band where drayage costs erode intermodal savings. California's Advanced Clean Trucks rule is compressing fleet replacement cycles for operators serving multi-state e-commerce networks.
- Intermodal:Rail-truck combinations capture margin above 500 miles where fuel cost spreads justify terminal handoffs. The I-10 and I-20 corridors lack sufficient megawatt charging infrastructure, forcing hybrid configurations on electrified line-haul pilots.
- Rail:Bulk and containerized freight moves on dedicated corridors.
- Air Freight:Time-definite cargo serves pharmaceutical and high-value electronics verticals.
Trucking carries the highest asset base. Intermodal is climbing the fastest as rail electrification pilots advance.
Technology:
Software and automation layers attract disproportionate venture capital relative to physical infrastructure, compressing payback periods through labor substitution.
- Automation Tools:Robotic sortation and autonomous yard tractors reduce dwell times at cross-dock nodes. Deployment concentrates in new greenfield facilities where modular cell layouts replace legacy fixed-conveyor systems.
- Routing Software:Proprietary algorithms optimize hub-and-spoke sortation velocity and dynamic load matching. FedEx and integrated carriers leverage these systems to displace broker-heavy procurement models in retail verticals.
- Tracking Systems:Real-time visibility platforms integrate telematics from electric powertrains and autonomous subsystems.
- Inventory Management:Warehouse execution systems synchronize stock levels across distributed fulfillment networks.
Automation Tools command the steepest expansion trajectory. Routing Software retains the largest installed base.
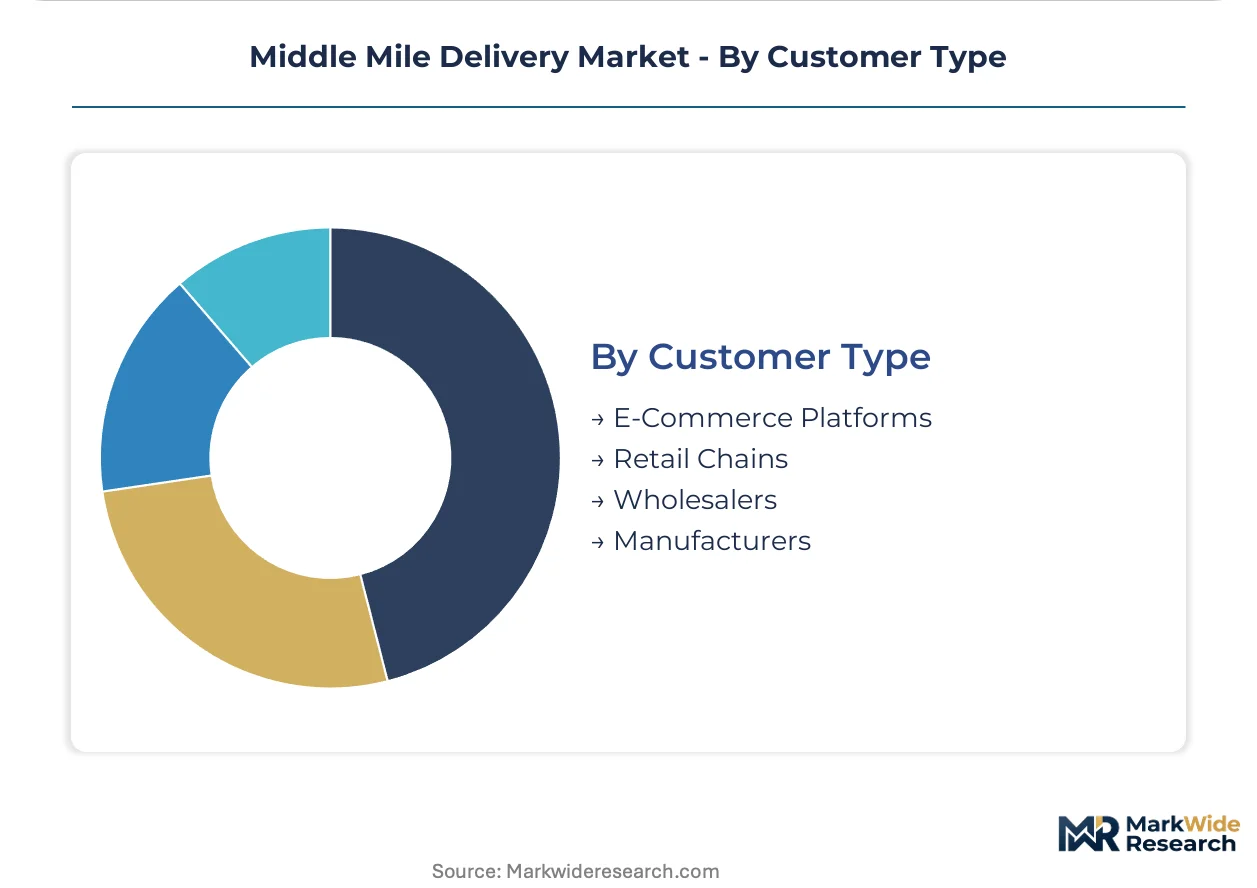
Customer Type:
Procurement patterns split between asset-heavy dedicated contracts and variable-cost brokered capacity, with consolidation favoring integrated providers.
- E-Commerce Platforms:Velocity-sensitive shippers are consolidating vendor relationships around line-haul providers controlling both assets and network visibility. The Texas-California lane exhibits this concentration most acutely, with multi-year dedicated contracts displacing spot-market procurement.
- Retail Chains:Seasonal volume swings drive demand for flexible cross-dock capacity and modular automation that adapts to peak periods.
- Wholesalers:Palletized freight moves through warehousing and deferred intermodal lanes.
- Manufacturers:Inbound supply chain coordination requires synchronized middle mile timing with production schedules.
E-Commerce Platforms anchor current volume. Retail Chains are gaining share fastest as seasonal automation investments scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The middle mile delivery industry traces its modern scale to the post-deregulation expansion of US intermodal networks during the 1980s, when rail-truck integration first enabled cost-efficient long-haul consolidation. That operational template now diffuses across freight corridors worldwide.
United States
E-commerce fulfillment networks and pharmaceutical cold chains drive middle mile investment across the Texas-California freight corridor. The EPA Phase 3 greenhouse gas standards compress fleet replacement cycles for Class 8 tractors operating on I-10 and I-20 lanes. Dallas-Fort Worth anchors the nation's largest inland port complex, where automated cross-docking facilities process drayage-to-intermodal handoffs.
Germany
Automotive just-in-sequence supply chains and chemical distribution networks sustain dense middle mile throughput across the Rhine-Ruhr industrial belt. The EU Green Deal and F-Gas Regulation mandate refrigerant transitions for temperature-validated intermodal assets serving pharmaceutical corridors. Hamburg's container terminals function as the primary North Sea gateway for electrified rail corridors extending to Milan and Warsaw.
China
Domestic e-commerce volume and manufacturing export flows concentrate middle mile demand along the Yangtze River Delta and Pearl River Delta corridors. MIIT dual carbon goals and GB standards for heavy-duty vehicle emissions accelerate fleet electrification timelines. Shanghai's Yangshan automated port integrates with dedicated freight rail corridors serving interior manufacturing clusters.
India
Pharmaceutical distribution networks and FMCG replenishment cycles expand middle mile infrastructure across the Delhi-Mumbai Industrial Corridor. The PLI scheme for logistics and warehousing subsidizes automated sortation investments at greenfield fulfillment centers. Gujarat's Mundra Port anchors a dedicated freight corridor with inland container depots at Ahmedabad and Vadodara.
Japan
Precision manufacturing supply chains and aging demographics intensify automation adoption across middle mile nodes. METI carbon neutrality roadmaps pressurize fleet operators toward hydrogen and battery-electric powertrains on Tokyo-Osaka corridors. Chubu Centrair International Airport anchors pharmaceutical air freight consolidation with temperature-controlled cross-dock facilities.
Middle Mile Delivery Market Competitive Landscape
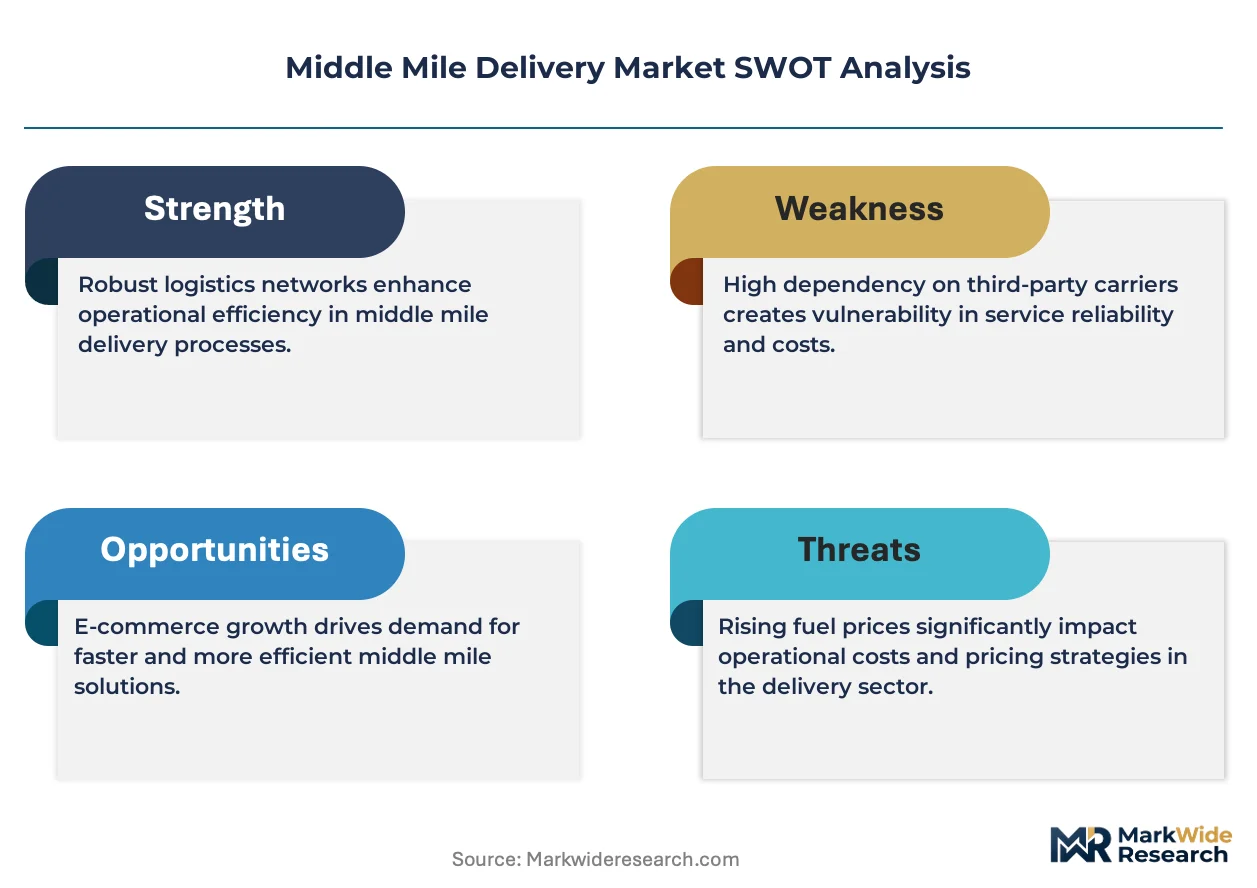
The competitive structure tilts toward integrated asset-and-network providers rather than broker-dependent intermediaries. Market concentration remains moderate, with top-tier operators controlling critical corridor density while regional specialists retain share in specialized temperature-controlled and time-definite segments. Two archetypes dominate: global integrated carriers with proprietary routing software and intermodal-heavy freight forwarders with rail corridor density. Competitive moves center on multi-year dedicated contract awards and electrified fleet pre-buying ahead of regulatory deadlines.
Within the integrated carrier tier, FedEx Corporation and United Parcel Service anchor North American hub-and-spoke networks with proprietary sortation velocity optimization. Kuehne + Nagel International AG represents the intermodal-forwarder archetype, leveraging density across rail corridors to sustain cost advantages in long-haul lanes. These three occupy positions that exemplify the strategic divergence between asset-heavy parcel integration and asset-light freight forwarding with corridor-specific scale.
| Leading Market Players |
|---|
| Kuehne + Nagel International AG |
| DB Schenker |
| United Parcel Service (UPS) |
| Nippon Express |
| C.H. Robinson Worldwide Inc. |
| DHL Supply Chain |
| DSV Panalpina A/S |
| CEVA Logistics |
| FedEx Corporation |
| Others |
Supply & Pricing Matrix
Certified electric-tractor technicians in the Dallas-Fort Worth metroplex command wage premiums that compress margin spreads between premium dedicated-contract pricing and standard brokered-rate tiers. Labor-cost differentials across the Texas-California corridor directly widen the pricing gap between asset-heavy integrated providers and variable-cost intermediaries.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates temperature-validated pharmaceutical lanes from general merchandise cross-docks and spot-market brokerage. Price differentiation hinges on EPA Phase 3 compliance certification and real-time visibility integration. Pricing pressure stems from battery-energy-density constraints forcing hybrid configurations on longer corridors. E-commerce platforms exhibit highest price sensitivity, while pharmaceutical distributors accept premium tiers for validated cold-chain assurance.
Supply Chain Analysis
Domestic-content mandates under California's Advanced Clean Trucks rule and the US EPA Phase 3 standards are reshaping tractor and trailer sourcing toward North American assembly. Supply concentrates in the United States, Mexico, and China for battery cells, electric drivetrains, and automated sortation components. Lithium-ion cells, lidar perception systems, and robotic sortation modules anchor raw material dependencies. Single-source vulnerability in semiconductor chips for telematics integration threatens equipment delivery schedules. Distribution runs through manufacturer-direct fleet sales and third-party equipment lessors serving multi-state operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle Mile Delivery Market represents a late-cycle quality story as pharmaceutical cold-chain specifications and EPA compliance certification displace commodity brokerage relationships. Demand is concentrating around providers with electrified asset bases and validated temperature infrastructure.
For Market Incumbents: To counter autonomous-yard-tractor entrants, deepen backward integration into charging infrastructure along the I-10 and I-20 corridors and secure multi-year dedicated contracts with top-10 e-commerce shippers before regulatory deadlines compress fleet replacement windows. For New Entrants and Emerging Players: Launch via temperature-validated intermodal services targeting pharmaceutical distribution networks in Europe where the EU F-Gas Regulation has created compliance-driven demand for lower-emission refrigerated rail assets and premium service tiers. For Investors and Strategic Acquirers: Integrated line-haul providers with proprietary routing software are the most active acquirer in this space, consolidating broker-heavy procurement models. Target mid-cap operators controlling dense rail corridor access in the Texas-California lane. Watch for inflection when megawatt charging station deployment accelerates on electrified corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Fleet Pre-Buying | California's Advanced Clean Trucks rule compresses procurement timelines for EPA Phase 3 compliance. |
| Autonomous Yard Tractor Deployment | Lidar-equipped electric tractors reduce dwell times at Dallas-Fort Worth cross-dock facilities. |
| Temperature-Validated Intermodal Expansion | EU F-Gas Regulation mandates lower-emission refrigerants for pharmaceutical rail corridors. |
| Proprietary Routing Software Investment | FedEx and UPS leverage hub-and-spoke optimization to displace broker-heavy retail procurement. |
| Rail Electrification Corridor Pilots | BNSF and Union Pacific test catenary-powered segments on the Los Angeles-Chicago lane. |
Research Methodology
Bottom-up e-commerce fulfillment modeling reconciled against top-down fleet asset tracking forms the analytical core of this study. Primary interviews with fleet procurement directors, cross-dock operations managers, rail corridor planners, and EPA regulatory compliance officers combined with secondary validation from FMCSA hours-of-service filings, EPA certification databases, SEC 10-K equipment disclosures, and customs drayage volume records. Triangulation across these sources anchors market sizing.
Input-output matrices map tractor deployment, charging infrastructure buildout, and cross-dock automation adoption across the projection horizon. Segmentation dimensions include service type, transport mode, technology layer, and customer vertical, with CAGRs derived from equipment replacement cycle analysis and regulatory mandate timelines. Freight volume correlations with e-commerce penetration rates and pharmaceutical cold-chain expansion inform trajectory assumptions.
Several conditions sit outside the modeled scope, including autonomous over-the-road trucking deployment timelines beyond yard tractors and potential battery chemistry breakthroughs altering range economics. Forecasts reflect assumptions about regulatory enforcement consistency and charging infrastructure funding continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market
Logistics and Shipping
Asia Pacific Domestic Courier Market
Logistics and Shipping
Spain 3PL Market
Logistics and Shipping
Halal Logistics Market
Logistics and Shipping
Air Freight Market
Logistics and Shipping
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
Germany Same Day Delivery Market
Logistics and Shipping
China Same Day Delivery Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
Germany Express Delivery Market