
 Automotive Fuel Supply System Market | 2026-2036
Automotive Fuel Supply System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fuel Supply System Market Analytics
Aftermarket service revenue is reconfiguring margin capture away from pure hardware sales across the automotive fuel supply system value chain. Robert Bosch GmbH leverages its injection technology leadership to sustain high-margin aftermarket parts flows. Denso Corporation anchors Asian OEM supply relationships through captive manufacturing scale. Continental AG competes on integrated pump-injector platforms that reduce assembly complexity for vehicle assemblers.
An automotive fuel supply system encompasses the complete assembly of pumps, injectors, tanks, filters, and pressure regulators that store, filter, meter, and deliver fuel to internal combustion engines at operating pressures typically ranging from 3 bar in port injection to over 200 bar in gasoline direct injection systems. Its primary commercial purpose is to ensure precise fuel metering, emission compliance, and safe containment across varying thermal and vibration environments. Gasoline direct injection technology leads value generation due to its compatibility with downsized turbocharged engines, while hybrid systems represent the fastest-growing technology segment as mild-hybrid architectures proliferate. Passenger vehicles occupy the dominant application position, though heavy-duty vehicles sustain premium pricing for high-pressure common-rail diesel components.
The US EPA enforces Tier 3 emission standards that limit particulate matter and evaporative hydrocarbon losses, directly shaping injector precision requirements and fuel tank permeation specifications. In Europe, the F-Gas Regulation and REACH compliance frameworks constrain material choices for seals and coatings in fuel system components. India's BIS and the PLI scheme for automotive manufacturing are accelerating localized fuel system production capacity. Stakeholders must monitor regulatory divergence between emission jurisdictions and calibrate platform standardization strategies accordingly.
Market Dynamics
Gasoline direct injection systems are compressing port fuel injection architectures across passenger vehicle platforms as turbocharged downsized engines become the dominant powertrain configuration. This technology migration is forcing wholesale recalibration of pump pressure specifications, injector nozzle geometries, and fuel rail material selections throughout the supply base.
Growth Catalysts
- EPA Tier 3 standards:Tightened evaporative emission limits are mandating upgraded fuel tank permeation barriers and enhanced vapor recovery systems across US vehicle fleets.
- Hybrid architectures:Mild-hybrid powertrains require sophisticated fuel pressure modulation for engine restart optimization, expanding addressable component value per vehicle.
- Vietnam manufacturing:Compact car and motorcycle production scaling in industrial zones around Ho Chi Minh City is generating concentrated demand for cost-optimized fuel system modules.
Market Restraints
- High-pressure component costs:Precision-machined piezoelectric injectors and stainless steel fuel rails carry material cost premiums that compress margins on entry-level vehicle segments.
- Supplier concentration:Critical pump and injector subassemblies remain captive to German and Japanese tier-one suppliers, creating single-source vulnerability for second-tier assemblers.
- Battery electric substitution:Zero-emission vehicle mandates in California and the EU are eroding long-term addressable market for combustion-optimized fuel system components.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for automotive manufacturing are accelerating localized fuel system component capacity in Tamil Nadu and Gujarat industrial corridors.
- Aftermarket sensor integration:Connected fuel pressure monitoring modules represent unpenetrated white space for telematics-enabled predictive maintenance services.
- Common-rail diesel retrofit:Heavy-duty fleet operators in Southeast Asia are upgrading aging mechanical injection systems to meet Euro 6 equivalent standards.
Industry Challenges
- Calibration engineering scarcity:Specialized expertise in high-pressure injection spray pattern optimization remains concentrated within incumbent supplier engineering centers.
- Multi-jurisdiction certification:Simultaneous EPA, Euro 6, and BIS homologation requirements extend product development timelines and testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fuel Supply System Market |
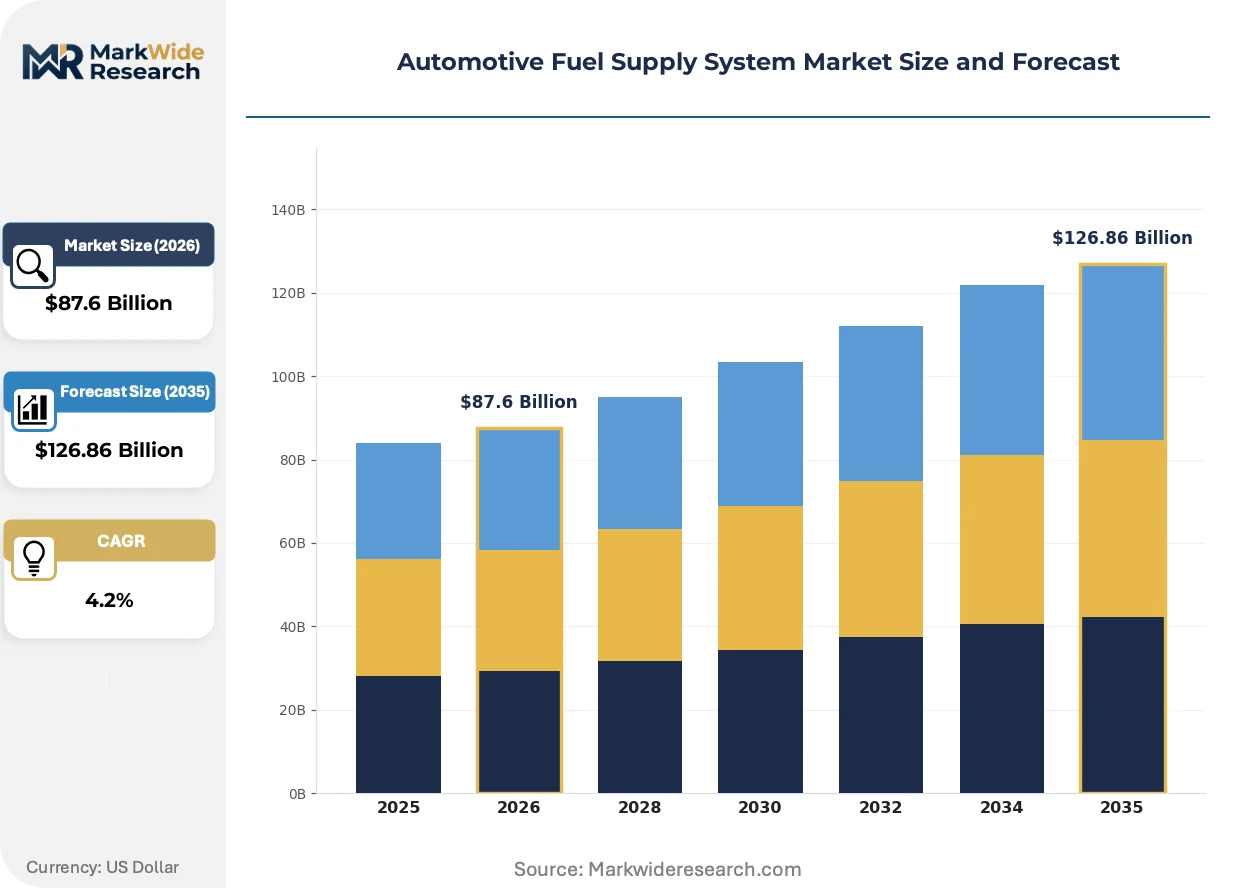
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $126.86 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Pumps, Injectors, Fuel Tanks, Filters Technology: Gasoline, Diesel, Alternative Fuels, Hybrid Systems Application: Passenger Vehicles, Light Commercial Vehicles, Heavy-Duty Vehicles, Electric Vehicles End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, Plastic Omnium, YAPP Automotive Systems Co., Ltd., TI Automotive, Delphi Technologies, Hitachi Astemo Ltd., Magneti Marelli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fuel Supply System Market Evolving Landscape
Digital twin simulation and additive manufacturing are compressing fuel system prototyping cycles while enabling topology-optimized component geometries previously unachievable through conventional machining. These capabilities are redrawing competitive boundaries between integrated system suppliers and specialized component manufacturers.
Electrohydraulic fuel injectors with integrated pressure sensors are rendering obsolete mechanically actuated solenoid designs across premium passenger vehicle segments. BMW and Mercedes-Benz powertrain divisions have completed platform transitions to fully electronic injection control. This shift is rendering obsolete legacy injector calibration equipment and service tooling throughout the aftermarket channel.
REACH substance restrictions on perfluorinated seal materials are compelling fuel system manufacturers to qualify alternative elastomer compounds for high-pressure rail connections. ECHA's 2023 update to Annex XVII constrained specific fluoropolymer grades previously standard in GDI applications. European suppliers are accelerating validation of hydrogenated nitrile rubber formulations to maintain compliance without performance degradation.
Fleet operators are unbundling fuel system maintenance from comprehensive service contracts and contracting directly with authorized component remanufacturers. This disintermediation of traditional dealership service channels is compressing parts margin capture for vehicle OEMs while expanding addressable revenue for independent remanufacturing specialists. The pattern is most pronounced in German commercial vehicle fleets operating under total cost of ownership procurement frameworks.
Automotive Fuel Supply System Market Segmentation
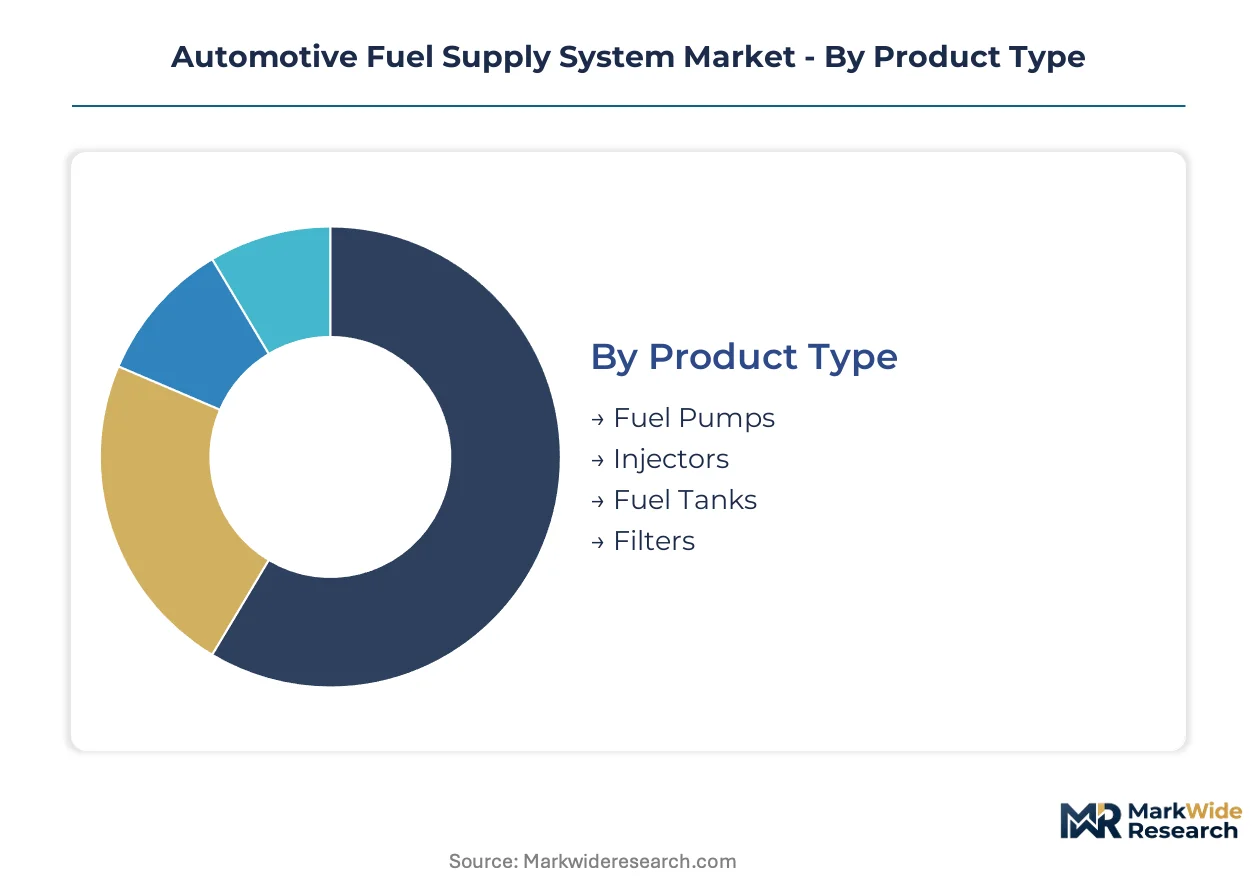
Segmentation in automotive fuel supply systems reveals how technology migration and regulatory pressure are redrawing competitive boundaries across component categories. Understanding these divisions exposes where value capture concentrates and where substitution risks loom largest.
Product Type:
Mature mechanical components coexist with precision-electronic subsystems at radically different margin profiles.
- Injectors:Piezoelectric and solenoid-actuated nozzles meter fuel at pressures exceeding 200 bar in gasoline direct injection architectures. Demand clusters in German and Japanese premium passenger vehicle programs where EPA Tier 3 and Euro 6 standards mandate sub-millisecond spray control.
- Fuel Pumps:High-pressure GDI pumps and in-tank electric modules generate recurring aftermarket revenue through wear-item replacement cycles. Southeast Asian light commercial fleets are expanding procurement of cost-optimized pump assemblies as vehicle production scales in Vietnam and Indonesia.
- Fuel Tanks:Multi-layer HDPE and steel designs incorporate permeation barriers to contain evaporative hydrocarbon losses under tightened emission limits.
- Filters:Fine-mesh filtration media protect injector orifices from particulate contamination in common-rail diesel and GDI systems.
Injectors handle the majority of throughput; fuel pumps are expanding most quickly on share as hybrid architectures proliferate.
Technology:
Cost tiers separate established combustion technologies from emerging hybrid configurations.
- Gasoline:Port fuel injection retains volume in entry-level segments while direct injection dominates turbocharged downsized engines. EPA Tier 3 sulfur limits and evaporative emission caps are forcing wholesale recalibration of injector spray patterns and fuel rail materials.
- Hybrid Systems:Mild-hybrid architectures require sophisticated pressure modulation for engine restart optimization, expanding component value per vehicle. India's PLI scheme for automotive manufacturing is accelerating localized production capacity for hybrid-optimized fuel modules in Tamil Nadu and Gujarat corridors.
- Diesel:High-pressure common-rail systems sustain premium pricing in heavy-duty applications where torque density requirements resist electrification.
- Alternative Fuels:Compressed natural gas and liquefied petroleum gas conversions demand specialized tank and pressure regulator configurations.
Gasoline technology commands the installed base; hybrid systems are gaining share fastest as electrification penetrates mainstream vehicle segments.
Application:
Volume concentration in passenger vehicles contrasts with margin premium in heavy-duty specialization.
- Passenger Vehicles:Downsized turbocharged engines and GDI penetration dominate component specification across compact, mid-size, and premium segments. Euro 6 emission standards and REACH substance restrictions are compelling material transitions in seals and coatings for high-pressure rail connections.
- Heavy-Duty Vehicles:Common-rail diesel injection sustains elevated pricing for precision-machined components operating at extreme pressures. Fleet operators in Southeast Asia are retrofitting aging mechanical systems to meet Euro 6 equivalent standards, generating concentrated aftermarket demand.
- Light Commercial Vehicles:Cost-optimized fuel system modules serve high-utilization delivery and logistics fleets.
- Electric Vehicles:Battery electric powertrains eliminate conventional fuel system content, representing long-term substitution risk for combustion-optimized suppliers.
Passenger vehicles absorb the dominant share of component output; heavy-duty applications deliver the steepest margin trajectory.
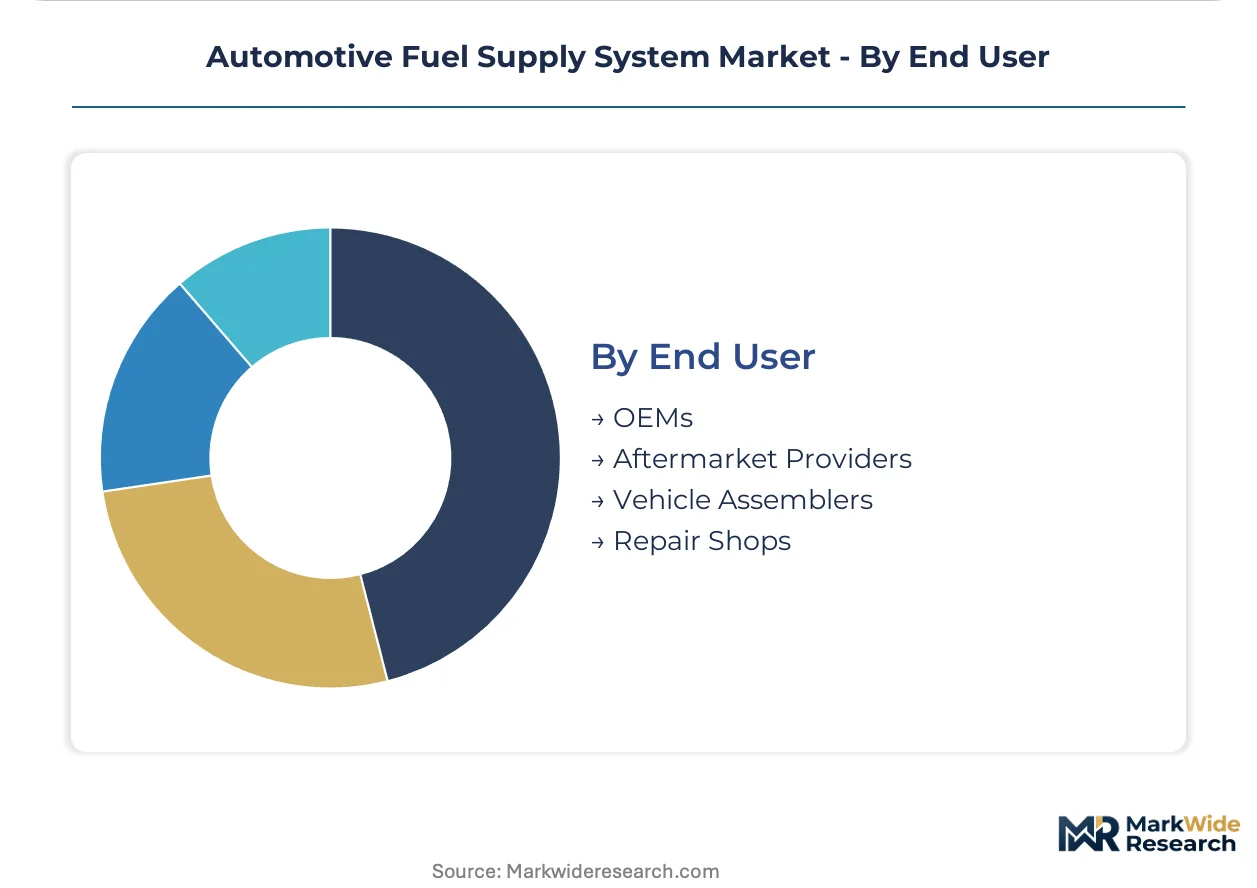
End User:
Supply concentration in OEM channels diverges from margin recapture opportunities in fragmented aftermarket structures.
- OEMs:Captive supply relationships with tier-one system integrators lock in multi-year platform specifications and volume commitments. Robert Bosch GmbH and Denso Corporation anchor these channels through injection technology leadership and Asian manufacturing scale.
- Aftermarket Providers:Independent remanufacturing specialists and authorized component distributors are capturing disintermediated service revenue as fleet operators unbundle maintenance from dealership contracts. German commercial vehicle fleets operating under total cost of ownership frameworks are driving this pattern most aggressively.
- Vehicle Assemblers:Integrated pump-injector platforms reduce assembly complexity and inventory carrying costs at final assembly plants.
- Repair Shops:Legacy injector calibration equipment faces obsolescence as electrohydraulic designs with integrated pressure sensors render mechanical solenoid service tooling obsolete.
OEMs command the majority of volume throughput; aftermarket providers are climbing the fastest on margin capture as service channels fragment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Southeast Asia and India exhibit acute price sensitivity for entry-level fuel system modules, while German and Japanese OEMs absorb substantial premiums for precision injection components. This demand-elasticity contrast shapes regional procurement patterns and supplier margin structures across the value chain.
United States
Light truck and SUV production volumes sustain robust demand for gasoline direct injection systems as turbocharged downsized engines dominate powertrain portfolios. EPA Tier 3 emission standards mandate upgraded fuel tank permeation barriers and enhanced vapor recovery systems. Detroit's automotive corridor concentrates injection technology R&D and high-pressure pump manufacturing capacity.
Germany
Premium passenger vehicle programs anchor European demand for piezoelectric injectors operating above 200 bar pressure thresholds. REACH substance restrictions and the F-Gas Regulation compel material transitions away from perfluorinated seal compounds. Stuttgart and Munich industrial zones host captive engineering centers specializing in spray pattern optimization for Euro 6 compliance.
China
Domestic brand expansion and joint venture production scale drive procurement of cost-optimized fuel pump assemblies and plastic fuel tank modules. MIIT fuel consumption regulations and GB standards for evaporative emissions tighten component specifications. Yangtze River Delta manufacturing clusters around Shanghai concentrate injection system assembly capacity for both local and export markets.
India
Motorcycle and compact car production scaling generates concentrated demand for affordable port fuel injection and carburetor replacement systems. BIS emission norms and the PLI scheme for automotive manufacturing accelerate localized fuel system component capacity. Tamil Nadu and Gujarat industrial corridors attract tier-one supplier investments in pump and injector module production.
Vietnam
Light commercial vehicle fleet expansion and two-wheeler manufacturing drive procurement of simplified fuel system architectures. Domestic content requirements and ASEAN harmonized emission frameworks shape supplier qualification protocols. Industrial zones surrounding Ho Chi Minh City concentrate cost-optimized fuel module assembly for regional export markets.
Automotive Fuel Supply System Market Competitive Landscape
Integrated system architects and specialized component fabricators split the market along capability-depth versus scale-efficiency lines. German and Japanese tier-one suppliers dominate high-pressure injection technology through decades of cumulative engineering investment. Three strategic archetypes prevail: full-system integrators owning complete pump-injector-rail portfolios; captive component specialists serving single OEM relationships; and emerging Asian scale players competing on manufacturing cost. Consolidation pressure intensifies as electrification shrinks addressable combustion-component markets and forces portfolio diversification into thermal management and hydrogen systems.
Among the integrated system tier, Robert Bosch GmbH anchors European and North American OEM supply relationships through injection technology leadership. Denso Corporation exemplifies the captive-scale archetype with deep manufacturing presence across Asian industrial corridors. Continental AG occupies a position bridging full-system integration with modular platform architectures. These three entities represent the competitive center of gravity against which mid-tier specialists and regional challengers calibrate positioning strategies.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| Plastic Omnium |
| YAPP Automotive Systems Co., Ltd. |
| TI Automotive |
| Delphi Technologies |
| Hitachi Astemo Ltd. |
| Magneti Marelli |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta port congestion and Red Sea routing disruptions compress margins on precision-machined injector subassemblies bound for European OEM assembly plants. These freight dynamics amplify pricing power for German and Japanese tier-one suppliers while forcing cost-optimized tier-two assemblers in Vietnam and India to absorb logistics premiums or surrender share.
Pricing Analysis
Aftermarket service contracts and remanufactured component streams now generate lifetime value multiples exceeding original equipment hardware sales. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales bundling intensity. Cost compression in entry-level gasoline direct injection modules is intensifying because Vietnamese and Indian OEM procurement teams enforce aggressive target costing. Fleet operators in Southeast Asia exhibit acute price sensitivity, while German premium passenger vehicle programs absorb substantial premiums for piezoelectric injector platforms.
Supply Chain Analysis
Stainless steel bar stock and piezoelectric ceramic substrates feed from German, Japanese, and Chinese specialty materials suppliers into high-pressure pump and injector machining centers. Precision-machined fuel rails and electrohydraulic actuator assemblies draw from captive manufacturing in Stuttgart, Nagoya, and Shanghai industrial zones. Single-source vulnerability for piezoelectric stack elements creates structural risk if geopolitical restrictions disrupt ceramic substrate flows. Distribution runs through tier-one system integrators delivering complete pump-injector-rail modules to final vehicle assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected fuel pressure monitoring and predictive maintenance services expand addressable revenue per vehicle faster than combustion hardware sales as electrification shrinks the installed base. This service-attach opportunity reconfigures margin capture toward recurring telemetry-enabled revenue streams.
For Market Incumbents: Entrench aftermarket channel control by acquiring authorized remanufacturing specialists and deploying proprietary diagnostic tooling that locks out independent repair shops. Battery electric substitution in California and EU markets threatens long-term addressable volume for combustion-optimized portfolios; backward integration into hydrogen fuel system thermal management preserves engineering relevance through the transition.
For New Entrants and Emerging Players: Build out localized pump assembly capacity in Tamil Nadu and Gujarat industrial corridors to capture India PLI scheme incentives and serve motorcycle and compact car OEM procurement. Common-rail diesel retrofit demand among Southeast Asian heavy-duty fleet operators represents the most penetrable white-space segment; partner with established aftermarket distributors to bypass captive tier-one supply relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core fuel system component divisions facing electrification headwinds. Long-term viability hinges on portfolio pivot toward thermal management and hydrogen injection systems; monitor California Air Resources Board zero-emission vehicle mandate acceleration as the critical inflection signal for combustion component demand trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces injector calibration complexity for OEMs serving multiple emission jurisdictions simultaneously. |
| Backward Integration into Piezoelectric Ceramics | Secures supply of critical actuator materials against ECHA REACH substance restrictions and export controls. |
| Software-Defined Injection Control | Enables over-the-air spray pattern updates for EPA Tier 3 and Euro 6 compliance without hardware swaps. |
| Geographic Manufacturing Footprint Expansion | Localizes production in Vietnam and Indonesia to serve ASEAN light commercial vehicle fleet growth. |
| Aftermarket Telematics Partnership | Captures predictive maintenance revenue from fleet operators unbundling service from dealership contracts. |
Research Methodology
Desk research of vehicle production databases, IHS Markit registration data, and regulatory filing repositories preceded structured interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel heads, and dealership service operations managers. Primary intelligence on injection technology roadmaps and hybrid architecture fuel system specifications was cross-validated against EPA, ECHA, and BIS technical documentation. Bottom-up component demand modeling and top-down vehicle production forecasts were triangulated to establish market sizing boundaries.
Assumptions held fixed include current EPA Tier 3 and Euro 6 emission standard stringency levels, mild-hybrid powertrain penetration trajectories, and observed tier-one supplier market shares across the projection horizon. Segmentation dimensions modeled encompass vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from regression analysis of historical vehicle production correlations with fuel system component bill-of-materials intensities, incorporating input from injection spray pattern optimization engineering centers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity addition by emerging Asian scale players or accelerated California zero-emission vehicle mandate enforcement would shift outcomes materially. Cross-checking against IEA automotive technology deployment benchmarks and S&P Global Mobility powertrain forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Key Blanks Market
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
Racing Vehicles Market
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Clutch Pedal Kit Market
Automotive Parts
Motorcycle Aluminum Casting Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Automotive Thermal Management Systems for Electric Vehicles Market
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
Automotive Aluminium Extrusion Market