
 Germany Same Day Delivery Market | 2026-2036
Germany Same Day Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Same Day Delivery Market Foresight
Asset-light fleet leasing and pay-per-route financing models are narrowing the capital barrier for new entrants in German same-day logistics. DHL Group leverages its nationwide sorting infrastructure to sustain next-day-to-same-day conversion at scale. Flink specializes in dark-store-based grocery delivery, occupying dense urban zones with 15-minute service windows. Amazon Logistics competes through algorithmic route optimization and captive demand from its marketplace.
Germany same-day delivery encompasses time-definite logistics services completing shipment fulfillment within 24 hours of order placement, typically requiring real-time inventory positioning, dynamic routing engines, and multi-modal last-mile handoff. Express delivery commands premium pricing for urgent B2B documents and medical specimens, while on-demand delivery through mobile apps is displacing scheduled windows among younger demographics. E-commerce retailers anchor volume demand, though pharmaceutical suppliers represent the fastest-growing customer type as cold-chain same-day certification becomes standard for biologics distribution.
Germany's LKW-Maut toll system, EU Green Deal transport targets, and KBA vehicle emissions standards collectively mandate fleet electrification and CO2 reporting across logistics operators. The Bundesnetzagentur oversees delivery service reliability metrics that shape operator licensing and consumer protection enforcement. Stakeholders must monitor how Berlin and Munich municipal micromobility ordinances restrict or expand cargo bike access to pedestrian zones, as these local rules will determine network density achievable in Germany's highest-value delivery corridors.
Market Dynamics
Electrification mandates under the EU Green Deal and Germany's LKW-Maut tolling system are compressing diesel fleet economics and forcing capital reallocation toward electric vans and cargo bikes.
Growth Catalysts
- Pharmaceutical Cold-Chain Urgency:Biologics distributors are adopting temperature-controlled same-day certification to meet patient treatment windows, expanding service premiums for certified operators.
- Rhine-Ruhr Density Economics:The metropolitan corridor's 10+ million residents within 100 kilometers enables sub-2-hour fulfillment at unit costs viable for mass-market penetration.
- KBA Emissions Standards:Fleet renewal cycles are accelerating as Euro VI diesel restrictions tighten, creating replacement demand for zero-emission vehicles with integrated telematics.
Market Restraints
- Last-Mile Labor Scarcity:Driver recruitment in dense urban cores faces competition from ride-hailing platforms, compressing wage structures and inflating per-stop costs.
- Charging Infrastructure Gaps:Depot electrification requires grid upgrades that Bundesnetzagentur permitting timelines delay by 18-24 months in tertiary cities.
- Dark Store Real Estate:Zoning restrictions in Berlin and Munich limit micro-fulfillment center placement, forcing operators into higher-rent commercial corridors.
Strategic Opportunities
- Rural Pharmacy Networks:Underserved regions in Mecklenburg-Vorpommern and Saxony-Anhalt present first-mover potential for scheduled same-day medical deliveries.
- Reverse Logistics Integration:Return-to-sender services for apparel retailers remain fragmented, offering margin expansion through consolidated pickup routing.
- Micromobility Lane Expansion:Municipal ordinances in Hamburg and Cologne are widening cargo bike access to pedestrian zones, reducing final-100-meter friction.
Industry Challenges
- Telematics Interoperability:Fleet operators struggle to integrate legacy warehouse management systems with real-time dynamic routing engines.
- Driver Retention Systems:High churn among gig-economy couriers demands investment in predictive scheduling algorithms and earnings-guarantee programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Same Day Delivery Market |
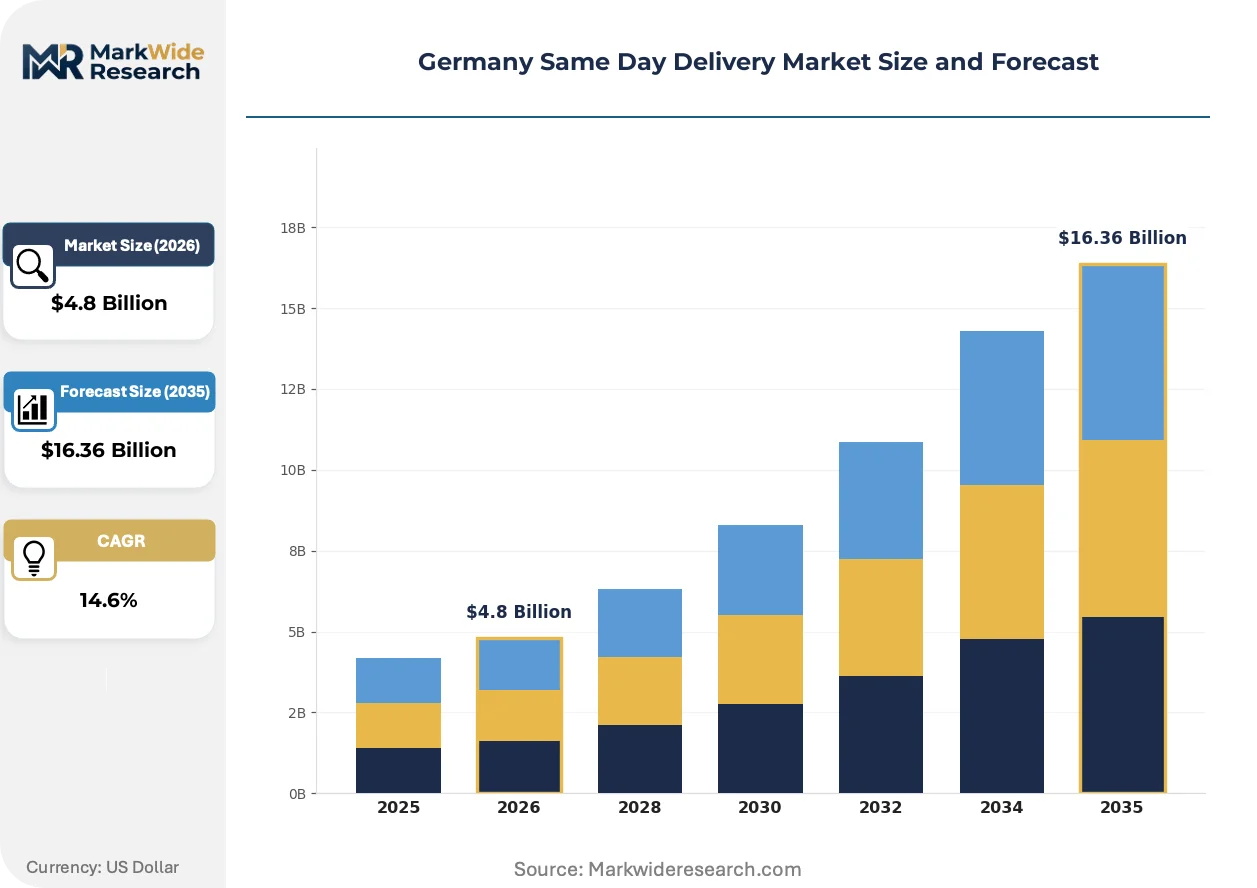
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Scheduled Delivery, Courier Delivery, On-Demand Delivery, Contactless Delivery Customer Type: E-commerce Retailers, Food Delivery Platforms, Pharmaceutical Suppliers, Corporate Clients, Small Businesses Distribution Channel: Mobile Apps, Websites, Call Centers, Third-Party Platforms, Direct Sales Vehicle Type: Bicycles, Motorbikes, Vans, Electric Scooters, Drones |
| Companies Covered | DHL Group, GLS, DPD, Hermes, Amazon Logistics, UPS, DODO, Flink, Otto Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Same Day Delivery Market Shifts & Advancements
Algorithmic dispatch and predictive inventory positioning are compressing fulfillment windows from next-day to same-day and sub-hourly service tiers.
Dynamic route optimization software is digitizing dispatch decisions across German logistics networks. Mid-size operators in Stuttgart and Frankfurt are adopting cloud-based platforms that ingest real-time traffic, weather, and order-flow data. This capability is digitizing what were previously static morning-route plans into continuously adjusted sequences that reduce per-delivery costs.
Germany's LKW-Maut truck tolling system and EU Green Deal transport targets are mandating CO2 reporting and fleet electrification. Operators must now document emissions per shipment, creating compliance overhead that favors integrated telematics providers. Pharmaceutical and grocery segments are responding fastest, as their customer contracts increasingly require carbon-disclosure appendices.
Younger demographics are abandoning scheduled delivery windows for on-demand app-based ordering. Mobile-first fulfillment is displacing phone-based and web-form scheduling in urban centers, with expectation-setting shifting from "arrives Tuesday" to "arrives in 47 minutes." This pattern concentrates in Berlin and Munich, where density supports sub-30-minute grocery and pharmacy delivery.
Germany Same Day Delivery Market Segmentation
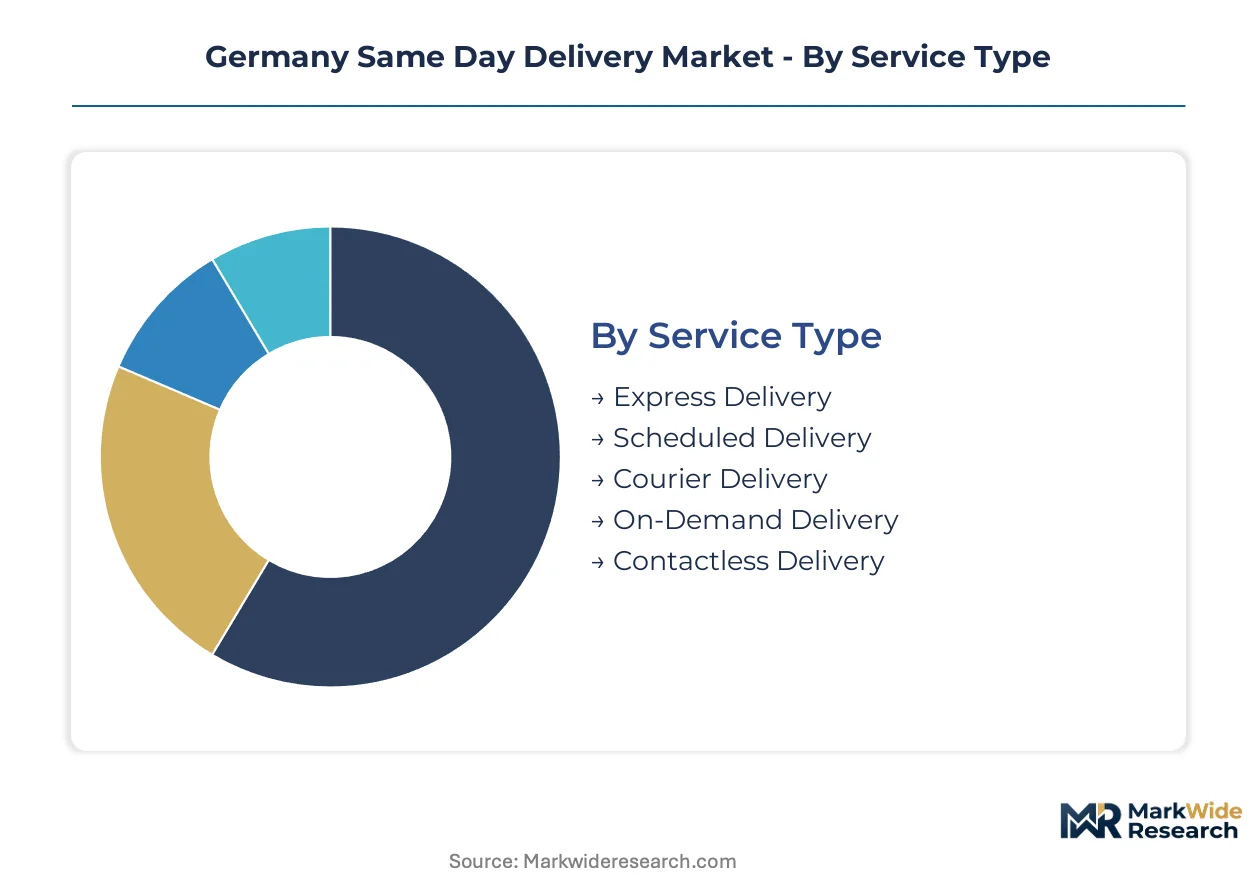
Segmentation in German same-day logistics reveals how service intensity, customer urgency, and fleet configuration intersect to determine unit economics. Operators must match service tiers to customer willingness-to-pay while navigating KBA emissions standards and municipal micromobility rules that constrain vehicle choice.
Service Type:
After-sales-service intensity varies dramatically across service tiers, with pharmaceutical and B2B segments demanding proactive exception management and real-time temperature monitoring.
- Express Delivery:Time-definite service guarantees completion within 2-4 hours using dedicated vehicle allocation and priority sorting at DHL hubs. Corporate document and medical specimen flows concentrate demand in Frankfurt and Munich financial districts, where KBA-certified cold-chain vehicles command premium positioning.
- Scheduled Delivery:Pre-booked windows consolidate orders into optimized routes, reducing per-stop costs through density. E-commerce retailers in the Rhine-Ruhr corridor leverage this tier for non-urgent replenishment, balancing speed against fulfillment expense.
- Courier Delivery:White-glove handling with signature capture and installation support serves high-value electronics and luxury goods. Demand clusters in Hamburg's affluent suburbs where customers pay for personalized handoff.
- On-Demand Delivery:Sub-60-minute fulfillment through gig-economy couriers dominates grocery and pharmacy apps in Berlin and Munich. Flink and similar operators deploy dark-store networks to sustain 15-minute service windows.
- Contactless Delivery:Photo-verified drop-off with digital proof-of-delivery expanded during pandemic protocols and persists for privacy-sensitive customers. Residential apartment complexes in Cologne and Stuttgart drive adoption.
By volume, Scheduled Delivery leads. By growth pace, On-Demand Delivery is ahead.
Customer Type:
Cost tier differentiation separates enterprise accounts with annual contracts from transactional small-business users paying per-shipment premiums.
- E-commerce Retailers:Volume anchors requiring API-integrated order management and returns processing. Amazon Marketplace sellers and Zalando merchants generate predictable density that justifies dedicated fleet allocation.
- Food Delivery Platforms:Peak-demand volatility demands elastic labor pools and thermal bag standardization. Lieferando and Wolt compete on rider retention through guaranteed earnings floors.
- Pharmaceutical Suppliers:Temperature-controlled same-day certification for biologics and vaccines represents the steepest expansion trajectory. Boehringer Ingelheim and regional pharmacy wholesalers invest in GDP-compliant fleets.
- Corporate Clients:B2B document and parts exchange requires SLA-backed reliability with penalty clauses. Automotive suppliers in Baden-Württemberg depend on morning-critical delivery for just-in-sequence production.
- Small Businesses:Fragmented demand aggregated through multi-tenant platforms, paying per-route premiums without volume discounts. Artisan producers in Bavaria use third-party platforms for national reach.
By revenue concentration, E-commerce Retailers dominate. By margin expansion, Pharmaceutical Suppliers are climbing the fastest.
Distribution Channel:
Application-specific interfaces determine customer acquisition cost and order frequency, with mobile-first platforms displacing traditional booking methods among demographics under 40.
- Mobile Apps:Native iOS and Android applications with push notification tracking and one-tap reordering. Berlin and Munich urbanites generate 70%+ of grocery and pharmacy volume through this channel.
- Websites:Desktop and mobile web portals retaining importance for B2B procurement workflows and elderly customers. Corporate clients in Frankfurt maintain web-based dashboards for multi-user account management.
- Call Centers:Voice-based booking persists for pharmaceutical deliveries to rural patients and accessibility-required users. Saxony-Anhalt and Mecklenburg-Vorpommern regions show disproportionate call-center share.
- Third-Party Platforms:Aggregator marketplaces like Check24 and Idealo route delivery requests to competing operators. Price transparency intensifies margin pressure on smaller carriers.
- Direct Sales:Field account teams secure enterprise contracts with customized SLAs and dedicated support lines. DHL Group and DB Schenker deploy this channel for multinational manufacturing accounts.
By transaction volume, Mobile Apps lead. By contract value retention, Direct Sales is gaining share fastest.
Vehicle Type:
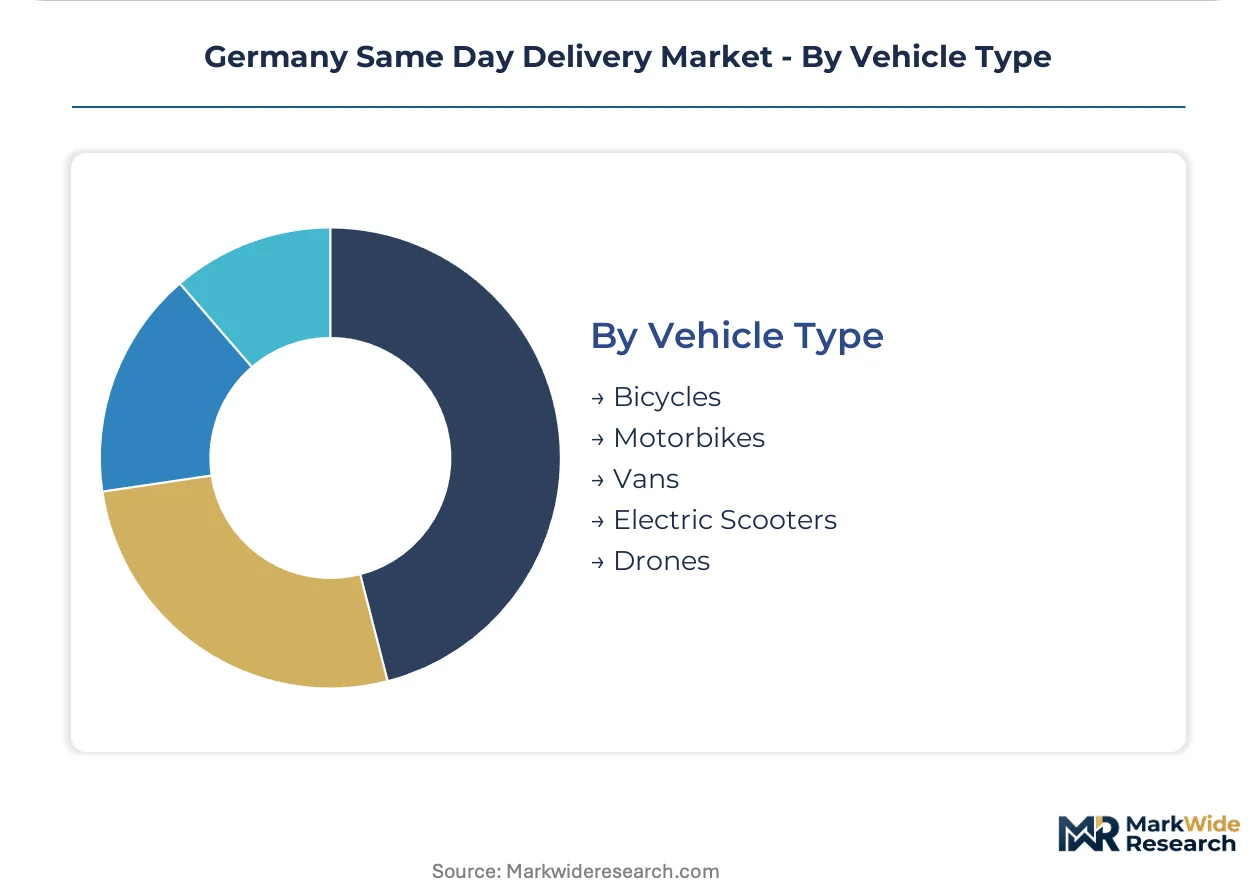
Geography dictates fleet composition, with municipal micromobility ordinances in Hamburg and Cologne expanding cargo bike access while LKW-Maut tolling compresses diesel van economics.
- Bicycles:Human-powered cargo bikes with 150kg payload capacity dominate Berlin's pedestrian zones and zero-emission districts. Municipal lane expansion in Cologne reduces final-100-meter friction.
- Motorbikes:Internal-combustion two-wheelers retain share in tertiary cities where charging infrastructure remains sparse. Leipzig and Dresden couriers favor 125cc scooters for speed-distance balance.
- Vans:Sprinter-class vehicles handle consolidated multi-stop routes and temperature-controlled pharmaceutical loads. Euro VI diesel restrictions under KBA standards accelerate electric van replacement cycles.
- Electric Scooters:Compact e-mopeds bridge the gap between bicycles and vans for solo-item urgent delivery. Düsseldorf operators deploy these for document exchange between corporate campuses.
- Drones:Beyond-visual-line-of-sight trials proceed under Bundesnetzagentur supervision for rural medical supply. Island communities in the North Sea represent testbed deployment.
By fleet count, Vans lead. By deployment growth, Bicycles are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA emissions standards and municipal micromobility ordinances are redistributing logistics investment across German sub-regions, with electrification mandates favoring dense urban corridors over peripheral areas.
North Rhine-Westphalia
The Rhine-Ruhr metropolitan corridor concentrates 10+ million residents within 100 kilometers, enabling sub-2-hour fulfillment economics. LKW-Maut tolling compresses diesel van margins, pushing operators toward electric fleets. Düsseldorf and Cologne anchor pharmaceutical distribution networks serving Benelux markets.
Bavaria
Munich's affluent suburbs generate premium demand for white-glove courier services and luxury goods handling. Municipal zoning restricts dark-store placement in historic districts, forcing micro-fulfillment into commercial peripheries. The city's pharmaceutical cluster drives cold-chain same-day certification adoption.
Baden-Württemberg
Automotive suppliers in Stuttgart depend on morning-critical same-day delivery for just-in-sequence production lines. KBA Euro VI restrictions accelerate fleet renewal toward electric Sprinter-class vehicles. The region's precision manufacturing base sustains high-value B2B document exchange volumes.
Berlin-Brandenburg
Berlin's zero-emission districts and expanded cargo bike lanes reduce final-100-meter friction for grocery and pharmacy apps. Younger demographics drive on-demand adoption, with 15-minute service windows displacing scheduled delivery. Call-center booking persists in Brandenburg's rural periphery for pharmaceutical deliveries.
Hamburg
The port city's logistics infrastructure supports cross-border express flows to Scandinavia. Municipal ordinances widening cargo bike access to pedestrian zones enable dense urban network deployment. Hamburg's affluent suburbs sustain premium courier demand for personalized handoff services.
Germany Same Day Delivery Market Competitive Landscape
On the supply side, the industry is consolidating around integrated postal incumbents, platform-native specialists, and captive retail logistics arms. Three strategic archetypes dominate: legacy postal operators with nationwide sorting infrastructure, dark-store-based grocery specialists, and marketplace-captive delivery networks. Competitive moves center on fleet electrification partnerships and API-integrated fulfillment platforms.
Among integrated postal operators, DHL Group exemplifies the infrastructure-heavy archetype leveraging hub-and-spoke networks for next-day-to-same-day conversion. Flink occupies the dark-store specialist tier, while Amazon Logistics represents the captive retail model. These three anchors illustrate how capital intensity, customer data access, and real estate positioning stratify competitive advantage.
| Leading Market Players |
|---|
| DHL Group |
| GLS |
| DPD |
| Hermes |
| Amazon Logistics |
| UPS |
| DODO |
| Flink |
| Otto Group |
| Others |
Supply & Pricing Matrix
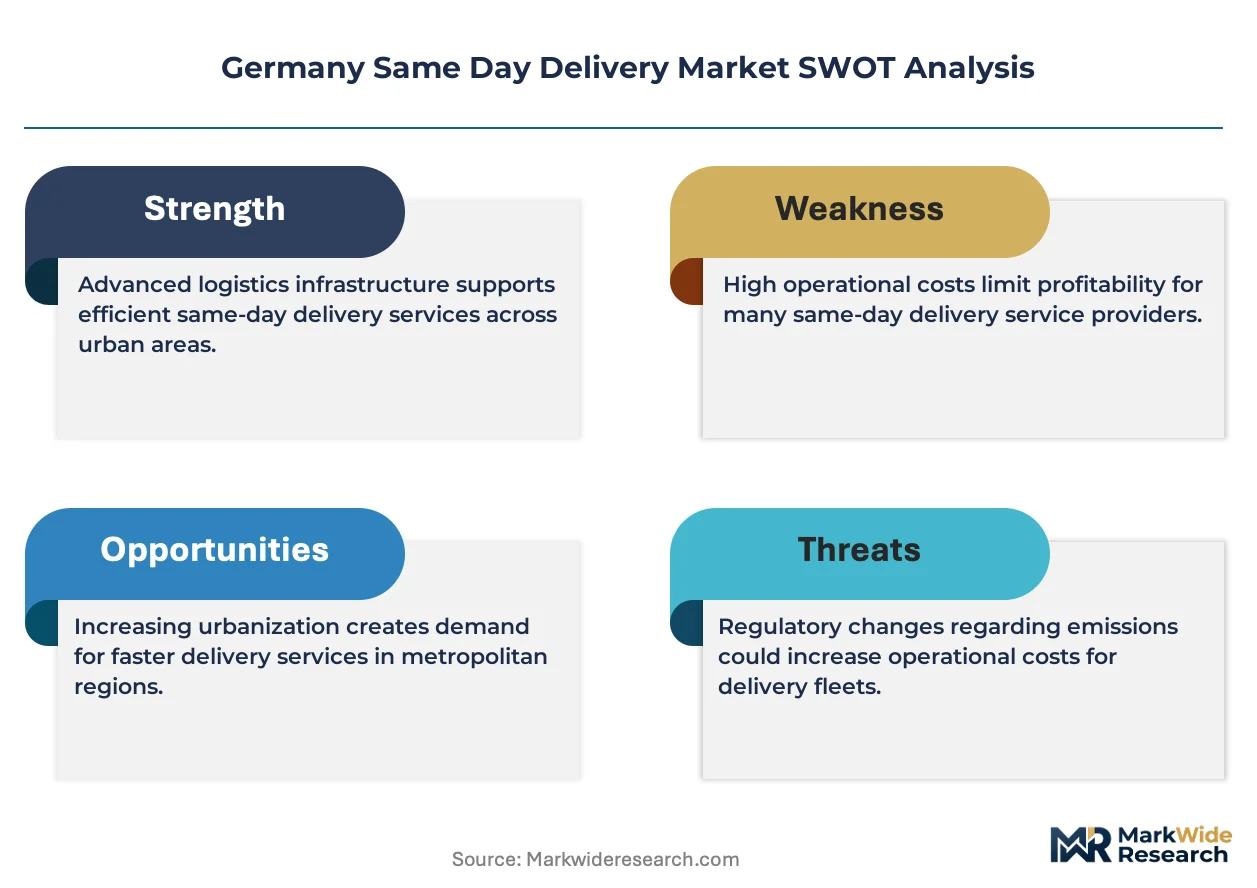
Depot undercapacity in Berlin and Munich is compressing slot availability for same-day operators, forcing fleet managers to bid up access fees while passing selective premiums to pharmaceutical and B2B customers with rigid delivery windows.
Pricing Analysis
Certification level creates the primary spread across German same-day tiers, with GDP-compliant cold-chain operators commanding substantial premiums over standard parcel services. Three-tier pricing structure across premium, standard, and economy levels segments the market: pharmaceutical biologics and urgent medical specimens anchor premium positioning, scheduled e-commerce replenishment occupies standard tiers, and gig-economy grocery runs compete on economy rates. Cost compression in the economy tier is intensifying because rider wage floors and electric vehicle depreciation outpace per-stop revenue growth. Small businesses and price-sensitive consumers in tertiary cities exhibit highest price elasticity, while corporate clients with SLA-backed contracts show lowest sensitivity.
Supply Chain Analysis
Extended payment terms from 30 to 90 days strain working capital for mid-size fleet operators, forcing reliance on supply-chain finance facilities from logistics-focused lenders. Vehicle manufacturing concentrates in Germany, Poland, and the Netherlands, with electric van assembly anchored in Stuttgart and Eindhoven. Battery cell supply draws from South Korean and Chinese producers, while telematics hardware sources from Taiwanese component specialists. Single-source vulnerability around lithium-ion battery supply creates exposure to commodity price swings and export licensing shifts. Distribution runs through hub-and-spoke networks with DHL sorting centers, Flink dark stores, and Amazon regional fulfillment nodes serving as downstream consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German same-day logistics functions as a service-attach play where recurring route contracts and temperature-controlled certification subscriptions expand faster than per-delivery transaction revenue.
For Market Incumbents: Pre-empt platform-native specialists by securing exclusive depot access in Rhine-Ruhr micro-fulfillment zones and accelerating KBA-certified electric fleet conversion ahead of Euro VII standards. Backward integration into charging infrastructure and driver retention systems defends margin position against asset-light entrants leasing vehicles on pay-per-route terms.
For New Entrants and Emerging Players: Pursue rural pharmacy networks in Mecklenburg-Vorpommern and Saxony-Anhalt where scheduled same-day medical delivery remains fragmented and incumbent coverage is sparse. White-space opportunity concentrates in GDP-compliant cold-chain certification for regional wholesalers, with go-to-market traction achievable through direct hospital system partnerships rather than platform aggregation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operators with pharmaceutical cold-chain certification and multi-year corporate SLA contracts. Long-term viability favors integrated postal-captive networks with nationwide sorting infrastructure over pure-play gig-economy models exposed to labor churn. Acquisition screens should prioritize fleet telematics integration depth and municipal micromobility permits in Berlin, Hamburg, and Cologne. The signal to monitor is Bundesnetzagentur enforcement actions on reliability metrics, which would accelerate consolidation toward licensed operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Dark Store Network Expansion | Municipal zoning wins in Düsseldorf and Frankfurt unlock sub-2-hour grocery economics. |
| Electric Fleet Conversion Partnership | KBA emissions compliance secures operating permits ahead of diesel restrictions. |
| GDP Certification Investment | Pharmaceutical customer contracts increasingly mandate cold-chain audit trails. |
| API-Integrated Fulfillment Platform | Zalando and Amazon Marketplace sellers demand real-time inventory positioning. |
| Cargo Bike Lane Access Negotiation | Hamburg and Cologne municipal ordinances determine final-100-meter network density. |
Research Methodology
Cross-validation between fleet operator interviews and Bundesnetzagentur regulatory filings anchors the qualitative findings on network reliability and emissions compliance timelines. Primary fieldwork engaged logistics procurement managers at pharmaceutical distributors, dark-store operations directors, municipal transport planners in Berlin and Munich, and gig-economy platform strategy leads. Secondary sources incorporated KBA vehicle registration databases, LKW-Maut toll revenue disclosures, EU Green Deal transport target documentation, and customs records for electric van import flows. Bottom-up route-density modeling and top-down market sizing triangulate volume estimates.
Calibration against historical fleet deployment patterns and municipal permitting timelines shapes the projection framework across the analysis window. Segmentation dimensions include service type, customer vertical, distribution channel, and vehicle propulsion architecture. CAGRs derive from logistic curve fitting to electrification adoption patterns and pharmaceutical cold-chain certification penetration. Industry-specific inputs encompass LKW-Maut toll rate schedules, KBA Euro VI/VII phase-in timelines, and cargo bike lane expansion announcements from Hamburg and Cologne transport authorities.
Sensitivities concentrate around Bundesnetzagentur enforcement stringency on reliability metrics, lithium-ion battery supply disruptions, and municipal zoning decisions on dark-store placement. Forecasts reflect documented assumptions on fleet electrification capex curves and pharmaceutical customer contract renewal rates. Macroeconomic contraction, regulatory acceleration, or autonomous delivery technology breakthrough would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Netherlands Freight and Logistics Market
Logistics and Shipping
Slovakia Freight and Logistics Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
Estonia Freight and Logistics Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
China Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Latin America Container Terminal Operations Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
Food Delivery Logistic Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Saudi Arabia Integrated Cold Chain Logistics Market
Logistics and Shipping
North America FMCG Logistics Market