
 Latin America Fourth Party Logistics (4PL) Market | 2026-2036
Latin America Fourth Party Logistics (4PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Fourth Party Logistics (4PL) Market Foresight
Buyer concentration in Latin American manufacturing is rebalancing as multinational automotive and electronics producers consolidate procurement under single 4PL orchestrators rather than fragmented 3PL contracts. Deutsche Post DHL anchors its regional network through integrated control-tower operations spanning Brazil and Mexico. Kuehne + Nagel differentiates via specialized pharmaceutical cold-chain compliance across Andean corridors. Gefco SA leverages its automotive heritage to dominate just-in-sequence production logistics for OEM plants in Puebla and São Bernardo do Campo.
Fourth Party Logistics denotes supply chain orchestration where a single entity manages and integrates all logistics resources, information flows, and strategic planning across multiple third-party providers without owning physical assets, functioning through real-time data analytics, vendor-neutral carrier allocation, and continuous network optimization to achieve total landed cost reduction. Inventory Management and Freight Forwarding segments command the deepest margin pools as shippers prioritize working-capital efficiency and customs-brokerage integration over commoditized transportation procurement. The Subscription-Based delivery model is gaining traction among large corporations seeking predictable operating expenditure structures for multi-year supply chain transformation programs.
Brazil's ANVISA pharmaceutical traceability mandates and Mexico's SAT customs digitization requirements are forcing 4PL providers to embed regulatory compliance modules directly into their control-tower platforms. Colombia's DIAN electronic invoicing integration and Chile's SII logistics documentation standards add further layers of cross-border data harmonization complexity. Stakeholders must evaluate whether to build captive regulatory technology capabilities or partner with specialized trade-compliance platforms as Latin American customs modernization accelerates.
Market Dynamics
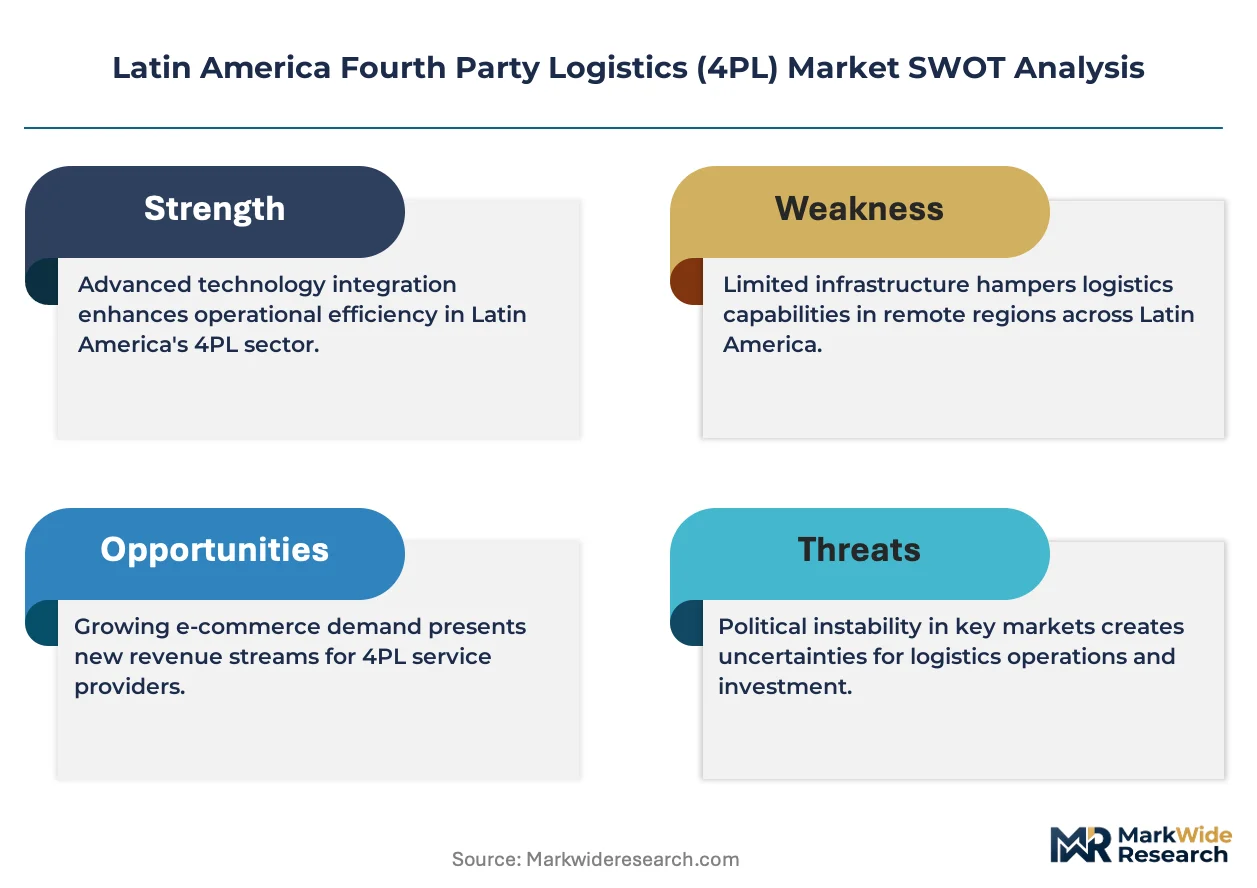
Latin American 4PL markets face structural pressure from customs digitization mandates that force orchestrators to rebuild control-tower architectures around real-time regulatory data feeds rather than retrospective compliance reporting.
Growth Catalysts
- Mexico's SAT customs digitization:Electronic manifest requirements are compelling automotive exporters to adopt integrated 4PL platforms for pre-arrival clearance coordination.
- Nearshoring manufacturing clusters:Electronics and medical device producers relocating from Asia to Baja California and Querétaro require synchronized multi-modal orchestration across US-Mexico corridors.
- Cold-chain pharmaceutical expansion:Temperature-sensitive biologics distribution across Andean corridors is driving demand for vendor-neutral carrier allocation with real-time monitoring.
Market Restraints
- Carrier market concentration:Brazil's domestic trucking sector remains dominated by fragmented owner-operator networks, limiting 4PL leverage in rate negotiations.
- Cross-border data infrastructure gaps:Inconsistent 4G/5G coverage across Paraguay-Uruguay corridors degrades real-time visibility for control-tower operations.
- Foreign exchange volatility:Argentine peso and Brazilian real fluctuations complicate multi-year contract structuring for subscription-based 4PL engagements.
Strategic Opportunities
- Colombia's Pacific port modernization:Buenaventura container terminal expansion creates white space for agribusiness export orchestration linking Cali industrial zones to Asian markets.
- Blockchain-IoT convergence:Immutable custody records combined with sensor telemetry enable pharmaceutical traceability compliance without redundant documentation layers.
- Peru's emerging lithium battery supply chain:Puno region extraction projects will require 4PL coordination for hazardous materials transport to Pacific export terminals.
Industry Challenges
- Control-tower talent scarcity:Supply chain data scientists fluent in Portuguese and Spanish command premium compensation, constraining provider scaling.
- Legacy ERP integration friction:SAP and Oracle systems deployed by Mexican automotive OEMs resist API-based connectivity with cloud-native 4PL platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Fourth Party Logistics (4PL) Market |
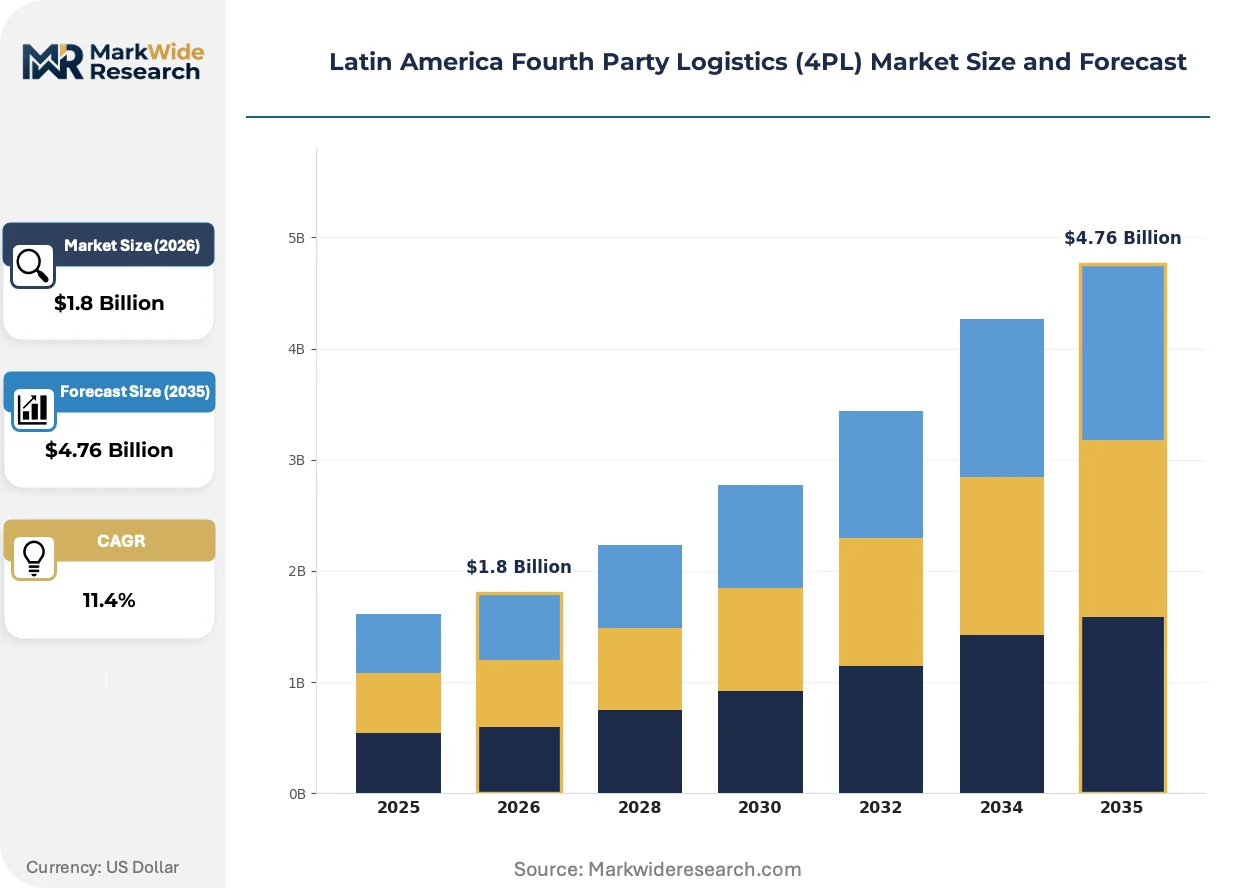
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Inventory Management, Freight Forwarding Industry Vertical: Automotive, Consumer Electronics, Pharmaceuticals, Food & Beverage Client Type: Small & Medium Enterprises, Large Corporations, Startups, E-commerce Delivery Model: On-Demand, Subscription-Based, Project-Based, Contractual |
| Companies Covered | Alonso Forwarding Colombia, PetroM Logistics, Deutsche Post DHL, Logifashion, Empresas Yoemar, Kuehne + Nagel, Points logistics Mexico SA de CV, Belog Integrated Logistics Solutions, Gefco SA, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Fourth Party Logistics (4PL) Market Shifts & Advancements
Distributed ledger architectures and predictive analytics are compressing decision cycles in Latin American supply chains, shifting competitive advantage from asset ownership toward algorithmic coordination capabilities.
Blockchain-enabled supply chain visibility is decentralizing trust mechanisms in cross-border pharmaceutical distribution. Brazilian and Mexican drug manufacturers are piloting permissioned networks for ANVISA and COFEPRIS traceability compliance. This architecture is decentralizing compliance verification away from centralized customs brokers toward automated smart-contract execution.
ANVISA's RDC 430 pharmaceutical serialization mandate forces 4PL providers to embed track-and-trace modules directly into control-tower platforms. The regulation mandates unit-level identification for high-risk medications circulating through Brazilian territory. Cold-chain specialists serving São Paulo state distribution hubs are prioritizing SAP ATTP integration over generic warehouse management systems.
Automotive assemblers in Puebla and São Bernardo do Campo are unbundling logistics procurement from long-term manufacturing agreements. Tier-1 suppliers now contract directly with 4PL orchestrators for just-in-sequence delivery, bypassing OEM-managed 3PL panels. This pattern concentrates most visibly among Japanese and German transplant manufacturers operating under lean production regimes.
Latin America Fourth Party Logistics (4PL) Market Segmentation
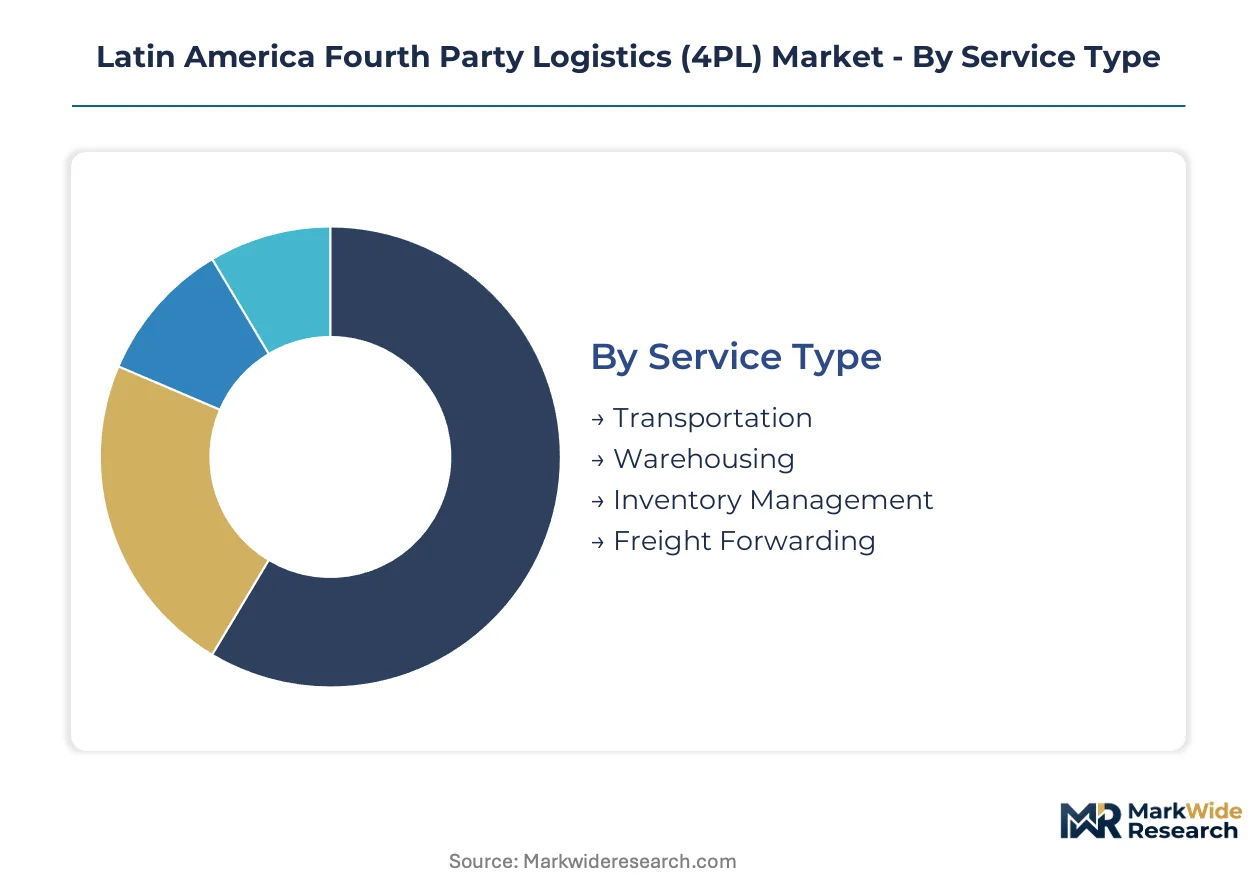
4PL orchestrators in Latin America configure service portfolios around divergent buyer maturity levels and asset ownership strategies. Pharmaceutical manufacturers and automotive OEMs demand fundamentally different control-tower architectures, forcing providers to modularize platform capabilities.
Service Type:
Buyer sophistication determines which service layers they internalize versus delegate to orchestrators.
- Transportation:Multi-modal coordination spanning Brazil's fragmented trucking networks and Mexico's rail corridors requires dynamic carrier allocation algorithms. São Paulo state automotive exporters prioritize this segment for just-in-sequence assembly line feeding.
- Inventory Management:Working capital optimization through demand sensing and safety stock positioning commands premium margins. Pharmaceutical distributors across Andean corridors adopt vendor-managed inventory structures to satisfy ANVISA traceability mandates.
- Warehousing:Network design and slotting optimization without asset ownership.
- Freight Forwarding:Customs brokerage integration with pre-arrival clearance coordination.
Volume sits with Transportation; growth tilts toward Inventory Management.
Industry Vertical:
Regulatory intensity and supply chain complexity separate vertical demand profiles.
- Pharmaceuticals:Temperature-controlled distribution with serialization compliance drives specialized 4PL engagement. Brazilian biologics manufacturers require ANVISA RDC 430 track-and-trace integration across cold-chain networks.
- Automotive:Lean production regimes demand synchronized inbound logistics and sequencing precision. Puebla and São Bernardo do Campo transplant OEMs unbundle logistics procurement from manufacturing agreements.
- Consumer Electronics:Nearshoring-driven volume with high velocity requirements.
- Food & Beverage:Shelf-life constraints and sanitary registry compliance.
Automotive commands current revenue concentration; Pharmaceuticals climbs the fastest.
Client Type:
Contract scale and platform integration depth vary dramatically across buyer size categories.
- Large Corporations:Multi-year transformation programs with control-tower deployment across regional manufacturing footprints. Mexican electronics and medical device producers relocating from Asia drive subscription-based engagement structures.
- E-commerce:Peak-season volatility and last-mile complexity require elastic orchestration capacity. Brazilian marketplace sellers demand real-time inventory visibility across São Paulo state distribution hubs.
- Small & Medium Enterprises:Modular service adoption with limited integration scope.
- Startups:On-demand flexibility without long-term platform commitment.
Large Corporations anchor contract value; E-commerce expands most quickly.
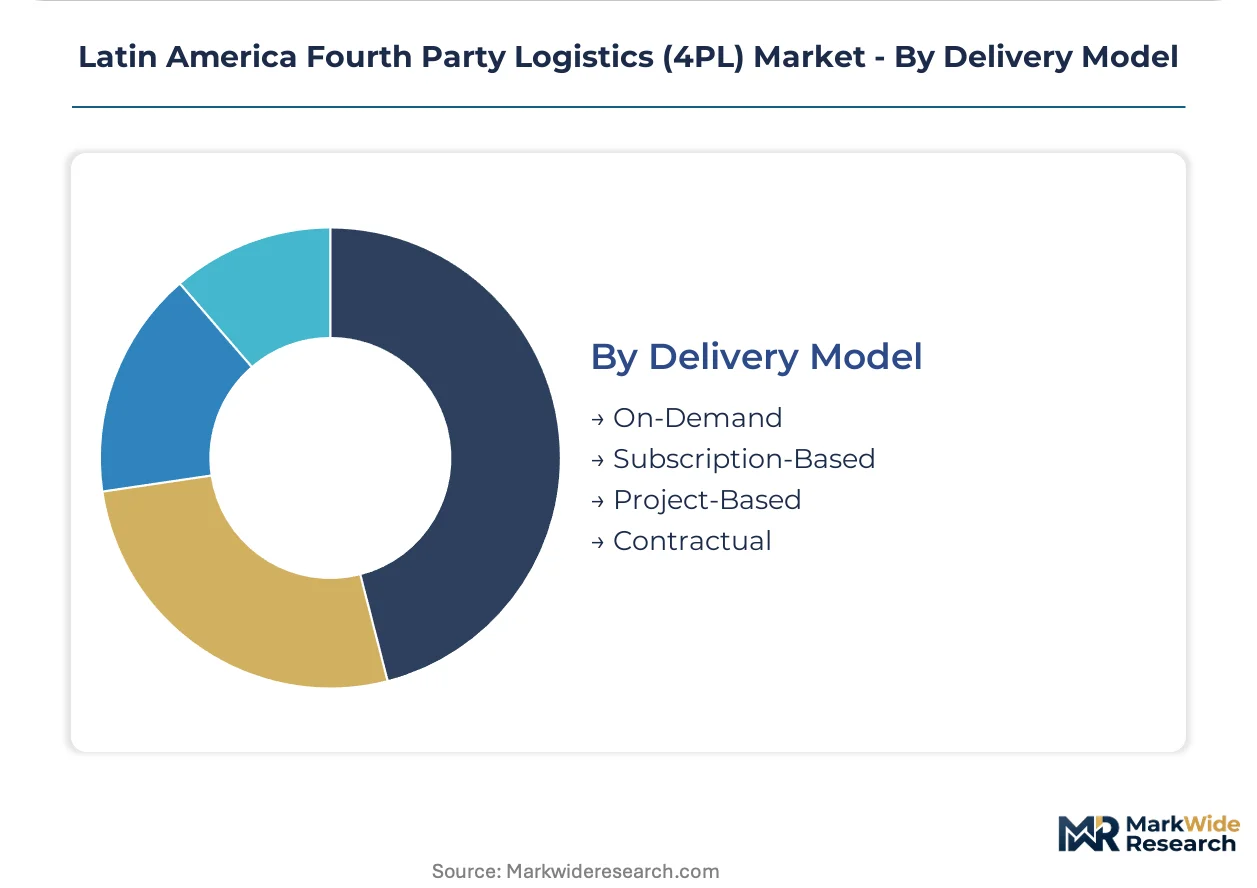
Delivery Model:
Pricing architecture and relationship duration reflect buyer risk tolerance and transformation ambition.
- Subscription-Based:Predictable operating expenditure structures for multi-year supply chain transformation programs. Large corporations favor this model for control-tower deployment and continuous network optimization.
- Contractual:Defined scope engagements with performance metrics and gain-sharing mechanisms. Automotive OEMs prefer this structure for just-in-sequence production logistics.
- On-Demand:Transactional access to orchestration capabilities without platform integration.
- Project-Based:Discrete transformation initiatives with finite duration.
Contractual models dominate current revenue; Subscription-Based gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's industrial corridor anchors Latin American 4PL demand through automotive and electronics export density. Mexican nearshoring clusters and Brazilian pharmaceutical distribution hubs concentrate orchestration requirements. Regional trade corridor expansion drives synchronized multi-modal coordination across Mercosur-aligned customs zones.
Brazil
Automotive exporters in São Bernardo do Campo and pharmaceutical distributors serving ANVISA-regulated cold chains dominate 4PL procurement. ANVISA's RDC 430 serialization mandate forces orchestrators to embed track-and-trace modules directly into control-tower platforms. São Paulo state distribution hubs prioritize SAP ATTP integration for biologics manufacturers requiring unit-level medication identification.
Mexico
Electronics and medical device producers relocating from Asia to Baja California and Querétaro drive subscription-based 4PL engagement structures. SAT customs digitization mandates electronic manifest requirements that compel automotive exporters toward integrated platforms for pre-arrival clearance coordination. Puebla transplant OEMs unbundle logistics procurement from manufacturing agreements, contracting tier-1 suppliers directly with orchestrators for just-in-sequence delivery.
Colombia
Agribusiness exporters linking Cali industrial zones to Asian markets through Buenaventura container terminal expansion create white space for orchestration services. DIAN electronic invoicing integration adds cross-border data harmonization complexity that 4PL providers must absorb into control-tower architectures. Pacific port modernization concentrates demand for synchronized multi-modal coordination across Andean corridor pharmaceutical distribution.
Chile
Lithium battery supply chain emergence from Puno region extraction projects will require hazardous materials transport coordination to Pacific export terminals. SII logistics documentation standards impose additional compliance layers on cross-border pharmaceutical distribution. Santiago-based pharmaceutical cold-chain specialists demand vendor-neutral carrier allocation with real-time temperature monitoring for biologics circulation.
Argentina
Consumer electronics importers and agricultural exporters face foreign exchange volatility that complicates multi-year contract structuring for subscription-based engagements. Mercosur-aligned customs modernization partially offsets peso fluctuation risks through standardized electronic documentation protocols. Buenos Aires distribution hubs concentrate fragmented owner-operator trucking networks that limit 4PL rate negotiation leverage.
Latin America Fourth Party Logistics (4PL) Market Competitive Landscape
Established logistics multinationals occupy the standard tier; emerging regional specialists pursue regulatory compliance differentiation through captive trade-technology capabilities. Market structure tilts toward consolidation as automotive OEMs and pharmaceutical manufacturers consolidate procurement under single orchestrators rather than fragmented 3PL panels. Three archetypes dominate: integrated control-tower operators, cold-chain compliance specialists, and automotive heritage players with just-in-sequence expertise. Competitive moves center on regulatory technology partnerships and multi-year subscription contract capture.
Among European-anchored logistics conglomerates, Deutsche Post DHL and Kuehne + Nagel exemplify divergent specialization strategies within the Latin American footprint. Deutsche Post DHL represents the integrated control-tower archetype spanning Brazil and Mexico through unified network operations. Kuehne + Nagel occupies a position emphasizing pharmaceutical cold-chain compliance across Andean corridors. Gefco SA, with French automotive heritage, anchors the just-in-sequence production logistics tier for OEM plants in Puebla and São Bernardo do Campo.
| Leading Market Players |
|---|
| Alonso Forwarding Colombia |
| PetroM Logistics |
| Deutsche Post DHL |
| Logifashion |
| Empresas Yoemar |
| Kuehne + Nagel |
| Points logistics Mexico SA de CV |
| Belog Integrated Logistics Solutions |
| Gefco SA |
| Others |
Supply & Pricing Matrix
Automotive OEM unbundling of logistics procurement from manufacturing agreements forces 4PL providers to restructure service bundles and absorb carrier rate volatility without passing full cost exposure to buyers. This demand-side consolidation concentrates pricing leverage among tier-1 suppliers contracting directly for just-in-sequence delivery.
Pricing Analysis
Warranty and compliance bundling separates premium 4PL engagements from transactional arrangements, with ANVISA traceability modules and SAT customs digitization integration commanding substantial premiums over baseline transportation management. Three-tier pricing structure across premium, standard, and economy levels reflects control-tower sophistication, regulatory technology embedding, and multi-modal coordination depth. Cost compression in the standard tier intensifies because carrier market fragmentation in Brazil limits orchestrator leverage. Small and medium enterprises exhibit highest price sensitivity, while large corporations prioritize predictable operating expenditure structures.
Supply Chain Analysis
Reverse logistics flows for pharmaceutical returns and temperature excursion products remain underdeveloped across Latin American corridors, creating liability exposure that 4PL providers must price into cold-chain engagements. Supply concentration centers on Brazil's São Paulo industrial corridor, Mexico's Baja California and Querétaro manufacturing clusters, and Colombia's Cali-Buenaventura agribusiness axis. Raw material dependencies span specialized reefer equipment, serialization hardware for ANVISA compliance, and cloud-native control-tower software licenses. Single-source vulnerability in carrier capacity during peak agricultural export windows strains network resilience. Distribution runs through hub-and-spoke configurations anchored at São Paulo and Mexico City distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Control-tower talent scarcity across Portuguese and Spanish fluency pools constrains provider scaling capacity, propping pricing power for incumbent orchestrators with established data science benches.
For Market Incumbents: Cement market position through captive regulatory technology development for ANVISA and SAT compliance modules, insulating against specialized trade-compliance platform partnerships. Deepen backward integration into pharmaceutical cold-chain infrastructure to defend margins against emerging cold-chain specialists. Prioritize multi-year subscription contract capture among nearshoring electronics manufacturers before competitive saturation. For New Entrants and Emerging Players: Regional trucking cooperatives represent the most penetrable channel partner type for gaining carrier allocation leverage in Brazil's fragmented owner-operator networks. Target Colombia's Pacific port modernization white space for agribusiness export orchestration linking Cali industrial zones to Asian markets. Pursue project-based engagements with lithium battery supply chain emergence in Peru's Puno region as proof-of-concept for hazardous materials coordination. For Investors and Strategic Acquirers: Re-rating potential sits with automotive heritage 4PL specialists given tier-1 supplier procurement unbundling acceleration across Puebla and São Bernardo do Campo transplant OEMs. Long-term viability favors providers with embedded regulatory technology capabilities rather than pure orchestration plays. Monitor SAT customs digitization implementation velocity and ANVISA RDC 430 enforcement rigor as inflection indicators for compliance-module demand.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Partnership | Embedding ANVISA and SAT compliance modules directly into control-tower platforms accelerates pre-arrival clearance coordination. |
| Multi-year Subscription Contract Capture | Predictable operating expenditure structures lock in large corporation transformation programs across nearshoring manufacturing clusters. |
| Cold-chain Infrastructure Investment | Specialized reefer capacity and temperature monitoring systems address biologics distribution requirements across Andean corridors. |
| Carrier Cooperative Integration | Dynamic allocation algorithms leverage fragmented Brazilian trucking networks through cooperative data sharing arrangements. |
| Blockchain-IoT Platform Deployment | Immutable custody records combined with sensor telemetry enable pharmaceutical traceability without redundant documentation layers. |
Research Methodology
Document review covered customs modernization directives, pharmaceutical serialization mandates, and automotive procurement pattern analyses, complemented by interviews with supply chain directors at multinational manufacturers, regulatory affairs leads at pharmaceutical distributors, control-tower operations managers at logistics providers, and procurement officers at tier-1 automotive suppliers. Secondary validation drew from ANVISA regulatory filings, SAT electronic manifest documentation, Mercosur trade statistics, and cloud logistics platform technical specifications. Bottom-up service segment sizing and top-down macroeconomic anchoring provided triangulation.
Segment-level demand modeling produced volume and value trajectories across the projection horizon, with service type, industry vertical, client category, and delivery model dimensions constituting the analytical framework. CAGRs derived from regression analysis against manufacturing output, trade corridor expansion, and regulatory implementation schedules. Forecast inputs incorporated nearshoring relocation velocity, pharmaceutical cold-chain compliance cost curves, and control-tower platform adoption rates.
Caveats apply where Argentine peso volatility, Brazilian carrier market fragmentation, or cross-border data infrastructure gaps could materially shift the outlook. Practitioners should monitor SAT electronic manifest enforcement timelines, ANVISA RDC 430 audit frequency, and 4G/5G corridor coverage expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Canada Cold Chain Logistics Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Multicarrier Shipping Software Market
Logistics and Shipping
Germany Automotive 3PL Market
Logistics and Shipping
Asia Pacific (APAC) Contract Logistics Market
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
Latin America Logistics Market
Logistics and Shipping
Spain Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
Halal Logistics Market
Logistics and Shipping
Air Freight Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
Singapore Last Mile Delivery Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market