
 Brazil Courier, Express, and Parcel (CEP) Market | 2026-2036
Brazil Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Courier, Express, and Parcel (CEP) Market Insights
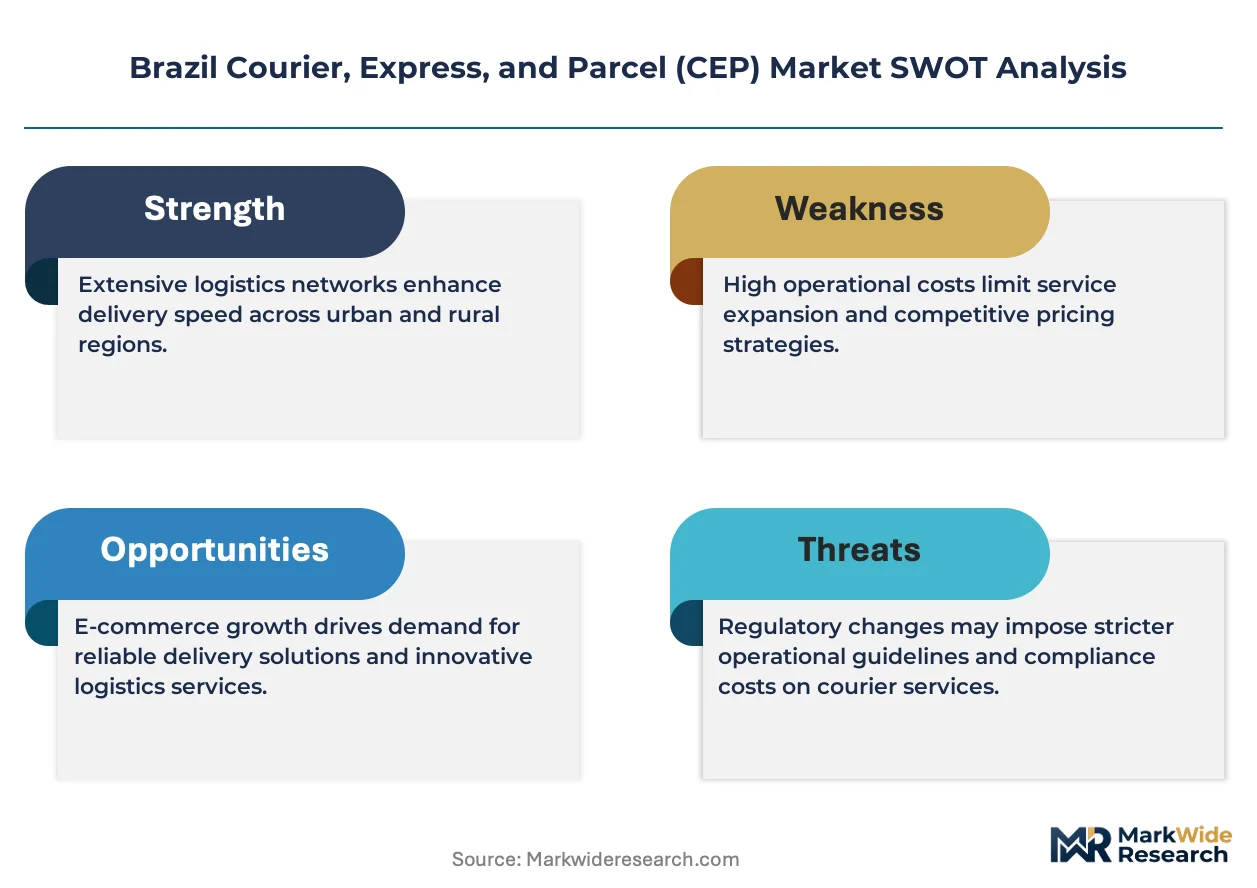
ANVISA's pharmaceutical cold-chain mandates and the National Transport Agency's freight digitization requirements are consolidating compliance costs for new entrants in Brazil's CEP sector. Correios anchors universal service obligations through its postal monopoly infrastructure across municipalities. DHL Group leverages temperature-controlled capabilities to sustain premium positioning in healthcare logistics. Loggi competes on algorithmic route density in metropolitan corridors.
Courier, Express, and Parcel services constitute time-definite freight movement encompassing document exchange, e-commerce fulfillment, and industrial parts distribution through integrated hub-and-spoke networks with GPS-tracked vehicles and electronic proof-of-delivery systems. Same-Day Delivery and Next-Day Delivery segments capture premium margin pools from pharmaceutical and electronics verticals requiring temperature integrity and chain-of-custody documentation. Ground transport dominates volume throughput due to Brazil's continental road infrastructure, while air freight concentrates in time-critical B2B corridors connecting manufacturing zones.
ANVISA enforces sanitary surveillance protocols for biopharmaceutical shipments, while the National Transport Agency regulates multimodal operator licensing and digital freight platform transparency. The Brazilian Consumer Defense Code imposes strict reverse-logistics obligations on e-commerce merchants, directly expanding parcel return volumes. Stakeholders must monitor impending carbon-emission disclosure rules from the Ministry of Environment and Climate Change that will reshape fleet procurement criteria and last-mile electrification timelines.
Market Dynamics
ANVISA's pharmaceutical cold-chain mandates and the National Transport Agency's freight digitization requirements are consolidating compliance costs for new entrants while forcing incumbent operators to reconfigure last-mile infrastructure across Brazil's metropolitan corridors.
Growth Catalysts
- E-commerce platform expansion:Digital marketplace fulfillment networks are intensifying last-mile density requirements in São Paulo and Rio de Janeiro, creating volume economies for parcel operators with urban hub positioning.
- ANVISA biopharmaceutical mandates:Temperature-controlled logistics requirements for vaccine and biologic distribution are expanding premium service tiers with specialized handling protocols.
- Marco Civil da Internet enforcement:Digital freight platform liability standards are professionalizing last-mile contractor relationships and accelerating formal employment structures in gig delivery networks.
Market Restraints
- Fuel cost volatility:Diesel price fluctuations directly compress ground transport margins, with road freight accounting for the dominant volume share across Brazil's continental distances.
- Correios infrastructure concentration:Universal postal service obligations and last-mile access to municipalities below 10,000 inhabitants create asymmetric competition for private operators.
- Customs clearance friction:Receita Federal import processing delays at São Paulo-Guarulhos and Viracopos air hubs extend international express transit times beyond competitive thresholds.
Strategic Opportunities
- Northeast corridor underpenetration:Salvador, Recife, and Fortaleza e-commerce penetration lags Southeast benchmarks, offering first-mover advantages for fulfillment center placement.
- Reverse logistics mandate expansion:Brazilian Consumer Defense Code obligations on e-commerce merchants are structurally expanding parcel return volumes and specialized collection infrastructure.
- Electrification incentives:Pending carbon-emission disclosure rules from the Ministry of Environment and Climate Change will reshape fleet procurement criteria and accelerate last-mile electric vehicle adoption timelines.
Industry Challenges
- Route optimization talent scarcity:Algorithmic dispatch and dynamic fleet management expertise remains concentrated among a limited pool of logistics technology specialists in São Paulo.
- Hub-and-spoke capex intensity:Automated sorting infrastructure and temperature-controlled cross-dock facilities require substantial capital deployment with extended payback periods.
- Electronic proof-of-delivery standardization:Fragmented digital signature and chain-of-custody documentation systems create interoperability friction between carrier networks and enterprise shippers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Courier, Express, and Parcel (CEP) Market |
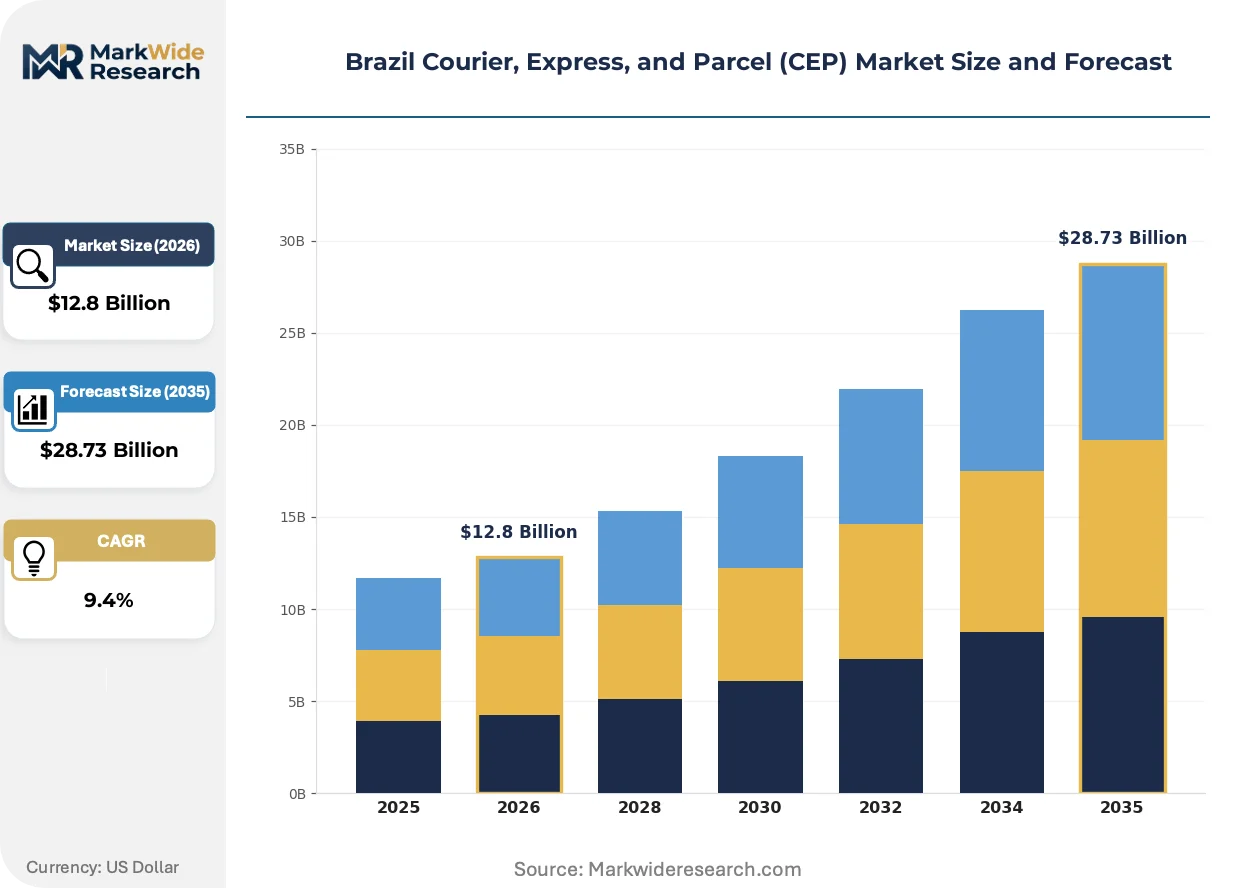
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Standard Shipping, Scheduled Pickup Delivery Mode: Ground, Air, Maritime, Drone Customer Type: B2B, B2C, E-Commerce, Retailers Package Size: Small Parcel, Medium Parcel, Large Parcel, Bulk |
| Companies Covered | DHL Group, Azul Cargo Express, Empresa Brasileira de Correios e Telegrafos, Sequoia Logística, Loggi, Jadlog, FedEx, Braspress Transportes Urgentes, Total Express, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Courier, Express, and Parcel (CEP) Market Trends and Innovations
Algorithmic route optimization and cold-chain infrastructure upgrades are compressing delivery windows while regulatory pressure on emissions transparency is forcing fleet composition decisions ahead of compliance deadlines.
Dynamic route optimization software is decentralizing dispatch authority from centralized control towers to driver-level decision systems. Mid-market e-commerce fulfillment operators are adopting these platforms fastest, compressing same-day coverage radii from urban cores to peripheral municipalities without proportional headcount expansion. The structural consequence is fragmenting the traditional hub-and-spoke model into distributed micro-fulfillment networks with reduced line-haul dependency.
ANVISA's updated sanitary surveillance protocols for temperature-sensitive pharmaceuticals are mandating real-time monitoring and deviation reporting. Cold-chain logistics providers must now deploy continuous data loggers with blockchain-anchored custody records for vaccine and biologic shipments. Healthcare verticals and diagnostic laboratory networks are absorbing compliance costs through dedicated service tier premiums, widening the capability gap between specialized and generalist operators.
Enterprise shippers are consolidating carrier relationships around outcome-based service level agreements rather than rate-card negotiations. Electronics and fashion retailers are displacing transactional spot pricing with committed volume contracts tied to on-time-in-full performance metrics. This shift is most visible in São Paulo's industrial belt, where multinational manufacturers are reducing approved vendor lists from twenty-plus carriers to three-to-four strategic partners with integrated visibility platforms.
Brazil Courier, Express, and Parcel (CEP) Market Segmentation
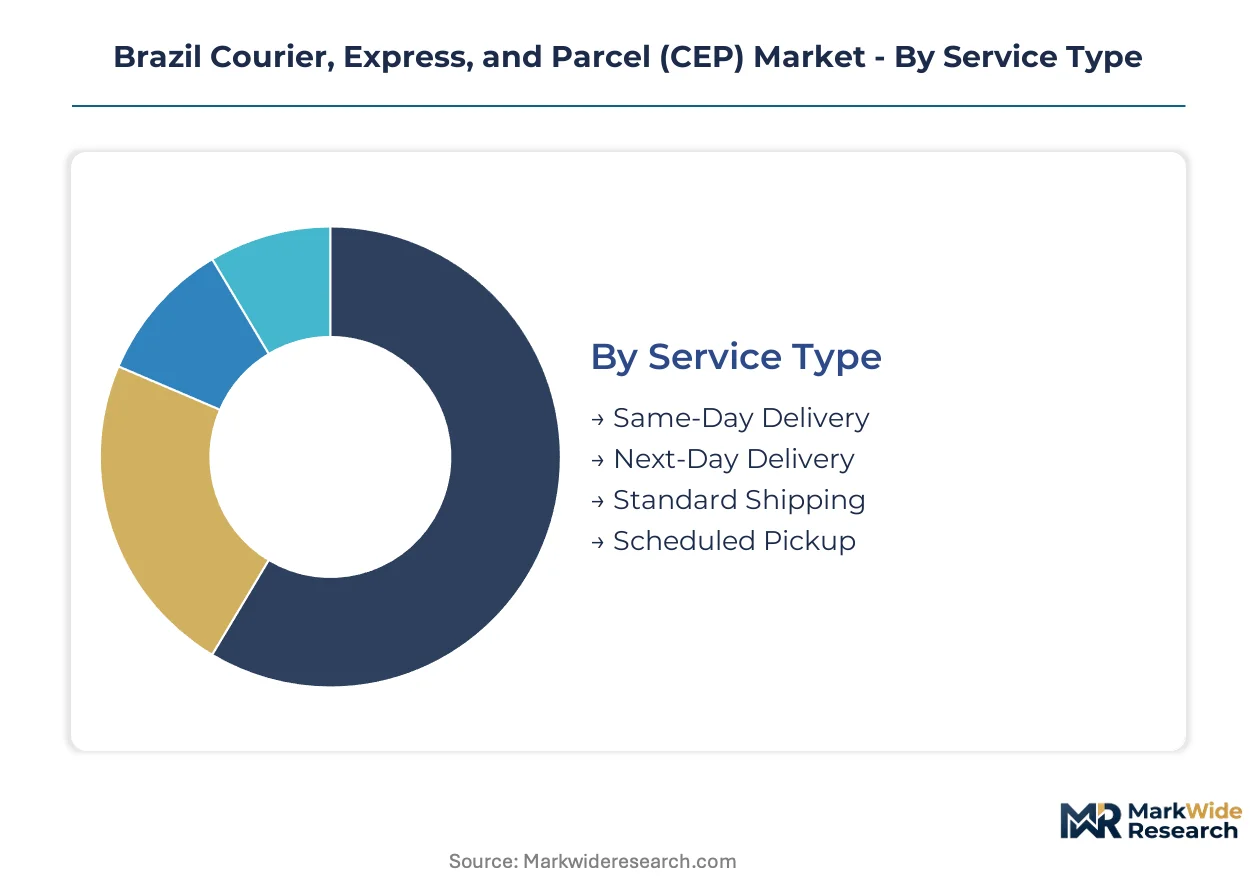
CEP service differentiation in Brazil reflects the tension between premium time-definite offerings and cost-optimized bulk distribution. Each segmentation dimension captures distinct operational requirements, capital intensity thresholds, and regulatory exposure profiles that shape competitive positioning across metropolitan corridors.
Service Type:
Standalone express services command dedicated fleet assets and real-time tracking infrastructure, while embedded fulfillment operates within broader e-commerce logistics platforms.
- Same-Day Delivery:Ultra-time-definite service requiring urban micro-fulfillment nodes and dynamic dispatch algorithms. São Paulo's electronics and pharmaceutical corridors absorb premium pricing for temperature-controlled urgent shipments under ANVISA mandates.
- Next-Day Delivery:Hub-and-spoke overnight operations with guaranteed morning arrival windows. Rio de Janeiro's fashion retail verticals and industrial parts distributors in São Paulo's ABC manufacturing belt concentrate committed volume contracts.
- Standard Shipping:Cost-optimized deferred delivery through consolidated line-haul networks with extended transit windows.
- Scheduled Pickup:Contracted collection windows for B2B account bases with predictable reverse logistics volumes.
Standard shipping leads volumes today; same-day delivery is gaining share fastest.
Delivery Mode:
Cost tier separation between capital-intensive air networks and asset-light ground operations determines margin structure and geographic reach.
- Ground:Dominant volume modality leveraging Brazil's continental road infrastructure with diesel-dependent cost structures. Southeast region's industrial corridors and agribusiness export routes sustain dense line-haul economics despite fuel price volatility compressing margins.
- Air:Time-critical express corridors connecting manufacturing zones through São Paulo-Guarulhos and Viracopos cargo terminals. Electronics and pharmaceutical verticals absorb premium rates for next-morning delivery guarantees.
- Maritime:Bulk parcel consolidation for coastal corridors with relaxed time constraints.
- Drone:Experimental last-mile modality for remote municipality access and traffic-congested urban cores.
Ground transport anchors volume economics; air freight captures premium margin pools.
Customer Type:
Application-driven segmentation separates enterprise procurement patterns from transactional consumer fulfillment requirements.
- B2B:Industrial parts distribution and inter-facility document exchange with contracted service level agreements. São Paulo's automotive and machinery manufacturing clusters drive consistent demand for scheduled pickup and next-day delivery tiers.
- E-Commerce:Marketplace fulfillment networks with explosive volume growth and stringent Consumer Defense Code reverse logistics obligations. Southeast region's digital retail penetration concentrates same-day and next-day density requirements.
- B2C:Individual shipper transactions with sporadic volume and price-sensitive carrier selection.
- Retailers:Omnichannel fulfillment bridging physical store networks with digital order capture.
E-commerce platforms are expanding most quickly; B2B relationships deliver margin stability.
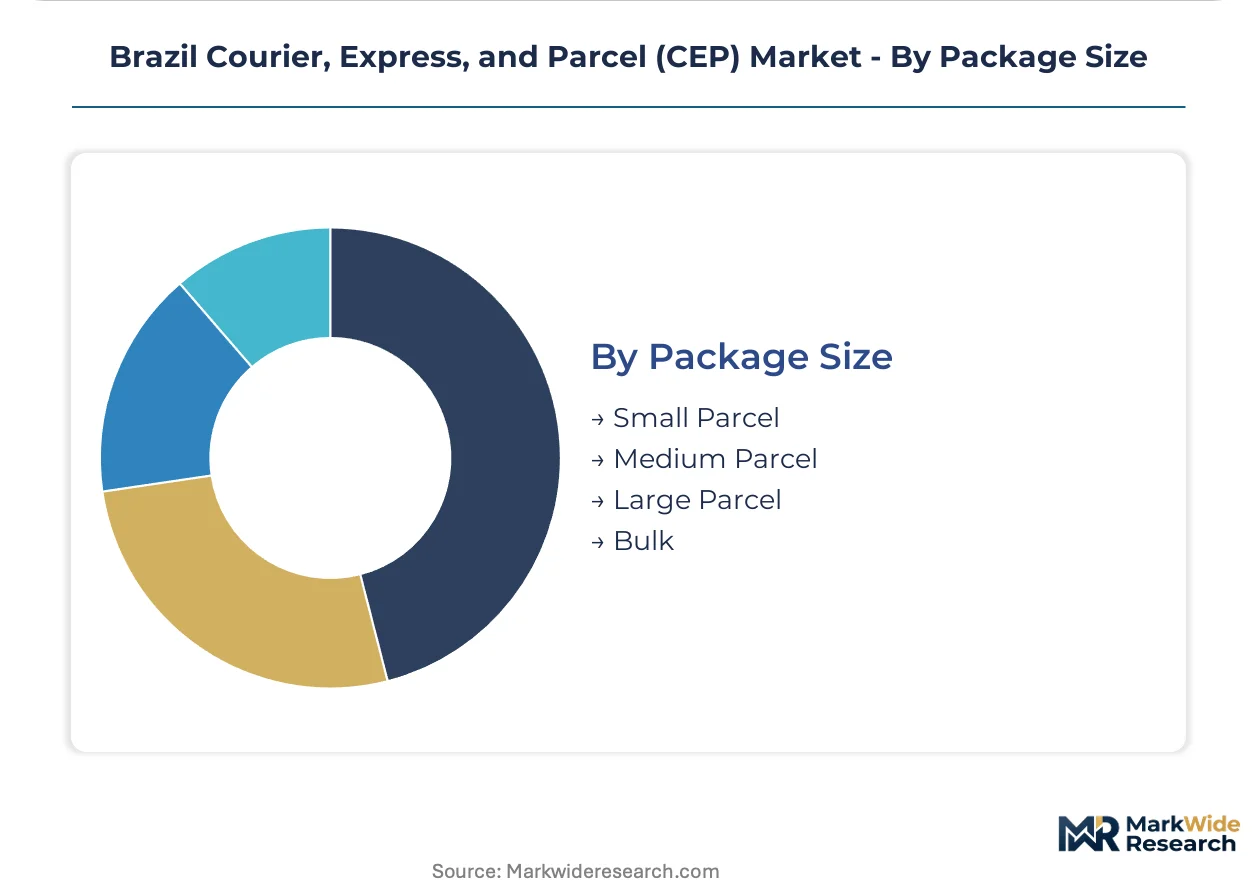
Package Size:
Handling infrastructure and sortation automation requirements scale non-linearly with dimensional weight categories.
- Small Parcel:Document envelopes and single-item e-commerce shipments compatible with automated belt sortation. Pharmaceutical samples and consumer electronics accessories dominate São Paulo and Rio de Janeiro premium corridors.
- Medium Parcel:Standard e-commerce boxes and industrial parts requiring manual handling intervention. Fashion retail and household goods verticals concentrate volume in Southeast distribution centers.
- Large Parcel:Bulky items demanding specialized lift equipment and non-standard vehicle configurations.
- Bulk:Palletized shipments approaching less-than-truckload thresholds with distinct rate negotiations.
Small parcels dominate transaction counts; medium parcels capture revenue concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics engineering talent and route optimization specialists concentrate in São Paulo's metropolitan corridor, anchoring operational excellence for nationwide CEP networks. This workforce distribution shapes regional competitive dynamics across Brazil's five dominant economic zones.
São Paulo
E-commerce fulfillment demand from electronics and fashion retailers drives same-day delivery density requirements. ANVISA's pharmaceutical cold-chain mandates enforce temperature-controlled infrastructure investments. The ABC manufacturing belt and Guarulhos air cargo terminal anchor premium express corridors for industrial parts and biopharmaceutical shipments.
Rio de Janeiro
Omnichannel retail networks and oilfield services logistics sustain next-day delivery commitments. The National Transport Agency's freight digitization requirements accelerate electronic proof-of-deployment adoption. Niterói and Duque de Caxias industrial zones concentrate B2B scheduled pickup contracts for machinery and maritime equipment distributors.
Minas Gerais
Agribusiness export corridors and mining equipment distribution generate heavy freight parcel volumes. The Brazilian Consumer Defense Code imposes reverse logistics obligations on Belo Horizonte-based e-commerce merchants. Contagem and Betim logistics parks host automated sorting hubs serving the Central-West connection routes.
Rio Grande do Sul
Automotive parts manufacturing and meat processing exports create temperature-sensitive shipment demand. Pending carbon-emission disclosure rules from the Ministry of Environment and Climate Change reshape fleet procurement in Porto Alegre metropolitan operations. Caxias do Sul industrial machinery clusters sustain dedicated B2B express lanes to São Paulo.
Bahia
Northeast corridor underpenetration offers first-mover positioning for fulfillment center placement. ANVISA sanitary surveillance protocols extend cold-chain compliance to Salvador's pharmaceutical distribution networks. Camaçari petrochemical complex and Feira de Santana agribusiness terminals anchor emerging ground transport density for deferred delivery tiers.
Brazil Courier, Express, and Parcel (CEP) Market Competitive Landscape
The competitive structure tilts toward state-affiliated universal service providers and multinational premium specialists. Correios maintains asymmetric last-mile access through postal monopoly infrastructure across municipalities below ten thousand inhabitants. DHL Group and FedEx occupy premium healthcare and electronics verticals with temperature-controlled capabilities. Two dominant competitive moves are reshaping positioning: algorithmic route density optimization in metropolitan corridors and strategic electrification of last-mile fleets ahead of environmental compliance deadlines.
Within the multinational premium tier, DHL Group and FedEx exemplify specialized cold-chain and time-definite service architectures. Correios anchors universal service obligations through its Empresa Brasileira de Correios e Telegrafos infrastructure. Among algorithmic-native competitors, Loggi occupies a position representing dynamic dispatch optimization in São Paulo and Rio de Janeiro density corridors. Jadlog and Total Express sit within the mid-market B2B express segment serving industrial parts distribution networks. Azul Cargo Express leverages integrated air-ground capabilities through Viracopos and Guarulhos cargo terminals.
| Leading Market Players |
|---|
| DHL Group |
| Azul Cargo Express |
| Empresa Brasileira de Correios e Telegrafos |
| Sequoia Logística |
| Loggi |
| Jadlog |
| FedEx |
| Braspress Transportes Urgentes |
| Total Express |
| Others |
Pricing and Supply Chain Analysis
Diesel cost pass-through mechanisms anchor ground transport pricing tiers from consolidated line-haul networks through last-mile density corridors in São Paulo and Rio de Janeiro. Fuel volatility compresses margins for standard shipping operators while insulating premium same-day and next-day segments with temperature-controlled infrastructure premiums.
Pricing Analysis
Unbundled per-shipment spot pricing dominates B2C transactions and small parcel e-commerce fulfillment, while bundled enterprise contracts with committed volume thresholds and performance-based SLAs capture B2B scheduled pickup and industrial parts distribution. Price differentiation hinges on time-definite guarantees and ANVISA cold-chain certification tiers, with pharmaceutical verticals absorbing substantial premiums for continuous monitoring capabilities. Pricing pressure stems from Correios' universal service obligations creating asymmetric competition in municipalities below ten thousand inhabitants. E-commerce merchants show highest price sensitivity due to Consumer Defense Code reverse logistics mandates, while healthcare distributors demonstrate lowest sensitivity given regulatory compliance requirements.
Supply Chain Analysis
ANVISA certification and National Transport Agency operator licensing create qualification gating that concentrates specialized cold-chain capacity among established multinational and state-affiliated providers. Vehicle manufacturing draws from Brazil's domestic assembly plants, China for electric drivetrain components, and Germany for precision sorting automation. Temperature-controlled packaging materials and real-time monitoring devices rest on single-source vulnerability from concentrated electronics suppliers. Distribution runs through hub-and-spoke networks anchored by automated sorting facilities in Contagem, Guarulhos cargo terminals, and Correios' municipal last-mile infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's CEP market functions as a regulatory compounder where ANVISA pharmaceutical mandates and National Transport Agency digitization requirements structurally expand compliance-driven service tiers. These regulatory milestones create durable demand for certified cold-chain infrastructure and electronic proof-of-delivery systems.
For Market Incumbents: Deepen algorithmic route density optimization in São Paulo and Rio de Janeiro metropolitan corridors to defend against Loggi's dynamic dispatch capabilities. Expand temperature-controlled cross-dock capacity ahead of pending Ministry of Environment carbon disclosure rules that will reshape fleet procurement criteria. Vertical integration into electric vehicle leasing pools offers channel control against fuel cost volatility eroding ground transport margins. For New Entrants and Emerging Players: Northeast corridor agribusiness distributors represent an underserved buyer archetype with deferred delivery requirements and limited same-day penetration. Salvador and Recife fulfillment center placement captures first-mover positioning before established operators consolidate density. A go-to-market angle anchored to Brazilian Consumer Defense Code reverse logistics compliance differentiates against transactional spot pricing competitors. For Investors and Strategic Acquirers: Roll-up economics work for mid-market B2B express operators with established scheduled pickup contracts because enterprise shippers are consolidating carrier relationships from twenty-plus vendors to three-to-four strategic partners. Long-term viability centers on integrated visibility platforms and outcome-based SLAs rather than rate-card negotiations. The signal to watch is Correios privatization progress and subsequent last-mile access reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | ANVISA mandates for vaccine distribution create dedicated service tier premiums in healthcare verticals. |
| Algorithmic Route Optimization Deployment | Dynamic dispatch platforms compress same-day coverage radii without proportional headcount expansion in dense corridors. |
| Electric Fleet Procurement Acceleration | Ministry of Environment disclosure rules reshape vehicle procurement criteria ahead of compliance deadlines. |
| Reverse Logistics Network Buildout | Consumer Defense Code obligations structurally expand parcel return volumes requiring specialized collection infrastructure. |
| Northeast Corridor Fulfillment Center Placement | Salvador and Recife underpenetration offers first-mover positioning before density economics lock in. |
Research Methodology
Direct dialogue with logistics technology specialists, route optimization engineers, pharmaceutical supply chain directors, e-commerce fulfillment operators, and National Transport Agency licensing officers grounded qualitative findings. Secondary validation drew from ANVISA regulatory filings, customs and trade data, SEC disclosures from listed logistics operators, and carrier fleet procurement records. Bottom-up volume modeling across service type, delivery mode, customer segment, and package size dimensions triangulated against top-down macroeconomic indicators.
Bottom-up segment-level projections across same-day, next-day, and standard shipping tiers combined with customer-type splits between B2B industrial distribution and e-commerce fulfillment networks. Ground transport volume assumptions incorporated diesel price elasticity and road infrastructure density variations by region. Air freight modeling integrated cargo terminal capacity constraints at Guarulhos and Viracopos. CAGRs derived from historical volume trajectories adjusted for regulatory catalysts and e-commerce penetration curves across the analysis window.
Underlying measurement precision varies by segment; same-day delivery and pharmaceutical cold-chain verticals carry tighter precision than emerging drone modality and Northeast corridor deferred shipping. Forecasts reflect assumptions about ANVISA mandate enforcement timelines, Correios operational restructuring, and e-commerce platform fulfillment network expansion. A model refresh is warranted upon material change in National Transport Agency digitization compliance deadlines or Ministry of Environment fleet electrification mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Freight Brokerage Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
Germany Automotive 3PL Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
US Mexico Cross Border FTL Freight Transport Market
Logistics and Shipping
Tanker Shipping Market
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
Project Logistics Market
Logistics and Shipping
China International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Japan Freight Forwarding Market
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
Bangladesh Contract Logistics Market