
 France Rail Freight Transport Market | 2026-2036
France Rail Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
France Rail Freight Transport Market Foresight
High-capacity intermodal specifications are redrawing competitive boundaries across French rail freight corridors. Fret SNCF leverages its legacy infrastructure dominance to anchor bulk agricultural flows through the Paris basin. Captrain France SAS differentiates through specialized chemical tank car services linking port complexes to inland production facilities. Europorte SAS competes aggressively on cross-border express routes into Belgium and Germany.
France rail freight transport encompasses the movement of goods via electrified and diesel-hauled railway networks operating at axle loads up to 22.5 tonnes and train lengths extending to 750 meters, primarily serving industrial supply chains requiring reliable, low-carbon alternatives to road haulage. Intermodal transport mode leads volume throughput as manufacturers consolidate containerized goods onto rail for long-distance trunk movements. Tank car equipment commands premium positioning due to stringent hazardous materials handling protocols and specialized maintenance requirements. Express service type captures accelerating demand from retail chains requiring time-definite delivery windows.
France's national railway safety authority and EU F-Gas Regulation constrain locomotive propulsion choices, pushing operators toward electric traction and alternative fuel retrofits. The EU Green Deal emissions targets and national carbon budgeting frameworks redirect shipper procurement toward certified low-carbon rail providers. Stakeholders must monitor infrastructure investment pacing on contested Lyon-Turin and Seine-Nord Europe corridors to anticipate capacity bottlenecks and routing advantages.
Market Dynamics
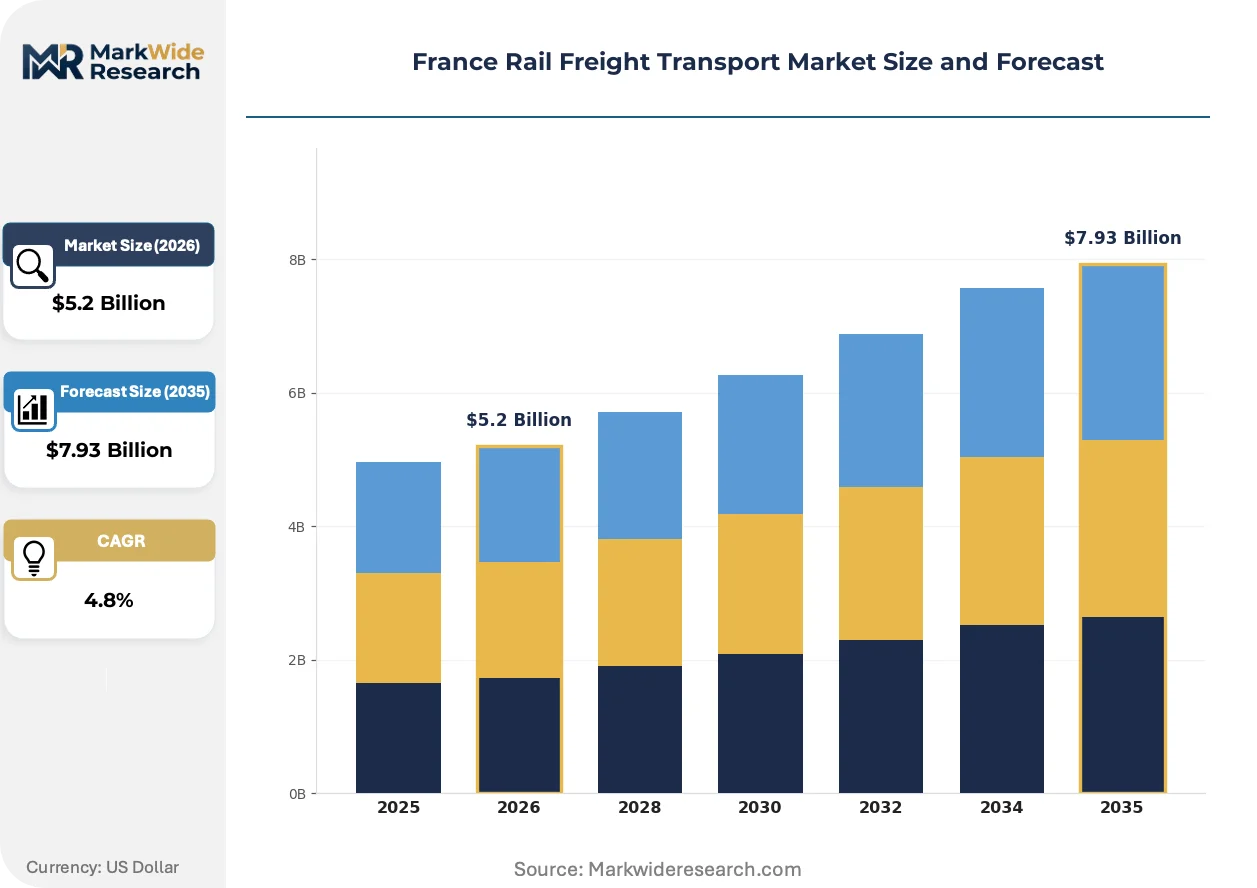
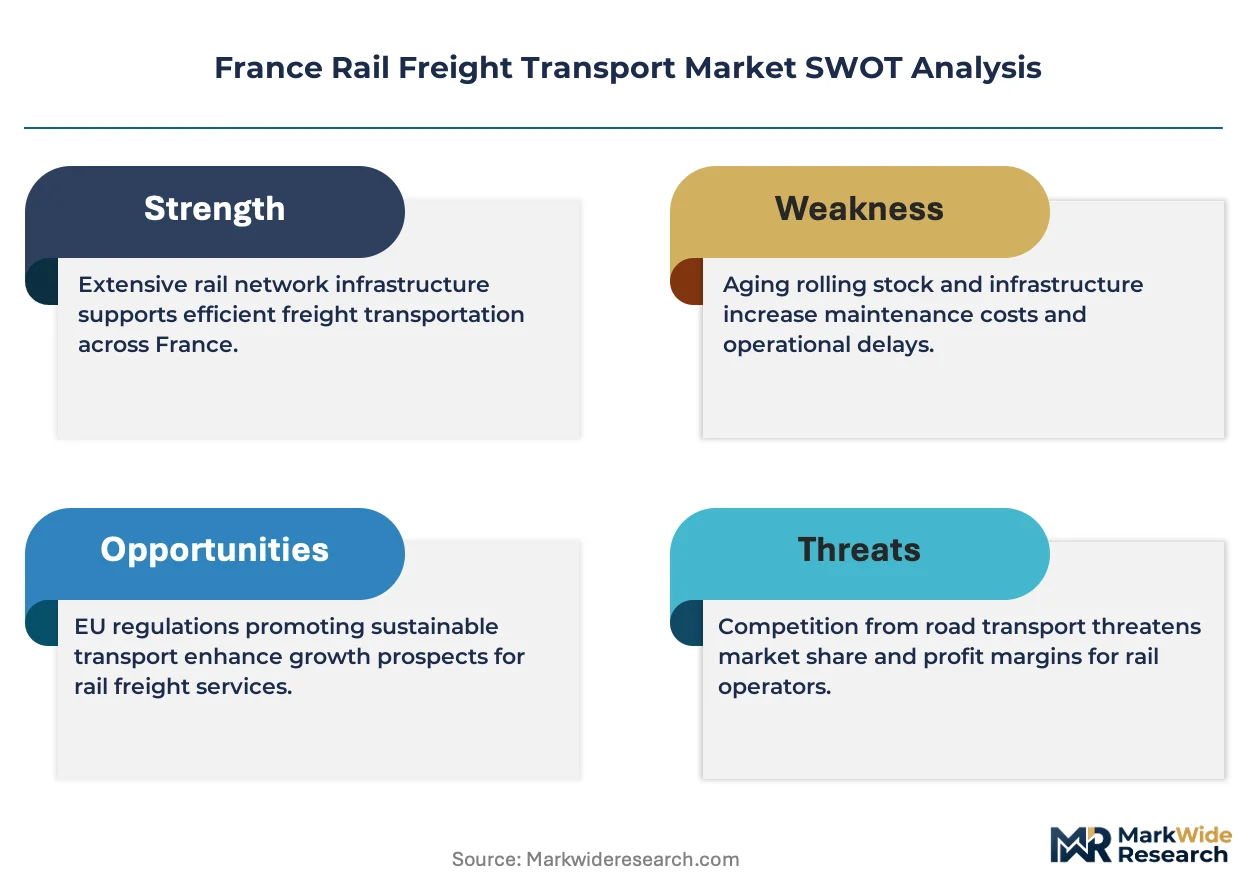
France's rail freight sector faces acute pressure from the EU Green Deal's locomotive emissions mandates, which are forcing operators to accelerate electric traction retrofits and alternative fuel pilots while navigating constrained infrastructure budgets.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases in cooling systems is pushing freight operators toward electric locomotive procurement, expanding addressable market for electrified corridor services.
- Chemical manufacturing:Hazardous material shippers are consolidating transport contracts onto rail to satisfy internal carbon reduction targets and insurance risk mitigation requirements.
- Lyon logistics corridor:Mediterranean port congestion is redirecting container flows through Rhône-Alpes rail terminals, amplifying demand for intermodal shuttle services.
Market Restraints
- Copper and rare earth input costs:Traction motor and battery pack manufacturing faces volatile commodity pricing, compressing fleet modernization timelines for mid-size operators.
- SNCF Réseau infrastructure concentration:Single-source dependency for track access and scheduling creates bottleneck risk on contested Seine-Nord Europe and Lyon-Turin corridors.
- Road haulage substitution:Flexible trucking networks capture urgent, non-scheduled freight movements that rail cannot accommodate due to fixed timetables.
Strategic Opportunities
- Seine-Nord Europe canal-rail intermodality:The under-construction waterway connection offers multimodal terminal development potential for agribulk and construction material flows.
- Battery-electric shunting locomotives:Yard operations at Marseille-Fos and Le Havre port complexes present early deployment scenarios for zero-emission last-mile traction.
- CSRD-aligned shipper procurement:Corporate sustainability reporting mandates are redirecting logistics tenders toward certified low-carbon rail providers with verified emissions data.
Industry Challenges
- Train driver certification pipelines:The specialized licensing requirements for hazardous materials and cross-border operations face multi-year training backlogs, constraining crew availability.
- Legacy diesel fleet stranding risk:Operators must balance accelerated depreciation of existing locomotives against uncertain hydrogen and battery technology maturation curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Rail Freight Transport Market |
| Market Size in 2026 | $5.2 Billion |
| Market Size in 2035 | $7.93 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Mode: Intermodal, Bulk, Automotive, Containerized, Chemicals, Agricultural Service Type: Long Haul, Short Haul, Express, Scheduled, On-Demand, Cross-Docking Customer Type: Manufacturers, Logistic Providers, Retail Chains, Construction Firms, Energy Producers, Third-Party Operators Rail Equipment: Locomotives, Flat Cars, Box Cars, Tank Cars, Hopper Cars, Refrigerator Cars |
| Companies Covered | Fret SNCF, Captrain France SAS, DB Cargo France SAS, Europorte SAS, REGIORAIL France S.A.S., Lineas NV/SA, Novatrans S.A., RDT 13, SNCF Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Rail Freight Transport Market Shifts & Advancements
Digital automation and alternative propulsion systems are actively restructuring competitive capabilities across French rail freight corridors, compressing operational cost structures while opening new service categories.
Autonomous shunting technology is decomposing traditional yard labor models. Port terminal operators at Marseille-Fos and Dunkerque are piloting remote-controlled locomotive movements to compress dwell times and reduce crew exposure to hazardous cargo zones. This automation is decomposing the cost advantage of smaller, labor-flexible trucking competitors in port hinterland markets.
France's national railway safety authority is tightening approval frameworks for hydrogen fuel cell locomotives ahead of EU-wide standardization. The regulatory sequencing is accelerating prototype testing partnerships between infrastructure managers and equipment suppliers. Alstom's hydrogen Coradia platform and similar demonstrators are navigating certification timelines that will determine 2030 fleet composition.
Shippers are consolidating procurement through fourth-party logistics providers that bundle rail with warehousing and customs brokerage. Retail chains and automotive suppliers are abandoning direct carrier contracts in favor of integrated service platforms. This concentration is most visible in the Paris basin, where consolidated buying power is compressing spot market rates and favoring operators with end-to-end digital visibility.
France Rail Freight Transport Market Segmentation
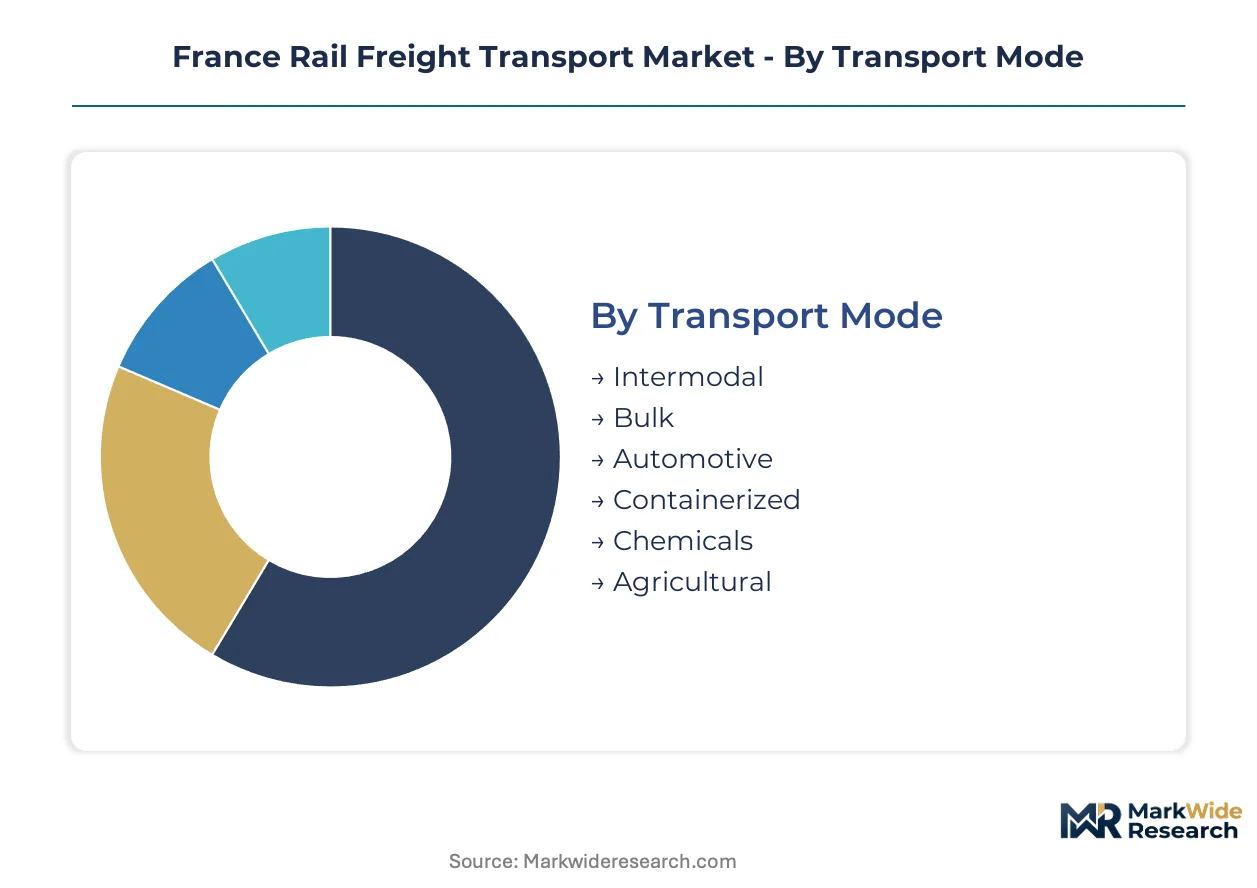
Rail freight segmentation in France reveals distinct margin architectures across transport modes, service tiers, and equipment categories. Understanding these divisions exposes where operators capture premium returns versus where commoditization pressures dominate.
Transport Mode:
Margin pools concentrate in specialized hazardous material movements and temperature-controlled flows, while bulk agricultural and standard container segments compete on operational efficiency.
- Intermodal:Combines standardized ISO containers with rail trunk haulage and road drayage for seamless origin-to-destination movement. Demand clusters around Lyon logistics corridor terminals serving Mediterranean-Northern European manufacturing supply chains, driven by retail chains consolidating procurement through integrated 4PL platforms.
- Chemicals:Dedicated tank car circuits handle hazardous liquids and gases under strict ADR and EU F-Gas Regulation protocols. Rhône-Alpes chemical manufacturers are expanding long-term contracts to satisfy internal carbon reduction targets and insurance risk mitigation requirements.
- Bulk:Open wagon movements of coal, minerals, and construction aggregates operate on high-volume, low-margin economics.
- Automotive:Finished vehicle transport using specialized multi-level auto racks serves assembly plant distribution networks.
- Containerized:Maritime box traffic from Le Havre and Marseille-Fos port complexes competes with barge and road alternatives.
- Agricultural:Grain and feedstuff flows through Paris basin corridors face seasonal volume volatility and price-sensitive shipper procurement.
The dominant share belongs to Intermodal, while Chemicals is closing the gap fastest.
Service Type:
Customer willingness to pay varies sharply by delivery certainty, with time-definite offerings commanding substantial premiums over flexible scheduling.
- Express:Guaranteed delivery windows within 24-48 hours for high-value, time-critical shipments. Automotive suppliers and pharmaceutical distributors in the Paris basin are abandoning direct carrier contracts for integrated platforms requiring precise scheduling.
- Scheduled:Fixed-timetable services on recurring routes offer predictability for planning-intensive supply chains. Lyon-Turin corridor congestion is amplifying demand for reliable departure slots as Mediterranean port volumes redirect northward.
- Long Haul:Trunk movements exceeding 500 kilometers compete directly with road haulage on cost per ton-kilometer.
- Short Haul:Regional feeder services face substitution pressure from flexible trucking networks.
- On-Demand:Ad hoc charter movements capture urgent, non-recurring freight requirements.
- Cross-Docking:Terminal-based consolidation and deconsolidation services add value through inventory postponement.
Scheduled services generate the highest revenue per train-kilometer, though Express is expanding most quickly as retail procurement tightens delivery windows.
Customer Type:
Procurement sophistication determines contract structures, with large integrated buyers extracting favorable terms through volume concentration while fragmented segments accept standard rate cards.
- Logistic Providers:Fourth-party logistics platforms bundle rail with warehousing, customs brokerage, and last-mile delivery. Consolidated buying power in the Paris basin is compressing spot market rates and favoring operators with end-to-end digital visibility.
- Manufacturers:Direct industrial shippers of raw materials and components maintain dedicated supply chain teams. Chemical manufacturers are consolidating transport contracts onto rail to satisfy CSRD-aligned corporate sustainability reporting mandates.
- Retail Chains:Omnichannel distribution networks require synchronized inbound and outbound flows.
- Construction Firms:Project-based demand for aggregates and prefabricated materials exhibits irregular volume patterns.
- Energy Producers:Coal, biomass, and nuclear fuel movements depend on national energy policy trajectories.
- Third-Party Operators:Smaller freight forwarders aggregate shipments across multiple underlying carriers.
Logistic Providers control the largest contract value, yet Manufacturers are gaining negotiating leverage through sustainability-linked procurement requirements.
Rail Equipment:
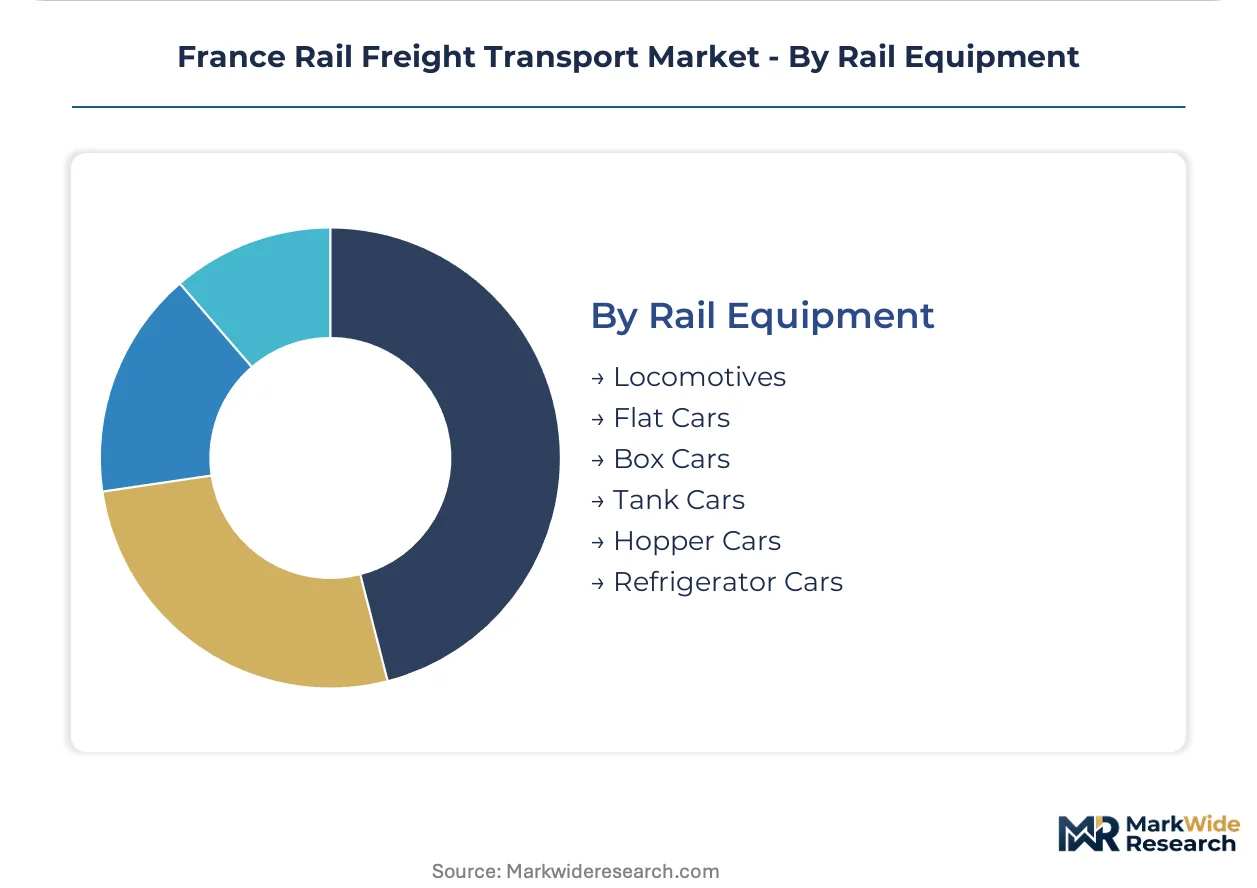
Asset specificity creates divergent investment returns, with specialized hazardous material and temperature-controlled equipment sustaining higher utilization rates than general-purpose rolling stock.
- Tank Cars:Pressure-rated and non-pressure cylindrical vessels engineered for liquid and gas commodities. Stringent maintenance protocols and specialized cleaning requirements create barriers to entry that protect incumbent operators serving port-to-plant chemical corridors.
- Locomotives:Electric and diesel-electric traction units subject to EU Green Deal emissions mandates. SNCF Réseau infrastructure concentration creates bottleneck risk for fleet deployment on contested Seine-Nord Europe and Lyon-Turin corridors.
- Flat Cars:Open deck platforms for containers, trailers, and oversized loads face cyclical demand tied to construction and renewable energy project cycles.
- Box Cars:Enclosed wagons for palletized and packaged goods compete with intermodal alternatives.
- Hopper Cars:Gravity-unloading designs for dry bulk commodities experience seasonal utilization swings.
- Refrigerator Cars:Insulated and mechanically cooled units for temperature-sensitive food and pharmaceutical products.
Tank Cars deliver the strongest returns on invested capital, while Locomotives face the steepest technology transition costs as electrification and alternative fuel retrofits accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lyon-Turin corridor channels Mediterranean container traffic into Northern European manufacturing networks, positioning France as a critical transit state between Iberian ports and German industrial zones.
Île-de-France
Paris basin terminals handle agribulk consolidation and express parcel distribution for national retail networks. SNCF Réseau prioritizes track maintenance windows on Grande Ceinture orbital lines under EU Green Deal infrastructure funding protocols. Le Bourget intermodal yard processes rising e-commerce container volumes from Belgian and Dutch gateway ports.
Auvergne-Rhône-Alpes
Rhône-Alpes chemical manufacturers anchor hazardous material flows between Fos-sur-Mer refineries and Lyon-Saint-Étienne production complexes. The EU F-Gas Regulation mandates fluorinated gas containment standards for refrigerated tank car circuits serving pharmaceutical distributors. Satolas intermodal terminal redirects Mediterranean shipping congestion onto rail shuttles toward Strasbourg and Mulhouse.
Provence-Alpes-Côte d'Azur
Marseille-Fos port authority manages container transshipment growth from North African and Middle Eastern trade lanes. France's national railway safety authority reviews hydrogen fuel cell locomotive certifications for yard shunting operations. Fos-Étang de Berre chemical corridor maintains dedicated tank car circuits for chlorine and petrochemical feedstocks.
Hauts-de-France
Dunkerque port terminals compete with Belgian Antwerp for cross-Channel Ro-Ro and container traffic. The Seine-Nord Europe canal-rail intermodal project receives state infrastructure subsidies under France's national carbon budgeting framework. Lille-Dourges logistics zone consolidates automotive supplier flows for Renault and Stellantis assembly plants.
Nouvelle-Aquitaine
Bordeaux-Paris rail corridors serve wine export consolidation and aeronautics component supply chains. ANSM hazardous material transport permits govern chemical tank car movements from Lacq gas field processing facilities. Bayonne-Biarritz border terminals handle Iberian peninsula transit freight toward UK and Northern European destinations.
France Rail Freight Transport Market Competitive Landscape
Listed infrastructure conglomerates compete with private specialists across equipment leasing and terminal operations, producing a tiered structure where scale advantages concentrate in intermodal trunk routes while niche operators capture chemical and express segments. Three archetypes dominate: legacy national carriers with track access privileges, private chemical specialists with hazardous material certifications, and cross-border express operators leveraging EU open access rules. Consolidation pressures favor strategic partnerships over outright acquisition, while fleet electrification investments separate capital-rich incumbents from constrained mid-tier competitors.
Within the legacy carrier tier, Fret SNCF anchors bulk agricultural and intermodal flows through inherited infrastructure dominance. Captrain France SAS and Europorte SAS occupy positions as private specialists—Captrain through chemical tank car circuits linking port complexes to inland plants, Europorte through aggressive cross-border express positioning into Belgium and Germany. These three exemplify how regulatory access rights and equipment specialization create defensible competitive positions against road haulage substitution.
| Leading Market Players |
|---|
| Fret SNCF |
| Captrain France SAS |
| DB Cargo France SAS |
| Europorte SAS |
| REGIORAIL France S.A.S. |
| Lineas NV/SA |
| Novatrans S.A. |
| RDT 13 |
| SNCF Logistics |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with SNCF Réseau lock in track access rights and price visibility for chemical manufacturers and intermodal operators, insulating committed shippers from spot market volatility while exposing flexible buyers to congestion surcharges on contested Lyon-Turin and Seine-Nord Europe corridors.
Pricing Analysis
Diesel-electric locomotive pricing faces accelerating compression against electric traction premiums as EU F-Gas Regulation mandates reshape fleet procurement economics. Three-tier pricing structure across certified low-carbon, standard electric, and legacy diesel service tiers reflects diverging compliance costs and carbon intensity verification. Price differentiation centers on emissions certification grade and volume scale, with large logistics providers extracting favorable terms through consolidated procurement. Margins are tightening in bulk agricultural segments due to seasonal demand volatility, while chemical tank car services sustain premium positioning through specialized ADR handling requirements and insurance risk mitigation bundling.
Supply Chain Analysis
SNCF Réseau infrastructure concentration creates a chokepoint that constrains fleet deployment flexibility and amplifies scheduling dependency for all operators serving French corridors. Traction motor manufacturing draws from China, Germany, and Japan, while battery pack assembly rests on South Korean and Chinese cell suppliers. Single-source vulnerability pervades track access allocation, with contested corridor capacity rationing threatening service reliability. Distribution runs through port-centric intermodal terminals at Marseille-Fos, Le Havre, and Dunkerque, feeding into Paris basin consolidation yards and Lyon logistics corridor shuttles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France rail freight transport sits in a cyclical recovery phase driven by Mediterranean port congestion redirecting container volumes onto Rhône-Alpes rail corridors, amplifying demand for reliable intermodal shuttle services and specialized chemical tank car circuits.
For Market Incumbents: Consolidate chemical tank car fleet ownership through targeted acquisitions of specialized leasing operators serving Fos-Étang de Berre and Lyon-Saint-Étienne production corridors. Secure long-term track access agreements on Seine-Nord Europe and Lyon-Turin corridors before capacity constraints intensify, locking in routing advantages against emerging cross-border competitors leveraging EU open access rules.
For New Entrants and Emerging Players: ADR hazardous materials certification fast-track programs offer entry pathways into chemical logistics segments where incumbent capacity constraints create service gaps. Target battery-electric shunting locomotive deployment at Marseille-Fos and Le Havre port complexes, where zero-emission mandates and yard automation pilots generate immediate equipment demand. Pursue fourth-party logistics platform partnerships to bypass direct shipper procurement barriers.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors specialized equipment lessors with certified low-carbon asset portfolios. Long-term viability hinges on exposure to electrified corridor services and hazardous materials handling capabilities rather than bulk commodity exposure. Monitor hydrogen fuel cell locomotive certification timelines as the critical inflection signal for 2030 fleet composition strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Locomotive Fleet Conversion | EU F-Gas Regulation compliance secures track access priority on carbon-budgeted corridors. |
| Hydrogen Shunting Locomotive Pilot | France's national railway safety authority certification opens zero-emission yard operations at port complexes. |
| Chemical Tank Car Circuit Expansion | ADR-certified dedicated circuits capture Rhône-Alpes manufacturer contract consolidation. |
| Fourth-Party Logistics Platform Integration | CSRD-aligned shipper procurement redirects tenders toward integrated service providers. |
| Seine-Nord Europe Terminal Development | Canal-rail intermodality positions agribulk and construction material flows for multimodal growth. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with rail freight operators, chemical manufacturer logistics directors, port authority terminal managers, and fourth-party logistics platform executives. Secondary validation incorporated EU F-Gas Regulation implementation tracking, SNCF Réseau infrastructure investment disclosures, ADR hazardous materials transport permit databases, and customs trade flow data. Bottom-up volume modeling across transport modes, service tiers, and equipment categories was triangulated against top-down macroeconomic freight demand indicators.
Across the analysis window, the forecasting framework modeled segmentation dimensions including transport mode specialization, service type tiering, customer procurement sophistication, and rail equipment asset specificity. CAGRs were derived from trend extrapolation of corridor capacity utilization, electrification investment pacing, and shipper contract duration patterns. Industry-specific inputs included EU Green Deal emissions target trajectories, Lyon-Turin corridor construction milestones, and hydrogen fuel cell locomotive certification timelines.
Underlying assumptions cover sustained EU F-Gas Regulation enforcement, SNCF Réseau infrastructure access pricing stability, and Mediterranean port congestion persistence, with deviation risk concentrated in alternative fuel technology maturation curves and cross-border regulatory harmonization delays. Practitioners should keep alternative scenarios live as EU-wide locomotive emissions standards and national carbon budgeting frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railcar Vehicle Toilet Market
Railway
Rail Seat Market
Railway
Railway System Market
Railway
Railway Draft Gears Market
Railway
Train Bogie Market
Railway
Locomotive Maintenance Market
Railway
Rolling Stocks Market
Railway
Railway Buffer Stops Market
Railway
Global Hyperloop Train Market
Railway
Railway Pantograph Market
Railway
Rail Brace Market
Railway
Bullet Train Market
Railway
India Rail Freight Transport Market
Railway
Railway Braking System Market
Railway
Global Train Control and Management Systems Market
Railway
Railway Rolling Stock Market