
 Sweden Cold Chain Logistics Market | 2026-2036
Sweden Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Cold Chain Logistics Market Insights
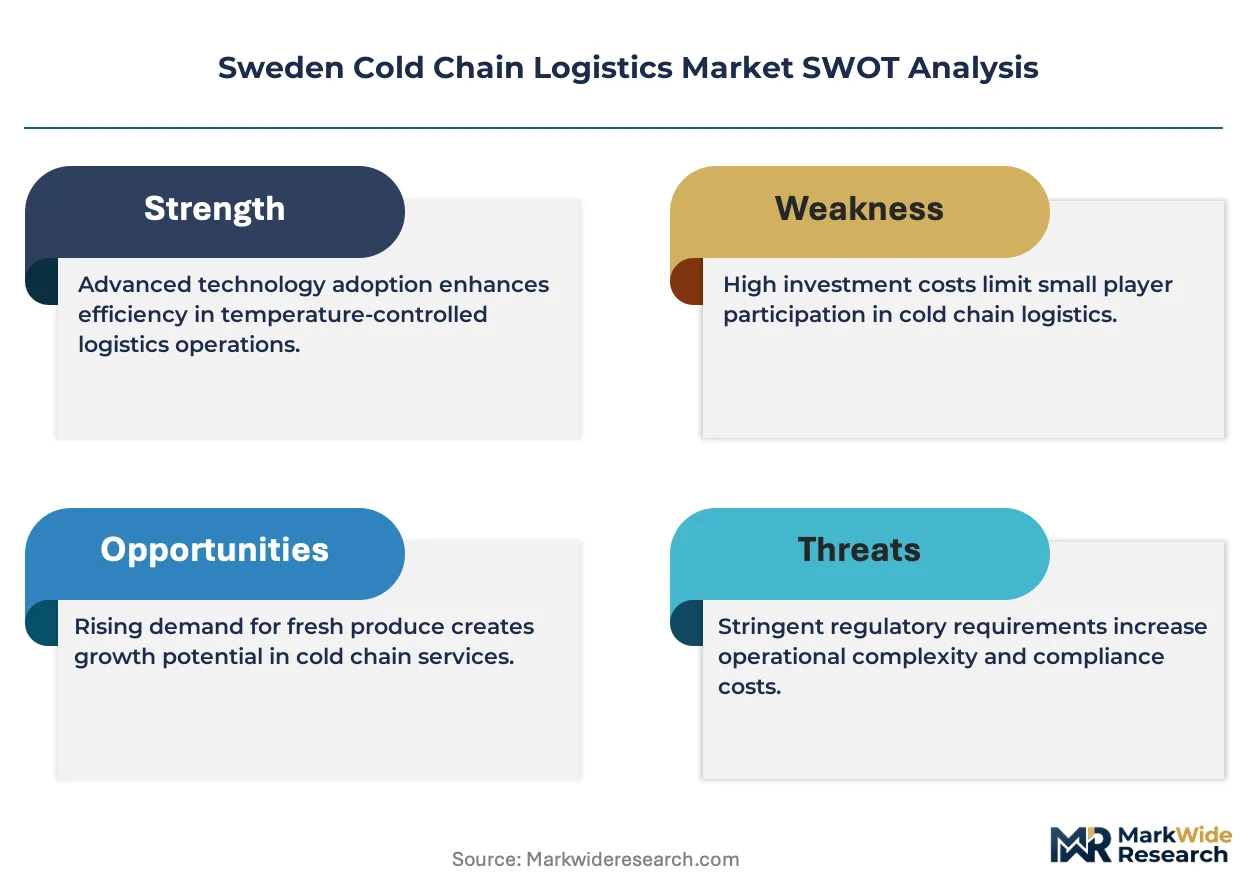
Sweden's alignment with the EU Green Deal and national carbon neutrality targets is consolidating demand for energy-efficient refrigerated transport and solar-powered cold storage facilities. DHL Logistics leverages its Nordic hub network to sustain pharmaceutical distribution dominance across the Scandinavian peninsula. Klimat Transport & Logistik AB anchors regional food logistics through specialized multi-temperature fleet operations. DB Schenker competes on intermodal rail-road refrigerated corridors linking southern Sweden to continental Europe.
Cold chain logistics encompasses the temperature-controlled supply chain infrastructure—refrigerated vehicles, insulated containers, cold storage warehouses, and real-time monitoring systems—that maintains product integrity between 2°C and 8°C for chilled goods and below -18°C for frozen commodities. The primary purpose is preventing thermal degradation of perishable pharmaceuticals, fresh produce, and frozen foods from manufacturing through last-mile delivery. Storage services dominate value capture due to high real estate and energy costs in Swedish urban centers, while IoT-based monitoring represents the fastest-expanding technology segment as pharmaceutical buyers mandate real-time temperature documentation. Food and beverage end users occupy the largest volume share, though pharmaceuticals generates superior margins driven by regulatory compliance premiums.
The Swedish Food Agency enforces cold chain traceability under EU Regulation 852/2004, while the Medical Products Agency mandates GDP compliance for pharmaceutical distribution, collectively elevating barriers for uncertified operators. BIS-equivalent Swedish Standards Institute certification for refrigerated transport equipment shapes equipment procurement decisions and fleet renewal cycles. Stakeholders must monitor EU F-Gas Regulation phase-down timelines, as refrigerant transition costs will reshape total cost of ownership calculations for Swedish cold storage operators.
Market Dynamics
Sweden's EU F-Gas Regulation compliance deadlines are compressing refrigerant transition timelines, forcing cold storage operators to accelerate capital deployment toward natural refrigerant systems before 2030 phase-down milestones.
Growth Catalysts
- Biologics manufacturing expansion:Swedish pharmaceutical clusters in Uppsala and Stockholm are scaling monoclonal antibody production, requiring expanded 2°C to 8°C distribution networks.
- EU Green Deal alignment:National carbon neutrality targets are consolidating public procurement preferences for solar-powered cold storage and electric refrigerated transport fleets.
- IoT sensor deployment:Real-time temperature monitoring systems are becoming mandatory for pharmaceutical GDP compliance, driving hardware refresh cycles across third-party logistics providers.
Market Restraints
- Electricity cost volatility:Nordic power market price swings are elevating operating expenditure for energy-intensive blast freezing operations in southern Sweden.
- Equipment supply concentration:Natural refrigerant compressor manufacturing is consolidating among German and Danish suppliers, extending lead times for Swedish fleet operators.
- Technical retrofit complexity:Existing cold storage facilities face ammonia charge limitations under updated ATEX directives, constraining expansion options in urban zones.
Strategic Opportunities
- Gothenburg port corridor:Underdeveloped temperature-controlled rail connections to continental Europe offer first-mover advantages for intermodal pharmaceutical transit.
- Cell and gene therapy logistics:Cryogenic (-150°C) chain requirements for CAR-T treatments are creating premium service tiers beyond conventional cold chain capabilities.
- Nordic Battery Belt synergies:Proximity to emerging Swedish battery cell manufacturing is opening adjacent temperature-controlled raw material logistics contracts.
Industry Challenges
- Refrigeration technician scarcity:Specialized ammonia system certification programs are producing insufficient graduates to match fleet electrification and natural refrigerant conversion timelines.
- Multi-agency compliance overlap:Simultaneous Swedish Food Agency traceability audits and Medical Products Agency GDP inspections are compressing operational bandwidth for dual-use facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Cold Chain Logistics Market |
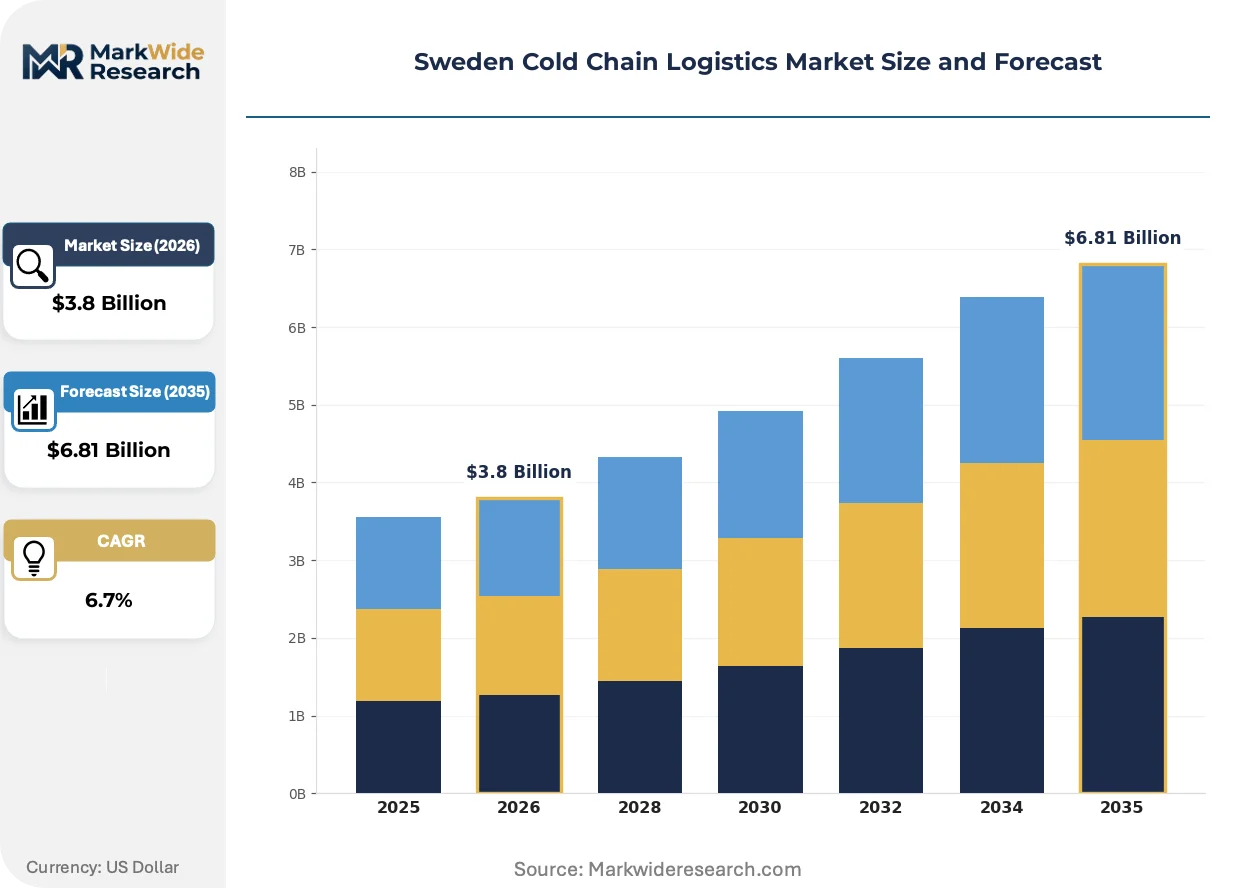
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Packaging, Monitoring Temperature Range: Frozen, Chilled, Ambient, Refrigerated End User: Pharmaceuticals, Food & Beverage, Healthcare, Chemicals Technology: IoT, GPS Tracking, Automation, Refrigeration Systems |
| Companies Covered | DHL Logistics, Klimat Transport & Logistik AB, DB Schenker, Bring Logistics, Nordic Cold Chain Solutions, Cool Carriers AB, Seafrigo Nordic AB, KMP Transport AB, NewCold Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Cold Chain Logistics Market Trends and Innovations
Distributed ledger architectures and edge computing are converging with electrified transport to reshape how Swedish operators validate chain-of-custody documentation across pharmaceutical and food safety regimes.
Blockchain-enabled temperature logging is decentralizing audit trail verification away from centralized quality management systems. Pharmaceutical distributors in the Stockholm-Uppsala corridor are piloting distributed ledger integration to satisfy Medical Products Agency GDP documentation requirements. This architecture is decentralizing compliance costs by eliminating redundant paper-based reconciliation across multi-modal handoffs.
EU F-Gas Regulation phase-down schedules are mandating refrigerant transitions across Swedish cold storage infrastructure. The regulation bans new equipment using high-global-warming-potential hydrofluorocarbons from 2025, compressing capital planning horizons. Food logistics operators in Skåne County are responding by accelerating ammonia and CO2 system deployments ahead of statutory deadlines.
Direct-to-pharmacy distribution models are compressing traditional wholesale intermediation in temperature-controlled pharmaceutical supply. Hospital pharmacy buyers are consolidating volume commitments with specialized cold chain carriers, bypassing generalist distributors. This pattern is most pronounced in the Västra Götaland region, where regional health authority procurement reforms favor outcome-based logistics contracts with guaranteed temperature integrity metrics.
Sweden Cold Chain Logistics Market Segmentation
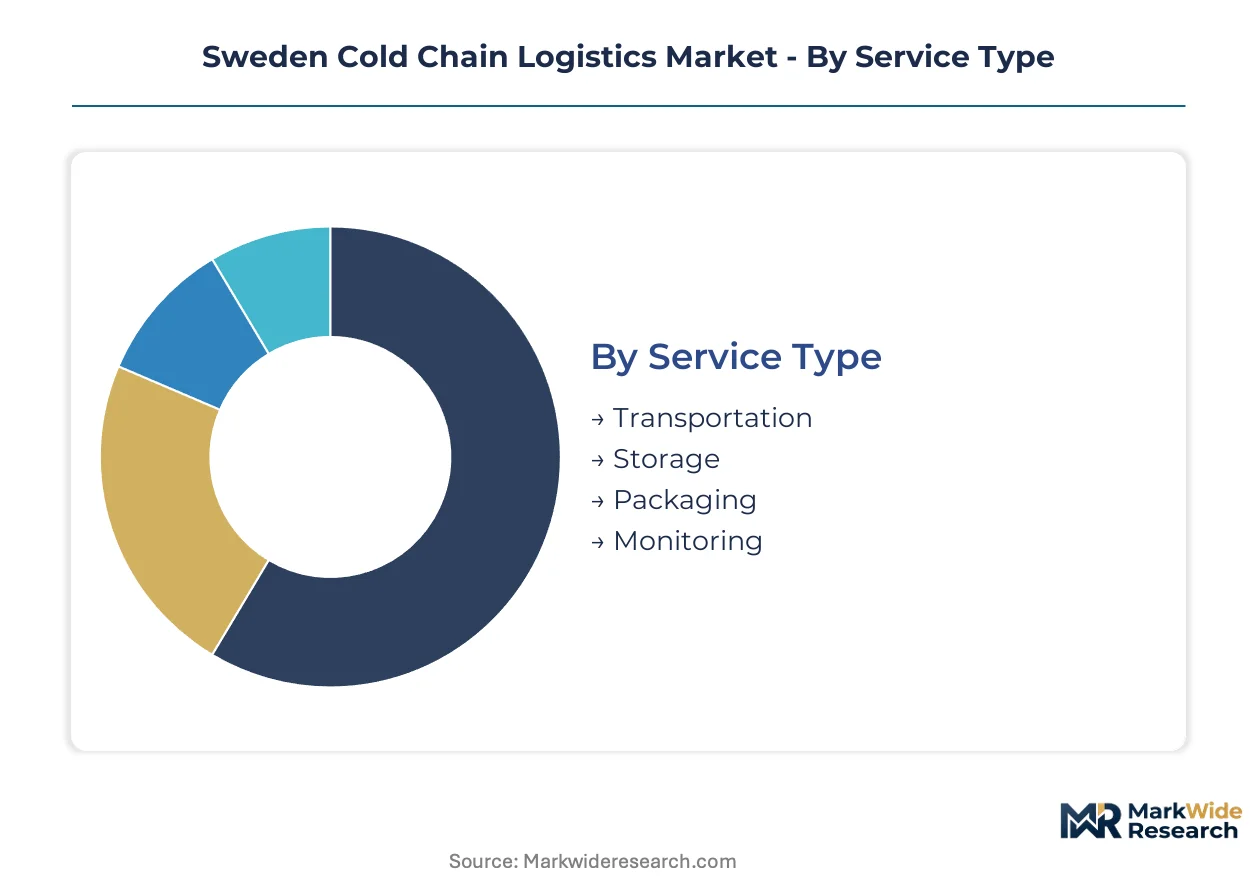
Temperature integrity requirements diverge sharply across Swedish pharmaceutical corridors versus food retail networks, forcing operators to configure equipment and compliance protocols around fundamentally different buyer risk profiles. Segmentation reveals how service specialization, thermal specifications, and regulatory density concentrate margin capture in distinct operational pockets.
Service Type:
Pharmaceutical distributors prioritize real-time documentation capabilities over pure transport speed, while food retailers optimize for cost-per-pallet across high-frequency replenishment cycles.
- Transportation:Refrigerated vehicle fleets configured for 2°C to 8°C pharmaceutical lanes command premium day rates versus frozen food haulage. Swedish Medical Products Agency GDP mandates are compressing carrier qualification timelines in the Stockholm-Uppsala corridor.
- Storage:Multi-temperature warehouses with segregated chambers for chilled biologics and frozen commodities dominate capital deployment. Urban land scarcity in Malmö and Gothenburg is elevating per-cubic-meter refrigeration costs above Nordic averages.
- Packaging:Insulated shippers with phase-change materials protect temperature-sensitive payloads during last-mile handoffs. Pharmaceutical parcel volumes are driving demand for validated thermal packaging in direct-to-pharmacy distribution models.
- Monitoring:IoT sensor networks providing continuous temperature logging and alert generation are becoming table stakes for GDP compliance. Hardware refresh cycles are accelerating as buyers mandate cloud-integrated telemetry.
Storage leads volumes today; monitoring is gaining share fastest.
Temperature Range:
Capital intensity escalates nonlinearly as temperature thresholds drop, with cryogenic infrastructure requiring fundamentally different engineering than conventional chilled systems.
- Frozen:Blast freezing operations at -18°C and below serve Swedish seafood export corridors and retail frozen food distribution. Electricity cost volatility in southern Sweden is compressing margins for energy-intensive freezing operations.
- Chilled:The 2°C to 8°C band dominates pharmaceutical biologics distribution and fresh dairy logistics. Uppsala's monoclonal antibody manufacturing cluster is expanding dedicated chilled lane capacity.
- Ambient:Controlled room temperature services handle packaging materials and non-refrigerated pharmaceutical ancillaries. This segment captures overflow volume during peak seasonal demand.
- Refrigerated:Broad-category transport and storage spanning multiple setpoints serves generalist third-party logistics providers. Fleet flexibility requirements are elevating multi-temperature vehicle specifications.
Chilled commands the steepest margin premium; frozen handles the largest tonnage throughput.
End User:
Regulatory audit frequency and documentation stringency separate pharmaceutical buyers from food and beverage operators, reshaping how logistics providers structure quality management systems.
- Pharmaceuticals:GDP-compliant distribution of vaccines, biologics, and temperature-sensitive therapeutics requires validated cold chain documentation. Swedish hospital pharmacy consolidation is favoring specialized carriers over generalist wholesalers.
- Food & Beverage:Fresh produce, dairy, meat, and frozen retail goods dominate volume throughput. Swedish Food Agency traceability mandates under EU hygiene regulations are elevating digital record-keeping requirements.
- Healthcare:Hospital and clinic supply chains for diagnostic reagents and blood products require intermediate temperature precision. Regional health authority procurement reforms are shifting toward outcome-based logistics contracts.
- Chemicals:Temperature-sensitive industrial and specialty chemicals occupy a niche with distinct hazard classification protocols. ATEX compliance for flammable refrigerants constrains facility location options.
Food and beverage anchors volume today; pharmaceuticals exhibits the strongest margin expansion trajectory.
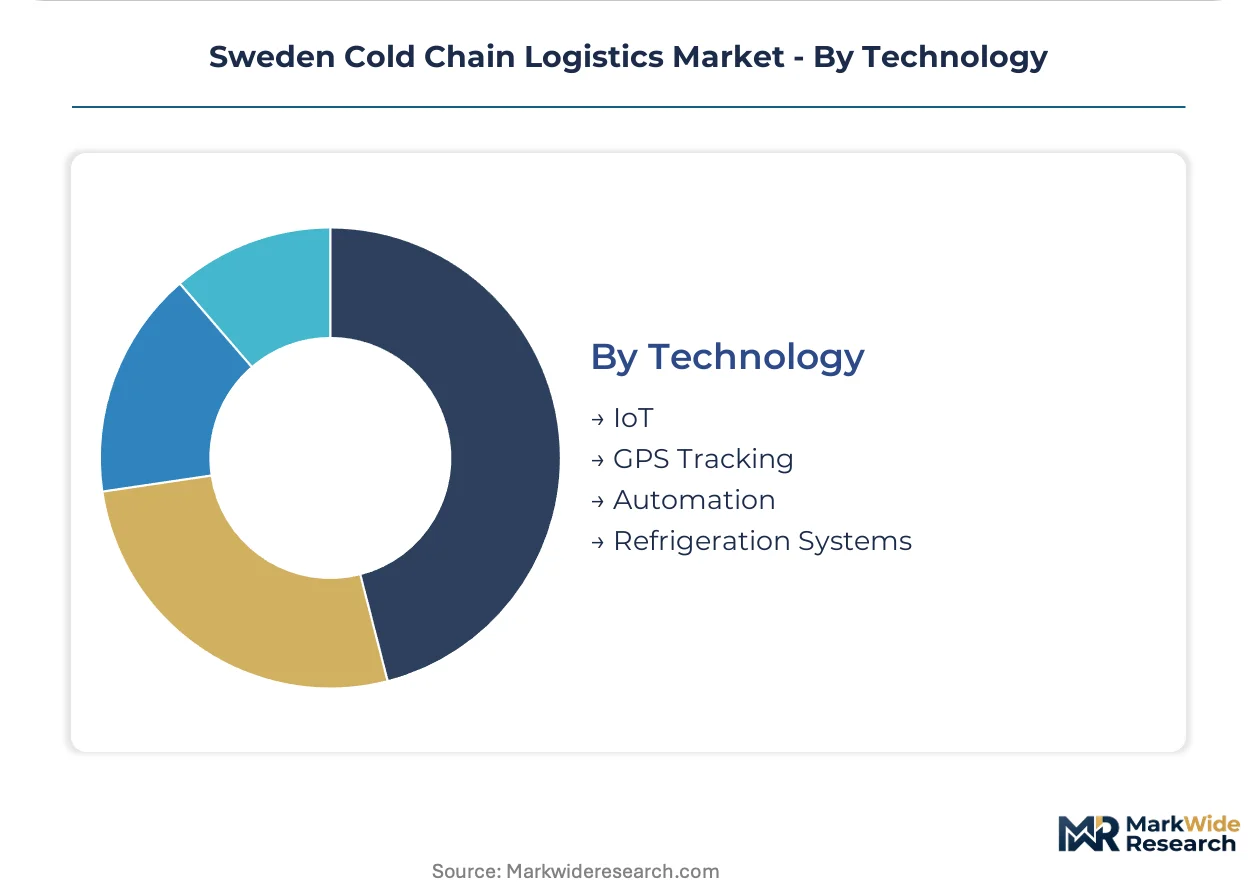
Technology:
Hardware refresh decisions increasingly hinge on interoperability with existing fleet management platforms and regulatory audit trail requirements rather than standalone performance specifications.
- IoT:Connected sensor networks enable real-time temperature, humidity, and location telemetry across multimodal shipments. Pharmaceutical GDP mandates are accelerating deployment of cellular-enabled data loggers.
- GPS Tracking:Geolocation systems provide chain-of-custody verification and route optimization for refrigerated fleets. Integration with temperature monitoring is becoming standard for high-value pharmaceutical lanes.
- Automation:Warehouse robotics and automated storage and retrieval systems reduce human touchpoints in temperature-controlled facilities. Labor scarcity in Swedish logistics hubs is elevating automation ROI calculations.
- Refrigeration Systems:Natural refrigerant compressors using ammonia and CO2 are displacing hydrofluorocarbon equipment ahead of EU F-Gas Regulation deadlines. Equipment supply concentration among German and Danish manufacturers is extending procurement lead times.
Refrigeration systems represent the largest installed base; IoT is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden's cold chain logistics industry traces its modern foundation to the 1970s expansion of pharmaceutical manufacturing in Uppsala and the consolidation of Nordic food retail distribution networks around Stockholm. This historical lineage established temperature-controlled infrastructure as a national competency long before biologics manufacturing reshaped demand profiles.
Stockholm-Uppsala Corridor
Monoclonal antibody production facilities and dense hospital pharmacy networks drive pharmaceutical cold chain demand. The Medical Products Agency enforces GDP compliance for all vaccine and biologics distribution. Uppsala's manufacturing cluster is expanding dedicated 2°C to 8°C lane capacity to serve export markets.
Gothenburg Metropolitan Area
Sweden's largest port handles temperature-controlled seafood exports and pharmaceutical transit to continental Europe. The Swedish Food Agency mandates traceability documentation under EU Regulation 852/2004 for all perishable cargo. Port operators are developing intermodal rail connections to bypass road congestion.
Skåne County
Intensive agricultural production and food processing create frozen and chilled distribution demand. EU F-Gas Regulation phase-down deadlines are accelerating ammonia and CO2 refrigeration system deployments. Malmö's urban land scarcity elevates cold storage construction costs above national averages.
Västra Götaland Region
Regional health authority procurement reforms favor outcome-based logistics contracts with guaranteed temperature integrity metrics. Direct-to-pharmacy distribution models are compressing traditional wholesale intermediation. Hospital pharmacy buyers in Gothenburg are consolidating volume commitments with specialized carriers.
Sweden Cold Chain Logistics Market Competitive Landscape
Capital-heavy cold storage operators compete with asset-light freight brokers for margin capture in Swedish temperature-controlled logistics. The market structure concentrates around integrated Nordic networks, regional specialists, and global forwarding groups. Three archetypes dominate: pharmaceutical GDP-certified carriers, multi-temperature food logistics providers, and intermodal rail-road operators. M&A activity targets specialized temperature capabilities, while fleet electrification programs absorb discretionary capital.
Among Germany-based forwarding groups, DHL Logistics and DB Schenker occupy positions anchoring pharmaceutical distribution and intermodal corridor development. Klimat Transport & Logistik AB represents the specialized regional archetype focused on multi-temperature food logistics operations.
| Leading Market Players |
|---|
| DHL Logistics |
| Klimat Transport & Logistik AB |
| DB Schenker |
| Bring Logistics |
| Nordic Cold Chain Solutions |
| Cool Carriers AB |
| Seafrigo Nordic AB |
| KMP Transport AB |
| NewCold Logistics |
| Others |
Pricing and Supply Chain Analysis
Horizontal consolidation among Nordic cold storage operators anchors both supply positioning and pricing power across Sweden's temperature-controlled logistics corridor. DHL Logistics and DB Schenker leverage integrated hub networks to capture pharmaceutical GDP-certified premiums, while regional specialists like Klimat Transport & Logistik AB defend food logistics margins through multi-temperature fleet specialization.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical GDP-certified lanes from general food haulage and ambient overflow services. Price differentiation hinges on Medical Products Agency certification grade and real-time IoT documentation capabilities. Cost compression in frozen food segments is intensifying because electricity volatility in southern Sweden elevates blast freezing operating expenditure. Hospital pharmacy buyers exhibit lowest price sensitivity due to outcome-based contracting mandates, while retail grocers drive hardest bargain on per-pallet storage rates.
Supply Chain Analysis
Direct-to-pharmacy channels handle consolidated hospital system demand, bypassing traditional wholesale intermediation in the Västra Götaland region. Equipment manufacturing concentrates in Germany and Denmark for natural refrigerant compressors, while ammonia and CO2 system components draw from Nordic specialist suppliers. Single-source vulnerability runs through German-Danish compressor manufacturing consolidation, extending fleet procurement lead times. Distribution runs through the Stockholm-Uppsala pharmaceutical corridor for biologics, with intermodal rail-road links serving Gothenburg port transit to continental Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's cold chain logistics market functions as a regulatory compounder where EU F-Gas Regulation phase-down deadlines force accelerated capital deployment toward natural refrigerant systems, structurally elevating compliance costs for uncertified operators.
For Market Incumbents: Cement pharmaceutical GDP certification moats by accelerating ammonia and CO2 refrigeration retrofits ahead of statutory deadlines. Expand dedicated 2°C to 8°C lane capacity in the Uppsala manufacturing cluster to capture monoclonal antibody distribution growth. Defend against specialized carrier encroachment through outcome-based contracting relationships with regional health authorities. For New Entrants and Emerging Players: Enter via cryogenic logistics capabilities for cell and gene therapy applications, where CAR-T treatment cold chains command premium service tiers beyond conventional temperature ranges. Target underdeveloped temperature-controlled rail connections from Gothenburg port to continental Europe as first-mover intermodal opportunity. Lead with blockchain-enabled temperature logging to differentiate audit trail documentation from incumbent paper-based systems. For Investors and Strategic Acquirers: Consolidation pressure builds where refrigeration technician scarcity constrains fleet electrification timelines, favoring acquirers with in-house training infrastructure. Five-to-ten-year viability favors operators with secured natural refrigerant equipment supply relationships and solar-powered cold storage assets. Monitor EU F-Gas Regulation enforcement intensity as inflection signal for distressed asset availability among laggard retrofitters.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant System Deployment | EU F-Gas Regulation compliance secures operational license continuity for Swedish cold storage facilities. |
| Pharmaceutical GDP Certification Investment | Medical Products Agency compliance enables access to monoclonal antibody distribution contracts in Uppsala. |
| IoT Sensor Network Integration | Real-time temperature telemetry satisfies hospital pharmacy outcome-based contracting requirements. |
| Intermodal Rail-Road Corridor Development | Gothenburg port connectivity reduces pharmaceutical transit congestion to continental European markets. |
| Cryogenic Logistics Capability Buildout | CAR-T therapy cold chains open premium service tiers beyond conventional 2°C to 8°C distribution. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture operational realities across Sweden's temperature-controlled logistics networks. Primary discussions engaged cold storage facility managers, pharmaceutical distribution executives, fleet procurement directors, and Swedish Food Agency compliance officers. Secondary validation drew from EU F-Gas Regulation implementation timelines, Medical Products Agency GDP guidance documents, Swedish Standards Institute equipment certifications, and Nordic power market price data. Bottom-up facility capacity modeling and top-down corridor demand aggregation were cross-checked for triangulation.
Historical reference periods spanning the 2019-2024 window anchored forward projections across the analysis window. Segmentation modeling incorporated service type, temperature range, end-user industry, and technology deployment dimensions. CAGRs were derived from equipment procurement cycle analysis, regulatory compliance cost trajectories, and pharmaceutical manufacturing expansion pipelines. Cryogenic logistics adoption curves and battery belt adjacency effects informed scenario-based forecast sensitivity.
Inputs from cold storage operators and pharmaceutical distributors were available through the study window; gaps in natural refrigerant equipment supply lead times introduce uncertainty bands around capital deployment timing assumptions. Forecasts reflect documented assumptions regarding EU regulatory enforcement intensity and Nordic electricity price normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Asean Freight Forwarding Market
Logistics and Shipping
United States Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
Sea Freight Forwarding Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
North America FMCG Logistics Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
Estonia Freight and Logistics Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
Germany Automotive 3PL Market