
 Thailand E-Commerce Logistics Market | 2026-2036
Thailand E-Commerce Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand E-Commerce Logistics Market Insights
Same-day delivery tier is unwinding across Bangkok's dense urban corridors, forcing incumbents to upgrade sortation automation and fleet electrification. Flash Express leverages its proprietary hub-and-spoke network to sustain next-day coverage across secondary provinces. Kerry Express anchors premium B2B contract logistics through temperature-controlled capabilities. J&T Express competes on cross-border parcel integration with Southeast Asian fulfillment lanes.
Thailand e-commerce logistics encompasses the physical movement, storage, and fulfillment of goods ordered through digital retail platforms, typically involving automated sortation systems processing 5,000–15,000 parcels per hour at peak throughput. Its primary commercial purpose is bridging inventory held in Bangkok-centric warehouses to dispersed consumers across 77 provinces within contracted delivery windows. Last-mile delivery dominates operational cost structures, absorbing roughly half of total fulfillment expenditure as rider density and route optimization determine unit economics. Express delivery is expanding fastest among delivery models, spurred by platform-level service guarantees and consumer willingness to pay for speed. Warehousing is maturing toward bonded and temperature-controlled specifications as cross-border e-commerce from China intensifies.
Thailand's Ministry of Digital Economy and Society, alongside the Electronic Transactions Development Agency, shapes platform accountability and data localization requirements that logistics providers must integrate into order management systems. The Bank of Thailand's prompt-pay infrastructure and digital wallet interoperability standards further condition cash-on-delivery volumes and rider payment reconciliation. Stakeholders must monitor whether proposed carbon offset mandates for delivery fleets will accelerate electric motorcycle adoption or compress margins for asset-light operators.
Market Dynamics
Same-day delivery guarantees across Bangkok's dense urban corridors are compressing sortation windows and forcing fleet electrification commitments from parcel operators.
Growth Catalysts
- Prompt-Pay Infrastructure:The Bank of Thailand's real-time payment rails are reducing cash-on-delivery friction and accelerating rider settlement cycles across last-mile networks.
- Fashion and Electronics Retail:Thai consumers in these segments are generating parcel volume density that justifies automated sortation investments in Greater Bangkok.
- Cross-Border E-Commerce Intensification:Fulfillment lanes from China are driving demand for bonded warehousing specifications and temperature-controlled capabilities.
Market Restraints
- Last-Mile Cost Concentration:Rider density requirements and route optimization complexity absorb roughly half of total fulfillment expenditure, compressing unit economics for asset-light operators.
- Secondary Province Coverage:Hub-and-spoke network economics disadvantage thinly populated provinces outside the Bangkok industrial corridor.
- Data Localization Compliance:Electronic Transactions Development Agency requirements impose order management system integration costs on logistics platforms.
Strategic Opportunities
- Temperature-Controlled B2B Contract Logistics:Premium segments in pharmaceuticals and fresh food remain underpenetrated relative to parcel delivery saturation.
- Electric Motorcycle Fleet Conversion:Proposed carbon offset mandates for delivery fleets create first-mover advantages for operators with capital deployment capacity.
- Secondary Province Next-Day Coverage:Flash Express has demonstrated proprietary network viability; comparable infrastructure gaps exist in northeastern and southern provinces.
Industry Challenges
- Sortation Automation Capex:Peak throughput requirements of 5,000–15,000 parcels per hour demand capital-intensive facility upgrades.
- Digital Wallet Interoperability:Rider payment reconciliation across multiple wallet standards complicates cash-on-delivery operations.
- Warehouse Bonding Certification:Cross-border fulfillment requires customs-integrated facility specifications with extended compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand E-Commerce Logistics Market |
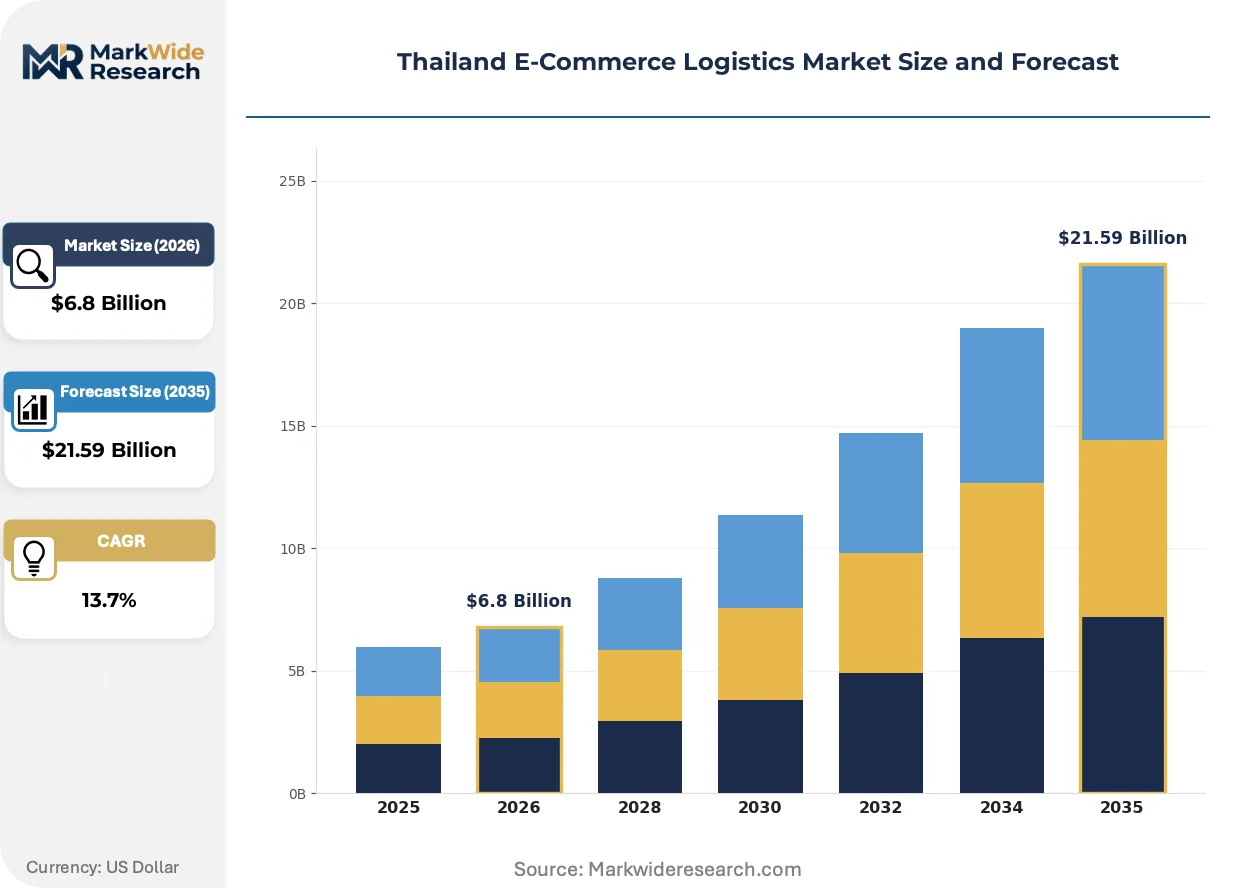
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Last-Mile Delivery, Order Fulfillment, Warehousing, Freight Forwarding Delivery Model: Same-Day Delivery, Scheduled Delivery, Standard Delivery, Express Delivery Customer Type: B2C, B2B, C2C, Online Marketplaces Packaging Type: Eco-Friendly Packaging, Bubble Wrap, Palletized Packaging, Bulk Packaging |
| Companies Covered | Thailand Post, Flash Express, J&T Express, Kerry Express, DHL eCommerce, SCG Express, FedEx, CJ Logistics, Ninja Van, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand E-Commerce Logistics Market Trends and Innovations
Automation, regulatory compliance, and consumer delivery expectations are converging to reshape capital deployment and operational priorities across Thai logistics networks.
Automated sortation systems are fragmenting traditional hub economics by enabling smaller, distributed processing nodes. E-commerce platforms and third-party logistics providers are deploying compact automation in provincial capitals to bypass Bangkok-centric consolidation. This technology is fragmenting the historical concentration of parcel processing in the capital corridor.
The Ministry of Digital Economy and Society's platform accountability frameworks are mandating traceability integration into order management systems. Logistics providers must embed real-time tracking and data localization protocols to maintain operating licenses. Express delivery operators face the steepest compliance costs given their direct platform integrations.
Consumer willingness to pay for speed is compressing delivery window expectations from next-day to same-day in Greater Bangkok. Traditional economy-tier options are losing share to guaranteed service levels with platform-level refunds for delays. This behavioral shift is most visible in fashion and electronics retail, where cancellation rates spike when delivery promises slip.
Thailand E-Commerce Logistics Market Segmentation
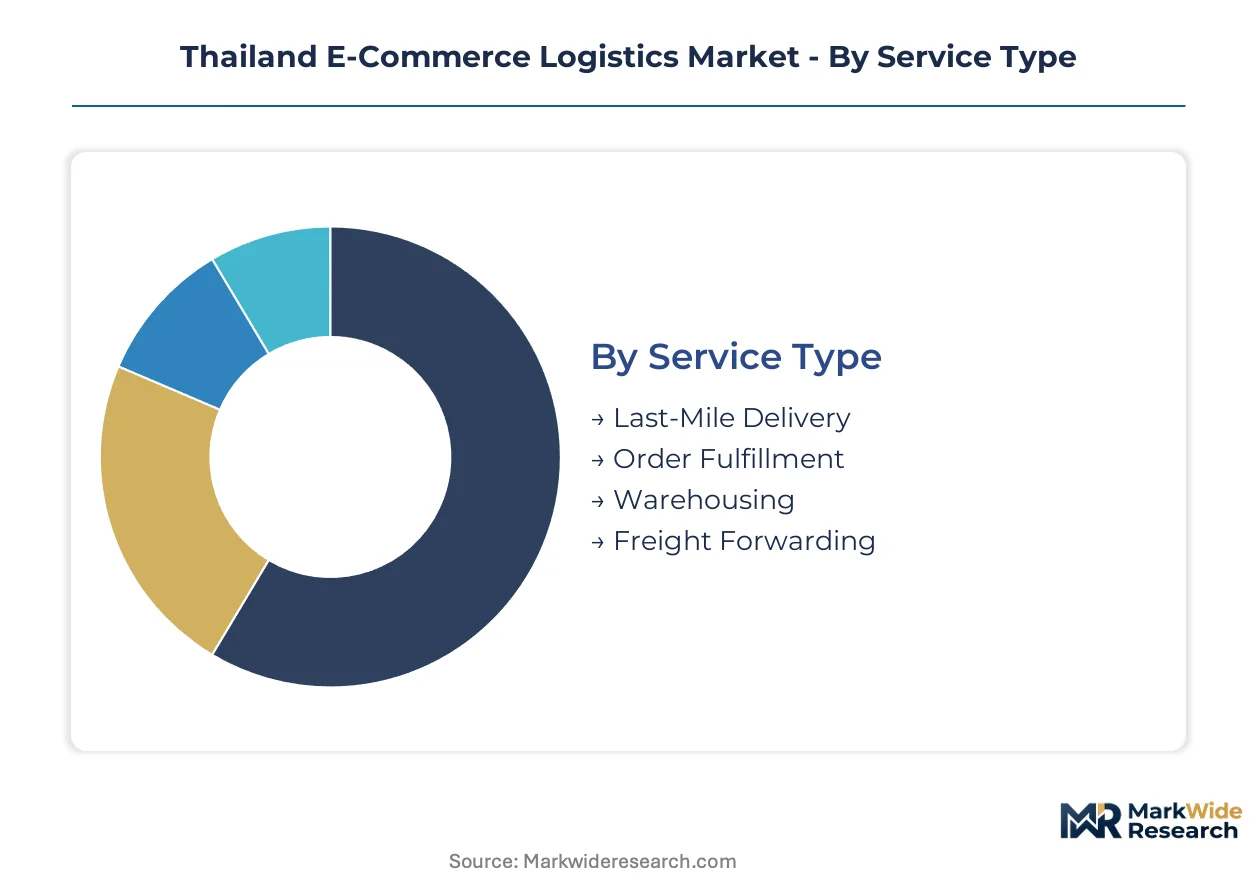
Thailand's e-commerce logistics market fragments across service architecture, delivery velocity commitments, customer contractual structures, and packaging specifications. Each dimension carries distinct capital intensity profiles and regulatory touchpoints that determine operator margin structures.
Service Type:
The Ministry of Digital Economy and Society's platform accountability frameworks impose traceability requirements that scale unevenly across service tiers, with last-mile operators facing the steepest compliance costs.
- Last-Mile Delivery:Rider-based parcel distribution from urban hubs to residential and commercial endpoints. Bangkok's dense urban corridors concentrate volume density that justifies electrified fleet investments, while secondary provinces strain unit economics.
- Order Fulfillment:Pick-pack-ship operations integrating warehouse management systems with platform order pipelines. Fashion and electronics retail segments drive automated sortation deployments processing 5,000–15,000 parcels per hour at peak.
- Warehousing:Inventory storage facilities spanning ambient, bonded, and temperature-controlled specifications. Cross-border e-commerce from China intensifies demand for customs-integrated bonded facilities with extended compliance timelines.
- Freight Forwarding:Consolidated cargo movement between international origins and Thai distribution nodes. Temperature-controlled capabilities anchor premium B2B contract logistics in pharmaceuticals and fresh food segments.
Last-mile delivery handles the majority of throughput; order fulfillment is gaining share fastest as platform service guarantees tighten.
Delivery Model:
Cost-to-serve differentials between velocity tiers are widening as Bangkok consumers demonstrate willingness to pay for compression from next-day to same-day windows.
- Same-Day Delivery:Guaranteed fulfillment within hours of order placement, enabled by distributed micro-fulfillment nodes. Greater Bangkok's urban density supports this tier, though cancellation rates spike when platform promises slip.
- Scheduled Delivery:Customer-designated arrival windows balancing convenience with operational predictability. Electronics retail segments favor this model for high-value items requiring recipient presence.
- Standard Delivery:Economy-tier service with extended windows, traditionally dominant outside Bangkok. Share erosion accelerates as guaranteed service levels with platform-level refunds capture consumer preference.
- Express Delivery:Next-day coverage commitments across provincial networks. Flash Express has demonstrated proprietary hub-and-spoke viability in secondary provinces where infrastructure gaps persist.
Express delivery handles the majority of throughput; same-day delivery is expanding most quickly on share.
Customer Type:
Application-specific requirements fragment procurement patterns, with B2B contracts demanding temperature-controlled capabilities that B2C parcel networks rarely replicate.
- B2C:Direct-to-consumer parcel delivery from digital retail platforms. The Bank of Thailand's prompt-pay infrastructure reduces cash-on-delivery friction and accelerates rider settlement cycles.
- B2B:Commercial contract logistics serving enterprise supply chains. Premium segments in pharmaceuticals and fresh food remain underpenetrated relative to parcel delivery saturation.
- C2C:Peer-to-peer parcel exchange through platform-mediated marketplaces. Digital wallet interoperability standards complicate payment reconciliation across multiple wallet providers.
- Online Marketplaces:Platform-integrated logistics serving multi-merchant ecosystems. Electronic Transactions Development Agency data localization requirements impose order management system integration costs.
B2C handles the majority of throughput; B2B is climbing the fastest on share.
Packaging Type:
Margin structures vary with material specifications, as proposed carbon offset mandates for delivery fleets extend to packaging waste accountability.
- Eco-Friendly Packaging:Biodegradable or recyclable materials aligned with emerging sustainability mandates. Regulatory pressure on fleet emissions suggests parallel packaging compliance timelines.
- Bubble Wrap:Protective cushioning for fragile electronics and fashion items. Electronics retail segments generate concentrated demand for damage-prevention specifications.
- Palletized Packaging:Unitized freight handling for B2B and warehouse transfer movements. Temperature-controlled B2B contract logistics favors palletized handling for pharmaceutical integrity.
- Bulk Packaging:Consolidated shipment configurations for high-volume merchants. Cross-border fulfillment lanes from China drive bonded warehousing specifications for bulk customs processing.
Bubble wrap handles the majority of throughput; eco-friendly packaging is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hub-and-spoke network economics concentrate fulfillment infrastructure within Thailand's central plains, while secondary provinces strain under thin population density and extended delivery windows.
Greater Bangkok
Fashion and electronics retail segments generate parcel volume density that justifies automated sortation investments processing 5,000–15,000 parcels per hour. The Ministry of Digital Economy and Society's platform accountability frameworks mandate traceability integration into order management systems. Bangkok's dense urban corridors now sustain same-day delivery tiers, forcing fleet electrification commitments from parcel operators competing on speed.
Eastern Economic Corridor
Cross-border e-commerce from China intensifies demand for bonded warehousing specifications and customs-integrated facilities. The Bank of Thailand's prompt-pay infrastructure reduces cash-on-delivery friction and accelerates rider settlement cycles. Laem Chabang port and surrounding industrial zones anchor temperature-controlled capabilities for pharmaceuticals and fresh food segments.
Central Plains
Agricultural e-commerce platforms drive C2C parcel exchange through platform-mediated marketplaces. Electronic Transactions Development Agency data localization requirements impose order management system integration costs on logistics platforms. Ayutthaya and surrounding provinces serve as overflow warehousing zones for Bangkok-centric inventory.
Northeastern Region
Flash Express has demonstrated proprietary hub-and-spoke viability where infrastructure gaps persist for next-day coverage. Digital wallet interoperability standards complicate payment reconciliation across multiple wallet providers. Khon Kaen and Udon Thani represent concentrated demand nodes in an otherwise dispersed regional landscape.
Southern Region
Island and coastal geography fragments last-mile economics despite tourism-driven retail activity. Proposed carbon offset mandates for delivery fleets create first-mover advantages for operators with capital deployment capacity. Hat Yai functions as the primary logistics hub connecting peninsular Thailand with Malaysian cross-border lanes.
Thailand E-Commerce Logistics Market Competitive Landscape
Concentration sits with diversified express networks that combine proprietary sortation infrastructure with multi-provincial coverage. The market structure spans three tiers: state-affiliated postal operators with universal service obligations, regional express specialists with hub-and-spoke density, and international integrators with cross-border capabilities. Strategic archetypes include automation-heavy parcel networks, temperature-controlled contract logistics providers, and asset-light platform aggregators. Dominant competitive moves encompass fleet electrification commitments and bonded warehousing certification for cross-border fulfillment.
Within the regional express tier, Flash Express and Kerry Express exemplify contrasting infrastructure strategies, while J&T Express occupies a position emphasizing cross-border parcel integration. Thailand Post anchors the state-affiliated tier with universal coverage obligations. DHL eCommerce and FedEx represent international integrators leveraging global network density for premium segments. Ninja Van and CJ Logistics sit within the Southeast Asian regional expansion archetype, competing on platform-level service guarantees across multiple national markets.
| Leading Market Players |
|---|
| Thailand Post |
| Flash Express |
| J&T Express |
| Kerry Express |
| DHL eCommerce |
| SCG Express |
| FedEx |
| CJ Logistics |
| Ninja Van |
| Others |
Pricing and Supply Chain Analysis
Hub throughput scale at 5,000–15,000 parcels per hour concentrates pricing power among Bangkok-centric operators with automated sortation, while thin volume density in secondary provinces elevates per-unit cost floors for regional coverage. This scale asymmetry shapes a market where electrified fleet commitments and bonded warehousing certification function as price-defending barriers.
Pricing Analysis
The Bank of Thailand's prompt-pay infrastructure dictates the pricing tier structure across last-mile networks, compressing cash-on-delivery premiums and accelerating settlement-driven cost efficiencies. Three-tier pricing structure across premium, standard, and economy levels separates same-day guarantees in Greater Bangkok from next-day provincial coverage and extended economy windows. Pricing pressure stems from rider density requirements absorbing roughly half of fulfillment expenditure, squeezing margins for asset-light operators. B2C parcel delivery demonstrates highest price sensitivity due to platform-level refund guarantees, while temperature-controlled B2B contract logistics maintains pricing resilience through pharmaceutical and fresh food certification requirements.
Supply Chain Analysis
Laem Chabang port congestion on inbound lanes from China elevates container availability risk for cross-border fulfillment inventory, conditioning bonded warehousing demand. Supply concentration rests on Chinese manufacturing origins for electronics and fashion inventory, Thai agricultural outputs for C2C agricultural platforms, and Malaysian cross-border lanes for southern region connectivity. Critical dependencies include automated sortation equipment, electric motorcycle fleets, and temperature-controlled vehicle specifications. Single-source vulnerability sits with proprietary hub-and-spoke networks in secondary provinces where Flash Express holds demonstrated viability. Distribution runs through Bangkok-centric consolidation nodes with provincial micro-fulfillment bypass emerging in automated sortation deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's e-commerce logistics market sits at a platform-economics inflection where the Electronic Transactions Development Agency's data localization mandates and digital wallet interoperability standards are rewiring competitive moats around order management system integration.
For Market Incumbents: Secure temperature-controlled B2B contract logistics capacity in pharmaceuticals and fresh food segments before specialized operators capture premium margin pools. Consolidate proprietary hub-and-spoke density in northeastern and southern provinces where Flash Express has demonstrated network viability but infrastructure gaps persist for next-day coverage. Electrified fleet commitments must accelerate ahead of proposed carbon offset mandates to defend position against capital-constrained asset-light competitors. For New Entrants and Emerging Players: Differentiate on secondary province next-day coverage where hub-and-spoke economics have discouraged incumbent investment, particularly in Khon Kaen and Udon Thani demand nodes. Target underpenetrated temperature-controlled B2B segments with pharmaceutical integrity specifications that parcel-saturated operators rarely replicate. Go-to-market leverage rests on customs-integrated bonded warehousing certification for cross-border e-commerce lanes from China. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automation-heavy parcel networks with demonstrated provincial coverage and platform-level service guarantee integration. Long-term viability hinges on operators with capital deployment capacity for fleet electrification and sortation automation ahead of regulatory compliance deadlines. Acquisition target archetype: regional express specialists with proprietary hub-and-spoke density and cross-border fulfillment certification. Signal to watch: Ministry of Digital Economy and Society carbon offset mandate finalization as fleet conversion inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Program | Positions operators ahead of Ministry of Digital Economy and Society carbon offset compliance mandates. |
| Bonded Warehousing Certification | Enables customs-integrated cross-border fulfillment from China through Laem Chabang corridor. |
| Automated Sortation Deployment | Achieves 5,000–15,000 parcels per hour throughput to sustain same-day guarantees in Greater Bangkok. |
| Temperature-Controlled Capability Buildout | Captures premium B2B contract logistics in pharmaceuticals and fresh food segments. |
| Provincial Hub Network Expansion | Extends next-day coverage to northeastern and southern provinces with demonstrated demand nodes. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with logistics operations directors, platform partnership leads, fleet procurement managers, and customs compliance officers; and secondary validation through Electronic Transactions Development Agency regulatory filings, Bank of Thailand payment infrastructure disclosures, and bonded warehousing certification databases. Primary fieldwork combined with trade lane volume data and operator capex disclosures enabled bottom-up and top-down triangulation across the projection horizon.
Across the modeling period, the analytical framework segmented volume and value outputs by service architecture, delivery velocity commitment, customer contractual structure, and packaging specification. CAGRs were derived from parcel throughput trajectories, warehouse absorption rates, and fleet utilization assumptions. Industry-specific forecast inputs included platform-level service guarantee penetration rates and cross-border e-commerce lane intensification from China.
Material uncertainties — regulatory timeline shifts for carbon offset mandates, digital wallet interoperability standard revisions, and bonded warehousing compliance delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding rider density economics and automated sortation deployment schedules. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Spain Freight and Logistics Market
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
Poland Third Party Logistics (3PL) Market
Logistics and Shipping
GCC Event Logistics Market
Logistics and Shipping
Intra-Asia Freight Forwarding Market
Logistics and Shipping
Sweden Courier, Express, and Parcel Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
Iraq Freight and Logistics Market
Logistics and Shipping
Ocean Freight Forwarding Market
Logistics and Shipping
United States Freight Brokerage Market
Logistics and Shipping
California Freight and Logistics Market
Logistics and Shipping
North America Cross Border Road Freight Transport Market
Logistics and Shipping
Australia Freight and Logistics Market
Logistics and Shipping
Latin America Air Freight Market