
 Global Digital Wound Measurement Devices Market | 2026-2036
Global Digital Wound Measurement Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Wound Measurement Devices Market Intelligence
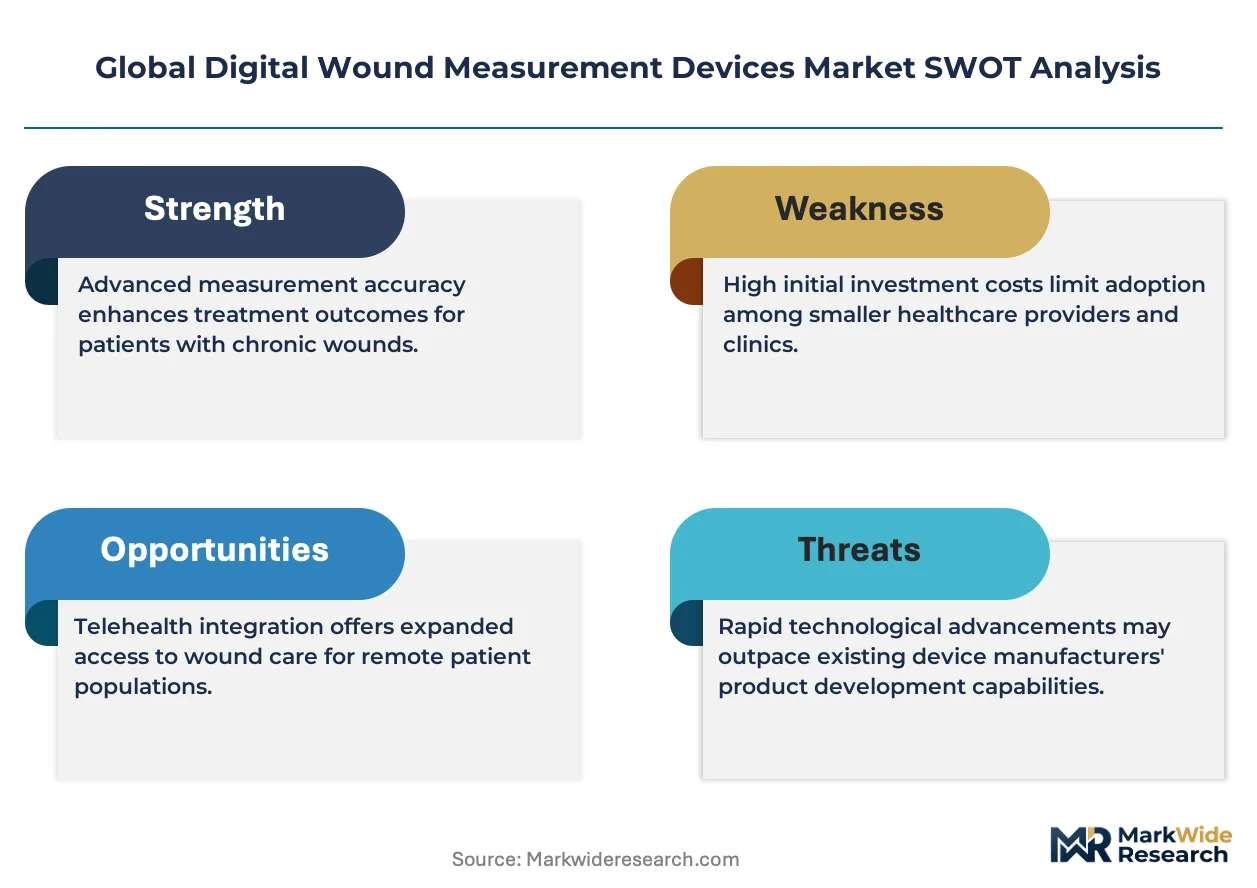
The increasing emphasis on decentralized care by Home Care Providers is redrawing the traditional market structure dominated by hospital-based wound care specialists. Swift Medical Inc. leverages its mobile-first platform to serve this distributed care model effectively. In contrast, Smith & Nephew plc sustains its position through extensive relationships with integrated hospital systems. Kent Imaging Inc. specializes in near-infrared spectroscopy technology for tissue oxygenation assessment.
Digital wound measurement devices are non-contact instruments that capture and analyze wound characteristics for objective clinical assessment. These systems utilize 3D imaging or photogrammetry to precisely calculate wound area, depth, and volume, eliminating manual measurement variability. Among product types, 3D Imaging Devices are gaining prominence over legacy laser systems. In application, chronic wound assessment for diabetic ulcer evaluation constitutes the largest source of clinical demand.
Market access hinges on clearance from bodies like the U.S. FDA and adherence to Europe's Medical Device Regulation (MDR). These frameworks mandate stringent clinical data validation and cybersecurity protocols for connected devices. Navigating the distinct approval pathways of regulators like Japan's PMDA is also critical. Success for device manufacturers depends on demonstrating improved patient outcomes and workflow efficiency to secure reimbursement.
Market Dynamics
The central force shaping the market is the integration of artificial intelligence into imaging platforms. This shift enables automated tissue classification and predictive analytics, moving devices beyond simple measurement tools to become core components of clinical decision support systems in chronic care.
Growth Catalysts
- Demographic Pressures:Japan's rapidly aging population and high prevalence of chronic conditions like diabetes create sustained demand for technologies that support efficient, long-term wound management in both hospital and home settings.
- Value-Based Care Initiatives:Reimbursement models in the United States are increasingly tied to patient outcomes, incentivizing providers to adopt objective measurement tools that document healing progress and improve care coordination.
- AI-Powered Analytics:The incorporation of artificial intelligence algorithms for automated wound tissue analysis improves diagnostic consistency and reduces the clinical assessment workload, accelerating adoption among time-constrained healthcare professionals.
Market Restraints
- High Acquisition Costs:The significant upfront capital investment required for advanced 3D imaging systems remains a substantial barrier for smaller clinics, independent practices, and home care agencies with limited budgets.
- Fragmented Regulatory Pathways:Navigating the distinct and rigorous approval processes of the U.S. FDA, Europe's MDR, and Japan's PMDA creates significant compliance overhead and time-to-market delays for manufacturers.
- Interoperability Hurdles:A lack of standardized data protocols complicates the integration of digital wound data into existing Electronic Health Record (EHR) systems, limiting workflow efficiency and data accessibility for clinicians.
Strategic Opportunities
- Expansion into Acute Care:Applying digital measurement technology to monitor post-operative surgical incisions and traumatic wounds represents a significant opportunity beyond the established chronic wound care segment.
- Sensor Fusion Development:Combining 3D imaging with thermal or hyperspectral sensors can provide a more comprehensive wound assessment, including infection indicators or tissue perfusion, creating higher-value diagnostic devices.
- Telehealth Platform Integration:Embedding wound measurement capabilities directly into major telehealth and remote patient monitoring platforms offers a new distribution channel to reach decentralized care providers at scale.
Industry Challenges
- Cybersecurity and Data Privacy:Ensuring compliance with data protection regulations like HIPAA in the U.S. and GDPR in Europe is a critical challenge for connected devices that transmit sensitive patient health information.
- Clinician Training and Adoption:Overcoming resistance to change and providing adequate training for healthcare staff to effectively use new digital tools and interpret their outputs is essential for successful implementation.
- Standardization of Metrics:A lack of universal standards for wound data collection and reporting across different devices hinders the ability to conduct large-scale research and compare clinical trial outcomes effectively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Wound Measurement Devices Market |
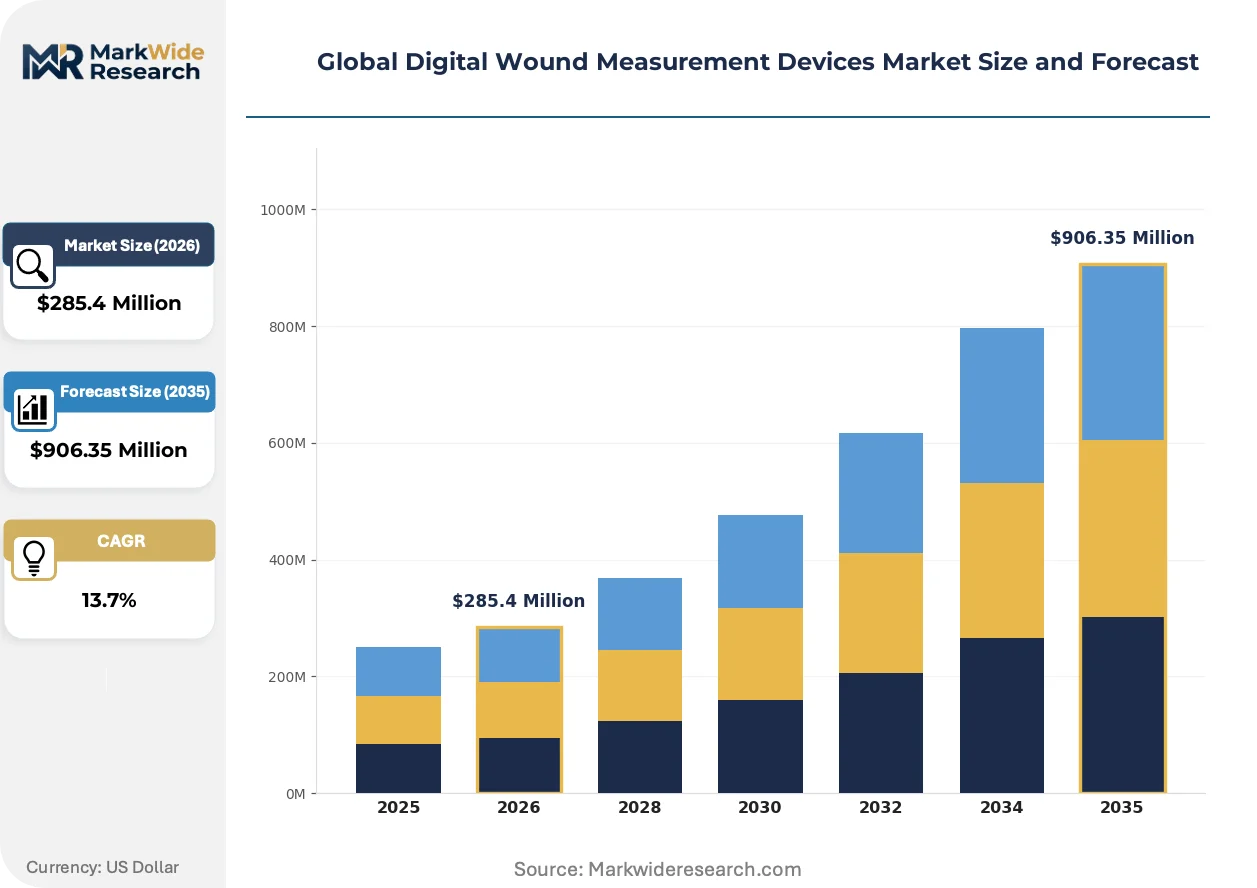
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $906.35 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Measurement Devices, Ultrasonic Measurement Devices, Photogrammetry Devices, 3D Imaging Devices Application: Chronic Wound Assessment, Surgical Wound Monitoring, Burn Care, Diabetic Ulcer Evaluation End User: Wound Care Specialists, Burn Treatment Centers, Rehabilitation Clinics, Home Care Providers Deployment Mode: Mobile Devices, Handheld Instruments, Standalone Systems, Integrated Hospital Equipment |
| Companies Covered | 3M company, Kent Imaging Inc., Swift Medical Inc., ARANZ Medical Limited, WoundVision, MolecuLight Inc., eKare Inc., WoundZoom Inc., Smith & Nephew plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Wound Measurement Devices Market Strategic Shifts & Innovations
Automation is fundamentally altering clinical workflows in wound care. The evolution from manual measurement to automated, data-driven assessment allows for more precise tracking of healing trajectories and facilitates remote oversight by specialized clinicians, improving access to expert care.
Near-infrared spectroscopy is a key technology providing non-invasive tissue oxygenation and perfusion data. Specialized wound care centers are adopting this technology for objective assessment of tissue viability in complex chronic wounds. The core sensor technology is miniaturizing, enabling the development of more accessible handheld devices for use at the patient's bedside or in a home care setting.
Europe's Medical Device Regulation (MDR) elevates the requirements for clinical evidence and post-market surveillance. This framework forces manufacturers to generate more extensive data validating device accuracy, safety, and clinical benefits. Software as a Medical Device (SaMD) applications are particularly affected, requiring robust documentation of their algorithms and stringent cybersecurity measures.
Reimbursement models are evolving from one-time capital equipment sales toward recurring software-as-a-service (SaaS) subscriptions. This payment structure lowers the initial investment barrier for home care providers and outpatient clinics, aligning costs with ongoing use. The trend is most visible in the United States, where it supports the financial model for scalable remote patient monitoring programs.
Global Digital Wound Measurement Devices Market Segmentation
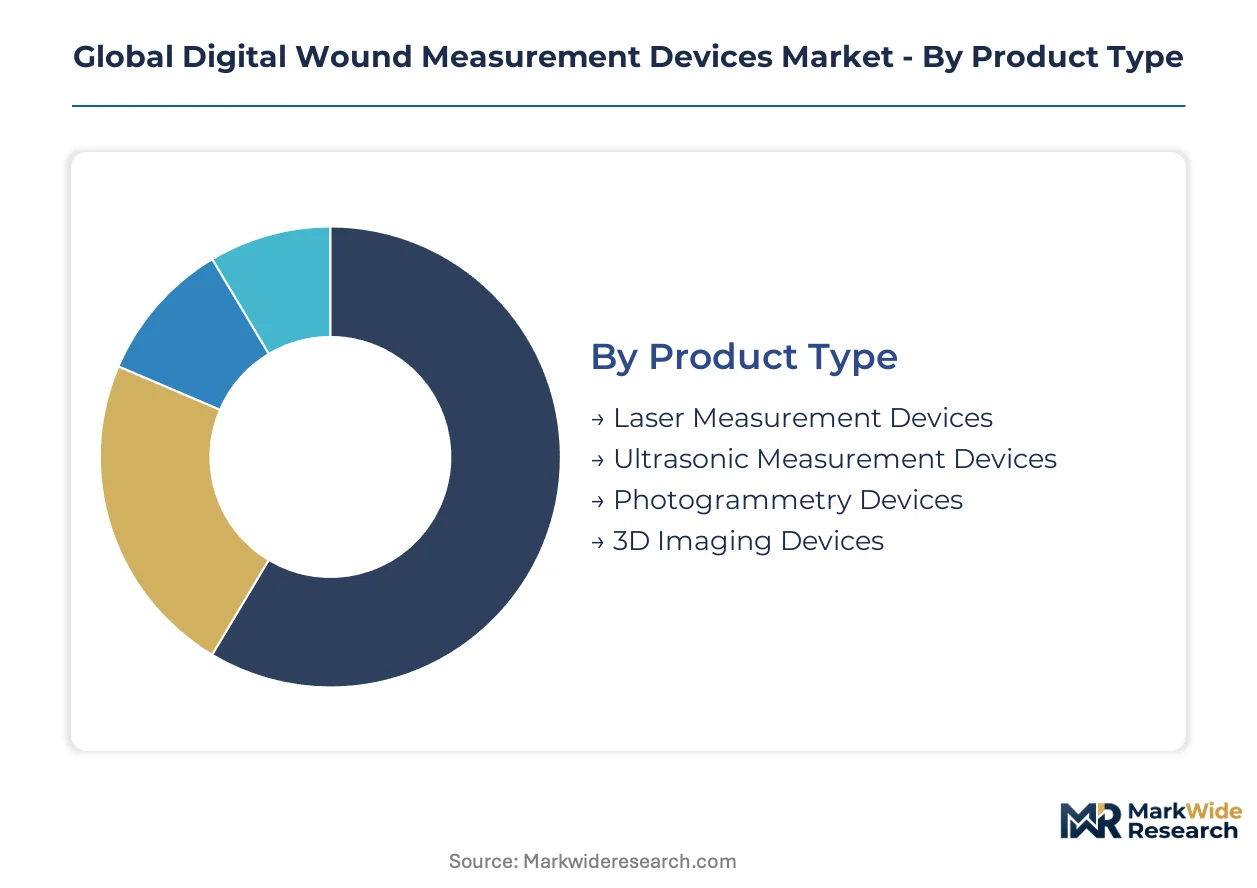
The Global Digital Wound Measurement Devices Market segments across several dimensions, reflecting the diverse technological approaches, clinical applications, end-user requirements, and deployment models. Understanding these distinctions is critical for manufacturers to tailor product development and market entry strategies effectively.
Product Type:
Regulatory bodies differentiate digital wound measurement devices based on their underlying imaging technologies, influencing approval pathways and clinical validation requirements.
- 3D Imaging Devices:These instruments capture comprehensive wound surface data using advanced optical sensors, creating detailed volumetric models. Demand in Japan is strong, driven by the need for precise chronic care management in an aging population.
- Photogrammetry Devices:Utilizing standard cameras and specialized software, these devices construct 3D wound models from multiple 2D images. Home Care Providers increasingly adopt this technology for remote patient monitoring due to its accessibility and ease of use.
- Laser Measurement Devices:These legacy systems employ laser triangulation for basic wound area and perimeter calculations, offering a cost-effective but less comprehensive assessment.
- Ultrasonic Measurement Devices:Using high-frequency sound waves, these devices assess wound depth and tissue characteristics, providing non-invasive insights particularly for deeper wounds.
Established volume favors Laser Measurement Devices; emerging adoption favors 3D Imaging Devices.
Application:
The clinical utility of digital wound measurement devices varies across distinct medical applications, each requiring specific analytical capabilities.
- Chronic Wound Assessment:This application involves continuous monitoring of slow-healing wounds, including pressure ulcers and venous leg ulcers, to track healing progression. Value-based care initiatives in the United States incentivize providers to adopt these tools for objective outcome documentation.
- Diabetic Ulcer Evaluation:Specifically targeting diabetic foot ulcers, this application requires precise measurement of wound dimensions and tissue viability for effective management and prevention of complications. Japan's high prevalence of diabetes creates sustained demand for these specialized tools.
- Surgical Wound Monitoring:Digital devices assess post-operative incision sites for early detection of complications like dehiscence or infection, improving patient recovery outcomes.
- Burn Care:These systems provide objective assessment of burn depth and surface area, crucial for guiding treatment strategies and monitoring healing in specialized burn treatment centers.
Demand concentrates heavily in chronic wound management, while acute care settings present significant expansion opportunities.
End User:
Different end-user segments integrate digital wound measurement devices into their clinical workflows, each driven by unique operational needs.
- Home Care Providers:These entities leverage digital devices for remote monitoring of patients in their homes, improving access to care and reducing hospital visits. The shift towards decentralized care models directly drives their adoption of mobile-first platforms.
- Wound Care Specialists:Physicians, nurses, and other clinicians specializing in wound management utilize these devices for objective assessment, treatment planning, and documentation in various clinical settings. AI-powered analytics improve diagnostic consistency for these time-constrained professionals.
- Burn Treatment Centers:Specialized facilities use digital tools for precise assessment and monitoring of burn injuries, supporting critical decision-making for complex cases.
- Rehabilitation Clinics:These clinics employ digital wound measurement to track healing progress for patients with pressure ulcers or other chronic wounds during their recovery and physical therapy.
Market penetration is highest among specialized clinicians, with rapid expansion observed in home-based care settings.
Deployment Mode:
The physical form factor and integration capabilities of digital wound measurement devices dictate their usability and deployment environment.
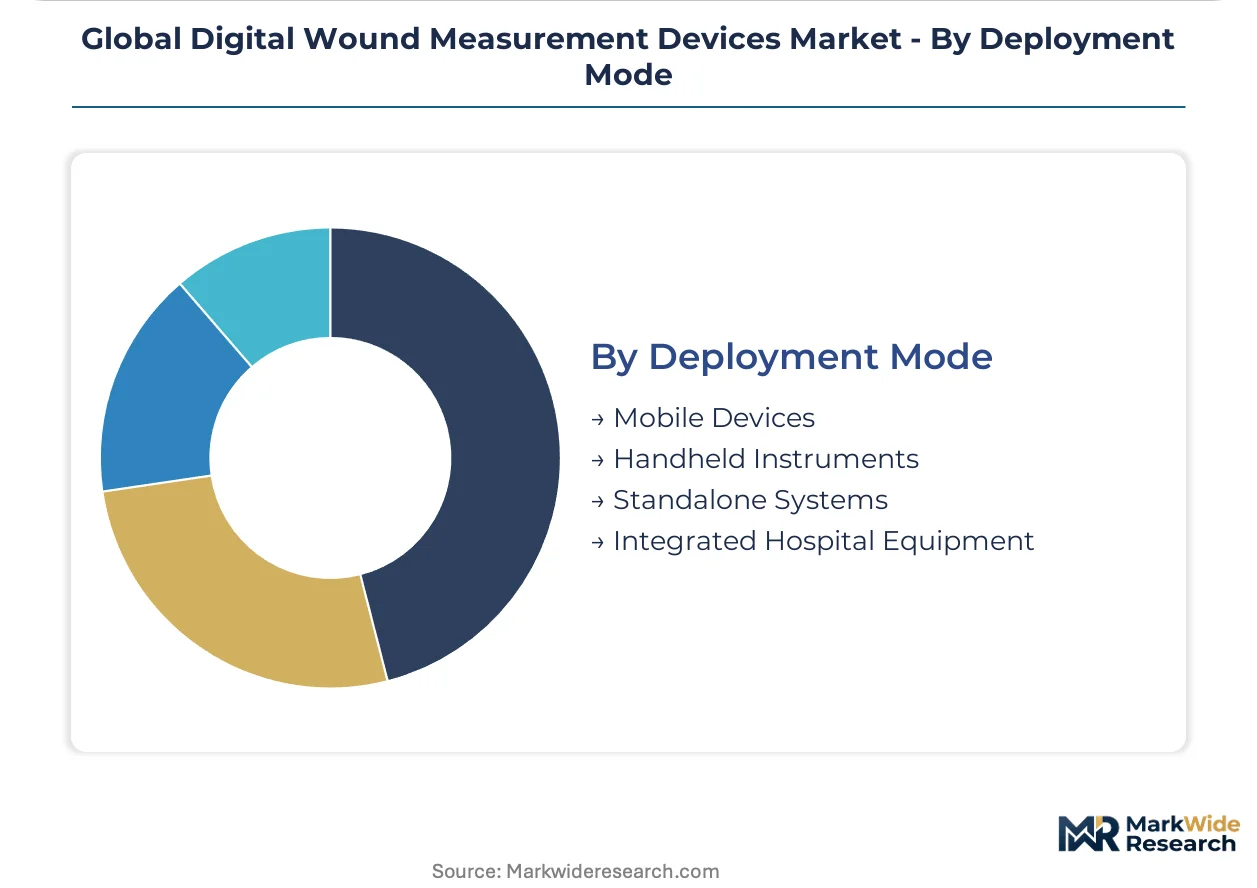
- Mobile Devices:These platforms, often smartphone or tablet-based, enable flexible, point-of-care wound assessment and are critical for telehealth and remote patient monitoring. Integration into existing telehealth platforms offers a new distribution channel.
- Handheld Instruments:Compact and portable, these dedicated devices offer specialized imaging and measurement capabilities for bedside use or in outpatient clinics. Miniaturization of core sensor technology enables more accessible handheld solutions.
- Standalone Systems:These dedicated units provide comprehensive wound analysis capabilities within a fixed clinical setting, often featuring larger screens and advanced software.
- Integrated Hospital Equipment:Digital wound measurement modules are incorporated into broader hospital information systems or existing medical carts, streamlining data flow within integrated hospital systems.
Technological evolution favors portable and integrated solutions, moving away from bulky, fixed installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global digital wound measurement devices market's infrastructure, built on advanced healthcare networks, underwrites its regional growth. Demand for these tools reflects diverse healthcare priorities, demographic shifts, and regulatory environments across key geographies. Each region contributes distinct drivers and challenges to the market's expansion.
Japan
Japan's robust national healthcare system drives sustained demand for digital wound measurement devices, particularly in chronic care. The country's rapidly aging population and high prevalence of diabetes necessitate efficient, long-term wound management solutions. The PMDA's clear regulatory pathways support market entry for innovative medical technologies. Tokyo's advanced medical research institutions actively integrate these devices into clinical practice and telehealth initiatives.
United States
The United States' extensive network of specialized wound care centers fuels the adoption of advanced digital measurement tools. Value-based care initiatives incentivize providers to document healing progression objectively, aligning with device capabilities. The U.S. FDA's stringent approval process ensures device efficacy and safety. Major metropolitan areas like Boston and San Francisco serve as hubs for medical device innovation, fostering new product development.
Germany
Germany's strong emphasis on clinical excellence and patient outcomes promotes the integration of digital wound measurement devices into hospital systems. The country's comprehensive healthcare insurance system supports investment in technologies that improve care coordination. Europe's Medical Device Regulation (MDR) sets high standards for clinical evidence and post-market surveillance. Cities like Munich and Berlin are centers for medical technology manufacturing and research.
United Kingdom
The United Kingdom's National Health Service (NHS) increasingly prioritizes remote patient monitoring and decentralized care, creating opportunities for digital wound solutions. Initiatives to reduce hospital readmissions for chronic conditions drive the adoption of objective measurement tools. Regulatory bodies within the UK align with European standards for medical device approval. London's vibrant health-tech ecosystem fosters innovation in connected medical devices.
Global Digital Wound Measurement Devices Market Key Industry Players
Concentration sits with established medical device manufacturers offering comprehensive solutions, alongside agile specialists focusing on niche technologies. The market features a blend of large, diversified players and innovative, mobile-first companies. Strategic archetypes include integrated system providers, specialized technology developers, and decentralized care platform innovators. Competitive moves often involve strategic partnerships to expand market reach and continuous innovation in AI-powered analytics.
Within the integrated hospital systems archetype, Smith & Nephew plc occupies a significant position, leveraging its extensive relationships with healthcare networks. Swift Medical Inc. exemplifies the mobile-first platform archetype, specifically serving the decentralized care model. Kent Imaging Inc. represents a specialized technology developer, focusing on near-infrared spectroscopy for tissue oxygenation assessment. These companies anchor different segments of the digital wound measurement devices market.
| Leading Market Players |
|---|
| 3M company |
| Kent Imaging Inc. |
| Swift Medical Inc. |
| ARANZ Medical Limited |
| WoundVision |
| MolecuLight Inc. |
| eKare Inc. |
| WoundZoom Inc. |
| Smith & Nephew plc |
| Others |
Cost & Logistics Intelligence
Average manufacturing lead times for advanced 3D imaging sensors, often exceeding 12 weeks, directly influence device availability and upstream component pricing power. This extended lead time necessitates strategic inventory management for device manufacturers.
Pricing Analysis
Volume-based discount structures characterize hardware sales, while software subscriptions often follow a tiered SaaS model based on user count or feature sets. Price differentiation stems from FDA/MDR clearance and the sophistication of AI-powered analytics. Pricing softness reflects increasing competition and value-based care initiatives incentivizing cost-efficiency. Home Care Providers and smaller clinics exhibit the highest price sensitivity, contrasting with larger hospital systems prioritizing comprehensive features.
Supply Chain Analysis
Strategic stockpiling of critical components like advanced optical sensors and microprocessors mitigates supply chain disruptions, contrasting with just-in-time practices for standard plastics. Device manufacturing concentrates in China for electronics assembly, Germany for precision optics, and the USA for AI software integration. The supply chain relies on specialized sensor inputs, creating single-source vulnerability for certain high-performance imaging modules. Distribution runs through direct sales teams to major hospital networks and specialized medical device distributors for decentralized care providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital wound measurement market is entering a cyclical recovery, driven by increasing healthcare expenditure and a renewed focus on chronic disease management post-pandemic. This upswing incentivizes strategic positioning across all stakeholder groups.
For Market Incumbents:Shield existing market share by strengthening relationships with integrated hospital systems and expanding comprehensive service contracts. Large manufacturers should invest heavily in FDA/MDR-compliant AI algorithm development to counter disruption from agile mobile-first platforms. Offering bundled solutions that include device hardware, software, and extensive clinician training can mitigate competitive threats. This approach leverages established sales channels and clinical trust.
For New Entrants and Emerging Players:Unmet demand for seamless integration into existing telehealth platforms represents a significant service-layer gap. New entrants should target Home Care Providers with accessible, photogrammetry-based solutions and intuitive mobile applications. Focusing on value-based care models and demonstrating workflow efficiency can accelerate adoption. A go-to-market strategy emphasizing ease of use and subscription-based pricing will penetrate this underserved segment.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across advanced 3D imaging device development, indicating a need for sustained investment. The market offers strong long-term viability over the next 5-10 years for solutions demonstrating clear patient outcome improvements and cost savings. Investors should target acquisition candidates with proprietary AI algorithms or unique sensor fusion capabilities. A key signal to watch is the expansion of reimbursement codes for remote patient monitoring and automated wound assessment.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrating wound measurement into major telehealth platforms expands reach for decentralized care providers. |
| AI Algorithm Development | Enhancing AI for automated tissue classification improves diagnostic consistency for clinicians. |
| Regulatory Pathway Acceleration | Expediting FDA and PMDA clearances ensures faster market access for innovative devices. |
| Sensor Fusion Research | Combining 3D imaging with hyperspectral data offers more comprehensive wound assessment. |
| Clinician Training Programs | Providing extensive training overcomes adoption barriers for healthcare staff using new digital tools. |
Research Approach
Desk research of FDA 510(k) clearances, MDR technical documentation, and clinical trial registries preceded structured interviews with wound care specialists, hospital procurement managers, and medical device engineers. This approach combined primary insights with extensive secondary validation. Bottom-up data aggregation and top-down market sizing ensured robust triangulation of market estimates. The methodology balanced quantitative data with qualitative expert perspectives.
Variance decomposition analysis identified key growth drivers across product type, application, end user, and deployment mode segments over the projection horizon. The quantitative model integrated historical growth trends with projected adoption rates to derive compound annual growth rates. Forecast inputs included aging population demographics and the prevalence of chronic diseases like diabetes. This framework provided a granular view of market evolution.
Forecasts assume regulatory continuity in U.S. FDA and European MDR regimes; material policy shifts would require re-modeling. Significant changes in healthcare reimbursement policies or new cybersecurity regulations for connected devices represent key risk factors. Revision becomes warranted when these conditions cross defined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Pressure Ulcer Treatment Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Japan Wound Care Management Devices Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
Venous Ulcer Treatment Market
Wound Care
Wound Healing Nutrition Market
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
Single-Use Negative Pressure Wound Therapy Devices Market
Wound Care
Gauze Bandage Rolls Market
Wound Care
Advanced Wound Care Management Market
Wound Care
Post-Operative Wound Treatment Market
Wound Care
Wound Care Market
Wound Care
Burn Care Centers Market
Wound Care
Maggot Debridement Market