
 Surgical Helmet Systems Market | 2026-2036
Surgical Helmet Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Helmet Systems Market Outlook
Hospital procurement consortiums is reshaping how surgical helmet systems reach end users, with group purchasing organizations consolidating vendor selection criteria. Stryker leverages its established orthopedic implant relationships to cross-sell integrated helmet systems into existing surgical workflows. MAXAIR Systems specializes in powered air-purifying respirator technology, sustaining premium positioning through filtration performance differentiation.
Surgical helmet systems are wearable positive-pressure enclosures that integrate HEPA filtration, LED illumination, and visor-based displays to protect operating room personnel from infectious aerosols and bodily fluids while enhancing visual acuity. Full-visor helmets dominate current revenue pools due to their comprehensive facial coverage and compatibility with augmented reality overlays, though disposable helmets are gaining traction in ambulatory settings seeking to eliminate reprocessing costs. Orthopedic surgery generates the largest application volume because prolonged joint replacement procedures maximize the value of integrated lighting and communication features.
FDA 510(k) clearance requirements govern device safety and efficacy claims in the United States, while the EU MDR imposes stricter clinical evidence standards for reusable systems seeking CE marking. The FDA's updated guidance on surgical smoke evacuation is pushing hospitals to evaluate helmet-integrated filtration as an engineering control alternative. Stakeholders must monitor how NMPA regulatory harmonization efforts in China reshape manufacturing location decisions and supply chain qualification protocols.
Market Dynamics
Orthopedic surgery suites are consolidating vendor relationships around integrated helmet-illumination systems, forcing suppliers to bundle filtration hardware with surgical workflow software rather than compete on device specifications alone.
Growth Catalysts
- FDA surgical smoke evacuation guidance:Updated engineering control recommendations position helmet-integrated HEPA filtration as a compliant alternative to ceiling-mounted evacuators in US hospital operating rooms.
- EU MDR clinical evidence requirements:Stricter CE marking standards for reusable systems accelerate replacement cycles as older devices fail to meet post-market surveillance obligations.
- Ambulatory surgery center expansion:Freestanding orthopedic facilities in the United States favor disposable helmet configurations to eliminate reprocessing infrastructure and regulatory compliance overhead.
Market Restraints
- Polypropylene filter supply concentration:HEPA media production clusters in East Asian manufacturing zones expose finished device assemblers to input cost volatility and logistics disruption.
- Reusable system reprocessing complexity:Automated cleaning validation requirements under AAMI ST81 impose capital-intensive washer-disinfector infrastructure on mid-sized hospital systems.
- Ceiling-mounted smoke evacuator substitution:Established suction-based systems in mature US academic medical centers resist displacement by wearable filtration alternatives despite comparable aerosol capture rates.
Strategic Opportunities
- German university hospital digitization mandates:Federal funding for OR 4.0 infrastructure creates procurement windows for helmet systems with native data interoperability and surgical workflow integration.
- Augmented reality visor convergence:Overlay integration between navigation software and helmet-mounted displays enables real-time implant positioning guidance during complex spinal procedures.
- Japanese super-aging society incentives:METI subsidies for infection prevention equipment in rural surgical facilities address personnel shortages through reduced PPE changeout protocols.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-functional expertise combining respiratory protection certification with surgical lighting design concentrates among a narrow pool of specialists in Minneapolis and Stuttgart device clusters.
- Legacy EMR integration complexity:Helmet-generated utilization data lacks standardized HL7 FHIR mapping, forcing custom API development for each hospital network's electronic medical record architecture.
- CE marking timeline compression:EU MDR notified body capacity constraints extend technical documentation review periods, delaying market entry for iterative product improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Helmet Systems Market |
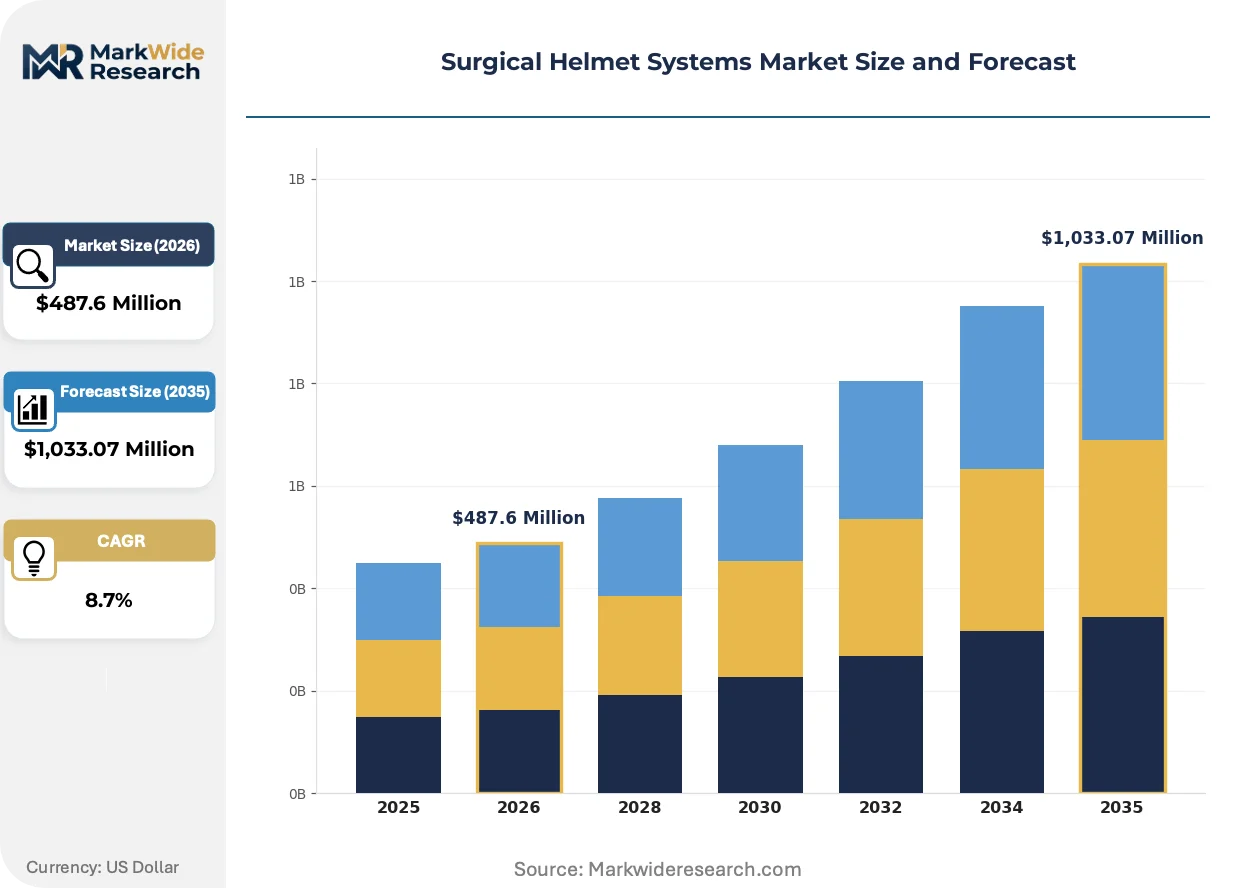
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Visor Helmets, Half-Visor Helmets, Disposable Helmets, Customizable Helmets Application: Neurosurgery, Orthopedic Surgery, Dental Surgery, Cardiothoracic Surgery End User: Hospitals, Surgical Centers, Clinics, Research Institutions Technology: LED Lighting, Augmented Reality, Communication Systems, Filtration Mechanisms |
| Companies Covered | THI Total Healthcare Innovation GmbH, Kaiser Technology Co., Ltd., Stryker, AresAir, Prodancy Pvt. Ltd. (Vizbl brand), Zimmer Biomet, Beijing ZKSK Technology Co., Ltd., Cardinal Health, MAXAIR Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Helmet Systems Market Strategic Shifts
Wearable filtration hardware is converging with surgical visualization platforms, compressing the traditional separation between personal protective equipment and operating room technology infrastructure.
Powered air-purifying respirator technology is hybridizing with augmented reality surgical navigation, enabling orthopedic surgeons to overlay patient-specific implant positioning data directly onto helmet visor displays during total joint replacement procedures. Academic medical centers in the United States and Germany are piloting these integrated systems to reduce cognitive load from separate head-mounted displays. This convergence is compressing the addressable market for standalone surgical navigation hardware by embedding core functionality into mandatory protective equipment.
The EU MDR's post-market clinical follow-up requirements are forcing reusable helmet manufacturers to maintain active surveillance registries tracking device-related adverse events across European hospital networks. Manufacturers must now submit periodic safety update reports to notified bodies, increasing regulatory affairs headcount and documentation burden. Reusable system suppliers with limited European installed bases are exiting the market rather than absorbing compliance costs, concentrating CE-marked offerings among larger portfolio holders.
Hospital procurement consortiums are consolidating vendor evaluation criteria around total cost-of-ownership metrics rather than per-unit acquisition pricing. Group purchasing organizations in the United States now weight reprocessing labor, filter replacement schedules, and training requirements equally with capital expenditure in sourcing decisions. This behavioral shift most visibly affects mid-tier community hospitals lacking dedicated sterile processing departments, which increasingly favor disposable configurations despite higher per-procedure supply costs.
Surgical Helmet Systems Market Segmentation
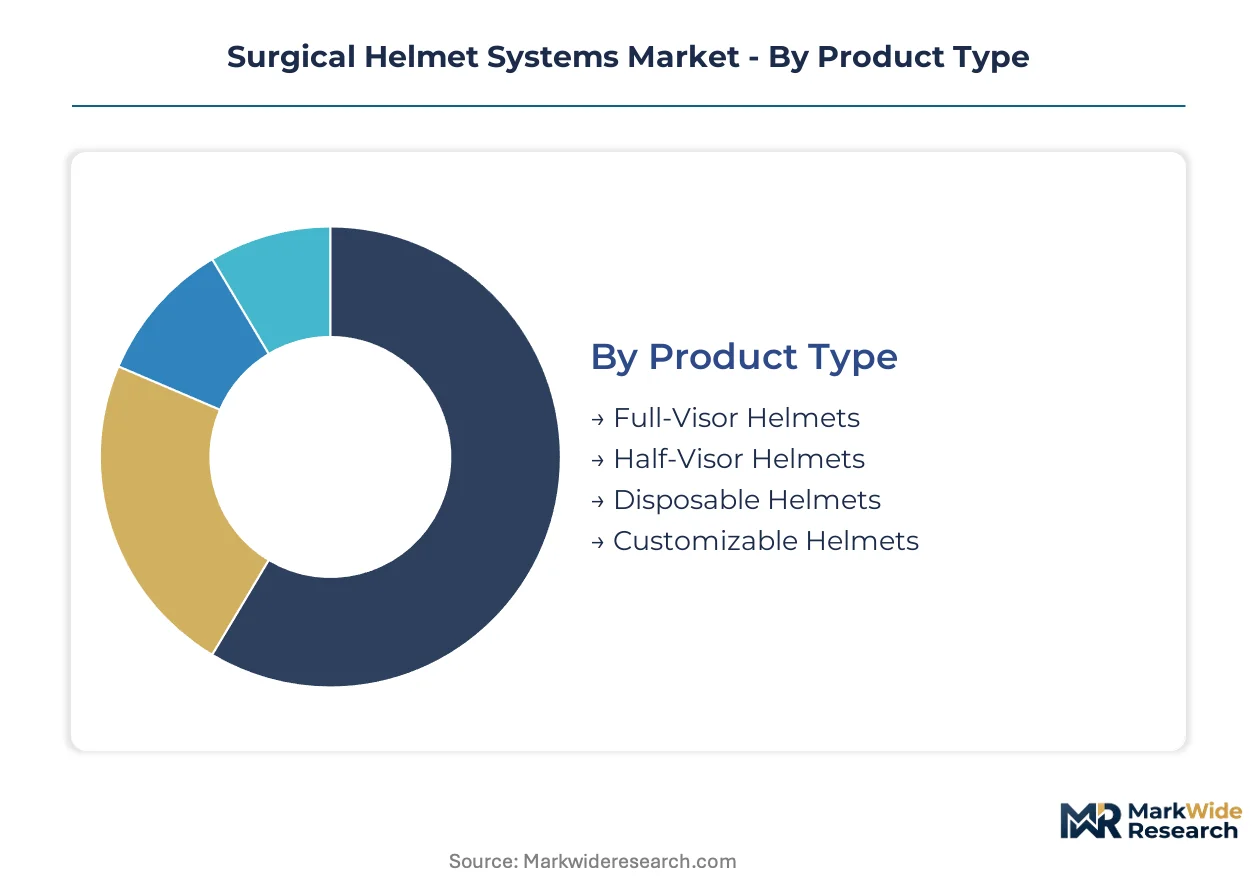
Surgical helmet systems fragment across four distinct dimensions that reshape service intensity and procurement economics. Product architecture determines reprocessing burdens and filter replacement cadences. Application specialization drives feature bundling decisions around visualization and communication protocols.
Product Type:
After-sales service intensity varies dramatically by helmet architecture, with reusable systems demanding multi-year maintenance contracts and disposable configurations eliminating field service entirely.
- Full-Visor Helmets:Comprehensive facial enclosures integrate HEPA filtration, LED illumination, and visor displays into sealed positive-pressure systems. Orthopedic surgery suites in the United States concentrate procurement here, drawn to augmented reality compatibility and extended procedure comfort that justifies premium capital expenditure.
- Disposable Helmets:Single-use polypropylene assemblies eliminate reprocessing infrastructure and AAMI ST81 validation requirements. Ambulatory surgery centers in Germany favor these configurations to sidestep washer-disinfector capital costs and simplify regulatory compliance overhead.
- Half-Visor Helmets:Partial facial coverage designs reduce weight and improve acoustic clarity for team communication. Research institutions pilot these for neurosurgical applications requiring frequent verbal coordination.
- Customizable Helmets:Modular platforms allow field replacement of visor types, filtration grades, and lighting arrays. Mid-sized hospital systems select these to standardize inventory across multiple surgical service lines.
Full-Visor Helmets hold the largest share; momentum sits with Disposable Helmets.
Application:
Procedure duration and aerosol exposure profiles determine which helmet features command priority in purchasing specifications.
- Orthopedic Surgery:Joint replacement procedures lasting three to six hours maximize returns on integrated LED illumination and hands-free communication. German university hospitals bundle these systems with navigation software to satisfy OR 4.0 digitization mandates.
- Neurosurgery:Microscopic precision demands demand exceptional visual acuity and minimal helmet weight. Academic medical centers in Japan evaluate augmented reality overlays for real-time anatomical guidance during complex spinal procedures.
- Cardiothoracic Surgery:High-volume fluid exposure and prolonged sternotomy procedures prioritize splash protection and respiratory isolation. United States cardiac centers emphasize FDA-compliant smoke evacuation integration.
- Dental Surgery:Shorter procedure times and lower aerosol concentrations favor lighter, less complex configurations. Outpatient clinics seek basic filtration without advanced visualization features.
Orthopedic Surgery dominates volume; Neurosurgery shows the steepest expansion trajectory from AR integration pilots.
End User:
Capital availability and sterile processing capacity create sharp segmentation in procurement behavior and contract structure.
- Hospitals:Integrated delivery networks negotiate enterprise-wide agreements spanning multiple surgical specialties. These buyers weight total cost-of-ownership metrics including reprocessing labor and filter replacement schedules against per-unit pricing.
- Surgical Centers:Freestanding facilities prioritize disposable configurations to eliminate capital equipment and compliance documentation. Group purchasing organization consolidation shapes vendor selection criteria for this segment.
- Clinics:Limited procedure volumes and constrained budgets favor basic half-visor systems with minimal feature integration. Rural Japanese facilities leverage METI infection prevention subsidies for equipment acquisition.
- Research Institutions:Academic medical centers pilot emerging technologies including AR navigation and surgical workflow software integration. These sites generate clinical evidence supporting regulatory submissions for reusable system manufacturers.
Hospitals command the greatest revenue concentration; Surgical Centers are climbing the fastest as ambulatory migration accelerates.
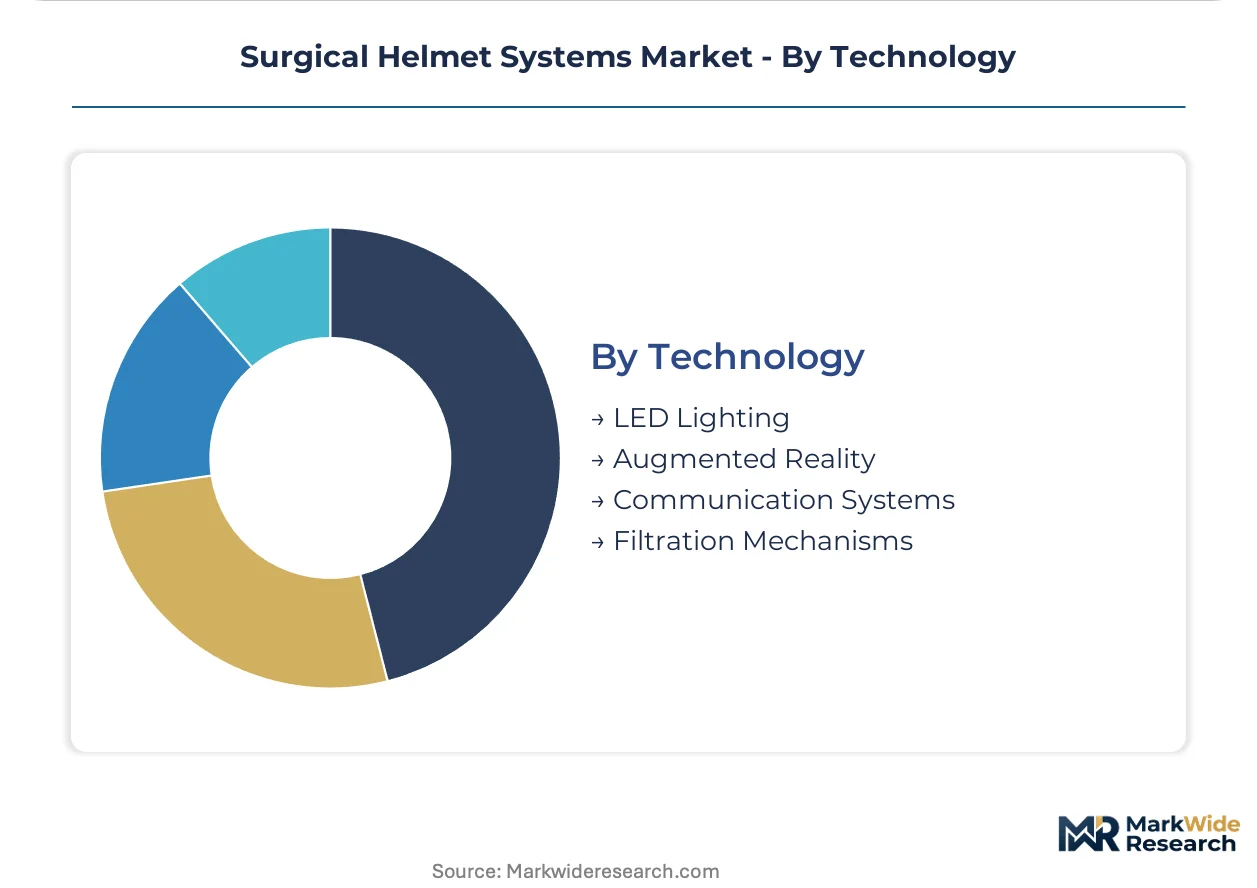
Technology:
Component integration strategies determine competitive differentiation and margin architecture across supplier portfolios.
- Filtration Mechanisms:Powered air-purifying respirator systems with HEPA media represent the core protective function. East Asian supply concentration for polypropylene filter media exposes assemblers to input cost volatility.
- LED Lighting:Surgical illumination integrated into helmet visors eliminates external headlamp interference. Orthopedic surgeons value shadow reduction during deep joint cavity visualization.
- Augmented Reality:Navigation software overlays project patient-specific implant positioning data directly onto visor displays. German and United States academic centers pilot these systems to reduce cognitive load from separate displays.
- Communication Systems:Hands-free audio integration enables sterile field coordination without mask removal. Noise cancellation algorithms address competing surgical equipment acoustic signatures.
Filtration Mechanisms anchor every configuration; Augmented Reality is gaining share fastest from convergence with surgical navigation platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics infrastructure underwrites Europe's distribution reach for surgical helmet systems, while the Trans-Pacific cable networks enable real-time surgical workflow software integration across East Asian manufacturing clusters and North American hospital systems.
United States
FDA surgical smoke evacuation guidance and ambulatory surgery center expansion drive procurement volume. The 510(k) clearance pathway governs reusable system market entry, with updated engineering control recommendations positioning helmet-integrated HEPA filtration as compliant alternatives to ceiling-mounted evacuators. Minneapolis anchors the biomedical engineering talent cluster where respiratory protection certification converges with surgical lighting design.
Germany
OR 4.0 digitization mandates and university hospital infrastructure funding reshape procurement specifications. The EU MDR imposes stricter clinical evidence standards for reusable systems seeking CE marking, accelerating replacement cycles as older devices fail post-market surveillance obligations. Stuttgart's device cluster concentrates cross-functional expertise combining filtration engineering with surgical visualization platforms.
Japan
METI subsidies for infection prevention equipment address personnel shortages through reduced PPE changeout protocols in rural surgical facilities. The PMDA regulatory framework governs market authorization, with super-aging society demographics concentrating demand in orthopedic and spinal procedures. Nagoya's Chubu region hosts pilot programs for augmented reality visor integration during complex surgical navigation.
China
NMPA regulatory harmonization efforts reshape manufacturing location decisions and supply chain qualification protocols for polypropylene filter media. Domestic production capacity expansion targets import substitution in powered air-purifying respirator assemblies. Beijing-Tianjin-Hebei concentrates finished device assembly operations serving hospital procurement networks across northern provinces.
Surgical Helmet Systems Market Competitive Environment
On the supply side, the industry is consolidating around integrated platform providers capable of bundling filtration hardware with surgical workflow software rather than competing on device specifications alone. The vendor base stratifies across three archetypes: diversified orthopedic implant conglomerates leveraging cross-selling relationships, specialized powered air-purifying respirator technology firms sustaining premium positioning through filtration performance, and disposable configuration specialists targeting ambulatory surgery center price sensitivity. Dominant competitive moves include strategic partnerships with group purchasing organizations and technology licensing agreements for augmented reality visor integration.
Among Germany-based innovators, THI Total Healthcare Innovation GmbH exemplifies the European engineering-focused archetype, while Stryker occupies a position within the diversified orthopedic implant tier leveraging established surgical workflow relationships. MAXAIR Systems represents the specialized filtration technology vector, anchoring premium market positioning through powered air-purifying respirator differentiation. Beijing ZKSK Technology Co., Ltd. sits within the Asia-Pacific manufacturing scale tier, reflecting China's concentration in polypropylene filter media and finished device assembly operations.
| Leading Market Players |
|---|
| THI Total Healthcare Innovation GmbH |
| Kaiser Technology Co., Ltd. |
| Stryker |
| AresAir |
| Prodancy Pvt. Ltd. (Vizbl brand) |
| Zimmer Biomet |
| Beijing ZKSK Technology Co., Ltd. |
| Cardinal Health |
| MAXAIR Systems |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in East Asian polypropylene filter media production is pressuring input costs downward while simultaneously concentrating supplier bargaining power among a narrow tier of HEPA media specialists, creating asymmetric pricing leverage that favors large-scale finished device assemblers over mid-tier competitors.
Pricing Analysis
Volume-discount tiering structures separate enterprise hospital networks purchasing multi-year maintenance contracts from ambulatory surgery centers procuring single-use disposable configurations on spot terms. Price differentiation hinges on FDA 510(k) clearance tier and bundled surgical workflow software integration, with premium positioning commanding substantial markups for augmented reality visor compatibility. Pricing pressure stems from group purchasing organization consolidation driving standardized sourcing criteria across integrated delivery networks. Surgical centers exhibit highest price sensitivity due to capital constraints and elimination of reprocessing infrastructure, while academic medical centers prioritize total cost-of-ownership metrics over per-unit acquisition.
Supply Chain Analysis
Extended payment terms from 60 to 90 days have become standard for East Asian filter media suppliers serving finished device assemblers, reflecting working capital pressure downstream through supply-chain finance facilities. Manufacturing concentration centers on China, South Korea, and Japan for polypropylene HEPA media, with Germany and the United States hosting final assembly and sterilization validation. Raw material dependencies include medical-grade polypropylene, lithium-ion battery cells for powered air-purifying respirator systems, and precision-molded polycarbonate visor components. Single-source vulnerability in East Asian filter media production exposes assemblers to logistics disruption from regional port congestion. Distribution runs through hospital procurement consortiums and group purchasing organizations that consolidate vendor evaluation criteria across multi-facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through group purchasing organization consolidation, with hospital procurement consortiums now dictating vendor selection criteria and total cost-of-ownership weightings across integrated delivery networks.
For Market Incumbents: Insulate market position through backward integration into polypropylene filter media production and captive supply of HEPA components, countering East Asian input cost volatility. Secure FDA 510(k) clearance for next-generation augmented reality visor platforms ahead of EU MDR clinical evidence deadlines. Deepen hospital system partnerships by embedding surgical workflow software that locks in multi-year maintenance contracts and raises switching costs for disposable configuration competitors. For New Entrants and Emerging Players: Establish a beachhead in German ambulatory surgery centers seeking disposable helmet configurations to sidestep washer-disinfector capital requirements and AAMI ST81 compliance overhead. Target rural Japanese surgical facilities leveraging METI infection prevention subsidies for equipment acquisition, where personnel shortages create urgent demand for reduced PPE changeout protocols. Pursue private-label manufacturing partnerships with established group purchasing organizations rather than direct hospital sales campaigns. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because stricter FDA surgical smoke evacuation guidance and EU MDR post-market surveillance obligations are forcing smaller reusable system manufacturers to exit, concentrating CE-marked offerings among larger portfolio holders. Acquisition targets should combine powered air-purifying respirator filtration expertise with nascent augmented reality software integration capabilities. Monitor FDA guidance document revisions on engineering control alternatives as the critical inflection signal for helmet-integrated filtration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Establishes US market entry legitimacy for reusable systems with HEPA filtration claims. |
| CE Marking Pathway | EU MDR clinical evidence requirements accelerate replacement cycles for legacy devices. |
| Hospital System Partnership | Group purchasing organization consolidation rewards integrated workflow software bundling. |
| Software Companion Development | Augmented reality visor integration reduces cognitive load from separate surgical navigation displays. |
| Reimbursement Strategy | METI infection prevention subsidies in Japan create procurement windows for rural facilities. |
Study Parameters
Initial hypotheses were tested against primary input from hospital purchasing committee directors, biomedical engineering specialists, group purchasing organization contract managers, and sterile processing department supervisors, then refined through secondary validation against FDA 510(k) clearance databases, EU MDR notified body technical documentation, hospital procurement consortium contract awards, and CMS Medicare reimbursement schedules. Bottom-up triangulation across surgeon utilization surveys and top-down reconciliation against GPO aggregate spending data anchored volume estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon, modeling surgical helmet system penetration by product architecture, application specialty, end-user capital availability, and technology integration intensity. Segmentation dimensions included full-visor versus disposable configurations, orthopedic versus neurosurgical application mix, hospital versus ambulatory center procurement behavior, and filtration mechanism versus augmented reality feature bundling. CAGRs derived from procedure volume elasticity to OR 4.0 digitization mandates and regulatory compliance cost pass-through assumptions.
Sensitivities concentrate around FDA guidance revision timing on surgical smoke evacuation engineering controls, EU MDR notified body capacity constraints extending CE marking timelines, and polypropylene filter media supply disruption from East Asian logistics chokepoints. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Urinary Collection Device Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
US Clear Aligners Market
Medical Devices
AI-enabled Medical Devices Market
Medical Devices
Global Coronary Artery Bypass Graft Devices Market
Medical Devices
Disposable Thermometer Market
Medical Devices
Glass Syringe Market
Medical Devices
Infertility Devices Market
Medical Devices
Global Nebulizers Market
Medical Devices
Automated Compounding Systems Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
Global Medical Loupes Market
Medical Devices
Wearable Pulse Oximeters Market
Medical Devices
Nerve Monitoring Devices Market