
 Japan Wound Care Management Devices Market | 2026-2036
Japan Wound Care Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Wound Care Management Devices Market Foresight
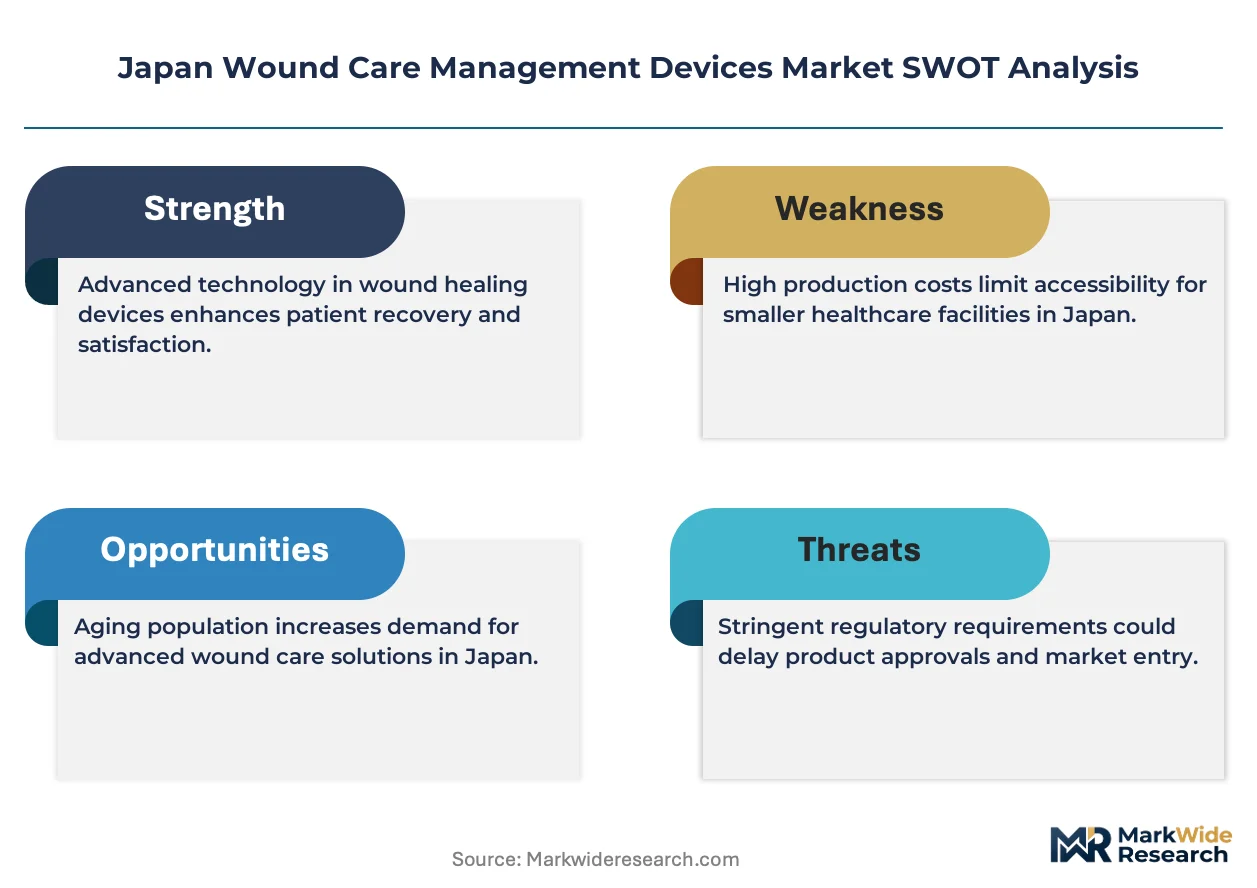
Japanese medical device manufacturing capacity is shifting toward value-added wound care platforms as domestic producers respond to aging-population surgical demand. Smith & Nephew leverages its advanced foam and hydrocolloid portfolio to sustain leadership in chronic wound applications. Medtronic anchors the surgical wound segment through its suture and stapling systems, while Molnlycke Health Care differentiates via premium antimicrobial dressings targeting hospital-acquired infection prevention.
Wound care management devices encompass dressings, closure instruments, skin substitutes, and adjunctive therapies engineered to maintain moist healing environments, manage exudate, and prevent bacterial colonization across acute and chronic lesions. These products typically incorporate absorbent polymers, occlusive films, or biological matrices designed to accelerate re-epithelialization and reduce dressing change frequency in clinical and home settings. Dressings command the largest revenue pool given their recurring consumption model, while antimicrobial technologies capture expanding margin as PMDA strengthens hospital infection control guidelines. Home care represents the fastest-growing end user channel as Japan's Ministry of Health promotes post-acute discharge and community-based wound management to reduce bed occupancy.
PMDA's medical device quality management standards and Japan's Pharmaceutical Affairs Law govern product registration, clinical evidence requirements, and post-market surveillance for wound care devices sold domestically. METI's reimbursement pricing mechanisms directly shape hospital purchasing patterns and manufacturer R&D prioritization toward cost-effective, clinically differentiated offerings. Stakeholders must monitor evolving antimicrobial resistance surveillance data and PMDA's accelerated review pathways to align portfolio development with both clinical need and regulatory incentive structures.
Market Dynamics
METI's reimbursement reforms are compressing hospital procurement cycles toward clinically differentiated antimicrobial platforms, forcing domestic manufacturers to accelerate value-added wound care development ahead of foreign competitors.
Growth Catalysts
- Aging Surgical Demand:Japan's demographic shift toward patients over 65 expands chronic wound prevalence and post-operative care requirements across Tokyo metropolitan hospital networks.
- Antimicrobial Reimbursement Incentives:METI's pricing mechanisms reward higher-grade infection prevention technologies, directing R&D investment toward advanced silver-ion and PHMB-integrated dressing platforms.
- Home Care Policy Mandate:The Ministry of Health's discharge acceleration protocols redirect wound management from inpatient beds to community-based settings, multiplying recurring dressing consumption.
Market Restraints
- Domestic Manufacturing Concentration:Production of advanced hydrofiber and foam substrates clusters among three Osaka-based material suppliers, creating input vulnerability.
- PMDA Clinical Evidence Requirements:Novel biological skin substitutes face 18-24 month review timelines for chronic wound efficacy claims, delaying commercialization.
- Generic Standard Dressing Substitution:Low-margin gauze and basic hydrocolloid products retain volume share in price-sensitive municipal hospitals outside major metros.
Strategic Opportunities
- Hokkaido and Tohoku Regional Expansion:Underpenetrated rural prefectures lack specialized wound care centers, creating whitespace for mobile clinic partnerships and telemedicine-integrated dressing delivery.
- Silver-Nanoparticle Biosensor Convergence:Integration of real-time infection monitoring with antimicrobial dressings enables premium positioning in burn centers and diabetic foot clinics.
- Pharmacy Channel Deregulation:Relaxed PMDA point-of-sale restrictions allow certified pharmacists to dispense advanced wound care products directly to home care patients.
Industry Challenges
- Specialized Wound Care Nurse Scarcity:Certification programs for negative pressure wound therapy and bioengineered tissue application lag demand across regional hospitals.
- Legacy EHR Integration Friction:Hospital procurement systems require custom API development to track dressing utilization against patient outcomes for reimbursement documentation.
- Antimicrobial Resistance Surveillance Compliance:PMDA mandates real-world evidence collection on bacterial colonization patterns, forcing manufacturers to fund multi-site post-market studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Wound Care Management Devices Market |
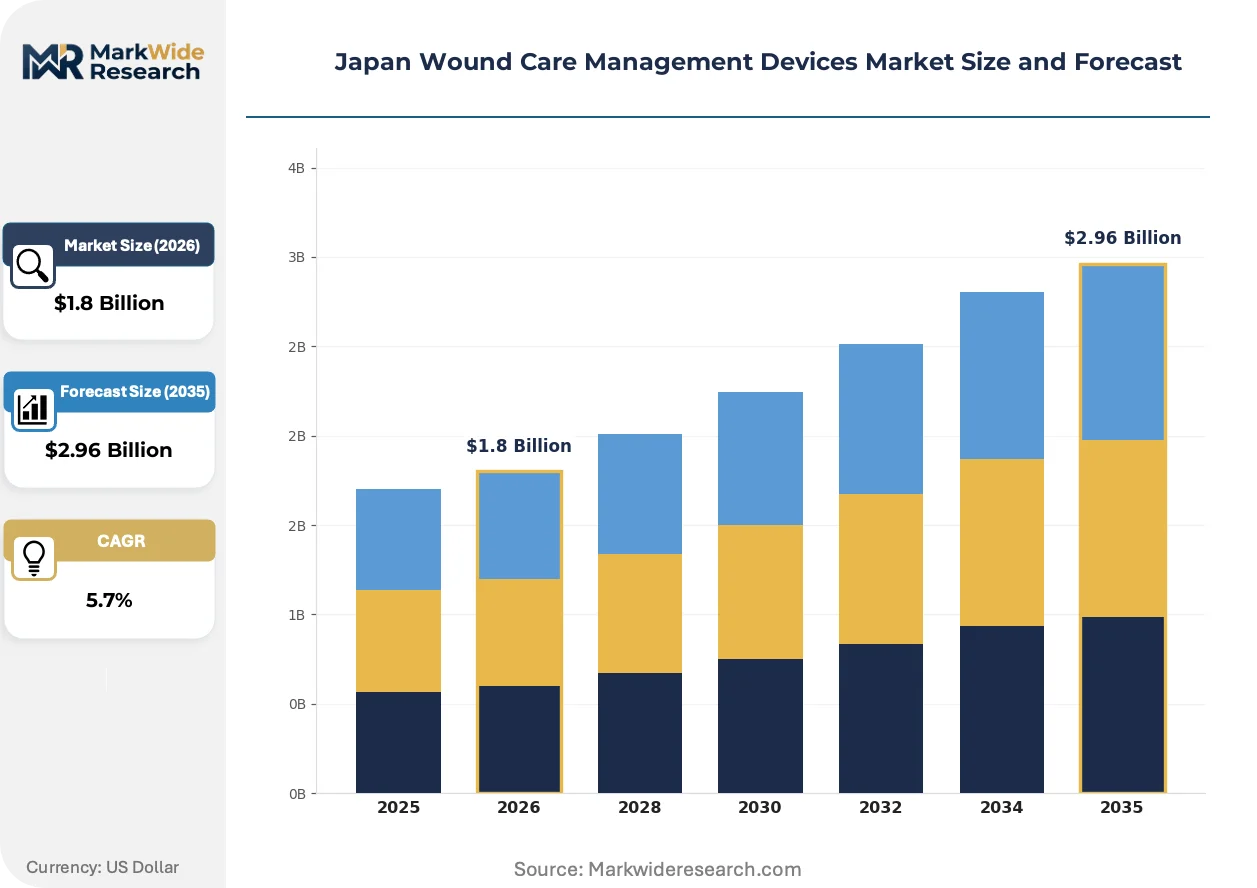
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Clamps, Adhesives, Skin Grafts End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Technology: Hydrocolloid, Foam, Alginate, Antimicrobial Application: Chronic Wounds, Surgical Wounds, Burns, Traumatic Injuries |
| Companies Covered | Smith & Nephew, Medtronic, B. Braun SE, 3M, Coloplast Group, ConvaTec Group, Molnlycke Health Care, Cardinal Health, Integra LifeSciences, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Wound Care Management Devices Market Shifts & Advancements
Japanese wound care is pivoting from passive moisture management to active therapeutic intervention, with sensor-embedded dressings and automated debridement systems compressing healing timelines.
Negative pressure wound therapy systems are automating exudate removal and granulation tissue monitoring in Tokyo's tertiary burn centers, reducing nursing labor intensity by half. Osaka's specialized diabetic foot clinics deploy these platforms for outpatient limb salvage protocols. The technology is automating previously manual dressing change workflows, enabling same-day discharge for complex surgical wounds.
PMDA's 2023 antimicrobial stewardship guidelines now mandate documented infection risk stratification before reimbursement approval for premium dressings. Hospitals must submit bacterial culture data to justify silver-impregnated or PHMB-based product selection. Burn centers and orthopedic wards have responded by integrating microbiology laboratories directly into wound care pathways.
Hospital purchasing cooperatives in Kansai and Kanto regions now bundle dressing procurement with outcomes-based service contracts, displacing traditional product-centric tenders. Suppliers assume inventory risk and provide on-site clinical training in exchange for multi-year exclusivity. This restructuring concentrates supplier relationships around three metropolitan purchasing alliances.
Japan Wound Care Management Devices Market Segmentation
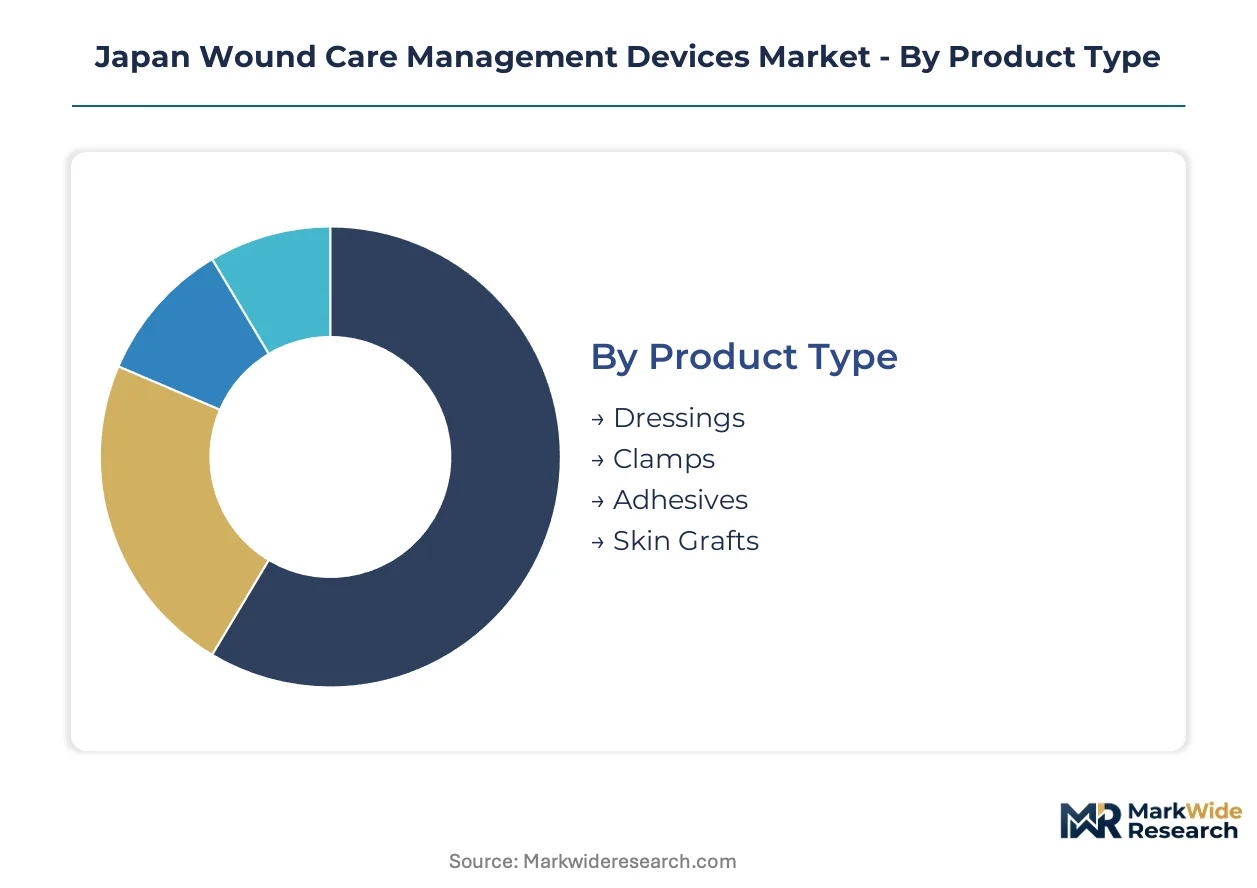
Segmentation in Japan's wound care market reveals how reimbursement incentives and clinical workflows reshape procurement priorities across product categories. Each dimension exposes different pressure points: METI's pricing tiers favor antimicrobial technologies, while the Ministry of Health's discharge protocols elevate home care channels.
Product Type:
Dressings dominate procurement volumes through recurring consumption, while skin grafts command premium positioning amid chronic wound complexity.
- Dressings:Absorbent polymers, occlusive films, and composite layers manage exudate across acute and chronic lesions. Tokyo metropolitan hospital networks concentrate demand for advanced foam and hydrocolloid variants as surgical volumes rise among patients over 65.
- Skin Grafts:Biological matrices and engineered tissue substitutes accelerate re-epithelialization in diabetic foot and burn applications. Osaka's specialized burn centers drive adoption amid PMDA's 18-24 month review timelines for novel efficacy claims.
- Clamps:Mechanical wound closure devices anchor surgical procedures in orthopedic and cardiovascular wards.
- Adhesives:Tissue bonding agents reduce suture requirements in minimally invasive procedures across Kansai region ambulatory centers.
Today's leader: Dressings. Tomorrow's challenger: Skin Grafts.
End User:
Hospital procurement concentrates in metropolitan purchasing alliances, while policy mandates redirect volume toward community-based settings.
- Hospitals:Tertiary centers in Tokyo and Osaka integrate microbiology laboratories into wound care pathways to satisfy PMDA's infection risk stratification requirements. Kansai and Kanto purchasing cooperatives now bundle procurement with outcomes-based service contracts.
- Home Care:Post-acute discharge protocols multiply recurring dressing consumption as certified pharmacists gain dispensing authority under relaxed PMDA point-of-sale restrictions.
- Clinics:Outpatient limb salvage protocols in diabetic foot centers deploy negative pressure systems for same-day discharge.
- Long-term Care Facilities:Municipal nursing homes outside major metros retain price-sensitive procurement of basic hydrocolloid and gauze products.
Hospital networks currently anchor revenue. Home care channels are climbing the fastest.
Technology:
Material science differentiation separates premium reimbursement tiers from commoditized standard care.
- Antimicrobial:Silver-ion and PHMB-integrated platforms capture expanding margin as PMDA strengthens hospital infection control guidelines. METI's pricing mechanisms explicitly reward documented bacterial colonization prevention.
- Foam:Superabsorbent polyurethane structures automate exudate management in Tokyo's tertiary burn centers, reducing nursing labor intensity.
- Hydrocolloid:Gel-forming carboxymethylcellulose layers maintain moist healing environments in pressure ulcer management.
- Alginate:Calcium-sodium fiber dressings derived from seaweed address highly exuding wounds in coastal prefecture supply chains.
Antimicrobial platforms command premium positioning. Foam substrates scale through automation integration.
Application:
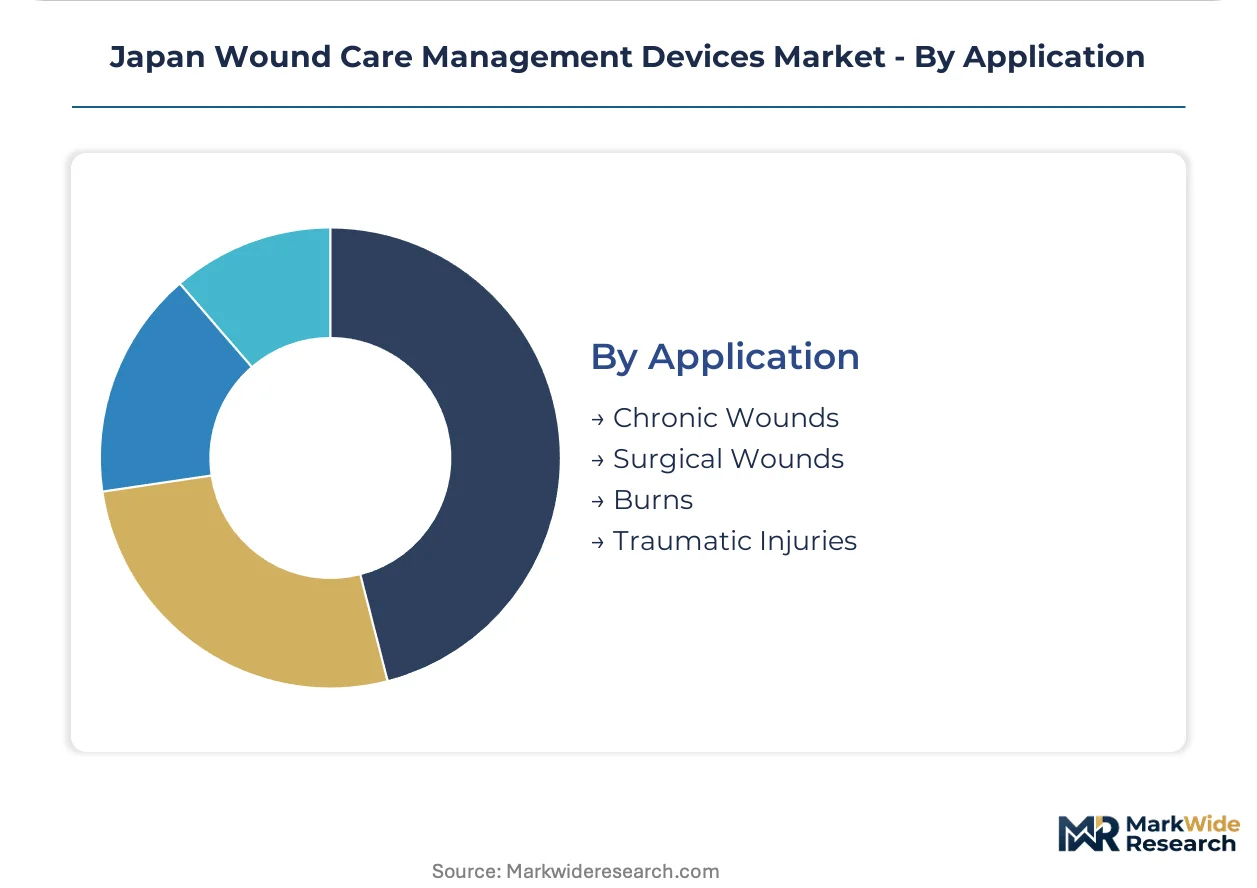
Demographic-driven surgical demand elevates chronic wound prevalence, while acute trauma maintains steady volume through Japan's aging infrastructure workforce.
- Chronic Wounds:Diabetic foot ulcers and pressure injuries sustain recurring dressing consumption as Japan's over-65 population expands. Hokkaido and Tohoku regional hospitals face specialized nurse scarcity for negative pressure therapy application.
- Surgical Wounds:Post-operative care requirements concentrate in Tokyo metropolitan networks where METI's reimbursement reforms compress procurement cycles toward clinically differentiated platforms.
- Burns:Thermal and chemical injuries drive demand for biosensor-integrated antimicrobial dressings in Osaka's specialized centers.
- Traumatic Injuries:Acute wound management maintains volume through industrial accidents and traffic incidents across manufacturing prefectures.
Chronic wounds anchor recurring revenue. Surgical wounds are gaining share fastest through procedure volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's wound care device procurement runs through centralized hospital purchasing alliances, while Japan's METI reimbursement reforms fragment procurement toward clinically differentiated platforms. Both systems concentrate demand in metropolitan hospital networks, yet regulatory incentives diverge sharply.
United States
FDA's 510(k) clearance pathways accelerate antimicrobial dressing commercialization ahead of PMDA timelines. Hospital-acquired infection penalties under CMS value-based purchasing redirect procurement toward silver-ion and PHMB-integrated platforms. Cleveland Clinic and Mayo Clinic anchor demand in the Midwest's tertiary burn center network.
Germany
EMA's Medical Device Regulation harmonization with BfArM standards compresses review timelines for biological skin substitutes. Diabetiker Fußzentren in Bavaria and North Rhine-Westphalia drive adoption of negative pressure systems for outpatient limb salvage. B. Braun SE anchors domestic manufacturing in Melsungen's medical device cluster.
China
NMPA's 2023 priority review pathways for antimicrobial wound care accelerate domestic manufacturer market entry. Provincial centralized procurement in Guangdong and Jiangsu compresses pricing for standard dressings while exempting premium biosensor-integrated platforms. Shanghai's Ruijin Hospital anchors demand in the Yangtze River Delta surgical corridor.
United Kingdom
NHS England's 2024 wound care framework mandates outcomes-based contracting for diabetic foot ulcer management. NICE technology appraisals stratify reimbursement between standard hydrocolloids and advanced antimicrobial matrices. Manchester's specialist wound care centers pilot automated debridement systems for pressure injury protocols.
Japan Wound Care Management Devices Market Competitive Landscape
European producers anchor the premium antimicrobial tier; Japanese specialists hold regional procurement relationships through METI-aligned distribution. The vendor base splits between consolidated multinational portfolios and domestic mid-cap fabricators with captive substrate supply. Three archetypes dominate: integrated material-science conglomerates, surgical closure specialists, and regional dressing manufacturers with backward integration into polymer substrates. Competitive moves concentrate on outcomes-based hospital contracting and antimicrobial technology licensing.
Among UK-based multinationals, Smith & Nephew and ConvaTec Group exemplify the integrated material-science archetype with broad dressing portfolios spanning foam to biological matrices. Medtronic, an Ireland-domiciled surgical devices conglomerate, anchors the wound closure segment through suture and stapling systems. These three occupy positions where scale-driven R&D investment intersects with regulatory compliance infrastructure across multiple jurisdictions.
| Leading Market Players |
|---|
| Smith & Nephew |
| Medtronic |
| B. Braun SE |
| 3M |
| Coloplast Group |
| ConvaTec Group |
| Molnlycke Health Care |
| Cardinal Health |
| Integra LifeSciences |
| Others |
Supply & Pricing Matrix
Metropolitan hospital purchasing alliances in Kanto and Kansai concentrate procurement volumes and compress supplier margins through outcomes-based contracting, forcing manufacturers to absorb inventory risk in exchange for multi-year exclusivity arrangements.
Pricing Analysis
Capacity additions in antimicrobial substrate manufacturing are reshaping price floors for silver-ion and PHMB-integrated dressings. Three-tier pricing structure across premium, standard, and economy levels separates METI-reimbursed antimicrobial platforms from basic hydrocolloids and commodity gauze. Price differentiation hinges on PMDA infection risk stratification documentation and clinical training bundling. Municipal hospitals outside Tokyo and Osaka exhibit highest price sensitivity, while specialized burn centers accept premium positioning for biosensor-integrated platforms.
Supply Chain Analysis
Direct-to-hospital channels handle metropolitan purchasing alliance demand, while pharmacy intermediaries serve expanding home care dispensing. Raw material supply concentrates in Japan, Germany, and the United States for advanced polyurethane foams, biological matrices, and antimicrobial agents. Production draws from three Osaka-based hydrofiber and foam substrate suppliers, creating single-source vulnerability for domestic manufacturers. Distribution runs through METI-aligned medical device wholesalers with cold-chain capabilities for biological skin substitutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's wound care market functions as a geographic-arbitrage play where PMDA's 18-24 month review timelines for novel biological substitutes deter foreign entrants, creating protected runway for domestic manufacturers with established regulatory relationships.
For Market Incumbents: Anchor antimicrobial technology leadership through backward integration into silver-nanoparticle substrate production, mitigating input vulnerability from Osaka supplier concentration. Lock in multi-year outcomes-based contracts with Kansai and Kanto purchasing cooperatives before pharmacy channel deregulation fragments hospital procurement. Invest in certified wound care nurse training programs to address specialized therapy application scarcity across regional hospitals.
For New Entrants and Emerging Players: Begin with Hokkaido and Tohoku mobile clinic partnerships where telemedicine-integrated dressing delivery remains underpenetrated and specialized wound care nurse certification programs lag demand. Target municipal nursing homes outside major metros with price-competitive hydrocolloid variants as an entry wedge. Pursue PMDA accelerated review pathway qualification for antimicrobial platforms with documented bacterial colonization prevention data.
For Investors and Strategic Acquirers: Domestic mid-cap dressing manufacturers with captive polymer substrate supply are the most active acquirer targets in this space, as material-science conglomerates seek METI-aligned distribution infrastructure. Long-term viability rests on portfolio exposure to home care channel growth and antimicrobial reimbursement tier expansion. Watch PMDA real-world evidence mandates on bacterial resistance patterns as the signal for regulatory compliance cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Outcomes-based contracting with Kansai purchasing alliances locks in multi-year exclusivity and inventory risk transfer. |
| Reimbursement Strategy | METI antimicrobial pricing tier qualification captures premium positioning for silver-ion and PHMB-integrated platforms. |
| Backward Integration | In-house production of hydrofiber substrates reduces dependency on three concentrated Osaka suppliers. |
| Software Companion Development | Biosensor-embedded dressings with real-time infection monitoring justify premium burn center positioning. |
| CE Marking Pathway | Parallel EMA MDR harmonization enables European market expansion for biological skin substitutes. |
Research Methodology
Multiple input streams — hospital procurement database analysis, GPO contract documentation, and CMS Medicare utilization data — were reconciled with primary interviews across hospital purchasing committees, biomedical engineers, wound care clinicians, and METI regulatory affairs specialists. Secondary validation incorporated PMDA device registration filings, METI reimbursement pricing circulars, and pharmaceutical affairs law amendments. Bottom-up demand modeling triangulated against top-down market sizing from trade flow analysis.
Data-stream reconciliation across product type, technology tier, end-user channel, and application severity dimensions enabled segmentation-level forecasting throughout the projection horizon. CAGRs derived from surgical volume demographics, discharge protocol policy trajectories, and antimicrobial dressing adoption curves. Modeled inputs included aging-population procedure expansion rates and home care pharmacist dispensing authority relaxation timelines.
Several conditions sit outside the modeled scope, including unforeseen PMDA regulatory timeline accelerations, abrupt METI reimbursement tier reclassifications, and antimicrobial resistance surveillance data discontinuities. Forecasts reflect stated assumptions on policy continuity and supply chain stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Venous Skin Ulcer Treatment Market
Wound Care
Wound Skin Care Market
Wound Care
Wound Retractor Market
Wound Care
Hydrocolloid Dressing Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Italy Wound Care Market
Wound Care
Advanced Wound Management Market
Wound Care
Surgical Dressing Market
Wound Care
Biopatches Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Liquid Bandages Market
Wound Care
Bioadhesive Wound Care Market
Wound Care
Enzymatic Wound Debridement Market
Wound Care
Wound Closure Devices Market
Wound Care
Topical Wound Agents Market
Wound Care
Wound Debridement (Wound Cleaning) Market