
 Addison Disease Testing Market | 2026-2036
Addison Disease Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Addison Disease Testing Market Outlook
EU MDR recertification timelines are expanding compliance burdens for in vitro diagnostic manufacturers serving European endocrinology clinics. F. Hoffmann-La Roche Ltd leverages its automated immunoassay platforms to sustain high-throughput cortisol testing workflows in centralized labs. Siemens Healthineers anchors its position through integrated analyzer systems that dominate hospital laboratory procurement channels. Abbott Laboratories competes on point-of-care accessibility, extending its reach into urgent care settings where rapid adrenal insufficiency screening carries clinical priority.
Addison disease testing encompasses biochemical and immunological assays that measure adrenal hormone levels, autoantibody presence, and corticotropin reserve to confirm primary or secondary adrenal insufficiency. The ACTH stimulation test remains the functional gold standard, requiring intravenous synthetic corticotropin administration with timed cortisol measurements to assess adrenal reserve capacity. Among technology platforms, LC-MS/MS is gaining fastest in reference laboratories due to superior specificity for low-concentration cortisol and metabolite quantification, while ELISA sustains the largest installed base in mid-volume hospital labs where cost-per-test economics dominate procurement decisions. Diagnostic laboratories capture the deepest margin pools through bundled endocrinology panel pricing, though homecare settings are emerging as a growth corridor through saliva-based cortisol collection kits.
FDA oversight of laboratory-developed tests shapes validation requirements for ACTH stimulation protocols in US-based reference labs, while EU MDR and IVDR frameworks impose conformity assessment burdens on manufacturers seeking CE marking for automated adrenal function analyzers. WHO endocrine disorder classification updates influence reimbursement coding and clinical guideline harmonization across national health systems. Stakeholders must monitor evolving payer coverage for multiplex autoimmune panels that incorporate 21-hydroxylase antibody testing alongside broader adrenal insufficiency biomarkers.
Market Dynamics
The Addison disease testing landscape is being restructured by the FDA's evolving oversight of laboratory-developed tests, which is forcing reference laboratories to revalidate ACTH stimulation protocols and recalibrate quality management systems.
Growth Catalysts
- Autoimmune screening protocol expansion:Hospital-based diagnostic laboratories are broadening endocrinology panel offerings to capture incidental adrenal insufficiency cases during routine diabetes and thyroid workups.
- EU IVDR framework maturation:The transition from IVDD to IVDR is accelerating CE marking renewals for automated cortisol analyzers, creating replacement demand for compliant instrumentation.
- Saliva-based cortisol collection:Homecare settings are adopting non-invasive sampling methods that bypass phlebotomy bottlenecks and expand testing access beyond hospital walls.
Market Restraints
- LC-MS/MS capital intensity:Reference laboratories face six-figure instrument investments plus specialized technician training to achieve superior cortisol specificity.
- Reagent supply concentration:Synthetic ACTH (cosyntropin) manufacturing concentrates among limited pharmaceutical suppliers, exposing testing workflows to shortage risk.
- 21-hydroxylase antibody assay complexity:Multiplex autoimmune panel validation requires extensive cross-reactivity testing that extends development timelines.
Strategic Opportunities
- Point-of-care adrenal screening:Urgent care clinics represent underpenetrated demand for rapid cortisol testing that bypasses centralized lab turnaround delays.
- WHO endocrine classification harmonization:Updated disorder taxonomies are streamlining reimbursement coding alignment across national health systems.
- Integrated analyzer-software convergence:Middleware platforms that unify immunoassay hardware with laboratory information systems are capturing premium positioning.
Industry Challenges
- Endocrinology subspecialist scarcity:Testing interpretation depends on trained clinicians who can distinguish primary from secondary adrenal insufficiency patterns.
- Legacy ELISA infrastructure lock-in:Mid-volume hospital laboratories face sunk-cost barriers when evaluating LC-MS/MS migration despite superior analytical performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Addison Disease Testing Market |
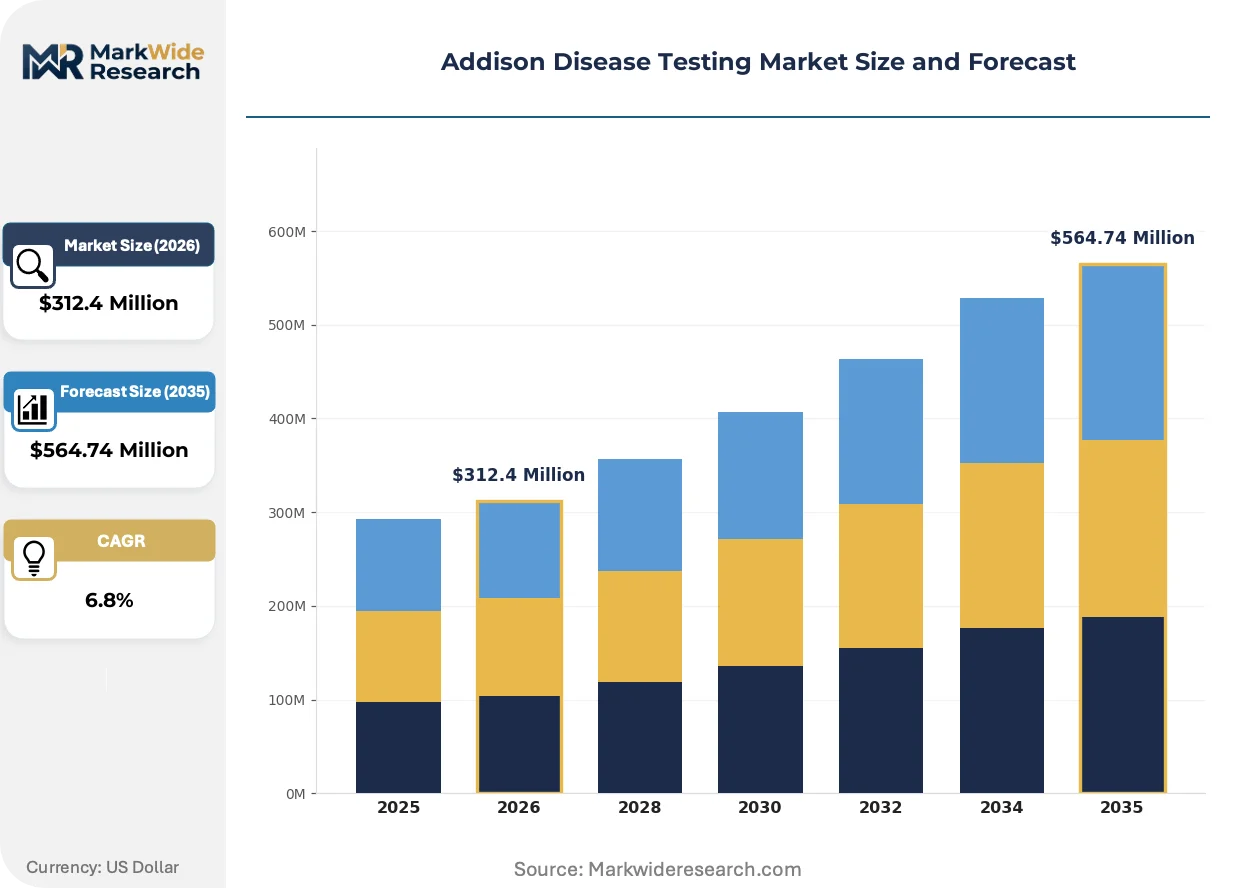
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: ACTH Stimulation Test, Cortisol Test, Insulin Tolerance Test, Plasma Renin Activity Technology: ELISA, Radioimmunoassay, LC-MS/MS, Immunofluorescence End User: Hospitals, Diagnostic Laboratories, Research Institutions, Homecare Settings Distribution Channel: Online Retail, Direct Sales, Third-party Distributors, Others |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott Laboratories, Siemens Healthineers, Thermo Fisher Scientific, Danaher Corporation, Quest Diagnostics, Laboratory Corporation of America Holdings, Bio-Rad Laboratories, DiaSorin S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Addison Disease Testing Market Strategic Shifts
Automation and regulatory harmonization are converging to reshape how adrenal function assays are developed, validated, and deployed across clinical settings.
LC-MS/MS technology is unifying cortisol and metabolite quantification workflows that previously required separate immunoassay runs. Reference laboratories in Germany and Switzerland are consolidating steroid hormone panels onto single platforms to reduce sample volume requirements and improve turnaround consistency. This unification is compressing the competitive gap between academic medical centers and high-throughput commercial laboratories.
EU MDR recertification timelines are extending conformity assessment periods for adrenal function analyzers previously cleared under IVDD. Manufacturers serving European endocrinology clinics must now submit expanded clinical evidence packages and engage with notified bodies facing capacity constraints. Smaller IVD developers are responding by partnering with established quality management consultants to navigate technical documentation requirements.
Hospital procurement committees are bundling endocrinology testing contracts with broader metabolic panel agreements to leverage volume discounts. This consolidation is displacing standalone adrenal function assay vendors from preferred supplier lists in favor of integrated diagnostic platform providers. The United States exhibits the most pronounced concentration, where health system consolidation has reduced the number of independent contracting entities by half over the past decade.
Addison Disease Testing Market Segmentation
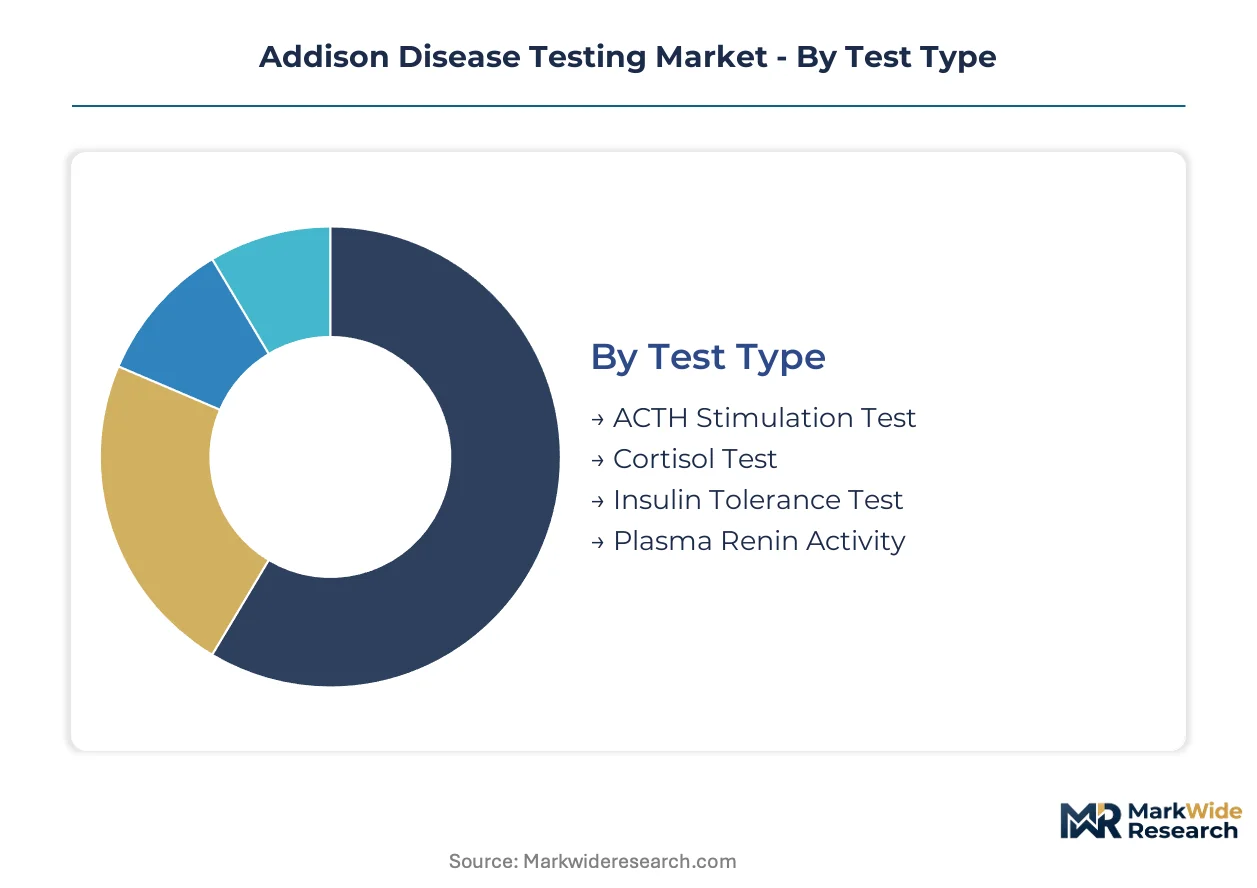
Test modality selection in Addison disease diagnostics hinges on analytical specificity requirements, throughput economics, and the clinical urgency of adrenal insufficiency confirmation. Procurement patterns diverge sharply between centralized reference laboratories optimizing for multiplex efficiency and point-of-care settings prioritizing rapid turnaround.
Test Type:
Supply concentration in synthetic ACTH manufacturing shapes availability and pricing dynamics across functional adrenal assessment protocols.
- ACTH Stimulation Test:Intravenous cosyntropin administration with timed serum cortisol measurements remains the functional gold standard for adrenal reserve assessment. Hospital-based diagnostic laboratories in the United States maintain the deepest installed base of stimulation protocols, though cosyntropin supply vulnerability from concentrated pharmaceutical manufacturers constrains test volume expansion.
- Cortisol Test:Serum and saliva-based cortisol quantification captures the broadest indication range from initial screening to therapeutic monitoring. German and Swiss reference laboratories are consolidating steroid hormone panels onto unified LC-MS/MS platforms to reduce sample volume requirements and improve analytical consistency.
- Insulin Tolerance Test:Hypoglycemia-induced stress response assessment reserved for secondary adrenal insufficiency differentiation in specialized endocrinology units.
- Plasma Renin Activity:Aldosterone-angiotensin axis evaluation supporting primary versus secondary classification in academic medical center workflows.
ACTH Stimulation Test absorbs the bulk of installed capacity; Cortisol Test is expanding most quickly through saliva-based home collection adoption.
Technology:
Capital intensity gradients separate high-throughput automated platforms from lower-volume manual methodologies in hospital laboratory procurement decisions.
- ELISA:Enzyme-linked immunosorbent assay platforms sustain the largest installed base in mid-volume hospital laboratories where cost-per-test economics dominate capital allocation. Mid-tier US health systems face sunk-cost barriers when evaluating LC-MS/MS migration despite superior analytical performance specifications.
- LC-MS/MS:Liquid chromatography-tandem mass spectrometry delivers superior specificity for low-concentration cortisol and metabolite quantification. Reference laboratories in Germany and Switzerland are consolidating steroid panels onto single platforms to compress turnaround consistency gaps with academic medical centers.
- Radioimmunoassay:Legacy isotopic detection methods retaining niche application in research protocols and resource-constrained settings.
- Immunofluorescence:Autoantibody visualization supporting 21-hydroxylase antibody detection in autoimmune adrenalitis confirmation.
ELISA retains the deepest penetration; LC-MS/MS is climbing the fastest as reference laboratories prioritize metabolite unification.
End User:
Site-of-care differentiation determines sample handling protocols, reimbursement coding complexity, and the feasibility of rapid therapeutic intervention.
- Hospitals:Inpatient and emergency department settings require STAT cortisol turnaround for acute adrenal crisis management. US health system consolidation has reduced independent contracting entities by half over the past decade, favoring integrated diagnostic platform vendors in procurement decisions.
- Diagnostic Laboratories:Centralized reference and hospital-based labs capture margin pools through bundled endocrinology panel pricing. EU MDR recertification timelines are extending conformity assessment periods for automated analyzers previously cleared under IVDD.
- Research Institutions:Academic medical centers driving protocol innovation for novel biomarker validation and rare adrenal disorder characterization.
- Homecare Settings:Saliva-based cortisol collection kits expanding access beyond phlebotomy-dependent workflows.
Diagnostic Laboratories command the highest test volumes; Homecare Settings are gaining share fastest through non-invasive sampling adoption.
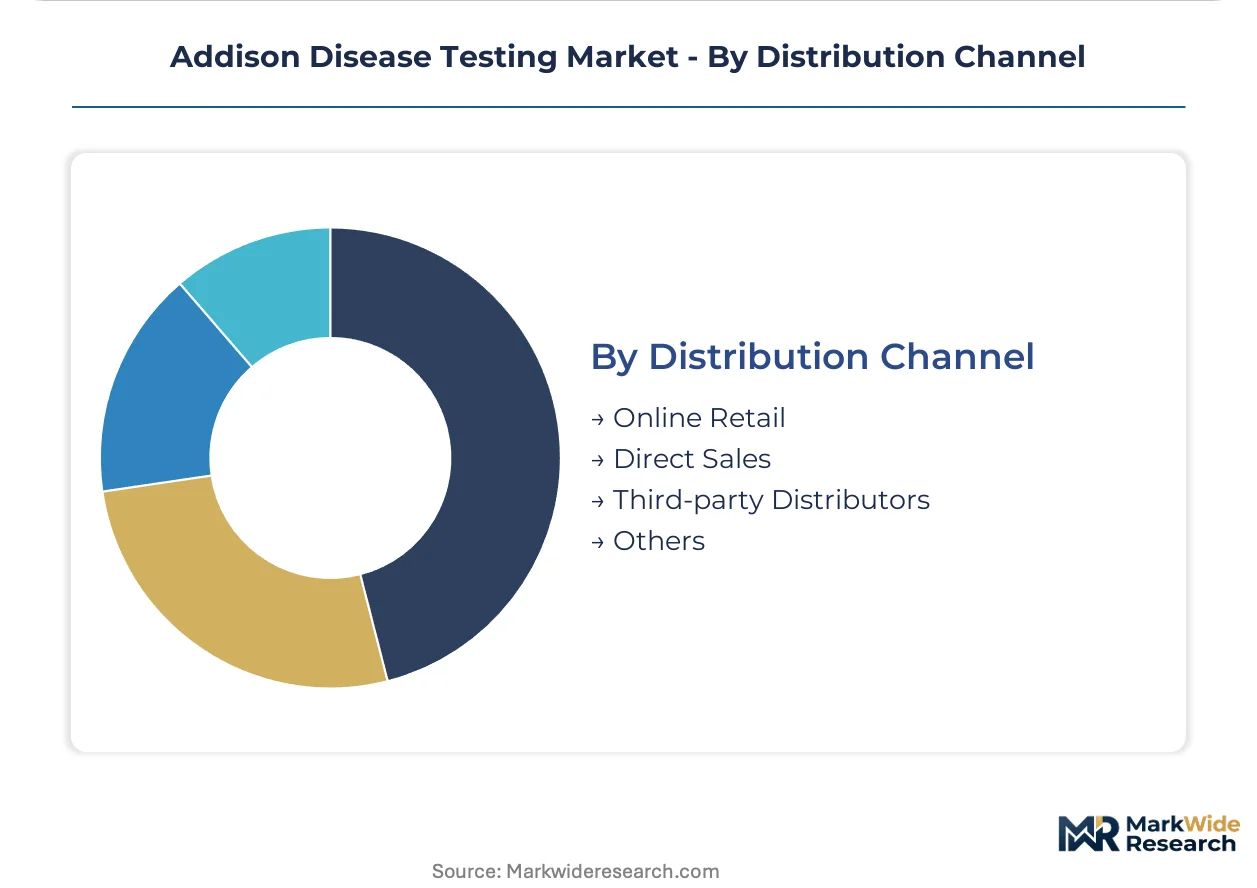
Distribution Channel:
Procurement pathway selection reflects capital equipment versus consumable purchasing patterns and the technical service intensity of analyzer deployment.
- Direct Sales:Manufacturer field organizations dominate automated immunoassay platform placement in health system laboratory networks. Siemens Healthineers and Roche leverage direct relationships to anchor integrated analyzer systems in hospital procurement channels.
- Third-party Distributors:Regional logistics providers supporting reagent supply continuity and emergency replacement inventory for mid-volume laboratories.
- Online Retail:Direct-to-consumer and clinic-facing portals for saliva collection kits and point-of-care rapid tests.
- Others:Group purchasing organizations and consignment arrangements for high-volume reference laboratory contracts.
Direct Sales captures the majority of capital equipment transactions; Online Retail is expanding most quickly in patient-directed home testing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the largest share of Addison disease testing capacity while Germany and Switzerland anchor European production of automated immunoassay platforms. Demand concentrates in health systems with established endocrinology referral networks, whereas supply-side capabilities cluster around precision instrument manufacturing hubs.
United States
Hospital-based diagnostic laboratories in the United States maintain the deepest installed base of ACTH stimulation protocols, driven by health system consolidation that has halved independent contracting entities over the past decade. FDA oversight of laboratory-developed tests is reshaping validation requirements for adrenal function assays in reference laboratories. The Greater Boston and San Francisco Bay Area clusters house specialized endocrinology centers advancing autoimmune screening protocol standardization.
Germany
German reference laboratories are consolidating steroid hormone panels onto unified LC-MS/MS platforms to reduce sample volume requirements and compress turnaround consistency. EU IVDR framework maturation is accelerating CE marking renewals for automated cortisol analyzers, creating replacement demand for compliant instrumentation. The Rhine-Ruhr metropolitan region anchors high-throughput diagnostic laboratory networks serving centralized hospital procurement channels.
Switzerland
Swiss laboratories prioritize metabolite unification on single platforms, narrowing performance gaps with academic medical centers through superior analytical specificity. Swissmedic maintains stringent conformity assessment timelines for IVD manufacturers seeking market authorization. The Basel-Zurich corridor concentrates precision diagnostics development, with Roche leveraging automated immunoassay platforms to sustain cortisol testing workflows.
United Kingdom
NHS endocrinology referral networks in the United Kingdom are expanding bundled panel offerings to capture incidental adrenal insufficiency cases during routine diabetes and thyroid workups. MHRA post-Brexit regulatory divergence is creating parallel compliance tracks for adrenal function assay manufacturers. London and the Southeast concentrate specialized testing infrastructure, though regional health system consolidation is shifting procurement toward integrated platform providers.
Japan
Japanese health systems are adopting saliva-based cortisol collection methods to bypass phlebotomy bottlenecks and expand testing access beyond hospital walls. PMDA guidance on companion diagnostics is influencing validation frameworks for multiplex autoimmune panels incorporating 21-hydroxylase antibody testing. The Kanto region, centered on Tokyo, dominates diagnostic platform deployment, while Osaka-Kansai laboratories drive protocol innovation for novel biomarker validation.
Addison Disease Testing Market Competitive Environment
The competitive structure tilts toward diversified diagnostic conglomerates with integrated analyzer-software capabilities. Hospital procurement consolidation favors vendors offering bundled endocrinology panel contracts over standalone assay specialists. Three archetypes dominate: automated platform providers anchoring high-throughput centralized laboratories, point-of-care accessibility specialists penetrating urgent care settings, and reference laboratory operators capturing margin pools through bundled pricing. Competitive moves concentrate on middleware convergence with laboratory information systems and strategic partnerships to navigate EU MDR recertification burdens.
Among diversified diagnostic conglomerates, F. Hoffmann-La Roche Ltd, Siemens Healthineers, and Abbott Laboratories occupy positions exemplifying distinct strategic vectors. Roche represents the automated platform archetype through its immunoassay systems serving centralized laboratory workflows. Siemens Healthineers anchors the integrated hardware-software convergence approach dominating hospital procurement channels. Abbott Laboratories exemplifies point-of-care accessibility extension, with its positioning in urgent care settings where rapid turnaround carries clinical priority. These three entities collectively illustrate how scale, integration depth, and site-of-care flexibility differentiate competitive positioning in adrenal function diagnostics.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Quest Diagnostics |
| Laboratory Corporation of America Holdings |
| Bio-Rad Laboratories |
| DiaSorin S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Specialized mass spectrometry technicians concentrated in the Rhine-Ruhr metropolitan region and Greater Boston clusters command wage premiums that compress pricing-tier spreads between reference laboratory and hospital-based testing services. Labor-cost differentials between these technical hubs and mid-volume health systems force tiered service pricing that reflects capability scarcity rather than pure reagent economics.
Pricing Analysis
Margin tightening in mid-volume hospital laboratories reflects the capital burden of LC-MS/MS migration against entrenched ELISA infrastructure. Three-tier pricing structure across premium reference laboratory, standard hospital lab, and economy point-of-care levels stratifies by analytical specificity and turnaround time. Cost compression in the standard tier accelerates because procurement committees bundle endocrinology contracts with broader metabolic panels. Research institutions exhibit lowest price sensitivity; urgent care clinics face acute budget constraints.
Supply Chain Analysis
Domestic-content mandates under EU IVDR are reshaping sourcing for European endocrinology clinics, forcing manufacturers to relocate final assembly or secure notified body certification within the trading bloc. Synthetic ACTH manufacturing concentrates in Switzerland and the United States, while precision immunoassay reagents draw from German and Japanese chemical suppliers. Single-source vulnerability in cosyntropin production exposes testing workflows to pharmaceutical shortage risk. Distribution runs through direct manufacturer field organizations for capital equipment and third-party logistics for reagent replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Addison disease testing market functions as a cost-of-compliance story where EU IVDR conformity assessment burdens create barrier-to-entry moats for manufacturers with established quality management systems and notified body relationships.
For Market Incumbents: Deepen middleware convergence with laboratory information systems to capture premium positioning as hospital procurement committees consolidate around integrated platform providers. Defend against point-of-care accessibility specialists by embedding automated immunoassay workflows into health system laboratory networks. Invest in CE marking renewal capacity to exploit replacement demand from IVDD-legacy instrument displacement.
For New Entrants and Emerging Players: FDA evolving guidance on laboratory-developed tests in the United States opens a window for reference laboratory operators capable of rapid ACTH stimulation protocol validation. Target homecare settings with saliva-based cortisol collection kits where phlebotomy bottlenecks create unmet demand. Pursue urgent care clinic partnerships as a go-to-market angle, leveraging rapid turnaround requirements that centralized laboratories cannot satisfy.
For Investors and Strategic Acquirers: Re-rating potential sits with diversified diagnostic conglomerates given hospital system consolidation favoring bundled endocrinology panel contractors over standalone assay specialists. Long-term viability hinges on middleware-software convergence capabilities and EU MDR navigation expertise. Monitor WHO endocrine disorder classification updates as the inflection signal for reimbursement coding harmonization across national health systems.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU IVDR compliance secures access to German and Swiss reference laboratory procurement channels. |
| Hospital System Partnership | Bundled endocrinology panel contracts displace standalone adrenal function assay vendors from preferred supplier lists. |
| Software Companion Development | Middleware platforms unify immunoassay hardware with laboratory information systems for premium positioning. |
| Reimbursement Strategy | WHO classification harmonization streamlines payer coverage for multiplex autoimmune panels. |
| Strategic Partnership | Quality management consultants help smaller IVD developers navigate EU MDR technical documentation requirements. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with endocrinology laboratory directors, hospital procurement managers, IVD regulatory affairs leads, and diagnostic platform engineers. FDA 510(k) submissions, EU notified body documentation, Swissmedic authorization records, and hospital GPO contract databases provided secondary validation. Bottom-up test volume modeling and top-down market sizing triangulated across these sources.
Data-stream reconciliation connected installed base estimates for automated immunoassay platforms with reagent consumption patterns and health system consolidation trends across the projection horizon. Segmentation dimensions included test modality, technology platform, end-user site-of-care, and regional regulatory cluster. CAGRs derived from test volume expansion rates, pricing trajectory assumptions, and instrument replacement cycles tied to EU MDR recertification timelines. Steroid hormone panel unification trends and saliva-based collection adoption curves informed scenario weighting.
The model assumes a particular technology adoption path; alternative pathways for LC-MS/MS platform consolidation would alter the outlook if mid-volume hospital laboratories accelerate migration beyond current sunk-cost barriers. Forecasts reflect assumptions regarding cosyntropin supply continuity, endocrinology subspecialist workforce availability, and payer coverage expansion for home-based cortisol monitoring. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Lipase Testing Reagents Market
Testing Services
United States Hospital Acquired Disease Testing Market
Testing Services
Testing and Analysis Services Market
Testing Services
Cholesterol Testing Services Market
Testing Services
Point of Care Testing Market
Testing Services
INR Test Meter Market
Testing Services
Europe Esoteric Testing Market
Testing Services
Apolipoprotein Testing Market
Testing Services
D-Dimer Testing Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
Medical Device Analytical Testing Outsourcing Market
Testing Services
US Independent Diagnostic Testing Facility Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Fertility and Pregnancy Rapid Test Kits Market