
 Single-Use Negative Pressure Wound Therapy Devices Market | 2026-2036
Single-Use Negative Pressure Wound Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Use Negative Pressure Wound Therapy Devices Market Outlook
CE marking under the EU Medical Device Regulation is unwinding the competitive field for smaller disposable NPWT entrants, raising clinical evidence and post-market surveillance obligations that favor established manufacturers. Smith & Nephew plc leverages its wound care heritage to dominate hospital procurement channels across Western Europe. Mölnlycke Health Care AB specializes in advanced dressing interfaces that differentiate its single-use systems from reusable alternatives. Cardinal Health Inc. controls distribution scale in North American acute care, anchoring its position through integrated supply contracts.
Single-use negative pressure wound therapy devices are sealed, battery-powered systems that apply sub-atmospheric pressure through proprietary foam or gauze interfaces to accelerate granulation tissue formation and wound closure. These systems operate at pressures between -75 and -125 mmHg, with canister capacities designed for 7-14 day wear times before disposal. Portable devices command the widest installed base among product types, though battery operated units are capturing fastest growth as ambulatory surgical volumes rise. Home care represents the most dynamic end user channel, driven by payer pressure to reduce hospital length of stay and skilled nursing facility utilization. Surgical wounds anchor application demand, while diabetic ulcers offer the deepest margin pools due to chronicity and reimbursement premiums for advanced therapies.
FDA 510(k) clearance requirements and the EU MDR technical documentation framework shape product development timelines and clinical trial investments for disposable NPWT systems. Japan's PMDA enforces stringent biocompatibility and electrical safety standards that filter out non-specialized competitors. Stakeholders must monitor evolving CMS national coverage determinations and parallel health technology assessment processes in Germany and France, as these will determine whether single-use formats achieve parity reimbursement with reusable systems in outpatient settings.
Market Dynamics
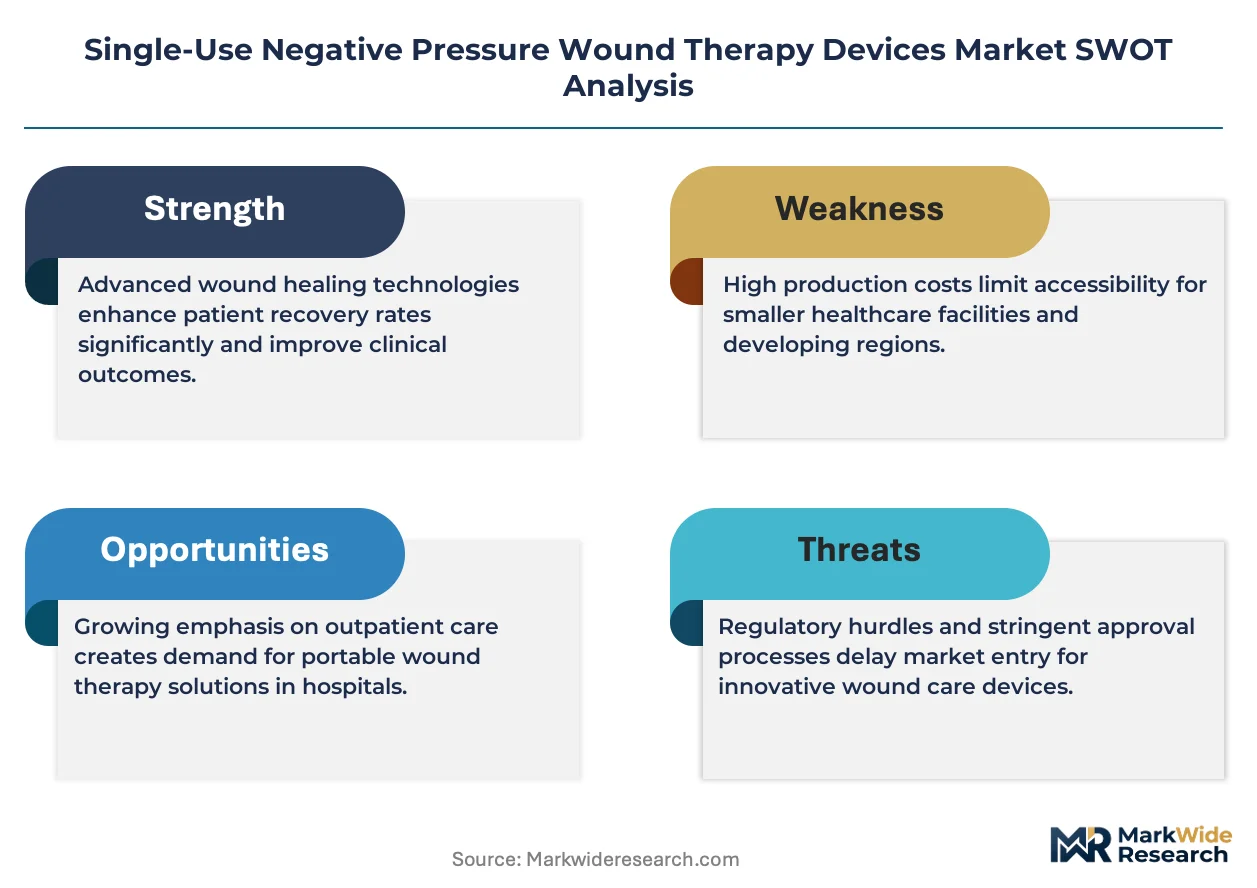
Reimbursement parity negotiations between single-use and reusable NPWT formats are compressing margin structures and forcing manufacturers to demonstrate superior total cost of ownership in outpatient settings.
Growth Catalysts
- EU MDR compliance deadlines:Stricter clinical evidence requirements for CE marking are filtering out marginal competitors and consolidating procurement around validated systems in German and French hospitals.
- Ambulatory surgical centers:Rising procedure volumes in US outpatient facilities are creating dedicated demand for portable, disposable negative pressure systems that eliminate sterilization logistics.
- Silicone interface materials:Advanced dressing adhesives are reducing skin trauma rates and expanding eligible patient populations for home-based NPWT.
Market Restraints
- Polymer feedstock volatility:Medical-grade polyurethane and ABS resin prices fluctuate with petrochemical markets, compressing gross margins on sealed canister assemblies.
- Single-source battery suppliers:Lithium cell concentration in East Asian manufacturing creates supply vulnerability for battery-powered disposable units.
- Reusable system substitution:Hospital capital committees in cost-constrained markets favor amortized rental NPWT over per-procedure disposables.
Strategic Opportunities
- Japan's aging rural populations:Home care infrastructure gaps in prefectures outside Tokyo and Osaka favor single-use systems that eliminate maintenance training.
- Chronic wound management protocols:CMS national coverage determinations for diabetic ulcer outpatient therapy are expanding addressable volume.
- Smart dressing integration:Convergence of negative pressure platforms with wireless exudate monitoring is opening premium positioning in post-acute settings.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies for new adhesive formulations extend product development cycles.
- Electrical safety certification:IEC 60601-1 third-edition compliance for battery-operated devices requires specialized testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Use Negative Pressure Wound Therapy Devices Market |
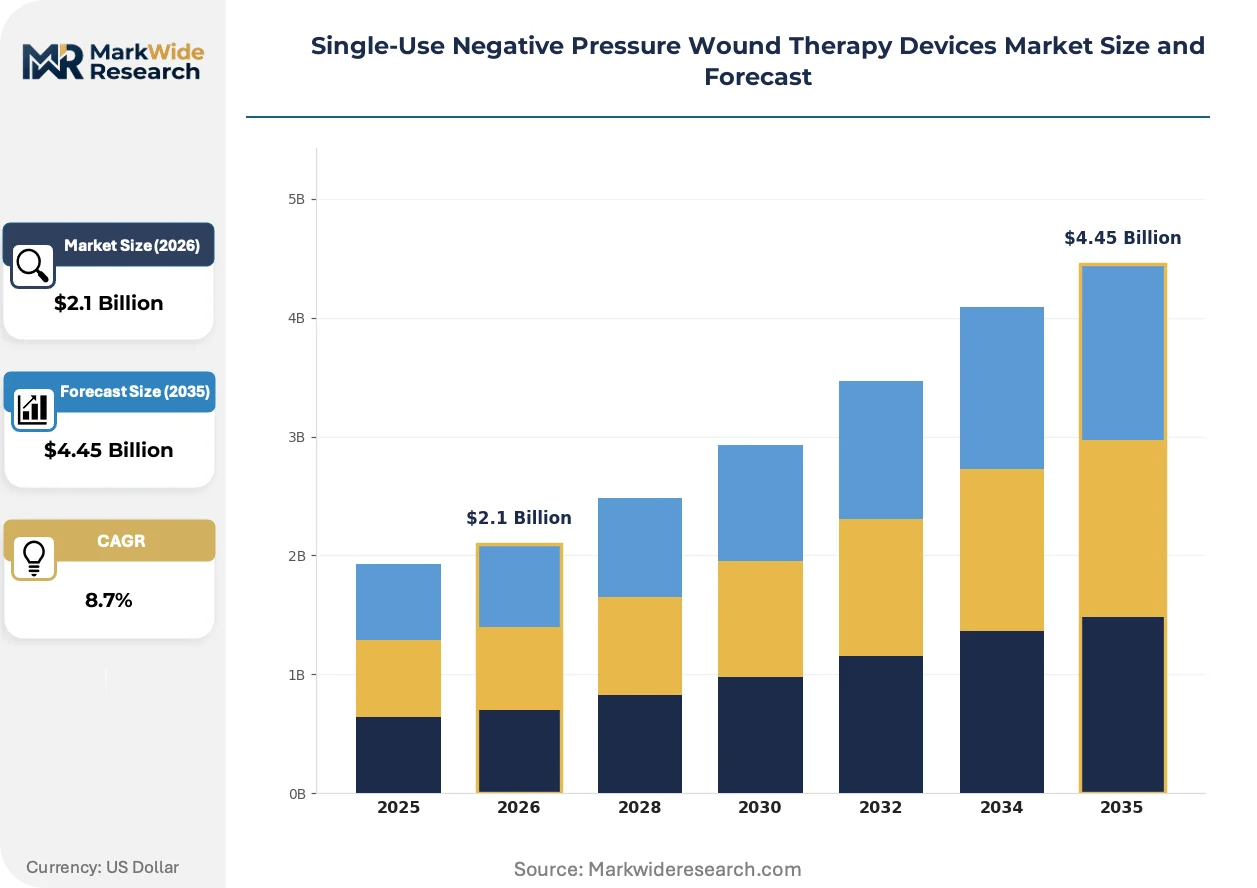
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Disposable Canisters, Battery Operated Units, Accessories End User: Hospitals, Home Care, Outpatient Clinics, Rehabilitation Centers Application: Surgical Wounds, Traumatic Injuries, Diabetic Ulcers, Pressure Sores Technology: Electromechanical Systems, Suction Pumps, Digital Monitors, Vacuum Systems |
| Companies Covered | ConvaTec Group plc, B. Braun Melsungen AG, Smith & Nephew plc, Genadyne Biotechnologies Inc., Cardinal Health Inc., 3M Company, Medela AG, Paul Hartmann AG, Mölnlycke Health Care AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Use Negative Pressure Wound Therapy Devices Market Strategic Shifts
Disposable NPWT platforms are fragmenting into distinct performance tiers as manufacturers balance cost compression against clinical differentiation in increasingly segmented buyer channels.
Canister-integrated pump designs are bifurcating the product landscape. Sealed suction mechanisms with fixed pressure algorithms now dominate high-volume surgical applications where standardization reduces training burden. Meanwhile, adjustable pressure systems with feedback sensors capture premium positioning in complex wound cases requiring titrated therapy. Hospital procurement committees in the United States are segmenting vendor lists accordingly.
MDR technical documentation requirements are reshaping competitive entry barriers. The European Union's expanded post-market surveillance obligations for Class IIa devices now mandate systematic clinical follow-up data that smaller manufacturers lack infrastructure to generate. Established suppliers with dedicated regulatory affairs teams in Ireland and the Netherlands are consolidating market access.
Home care distributors are unbundling device provisioning from clinical training services. Third-party logistics providers now manage inventory and patient onboarding separately from wound care specialist referrals, compressing traditional manufacturer-direct relationships. This channel restructuring is most advanced in Germany, where statutory health insurance funds pressure integrated care contracts.
Single-Use Negative Pressure Wound Therapy Devices Market Segmentation
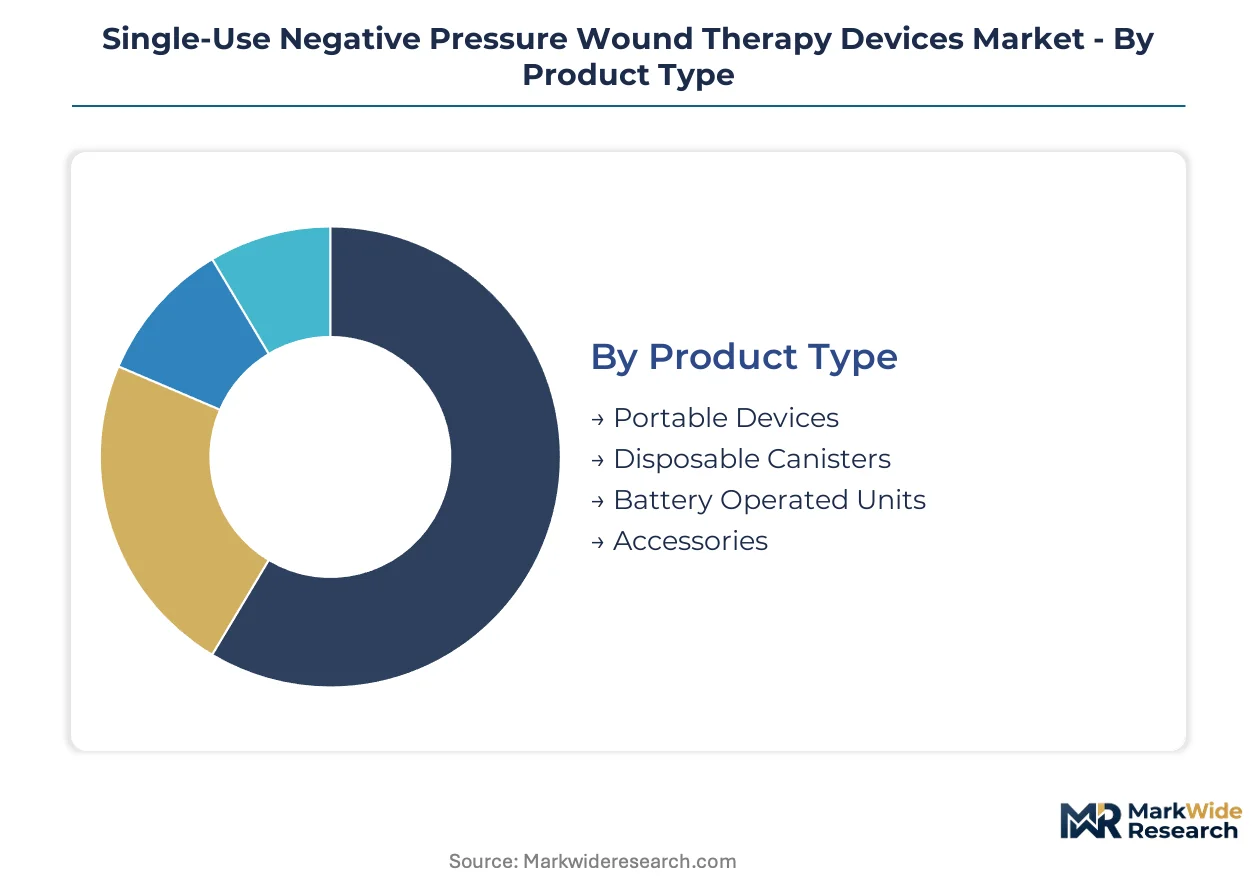
Segmentation in single-use NPWT devices determines channel economics and reimbursement pathways. Product format dictates whether systems flow through acute care procurement or home medical equipment distributors. Application severity shapes pressure algorithm requirements and wear-time specifications.
Product Type:
Channel mix varies sharply by product format, with hospital supply chains favoring integrated pump-canister systems while home care channels prioritize patient-portable units with simplified interfaces.
- Portable Devices:Sealed battery-powered units with fixed pressure algorithms dominate surgical discharge protocols. Demand concentrates in United States ambulatory surgical centers where elimination of sterilization logistics drives procurement preference. These systems anchor the broadest installed base through integrated supply contracts with group purchasing organizations.
- Battery Operated Units:Compact disposable pumps with lithium cell power sources enable 7-14 day wear times without external power. German statutory health insurance funds favor these formats for integrated care contracts covering rural home care populations. Expansion concentrates here as ambulatory surgical volumes rise and payer pressure reduces hospital length of stay.
- Disposable Canisters:Exudate collection reservoirs with hydrophobic filters prevent fluid backflow into pump mechanisms.
- Accessories:Proprietary foam dressings, gauze interfaces, and adhesive drapes complete system configurations.
Portable devices dominate installed base. Battery operated units represent the fastest-growing trajectory as outpatient channels expand.
End User:
Customer type determines pricing tolerance and service bundling requirements, with acute care buyers negotiating volume discounts and home care channels demanding patient training support.
- Hospitals:Acute care facilities procure through centralized supply chains with emphasis on standardization and staff training efficiency. Demand concentrates in surgical wards and intensive care units where NPWT reduces complication rates and readmission penalties. These buyers favor sealed systems with minimal maintenance requirements.
- Home Care:Outpatient wound management settings prioritize patient-operable devices with clear alarm indicators and simplified dressing changes. Japan's aging rural populations outside Tokyo and Osaka prefectures favor single-use formats that eliminate maintenance training for family caregivers. This channel commands premium positioning due to reimbursement premiums for advanced therapies.
- Outpatient Clinics:Freestanding surgical facilities require portable systems for immediate post-procedure application.
- Rehabilitation Centers:Long-term care settings apply NPWT for pressure sore management and post-surgical recovery.
Hospitals dominate installed base. Home care is where expansion concentrates.
Application:
Wound etiology shapes pressure algorithm requirements and reimbursement coding, with chronic conditions commanding sustained therapy durations and premium reimbursement tiers.
- Surgical Wounds:Incisional and dehisced surgical sites require standardized negative pressure application to reduce seroma formation and accelerate primary closure. Demand concentrates in high-volume orthopedic and cardiothoracic procedures across United States hospital systems. These applications anchor the largest procedure volume.
- Diabetic Ulcers:Neuropathic foot wounds in diabetic patients demand extended therapy durations with frequent dressing changes. CMS national coverage determinations for outpatient diabetic ulcer therapy are expanding addressable volume in United States Medicare populations. This application offers the deepest margin pools due to chronicity and reimbursement premiums.
- Traumatic Injuries:Open fracture and soft tissue trauma cases require immediate NPWT application in emergency settings.
- Pressure Sores:Facility-acquired and community-acquired pressure injuries in immobilized patients.
Surgical wounds dominate installed base. Diabetic ulcers represent the steepest expansion trajectory as chronic disease prevalence rises.
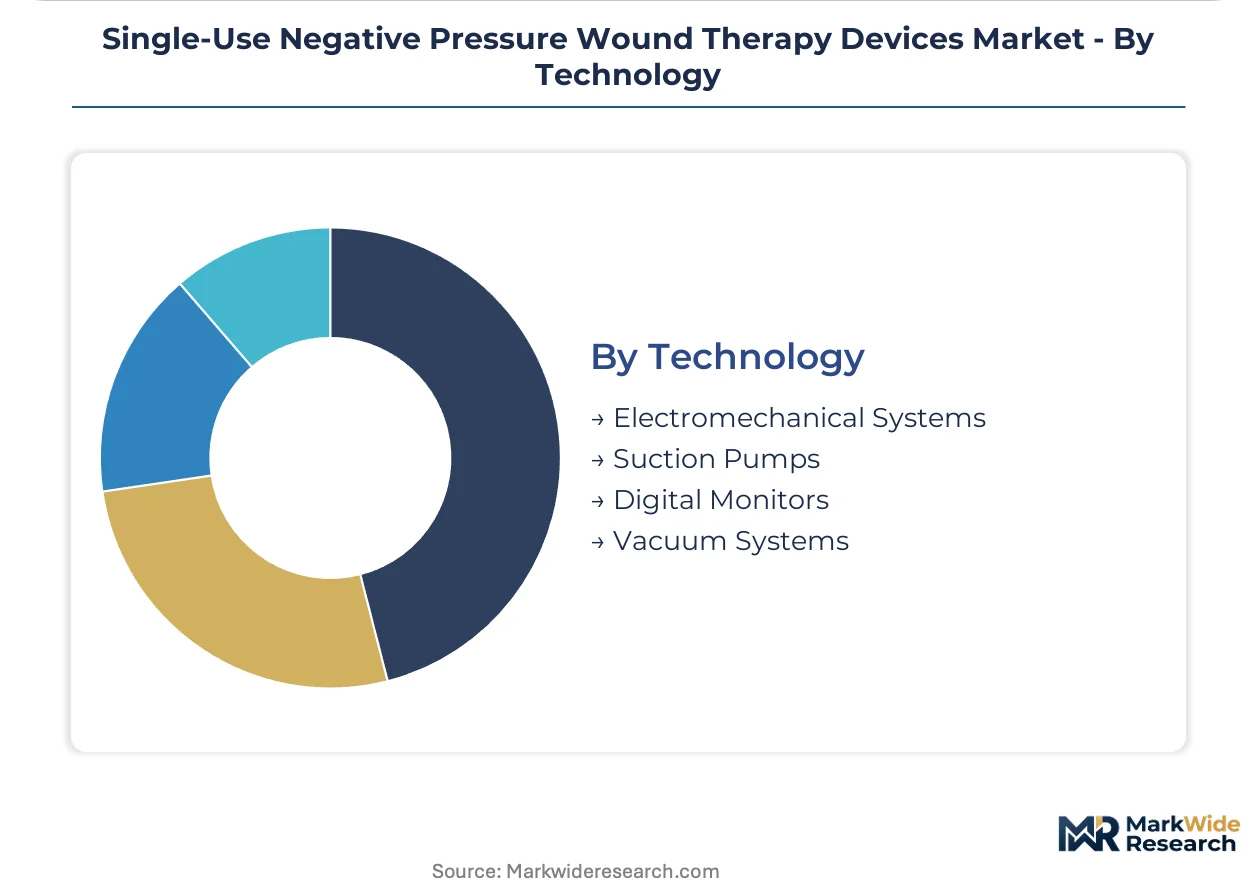
Technology:
Technology tier determines manufacturing complexity and regulatory classification, with digital monitoring capabilities commanding premium positioning in post-acute settings.
- Electromechanical Systems:Integrated pump-motor assemblies with pressure feedback sensors enable titrated therapy for complex wound cases. Demand concentrates in German and French hospitals where MDR compliance favors validated systems with systematic clinical follow-up data. These systems capture premium positioning through adjustable pressure algorithms.
- Suction Pumps:Basic negative pressure generation mechanisms with fixed pressure settings serve high-volume surgical applications. United States ambulatory surgical centers favor these formats for standardization and reduced training burden. This technology anchors the broadest cost-competitive tier.
- Digital Monitors:Wireless exudate monitoring and pressure feedback systems enable remote patient surveillance.
- Vacuum Systems:Passive suction mechanisms without powered pumps serve select low-cost market segments.
Suction pumps dominate installed base. Electromechanical systems are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement incentives for outpatient wound management are reshaping geographic demand patterns. CMS national coverage determinations in the United States and statutory health insurance reforms in Germany accelerate home care adoption. Japan's aging demographics and rural healthcare gaps favor single-use formats that eliminate caregiver training requirements.
United States
Ambulatory surgical center expansion drives portable disposable NPWT procurement. FDA 510(k) clearance pathways standardize quality benchmarks for sealed pump-canister systems. Hospital supply chains in Texas and Florida concentrate procurement through integrated group purchasing organization contracts.
Germany
Statutory health insurance funds pressure integrated care contracts toward home-based wound management. EU MDR technical documentation requirements filter marginal competitors from CE marking pathways. Medical device clusters in North Rhine-Westphalia consolidate regulatory affairs infrastructure for post-market surveillance compliance.
Japan
Aging rural populations outside Tokyo and Osaka prefectures face home care infrastructure gaps. PMDA enforces stringent biocompatibility and electrical safety standards for battery-operated disposable units. Nagoya-based medical device distributors manage inventory separately from wound care specialist referrals.
United Kingdom
NHS England procurement frameworks emphasize total cost of ownership comparisons between single-use and reusable NPWT formats. MHRA post-Brexit regulatory alignment maintains CE marking recognition for transitional market access. London and Southeast England hospital networks pilot smart dressing integration with remote patient monitoring.
France
ANSM clinical evidence requirements for Class IIa device registration favor established manufacturers with systematic follow-up data. Regional health agencies in Île-de-France negotiate outcome-based contracts for diabetic ulcer outpatient therapy. Lyon-based wound care specialists drive adoption of silicone interface materials to reduce skin trauma rates.
Single-Use Negative Pressure Wound Therapy Devices Market Competitive Environment
Listed leaders compete with private specialists across regulatory compliance capabilities and distribution scale. The vendor base concentrates around wound care heritage conglomerates and diversified medical device suppliers, with tiered positioning between premium clinical systems and cost-competitive surgical formats. Three archetypes dominate: integrated wound care specialists with hospital procurement channel control, diversified health care conglomerates leveraging supply chain scale, and regional private manufacturers targeting price-sensitive home care segments. Competitive moves center on M&A for regulatory infrastructure and backward integration into proprietary dressing materials.
Within the integrated wound care specialist tier, Smith & Nephew plc and Mölnlycke Health Care AB exemplify heritage-driven hospital channel dominance. Cardinal Health Inc. occupies a position among diversified supply chain conglomerates anchoring North American acute care distribution. These three entities represent distinct strategic postures: wound-specific clinical credibility, advanced dressing interface specialization, and procurement scale integration respectively.
| Leading Market Players |
|---|
| ConvaTec Group plc |
| B. Braun Melsungen AG |
| Smith & Nephew plc |
| Genadyne Biotechnologies Inc. |
| Cardinal Health Inc. |
| 3M Company |
| Medela AG |
| Paul Hartmann AG |
| Mölnlycke Health Care AB |
| Others |
Value Chain & Pricing Dynamics
Silicone interface materials replacing traditional acrylic adhesives simultaneously relocate dressing component sourcing toward German and Swedish chemical clusters while compressing margin structures for manufacturers locked into legacy supply agreements. This substitution dynamic concentrates pricing power with specialized polymer suppliers and forces device makers to absorb reformulation costs or surrender hospital procurement contracts.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 510(k) cleared and MDR-validated systems commanding hospital procurement premiums against unvalidated alternatives. Per-unit transactional pricing dominates, with volume scale and after-sales service bundling as secondary differentiation factors. Cost compression in standard surgical tiers is intensifying because reimbursement parity negotiations between single-use and reusable formats squeeze per-procedure margins. Ambulatory surgical centers exhibit highest price sensitivity due to fixed case-rate economics, while academic medical centers prioritize clinical validation over unit cost.
Supply Chain Analysis
China and South Korea anchor lithium cell production for battery-operated disposable units, while Germany and the United States concentrate electromechanical pump assembly. Medical-grade polyurethane from Belgian petrochemical complexes and ABS resin from Gulf Coast refineries constitute critical raw material dependencies. Single-source vulnerability in East Asian battery manufacturing creates supply exposure for portable device makers. Distribution runs through integrated group purchasing organizations in North American acute care and statutory health insurance networks in German home care.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital system consolidation and ambulatory surgical center roll-ups, compressing vendor lists and amplifying price leverage for procurement committees.
For Market Incumbents: Compound regulatory infrastructure advantages by accelerating MDR post-market surveillance data generation to filter marginal competitors from CE marking pathways. Deepen backward integration into proprietary silicone adhesive formulations to defend margin position against polymer feedstock volatility and lock in dressing interface differentiation. For New Entrants and Emerging Players: Differentiate on smart dressing integration with wireless exudate monitoring to capture premium positioning in Japanese rural home care and German integrated care contracts. Target Japan's aging prefectures outside Tokyo and Osaka where infrastructure gaps favor maintenance-free single-use formats and PMDA validation barriers deter non-specialized competitors. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier manufacturers with established regulatory affairs teams in Ireland or the Netherlands and underdeveloped smart monitoring capabilities, as these entities offer acquisition currency for digital convergence plays. Monitor CMS national coverage determination expansions for diabetic ulcer outpatient therapy as the inflection signal for home care channel acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR technical documentation investments filter competitors from German and French hospital procurement. |
| Hospital System Partnership | Integrated supply contracts with group purchasing organizations anchor North American acute care volume. |
| Software Companion Development | Wireless exudate monitoring integration opens premium positioning in post-acute and home care settings. |
| Reimbursement Strategy | CMS national coverage determination alignment determines outpatient diabetic ulcer therapy addressability. |
| FDA Submission | 510(k) clearance standardization enables ambulatory surgical center procurement in Texas and Florida. |
Study Parameters
Desk research of FDA 510(k) filings, EU MDR technical documentation databases, CMS national coverage determinations, and hospital procurement contract disclosures preceded structured interviews with wound care clinicians, biomedical engineers, group purchasing organization contracts managers, and statutory health insurance fund administrators. Primary fieldwork combined with secondary validation through SEC 10-K regulatory disclosures and trade data from medical device customs records. Bottom-up unit volume estimates triangulated against top-down expenditure flows from national health accounts.
Variance decomposition across product type, end user channel, wound application severity, and technology tier shaped the analytical framework over the projection horizon. CAGRs derived from segmented growth rate modeling incorporating procedure volume trajectories, reimbursement policy elasticity, and technology substitution curves. Forecast inputs included ambulatory surgical center expansion rates and polymer feedstock price volatility indices.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR enforcement, and Japan PMDA biocompatibility standards; material policy shifts would require re-modeling. Specific risks include CMS coverage determination reversals, lithium cell supply disruptions, and MDR post-market surveillance obligation expansions. Recalibration cycles align with material shifts in reimbursement policy, regulatory enforcement intensity, and raw material cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Surgical Wound Care Market
Wound Care
Burn Care Centers Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Wound Cleanser Products Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Surgical Dressing Market
Wound Care
Wound Closure Strips Market
Wound Care
Hydrocolloid Dressing Market
Wound Care
Global Surgical Drains/Wound Drainage Market
Wound Care
Wound Skin Care Market
Wound Care
Decubitus Ulcer Treatment Products Market
Wound Care
Wound Retractor Market
Wound Care
Antimicrobial Wound Dressings Market
Wound Care
Venous Skin Ulcer Treatment Market
Wound Care
Negative Pressure Wound Therapy Market
Wound Care
Vascular Ulcer Treatment Market