
 Pressure Ulcer Treatment Market | 2026-2036
Pressure Ulcer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Ulcer Treatment Market Analysis
CMS non-payment rules for hospital-acquired pressure injuries is expanding the cost-of-entry calculus for wound care programs in acute care settings. Molnlycke Health Care leverages its Scandinavian manufacturing base to sustain premium positioning in advanced foam dressings across European and North American channels. Coloplast anchors its competitive stance through specialized hydrocolloid portfolios tailored to sacral and heel wound anatomies. Smith & Nephew competes on negative pressure therapy integration, extending its reach into post-acute and homecare transitions.
Pressure ulcer treatment encompasses therapeutic interventions designed to prevent, manage, and heal localized skin and underlying tissue damage caused by sustained pressure, friction, or shear forces. Hydrocolloid and foam dressings constitute the dominant product categories, with hydrocolloid formulations forming gel matrices upon contact with exudate to maintain moist wound environments conducive to autolytic debridement. Application segmentation reveals long-term care facilities as the most mature demand channel, while homecare represents the fastest-growing segment as discharge protocols accelerate and remote monitoring technologies enable outpatient wound management. Technology differentiation centers on negative pressure therapy devices, which command premium pricing due to their mechanized exudate removal and microdeformational tissue stimulation capabilities.
FDA 510(k) clearance pathways govern device introductions, while EMA medical device regulations and ISO 13485 quality management standards shape transatlantic market access requirements. The EU Medical Device Regulation intensifies clinical evidence demands for advanced dressings, compressing timelines for smaller manufacturers lacking dedicated regulatory affairs infrastructure. Stakeholders must monitor reimbursement code consolidation dynamics and antimicrobial resistance scrutiny affecting silver-impregnated dressing formulations.
Market Dynamics
Hospital-acquired condition non-payment policies are fundamentally restructuring wound care economics, forcing acute care systems to internalize prevention costs while accelerating investment in moisture-retentive dressing protocols and negative pressure therapy infrastructure.
Growth Catalysts
- CMS Hospital-Acquired Condition Reduction Program:Medicare non-payment for Stage III/IV pressure injuries creates direct financial accountability, driving capital allocation toward dedicated wound care units and advanced dressing formularies.
- Hydrocolloid gel matrix technology:Autolytic debridement capabilities reduce manual intervention requirements, expanding nurse practitioner autonomy in long-term care and skilled nursing facility protocols.
- Japan's super-aged demographic profile:Population over 65 exceeds 29 percent, concentrating demand for sacral and heel wound management in institutional and homecare settings simultaneously.
Market Restraints
- Silver-impregnated dressing cost volatility:Antimicrobial raw material pricing fluctuates with precious metals markets, compressing margin structures for advanced antimicrobial portfolios.
- EU MDR clinical evidence requirements:Expanded documentation demands for Class IIa and IIb wound dressings extend regulatory timelines, disadvantaging manufacturers lacking dedicated regulatory infrastructure.
- Negative pressure therapy capital intensity:Device acquisition and disposable tubing costs limit penetration in underfunded long-term care facilities and developing market acute care settings.
Strategic Opportunities
- Remote patient monitoring integration:Sensor-enabled dressings transmitting exudate levels and temperature data enable hospital-at-home reimbursement models, opening Medicare Advantage and commercial payer channels.
- Germany's outpatient wound care reimbursement clarity:Structured EBM codes for specialized wound management support independent wound center proliferation outside hospital cost structures.
- Foam-hydrocolloid hybrid convergence:Combined absorbent and moisture-retentive properties address mixed exudate presentations, capturing share from single-mechanism legacy formulations.
Industry Challenges
- Wound care specialist certification bottlenecks:WOCN credentialing capacity constraints limit clinical workforce expansion, creating service delivery gaps in rural and underserved urban markets.
- ISO 13485 quality management system implementation:Smaller dressing manufacturers face disproportionate compliance costs when scaling from regional to transatlantic distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Ulcer Treatment Market |
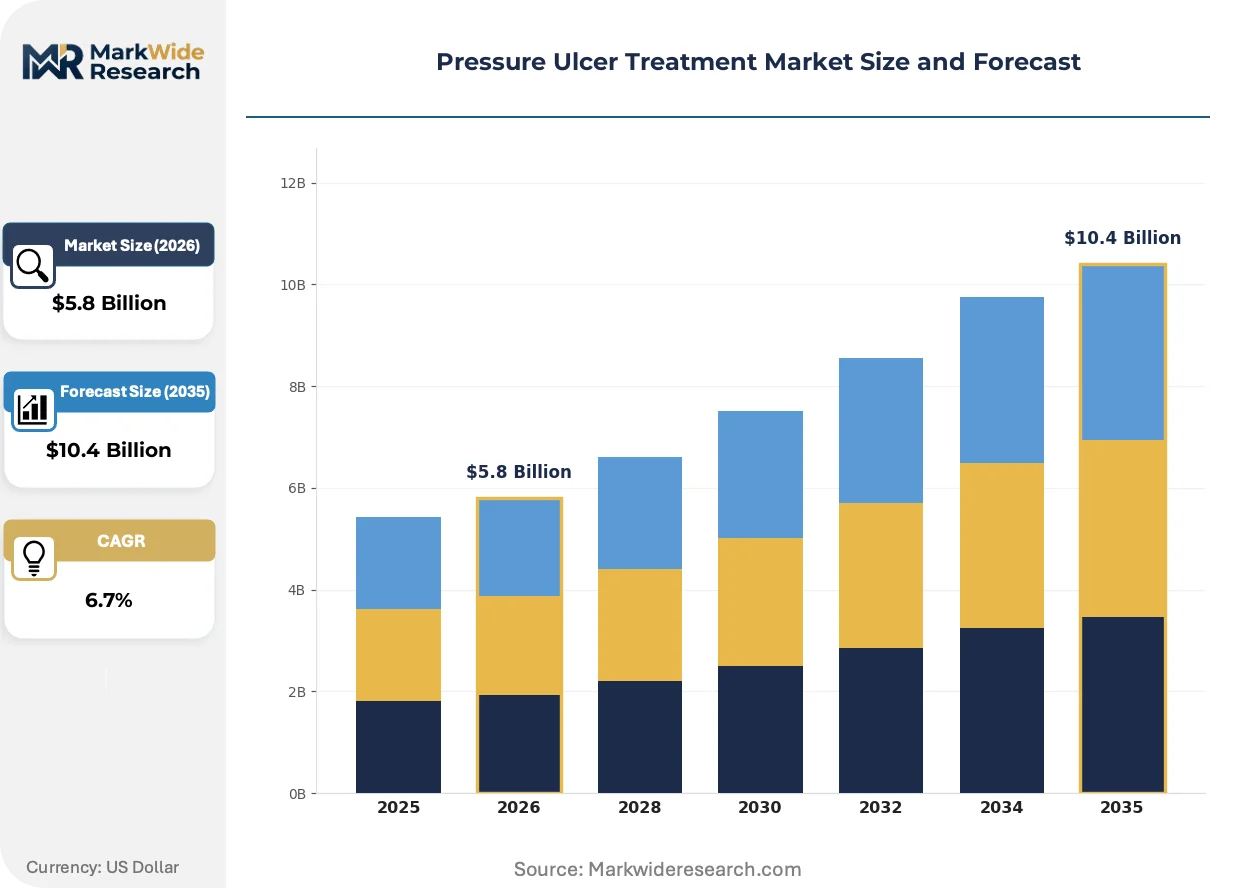
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Topical Agents, Mattresses, Devices Application: Homecare, Hospitals, Long-term Care, Outpatient Facilities Technology: Hydrocolloid, Foam, Alginate, Negative Pressure Therapy End User: Nursing Homes, Rehabilitation Centers, Palliative Care, Ambulatory Surgical Centers |
| Companies Covered | Molnlycke Health Care, Coloplast, Smith & Nephew, Cardinal Health, Integra LifeSciences, ConvaTec Group, B. Braun, Medline Industries, 3M Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Ulcer Treatment Market Emerging Trajectories
Moisture-retentive healing paradigms are displacing traditional dry wound management, while regulatory evidence requirements and remote monitoring capabilities simultaneously reshape product development priorities and care delivery architectures.
Smart dressing technology is unifying exudate management with biometric monitoring. Negative pressure therapy devices now incorporate pressure sensors and wireless transmission modules, enabling real-time wound status documentation. Acute care systems in the United States and Germany are piloting these integrated systems for post-discharge surveillance, compressing the boundary between institutional and home-based wound management.
EU Medical Device Regulation intensifies clinical evidence requirements for hydrocolloid and foam dressings previously cleared under lighter protocols. Manufacturers must now generate prospective clinical data or systematic literature reviews for substantial equivalence claims. This regulatory friction disproportionately affects mid-tier suppliers lacking dedicated clinical affairs teams, consolidating competitive position around established players with existing trial infrastructure.
Homecare channels are capturing volume from traditional long-term care facilities as discharge protocols accelerate and family caregiver training programs expand. Medicare Advantage plans in the United States increasingly bundle wound care supplies with skilled nursing visits, shifting procurement authority from facility purchasing committees to regional home health agencies. This channel migration demands simplified dressing application designs and enhanced patient education materials.
Pressure Ulcer Treatment Market Segmentation
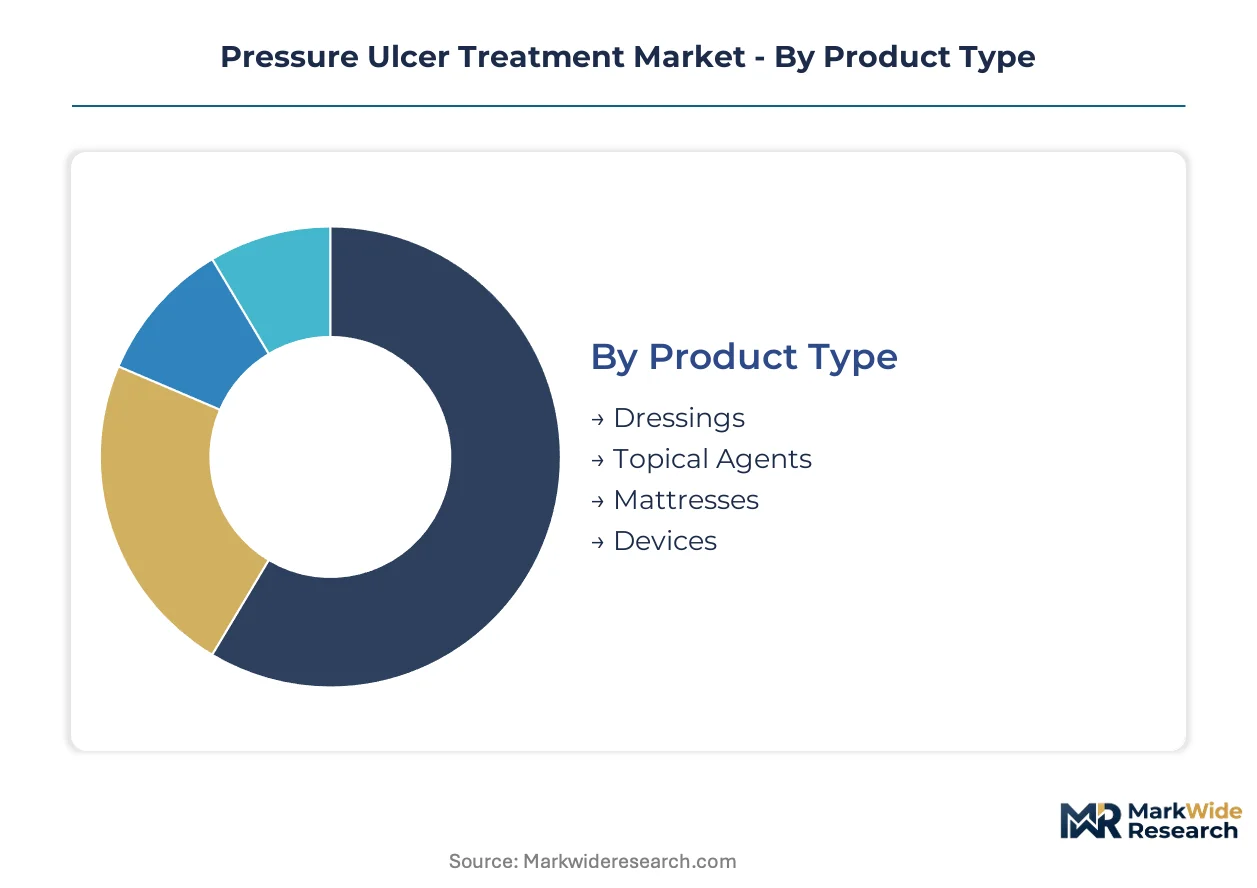
Pressure ulcer treatment markets fragment across four distinct category axes, each governing procurement authority and margin capture differently. Product type and technology dimensions concentrate manufacturing investment, while application and end-user channels dictate reimbursement pathways and clinical workflow integration.
Product Type:
Supply concentration clusters around absorbent and moisture-retentive platforms, with manufacturing scale determining competitive position across institutional procurement channels.
- Dressings:Hydrocolloid and foam formulations dominate hospital formularies due to autolytic debridement capabilities and extended wear times. Long-term care facilities in Germany and Japan absorb the bulk of standard foam capacity as CMS non-payment policies drive prevention-focused inventory builds.
- Devices:Negative pressure therapy systems command premium positioning through mechanized exudate removal and microdeformational tissue stimulation. Acute care systems in the United States concentrate demand as hospital-acquired condition penalties intensify capital allocation toward proven intervention technologies.
- Topical Agents:Enzymatic and antimicrobial formulations serve adjunctive roles in necrotic wound preparation.
- Mattresses:Alternating pressure and low-air-loss surfaces address primary prevention in immobile patient populations.
Dressings absorb the bulk of installed capacity; Devices are expanding most quickly.
Application:
Channel migration from institutional to outpatient settings is redistributing procurement authority and demanding simplified product designs.
- Long-term Care:Skilled nursing facilities represent the most mature demand channel with established wound care protocols and dedicated nursing specialization. Japan's super-aged demographic profile concentrates sacral and heel wound incidence in institutional settings with 24-hour monitoring capabilities.
- Homecare:Discharge acceleration and remote monitoring enablement position this channel for steepest expansion trajectory. Medicare Advantage plans in the United States increasingly bundle wound supplies with skilled nursing visits, shifting purchasing decisions to regional home health agencies.
- Hospitals:Acute care settings prioritize prevention infrastructure over treatment products due to non-payment policy exposure.
- Outpatient Facilities:Specialized wound centers in Germany leverage EBM reimbursement clarity to operate outside hospital cost structures.
Long-term Care retains the deepest installed base; Homecare is climbing the fastest.
Technology:
Regulatory evidence requirements are compressing competitive timelines and consolidating position around established clinical trial infrastructure.
- Foam:Open-cell polyurethane structures manage moderate-to-heavy exudate through capillary action and vertical wicking. Molnlycke Health Care's Scandinavian manufacturing base sustains premium supply to North American and European channels with consistent quality scale.
- Hydrocolloid:Carboxymethylcellulose and gelatin matrices form cohesive gels upon exudate contact, maintaining moist wound environments conducive to autolytic debridement. Coloplast anchors specialized portfolios targeting sacral and heel anatomies with shaped conformability.
- Alginate:Calcium-sodium fiber dressings derived from brown seaweed address heavily exuding wounds through ion exchange gel formation.
- Negative Pressure Therapy:Vacuum-assisted closure devices command premium pricing tiers due to mechanized fluid removal and documented healing acceleration.
Foam and Hydrocolloid together absorb the bulk of dressing capacity; Negative Pressure Therapy is gaining share fastest.
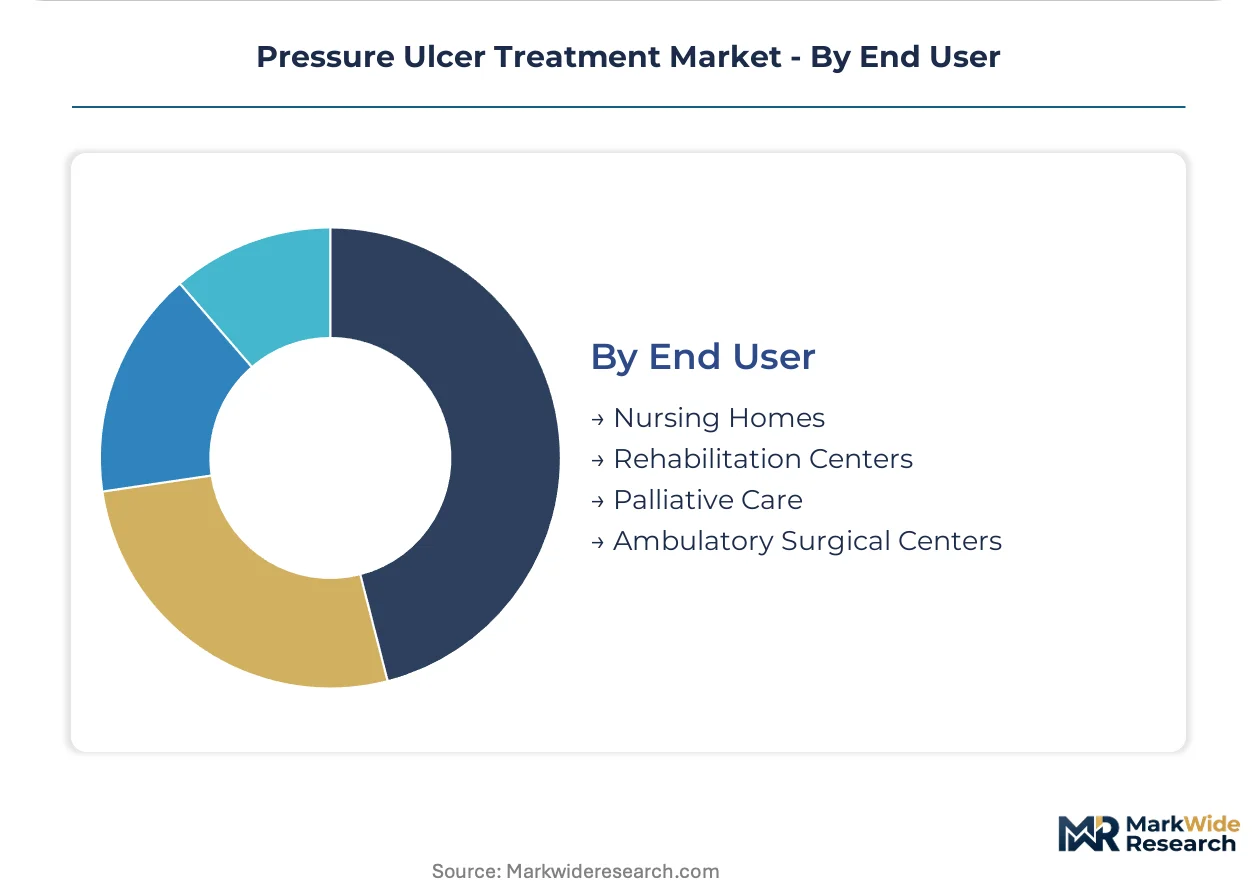
End User:
Credentialing capacity constraints and reimbursement fragmentation shape service delivery economics across institutional categories.
- Nursing Homes:Medicaid-dependent reimbursement structures limit advanced dressing adoption despite high patient acuity and pressure injury incidence.
- Rehabilitation Centers:Transitional care settings bridge acute discharge and long-term placement, requiring versatile wound management protocols.
- Palliative Care:Comfort-focused outcomes prioritize exudate containment and odor management over healing acceleration.
- Ambulatory Surgical Centers:Same-day procedure volumes generate limited pressure ulcer treatment demand relative to institutional counterparts.
Nursing Homes absorb the bulk of patient volume; Rehabilitation Centers are expanding most quickly as transitional care protocols lengthen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MedTech tax-incentive zones in Massachusetts and Minnesota concentrate advanced wound care R&D, while Germany's EBM reimbursement clarity and Japan's super-aged demographic profile anchor institutional demand for pressure ulcer prevention infrastructure.
United States
CMS Hospital-Acquired Condition Reduction Program penalties drive capital allocation toward dedicated wound care units in acute care systems. FDA 510(k) clearance pathways govern negative pressure therapy device introductions. Minneapolis-St. Paul medical device clusters host manufacturing scale for foam dressing production serving North American hospital formularies.
Germany
Structured EBM codes for specialized wound management support independent wound center proliferation outside hospital cost structures. EU Medical Device Regulation intensifies clinical evidence requirements for hydrocolloid dressings. Bavaria's medical technology corridor anchors production of advanced moisture-retentive dressing platforms for European distribution.
Japan
Population over 65 exceeds 29 percent, concentrating sacral and heel wound incidence in institutional and homecare settings simultaneously. PMDA medical device regulations shape market access for negative pressure therapy systems. Kanto region acute care networks pilot sensor-enabled dressing integration for post-discharge surveillance protocols.
United Kingdom
NHS England wound care transformation programs accelerate adoption of autolytic debridement protocols in community nursing services. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards. Greater London procurement frameworks consolidate purchasing authority for advanced dressing formularies across integrated care systems.
Canada
Provincial health authority non-payment policies for hospital-acquired pressure injuries mirror CMS accountability structures. Health Canada medical device licensing requirements govern negative pressure therapy market entry. Ontario's Golden Horseshoe medical device manufacturing base supplies foam and hydrocolloid capacity for North American institutional channels.
Pressure Ulcer Treatment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology vectors. Market structure concentrates around established clinical trial infrastructure and regulatory affairs capabilities, with tiered positioning separating premium technology integrators from commodity dressing suppliers. Three archetypes dominate: Scandinavian manufacturing-based foam specialists, diversified MedTech conglomerates with negative pressure therapy portfolios, and regional pure-plays serving procurement-consolidated long-term care channels. Competitive moves center on M&A for regulatory infrastructure acquisition and strategic partnerships for homecare channel access.
Among Scandinavian-origin specialists, Molnlycke Health Care occupies a position exemplifying premium foam dressing manufacturing scale. Coloplast represents the hydrocolloid specialization archetype with shaped conformability portfolios. Smith & Nephew anchors the negative pressure therapy integration tier, extending device reach into post-acute transitions. These three entities exemplify how regulatory evidence generation capabilities and channel-specific product architectures determine competitive position.
| Leading Market Players |
|---|
| Molnlycke Health Care |
| Coloplast |
| Smith & Nephew |
| Cardinal Health |
| Integra LifeSciences |
| ConvaTec Group |
| B. Braun |
| Medline Industries |
| 3M Health Care |
| Others |
Supply Flow & Price Mechanics
CMS non-payment policies for hospital-acquired pressure injuries are forcing acute care systems toward premium moisture-retentive dressing formularies, compelling suppliers to scale Scandinavian and North American manufacturing capacity while absorbing silver-impregnated raw material volatility.
Pricing Analysis
Short lead-time premiums distinguish negative pressure therapy device procurement from standard dressing spot markets. Three-tier pricing structure across premium, standard, and economy levels segments by FDA clearance tier and clinical evidence depth. Pricing pressure stems from EU MDR documentation demands compressing margin structures for mid-tier antimicrobial portfolios. Long-term care facilities exhibit highest price sensitivity due to Medicaid-dependent reimbursement, while acute care systems prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Direct-to-hospital GPO channels handle institutional volume, while regional home health agencies capture accelerating homecare demand. Manufacturing concentrates in Sweden, Denmark, and the Minneapolis-St. Paul corridor for foam dressing production, with Bavaria anchoring hydrocolloid capacity. Raw material dependencies include medical-grade polyurethane, carboxymethylcellulose, and silver-ion antimicrobial compounds. Single-source vulnerability in Scandinavian polymer supply creates exposure. Distribution runs through group purchasing organizations and specialized wound care distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pressure ulcer treatment market functions as a cost-of-compliance arena where EU MDR clinical evidence requirements erect durable barriers against undercapitalized entrants lacking dedicated regulatory infrastructure.
For Market Incumbents: Lock in regulatory affairs scale advantages by acquiring mid-tier manufacturers facing EU MDR documentation bottlenecks. Expand negative pressure therapy disposable manufacturing in Minnesota to capture CMS-driven acute care demand. Consolidate position against emerging sensor-enabled dressing entrants through exclusive hospital system partnership structures.
For New Entrants and Emerging Players: Sensor-enabled dressing platforms transmitting exudate and temperature data offer the most penetrable wedge into Medicare Advantage hospital-at-home reimbursement channels. Target Germany's independent wound center proliferation outside hospital cost structures. Pursue software companion development partnerships with established dressing manufacturers lacking digital capabilities.
For Investors and Strategic Acquirers: The window for entry favors clinical trial infrastructure specialists with existing EU MDR technical documentation libraries. Five-to-ten year viability hinges on regulatory compliance moats deepening faster than capital can replicate them. Watch FDA 510(k) clearance velocity for negative pressure therapy accessories as inflection signal for homecare channel capture rates.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates market access timelines for hydrocolloid and foam dressing portfolios against undercapitalized competitors. |
| Hospital System Partnership Expansion | Locks in formulary placement for negative pressure therapy systems under CMS non-payment accountability structures. |
| Sensor-Enabled Dressing Development | Enables Medicare Advantage reimbursement capture in hospital-at-home channels through remote monitoring integration. |
| Scandinavian Manufacturing Scale Addition | Secures premium foam dressing supply continuity for North American GPO contract fulfillment. |
| WOCN Certification Program Sponsorship | Addresses specialist workforce bottlenecks constraining service delivery in rural and underserved urban markets. |
Methodological Framework
Document review covered FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare cost reports, and hospital procurement databases, complemented by interviews with wound care clinicians, hospital purchasing committee directors, GPO contracts managers, and biomedical engineers specializing in negative pressure therapy systems. Secondary validation drew from ISO 13485 certification registries, EMA medical device guidance documents, and trade flow data for medical-grade polymer inputs. Bottom-up demand modeling triangulated against top-down reimbursement expenditure analysis.
Cross-referencing historical dressing adoption curves with expert panel input on EU MDR implementation timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application channel, technology platform, and end-user facility category. CAGRs derived from regression analysis of installed base expansion and replacement cycle dynamics, incorporating PMDA regulatory velocity for Japan's super-aged demographic demand and Germany's EBM code reimbursement clarity as industry-specific inputs.
Several conditions sit outside the modeled scope, including antimicrobial resistance regulatory bans affecting silver-impregnated formulations and tariff restructuring on Scandinavian polymer imports. Forecasts reflect assumptions regarding CMS non-payment policy continuity and EU MDR enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Surgical Wound Care Market
Wound Care
Wound Care Sealants Market
Wound Care
US Wound Irrigation System Market
Wound Care
Asia Pacific Advanced Wound Care Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Dental Wound Dressings Market
Wound Care
Acute Wound Care Market
Wound Care
Advanced Wound Care Market
Wound Care
Advanced Wound Dressings Market
Wound Care
Wound Irrigation Solutions Market
Wound Care
Negative Pressure Wound Therapy Market
Wound Care
Global Burn Care Market
Wound Care
Global Compression Bandages Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
Interactive Wound Dressing Market
Wound Care
Philippines Wound Care Market