
 Maggot Debridement Market | 2026-2036
Maggot Debridement Market Size, Share, and Industry Trends Forecast 2026-2036
Maggot Debridement Market Intelligence
Synthetic enzymatic debridement gels are repositioning traditional larval therapy economics, yet sterilized maggots retain cost advantages in recalcitrant wound cases. BioMonde leverages its European breeding facility network to sustain supply continuity across NHS procurement channels. Monarch Labs anchors North American production capacity with FDA-registered cleanroom operations. Smith & Nephew competes through broader advanced wound care portfolios that cross-sell larval adjuncts.
Maggot debridement employs sterile Lucilia sericata larvae to enzymatically liquefy necrotic tissue while preserving viable wound bed structures, typically requiring 48-72 hour application cycles at 37°C with controlled moisture barriers. The primary commercial purpose centers on treating wounds unresponsive to conventional sharp or autolytic debridement, particularly in diabetic limb salvage protocols. Sterilized maggots dominate current volume flows due to established reimbursement codes and clinical familiarity, while bioengineered maggots attract R&D investment for genetically enhanced protease secretion profiles. Single-use kits capture the majority of hospital procurement spend, though bulk supply arrangements persist in long-term care facilities managing recurrent venous ulcer caseloads.
FDA 510(k) clearance pathways and the EU Medical Device Regulation collectively shape product standardization, with sterility assurance levels and species authentication now mandatory for commercial distribution. The EPA regulates larval breeding facility waste streams, adding compliance layers to domestic production economics. Home care delivery modes remain underdeveloped relative to institutional channels, creating unresolved questions about remote monitoring protocols and caregiver training standards that stakeholders must address before segment expansion accelerates.
Market Dynamics
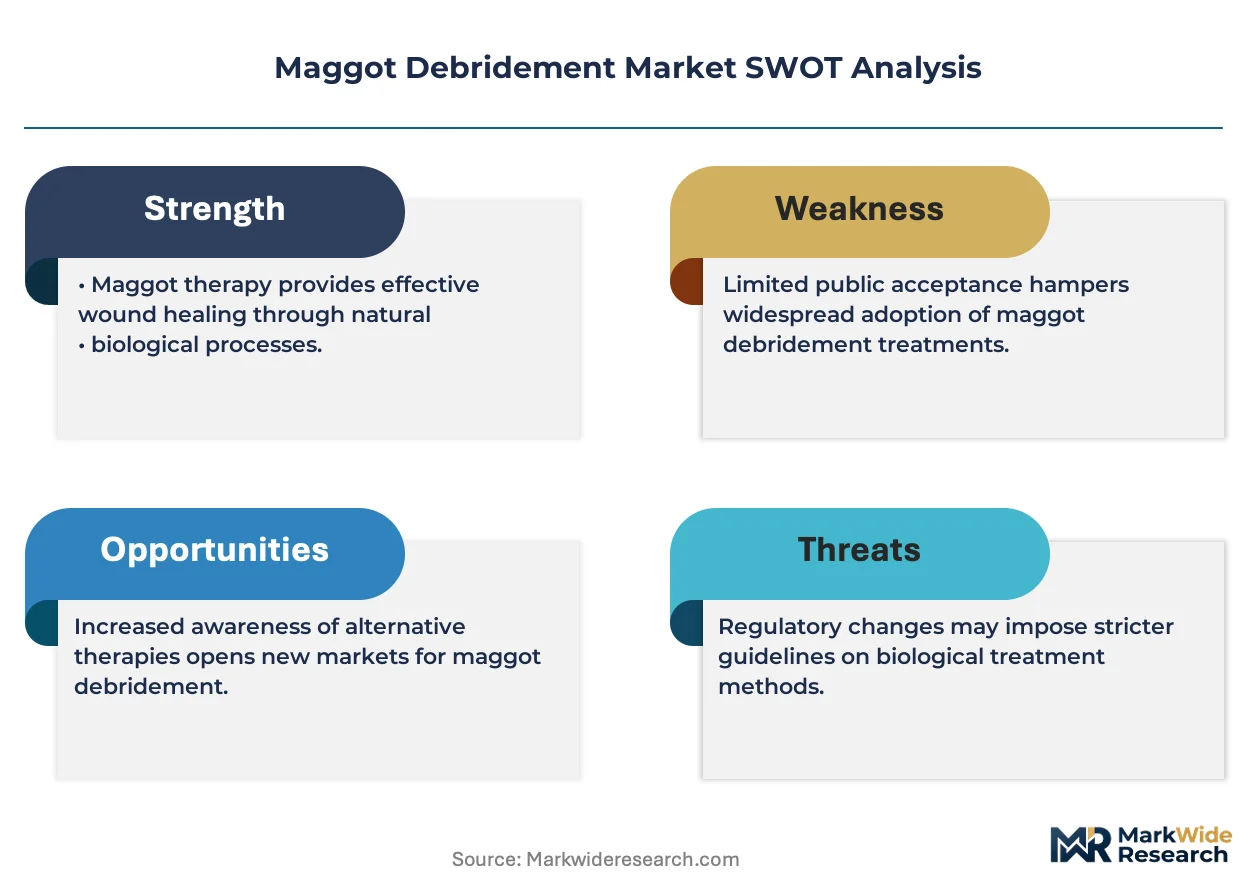
Sterile maggot supply chains concentrate in cleanroom breeding facilities, creating geographic dependencies that amplify procurement risk when demand surges in hospital wound care centers. FDA 510(k) clearance requirements and EU MDR sterility mandates compress vendor margins while elevating compliance barriers for new entrants.
Growth Catalysts
- Reimbursement maturation:Germany's statutory health insurance funds now cover biosurgical debridement under DRG codes, normalizing larval therapy in diabetic limb salvage protocols.
- Chronic wound prevalence:Hospital wound care centers report rising venous ulcer caseloads among aging populations, exhausting conventional sharp debridement capacity.
- Enzymatic specificity:Lucilia sericata proteases liquefy necrotic tissue without damaging viable wound bed structures, outperforming synthetic alternatives in recalcitrant cases.
Market Restraints
- Input cost volatility:Sterile blood meal and controlled-temperature breeding infrastructure consume 40-60% of production costs, exposing margins to energy price swings.
- Supply concentration risk:North American production clusters in FDA-registered cleanroom facilities, creating single-point vulnerabilities during demand spikes.
- Substitution threat:Synthetic enzymatic debridement gels from Smith & Nephew and Coloplast reposition pricing economics in moderate-complexity wounds.
Strategic Opportunities
- Home care penetration:Remote monitoring protocols for caregiver-trained maggot application remain underdeveloped, presenting first-mover advantages in long-term care settings.
- Genetic enhancement R&D:Bioengineered maggots with accelerated protease secretion profiles could compress 48-72 hour treatment cycles, commanding premium positioning.
- EU Green Deal alignment:Biosurgical waste streams qualify for circular economy procurement preferences in NHS sustainability frameworks.
Industry Challenges
- Species authentication complexity:EU MDR mandates PCR-based Lucilia sericata verification, extending batch release timelines and requiring capital-intensive laboratory infrastructure.
- Caregiver training standardization:Home care expansion depends on validated competency frameworks for non-clinical wound dressing changes that no regulator has yet established.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maggot Debridement Market |
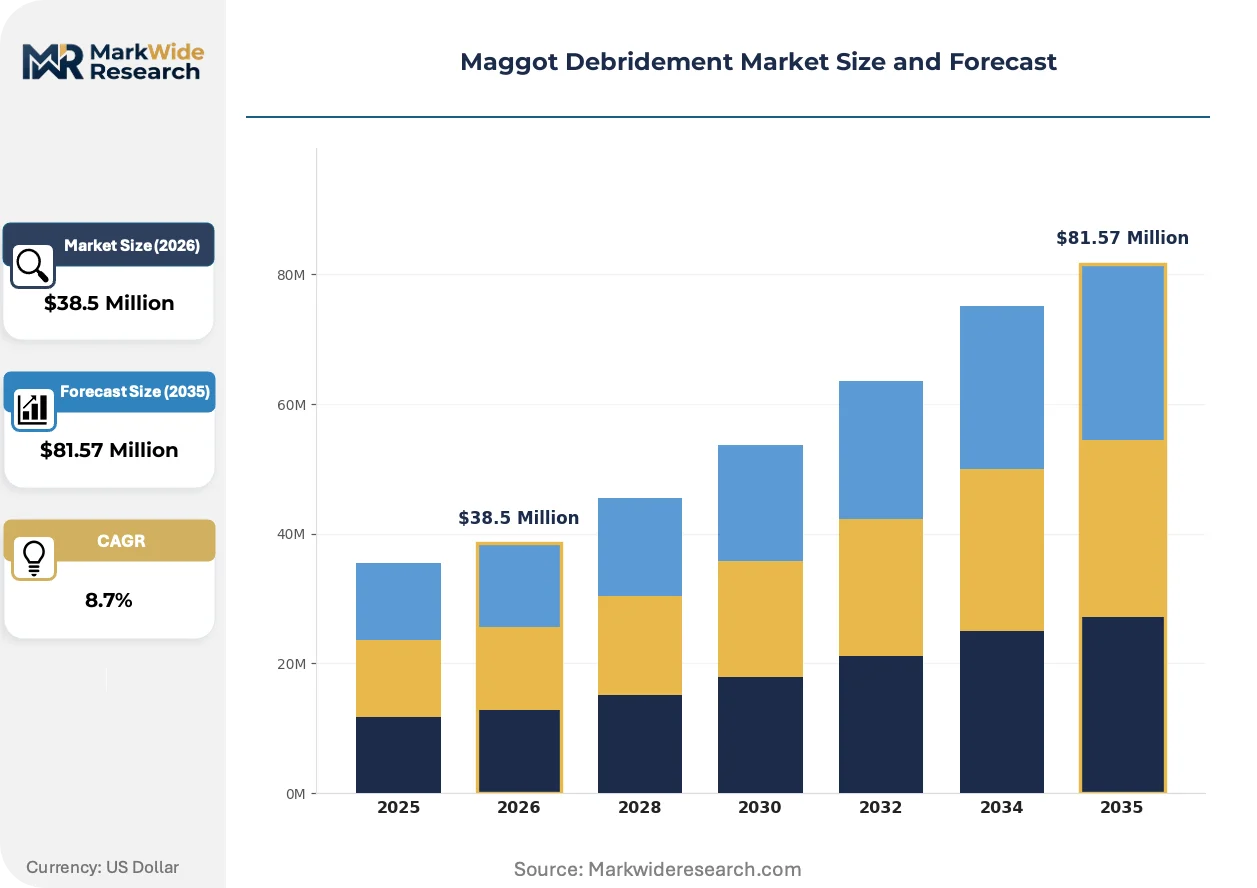
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $81.57 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Maggots, Sterilized Maggots, Bioengineered Maggots, Medicinal Products Application: Wound Healing, Diabetic Ulcers, Venous Ulcers, Burn Treatment End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Delivery Mode: Single-use Kits, Bulk Supply, Prepackaged Solutions, Customized Solutions |
| Companies Covered | BioMonde, Monarch Labs, Mega Pharma (Pvt) Ltd., Smith & Nephew, Coloplast, B. Braun Melsungen AG, Mölnlycke Healthcare, Lohmann & Rauscher, Arobella Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maggot Debridement Market Strategic Shifts & Innovations
Electrification of wound bed monitoring is compressing treatment cycles and enabling real-time larval therapy adjustments. Three forces are restructuring how sterile maggots integrate into advanced wound care protocols.
Wireless moisture and temperature sensors embedded in controlled-release dressings are electrifying clinical confidence in outpatient maggot applications. Hospital wound care centers in Germany and the United Kingdom pilot these systems to reduce 48-72 hour inspection intervals. The technology is electrifying reimbursement negotiations by generating objective compliance data for payor audits.
EU MDR sterility assurance level requirements now mandate species-specific PCR authentication for every commercial maggot batch. Cleanroom breeding facilities face six-figure validation costs per production line, consolidating vendor tiers. French and British hospital procurement teams now require MDR-compliant documentation, filtering out uncertified suppliers from NHS and AP-HP tenders.
Outcome-based contracts are displacing unit-price procurement in German statutory insurance networks. Hospital wound care centers negotiate per-healed-ulcer fees rather than per-kit purchases, transferring outcome risk to maggot suppliers. This model concentrates most visibly in Bavaria and North Rhine-Westphalia, where integrated care contracts bundle debridement with downstream revascularization procedures.
Maggot Debridement Market Segmentation
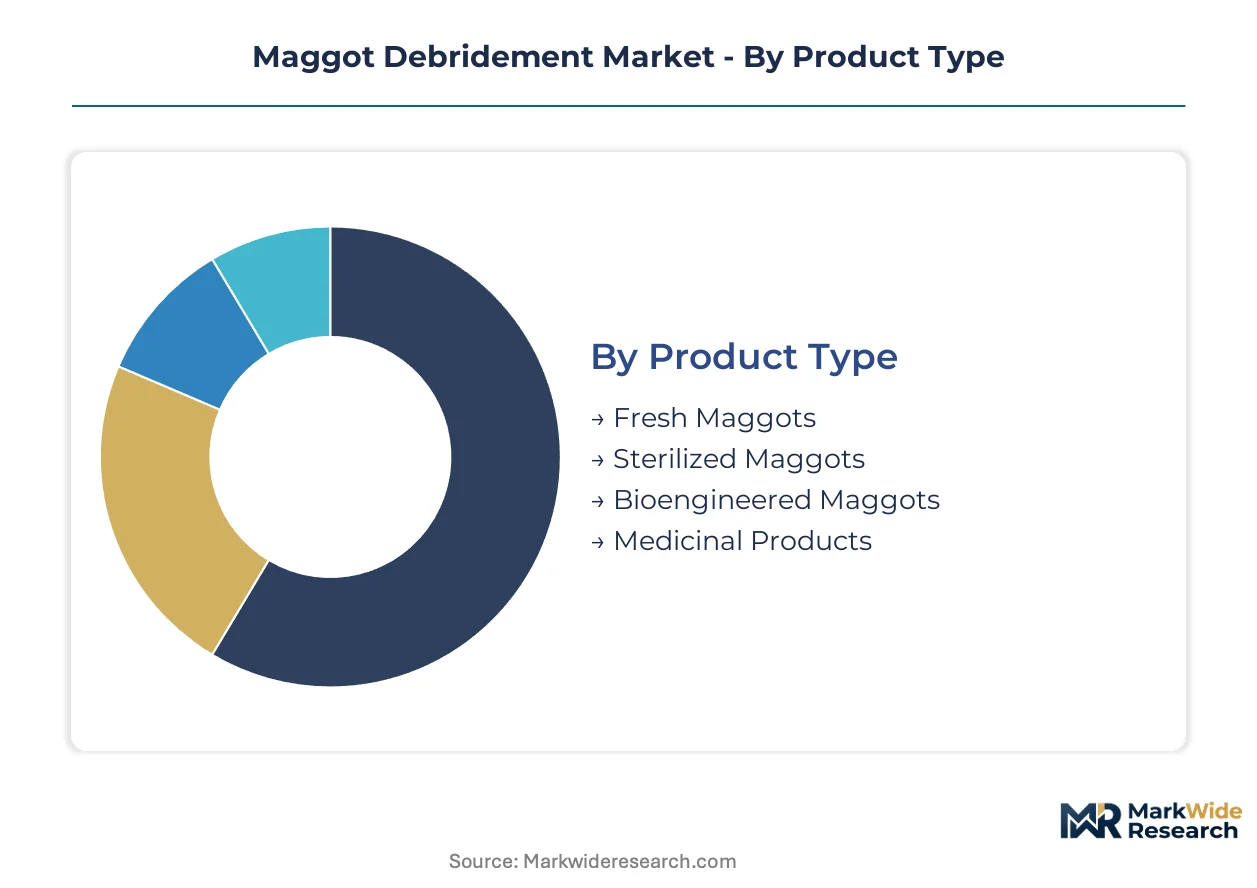
Maggot debridement procurement patterns diverge sharply across sterility grades, clinical settings, and supply formats. Understanding these fault lines clarifies where pricing power concentrates and which segments attract regulatory scrutiny.
Product Type:
Hospital procurement teams weight sterility assurance levels against per-treatment economics when selecting larval formats.
- Sterilized Maggots:Gamma-irradiated Lucilia sericata larvae processed in FDA-registered cleanrooms meet EU MDR sterility mandates. German statutory insurance funds reimburse these under DRG codes, cementing their position in diabetic limb salvage protocols.
- Bioengineered Maggots:Genetically selected strains with enhanced protease secretion profiles compress standard 48-72 hour debridement cycles. R&D investment clusters in French and British breeding facilities targeting premium positioning in recalcitrant wound cases.
- Fresh Maggots:Non-sterile larvae used in veterinary and research applications with limited human clinical penetration.
- Medicinal Products:FDA 510(k)-cleared and CE-marked larvae packaged as regulated medical devices for commercial distribution.
Sterilized Maggots leads on scale; Bioengineered Maggots leads on momentum.
Application:
Clinical indication determines reimbursement eligibility and treatment protocol complexity.
- Diabetic Ulcers:Limb salvage protocols in hospital wound care centers drive volume concentration. Germany's integrated care contracts bundle biosurgical debridement with downstream revascularization, normalizing larval therapy in diabetic foot clinics.
- Venous Ulcers:Recalcitrant cases unresponsive to sharp debridement sustain demand in long-term care facilities. Aging population caseloads exhaust conventional treatment capacity across NHS procurement channels.
- Wound Healing:General debridement applications spanning traumatic and surgical wound types.
- Burn Treatment:Eschar removal in partial-thickness burns where enzymatic specificity preserves viable tissue.
Diabetic Ulcers dominates procurement volume; Venous Ulcers shows steepest expansion trajectory.
End User:
Facility type dictates caregiver training requirements and regulatory oversight intensity.
- Hospitals:Centralized wound care centers with dedicated biosurgical protocols and infection control infrastructure. German and British hospital procurement teams require MDR-compliant documentation and PCR-based species authentication.
- Long-term Care Facilities:Recurrent venous ulcer management drives bulk supply arrangements. Caregiver competency frameworks for non-clinical dressing changes remain unresolved, constraining segment acceleration.
- Clinics:Outpatient wound care settings with limited biosurgical capacity.
- Home Care:Remote monitoring protocols for caregiver-trained maggot application remain underdeveloped across all geographies.
Hospitals captures the majority of institutional spend; Home Care presents untapped first-mover potential.
Delivery Mode:
Packaging format aligns with inventory turnover and treatment frequency patterns.
- Single-use Kits:Sterile maggots in controlled-release dressings with moisture barriers and temperature monitoring. Hospital procurement teams in Germany and the United Kingdom favor these for audit compliance and payor documentation.
- Bulk Supply:Large-volume arrangements for facilities managing recurrent caseloads. Long-term care contracts in Bavaria and North Rhine-Westphalia negotiate per-healed-ulcer fees rather than unit purchases.
- Prepackaged Solutions:Standardized configurations for common wound sizes and treatment durations.
- Customized Solutions:Patient-specific maggot counts and dressing specifications for complex wound geometries.
Single-use Kits commands premium positioning; Bulk Supply anchors cost-sensitive procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital wound care centers anchor biosurgical debridement demand through mature reimbursement frameworks and integrated care contracting. Facility-level procurement concentrates in Bavaria and North Rhine-Westphalia, where outcome-based fee structures normalize larval therapy in diabetic limb salvage protocols.
United States
FDA-registered cleanroom breeding facilities in California and North Carolina supply sterile Lucilia sericata larvae under 510(k) clearance pathways. EPA regulations govern larval breeding waste streams, adding compliance layers to domestic production economics. Monarch Labs anchors North American capacity with hospital procurement contracts spanning major wound care centers.
Germany
Statutory health insurance funds reimburse biosurgical debridement under DRG codes, cementing larval therapy in diabetic foot clinics. EU MDR sterility mandates and PCR-based species authentication requirements filter uncertified suppliers from NHS tenders. Bavarian integrated care contracts bundle debridement with downstream revascularization, transferring outcome risk to suppliers.
United Kingdom
NHS procurement channels sustain demand through BioMonde's European breeding facility network and supply continuity agreements. EU MDR compliance documentation now mandatory for hospital tenders filters market access. London and Manchester wound care centers pilot wireless moisture sensors in controlled-release dressings to compress inspection intervals.
France
ANSM oversight of medical device sterility assurance levels elevates batch release timelines for commercial maggot distribution. AP-HP procurement teams in Paris require MDR-compliant documentation and species authentication. French breeding facilities attract R&D investment for genetically enhanced protease secretion profiles targeting premium positioning.
Switzerland
Swissmedic regulation of sterile medical devices aligns with EU MDR standards while maintaining independent certification pathways. Zurich and Geneva hospital networks participate in cross-border procurement with German and Austrian wound care centers. Biosurgical waste stream management qualifies for circular economy preferences in sustainability frameworks.
Maggot Debridement Market Key Industry Players
Global majors compete with regional champions across cleanroom breeding capacity and regulatory certification depth. The vendor base stratifies into FDA-registered North American producers, EU MDR-compliant European networks, and diversified advanced wound care portfolios. Three archetypes dominate: sterile breeding specialists, diversified medical device conglomerates, and biosurgical R&D innovators. Competitive moves concentrate on M&A for cleanroom facility access and strategic partnerships for NHS procurement channel penetration.
Among sterile breeding specialists, BioMonde and Monarch Labs exemplify the regulatory-compliant archetype through FDA and EU MDR registrations. Smith & Nephew occupies a position within diversified medical device portfolios that cross-sell larval adjuncts alongside broader advanced wound care offerings. Coloplast represents substitution-threat competitors repositioning synthetic enzymatic alternatives against traditional larval economics.
| Leading Market Players |
|---|
| BioMonde |
| Monarch Labs |
| Mega Pharma (Pvt) Ltd. |
| Smith & Nephew |
| Coloplast |
| B. Braun Melsungen AG |
| Mölnlycke Healthcare |
| Lohmann & Rauscher |
| Arobella Medical |
| Others |
Cost & Logistics Intelligence
Cleanroom entomology technicians in Bavaria and North Rhine-Westphalia command wage premiums that compress margin spreads between sterilized and bioengineered maggot tiers. Labor-cost differentials between FDA-registered US facilities and EU MDR-compliant European breeding centers widen pricing gaps for hospital procurement teams negotiating cross-border supply agreements.
Pricing Analysis
Input-cost pass-through from sterile blood meal and controlled-temperature breeding infrastructure drives three-tier pricing stratification across premium bioengineered, standard sterilized, and economy fresh-maggot segments. Certification grade—EU MDR PCR-authenticated versus non-compliant batches—creates the primary price differentiation driver alongside volume scale in long-term care contracts. Pricing pressure stems from synthetic enzymatic debridement gels repositioning economics in moderate-complexity wounds. Long-term care facilities show highest price sensitivity due to recurrent venous ulcer caseloads; hospital wound care centers prioritize sterility assurance over unit cost.
Supply Chain Analysis
Sterile blood meal supply rests on agricultural processing networks concentrated in Germany, the United Kingdom, and France, with gamma-irradiation equipment dependency tethering production to specialized cleanroom infrastructure. Lucilia sericata egg stocks, controlled-temperature breeding chambers, and PCR authentication laboratories anchor raw material and component flows. Single-source vulnerability clusters in FDA-registered North American cleanroom facilities during demand surges. Distribution runs through hospital procurement channels and NHS supply continuity agreements with limited home care penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's mature DRG reimbursement for biosurgical debridement against the United States' fragmented payer landscape creates a geographic-arbitrage opportunity for suppliers with dual regulatory registrations.
For Market Incumbents: Cement supply continuity advantages by expanding EU MDR-compliant cleanroom capacity in French and British breeding facilities. Lock in long-term NHS procurement channel partnerships before outcome-based contracting spreads beyond Bavaria. Synthetic enzymatic substitution threats from diversified medical device portfolios demand accelerated R&D investment in genetically enhanced protease secretion profiles. For New Entrants and Emerging Players: Home care caregiver networks represent the most penetrable buyer archetype given unresolved remote monitoring protocols and absent competency frameworks. Target long-term care facilities managing recurrent venous ulcer caseloads through bulk supply arrangements with per-healed-ulcer fee structures. Partner with wireless sensor manufacturers to bundle real-time wound monitoring with maggot application training. For Investors and Strategic Acquirers: Diversified advanced wound care conglomerates are the most active acquirer in this space, seeking cleanroom breeding facility access to cross-sell larval adjuncts. Acquisition target archetypes include EU MDR-registered sterile breeding specialists with established NHS procurement relationships. Watch for FDA 510(k) clearance pathway streamlining as an inflection signal for North American production economics.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | PCR-based species authentication mandates filter uncertified suppliers from NHS and AP-HP tenders. |
| Home Care Protocol Development | Remote monitoring systems for caregiver-trained maggot application unlock first-mover advantages in long-term care. |
| Genetic Enhancement R&D | Bioengineered Lucilia sericata strains with accelerated protease secretion command premium positioning in recalcitrant wounds. |
| Outcome-Based Contracting | Per-healed-ulcer fee structures in German statutory insurance networks transfer clinical risk to suppliers. |
| Cleanroom Capacity Expansion | FDA-registered and EU MDR-compliant breeding facilities anchor supply security during hospital demand spikes. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital wound care center directors, GPO contracts managers, biomedical engineers, and sterile breeding facility operators with secondary validation against FDA 510(k) filings, EU MDR technical documentation, NHS procurement databases, and hospital supply chain disclosures. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across sterility grades, clinical applications, and delivery modes.
Historical reference periods anchored the projection horizon to observed reimbursement maturation trajectories in Germany and FDA clearance pathway evolution in the United States. The analytical framework modeled demand across product type, application, end user, and delivery mode dimensions, with CAGRs derived from sterilized maggot volume trends and bioengineered product pipeline progression. Forecast inputs incorporated chronic wound prevalence patterns, energy price volatility impacts on breeding infrastructure costs, and synthetic enzymatic debridement substitution elasticity.
Underlying measurement precision varies by segment; sterilized maggot procurement through established hospital channels carries tighter precision than home care penetration estimates where validated protocols remain absent. Forecasts reflect documented assumptions about regulatory clearance timelines and reimbursement code expansion. Supply concentration risk in cleanroom breeding facilities, caregiver training standardization delays, and synthetic alternative pricing repositioning warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Topical Wound Agents Market
Wound Care
Wound Skin Care Market
Wound Care
Wound Care Centers Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Global Surgical Drains/Wound Drainage Market
Wound Care
Wound Closure Strips Market
Wound Care
Chronic Wound Care Market
Wound Care
Decubitus Ulcer Treatment Products Market
Wound Care
Wound Management Market
Wound Care
US Burn Care Centers Market
Wound Care
Italy Wound Care Market
Wound Care
Burn Care Centers Market
Wound Care
North America Wound Care Management Market
Wound Care
Dental Wound Dressings Market
Wound Care
Pressure Ulcer Treatment Market
Wound Care
Surgical Wound Care Market